
 Europe Restaurant Furniture Market | 2026-2036
Europe Restaurant Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Restaurant Furniture Market Analysis
Direct-to-hospitality procurement is narrowing as contract dealers consolidate specification influence across Southern Europe. Pedrali anchors its position through in-house production of molded polypropylene seating near Bergamo. Andreu World competes via FSC-certified wood programs that align with Spanish and Portuguese green building codes. Tonon leverages artisanal upholstery capabilities from its Friuli base to sustain premium positioning against standardized imports.
Europe restaurant furniture encompasses fixed and loose seating, surface, and storage systems engineered for commercial foodservice environments, typically rated for fire resistance, load-bearing capacity, and repetitive cleaning cycles. Manufacturers employ thermoformed polymers, powder-coated steel tubing, and engineered hardwood laminates to achieve durability thresholds exceeding residential standards by a factor of five to ten. Chairs and tables capture the dominant revenue share, though booths command superior margins in fine dining retrofit cycles. Metal frames are displacing solid wood in fast-casual rollouts where turnaround speed and vandal resistance outweigh aesthetic warmth. Modern styling leads specification volumes, while industrial aesthetics retain niche strength in converted warehouse venues across the Netherlands and Belgium.
CE marking under the Construction Products Regulation governs structural safety claims, while REACH restricts chromium and formaldehyde in surface treatments applied to metal and wood substrates. The EU Green Deal's embodied carbon reporting requirements are forcing suppliers to document supply chain emissions or risk exclusion from public-sector hospitality tenders. ECHA substance evaluations are accelerating phase-outs of legacy flame retardants in upholstered products, redirecting R&D toward halogen-free alternatives. Stakeholders must decide whether to absorb certification costs or pass them through to operators already facing energy price volatility.
Market Dynamics
The EU Green Deal's embodied carbon reporting requirements are forcing restaurant furniture manufacturers to reconfigure supply chains around certified sustainable timber and recycled metal inputs, compressing margins for non-compliant producers while creating specification advantages for early certifiers.
Growth Catalysts
- Outdoor Seating Expansion:Fine dining establishments across Germany, France, and Italy are expanding al fresco capacities to capture tourism revenue, driving demand for weather-resistant polypropylene and powder-coated aluminum furniture systems.
- REACH Compliance Advantage:Manufacturers with halogen-free flame retardant portfolios are capturing specification share as ECHA accelerates legacy chemical phase-outs in upholstered seating.
- Coastal Tourism Corridors:Mediterranean zones from Barcelona to the Amalfi Coast are experiencing restaurant opening surges that prioritize durable, salt-air-resistant furniture solutions over residential-grade alternatives.
Market Restraints
- Energy Input Volatility:Natural gas and electricity price instability across the Eurozone is compressing margins for energy-intensive powder-coating and thermoforming operations.
- Baltic Timber Supply Concentration:Certified sustainable hardwood supply chains remain concentrated in limited FSC-managed Baltic and Nordic forests, creating bottleneck risks for European manufacturers.
- Metal-to-Wood Substitution Limits:Fast-casual operators seeking vandal-resistant metal frames face aesthetic trade-offs in premium positioning against solid wood alternatives in fine dining segments.
Strategic Opportunities
- Portuguese Green Building Alignment:Spanish and Portuguese green building codes are creating specification pull for FSC-certified wood programs that manufacturers can leverage for public-sector hospitality tenders.
- Circular Material Innovation:Recycled ocean plastic and post-industrial polymer streams are converging with advanced molding technologies to create differentiated sustainable seating lines.
- Direct-to-Operator Digital Channels:Contract dealer consolidation in Southern Europe is opening white space for manufacturers to build proprietary specification platforms targeting independent restaurant groups.
Industry Challenges
- Artisanal Upholstery Scarcity:Premium positioning dependent on hand-finished textile work faces talent pipeline constraints in traditional manufacturing clusters like Friuli.
- CE Marking Timeline Compression:Construction Products Regulation structural safety certification cycles are elongating product development schedules for new frame designs.
- Legacy Inventory Stranded:Pre-Green Deal stock with non-compliant surface treatments requires costly reformulation or write-downs as public-sector tenders mandate embodied carbon documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Restaurant Furniture Market |
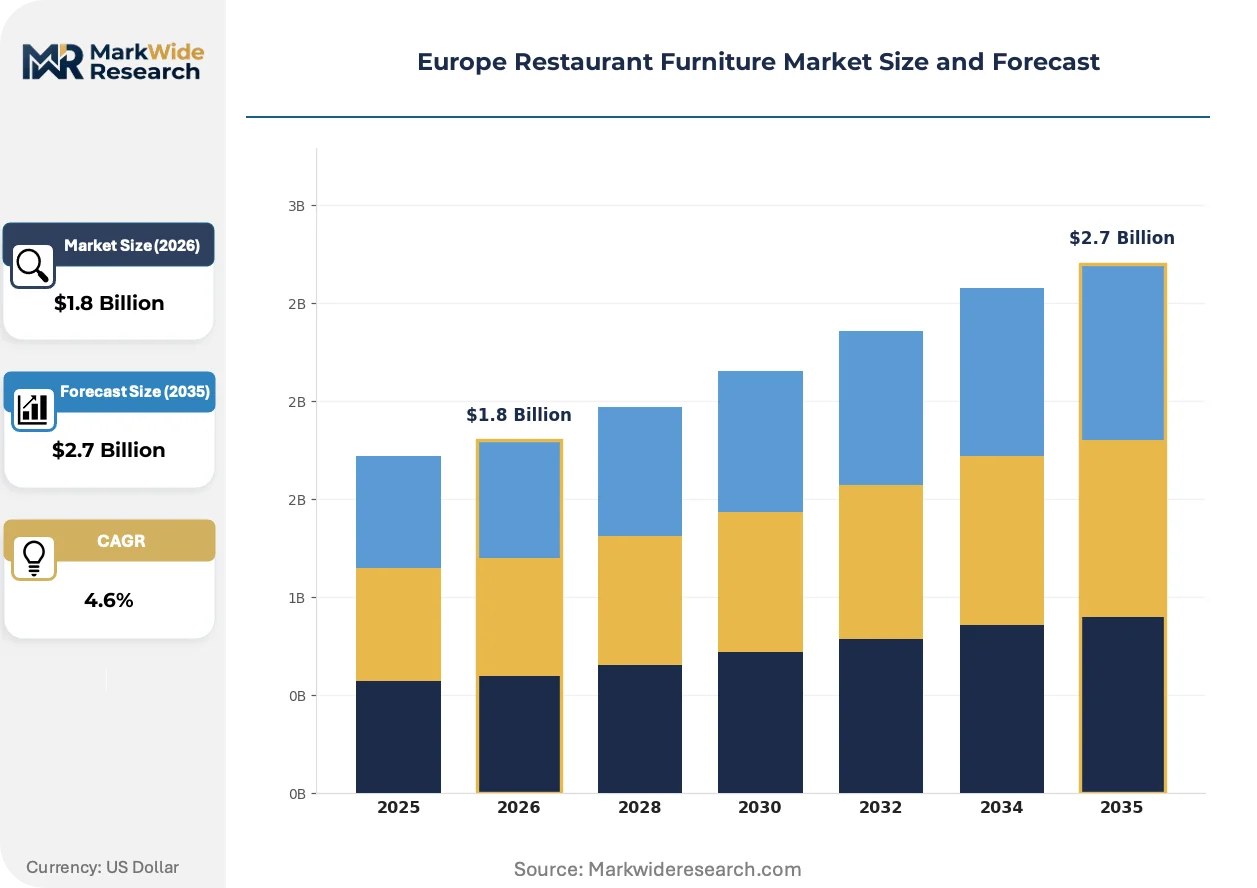
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Tables, Booths, Bar Stools Material: Wood, Metal, Plastic, Fabric Style: Modern, Rustic, Industrial, Traditional End User: Casual Dining, Fine Dining, Cafes, Fast Casual |
| Companies Covered | Pedrali, Tonon, Andreu World, Vondom, Billiani, Kristalia, Fiam, Nardi, Arper, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Restaurant Furniture Market Emerging Trajectories
Thermoformed polymer seating systems are capturing specification share from traditional materials as durability requirements intensify and sustainability credentials become gatekeeping factors in procurement decisions.
Modular polypropylene shell construction is migrating from injection-molded fixed seating toward adaptable, stackable systems that withstand repetitive commercial cleaning cycles. Fast-casual chains across the Netherlands and Belgium are specifying these configurations for rapid table-turn environments. The technology is migrating from standardized import offerings toward in-house European production that shortens lead times and enables custom color matching.
ECHA substance evaluations under REACH are accelerating phase-outs of brominated flame retardants in upholstered restaurant furniture. Manufacturers are redirecting R&D expenditure toward halogen-free chemical alternatives and inherent fire-resistant textile fibers. Spanish and Portuguese suppliers with early certification are capturing specification influence in public-sector hospitality tenders that now exclude legacy-treated products.
Contract dealer networks are consolidating specification control across Southern Europe, compressing manufacturer margins and lengthening payment cycles. Independent restaurant groups in Italy and Greece are responding by forming purchasing cooperatives that bypass traditional distribution tiers. This channel disintermediation is most visible in mid-market urban renovation projects where speed-to-site outweighs brand specification loyalty.
Europe Restaurant Furniture Market Segmentation
Segmentation in the Europe restaurant furniture market reveals how procurement priorities diverge across operational models, from fast-casual chains prioritizing turnaround durability to fine dining establishments investing in bespoke upholstery systems. Understanding these divides enables manufacturers to align certification investments and production capacity with the segments where specification influence concentrates.
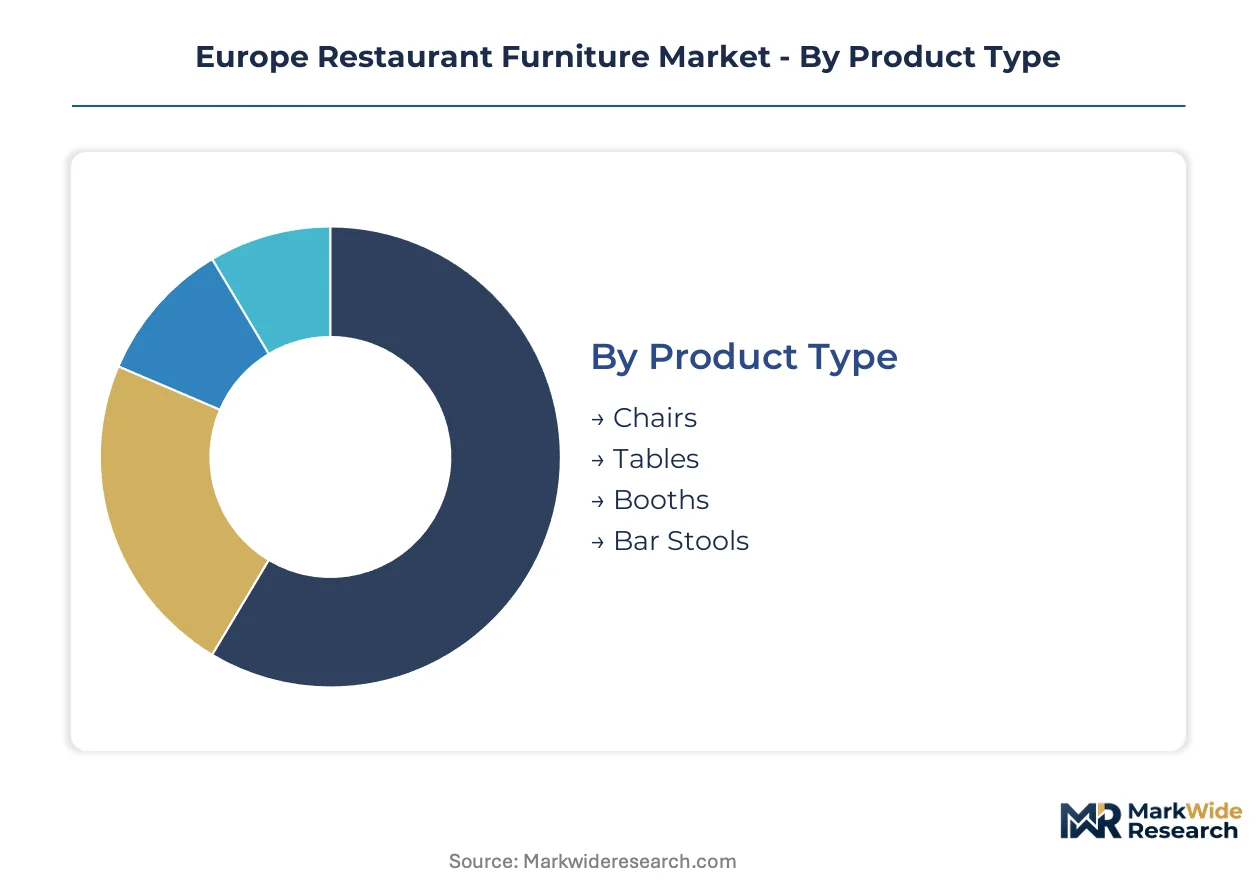
Product Type:
Volume concentration across seating and surface categories tracks directly to renovation cycles and seating density requirements in commercial foodservice environments.
- Chairs:Stackable and fixed-frame designs dominate procurement volumes, with polypropylene shell construction gaining specification share in Mediterranean coastal zones where salt-air corrosion accelerates metal fatigue. Fast-casual operators across the Netherlands and Belgium prioritize rapid-clean surfaces over aesthetic warmth.
- Tables:Powder-coated steel bases with engineered laminate tops capture the bulk of fast-casual rollouts, while solid hardwood surfaces retain specification in German and French fine dining retrofit cycles where table-turn speed matters less than tactile quality.
- Booths:Custom upholstered bench seating commands premium positioning in enclosed dining configurations, with REACH-compliant flame retardant treatments becoming mandatory for public-sector hospitality tenders.
- Bar Stools:Footrail-height seating for counter-service formats concentrates demand in urban Spanish and Portuguese markets where café-bar hybrids expand seating capacity.
Chairs hold installed capacity. Tables is rotating up the share rankings.
Material:
Raw material selection in European restaurant furniture production now hinges on embodied carbon documentation requirements under the EU Green Deal, reshaping supplier qualification criteria.
- Wood:FSC-certified hardwood from Baltic and Nordic forests sustains premium positioning in fine dining segments, though supply concentration creates bottleneck risks for manufacturers scaling certified programs.
- Metal:Powder-coated steel tubing and recycled aluminum frames displace solid wood in high-traffic casual formats, with energy-intensive coating operations facing margin compression from Eurozone electricity price volatility.
- Plastic:Thermoformed polypropylene and recycled ocean polymer streams are converging with advanced molding technologies to create differentiated sustainable seating lines for coastal tourism corridors.
- Fabric:Halogen-free flame retardant upholstery is capturing specification share as ECHA accelerates legacy chemical phase-outs, redirecting R&D toward inherent fire-resistant textile fibers.
Metal holds installed capacity. Plastic is climbing the fastest.
Style:
Aesthetic positioning in European foodservice design tracks to venue type and geographic clustering of renovation activity, with regulatory pressure on material sourcing increasingly constraining stylistic choice.
- Modern:Clean-lined minimalism with molded polymer and powder-coated metal surfaces leads specification volumes across Northern European markets where maintenance efficiency outweighs ornamental detail.
- Rustic:Reclaimed timber and distressed finishes retain niche strength in converted agricultural venues across Tuscany and Provence, though FSC certification requirements constrain authentic reclaimed sourcing.
- Industrial:Exposed steel framing and raw material honesty maintains specification in warehouse conversion projects across the Netherlands and Belgium, with metal-to-wood substitution limits becoming apparent in premium positioning attempts.
- Traditional:Ornate carving and classic proportions concentrate in heritage hotel dining rooms and formal establishments in Vienna and Paris, dependent on artisanal upholstery capabilities facing talent pipeline constraints.
Modern holds installed capacity. Industrial is gaining share fastest.
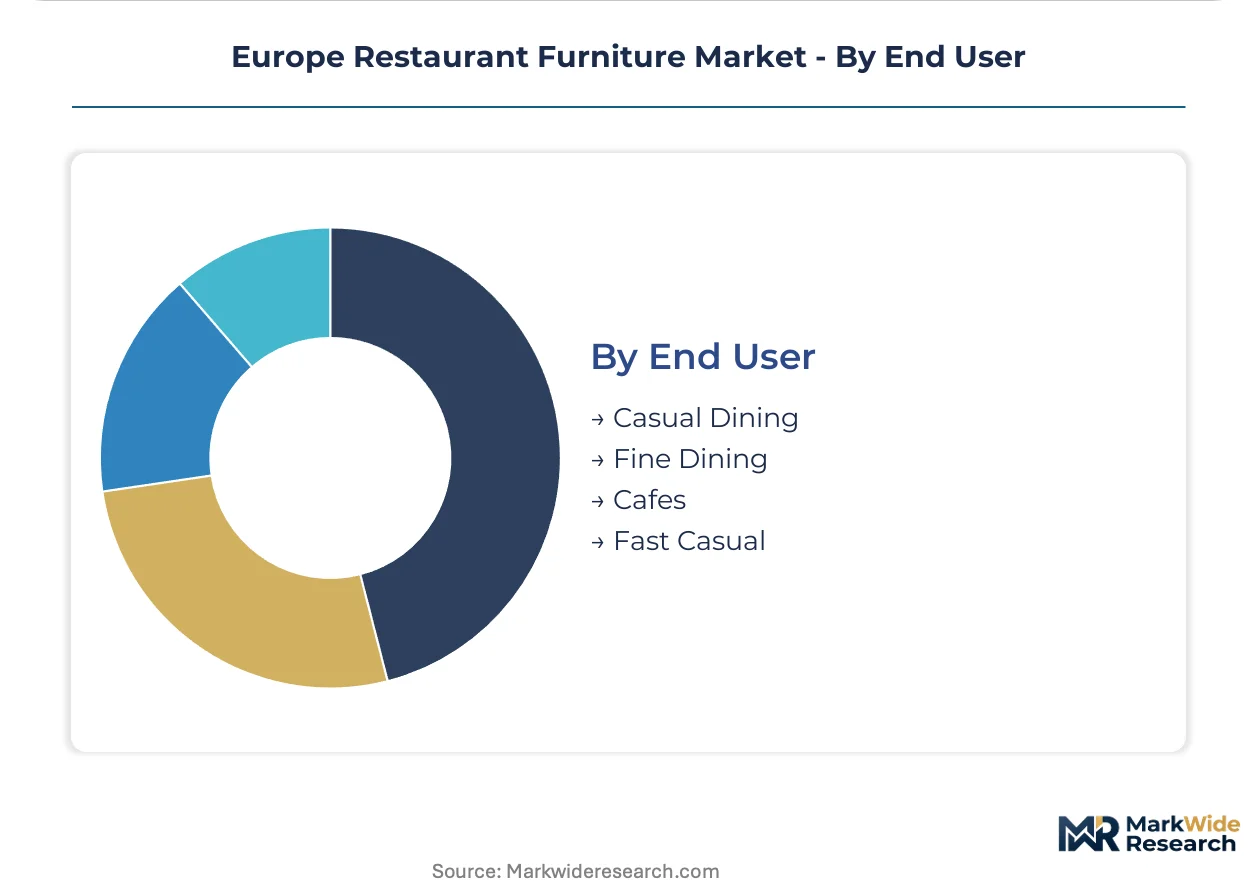
End User:
Operational model determines durability thresholds, cleaning cycle intensity, and the trade-off between initial procurement cost and total lifecycle replacement schedules.
- Casual Dining:Mid-market chains across suburban France and Germany prioritize standardized, rapidly replaceable seating systems that withstand repetitive commercial cleaning without specialized maintenance protocols.
- Fine Dining:Establishments in Milan, Paris, and Munich invest in bespoke upholstery and solid wood surfaces where CE marking under the Construction Products Regulation governs structural safety claims for custom frame designs.
- Cafes:High-turnover coffee service formats in Barcelona and Lisbon favor compact, stackable seating configurations that maximize floor plan flexibility during peak morning rushes.
- Fast Casual:Quick-service formats with limited table service specify vandal-resistant metal frames and thermoformed polymer surfaces where turnaround speed outweighs aesthetic warmth.
Casual Dining holds installed capacity. Fast Casual is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance and the EU Green Deal anchor competitive positioning across Europe, with national regulations fragmenting procurement requirements from the Baltic to the Mediterranean. Coastal tourism corridors and urban renovation cycles drive divergent demand patterns.
Germany
Fine dining establishments in Munich and Berlin are expanding outdoor seating capacities to capture returning tourism revenue. The national implementation of EU Green Deal embodied carbon reporting forces manufacturers to document supply chain emissions for public-sector tenders. The Bergamo-adjacent industrial cluster supplies molded polypropylene seating systems to German operators seeking rapid-clean durability.
France
Parisian fine dining retrofit cycles prioritize bespoke upholstery and solid wood surfaces where tactile quality outweighs turnaround speed. ECHA evaluations under REACH accelerate legacy flame retardant phase-outs in upholstered products. Provence agricultural venue conversions sustain niche demand for reclaimed timber finishes despite FSC certification constraints.
Italy
Milanese design houses drive specification for premium seating systems in enclosed dining configurations. CE marking under the Construction Products Regulation governs structural safety claims for custom frame designs. The Friuli manufacturing base sustains artisanal upholstery capabilities for hand-finished textile work in traditional clusters.
Spain
Barcelona café-bar hybrids expand counter-service seating capacity in dense urban formats. Spanish green building codes create specification pull for FSC-certified wood programs in public-sector hospitality tenders. Mediterranean coastal zones from Barcelona to Valencia experience restaurant opening surges requiring salt-air-resistant furniture solutions.
Netherlands
Warehouse conversion projects across Amsterdam and Rotterdam specify industrial aesthetic metal framing for converted venues. Eurozone electricity price volatility compresses margins for energy-intensive powder-coating operations. Fast-casual chains prioritize thermoformed polymer configurations for rapid table-turn environments over aesthetic warmth.
Europe Restaurant Furniture Market Vendor Landscape
Design-led specialists and scale-driven manufacturers split the market along premium-standard fault lines. The vendor base concentrates in Northern Italian and Spanish industrial clusters where proximity to specification influencers compresses lead times. Three archetypes dominate: heritage craft houses with captive upholstery capabilities, polymer molding specialists with in-house color matching, and metal fabrication operations with powder-coating integration. Competitive moves center on FSC certification pre-emption for Green Deal compliance and direct-to-operator digital channel development bypassing consolidated contract dealers.
Among Italian fabricators, Pedrali anchors the polymer molding archetype through in-house production capabilities, while Tonon occupies a position within heritage craft upholstery traditions from its Friuli base. Andreu World represents the sustainability-certification vector with early FSC-aligned programs. These three exemplify how geographic clustering near specification hubs—Bergamo for molded seating, Friuli for textile finishing, Valencia for Mediterranean distribution—shapes competitive positioning against standardized import competition.
| Leading Market Players |
|---|
| Pedrali |
| Tonon |
| Andreu World |
| Vondom |
| Billiani |
| Kristalia |
| Fiam |
| Nardi |
| Arper |
| Others |
Supply Flow & Price Mechanics
Baltic and Nordic FSC-certified hardwood concentration feeds directly into margin pools at the premium upholstery tier, where German and French fine dining operators absorb certification premiums while fast-casual chains face cost compression from metal substitution limits.
Pricing Analysis
Price spreads between Italian artisanal producers and standardized Polish imports exceed three-to-one for comparable seating configurations. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and geographic delivery cost, with CE-marked custom frames commanding substantial premia over catalog offerings. Cost compression in the thermoformed polymer tier is intensifying because energy-intensive molding operations face Eurozone electricity volatility. Fast-casual chains exhibit highest price sensitivity, while heritage hotel operators in Vienna and Paris show lowest elasticity for hand-finished textile work.
Supply Chain Analysis
REACH restrictions on chromium and formaldehyde surface treatments limit cross-border flows of non-compliant metal and wood substrates into EU member states. Manufacturing gravity centers on Northern Italy, Spain, and Poland, with raw material flows drawing from Baltic timber estates, recycled aluminum streams, and post-industrial polymer recovery networks. Single-source vulnerability concentrates in certified sustainable hardwood supply chains managed through limited FSC-accredited Baltic forests. Distribution runs through consolidating contract dealer networks across Southern Europe, with direct-to-operator digital channels emerging as alternative pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to Mediterranean tourism corridor reopenings and deferred renovation backlogs accumulated across pandemic-disrupted years.
For Market Incumbents: Insulate specification influence by accelerating FSC certification pre-emption ahead of EU Green Deal embodied carbon documentation mandates, while capturing in-house polymer molding capacity near Bergamo to shorten lead times against standardized import competition. Threat substitution from Asian thermoformed seating producers intensifies margin pressure in the mid-market tier.
For New Entrants and Emerging Players: Build out direct-to-operator digital platforms targeting independent restaurant purchasing cooperatives in Italy and Greece, where contract dealer consolidation has created white space for specification bypass. The most penetrable segment sits in mid-market urban renovation projects where speed-to-site outweighs brand loyalty. A circular material innovation angle leveraging recycled ocean polymer streams offers differentiated positioning against incumbent catalog offerings.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed polymer molding specialists in Northern Italy that have scaled production but lack sustainability certification depth for public-sector tender eligibility. Long-term viability across the five-to-ten year window hinges on Green Deal compliance infrastructure rather than volume scale alone. The signal to watch is ECHA acceleration of legacy flame retardant phase-outs, which would strand pre-certified inventory and reward early halogen-free R&D spend.
| Strategic Initiative | Industry Significance |
|---|---|
| FSC Certification Pre-emption | Aligns supplier qualification with EU Green Deal public-sector tender requirements before mandatory deadlines. |
| In-house Polymer Molding Scale-up | Shortens lead times for Mediterranean coastal operators facing seasonal installation windows. |
| Halogen-free Flame Retardant R&D | Captures specification share as ECHA accelerates legacy chemical phase-outs in upholstered seating. |
| Direct-to-Operator Digital Channel | Bypasses consolidating contract dealer networks that compress manufacturer margins across Southern Europe. |
| Circular Material Product Line Launch | Differentiates sustainable seating offerings through recycled ocean polymer and post-industrial streams. |
Methodological Framework
A standing panel of restaurant procurement directors, contract dealer specification consultants, FSC certification auditors, and polymer molding plant managers provided ongoing calibration across primary interview cycles. Secondary validation drew from EU Construction Products Regulation filings, ECHA substance evaluation databases, customs trade data for furniture imports, and hospitality industry renovation tracking. Bottom-up installation data triangulated against top-down manufacturer shipment reports.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling across product type, material composition, end-user operational model, and regional regulatory cluster. CAGRs derived from fitted trend analysis incorporating tourism recovery trajectories, green building code adoption curves, and energy price volatility assumptions. Industry-specific inputs included seasonal installation patterns for Mediterranean coastal zones and fine dining retrofit cycle durations.
The forecast holds incumbent behavior within observed patterns; aggressive certification investment or channel disintermediation moves by mid-cap specialists would shift outcomes beyond modeled ranges. Cross-checking against national hospitality association renovation surveys and Eurostat construction investment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
North America Countertop Market
Kitchen and Dining
North America Tabletop Kitchen Products Market
Kitchen and Dining
Vietnam Kitchen Furniture Market
Kitchen and Dining
Kitchen Furniture and Fixtures Market
Kitchen and Dining
Opalware Dinnerware and Crockery Market
Kitchen and Dining
UAE Kitchen Hoods Market
Kitchen and Dining
Turkey Kitchen Furniture Market
Kitchen and Dining
Kitchen Sinks Market
Kitchen and Dining
Asia-Pacific Kitchen Furniture Market
Kitchen and Dining
India Modular Kitchen Market
Kitchen and Dining
Sweden Household Electric Grills Market
Kitchen and Dining
Global Kitchen Woks Market
Kitchen and Dining
Built-In Cabinet Market
Kitchen and Dining
Australia Kitchen Furniture Market
Kitchen and Dining
Kitchen Countertop Market
Kitchen and Dining
Qatar Kitchen Hood Market