
 Used Restaurant Equipment Market | 2026-2036
Used Restaurant Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Used Restaurant Equipment Market Outlook
NSF/ANSI Standard 7 for commercial refrigerators and freezers is realigning the cost-of-entry calculus for independent restaurant operators seeking certified pre-owned equipment. Gator Chef leverages its refurbishment protocols to compete on compliance credibility in the southeastern United States. Jean's Restaurant Supply anchors its market position through deep inventory of NSF-listed refrigeration units. Texas Restaurant Supply dominates regional auction channels by controlling liquidation flows from distressed hospitality assets across the state.
Used restaurant equipment comprises previously operated commercial-grade appliances, fixtures, and preparation systems originally manufactured for foodservice environments, typically constructed from stainless steel with gas or electric power configurations and designed for continuous-duty cycles exceeding twelve hours daily. The primary commercial purpose centers on enabling food preparation, storage, and service at reduced capital expenditure relative to new equipment procurement. Refrigerators and ovens occupy the largest volume positions within product type segments, reflecting their essential role in virtually all foodservice operations. Certified pre-owned condition categories command margin premiums over as-is inventory due to verified functionality and warranty coverage. Food trucks represent the fastest-growing end user segment, driven by mobility requirements and constrained startup budgets that favor depreciated equipment with immediate deployment capability.
The United States Department of Energy enforces efficiency standards under the Energy Policy and Conservation Act that constrain which used refrigeration equipment can legally re-enter commerce, directly filtering available inventory. State-level health departments coordinate with FDA Food Code provisions to mandate equipment surface materials and cleanability standards that refurbishment operations must address. OSHA workplace safety requirements influence the handling and reconditioning protocols applied to heavy cooking equipment during resale preparation. Stakeholders must monitor evolving energy efficiency thresholds and health code harmonization efforts to anticipate which equipment categories will retain resale viability versus face accelerated obsolescence.
Market Dynamics
NSF certification mandates are restructuring competitive entry barriers for refurbished commercial kitchen equipment, forcing independent suppliers to invest in testing infrastructure while advantaging incumbents with established compliance workflows.
Growth Catalysts
- Food truck fleet expansion:Mobile foodservice operators in Texas and Florida are sourcing depreciated refrigeration and cooking systems to minimize startup capital deployment.
- Energy Policy and Conservation Act efficiency thresholds:Federal standards filtering non-compliant used equipment are creating scarcity premiums for certified pre-owned inventory that meets compliance.
- Auction channel digitization:Online liquidation platforms are compressing price discovery timelines and expanding buyer access to distressed hospitality assets nationwide.
Market Restraints
- Stainless steel input volatility:Raw material cost swings compress refurbishment margins and destabilize pricing predictability for reconditioned equipment.
- Texas supply concentration:Regional auction dominance by single-state liquidation flows creates geographic dependency risk for national distributors.
- Substitution from lease-to-own programs:Equipment financing alternatives reduce price-sensitive buyer reliance on depreciated capital goods.
Strategic Opportunities
- Underpenetrated Pacific Northwest markets:Washington and Oregon restaurant density lags refurbishment supplier coverage, creating whitespace for regional expansion.
- Convergence of IoT diagnostics with refurbishment:Remote monitoring integration enables predictive maintenance offerings on certified pre-owned units.
- OSHA workplace safety protocol bundling:Suppliers can differentiate by incorporating reconditioning documentation that satisfies buyer risk management requirements.
Industry Challenges
- EPA refrigerant handling certification gaps:Technician shortages delay refrigeration unit turnaround times and constrain refurbishment throughput.
- NSF/ANSI Standard 7 testing backlog:Third-party certification queue lengths extend inventory holding periods and compress working capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Used Restaurant Equipment Market |
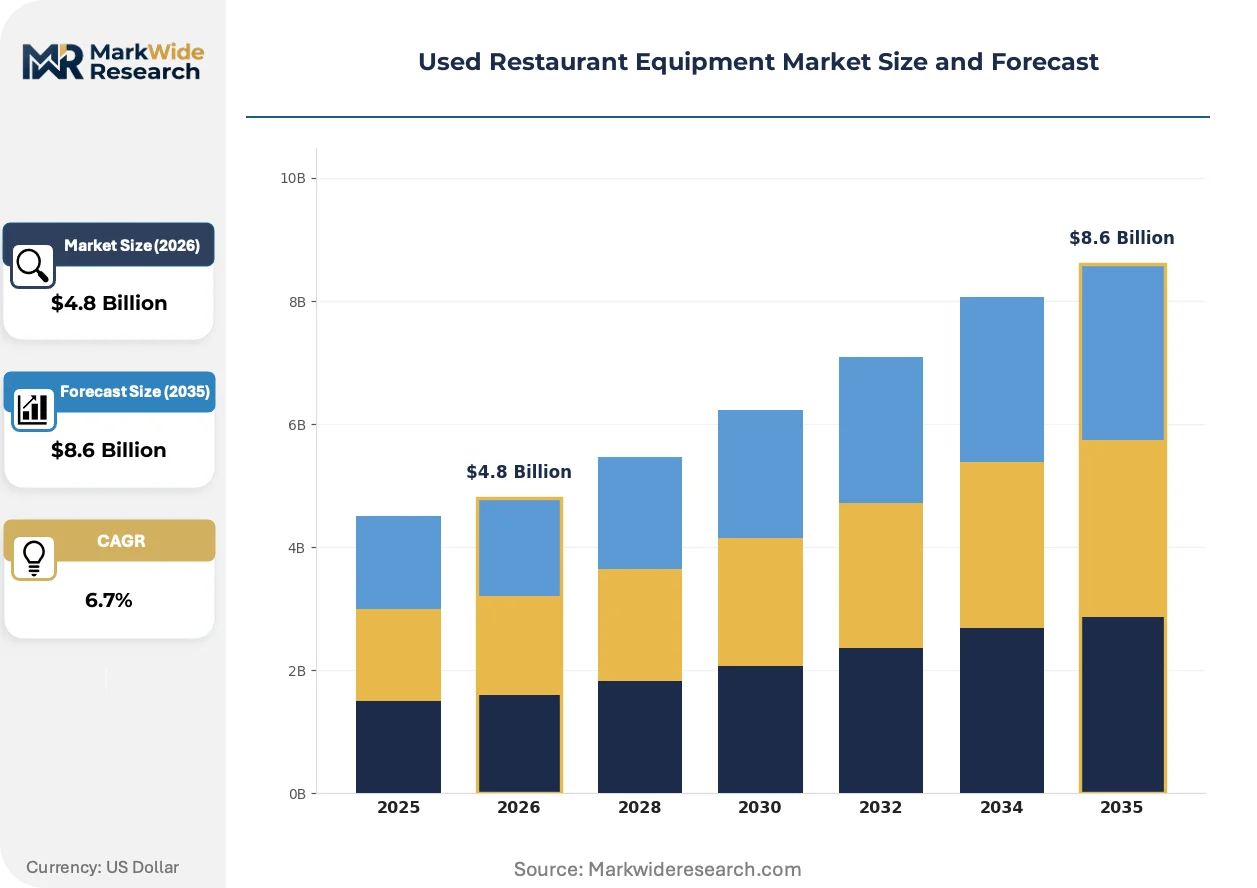
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ovens, Grills, Refrigerators, Fryers End User: Restaurants, Catering Services, Food Trucks, Bakeries Sales Channel: Online Retailers, Auctions, Wholesalers, Direct Sales Condition: Refurbished, As-Is, Overhauled, Certified Pre-Owned |
| Companies Covered | Gator Chef, Jean's Restaurant Supply, City Food Equipment, A City Discount, Restaurant Equippers, Texas Restaurant Supply, United Restaurant Equipment, Alternative Sales Corp., Dine Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Used Restaurant Equipment Market Strategic Shifts
Digital auction infrastructure and remote equipment diagnostics are compressing traditional refurbishment timelines while elevating transparency standards for secondary market transactions.
Cloud-connected temperature monitoring systems are consolidating into refurbished refrigeration units as buyers demand verifiable cold-chain documentation for insurance and liability purposes. Independent quick-service restaurants are adopting these retrofitted systems fastest, recognizing that sensor integration transforms depreciated assets into compliance-ready inventory. This capability compression is consolidating supplier differentiation around data-enabled certification rather than purely mechanical restoration.
The FDA Food Code harmonization push across state health departments is tightening surface material and cleanability specifications for re-entering equipment. Refurbishment operations must now document welding seam standards and coating compliance before resale, elevating process rigor. Texas and Florida health departments are enforcing these provisions most aggressively, forcing regional suppliers to retrain fabrication protocols.
Buyer preference is rotating toward certified pre-owned condition categories with verified functionality documentation and limited warranty coverage. Traditional as-is auction purchases are losing share to inspection-guaranteed transactions, particularly among first-time restaurant operators with limited technical assessment capability. This behavioral shift concentrates in metropolitan Texas markets where auction volume and buyer sophistication intersect most densely.
Used Restaurant Equipment Market Segmentation
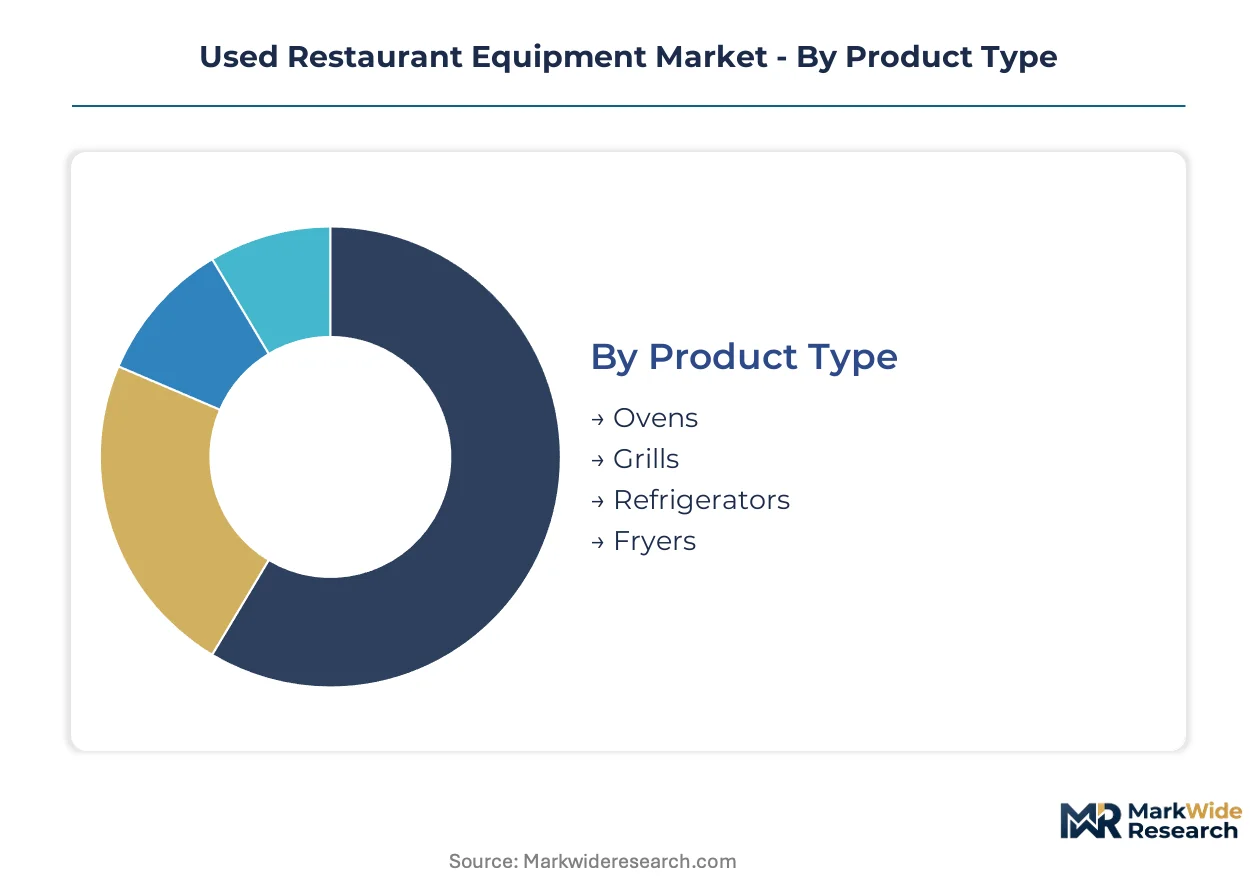
Equipment segmentation in the secondary foodservice market determines liquidity depth and margin capture. Condition certification and sales channel selection directly influence buyer risk tolerance and working capital deployment cycles for independent restaurant operators.
Product Type:
Stainless steel construction standards and thermal performance specifications define the refurbishment investment required for each equipment category.
- Refrigerators:NSF/ANSI Standard 7 compliance mandates govern compressor refurbishment and insulation integrity testing. Demand concentrates in Texas quick-service chains seeking verified cold-chain documentation for liability coverage.
- Ovens:Gas and electric configurations require distinct reconditioning protocols for burner calibration and thermostat accuracy. Independent pizzerias in Florida represent the densest buyer concentration for deck oven refurbishment.
- Grills:Heavy-gauge steel recovery and burner replacement dominate reconditioning workflows for charbroiler units.
- Fryers:Oil vat integrity testing and filtration system restoration address the highest-temperature operational stresses in commercial kitchens.
Mature deployment sits with Refrigerators. Newer deployment is concentrated in Ovens as pizza segment expansion accelerates.
End User:
Capital constraints and mobility requirements segment buyer sophistication and equipment lifecycle expectations across foodservice formats.
- Food Trucks:Space-constrained mobile operators prioritize compact refrigeration and ventless cooking systems with immediate deployment capability. Texas and Florida fleet expansion is absorbing depreciated equipment fastest among all end-user categories.
- Restaurants:Independent quick-service operators balance NSF certification requirements against upfront cost minimization, driving certified pre-owned preference over as-is purchases.
- Catering Services:Event-based volume volatility favors flexible equipment procurement through auction channels rather than fixed capital commitment.
- Bakeries:Precision temperature control requirements for proofing and baking equipment elevate refurbishment standards for convection and deck oven categories.
Volume leadership remains with Restaurants. Steepest expansion trajectory belongs to Food Trucks as mobile foodservice penetration deepens.
Sales Channel:
Price discovery transparency and inspection access differentiate channel economics for buyers and liquidation velocity for sellers.
- Auctions:Texas Restaurant Supply controls regional distressed asset flows through physical and digital auction platforms, compressing price discovery timelines for hospitality liquidation.
- Online Retailers:Digital inventory aggregation expands geographic buyer access but introduces shipping cost complexity for heavy stainless steel equipment.
- Wholesalers:Jean's Restaurant Supply and Gator Chef leverage volume purchasing and refurbishment infrastructure to supply regional dealer networks with NSF-listed inventory.
- Direct Sales:Manufacturer-authorized refurbishment programs offer warranty-backed certified pre-owned units at margin premiums to auction alternatives.
Transaction liquidity peaks at Auctions. Buyer trust formation is advancing fastest through Direct Sales as warranty documentation standardizes.
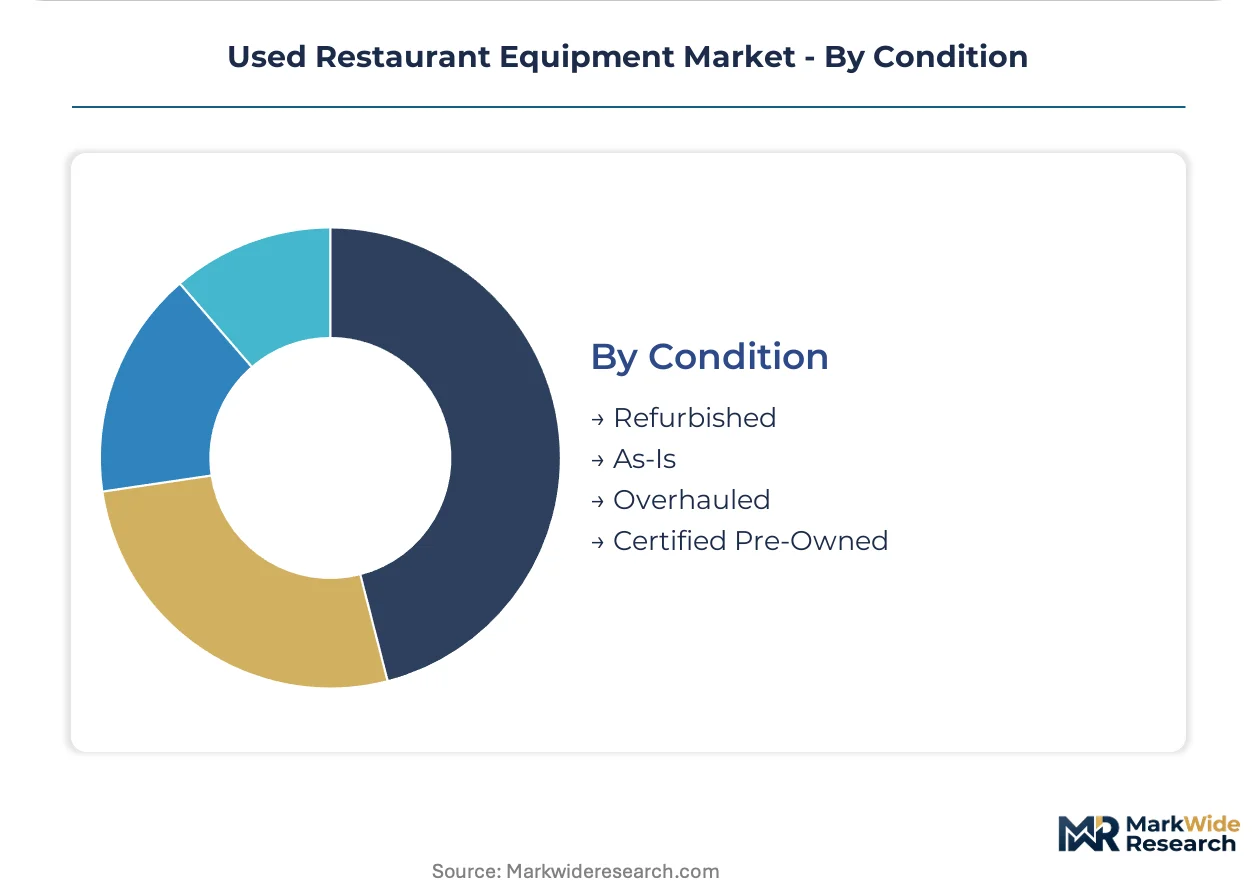
Condition:
Functional verification depth and warranty coverage duration stratify pricing tiers and buyer risk profiles.
- Certified Pre-Owned:NSF-certified testing protocols and limited warranty coverage command margin premiums over unverified inventory. FDA Food Code harmonization across Texas and Florida health departments is accelerating buyer migration toward this tier.
- Refurbished:Component replacement and cosmetic restoration without third-party certification occupy the mid-market price position for cost-sensitive operators.
- Overhauled:Comprehensive mechanical rebuilding approaches new-equipment performance specifications at reduced capital outlay for high-utilization kitchen environments.
- As-Is:Unverified functionality with buyer-assumed risk concentrates in cash-constrained startup operators with technical assessment capability.
Share consolidation is concentrating in Certified Pre-Owned. As-Is is losing ground fastest as first-time operator buyer share expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas Opportunity Zones and state-level tax abatements for foodservice ventures concentrate used equipment procurement in high-velocity secondary markets. Independent restaurant formations and distressed asset liquidations generate unmatched refurbishment demand in designated enterprise communities.
United States
Food truck fleet expansion across Texas and Florida absorbs depreciated refrigeration and ventless cooking systems fastest among all end-user categories. The FDA Food Code harmonization push tightens surface material specifications that refurbishment operations must document before resale. Houston and Dallas auction corridors control regional liquidation flows from distressed hospitality assets.
Germany
Commercial kitchen efficiency mandates under the EU F-Gas Regulation filter non-compliant used refrigeration from legal commerce. The country's national food safety regulator enforces cleanability standards that elevate reconditioning protocols for stainless steel equipment. Berlin and Munich restaurant clusters favor certified pre-owned inventory with verified energy performance documentation.
Canada
Provincial health departments coordinate with federal food code provisions to mandate equipment surface materials that refurbishment operations must address. Health Canada oversight extends to cold-chain documentation requirements for insurance and liability purposes. Toronto and Vancouver metropolitan markets concentrate buyer sophistication and auction volume intersection.
Australia
Foodservice startup density in metropolitan corridors drives certified pre-owned preference over as-is purchases among first-time operators. The country's national food standards code governs commercial equipment cleanability specifications that reconditioning workflows must satisfy. Sydney and Melbourne refurbishment suppliers leverage volume purchasing to supply regional dealer networks.
United Kingdom
Independent quick-service restaurant expansion balances NSF-equivalent certification requirements against upfront cost minimization. The Food Standards Agency coordinates with local authority enforcement to mandate equipment surface materials and welding seam standards. London and Birmingham auction channels compress price discovery timelines for hospitality liquidation assets.
Used Restaurant Equipment Market Competitive Environment
United States suppliers anchor the auction and wholesale tiers; European specialists hold certification-intensive refurbishment positions. Market structure fragments across regional inventory aggregators, digital liquidation platforms, and manufacturer-authorized reconditioning programs. Three archetypes dominate: geography-bound auction controllers, NSF-certified refurbishment specialists, and inventory-heavy wholesale distributors. Competitive moves concentrate on auction channel digitization and compliance documentation bundling.
Among United States-based suppliers, Texas Restaurant Supply, Gator Chef, and Jean's Restaurant Supply occupy positions across distinct channel archetypes. Texas Restaurant Supply exemplifies geography-bound auction control through distressed asset flow management. Gator Chef represents the NSF-certified refurbishment specialist model competing on compliance credibility. Jean's Restaurant Supply anchors the inventory-heavy wholesale distributor tier through deep refrigeration unit stocks.
| Leading Market Players |
|---|
| Gator Chef |
| Jean's Restaurant Supply |
| City Food Equipment |
| A City Discount |
| Restaurant Equippers |
| Texas Restaurant Supply |
| United Restaurant Equipment |
| Alternative Sales Corp. |
| Dine Company |
| Others |
Value Chain & Pricing Dynamics
Stainless steel input volatility cascades through refurbishment margins to stratify certified pre-owned equipment across premium-mid-economy pricing tiers, with Texas auction corridors anchoring cost baselines for national distribution networks.
Pricing Analysis
Lead-time compression commands margin premiums in the used restaurant equipment market, with immediate-deployment certified pre-owned units carrying substantial markups over spot-auction as-is inventory. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified warranty-backed units from component-replaced refurbished stock and unverified auction lots. Cost compression in the as-is tier is intensifying because food truck operators with technical assessment capability arbitrage price spreads. First-time independent restaurant operators exhibit highest price sensitivity, while high-utilization quick-service chains prioritize total-cost-of-ownership over upfront outlay.
Supply Chain Analysis
Stainless steel sheet supply rests on domestic mill capacity and import flows from China and India, with gauge specifications governing fabrication feasibility for commercial kitchen equipment. Refurbishment operations draw from distressed hospitality asset liquidations, EPA-certified refrigerant reclaim networks, and third-party NSF testing laboratories. Single-source vulnerability concentrates in Texas auction channels controlling regional liquidation flows. Distribution runs through wholesaler networks anchored by regional inventory aggregators, digital liquidation platforms, and manufacturer-authorized reconditioning programs serving independent restaurant operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The used restaurant equipment market functions as a cost-of-compliance story where NSF/ANSI Standard 7 certification requirements erect barrier-to-entry moats favoring incumbents with established testing infrastructure and documented refurbishment protocols.
For Market Incumbents: Deploy certification bundling as the primary defensive lever. Incumbents should deepen NSF testing queue relationships to compress inventory holding periods while expanding IoT-enabled cold-chain documentation offerings that address buyer insurance requirements. Lease-to-own program expansion from equipment financiers represents the most acute substitution threat requiring competitive response through warranty-term extension. For New Entrants and Emerging Players: Online auction platform specialization offers the most penetrable entry vector for new competitors. Pacific Northwest metropolitan corridors present whitespace opportunities where restaurant density exceeds refurbishment supplier coverage, particularly in Seattle and Portland markets. A digital-first consignment model targeting distressed hospitality asset liquidation can bypass capital-intensive inventory holding while capturing transaction fees. For Investors and Strategic Acquirers: EPA refrigerant handling certification backlog resolution is the leading indicator that refurbishment throughput constraints will ease and working capital velocity will improve. Long-term viability favors vertically integrated regional specialists combining auction channel control with in-house NSF certification capability. Consolidation opportunity concentrates in Texas and Florida where food truck fleet expansion sustains equipment demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| NSF Certification Infrastructure Investment | Testing laboratory partnerships with NSF International compress third-party queue delays for refrigeration units. |
| IoT Diagnostics Integration | Cloud-connected temperature monitoring retrofits transform depreciated assets into compliance-ready inventory for liability-conscious buyers. |
| Auction Channel Digitization | Online liquidation platforms expand geographic buyer access beyond Texas auction corridor concentration. |
| Refrigerant Reclaim Network Expansion | EPA-certified technician capacity addresses certification gaps constraining refrigeration unit turnaround times. |
| Pacific Northwest Geographic Expansion | Washington and Oregon market entry captures underpenetrated restaurant formation demand. |
Study Parameters
Document review covered SEC filings from restaurant supply distributors, EPA enforcement actions on refrigerant handling, NSF International certification databases, and state health department equipment codes, complemented by interviews with refurbishment facility operators, auction platform managers, independent restaurant procurement officers, and commercial kitchen equipment technicians. Secondary validation drew from FDA Food Code harmonization documents, Department of Energy efficiency standard updates, and customs trade data on stainless steel equipment imports. Bottom-up equipment transaction volume estimates were triangulated against top-down market size calculations from capital expenditure surveys.
Historical auction transaction velocity was cross-referenced against panel input from regional wholesalers to establish baseline demand patterns across the projection horizon. The analytical framework modeled segmentation dimensions including equipment condition tier, sales channel type, end-user format, and geographic market cluster. CAGRs were derived from equipment replacement cycle analysis and restaurant formation rate projections. Forecast inputs incorporated food truck fleet expansion trajectories and NSF certification queue length trends.
The model holds under stable regulatory enforcement intensity and consistent energy efficiency threshold evolution; deviation in EPA refrigerant policy stringency or state-level health code harmonization pace would shift refurbishment viability assumptions. A small set of named triggers warrants ongoing watch: FDA Food Code adoption velocity, stainless steel input cost volatility, and food truck operator financing availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
Smart Food Scale Market
Food Service Equipment
Popcorn Machine Market
Food Service Equipment
Meal Delivery Carts and Racks Market
Food Service Equipment
Commercial Stainless Steel Cooking Equipment Market
Food Service Equipment
Combi Cooler Market
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
Draught Beer Chiller Market
Food Service Equipment
Food Trays and Bowls Market
Food Service Equipment
Reach-In Refrigerators Market
Food Service Equipment
Ice Maker Market
Food Service Equipment
Restaurant Fryers Market
Food Service Equipment
Commercial Catering Equipment Market
Food Service Equipment
Commercial Hot Dog Cooker Market
Food Service Equipment
Multi Cooker Market