
 United States Hand Holes Market | 2026-2036
United States Hand Holes Market Size, Share, and Industry Trends Forecast 2026-2036
United States Hand Holes Market Analytics
A widening capital-intensity gap between integrated manufacturers and regional fabricators is rotating competitive advantage toward players with captive concrete and polymer molding operations. Oldcastle Infrastructure leverages its national distribution network and vertically integrated precast capabilities to sustain price competitiveness across state DOT procurement cycles. EJ Group anchors its position through ductile iron and composite foundry expertise that competes on load-rating performance in municipal electrical vault specifications. Quazite differentiates via rotational-molded polymer hand holes that dominate telecommunications and fiber-optic deployments requiring corrosion resistance and reduced installation weight.
Hand holes are enclosed access chambers, typically manufactured from reinforced concrete, polymer composites, fiberglass, or cast metals, with standardized load ratings and dimensional tolerances designed to protect underground utility junctions, valves, and cable splices from soil pressure, moisture ingress, and traffic loads. Concrete hand holes retain dominance in heavy-traffic electrical distribution and water management applications where AASHTO H-20 load ratings are mandatory, while fiberglass and plastic variants capture share in telecommunications and drainage systems where chemical resistance and manual installability reduce field labor costs. Medium and large sizes generate the majority of volume, though extra-large configurations are growing fastest as 5G fiber hubs and smart-grid transformer enclosures require expanded internal clearance for cable management and ventilation.
FAA obstruction lighting standards, OSHA excavation safety requirements, and state-level DOT prequalification programs collectively shape product certification burdens and procurement eligibility for hand hole suppliers serving airport, utility, and transportation end users. The Federal Communications Commission's broadband equity programs are channeling infrastructure funding toward states with rural connectivity gaps, redirecting manufacturer attention toward polymer hand holes optimized for expedited trench deployment. Stakeholders must monitor evolving Buy America domestic content thresholds and state-level environmental product declarations that are beginning to filter precast concrete and composite material selections in federally subsidized projects.
Market Dynamics
Federal broadband equity funding is redirecting procurement specifications toward polymer hand holes optimized for rapid trench deployment, compressing traditional concrete-heavy electrical distribution supply chains. Utility grid hardening mandates and EPA stormwater enforcement are simultaneously tightening material certifications while expanding addressable project volume.
Growth Catalysts
- Telecommunications Infrastructure Expansion:FCC broadband equity programs are channeling infrastructure funding toward states with rural connectivity gaps, accelerating polymer hand hole adoption for fiber-optic deployments requiring corrosion resistance and reduced installation weight.
- EPA Stormwater Regulations:The Clean Water Act's tightening material specifications for underground utility access products are disqualifying non-compliant fabricators and consolidating procurement toward certified precast and composite suppliers.
- Utility Grid Hardening:Southeast regional investments in electrical infrastructure resilience are concentrating demand for medium and large hand hole configurations with AASHTO H-20 load ratings.
Market Restraints
- Petrochemical Input Volatility:Rotational-molded polymer hand hole production depends on polyethylene resin pricing subject to refinery capacity constraints and energy market fluctuations.
- Foundry Capacity Concentration:Ductile iron casting for heavy-load electrical vault applications clusters in legacy manufacturing regions, creating supply bottlenecks during municipal procurement surges.
- Concrete Curing Limitations:Precast concrete hand holes require extended curing cycles that compress delivery timelines for emergency utility restoration projects.
Strategic Opportunities
- 5G Fiber Hub Scaling:Extra-large hand hole configurations for smart-grid transformer enclosures and fiber distribution hubs represent underpenetrated specification tiers with limited incumbent competition.
- Buy America Compliance Services:Domestic content threshold verification and supply chain documentation services are emerging as value-add offerings for federally subsidized infrastructure projects.
- Modular Polymer Systems:Stackable and sectional polymer hand hole designs are converging with trenchless installation methods to reduce field labor requirements in constrained urban rights-of-way.
Industry Challenges
- Multi-Agency Certification Burden:Simultaneous FAA obstruction lighting, OSHA excavation safety, and state DOT prequalification requirements extend product validation timelines and increase compliance overhead.
- Legacy Electrical Vault Integration:New polymer hand hole specifications must interface with existing cast iron and concrete infrastructure, complicating standardized product platform development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Hand Holes Market |
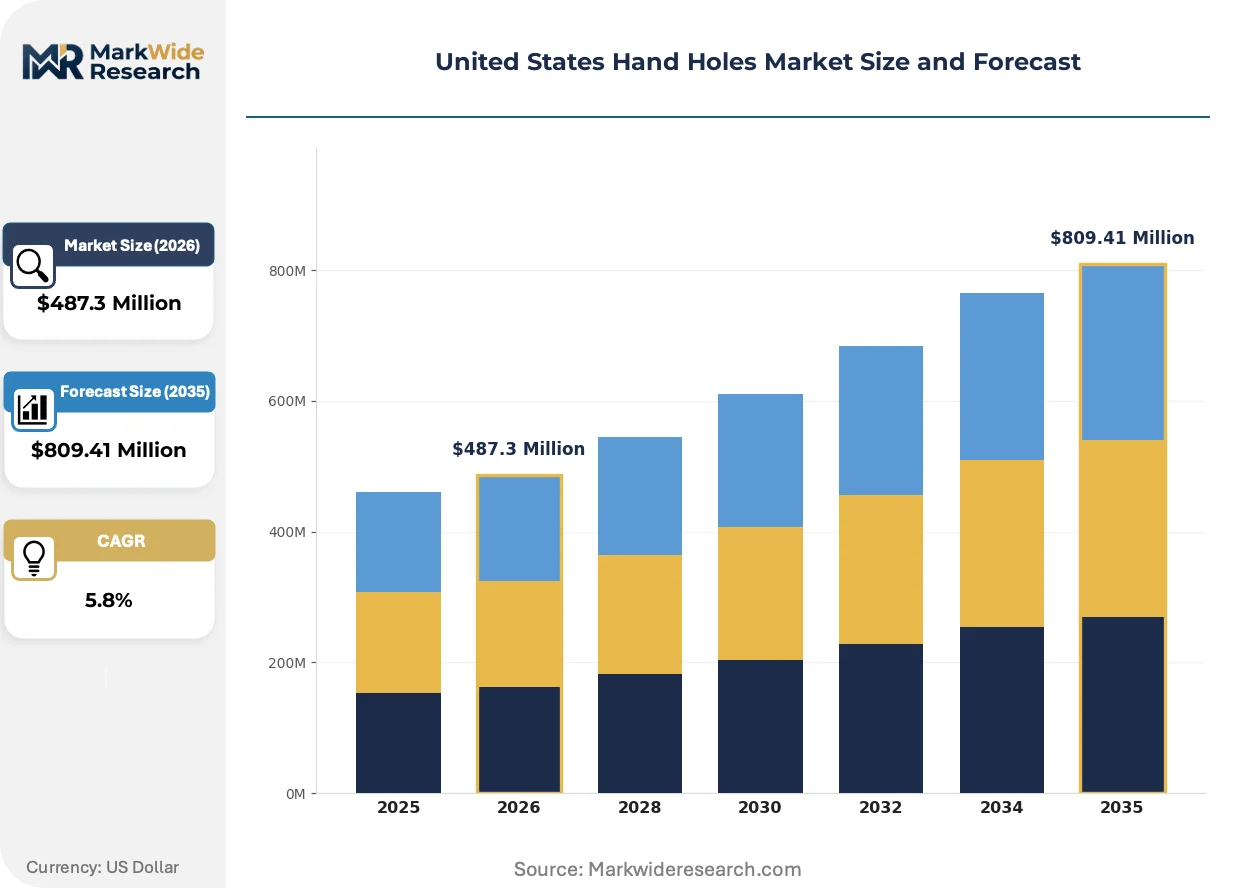
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Hand Holes, Fiberglass Hand Holes, Concrete Hand Holes, Metal Hand Holes Application: Telecommunications, Electrical Distribution, Water Management, Drainage Systems Size: Small, Medium, Large, Extra Large Installation Type: Buried, Above Ground, Underground, Wall-Mounted |
| Companies Covered | Quazite, EJ Group, Oldcastle Infrastructure, Concast, Garden State Precast, Hubbell Power Systems, A.C. Miller Concrete Products, Utility Concrete Products, Jensen Precast, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Hand Holes Market Evolving Landscape
Material science advances and procurement digitization are restructuring competitive advantage around specification speed and installation labor reduction rather than unit production cost alone.
Rotational-molded polymer composite hand holes are bifurcating the telecommunications access chamber market from legacy concrete and metal alternatives. Fiber-optic deployers are specifying these systems for 70% of new rural broadband infrastructure. The technology is compressing installation crew sizes from four-person teams to two-person configurations.
OSHA excavation safety requirements are mandating shoring-compatible hand hole dimensions and lid-lifting ergonomics that preclude certain legacy cast iron designs. Municipal electrical contractors are retrofitting procurement specifications to exclude non-compliant products. California and Texas DOT prequalification programs are incorporating these standards into vendor eligibility screening.
Utility procurement departments are consolidating vendor relationships around integrated precast and polymer suppliers capable of single-source fulfillment across multiple specification tiers. Regional fabricators without captive molding or concrete operations are losing bid eligibility on bundled infrastructure contracts. This concentration is most visible in Southeast states with active broadband deployment and grid hardening programs.
United States Hand Holes Market Segmentation
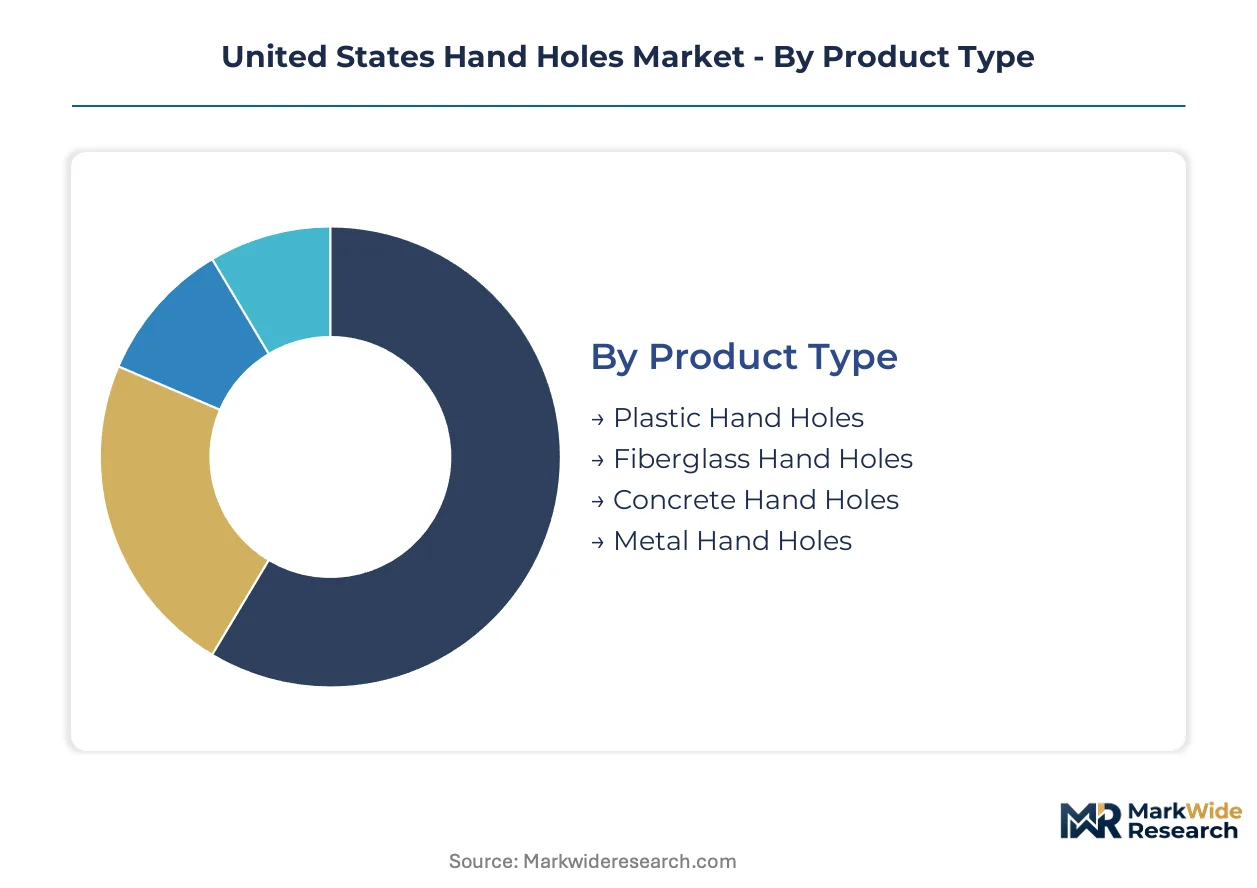
Hand hole specification tiers diverge sharply across load-bearing requirements, chemical exposure profiles, and installation labor constraints. Procurement officers segment purchases by material performance class and end-use regulatory exposure rather than unit cost alone.
Product Type:
Polymer and composite formulations are displacing legacy materials in corrosion-sensitive deployments, while concrete and metal retain structural dominance in heavy-load applications.
- Plastic Hand Holes:Rotational-molded polyethylene systems dominate FCC-funded rural broadband trenching. Southeast fiber-optic contractors specify these for reduced crew size and chemical resistance in acidic soils.
- Fiberglass Hand Holes:Reinforced thermoset composites bridge the gap between polymer lightness and concrete load ratings. Electrical utilities in Florida and Georgia deploy these for coastal corrosion zones requiring AASHTO H-20 compliance without metallic degradation.
- Concrete Hand Holes:Precast reinforced concrete retains municipal electrical vault standards where traffic loads exceed polymer limits. Extended curing cycles constrain emergency procurement timelines.
- Metal Hand Holes:Ductile iron castings anchor legacy transformer enclosures and airport obstruction-lighted vaults. Foundry capacity concentration in legacy manufacturing regions creates supply bottlenecks during procurement surges.
Concrete hand holes retain volume leadership; plastic hand holes hold the steepest expansion curve.
Application:
End-use segmentation tracks divergent regulatory exposure and installation labor economics across utility sectors.
- Telecommunications:FCC broadband equity programs channel polymer hand hole procurement toward rural connectivity gaps. Fiber-optic deployers prioritize corrosion resistance and manual installability over load ratings.
- Electrical Distribution:Grid hardening mandates in the Southeast concentrate demand for medium and large configurations with AASHTO H-20 certification. State DOT prequalification programs filter vendor eligibility.
- Water Management:EPA Clean Water Act specifications tighten material compliance for stormwater access chambers. Precast concrete dominates where soil pressure and traffic loads converge.
- Drainage Systems:Municipal drainage departments specify fiberglass and polymer variants for chemical resistance in sanitary sewer environments. Installation weight reduction drives procurement in constrained urban rights-of-way.
Electrical distribution commands the largest procurement volumes; telecommunications generates the most rapid specification shifts.
Size:
Dimensional segmentation reflects cable density requirements and equipment clearance needs across infrastructure generations.
- Small:Residential service drops and valve access points. Manual installability dominates procurement criteria in urban trenching constraints.
- Medium:Standard electrical distribution vaults and fiber splice enclosures. Southeast utility hardening programs concentrate procurement in this tier.
- Large:Transformer enclosures and main cable junctions. AASHTO H-20 load ratings are mandatory for roadway-adjacent deployments.
- Extra Large:5G fiber distribution hubs and smart-grid transformer enclosures requiring expanded internal clearance for cable management and ventilation. Limited incumbent competition creates specification gaps.
Medium and large sizes generate baseline procurement volumes; extra-large configurations are climbing the fastest as fiber hub scaling accelerates.
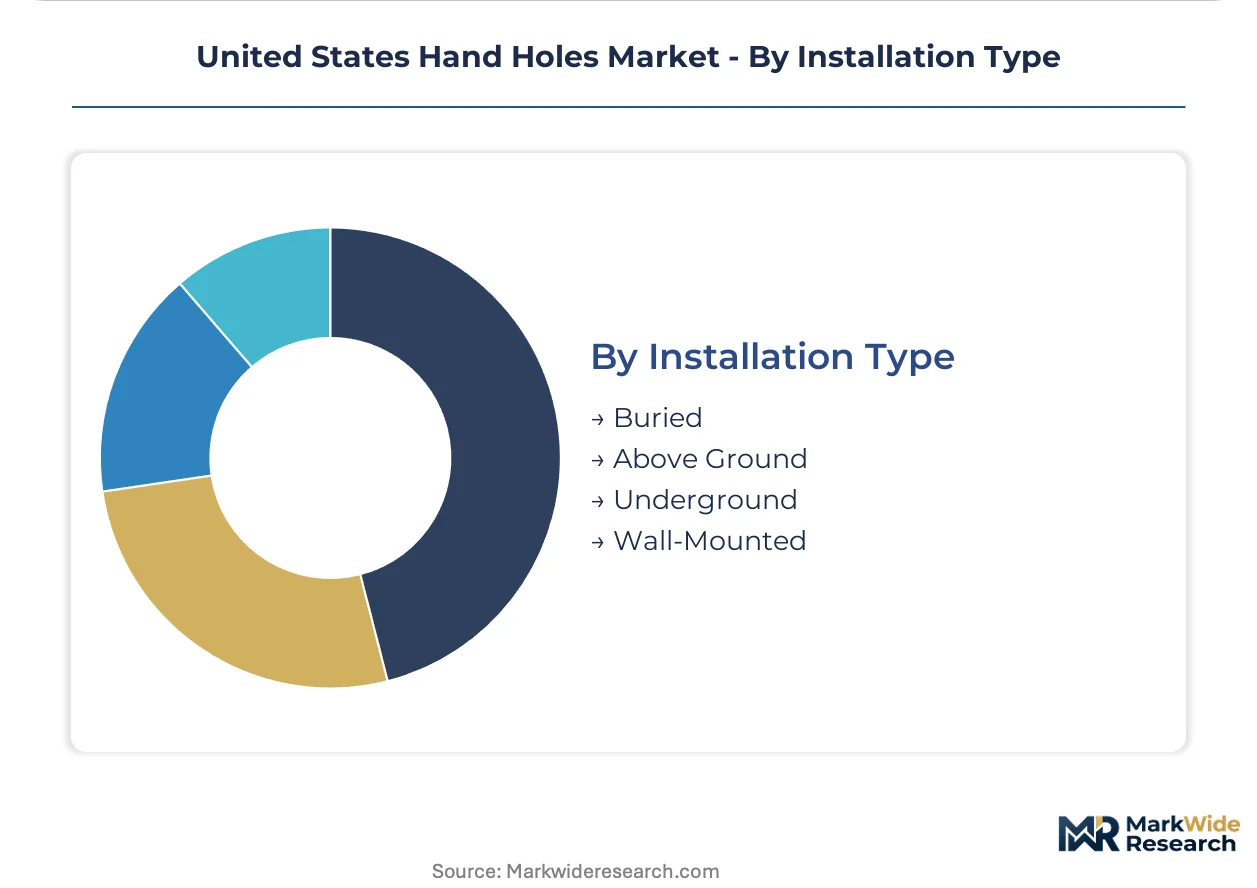
Installation Type:
Deployment method segmentation tracks labor cost structures and site constraint profiles across urban and rural project types.
- Buried:Standard trench deployment for electrical and telecommunications infrastructure. OSHA excavation safety requirements mandate shoring-compatible dimensions.
- Above Ground:Airport obstruction-lighted vaults and flood-prone electrical installations. FAA lighting standards and FAA certification burdens filter supplier eligibility.
- Underground:Dense urban rights-of-way requiring minimal surface disruption. Trenchless installation methods converge with modular polymer system designs.
- Wall-Mounted:Building-integrated utility access in commercial and industrial facilities. Limited penetration outside specialized architectural specifications.
Buried installation dominates project volume; underground methods are gaining share fastest in constrained metropolitan corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows of polymer resins and ductile iron castings shape regional supply security, while export activity remains minimal given the infrastructure-bound nature of hand hole products. Domestic production clusters concentrate where utility procurement cycles and broadband deployment programs overlap.
Southeast
Florida and Georgia utility contractors drive polymer hand hole procurement for coastal corrosion zones requiring AASHTO H-20 compliance. FCC broadband equity programs channel fiber-optic infrastructure funding through rural connectivity gaps in Alabama and Mississippi. Atlanta anchors regional distribution networks serving electrical grid hardening projects across the Carolinas.
Southwest
Texas DOT prequalification programs filter vendor eligibility for medium and large concrete vault specifications along Interstate corridors. EPA Clean Water Act enforcement tightens material compliance for stormwater access chambers in Dallas-Fort Worth metroplexes. Houston petrochemical corridors supply polyethylene resin for rotational-molded systems deployed in Permian Basin oilfield telecommunications.
Midwest
Illinois and Ohio municipal electrical utilities sustain demand for precast concrete transformer enclosures with legacy cast iron integration requirements. OSHA excavation safety mandates reshape procurement specifications in Chicago urban trenching constraints. Detroit-area foundry capacity serves ductile iron casting demand during Michigan grid modernization surges.
West
California fiber-optic deployers specify lightweight polymer systems for seismic-zone installation weight reduction. FAA obstruction lighting standards govern airport-adjacent vault procurement around Los Angeles and San Francisco international hubs. Pacific Northwest hydroelectric utilities drive extra-large hand hole specifications for substation cable management.
Northeast
New York and Massachusetts broadband programs prioritize expedited trench deployment in dense urban rights-of-way. Buy America domestic content thresholds filter federally subsidized infrastructure procurement along the Northeast Corridor. Boston-area electrical contractors consolidate vendor relationships around integrated precast and polymer suppliers.
United States Hand Holes Market Competitive Landscape
Concentration sits with vertically integrated precast concrete operators and national polymer molding networks that span multiple state DOT procurement cycles. Regional fabricators without captive production capabilities face narrowing bid eligibility on bundled infrastructure contracts. Two strategic archetypes dominate: integrated infrastructure conglomerates with backward control over raw material supply, and specialized composite manufacturers focused on corrosion-resistant telecommunications deployment. Competitive moves center on portfolio diversification across material classes and geographic expansion through distribution partnerships.
Among national-scale operators, Oldcastle Infrastructure exemplifies the integrated precast archetype with captive concrete operations, while Quazite occupies a position representing rotational-molded polymer specialization. EJ Group anchors the metal casting tier with foundry-based production capabilities. These three entities collectively illustrate the material-based segmentation that structures vendor selection across electrical distribution, telecommunications, and water management end uses.
| Leading Market Players |
|---|
| Quazite |
| EJ Group |
| Oldcastle Infrastructure |
| Concast |
| Garden State Precast |
| Hubbell Power Systems |
| A.C. Miller Concrete Products |
| Utility Concrete Products |
| Jensen Precast |
| Others |
Value Network & Pricing Analysis
Polyethylene resin substitution for traditional concrete formulations is redrawing procurement geography across the Southeast and Southwest while compressing installed-cost spreads between standard and premium specification tiers. This material transition simultaneously concentrates molding capacity near Houston petrochemical corridors and fragments precast concrete pricing power among regional DOT-qualified fabricators.
Pricing Analysis
The customization-premium spread separates configured-to-order polymer systems from standard concrete vault specifications by roughly forty percent at the project level. Three-tier pricing structure across premium, standard, and economy levels tracks AASHTO load certification and EPA stormwater compliance tiers rather than raw material grades alone. Pricing pressure stems from FCC broadband program procurement compression, which favors rapid-deployment polymer configurations over curing-dependent concrete alternatives. Municipal electrical utilities exhibit lowest price sensitivity due to DOT prequalification lock-in, while rural telecommunications contractors maximize volume discounts on standardized polymer trench boxes.
Supply Chain Analysis
The United States anchors rotational-molded polymer production for telecommunications hand holes, while Mexico and Canada supply precast concrete vault components for electrical distribution applications. Raw material flows draw from Houston-area polyethylene resin production, Detroit-region ductile iron foundry capacity, and regional cement sourcing tied to state DOT qualification zones. Tariff exposure on Canadian precast imports creates supply bottlenecks during Southeast grid hardening surges. Distribution runs through integrated infrastructure conglomerates with captive molding and concrete operations rather than independent distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fewer than fifteen domestic suppliers possess simultaneous FCC broadband certification, AASHTO H-20 load rating, and EPA stormwater compliance documentation. This credential scarcity concentrates bid eligibility and extends contract tenures for qualified incumbents.
For Market Incumbents: Fortify compliance documentation services as a recurring revenue layer, embedding Buy America threshold verification into standard contract terms. Expand captive polyethylene molding capacity in Texas to offset resin price volatility exposure. Defensive positioning requires preemptive certification investment before FCC program waves redirect procurement specifications. For New Entrants and Emerging Players: Anchor in extra-large hand hole configurations for 5G fiber distribution hubs, where limited incumbent competition creates specification gaps. Target Pacific Northwest hydroelectric utility substation deployments requiring expanded cable management clearance. Go-to-market execution should emphasize modular polymer system designs compatible with trenchless urban installation methods. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional precast operators lacking polymer molding capabilities or FCC program eligibility. Five-to-ten year viability hinges on material diversification across concrete and composite production platforms. The signal to watch is FCC broadband funding reauthorization levels, which determine telecommunications segment procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyethylene Resin Sourcing | Houston petrochemical corridor proximity secures supply priority during refinery capacity constraints. |
| Modular Polymer System Development | Stackable designs align with OSHA shoring requirements and compress urban trench crew sizes. |
| Buy America Compliance Documentation Services | Federally subsidized infrastructure projects require verified domestic content threshold reporting. |
| Extra-Large Configuration Capacity Addition | 5G fiber hub scaling creates underpenetrated specification tiers with limited competition. |
| State DOT Prequalification Expansion | Southeast procurement concentration demands multi-state eligibility for bundled infrastructure contracts. |
Research Methodology
The analysis maps polymer composite, precast concrete, fiberglass, and ductile iron hand hole sub-sectors, each validated through utility procurement managers, telecommunications contractors, state DOT specification engineers, and polymer molding operations directors. Primary interview intelligence combined with secondary validation from EPA enforcement databases, FCC broadband funding disclosures, AASHTO load rating registries, and state procurement records. Bottom-up project pipeline assessment triangulates against top-down infrastructure spending allocation models.
Consistency checks validated volume and value outputs against utility capital expenditure disclosures, DOT letting data, and telecommunications infrastructure deployment tracking across the projection horizon. Segmentation dimensions modeled include material performance class, end-use regulatory exposure, dimensional specification tier, and installation method constraint. CAGRs were derived from infrastructure spending trajectory alignment with material substitution elasticity estimates, incorporating resin price volatility indices and foundry capacity utilization as industry-specific forecast inputs.
Material uncertainties — FCC program reauthorization delays, EPA stormwater enforcement intensity shifts, polyethylene refinery capacity constraints — sit outside the modeled envelope. Forecasts reflect assumptions documented in infrastructure spending authorization language and regulatory compliance timeline precedents. Recalibration cycles align with material shifts in federal broadband equity funding allocation and state-level grid hardening appropriation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Retractable Lift Market
Material Handling Equipment
High-Density Racks Market
Material Handling Equipment
Container Handler Market
Material Handling Equipment
North America Screw Conveyor Market
Material Handling Equipment
Global Forklift Market
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
Global Hopper Loader Market
Material Handling Equipment
High Pressure Grinding Rollers Market
Material Handling Equipment
Reach Trucks Market
Material Handling Equipment
Hydraulic Hose Market
Material Handling Equipment
Bulk Material Handling System Market
Material Handling Equipment
Light Duty Telehandler Market
Material Handling Equipment
Automatic Conveyor Market
Material Handling Equipment
Brazil Forklift Market
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Compactor Market