
 Japan Tequila Market | 2026-2036
Japan Tequila Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Tequila Market Insights
Certified agave spirit sommeliers and mixology-trained bartenders is reorganizing how Japanese consumers experience tequila, moving the category beyond shots toward sipping and cocktail culture. Suntory leverages its domestic distribution muscle to anchor premium tequila placements in upscale Tokyo bars. Patron Spirits competes through sustained investment in bartender education programs across Osaka and Fukuoka. Jose Cuervo dominates the retail shelf with controlled placement in major supermarket chains and dedicated liquor stores.
Tequila is a distilled spirit produced exclusively from fermented blue agave juice, with Mexican Denomination of Origin requiring minimum regional sourcing and specific alcohol content ranging from 35% to 55% ABV, functioning primarily as a base for cocktails and a premium sipping beverage in Japanese on-trade venues. Blanco expressions lead volume as bartenders favor their unaged agave purity for cocktail construction, while Reposado captures expanding margin pools as consumers trade up to oak-rested complexity. The Super Premium price tier is accelerating fastest among retail consumers seeking gifting-grade bottles, though Economy labels still occupy substantial shelf space in suburban liquor stores.
PMDA oversees labeling standards for imported alcoholic beverages, while METI monitors trade compliance under Japan-Mexico economic partnership frameworks, together ensuring product authenticity and shaping import cost structures that filter into final pricing. National Tax Agency liquor tax classifications directly determine excise burdens on agave spirits relative to domestic shochu and whisky, influencing competitive positioning across price tiers. Stakeholders must monitor potential revisions to Japan-Mexico EPA provisions and evolving consumer protection standards around origin claims as the category matures.
Market Dynamics
The National Tax Agency's revised liquor tax framework is compressing import cost structures while simultaneously elevating compliance burdens for agave spirit distributors, forcing a recalibration of pricing tiers across on-trade and retail channels.
Growth Catalysts
- Certified sommelier programs:Bartender education initiatives in Osaka and Fukuoka are accelerating premium tequila adoption beyond Tokyo's core market, expanding geographic penetration.
- METI trade compliance frameworks:Japan-Mexico economic partnership provisions are streamlining import documentation, reducing clearance friction for agave spirits entering Kanto region ports.
- On-trade cocktail experimentation:Premium bars in Greater Tokyo are constructing innovative tequila-based menus, pulling consumer perception away from shot culture toward sipping occasions.
Market Restraints
- Agave supply concentration:Blue agave cultivation clusters in Jalisco, Mexico, creating weather and harvest volatility that transmits directly to Japanese import pricing.
- PMDA labeling standards:Stringent alcoholic beverage documentation requirements impose compliance costs that disproportionately burden smaller import distributors.
- Shochu substitution threat:Domestic Japanese spirits maintain tax-advantaged positioning and cultural familiarity, limiting tequila's household penetration in suburban markets.
Strategic Opportunities
- Kansai region underpenetration:Kyoto and Osaka metropolitan areas show lower tequila consumption intensity than Tokyo, presenting whitespace for targeted on-trade development.
- Super Premium gifting segment:Retail consumers are trading up to oak-rested Reposado expressions for ceremonial occasions, expanding margin pools beyond standard Blanco volumes.
- E-commerce direct channels:Specialized liquor platforms are circumventing traditional supermarket gatekeepers, enabling craft tequila brands to reach educated consumers directly.
Industry Challenges
- Agave spirit sommelier scarcity:Trained personnel capable of guiding consumers through terroir and production method distinctions remain concentrated in Tokyo, constraining category elevation elsewhere.
- Denominación de Origen verification:Authenticity documentation requirements create compliance timeline friction for importers sourcing from smaller Mexican producers outside Jalisco's core zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Tequila Market |
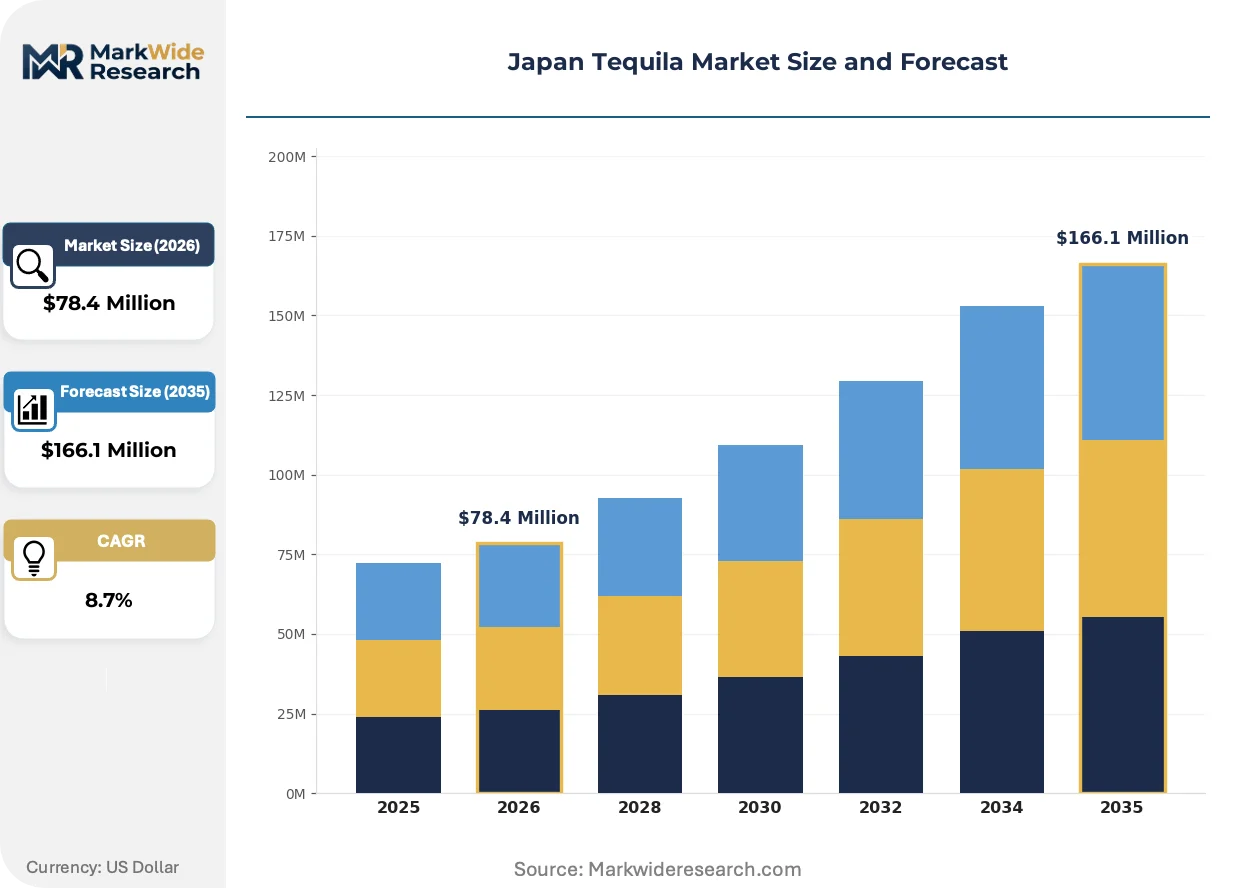
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $166.1 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blanco, Reposado, Añejo, Extra Añejo Customer Type: Retail Consumers, Bars, Restaurants, Hotels Distribution Channel: Online, Supermarkets, Liquor Stores, Duty-Free Shops Price Tier: Premium, Super Premium, Value, Economy |
| Companies Covered | Suntory, Patron Spirits, Jose Cuervo, Campari Group, Don Julio, Diageo, Brown-Forman, Constellation Brands, Pernod Ricard, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Tequila Market Trends and Innovations
Japanese tequila consumption is fragmenting across occasion types, with bartenders and retail buyers pursuing divergent quality signals that reshape how brands configure their portfolio and channel strategies.
Small-batch ceramic still distillation is miniaturizing production footprints for craft tequila entrants, enabling micro-lot experimentation that premium Tokyo bars are adopting at accelerating pace. This technology compresses the traditional industrial scale barrier, allowing niche Mexican producers to enter the Japanese market without massive capital deployment.
PMDA labeling standards for imported alcoholic beverages are tightening origin claim documentation, forcing distributors to reconstruct supply chain transparency from agave field to bottle. Super Premium retail SKUs face the steepest compliance adjustment as gifting consumers demand verifiable provenance credentials.
Consumption occasions are bifurcating sharply between on-trade cocktail construction and off-trade ceremonial gifting, with minimal overlap in purchase behavior. Bartenders prioritize unaged Blanco purity for mixology, while retail buyers seek oak complexity for presentation, forcing brand portfolios to maintain dual quality narratives without cannibalization.
Japan Tequila Market Segmentation
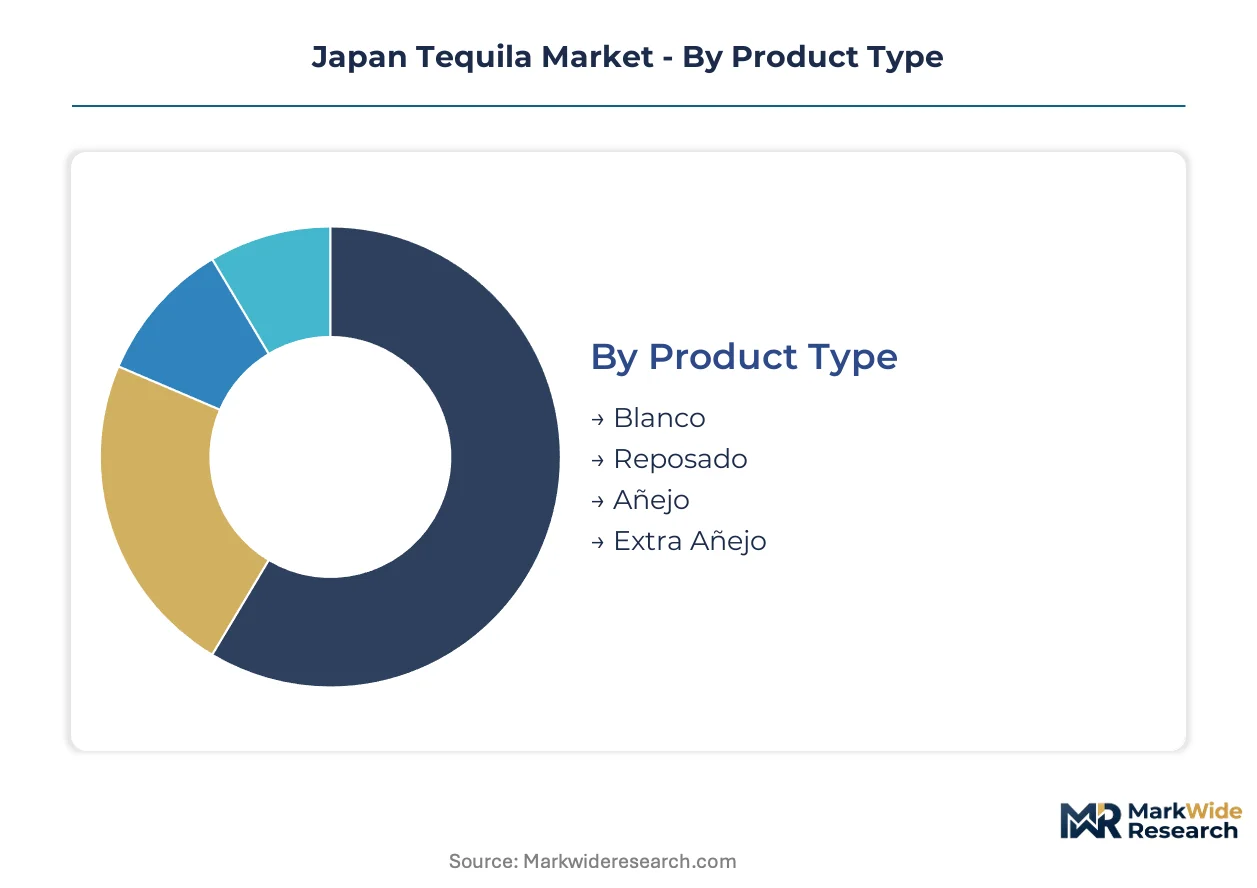
Japan's tequila market fragments across four distinct dimensions, each revealing how agave spirits navigate domestic distribution constraints and import-dependent supply chains. Understanding these splits exposes where pricing power concentrates and which channels resist premiumization.
Product Type:
Domestic consumption patterns favor unaged expressions that travel directly from Jalisco stills to Tokyo bars without extended warehouse rests, while aged categories serve ceremonial retail occasions demanding oak complexity.
- Blanco:Unaged tequila bottled immediately after distillation preserves raw agave character with zero wood interference. Bartenders across Greater Tokyo prioritize this expression for cocktail construction, driving volume through on-trade channels where purity commands technical respect.
- Reposado:Oak-rested for two to eleven months, this tier bridges mixology utility and sipping sophistication. Consumers in Osaka and Kyoto are trading up to Reposado for home consumption, expanding margin pools as gifting occasions multiply.
- Añejo:One to three years of barrel aging develops caramel and vanilla depth for dedicated sipping. Limited distribution concentrates in upscale Tokyo liquor stores serving collectors.
- Extra Añejo:Extended aging beyond three years produces ultra-premium expressions with whiskey-like complexity. Minimal volume reflects extreme scarcity and import cost barriers.
Blanco commands the established base. The steepest expansion runs through Reposado.
Customer Type:
Cost tier stratification separates high-frequency on-trade purchasers from low-frequency retail buyers seeking presentation-grade bottles for specific social rituals.
- Bars:Premium cocktail lounges in Tokyo's Shibuya and Ginza districts drive Blanco volume through rapid inventory turnover and menu innovation. Bartender education investments by distributors reinforce technical loyalty to specific agave profiles.
- Restaurants:Mexican and Latin American dining concepts in Osaka and Fukuoka incorporate tequila into beverage programs, though penetration lags Tokyo intensity. Margarita-centric programs dominate over sipping presentations.
- Retail Consumers:Individual purchasers seeking gifting or home consumption gravitate toward Reposado and Añejo expressions. E-commerce platforms are capturing educated buyers bypassing traditional supermarket gatekeepers.
- Hotels:International properties in Roppongi and Marunouchi maintain curated agave selections for foreign guests, with limited influence on domestic taste formation.
Bars anchor volume throughput. Retail Consumers are climbing the fastest toward margin-rich aged expressions.
Distribution Channel:
Volume concentration favors physical retail where PMDA labeling compliance is standardized, while digital channels fragment around specialized knowledge communities.
- Liquor Stores:Dedicated alcohol retailers in Tokyo and Osaka maintain the broadest agave spirit selections, with certified staff guiding consumers through Denominación de Origen verification. METI import documentation requirements are streamlined for established retail distributors.
- Supermarkets:Major chains stock economy and value-tier expressions with limited aged inventory, prioritizing Jose Cuervo and similarly scaled brands with national marketing support.
- Online:Specialized liquor platforms circumvent traditional shelf-space constraints, enabling craft Mexican producers to reach educated Kanto consumers directly. PMDA labeling standards create compliance friction for smaller entrants.
- Duty-Free Shops:Narita and Haneda airport retail captures foreign traveler demand with limited spillover into domestic consumption patterns.
Liquor Stores control the established base. Online channels are gaining share fastest among premium-seeking consumers.
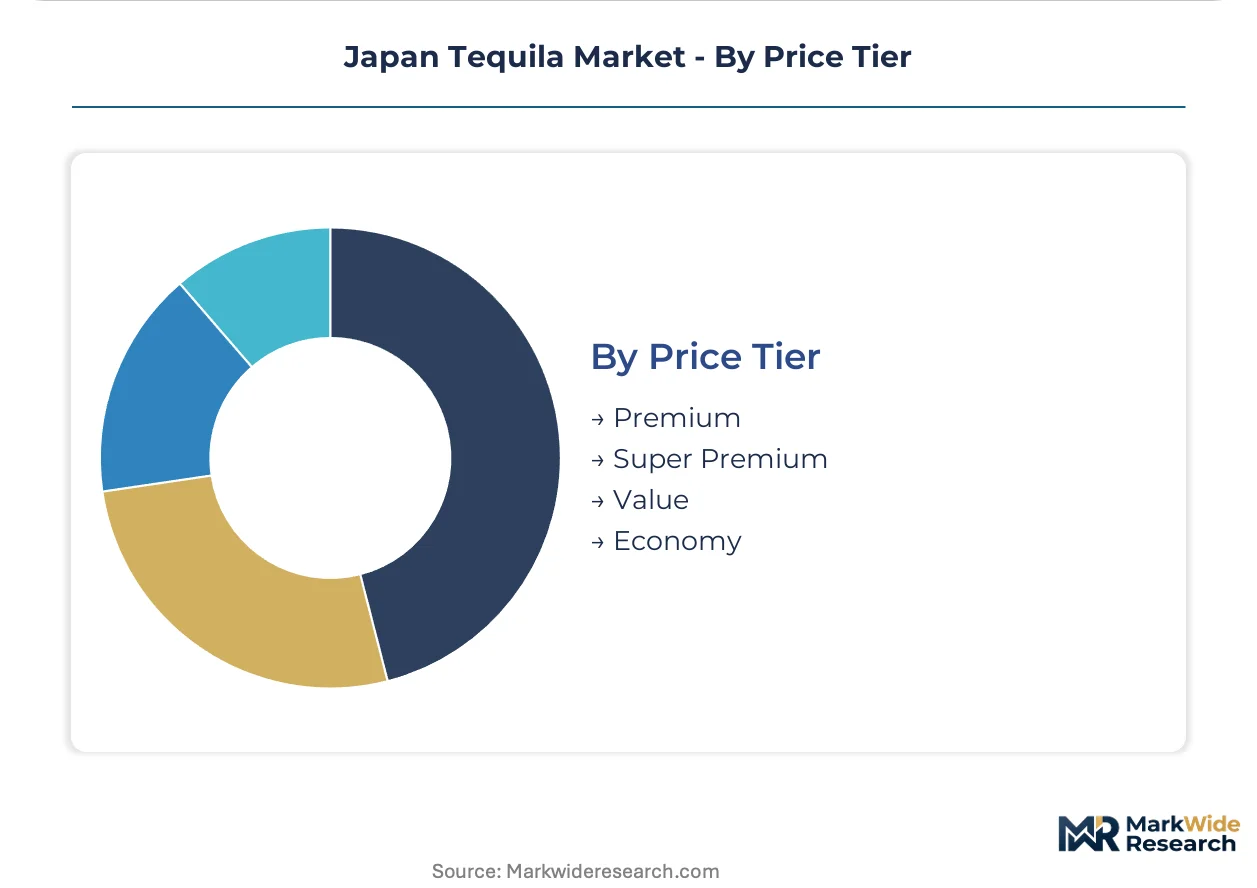
Price Tier:
Margin structure concentrates in super premium expressions where agave sourcing transparency and production method storytelling justify elevated price positioning.
- Super Premium:Small-batch and single-estate expressions command gifting-grade pricing through verified provenance narratives. Consumers in Greater Tokyo seek these bottles for ceremonial presentation.
- Premium:Established brands with consistent quality and recognizable labeling occupy stable retail shelf positions across Kanto supermarkets and liquor stores.
- Value:Entry-level 100% agave expressions compete with domestic shochu on price while maintaining regulatory compliance for restaurant and bar procurement.
- Economy:Mixto tequilas and value-priced 100% agave labels dominate suburban liquor store volume, constrained by shochu substitution and limited consumer education.
Economy labels command the established base. Super Premium is climbing the fastest as gifting occasions multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese tequila consumption fragments sharply across metropolitan corridors, with Greater Tokyo driving on-trade cocktail sophistication while regional centers lag in agave spirit penetration. Kansai consumers favor ceremonial gifting formats that diverge from Tokyo's bar-centric volume model.
Kanto/Tokyo
Shibuya and Ginza cocktail lounges anchor Japan's highest tequila throughput, where certified sommeliers guide consumers through single-estate expressions. METI import documentation streamlines clearance through Yokohama and Tokyo ports, reducing distributor friction. National Tax Agency liquor tax classifications here shape national pricing benchmarks that filter outward to secondary markets.
Kansai/Osaka
Osaka's beverage programs emphasize Margarita-centric formats over sipping presentations, creating demand for value-tier Blanco expressions. PMDA labeling standards impose uniform compliance costs that burden smaller Kansai distributors relative to Tokyo-scale operators. Dotonbori entertainment districts concentrate on-trade volume, though bartender education investments by Patron Spirits are expanding premium penetration.
Chubu/Nagoya
Nagoya's manufacturing-affluent consumer base shows emerging interest in Super Premium gifting formats for business entertainment. METI monitors trade compliance under Japan-Mexico EPA frameworks that determine landed costs for Chubu-based importers. Sakae district hotels and international restaurants maintain curated selections, with limited domestic taste formation influence.
Kyushu/Fukuoka
Fukuoka's proximity to Asian transit routes positions it as an emerging testbed for craft tequila distribution outside Tokyo's saturated channels. Bartender education programs sponsored by international distributors are accelerating premium adoption beyond traditional shot culture. Tenjin entertainment quarters show faster Super Premium growth than comparable-sized Chubu metros.
Hokkaido
Sapporo's winter tourism economy creates seasonal demand spikes through duty-adjacent retail and hotel bars serving international visitors. Domestic shochu substitution pressure intensifies in Hokkaido's suburban liquor stores, constraining tequila household penetration. Suntory leverages its domestic distribution muscle to maintain shelf presence despite lower per-capita consumption intensity.
Japan Tequila Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational spirits conglomerates controlling retail shelf space while craft distributors carve on-trade niches. The structure favors portfolio breadth over single-category depth, as cross-promotional leverage with whisky and vodka lines reduces customer acquisition costs. Three archetypes dominate: diversified global houses with Japanese distribution partnerships, Mexico-origin specialists pursuing bartender education investments, and domestic beverage giants leveraging existing retail relationships. Competitive moves concentrate on strategic partnerships with Kanto region bar chains and portfolio diversification into aged expressions that capture gifting margins.
Among diversified global houses, Diageo and Pernod Ricard occupy positions defined by cross-category promotional infrastructure and existing relationships with Japanese retail gatekeepers. Suntory anchors the domestic tier, exemplifying how Japanese beverage conglomerates leverage established distribution networks to secure premium placements without direct agave sourcing exposure. Patron Spirits represents the specialist archetype, sitting within the Mexico-origin tier where sustained bartender education investments in Osaka and Fukuoka expand geographic penetration beyond Tokyo's core market.
| Leading Market Players |
|---|
| Suntory |
| Patron Spirits |
| Jose Cuervo |
| Campari Group |
| Don Julio |
| Diageo |
| Brown-Forman |
| Constellation Brands |
| Pernod Ricard |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Jalisco-based agave growers and Japanese import distributors lock in multi-year supply access while providing price visibility that buffers against harvest volatility in Mexico's central highlands. These contractual structures concentrate procurement leverage among established Tokyo distributors with established National Tax Agency clearance relationships, forcing smaller Kansai operators into spot-market exposure.
Pricing Analysis
Contract-based long-term offtake dominates Super Premium tier procurement, with pricing stratifying across premium, standard, and economy tiers based on agave sourcing transparency and barrel-aging duration. Price differentiation centers on Denominación de Origen verification costs and certified sommelier-guided placement in Ginza cocktail lounges. Cost compression in Economy labels intensifies as domestic shochu substitutes exploit tax-advantaged positioning. Retail consumers seeking gifting-grade Reposado expressions demonstrate lowest price sensitivity, while suburban liquor store shoppers in Hokkaido exhibit acute responsiveness to shochu-tequila price spreads.
Supply Chain Analysis
Mexico anchors blue agave cultivation with secondary processing concentration in Guadalajara industrial zones before ocean freight consolidation at Manzanillo and Lázaro Cárdenas ports. Raw material dependencies encompass mature agave piñas, American white oak barrels for Reposado aging, and ceramic still components for craft micro-lot entrants. Single-source vulnerability concentrates in Jalisco's weather-exposed harvest cycles, where drought or frost transmits directly to Japanese import pricing. Distribution runs through Yokohama and Tokyo port clearance facilities before channeling into licensed liquor stores and specialized e-commerce platforms serving Greater Tokyo's educated consumer base.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japanese tequila consumption fragments across occasion types, with bartender-guided on-trade experimentation and ceremonial retail gifting creating distinct competitive arenas that favor specialized positioning over portfolio breadth.
For Market Incumbents: Consolidate bartender education investments in Osaka and Fukuoka to preempt craft distributor encroachment beyond Tokyo's saturated core. Deepen backward integration into Jalisco agave sourcing through direct estate partnerships, securing supply priority before smaller entrants establish contractual footholds. Channel control through certified sommelier placement programs defends margin position against supermarket price wars. For New Entrants and Emerging Players: Bartender certification gaps in Kyoto and Nagoya present whitespace for education-first market entry strategies bypassing Suntory's retail gatekeeper relationships. Target Kansai's underdeveloped sipping culture through ceramic still micro-lot positioning that commands technical respect from mixology-trained bar staff. Direct-to-consumer e-commerce platforms circumvent PMDA compliance burdens that disproportionately burden smaller import distributors. For Investors and Strategic Acquirers: Capital is best deployed toward craft distributors with established Jalisco producer networks and certified agave spirit sommelier training infrastructure. Long-term viability hinges on portfolio diversification into oak-rested expressions capturing gifting margin expansion. Monitor National Tax Agency liquor tax revision announcements as inflection indicators for import cost structure shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Bartender Education Program Expansion | Patron Spirits demonstrates how Osaka and Fukuoka investments accelerate premium adoption beyond Tokyo. |
| Direct Estate Sourcing Partnership | Single-estate agave contracts provide Denominación de Origen verification for Super Premium gifting positioning. |
| E-commerce Platform Development | Specialized liquor platforms bypass supermarket gatekeepers to reach educated Kanto consumers directly. |
| Ceramic Still Micro-lot Introduction | Small-batch production technology enables craft entrants to enter Japan without massive capital deployment. |
| Certified Sommelier Placement Network | Technical staff concentration in Tokyo bars elevates consumer perception toward sipping occasions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of National Tax Agency liquor tax classifications, METI trade compliance documentation, and PMDA labeling standards for imported alcoholic beverages. Primary interviews encompassed agave spirit import distributors, certified sommeliers at Ginza cocktail lounges, liquor store procurement managers across Kanto and Kansai, and Mexican producer export directors. Secondary validation drew from customs clearance records, Japan-Mexico EPA provision texts, and retail audit data from Tokyo and Osaka metropolitan markets. Bottom-up volume estimates from on-trade channel checks triangulate against top-down market sizing from excise tax revenue flows.
Segmentation dimensions modeled span product type, customer type, distribution channel, and price tier across the analysis window. The analytical framework projects value expansion by mapping Blanco volume concentration in Greater Tokyo bars against Reposado margin growth in Kansai retail gifting. CAGRs derive from import volume trajectories at Yokohama and Tokyo ports, cross-referenced with certified sommelier program expansion rates and e-commerce platform transaction data. Agave harvest cycle volatility and National Tax Agency excise adjustments feed into scenario-weighted projections.
Underlying assumptions cover stable Japan-Mexico EPA provisions and sustained Kanto on-trade experimentation, with deviation risk concentrated in Jalisco weather disruptions and shochu tax advantage revisions. Forecasts reflect these conditions without claiming predictive certainty. Recalibration cycles align with material shifts in National Tax Agency liquor tax frameworks and METI import documentation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
United States Tequila Market
Alcoholic Beverages
US Frozen Cocktail Popsicles Market
Alcoholic Beverages
Kegs Market
Alcoholic Beverages
Citrus Alcohol Market
Alcoholic Beverages
Beer Stabilizers Market
Alcoholic Beverages
Alcohol Gummies Market
Alcoholic Beverages
Low Alcohol Beverages Market
Alcoholic Beverages
Pinot Meunier Market
Alcoholic Beverages
South America Alcoholic Beverages Market
Alcoholic Beverages
Whiskey Market
Alcoholic Beverages
India Alcohol Market
Alcoholic Beverages
UK Tequila Market
Alcoholic Beverages
Grain Neutral Spirits Market
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
Premium Spirit Market
Alcoholic Beverages
Beer Cans Market