
 Kegs Market | 2026-2036
Kegs Market Size, Share, and Industry Trends Forecast 2026-2036
Kegs Market Analysis
Stainless steel is expanding its dominance in premium beverage logistics while aluminum challenges it in weight-sensitive shipping lanes. Blefa GmbH anchors German engineering standards across European brewing supply chains. THIELMANN The Container Company specializes in stainless-steel ISO tank innovations that extend into keg-adjacent formats. American Keg Company dominates domestic U.S. manufacturing with captive steel sourcing and Midwest fabrication.
A keg is a cylindrical container, historically steel, now also aluminum, plastic, or glass, engineered to hold, transport, and dispense pressurized beverages under carbonation; standard capacities range from five to nearly sixty liters, with valve and spear mechanisms designed for repeated filling, cleaning, and tapping cycles. Stainless steel commands the material segment due to durability and flavor neutrality in craft beer handling, while plastic PET variants represent the fastest-expanding niche as breweries seek one-way export solutions that eliminate reverse logistics. The end-user split shows bars sustaining baseline volume, restaurants demanding compact sixth-keg formats for space-constrained installations, and events driving seasonal spikes that favor disposable or deposit-light alternatives.
The U.S. FDA governs food-contact materials for beverage containers, while EPA rules on steel and aluminum manufacturing emissions shape domestic sourcing economics; in Europe, REACH chemical restrictions and the F-Gas Regulation on cooling compressors indirectly steer keg fleet specifications through supply-chain carbon accounting. Stakeholders must monitor how deposit-return schemes and extended producer responsibility laws in multiple jurisdictions will restructure ownership models between breweries, leasing pools, and container manufacturers.
Market Dynamics
The keg market is being restructured by the tension between reusable stainless-steel fleets and single-use PET alternatives, with Germany's national packaging regulator forcing circular-economy compliance that elevates deposit-return schemes over one-way exports. This regulatory pressure is compressing profit margins for breweries that lack pooling infrastructure while rewarding logistics platforms that control reverse supply chains.
Growth Catalysts
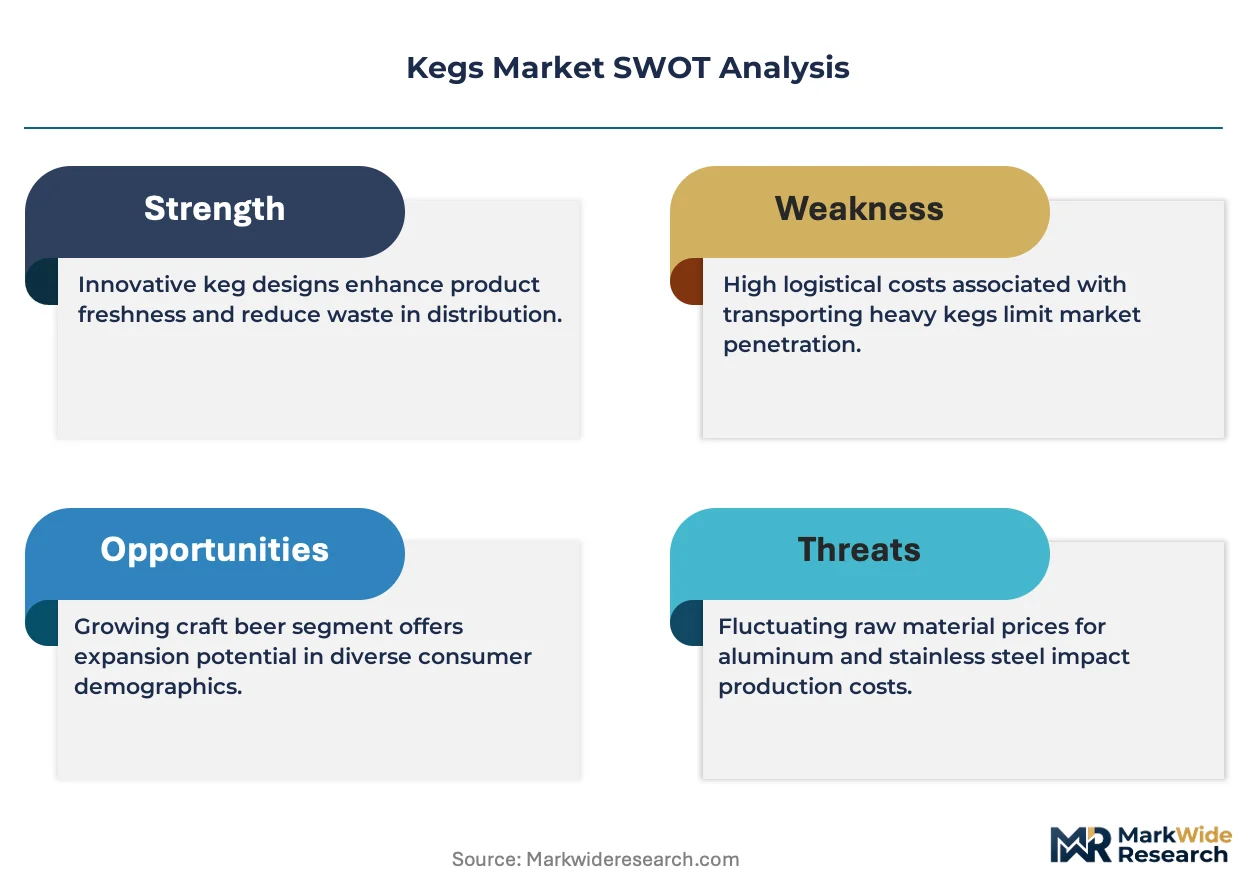
- REACH chemical restrictions:Europe's tightening food-contact material standards are disqualifying lower-grade aluminum alloys, pushing craft breweries toward certified stainless-steel sourcing that extends keg lifecycle durability.
- Keg pooling services:Third-party logistics platforms in the United States are consolidating fragmented brewery fleets into centralized asset pools that reduce per-unit handling costs and accelerate tap-to-tap turnaround.
- Polyethylene terephthalate (PET) variants:Lightweight plastic kegs are penetrating export-heavy craft segments where reverse logistics costs exceed container depreciation, particularly for seasonal and limited-release distribution.
Market Restraints
- Steel price volatility:Input cost swings for cold-rolled stainless are compressing fabrication margins at Midwest U.S. manufacturing clusters where captive sourcing agreements have lapsed.
- Supply concentration in German engineering:Precision valve and spear mechanism production clusters around Blefa GmbH's supplier network, creating single-source vulnerability for North American fabricators.
- Aluminum flavor neutrality limitations:Technical performance gaps in long-term acidic beverage contact are restricting aluminum keg penetration beyond cider and sparkling water categories.
Strategic Opportunities
- Underpenetrated Indian craft brewing:Mumbai and Bangalore microbrewery licensing reforms are opening demand for compact sixth-keg formats that fit space-constrained urban taprooms.
- EU Green Deal carbon accounting:Embedded emissions disclosure requirements are creating competitive advantage for breweries with ISO-certified reusable fleets over PET-dependent exporters.
- Smart keg telemetry convergence:Integration of RFID tracking with pressure sensors is enabling usage-based leasing models that unbundle asset ownership from beverage supply contracts.
Industry Challenges
- Spear valve technician scarcity:Specialized repair skills for mixed-material keg fleets are concentrating in legacy brewing regions, creating service deserts in emerging craft markets.
- Extended producer responsibility compliance:Multi-jurisdictional deposit-return scheme registration is forcing breweries to maintain parallel fleet tracking systems with incompatible data standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kegs Market |
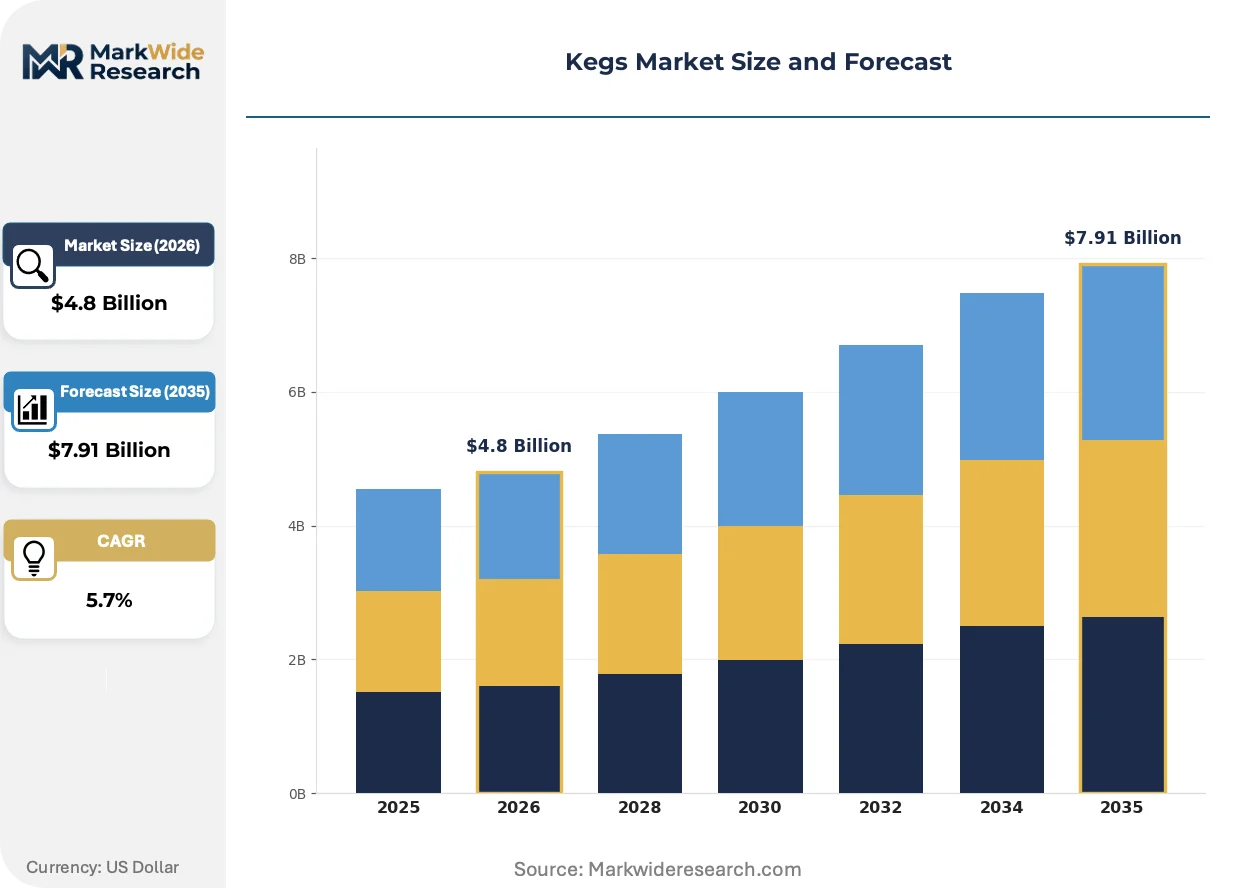
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pony Keg, Half Keg, Quarter Keg, Sixth Keg Material: Stainless Steel, Plastic, Aluminum, Glass End User: Bars, Restaurants, Breweries, Events Size: Small, Medium, Large, Extra Large |
| Companies Covered | American Keg Company, NDL Keg, Blefa GmbH, Shinhan Industrial Co., Ltd., Ningbo BestFriends Beverage Containers Co. Ltd., Schaefer Container Systems, THIELMANN The Container Company, Petainer, Ardagh Group S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kegs Market Emerging Trajectories
Automation of keg washing and inspection lines is compressing labor costs while raising quality thresholds, and regulatory carbon accounting is rewriting procurement specifications across European brewing supply chains. These forces are converging to favor capital-intensive pooling operators over small-scale brewery-owned fleets.
RFID-enabled keg tracking is automating inventory reconciliation across multi-brewery pooling networks. Regional craft alliances in the Pacific Northwest are deploying these systems to eliminate manual yard counts and accelerate damage attribution. The technology is automating settlement disputes between breweries and logistics providers that previously consumed quarterly reconciliation cycles.
The F-Gas Regulation on cooling compressors is reshaping keg fleet specifications through indirect carbon accounting pressure. Breweries must now document refrigerant leakage rates across their entire cold chain, including leased keg storage. This policy is compressing demand for aluminum variants with higher thermal conductivity requirements that conflict with energy-efficient cooling systems.
Leasing is displacing ownership in craft brewery procurement patterns, particularly among operations founded after 2018. Keg pooling services now handle fill-to-tap logistics for over half of U.S. independent brewery volume, unbundling capital expenditure from production scaling decisions. This shift is most visible in Texas and Colorado, where rapid brewery count expansion has outpaced internal fleet management capabilities.
Kegs Market Segmentation
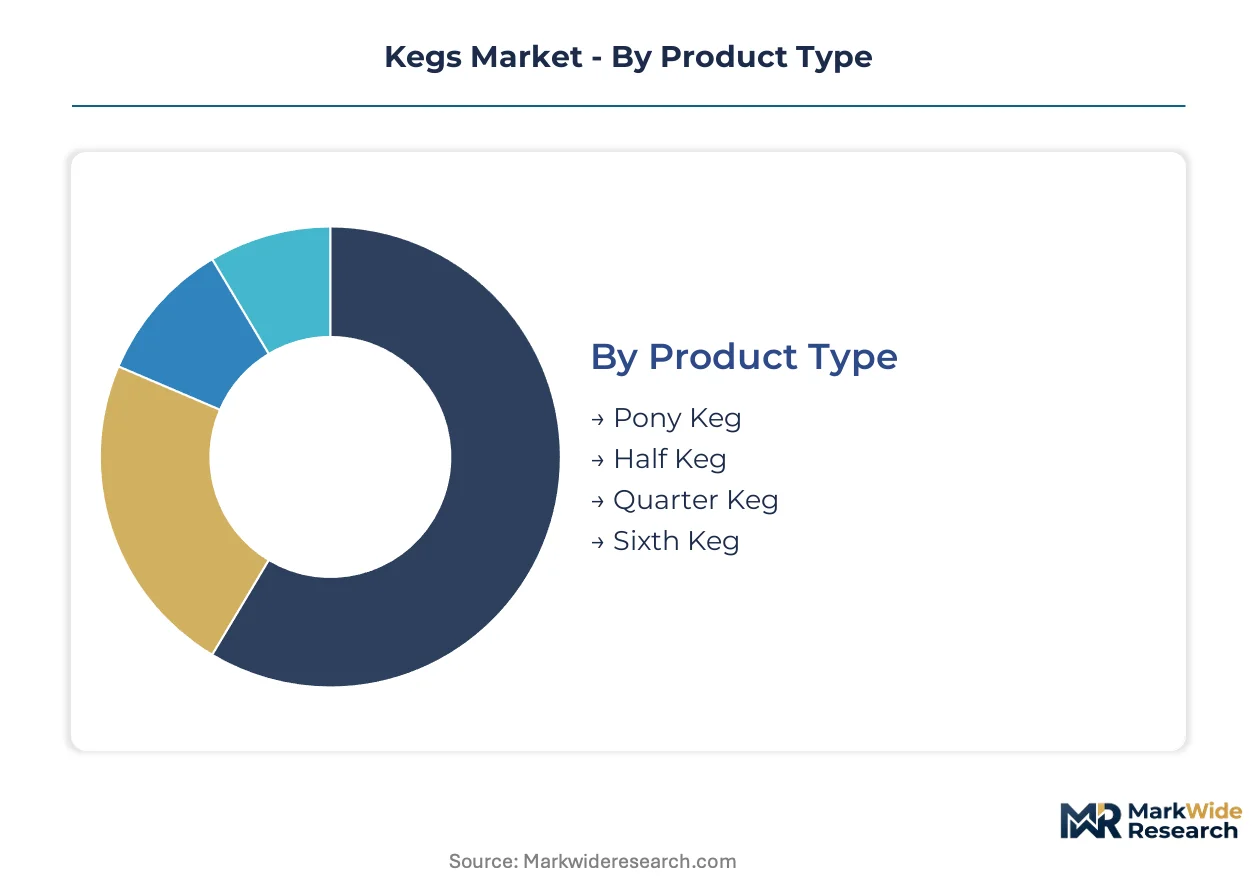
Keg segmentation reveals divergent compliance burdens across material grades and capacity formats. Certification requirements from FDA food-contact rules and EU REACH chemical standards fragment procurement strategies by end-use channel and geographic exposure.
Product Type:
Half Keg and Quarter Keg formats carry FDA food-contact certification requirements for stainless-steel variants sold into U.S. interstate commerce, while Sixth Keg compact formats face lighter documentation loads for intrastate craft distribution.
- Half Keg:The 15.5-gallon industry workhorse constructed from double-walled stainless steel with reinforced chime rings for stacking durability. Demand concentrates in high-volume U.S. sports bars and German beer halls where throughput economics favor standardized 50-liter fills over format flexibility.
- Quarter Keg:7.75-gallon intermediate capacity engineered with identical valve interfaces as Half Keg formats for operational compatibility. Restaurants in space-constrained Manhattan and London districts specify this format to balance per-tap variety against cooler footprint limitations.
- Sixth Keg:Compact 5.16-gallon format with slim-diameter profile for under-counter installations. Mumbai microbreweries license these for urban taprooms with sub-100-seat capacity limits.
- Pony Keg:Legacy 7.75-gallon naming variant with identical physical specifications to Quarter Keg; regional terminology persists in Texas and Oklahoma distribution networks.
Leading the category by volume: Half Keg. Growing fastest: Sixth Keg.
Material:
Cost tier stratification separates premium-certified stainless from economy PET variants, with aluminum occupying a narrowing mid-market position constrained by flavor neutrality limitations in acidic beverage contact.
- Stainless Steel:Cold-rolled 304-grade construction with electropolished interiors meeting FDA and EU food-contact standards; Blefa GmbH's German engineering anchors European supply chains. Craft breweries in Colorado and Oregon specify certified sourcing for extended lifecycle durability against acidic IPA contact.
- Plastic:PET blow-molded single-use variants eliminating reverse logistics for seasonal export shipments. German packaging regulator circular-economy quotas compress domestic adoption, forcing PET concentration in transatlantic craft exports from U.S. East Coast ports.
- Aluminum:Drawn-and-ironed construction with polymer interior liners for flavor isolation; thermal conductivity requirements conflict with EU F-Gas Regulation cooling efficiency mandates.
- Glass:Niche heritage format for specialty lambic and wild-fermentation categories requiring oxygen permeability monitoring; fragility restricts deployment to on-premise consumption with deposit-return infrastructure.
Volume concentration: Stainless Steel. Steepest expansion trajectory: Plastic.
End User:
Customer type determines fleet ownership structure, with bars and restaurants leasing through pooling services while breweries retain direct control over export-bound assets.
- Bars:High-frequency tap establishments sustaining baseline stainless-steel fleet utilization through keg pooling agreements; RFID tracking automates inventory reconciliation across multi-brewery networks.
- Restaurants:Space-constrained operators driving Sixth Keg format specification for under-counter cooler installations; procurement shifts toward leasing to unbundle capital expenditure from menu expansion decisions.
- Breweries:Direct fleet ownership for export channels requiring customs documentation control; German and U.S. craft producers maintain parallel tracking systems for incompatible deposit-return scheme registrations.
- Events:Seasonal demand spikes favoring PET disposable formats or deposit-light alternatives; Texas festival circuits and Munich Oktoberfest deployments drive annual procurement cycles.
Dominant volume channel: Bars. Fastest-growing procurement mode: Events.
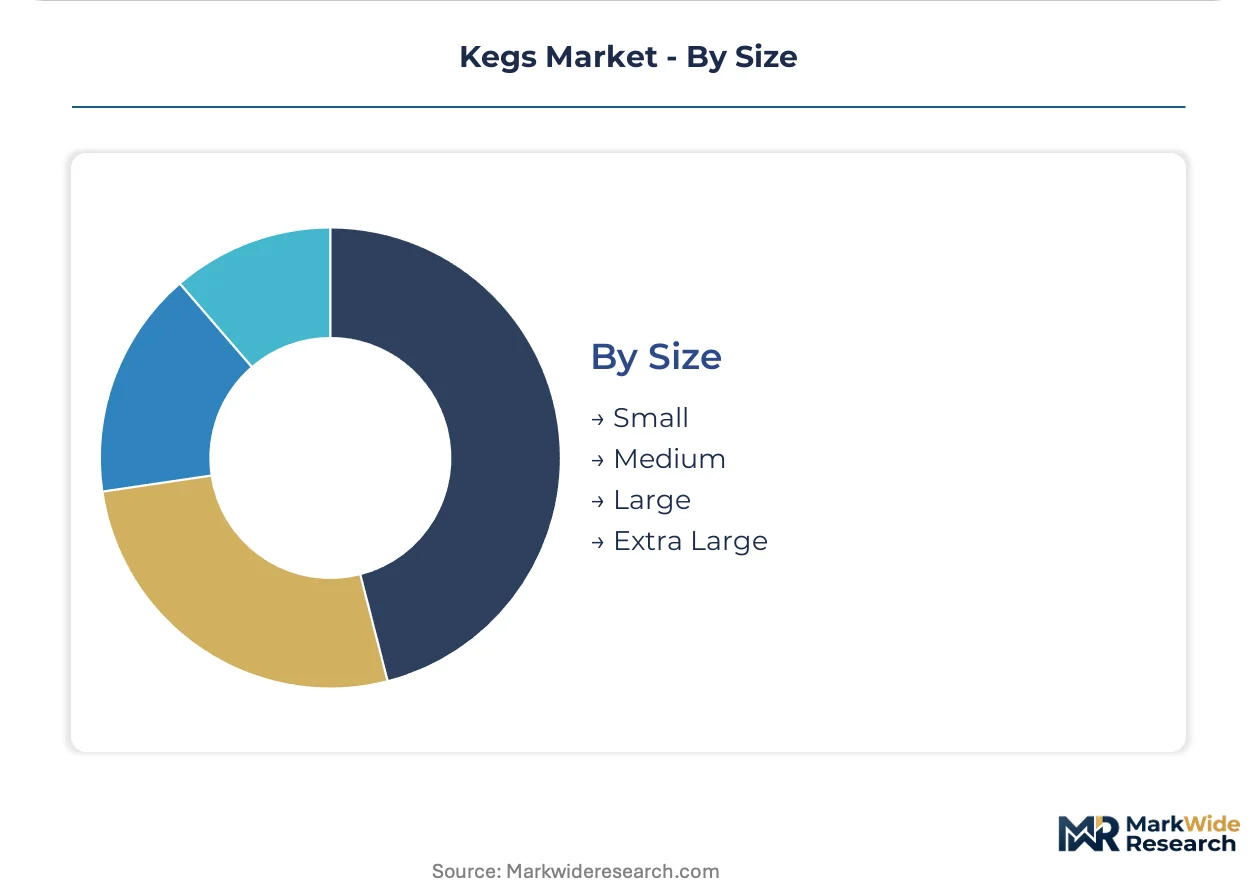
Size:
Physical dimension categories map imperfectly to standardized liter capacities, creating procurement friction between North American gallon-denominated specifications and European metric standards.
- Large:50-liter and 15.5-gallon formats dominating interstate distribution economics; German deposit-return schemes mandate this standard for circular-economy compliance.
- Medium:30-liter and Quarter Keg equivalents serving restaurant chains with standardized cooler footprints across multi-state U.S. operations.
- Small:20-liter and Sixth Keg formats penetrating Indian urban microbreweries under Bangalore and Mumbai licensing reforms.
- Extra Large:58.6-liter Euro barrels and oversized festival formats for high-throughput temporary installations; limited standardization fragments supplier compatibility.
Volume leader: Large. Gaining share fastest: Small.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Special Economic Zone policy for beverage packaging has concentrated PET keg manufacturing near Mumbai port facilities, drawing craft brewery procurement from Southeast Asian export markets.
United States
Independent brewery counts in Texas and Colorado have multiplied since 2018, overwhelming internal fleet management capabilities. EPA rules on steel manufacturing emissions shape domestic sourcing economics for Midwest fabricators. Keg pooling services in the Pacific Northwest now deploy RFID tracking to automate inventory reconciliation across multi-brewery networks.
Germany
Blefa GmbH's precision valve production anchors European supply chains for stainless-steel formats. The national packaging regulator enforces circular-economy return quotas that favor reusable container formats over one-way exports. Bavarian beer halls sustain standardized 50-liter fill demand where throughput economics dominate format selection.
India
Mumbai and Bangalore microbrewery licensing reforms are opening demand for compact sixth-keg formats that fit space-constrained urban taprooms. FSSAI food-contact material standards govern beverage container imports. Maharashtra-based taprooms under 100-seat capacity limits specify slim-diameter profiles for under-counter installations.
China
Ningbo manufacturing clusters supply blow-molded PET variants for transatlantic craft exports. GB standards on food-contact plastics shape export certification requirements. Yangtze River Delta fabricators concentrate lightweight keg production for seasonal and limited-release distribution where reverse logistics costs exceed container depreciation.
United Kingdom
London restaurants in space-constrained districts specify Quarter Keg formats to balance per-tap variety against cooler footprint limitations. REACH chemical restrictions on food-contact materials disqualify lower-grade aluminum alloys, pushing procurement toward certified stainless-steel sourcing. Midlands-based logistics platforms consolidate fragmented brewery fleets into centralized asset pools.
Kegs Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with stainless-steel fabricators commanding premium positioning while PET blow-molders compete on export logistics economics. The vendor base clusters around three strategic archetypes: German-engineered precision valve specialists, Chinese-scale PET producers, and North American pooling service operators. Capacity expansion and strategic partnerships represent the dominant competitive moves, as regional players seek technology licensing agreements to bridge material-grade gaps.
Among German-engineered specialists, Blefa GmbH and THIELMANN The Container Company exemplify precision manufacturing archetypes that anchor European supply chain standards. American Keg Company occupies a position within North American captive steel sourcing networks. These three represent distinct competitive vectors: certified lifecycle durability, ISO tank format adjacencies, and domestic fabrication scale respectively.
| Leading Market Players |
|---|
| American Keg Company |
| NDL Keg |
| Blefa GmbH |
| Shinhan Industrial Co., Ltd. |
| Ningbo BestFriends Beverage Containers Co. Ltd. |
| Schaefer Container Systems |
| THIELMANN The Container Company |
| Petainer |
| Ardagh Group S.A. |
| Others |
Supply Flow & Price Mechanics
Germany's circular-economy return quotas gate qualified supply for premium-tier stainless-steel keg access, compressing margins for breweries lacking certified sourcing while elevating deposit-return compliant fleets to pricing power positions. This regulatory filter concentrates premium pricing among ISO-certified fabricators with captive valve production, forcing buyer archetypes into tiered procurement strategies.
Pricing Analysis
Short lead-time premiums distinguish contract-based long-term offtake from spot inventory discounts in keg procurement. Pricing stratifies across certified stainless-steel, standard aluminum, and economy PET tiers, with FDA and EU REACH certification levels commanding material premiums. Cost compression in aluminum grades is intensifying because REACH chemical restrictions disqualify lower-tier alloys, while craft breweries show least price sensitivity for lifecycle-durable formats and event organizers exhibit highest spot-market responsiveness.
Supply Chain Analysis
Dual-sourcing requirements from North American craft breweries mandate multi-supplier qualification across German valve engineering and Chinese PET blow-molding clusters. Supply draws from Germany, China, and Midwest U.S. steel fabrication hubs, with cold-rolled stainless, precision spear mechanisms, and blow-molded PET as critical inputs. Single-source vulnerability around Blefa GmbH's supplier network creates structural risk, while distribution runs through keg pooling platforms consolidating fragmented brewery fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Valve mechanism fabrication capacity represents the binding constraint propping pricing for qualified stainless-steel fleets, with technician scarcity extending lead times and compressing spot availability.
For Market Incumbents: Anchor German engineering standards through exclusive supplier agreements with Blefa GmbH's precision valve network, defending against PET substitution in export channels. Prioritize backward integration into spear mechanism production to eliminate single-source exposure, while extending ISO-certified fleet lifecycles through automated washing line investments that raise rival cost structures.
For New Entrants and Emerging Players: Capture Mumbai and Bangalore microbrewery licensing reforms with compact Sixth Keg formats tailored to sub-100-seat capacity limits. The Indian urban taproom segment offers lowest competitive density, with FSSAI food-contact certification as the critical go-to-market gateway for premium positioning against unqualified imports.
For Investors and Strategic Acquirers: RFID telemetry integration with pressure sensors is the leading indicator that usage-based leasing models will unbundle asset ownership from beverage supply contracts. Long-term viability centers on pooling platform operators with captive reverse logistics infrastructure, not brewery-owned fleets. Monitor German packaging regulator enforcement actions as the inflection signal for circular-economy compliance valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Valve Production | Eliminates Blefa GmbH single-source dependency for North American fabricators. |
| RFID Telemetry Platform Deployment | Enables usage-based leasing models unbundling ownership from supply contracts. |
| PET Manufacturing Scale-Up in Ningbo | Captures transatlantic craft export demand where reverse logistics costs dominate. |
| Sixth Keg Format Certification Investment | Unlocks Mumbai and Bangalore microbrewery licensing reform opportunities. |
| Keg Pooling Service Expansion | Consolidates fragmented Texas and Colorado brewery fleets into centralized asset pools. |
Methodological Framework
Multi-period observation of brewery fleet utilization rates, deposit-return scheme registrations, and valve mechanism lead times anchored the trend analysis, supplemented by interviews with keg pooling logistics directors, craft brewery procurement managers, stainless-steel fabricator plant engineers, and German packaging regulator compliance officers. Secondary validation drew from EPA steel manufacturing emission filings, EU REACH chemical restriction updates, FSSAI food-contact standards, and customs trade data for PET keg movements. Bottom-up brewery count modeling triangulated against top-down beverage volume projections.
Input-output matrices mapped material grade specifications to end-user channel requirements across the projection horizon, with segmentation dimensions spanning capacity format, material certification tier, ownership model, and geographic regulatory cluster. CAGRs derived from iterative reconciliation of fleet replacement cycles, brewery formation rates, and pooling service penetration curves, with carbon accounting disclosure requirements and cooling compressor efficiency standards as industry-specific forecast modifiers.
The model holds under sustained German circular-economy enforcement and stable stainless-steel input costs; deviation in REACH chemical restriction timelines or steel price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
South America Beer Market
Alcoholic Beverages
Brewers Spent Grain Market
Alcoholic Beverages
Dark Beer Market
Alcoholic Beverages
Nitro Cocktails Market
Alcoholic Beverages
Non-Fuel Grade Alcohol Market
Alcoholic Beverages
Wine Glass Market
Alcoholic Beverages
Cigar and Cigarillos Market
Alcoholic Beverages
Russia Tequila Market
Alcoholic Beverages
Guerbet Alcohols Market
Alcoholic Beverages
Apple Wine Market
Alcoholic Beverages
Mushroom Beer Market
Alcoholic Beverages
Beer Bottle Market
Alcoholic Beverages
Stemware Market
Alcoholic Beverages
US Alcohol E-Commerce Market
Alcoholic Beverages
East Africa Alcoholic Beverages Market
Alcoholic Beverages
Australia and New Zealand Tequila Market