
 Pinot Meunier Market | 2026-2036
Pinot Meunier Market Size, Share, and Industry Trends Forecast 2026-2036
Pinot Meunier Market Outlook
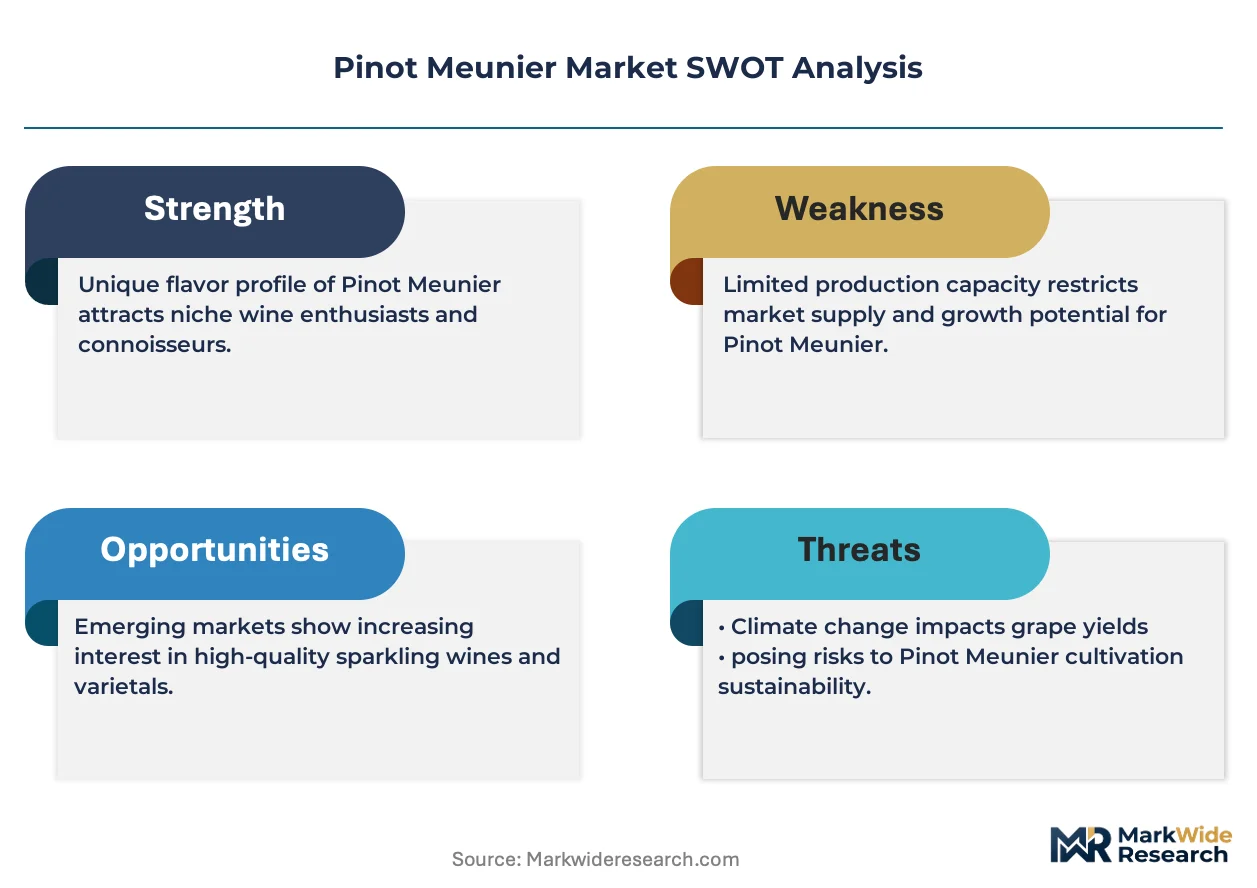
The capital-intensity divergence between large négociant houses and small grower-producers is unwinding traditional competitive boundaries in Pinot Meunier. Bollinger leverages its estate vineyard control and barrel-aging infrastructure to command premium positioning in prestige cuvées. Jérôme Prévost sustains a micro-scale model focused on single-village, single-varietal expressions that redefine terroir transparency. Egly-Ouriet anchors its reputation through extended lees aging and low-dosage winemaking that extracts structural depth from Pinot Meunier's naturally fruity profile.
Pinot Meunier is a black-skinned Vitis vinifera grape distinguished by a flour-dusted underside to its leaves, thriving in cooler climates where its early budding and late ripening cycle resists spring frost and autumn rot. Its primary commercial purpose centers on Champagne production, where it contributes red-fruit aromatics, body, and rapid maturation to blends, though still-wine expressions are gaining recognition. Sparkling wine remains the dominant product type by value, while still wine represents the fastest-growing category as producers in cooler New World sites exploit the variety's freshness and lower tannin structure. The application split shows celebratory events commanding the highest per-bottle margins, whereas retail sales drive aggregate volume throughput across supermarket and independent channels.
France's national wine regulator, the INAO, governs Appellation d'Origine Contrôlée standards that mandate Pinot Meunier's permitted role in Champagne blends and restrict still-wine labeling. The EU's Common Agricultural Policy cross-compliance rules and REACH chemical registration requirements shape vineyard input choices and cellar sanitation protocols. Stakeholders must monitor how climate-driven varietal redistribution interacts with appellation law rigidities that currently constrain geographic and stylistic experimentation.
Market Dynamics
Climate adaptation is forcing Champagne houses and grower-producers to redistribute vineyard portfolios toward cold-hardy varieties, with Pinot Meunier plantings expanding in frost-prone sub-regions as spring temperature volatility intensifies across northern France.
Growth Catalysts
- EU Common Agricultural Policy sustainability requirements:Cross-compliance rules on soil health and biodiversity are channeling vineyard investment toward regenerative practices that favor Pinot Meunier's lower chemical input needs.
- Non-vintage Champagne blending protocols:Houses rely on Pinot Meunier's rapid maturation and red-fruit aromatics to maintain consistent house styles across variable vintages.
- Marne Valley terroir concentration:The valley's clay-limestone soils and cooler mesoclimate sustain dominant Pinot Meunier plantings that supply base wines for volume production.
Market Restraints
- Appellation law rigidity:INAO standards restrict still-wine labeling and geographic experimentation, constraining stylistic diversification outside sparkling formats.
- Champagne grape supply concentration:Dependence on the Marne Valley and Aube for quality fruit creates regional weather and disease exposure risks.
- Pinot Noir and Chardonnay substitution:Prestige cuvée producers prioritize these varieties for aging potential, limiting Pinot Meunier's ceiling price positioning.
Strategic Opportunities
- Still-wine category emergence:Producers in cooler New World sites are exploiting Pinot Meunier's freshness and lower tannin structure for table wine expressions.
- Organic certification acceleration:EU organic standards and consumer willingness to pay premiums for certified bottles are rewarding conversion investments.
- Direct-to-consumer channel expansion:Grower-producers are bypassing négociant networks through estate tasting rooms and subscription models.
Industry Challenges
- Lees-aging expertise scarcity:Extended sur lie maturation techniques require specialized cellar labor that smaller producers struggle to retain.
- Climate-driven harvest timing volatility:Compressed picking windows demand flexible labor contracts and equipment access that strain fixed-cost structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pinot Meunier Market |
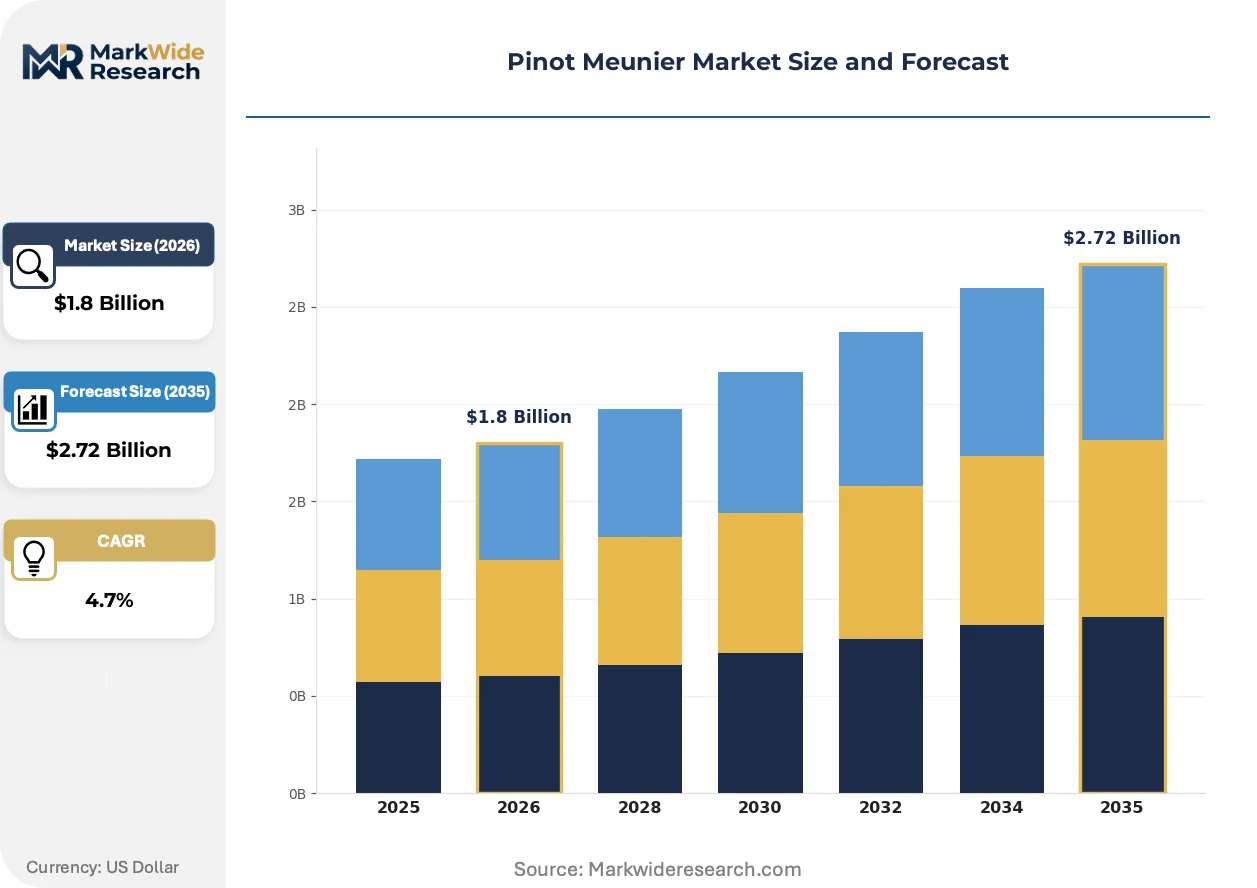
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sparkling Wine, Still Wine, Rosé, Vintage Application: Culinary Use, Celebratory Events, Wine Tastings, Retail Sales End User: Restaurants, Retailers, Distributors, Private Consumers Harvest Technique: Manual Harvesting, Mechanical Harvesting, Selective Picking, Bulk Collection |
| Companies Covered | Egly-Ouriet, Chartogne-Taillet, Jérôme Prévost, Bollinger, Laherte Frères, Françoise Bedel, Tarlant, Piper-Heidsieck, Laurent-Perrier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pinot Meunier Market Strategic Shifts
Precision viticulture and regenerative farming are converging to reshape canopy management and soil biology in Pinot Meunier vineyards, while regulatory pressure on chemical inputs accelerates alternative disease control adoption.
Lidar-equipped drones coupled with multispectral imaging are displacing manual vineyard scouting for vigor mapping and targeted intervention. Grower-producers in the Montagne de Reims are deploying these systems to identify frost-damaged sectors within 48 hours of events. The technology is displacing uniform spraying regimes with zonal treatment protocols that cut input volumes by sector-specific prescriptions.
REACH chemical registration requirements are tightening allowable fungicide portfolios for European vineyard operators. The regulation is forcing substitution of conventional sulfur and copper formulations with biocontrol agents and pheromone disruption systems. Organic-certified producers in the Marne Valley face compressed compliance timelines as re-registration deadlines approach for legacy protectants.
Restaurant sommeliers and independent merchants are consolidating purchasing around single-village, single-varietal grower Champagnes that emphasize terroir transparency over house consistency. This curator-driven channel is displacing supermarket-listed non-vintage blends as the prestige reference point for educated consumers. The shift concentrates in Paris, London, and New York where distribution now favors direct import relationships with micro-scale estates.
Pinot Meunier Market Segmentation
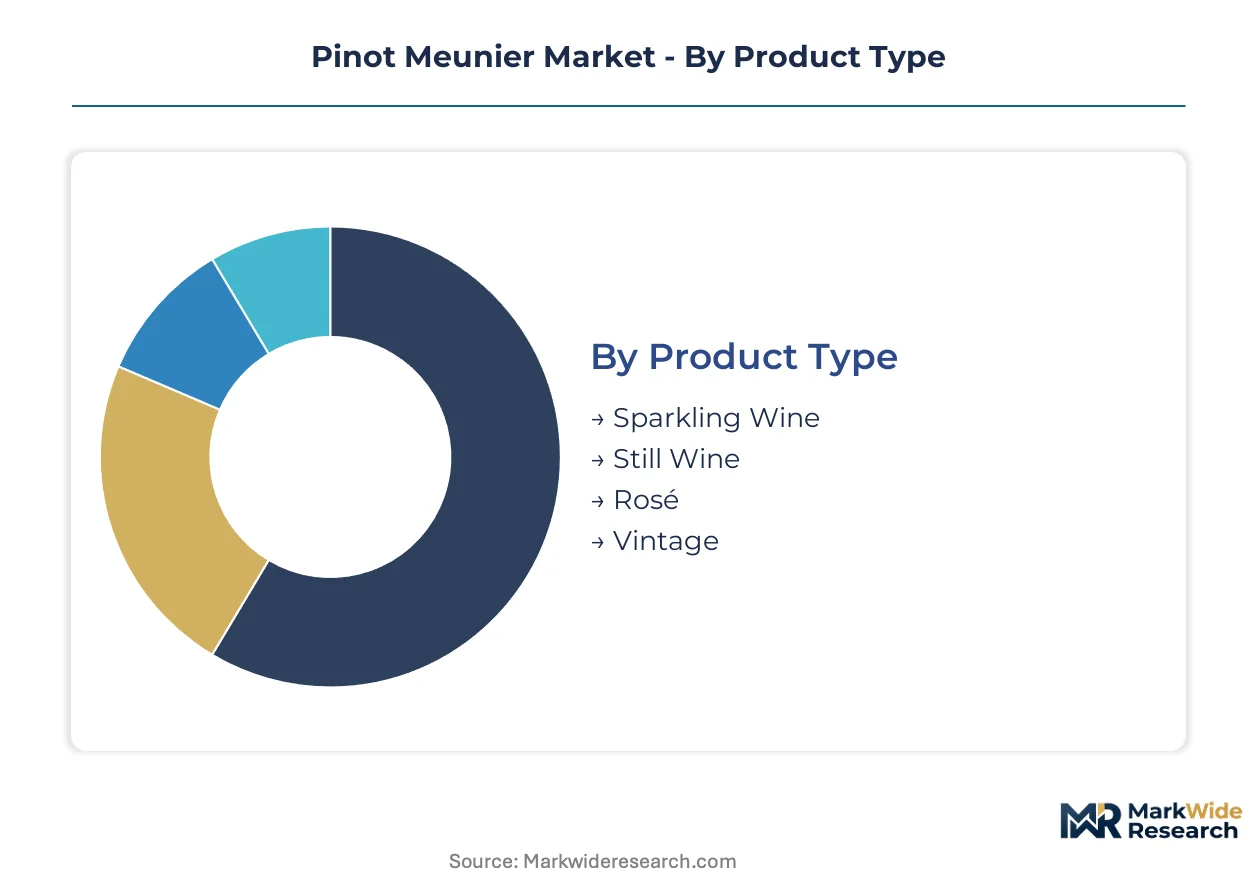
Pinot Meunier's commercial structure fragments across production formats, consumption occasions, and supply chain positions. Regulatory frameworks governing appellation status, organic certification, and labeling rights create divergent margin profiles across each segment boundary.
Product Type:
EU REACH chemical registration thresholds and INAO appellation law carve distinct compliance burdens across formats, with sparkling wine facing the most stringent dosage and aging mandates.
- Sparkling Wine:Traditional method secondary fermentation in bottle produces the mousse and autolytic complexity that defines Champagne. Demand concentrates in France's Marne Valley, where clay-limestone soils sustain dominant Pinot Meunier plantings for non-vintage blending.
- Still Wine:Direct pressing and temperature-controlled fermentation preserves the variety's red-fruit aromatics without bubble structure. Emerging adoption favors cooler New World sites in England and Tasmania, where producers exploit lower tannin profiles for table wine expressions that bypass Champagne's appellation constraints.
- Rosé:Brief skin contact or saignée methods extract delicate color for sparkling and still formats. The style gains traction in direct-to-consumer channels where visual differentiation commands shelf attention.
- Vintage:Single-declaration wines require extended lees aging under INAO protocols. Prestige cuvée houses dominate this tier through estate vineyard control and reserve wine libraries.
Established volume favors Sparkling Wine; emerging adoption favors Still Wine.
Application:
Margin structures invert between high-volume retail throughput and low-volume ceremonial pricing, with occasion-based segmentation determining distribution channel selection.
- Culinary Use:Reduction sauces and dessert pairings exploit Pinot Meunier's acidity and moderate alcohol. Demand concentrates in Michelin-tier restaurants across Paris and London, where sommelier-driven by-the-glass programs elevate grower-producer visibility.
- Celebratory Events:Weddings and corporate functions generate the highest per-bottle margins through prestige cuvée placement. The segment concentrates in direct import relationships that bypass wholesale markups.
- Wine Tastings:Educational and comparative formats favor single-village, single-varietal expressions that demonstrate terroir transparency. Independent merchants curate these portfolios around micro-scale estates.
- Retail Sales:Supermarket and independent shop channels drive aggregate volume throughput for non-vintage blends. Price competition intensifies as négociant houses defend shelf position against private-label entrants.
Celebratory Events capture premium pricing; Retail Sales absorb volume scale.
End User:
Procurement authority concentrates differently across on-premise, off-premise, and intermediate channels, with each tier imposing distinct technical and logistical requirements.
- Restaurants:On-premise accounts select for by-the-glass profitability and food-pairing versatility. Sommelier influence in Paris, London, and New York redirects purchasing toward grower Champagnes with transparent sourcing narratives.
- Retailers:Supermarket chains and independent merchants balance inventory turns against margin targets. The segment demands consistent supply for listed non-vintage expressions.
- Distributors:Négociant networks and direct importers manage regulatory compliance and temperature-controlled logistics across borders. Consolidation favors portfolios with vertical range from entry-level to prestige tiers.
- Private Consumers:Subscription models and estate tasting rooms enable grower-producers to capture margin otherwise surrendered to wholesale channels. The segment expands through direct-to-consumer platforms.
Distributors intermediate mass volume; Private Consumers expand margin capture.
Harvest Technique:
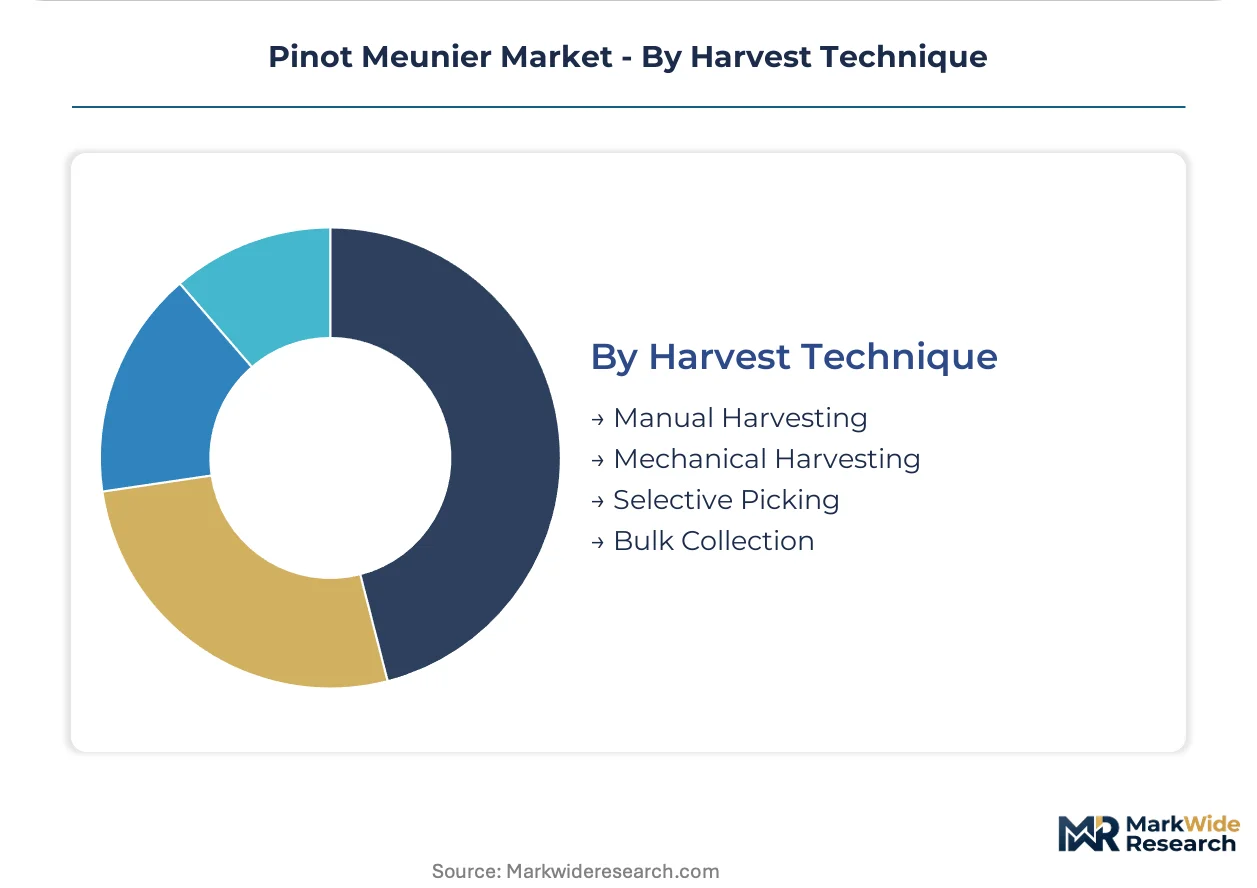
Labor cost trajectories and equipment depreciation schedules create divergent capital intensity profiles, with technique selection constraining achievable wine style and appellation eligibility.
- Manual Harvesting:Hand-picking into small crates preserves bunch integrity for whole-press fermentation. Demand concentrates in Grand Cru and Premier Cru vineyards where appellation law mandates gentle handling for vintage-dated wines.
- Mechanical Harvesting:Tractor-mounted harvesters reduce per-hectare labor costs for volume-oriented non-vintage production. The technique expands in frost-prone sub-regions where compressed picking windows strain manual crew availability.
- Selective Picking:Multiple passes through vineyard rows separate optimal ripeness levels for base wine blending. Precision viticulture data guides zonal harvesting protocols that match fruit character to intended cuvée style.
- Bulk Collection:Large-container gathering sacrifices individual bunch selection for operational speed. The method serves industrial-scale négociant supply contracts with relaxed quality sorting requirements.
Manual Harvesting sustains premium positioning; Mechanical Harvesting climbs the fastest for volume scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Champagne commands price premiums that English sparkling wine cannot yet match, though the gap narrows as climate shifts redistribute viable Pinot Meunier terroir northward. Regional pricing power now tracks frost-risk exposure more than historical prestige.
France
Marne Valley growers dominate global Pinot Meunier supply, with clay-limestone soils sustaining frost-resistant plantings that feed non-vintage Champagne blends. INAO appellation standards govern dosage limits and minimum aging requirements that constrain stylistic experimentation. Reims and Épernay anchor production infrastructure, where négociant houses and grower-producers compete for Grand Cru vineyard access.
United Kingdom
English sparkling wine producers in Kent and Sussex exploit warming temperatures to ripen Pinot Meunier in chalk soils analogous to Champagne's Côte des Blancs. DEFRA agricultural transition schemes subsidize vineyard establishment costs for regenerative farming conversions. The Weald and South Downs concentrate new plantings, where producers like Nyetimber and Ridgeview scale secondary fermentation capacity.
Australia
Tasmanian cool-climate sites in the Tamar Valley and Coal River Valley yield Pinot Meunier for sparkling base wines with pronounced acidity. Wine Australia export development grants support market access initiatives for premium sparkling categories. Hobart's urban fringe hosts experimental still-wine producers exploiting the variety's lower tannin structure for table wine expressions.
Germany
Baden and Württemberg growers cultivate Pinot Meunier (Schwarzriesling) for Sekt production and increasingly for still red wines. The German Wine Institute's sustainability certification program channels investment toward organic vineyard management. Kaiserstuhl volcanic soils in Baden sustain concentrated plantings where cooperatives and estate wineries compete for domestic retail placement.
United States
Oregon's Willamette Valley and California's Anderson Valley host experimental Pinot Meunier plantings for méthode champenoise sparkling programs. TTB labeling regulations permit varietal designation for wines containing 75% Pinot Meunier, below Champagne's stricter blending protocols. McMinnville and Philo clusters concentrate small-lot producers selling through direct-to-consumer channels and restaurant allocations.
Pinot Meunier Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with large négociant houses commanding scale economies in dosage and aging infrastructure while micro-scale growers capture terroir premiums through single-village expressions. Market structure fragments across three tiers: heritage houses with century-old reserve wine libraries, mid-scale growers with estate vineyard control, and emerging producers in New World sites exploiting regulatory arbitrage on appellation constraints. Dominant competitive moves include backward integration into estate vineyard acquisition and forward integration into direct-to-consumer subscription channels that bypass wholesale markups.
Within the grower-producer archetype, Egly-Ouriet, Jérôme Prévost, and Chartogne-Taillet exemplify terroir-transparent positioning. These Marne Valley-based estates occupy positions defined by extended lees aging protocols and low-dosage winemaking that extracts structural complexity from Pinot Meunier's naturally fruity profile. Their market presence represents a curator-driven channel shift that privileges single-village transparency over house consistency.
| Leading Market Players |
|---|
| Egly-Ouriet |
| Chartogne-Taillet |
| Jérôme Prévost |
| Bollinger |
| Laherte Frères |
| Françoise Bedel |
| Tarlant |
| Piper-Heidsieck |
| Laurent-Perrier |
| Others |
Value Chain & Pricing Dynamics
INAO appellation standards and EU organic certification regimes simultaneously gate supply qualification and price differentiation, restricting vineyard access for non-compliant producers while enabling certified estates to command tiered premiums across retail and direct-to-consumer channels.
Pricing Analysis
Configured-to-order pricing for single-village, single-varietal grower Champagnes commands spreads of three to five times standard non-vintage blends. Price differentiation rests on certification level (organic conversion status) and extended lees-aging protocols that extract structural complexity. Cost compression in entry-tier retail channels is intensifying because négociant houses defend shelf position against private-label entrants. Supermarket buyers exhibit highest price sensitivity; collector-driven direct-import channels show least.
Supply Chain Analysis
Inbound logistics costs from Marne Valley crushing facilities to Reims and Épernay bottling centers hinge on diesel price volatility and contracted harvest labor availability. Supply concentrates in France, the United Kingdom, and Tasmania, with raw material dependencies on certified vine nursery stock, French oak barrel supply, and dosage liqueur reserves. Single-source vulnerability runs through Marne Valley frost exposure that compresses annual fruit supply. Distribution runs through négociant wholesale networks, direct-import relationships, and estate subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pinot Meunier's service-attach opportunity centers on estate tasting room experiences and subscription allocations that expand faster than base wine volume, capturing margin otherwise surrendered to wholesale markups.
For Market Incumbents: Consolidate estate vineyard control in frost-prone Marne Valley sub-regions to secure supply against climate-driven vintage volatility. Acquire reserve wine libraries from distressed grower-producers to maintain non-vintage blending consistency. Backward integration into certified organic vineyard management insulates against REACH chemical re-registration deadlines that threaten conventional input portfolios. For New Entrants and Emerging Players: Anchor in English sparkling wine's still-wine white space, where DEFRA transition schemes subsidize vineyard establishment and appellation constraints do not limit varietal labeling. Target Tasmania's table wine experimentation corridor for lower-tannin expressions. Deploy direct-to-consumer subscription models that bypass established négociant distribution gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across mechanical harvesting and precision viticulture technology adoption, enabling mid-scale estate expansion without proportional labor cost scaling. Long-term viability favors vertically integrated producers with captive vineyard supply and reserve wine aging infrastructure. Monitor organic certification conversion rates as the inflection signal for sustained price premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Estate Vineyard Acquisition | Secures frost-resistant terroir in Marne Valley sub-regions against climate volatility. |
| Organic Certification Conversion | Unlocks EU CAP cross-compliance subsidies and premium channel placement. |
| Direct-to-Consumer Platform Launch | Bypasses négociant markups through subscription and tasting room allocation models. |
| Extended Lees Aging Protocol Investment | Differentiates grower-producer positioning against volume-oriented house blends. |
| Precision Viticulture Technology Deployment | Reduces input volumes through zonal treatment protocols guided by multispectral data. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of INAO regulatory filings, EU CAP implementation reports, and customs trade data. Interviews with vineyard managers, négociant procurement directors, independent merchant buyers, and cooperage suppliers inform supply-side dynamics. Secondary validation draws from Champagne house annual reports, organic certification body records, and regional agricultural ministry statistics. Bottom-up vineyard area and yield estimates triangulate against top-down value chain revenue assessments.
Segmentation dimensions modeled include product type, application occasion, harvest technique, and end-user channel across the projection horizon. CAGRs derive from fitted growth curves applied to volume and value trajectories. Forecast inputs incorporate climate scenario projections for frost frequency and EU regulatory compliance cost assumptions.
Material uncertainties — harvest timing volatility, REACH chemical re-registration outcomes, and consumer willingness-to-pay for certified organic premiums — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Hopped Malt Extract Market
Alcoholic Beverages
Industrial Alcohol Market
Alcoholic Beverages
North America Tequila Market
Alcoholic Beverages
Global Bourbon Market
Alcoholic Beverages
West Africa Alcoholic Beverages Market
Alcoholic Beverages
Pineapple Beer Market
Alcoholic Beverages
Digital Shaker Market
Alcoholic Beverages
Gluten Free Alcoholic Drinks Market
Alcoholic Beverages
North America Spirits Market
Alcoholic Beverages
Specialty Beer Market
Alcoholic Beverages
Tea Beer Market
Alcoholic Beverages
Asia-Pacific Spirits Market
Alcoholic Beverages
Sparkling Wine Market
Alcoholic Beverages
Stemware Market
Alcoholic Beverages
Spain Alcohol E-Commerce Market
Alcoholic Beverages
Fruit Beer Market