
 Beer Cans Market | 2026-2036
Beer Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Beer Cans Market Analysis
CE marking under the EU Packaging and Packaging Waste Directive is reorganizing which converters qualify for European brewer contracts. Ball Corporation leverages captive aluminum supply and beverage can plant scale across the Americas. Crown Holdings anchors its position through deep R&D in lightweighting alloys and shaping technologies. Silgan Containers competes via specialized coatings that extend shelf stability for craft and premium beer portfolios.
Beer cans are cylindrical metal containers, typically drawn from aluminum alloy sheet with a 202 or 204 diameter end, engineered to withstand internal pressures of 90 psi while providing complete light and oxygen barrier protection for carbonated beverages. The aluminum material segment dominates volume due to its superior recyclability and weight advantage over steel, while the 330ml and 500ml capacity bands capture the majority of mainstream lager and craft ale formats. Surface finish stratification sees printed direct-to-metal designs commanding premium positioning against labeled economy tiers, and retail distribution channels maintain share leadership despite online growth in subscription craft beer services.
EPA guidelines on volatile organic compound emissions from can coating operations constrain domestic US manufacturing, while REACH compliance in Europe governs bisphenol-A migration limits and chemical safety in interior linings. FDA food-contact substance notifications create a dual-track approval burden for suppliers serving both American and European brewers. Stakeholders must monitor evolving extended producer responsibility schemes and deposit-return legislation as these frameworks increasingly determine regional cost structures and competitive access.
Market Dynamics
Aluminum alloy supply concentration and EU packaging waste mandates are forcing brewers to requalify their converter base, reshaping contract structures and regional sourcing strategies across the beverage packaging value chain.
Growth Catalysts
- EU Packaging and Packaging Waste Directive:CE marking requirements are accelerating material substitution from glass to aluminum across European brewer portfolios.
- Craft brewery expansion:Small-batch producers in the United States and Germany are converting draft volumes to canned formats for distribution efficiency.
- Tropical climate storage:Off-premise consumption patterns in Brazil and Mexico favor aluminum cans over bottles for thermal stability.
Market Restraints
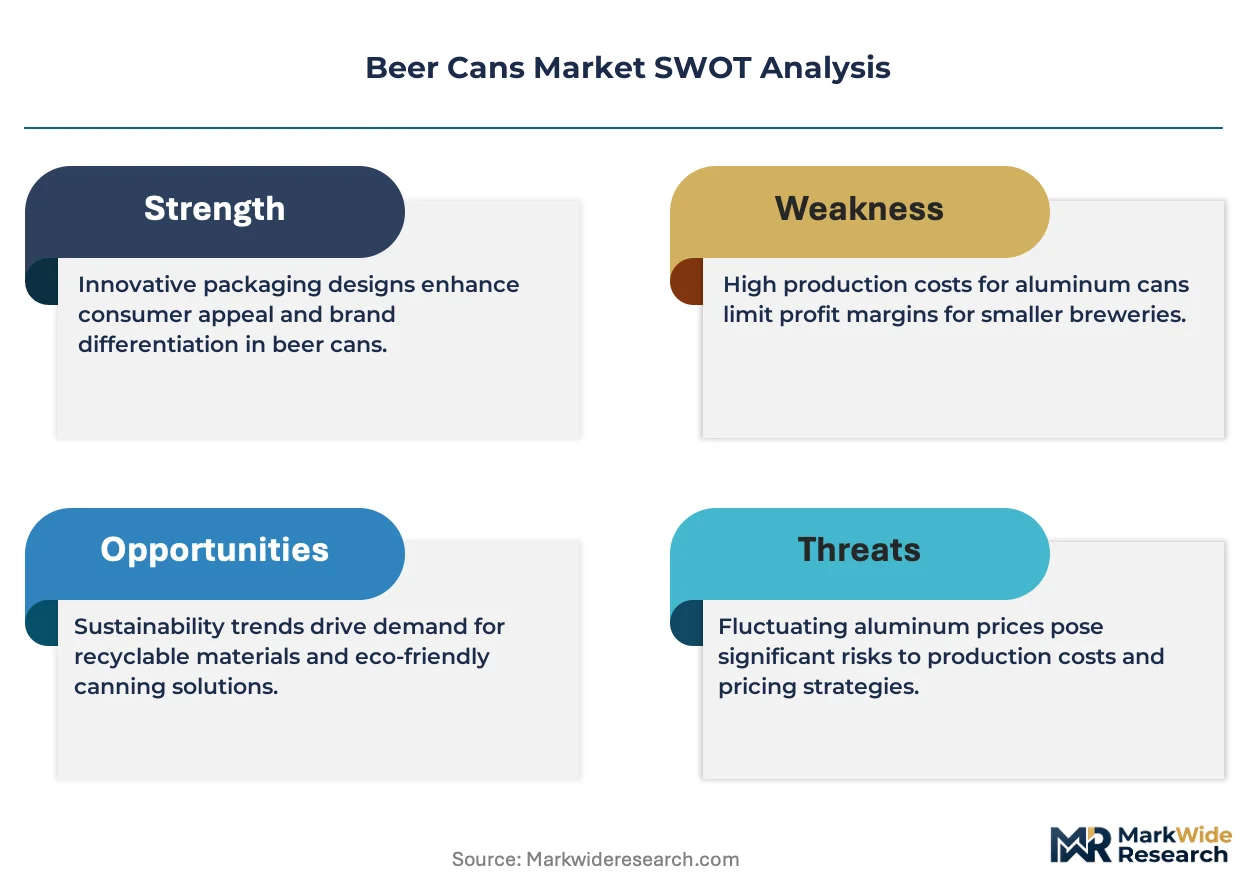
- Aluminum ingot price volatility:Primary metal cost swings compress converter margins and destabilize long-term brewer contracts.
- Can coating regulatory friction:EPA volatile organic compound emission limits constrain domestic US manufacturing capacity expansion.
- Steel can residual substitution:Lower-cost tinplate alternatives retain share in price-sensitive economy lager segments.
Strategic Opportunities
- India beverage market penetration:Rising middle-class consumption and modern trade expansion create underdeveloped demand for canned beer formats.
- Deposit-return scheme expansion:Extended producer responsibility frameworks in Germany and Scandinavian markets incentivize closed-loop aluminum recovery.
- Digital printing convergence:Direct-to-metal decoration technology enables short-run customization for limited-release craft portfolios.
Industry Challenges
- Dual-track FDA-REACH compliance:Interior lining substance notifications create parallel approval burdens for suppliers serving transatlantic brewers.
- Lightweighting alloy R&D capex:Continuous gauge reduction programs demand sustained capital deployment without immediate volume returns.
- Recycling stream contamination:Mixed-material labels and closures complicate aluminum recovery purity standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beer Cans Market |
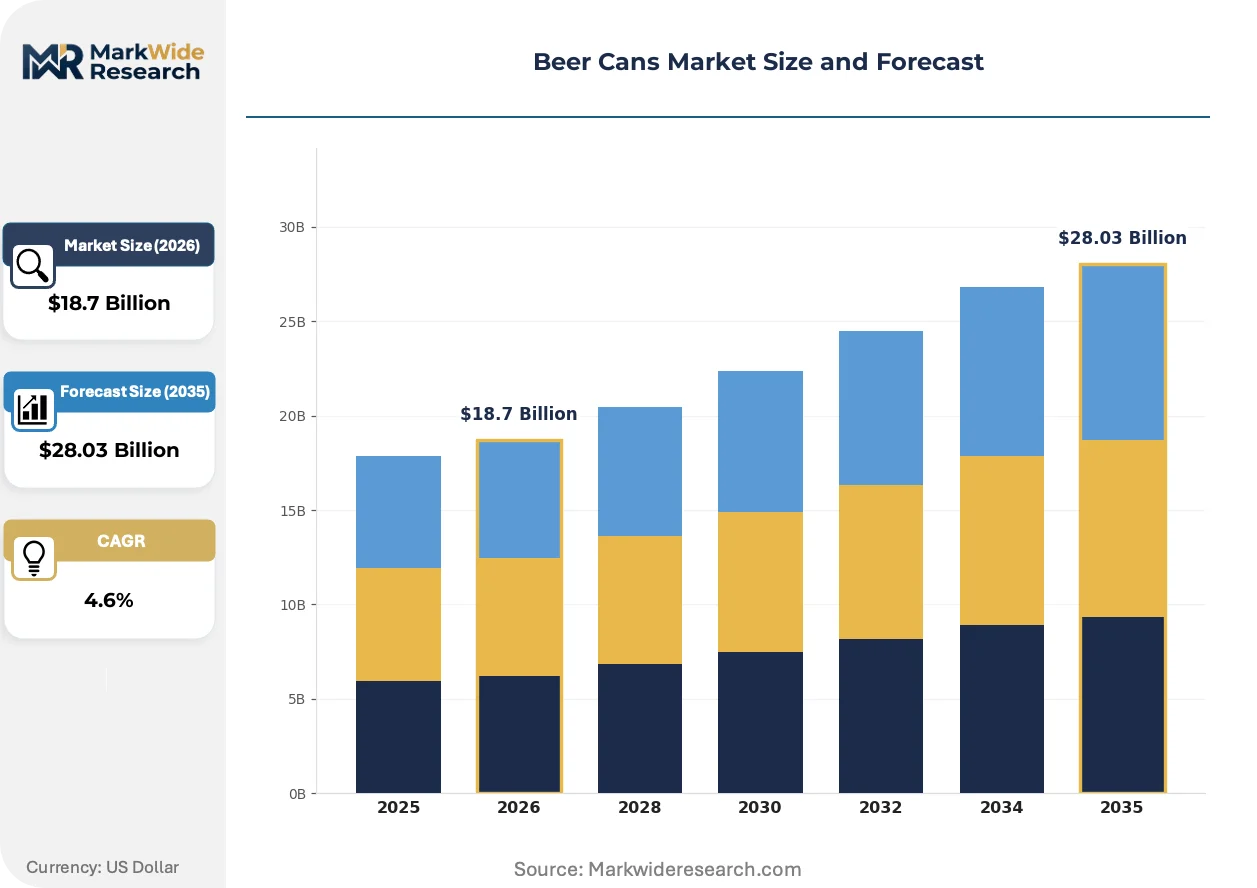
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Steel, Plastic, Tin Capacity: 330ml, 500ml, 750ml, 1L Surface Finish: Matte, Glossy, Printed, Labelled Distribution Channel: Retail, Wholesale, Direct Sales, Online |
| Companies Covered | Ardagh Group, Silgan Containers, Ball Corporation, CPMC Holdings, Orora Packaging Australia, Crown Holdings, Can-Pack, Daiwa Can Co, Toyo Seikan Group Holdings Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beer Cans Market Emerging Trajectories
Material science advances and regulatory pressure on interior coatings are splitting the competitive landscape between premium sustainable formats and legacy economy production, with converter specialization deepening.
Direct-to-metal digital printing is bifurcating the surface finish market. High-definition inkjet systems enable photorealistic imagery and variable data integration for craft brewer marketing. Premium positioning now separates from labeled economy tiers through decoration technology rather than substrate alone.
REACH bisphenol-A migration limits are restructuring interior lining formulations. European brewers face mandatory substitution timelines for epoxy-based coatings. Suppliers are accelerating polyester and acrylic alternative qualification to maintain EFSA compliance and avoid supply disruption.
Subscription craft beer channels are fragmenting traditional distributor relationships. Direct-to-consumer platforms in the United States and United Kingdom bypass three-tier systems for limited releases. This disintermediation concentrates volume with specialized can converters capable of sub-10,000 unit production runs.
Beer Cans Market Segmentation
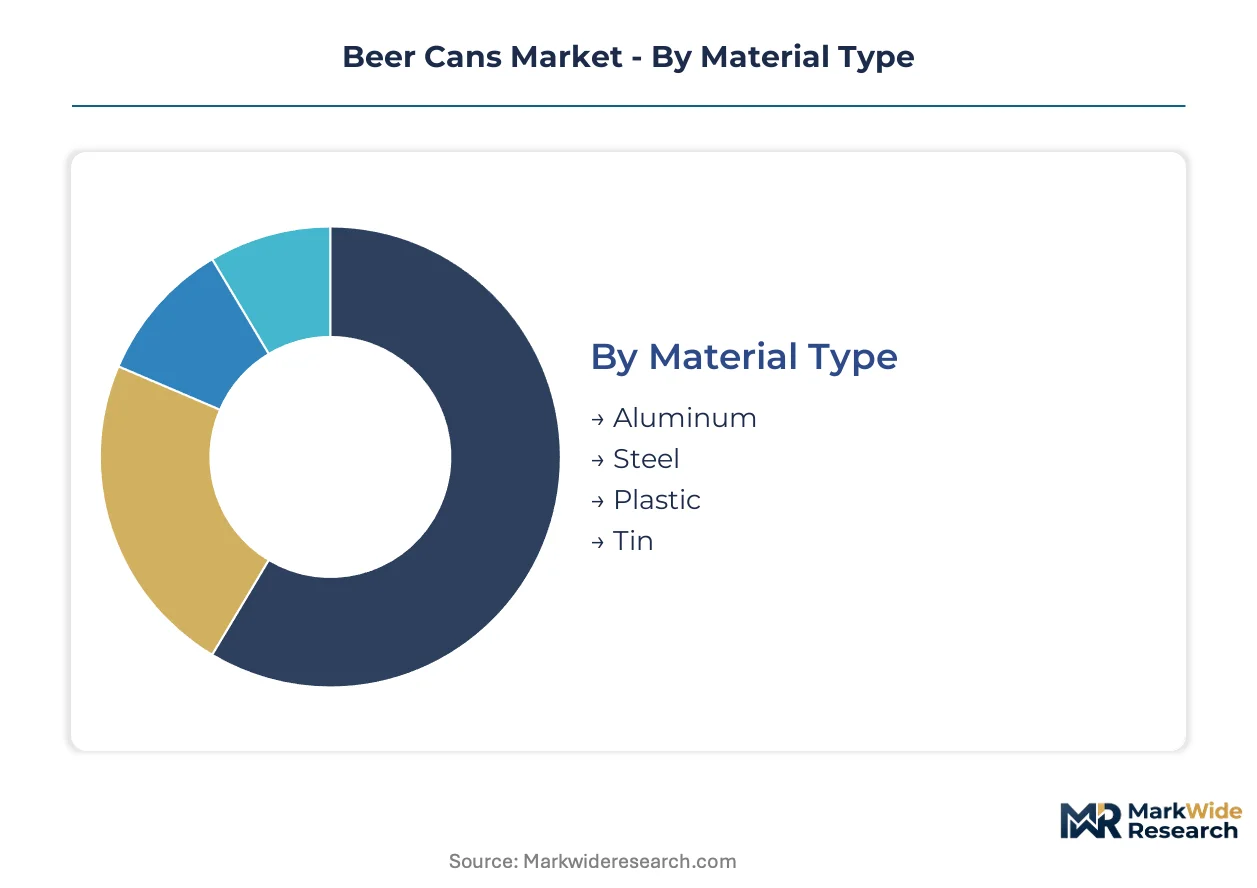
Beer can segmentation reflects divergent technical requirements across regulatory jurisdictions and consumption occasions. Converter specialization deepens as material science, capacity optimization, and surface decoration each carry distinct compliance burdens and margin profiles.
Material Type:
REACH bisphenol-A migration limits and EPA volatile organic compound emission standards split converter qualification between European and American brewer contracts.
- Aluminum:Drawn from alloy sheet with 202 or 204 diameter ends, aluminum withstands 90 psi internal pressure while delivering complete light and oxygen barrier protection. Demand concentrates in Brazil and Mexico where tropical climate storage and off-premise consumption patterns favor thermal stability over glass. CE marking under EU packaging regulations accelerates substitution from tinplate and steel across German and Scandinavian brewer portfolios.
- Steel:Tinplate construction retains residual share in price-sensitive economy lager segments, particularly where primary aluminum ingot volatility compresses converter margins. Lower material costs attract volume brewers in Eastern European and select Latin American markets with less stringent extended producer responsibility frameworks.
- Plastic:Polymer substrates serve niche applications requiring shatter resistance and reduced shipping weight, though limited barrier performance constrains carbonation retention for mainstream beer formats.
- Tin:Legacy tinplate specifications persist in specialty and commemorative packaging where substrate authenticity supports premium positioning, despite higher unit economics and recycling complexity.
Established volume favors aluminum; emerging adoption for plastic continues in non-carbonated and ready-to-drink adjacent categories.
Capacity:
Distribution economics and consumption occasion fragmentation drive capacity band concentration, with craft brewery expansion reshaping run-length requirements.
- 330ml:The standard format for mainstream lager and ale portfolios, 330ml cans optimize palletization efficiency and retail shelf density. German and British brewers specify this capacity for domestic premium and standard tier positioning.
- 500ml:Larger format cans capture craft ale and session beer demand in the United States and United Kingdom, where direct-to-consumer subscription channels favor single-serve packaging with extended shelf stability.
- 750ml:Emerging capacity for sharing occasions and limited-release craft portfolios, 750ml formats enable premium positioning through distinctive silhouette differentiation on crowded retail shelves.
- 1L:Economy-tier multi-serve applications in Brazil and Mexico leverage thermal mass advantages for outdoor consumption, though filling line requalification costs limit converter adoption.
Mainstream lager specifications anchor 330ml volume; craft brewery conversion to canned formats expands 500ml share most steeply.
Surface Finish:
Decoration technology bifurcation separates premium sustainable formats from labeled economy production as digital printing capex reshapes converter specialization.
- Matte:Non-reflective coatings support tactile premium positioning and reduced fingerprint visibility, attracting craft brewer specifications for limited-release portfolios where shelf differentiation commands price premiums.
- Glossy:High-sheen finishes dominate mainstream lager and ale applications, offering maximum brand color saturation and retail visibility under fluorescent and LED lighting conditions.
- Printed:Direct-to-metal digital printing enables photorealistic imagery and variable data integration for sub-10,000 unit craft production runs, fragmenting traditional converter relationships through disintermediated subscription channels.
- Labelled:Pressure-sensitive and shrink-sleeve labels retain economy-tier share where run lengths and capital constraints preclude inline decoration investment, though mixed-material recovery complicates aluminum stream purity.
Converter investment in digital printing accelerates printed finish adoption; labelled formats retain residual share in price-driven emerging market segments.
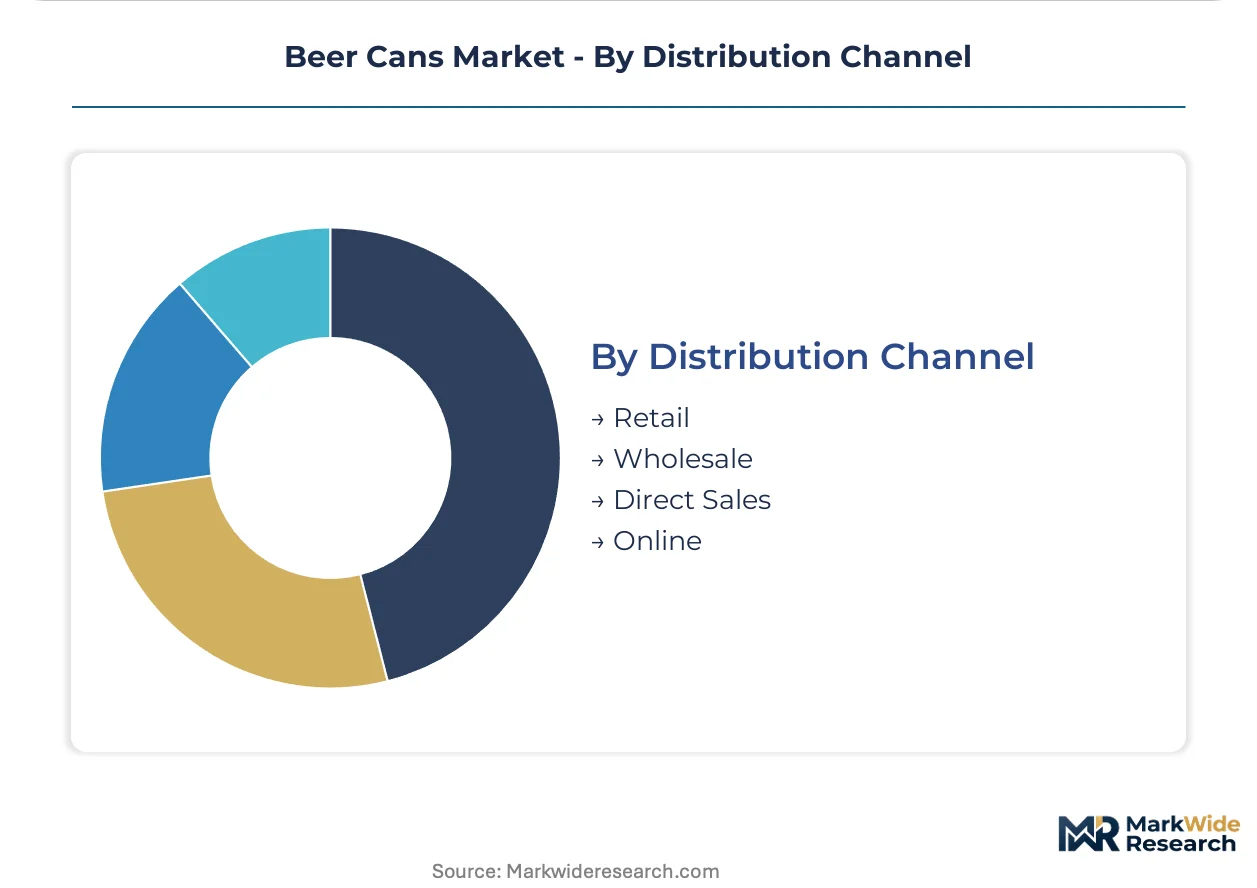
Distribution Channel:
Three-tier system fragmentation and extended producer responsibility schemes restructure channel economics across North American and European markets.
- Retail:Supermarket and convenience store channels maintain volume leadership despite online growth, with deposit-return legislation in Germany and Scandinavian markets incentivizing closed-loop aluminum recovery infrastructure.
- Wholesale:Distributor relationships concentrate volume for national brewer portfolios, though craft brewery bypass strategies erode traditional intermediary margins in the United States.
- Direct Sales:Brewery taproom and on-site canning operations capture margin premiums through vertical integration, constrained by FDA food-contact substance notification requirements for interior lining formulations.
- Online:Subscription craft beer platforms in the United States and United Kingdom disintermediate three-tier systems, concentrating demand with specialized converters capable of short-run customization and rapid turnaround.
Retail infrastructure anchors volume concentration; online channel expansion gains share fastest among craft and limited-release portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU packaging waste directives and aluminum recycling mandates are reorganizing converter qualification requirements across major brewing markets. CE marking obligations and extended producer responsibility frameworks now determine contract eligibility and regional sourcing strategies for beverage can supply.
United States
Craft brewery conversion from draft to canned formats accelerates demand for 500ml and 16oz specifications. EPA volatile organic compound emission limits constrain coating operation expansions, particularly in California and Texas manufacturing clusters. Pacific Northwest brewing hubs in Oregon and Washington drive short-run customization requirements for limited-release portfolios.
Germany
Deposit-return legislation under the German Packaging Act incentivizes closed-loop aluminum recovery infrastructure for mainstream lager distribution. REACH bisphenol-A migration limits mandate epoxy coating substitution timelines, forcing interior lining requalification across Bavarian and North Rhine-Westphalia brewing operations. Ball Corporation's beverage can plant scale anchors converter supply for domestic premium portfolios.
Brazil
Tropical climate storage requirements and off-premise consumption patterns favor aluminum cans over glass for thermal stability in outdoor retail channels. ANVISA food-contact substance regulations govern interior coating safety for canned beer formats. São Paulo and Minas Gerais industrial corridors concentrate converter capacity for economy-tier multi-serve applications.
Mexico
Export-oriented brewing operations and domestic consumption growth concentrate demand in 330ml and 500ml standard formats. Extended producer responsibility frameworks under federal environmental law reshape aluminum recovery economics for Mexico City and Nuevo León manufacturing bases. Crown Holdings' lightweighting alloy R&D serves premium positioning requirements for international brand portfolios.
India
Rising middle-class consumption and modern trade expansion create underdeveloped demand for canned beer formats beyond traditional bottle preferences. FSSAI food safety standards and BIS packaging specifications establish compliance thresholds for interior lining formulations. Maharashtra and Karnataka brewing clusters drive initial converter qualification for premium lager and craft ale introductions.
Beer Cans Market Vendor Landscape
Player mix skews toward integrated metal packaging specialists with captive aluminum supply and beverage-dedicated plant networks. Tiered competitive positioning separates scale-driven converters with multinational plant footprints from regional specialists serving craft brewery short-run requirements. Strategic archetypes include captive aluminum integrators, coating technology specialists, and digital printing-enabled customization providers. Dominant competitive moves center on lightweighting alloy R&D deployment and strategic partnerships with craft brewery subscription channels.
Within the integrated packaging tier, Ball Corporation, Crown Holdings, and Silgan Containers exemplify distinct capability emphases. Ball Corporation anchors scale-driven supply through Americas-focused beverage can plant networks. Crown Holdings occupies a position emphasizing material science specialization for gauge reduction programs. Silgan Containers sits within the coating technology vector, representing interior lining formulation expertise for shelf stability extension. Ardagh Group and Can-Pack exemplify European-originated converters with multinational qualification for CE-marked brewer contracts. Daiwa Can Co and Toyo Seikan Group Holdings Ltd represent Asia-Pacific-based fabricators with regional regulatory alignment for Japanese and Southeast Asian brewing operations.
| Leading Market Players |
|---|
| Ardagh Group |
| Silgan Containers |
| Ball Corporation |
| CPMC Holdings |
| Orora Packaging Australia |
| Crown Holdings |
| Can-Pack |
| Daiwa Can Co |
| Toyo Seikan Group Holdings Ltd |
| Others |
Supply Flow & Price Mechanics
Aluminum substitution for glass under EU packaging waste mandates is redrawing supply geography toward CE-marked converters while compressing legacy tinplate pricing tiers. Brewer requalification programs concentrate contract volume with integrated metal suppliers possessing captive alloy supply and beverage-dedicated plant networks.
Pricing Analysis
Cost-plus contracts indexed to LME primary aluminum ingot benchmarks dominate long-term brewer-converter agreements. Price differentiation hinges on gauge specification and CE marking compliance tier, with lightweighting alloy premiums separating integrated specialists from regional fabricators. Pricing pressure stems from ingot volatility destabilizing converter margins, particularly for non-captive suppliers serving price-sensitive economy lager portfolios in Eastern European markets.
Supply Chain Analysis
Primary aluminum smelting concentration in Brazil, Russia, and Australia constrains converter feedstock security for European and North American can plants. The supply chain draws from bauxite extraction, alumina refining, and rolling mill capacity, with ingot price swings transmitting directly to can sheet costs. Tariff exposure on Russian aluminum creates single-source vulnerability for European brewers. Distribution runs through three-tier wholesale systems in the United States and direct-to-retail logistics in Brazil and Mexico.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital printing and short-run customization services represent a faster-expanding recurring-revenue layer than commodity can fabrication, rewarding converters that attach design and logistics capabilities to core metal supply.
For Market Incumbents: Shield market position by deepening captive aluminum supply through backward integration into rolling mill capacity, particularly for CE-marked European contracts facing ingot tariff exposure. Accelerate interior lining requalification ahead of REACH bisphenol-A substitution deadlines to preempt supply disruption for Bavarian and North Rhine-Westphalia brewing operations.
For New Entrants and Emerging Players: Short-run digital printing capabilities for craft brewery subscription channels offer incumbents under-serve at volumes below 10,000 units. Target Pacific Northwest and United Kingdom craft brewing clusters with rapid-turnaround direct-to-metal decoration. Pursue equipment-light contract manufacturing partnerships rather than greenfield can plant investment.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors coating technology specialists with REACH-compliant interior lining portfolios. Long-term viability rests on regulatory compliance moats rather than scale alone. Monitor EFSA migration limit enforcement timelines as the inflection signal for coating formulation substitution demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Lightweighting Alloy R&D Deployment | Ball Corporation and Crown Holdings reduce gauge to cut aluminum input costs per thousand cans. |
| Digital Printing Capability Buildout | Converters capture craft brewery subscription volume through sub-10,000 unit production flexibility. |
| REACH-Compliant Coating Substitution | Suppliers requalify polyester and acrylic interior linings ahead of EFSA bisphenol-A migration deadlines. |
| Captive Aluminum Supply Integration | Backward integration into rolling mill capacity insulates converter margins from LME ingot volatility. |
| Deposit-Return Infrastructure Partnership | German and Scandinavian closed-loop recovery systems secure aluminum stream purity for premium positioning. |
Methodological Framework
A spread of perspectives from beverage can plant managers, brewer procurement directors, aluminum rolling mill technical leads, and regulatory compliance officers converged on the working assumptions. Primary fieldwork combined with secondary validation against EPA emission filings, ECHA REACH registration databases, SEC 10-K packaging segment disclosures, and EU Packaging Directive implementation reports. Bottom-up volume modeling triangulated against top-down aluminum can shipment data.
Segmentation dimensions modeled include material type, capacity band, surface finish technology, and distribution channel across the projection horizon. CAGRs derived from regression analysis of historical brewer packaging mix shifts and regulatory adoption curves. Industry-specific forecast inputs incorporated craft brewery canning line installation rates and EU extended producer responsibility scheme expansion timelines.
Underlying assumptions cover aluminum ingot price band stability and REACH enforcement consistency, with deviation risk concentrated in tariff policy shifts and coating requalification delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Isoamyl Alcohol Market
Alcoholic Beverages
Global Craft Vodka Market
Alcoholic Beverages
RTD Bottled Cocktails Market
Alcoholic Beverages
Balsam Bottle Market
Alcoholic Beverages
Gluten-Free Beer Market
Alcoholic Beverages
Low Alcohol Beverages Market
Alcoholic Beverages
Global Premium Gin Market
Alcoholic Beverages
South America Alcoholic Beverages Market
Alcoholic Beverages
RTD Cocktail Shots Market
Alcoholic Beverages
Canned Alcoholic Beverages Market
Alcoholic Beverages
Wine Enzymes Market
Alcoholic Beverages
Hip Flask Market
Alcoholic Beverages
Wine Bottle Sterilizer Market
Alcoholic Beverages
Wine Bags Market
Alcoholic Beverages
Luzhou-Flavor Liquor Market
Alcoholic Beverages
US Wine Market