
 Italy Location-Based Services Market | 2026-2036
Italy Location-Based Services Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Location-Based Services Market Insights
Single-source mapping data procurement is consolidating around hybrid cloud platforms that blend real-time telemetry with historic spatial databases. HERE Technologies anchors its Italian operations through high-definition road network coverage for automotive clients. Google competes by extending its indoor positioning capabilities across major Italian shopping centers and transit hubs. TomTom specializes in fleet optimization algorithms tailored to Mediterranean logistics corridors.
Location-based services fuse geospatial coordinates with contextual data streams to deliver position-dependent functionality across mobile and fixed infrastructure, typically processing latitude-longitude pairs through cellular triangulation, satellite constellations, or beacon mesh networks with sub-ten-meter accuracy thresholds. The primary commercial purpose centers on reducing friction in physical-to-digital customer journeys while optimizing asset utilization. Navigation services within the service type category occupy the largest revenue pool given Italy's dense urban cores and complex historic street grids. Bluetooth deployments under the technology dimension are expanding fastest as beacon density rises in Venetian retail clusters and Florentine museum complexes. Cloud deployment options capture disproportionate margin attention from mid-market logistics operators seeking elastic compute for seasonal freight surges.
Italy's national data protection authority enforces GDPR-derived location privacy rules that mandate explicit consent for persistent geotracking, while the EU AI Act imposes risk-classification requirements on automated spatial decision systems deployed in public infrastructure. The Italian Agency for Digital Transformation coordinates smart city standards that shape procurement specifications for municipal LBS integrations. Stakeholders must monitor evolving interoperability mandates between national digital identity frameworks and private location service providers.
Market Dynamics
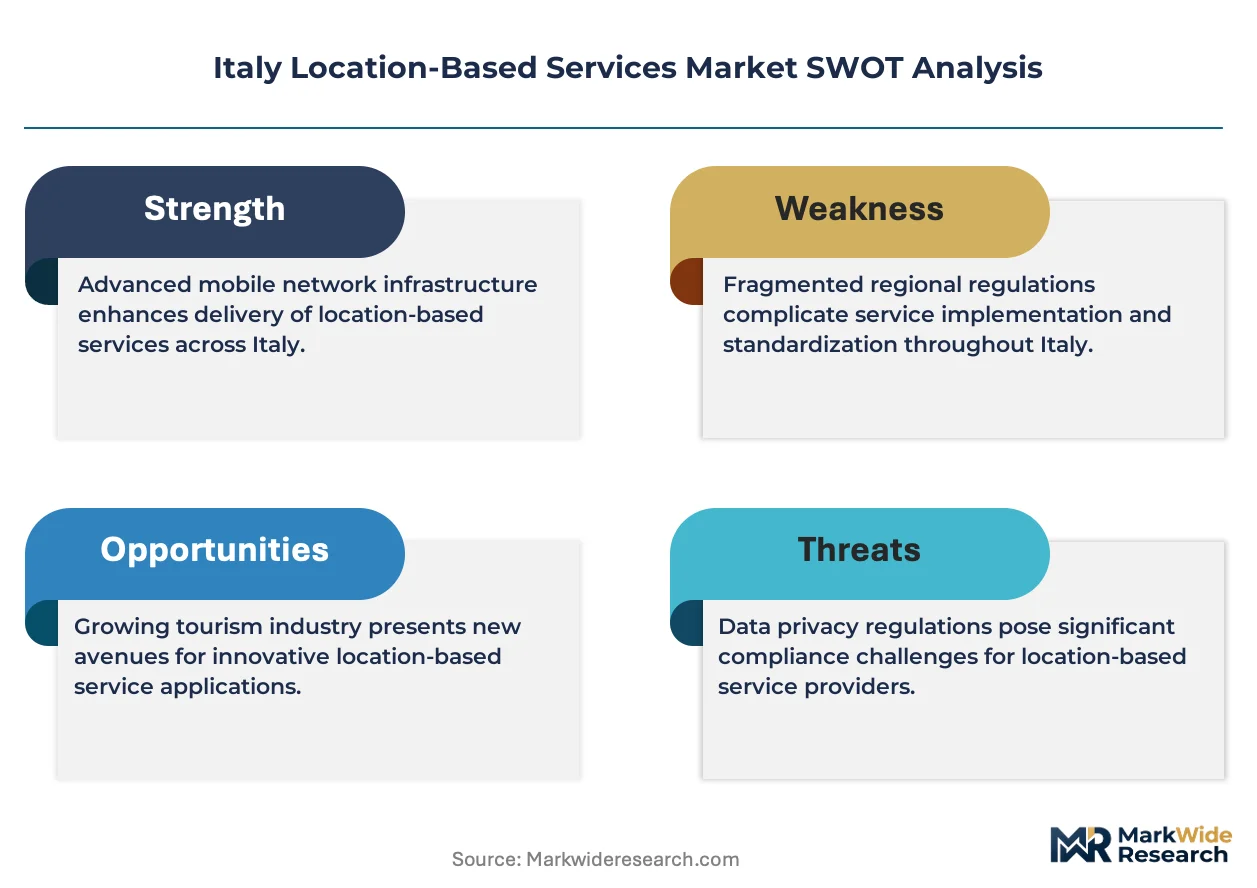
Italy's location-based services sector is restructuring around the tension between real-time spatial intelligence demand and the EU AI Act's risk-classification mandates for automated geospatial decision systems.
Growth Catalysts
- Smart city procurement mandates:The Italian Agency for Digital Transformation coordinates municipal standards that require location-aware infrastructure in urban renewal contracts.
- Bluetooth beacon mesh density:Venetian retail clusters and Florentine museum complexes are deploying sub-ten-meter accuracy beacon networks for proximity marketing.
- Fleet optimization demand:Mediterranean logistics corridors drive adoption of cloud-elastic compute for seasonal freight surge management.
Market Restraints
- GDPR-derived consent friction:Italy's national data protection authority mandates explicit opt-in for persistent geotracking, increasing customer acquisition costs.
- Historic street grid complexity:Dense urban cores with medieval infrastructure limit satellite triangulation accuracy below commercial thresholds.
- Hybrid cloud integration costs:Mid-market logistics operators face capex barriers blending real-time telemetry with legacy spatial databases.
Strategic Opportunities
- Rome tourism corridor expansion:Unmet demand exists for indoor positioning in transit hubs connecting historic districts.
- AI Act compliance services:Risk-classification tooling for automated spatial decision systems represents nascent vendor white space.
- Cellular triangulation-beacon convergence:Fusing 5G positioning with Bluetooth mesh creates redundancy for financial district applications.
Industry Challenges
- Geospatial data science talent scarcity:Italian universities produce insufficient specialists in spatial statistics and real-time stream processing.
- Interoperability with SPID:Italy's national digital identity framework requires complex API integration for municipal LBS procurement compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Location-Based Services Market |
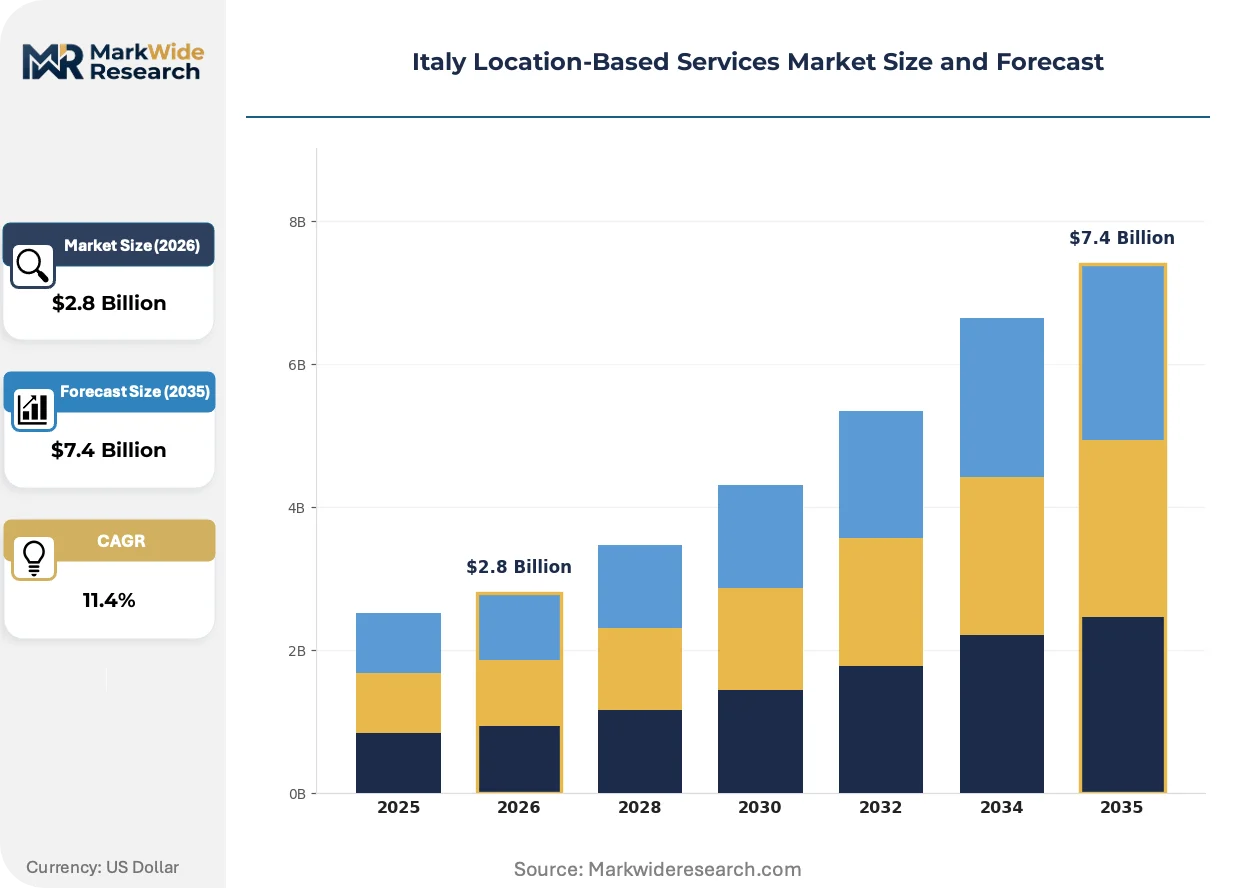
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Navigation, Advertising, Tracking, Analytics Technology: GPS, Wi-Fi, RFID, Bluetooth End User: Retail, Transportation, Healthcare, Tourism Deployment: On-Premise, Cloud, Hybrid, Mobile |
| Companies Covered | Google, HERE Technologies, TomTom, Apple, Esri Italia, IBM Corporation, Cisco Systems, Zebra Technologies Corporation, Microsoft, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Location-Based Services Market Trends and Innovations
Spatial computing architectures are absorbing contextual data streams at unprecedented velocity, forcing vendors to reengineer latency-sensitive pipelines for Italian urban density.
Ultra-wideband positioning is absorbing indoor navigation tasks previously handled by Wi-Fi fingerprinting. Milan's financial district deploys centimeter-accuracy asset tracking for high-value document workflows. The technology is absorbing premium service tier margins as accuracy thresholds tighten.
The EU AI Act imposes risk-classification requirements on automated spatial decision systems deployed in public infrastructure. Municipal procurement specifications now mandate algorithmic impact assessments for smart city integrations. Milan and Rome transit authorities are responding by segmenting vendor pools between high-risk and limited-risk application categories.
Italian retailers are unbundling location-based advertising from legacy media buys. Procurement teams now negotiate directly with beacon network operators, bypassing traditional agency intermediaries. This disintermediation concentrates in Florentine museum complexes where cultural institutions seek direct visitor journey analytics ownership.
Italy Location-Based Services Market Segmentation
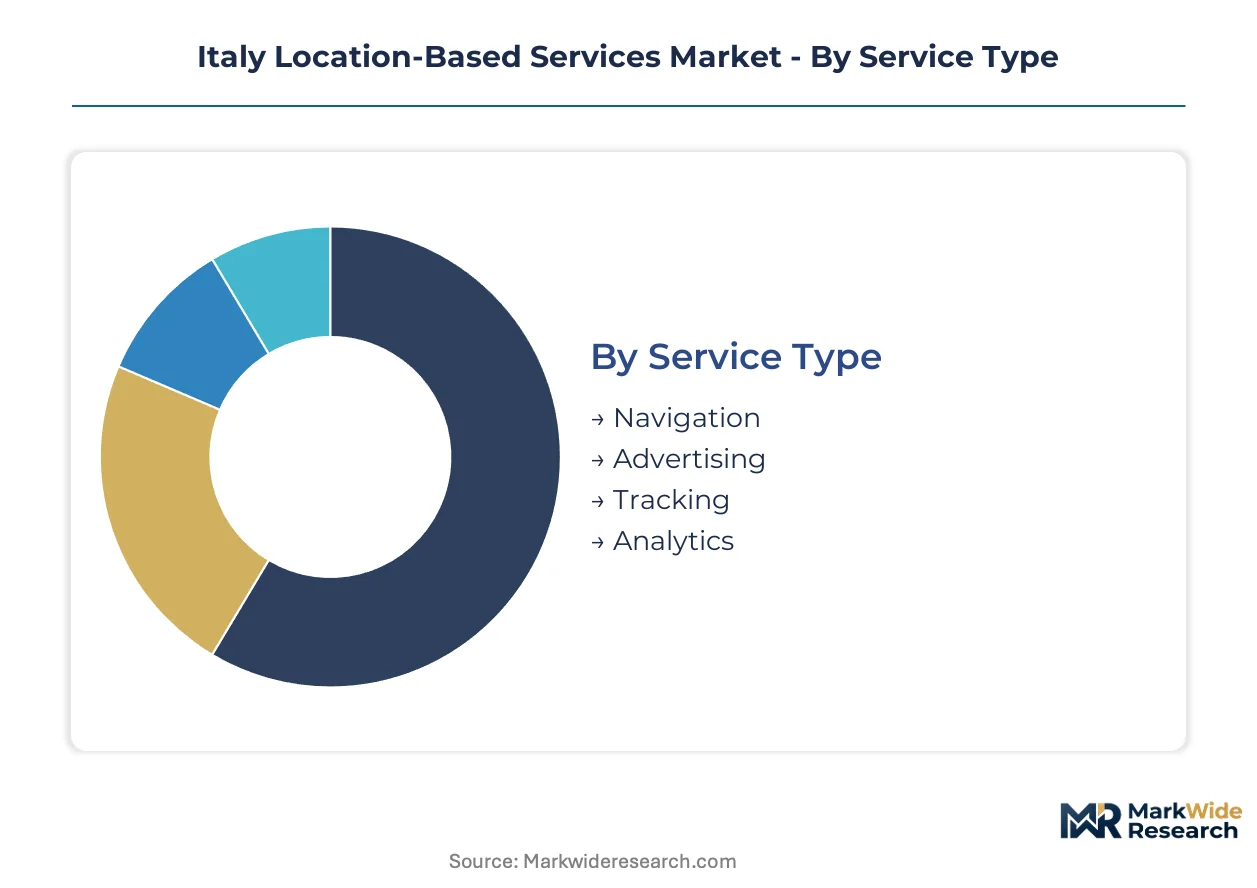
Italian enterprises select location-based services based on precision requirements, data sovereignty needs, and integration complexity with legacy municipal infrastructure. Segmentation reveals diverging margin profiles across service architectures, with navigation commanding stable revenue pools while beacon-based advertising captures expansion capital.
Service Type:
Buyer decisions here pivot on operational friction reduction versus customer engagement depth, with automotive and logistics procurement teams prioritizing different performance thresholds than retail marketers.
- Navigation:Processes latitude-longitude pairs through satellite constellations and cellular triangulation to generate turn-by-turn routing. Demand concentrates in Milan's financial district and Rome's tourism corridors, where dense urban cores and complex historic street grids create premium accuracy requirements. The segment captures the largest revenue pool given Italy's infrastructure complexity.
- Advertising:Fuses geospatial coordinates with contextual data streams to deliver proximity-triggered promotions via beacon mesh networks. Venetian retail clusters and Florentine museum complexes are expanding deployments fastest as institutions seek direct visitor journey analytics ownership. Procurement teams now negotiate directly with beacon network operators, bypassing traditional agency intermediaries.
- Tracking:Enables real-time asset visibility through hybrid cloud platforms blending telemetry with historic spatial databases. Mediterranean logistics corridors drive adoption for fleet optimization.
- Analytics:Processes spatial data streams to generate behavioral pattern recognition and footfall attribution. Smart city procurement mandates from the Italian Agency for Digital Transformation accelerate municipal adoption.
Volume sits with Navigation; growth tilts toward Advertising.
Technology:
Technology selection follows accuracy thresholds and power consumption trade-offs, with indoor versus outdoor use cases dictating hardware procurement specifications.
- GPS:Satellite-based positioning delivering meter-level accuracy for outdoor navigation and fleet management. National road network coverage investments by automotive-focused vendors sustain deployment.
- Wi-Fi:Indoor fingerprinting systems leveraging existing infrastructure for sub-ten-meter accuracy. Retail and hospitality sectors in historic urban centers favor this for lower capex requirements.
- RFID:Passive and active tag systems for controlled-environment asset tracking. Healthcare facilities deploy for equipment location in large hospital complexes.
- Bluetooth:Low-energy beacon mesh networks achieving centimeter-accuracy through ultra-wideband positioning. Milan's financial district deploys this for high-value document workflows, absorbing premium service tier margins as accuracy thresholds tighten.
Deployment scale favors GPS; margin expansion concentrates in Bluetooth.
End User:
End-user segmentation reflects diverging compliance burdens, with public infrastructure facing EU AI Act risk-classification mandates that private retail deployments largely avoid.
- Retail:Proximity marketing and indoor navigation for customer journey optimization. Venetian retail clusters and Florentine museum complexes lead beacon density expansion.
- Transportation:Fleet optimization algorithms and transit hub passenger flow management. Mediterranean logistics corridors drive cloud-elastic compute adoption for seasonal freight surges.
- Healthcare:Asset tracking and patient flow analytics with strict GDPR-derived consent requirements. Large hospital complexes in northern Italy prioritize RFID for equipment location.
- Tourism:Indoor positioning in transit hubs connecting historic districts, multilingual wayfinding, and cultural institution visitor analytics. Rome's tourism corridors show unmet demand for enhanced navigation infrastructure.
Revenue concentration rests with Retail; regulatory complexity peaks in Healthcare.
Deployment:
Deployment architecture decisions hinge on data residency requirements and compute elasticity needs, with mid-market logistics operators facing particular capex barriers.
- On-Premise:Localized server infrastructure for sensitive spatial data processing. Healthcare and financial services procurement favor this for GDPR compliance control.
- Cloud:Elastic compute resources scaling with seasonal demand fluctuations. Mid-market logistics operators capture disproportionate margin attention for freight surge management.
- Hybrid:Blends real-time telemetry with legacy spatial databases. Integration costs create barriers for smaller operators despite performance advantages.
- Mobile:Edge-processing on consumer and enterprise devices with intermittent connectivity support. Tourism applications prioritize offline functionality for international visitors.
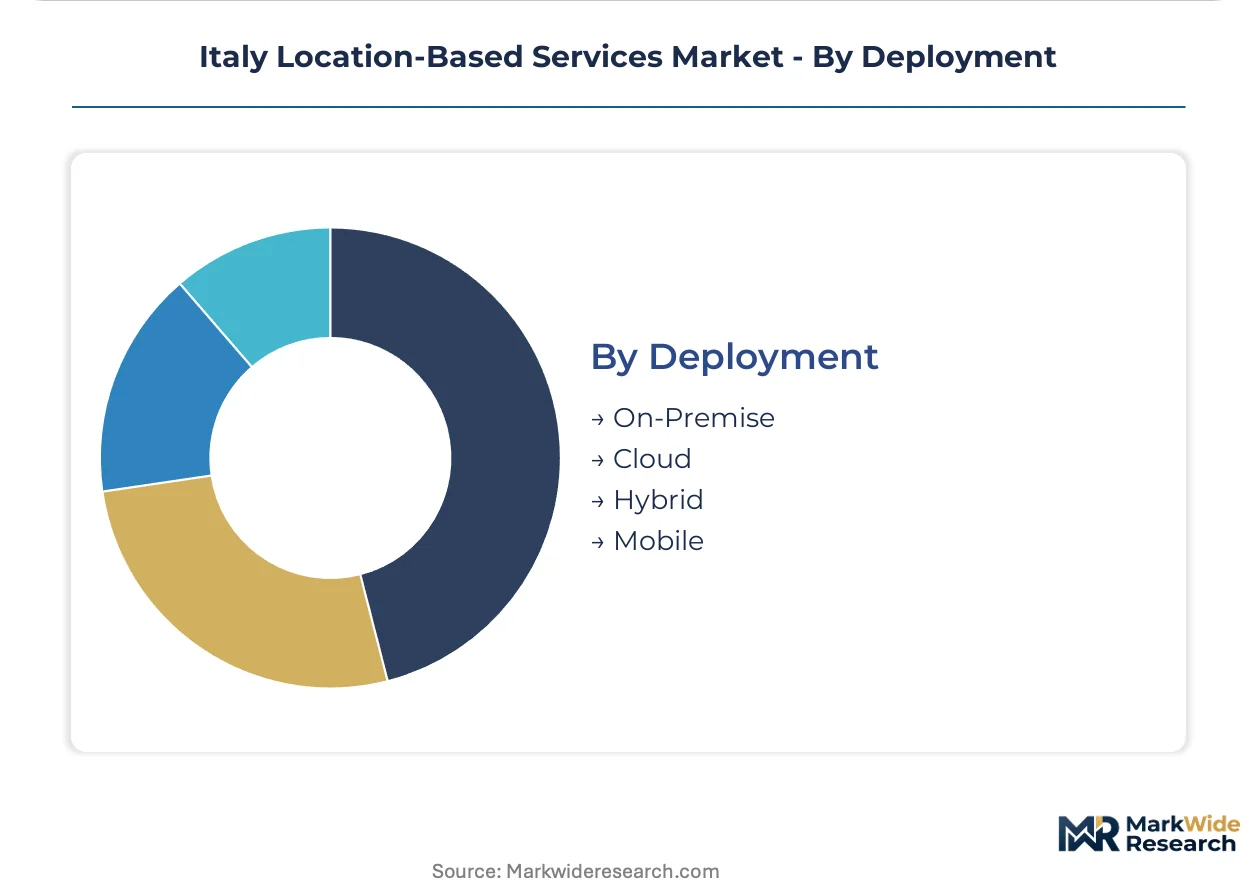
Hybrid captures technical preference; Cloud secures fastest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian location-based services demand concentrates in northern industrial corridors and central tourism arteries, with procurement patterns diverging sharply between logistics-heavy sub-regions and heritage-focused urban centers.
Lombardy
Milan's financial district drives centimeter-accuracy asset tracking demand for high-value document workflows. The Italian Agency for Digital Transformation mandates location-aware infrastructure in municipal renewal contracts affecting the metropolitan area. Bergamo and Brescia logistics clusters deploy cloud-elastic compute for seasonal freight surge management across Mediterranean corridors.
Veneto
Venetian retail clusters expand sub-ten-meter accuracy beacon networks for proximity marketing at unprecedented density. GDPR-derived consent requirements enforced by Italy's national data protection authority shape customer acquisition protocols. Padua and Verona industrial zones integrate hybrid cloud platforms blending real-time telemetry with legacy spatial databases.
Tuscany
Florentine museum complexes lead cultural institution adoption of direct visitor journey analytics ownership. The EU AI Act's risk-classification mandates for automated spatial decision systems constrain smart city procurement specifications. Pisa and Livorno port logistics operators prioritize fleet optimization algorithms tailored to Mediterranean shipping routes.
Lazio
Rome's tourism corridors exhibit unmet demand for indoor positioning in transit hubs connecting historic districts. National smart city directives coordinated through the Italian Agency for Digital Transformation accelerate municipal LBS integration timelines. Fiumicino airport and surrounding logistics zones drive cloud deployment adoption for passenger flow management systems.
Piedmont
Turin's automotive manufacturing heritage sustains demand for high-definition road network coverage serving connected vehicle programs. Italy's national data protection authority enforces explicit opt-in requirements for persistent geotracking applications. The Alpine logistics corridor bordering France and Switzerland concentrates fleet optimization technology deployment for cross-border freight.
Italy Location-Based Services Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors position for EU AI Act compliance mandates and smart city procurement cycles. The vendor base organizes around three distinct tiers: global mapping platforms with automotive anchor clients, cloud-native entrants specializing in retail proximity marketing, and legacy enterprise IT providers repurposing infrastructure portfolios. Two strategic archetypes have crystallized: accuracy-specialized positioning technology vendors and compliance-forward system integrators. M&A activity and technology licensing agreements represent the primary competitive vectors as firms seek to fuse 5G positioning capabilities with Bluetooth mesh redundancy.
Within the global mapping platform tier, Google and HERE Technologies anchor contrasting positioning strategies, with the former exemplifying cloud-native indoor capabilities and the latter representing automotive-grade road network specialization. TomTom occupies a distinct position among fleet optimization specialists targeting Mediterranean logistics corridors. These three entities collectively represent the competitive fault lines around which mid-market Italian operators and municipal procurement teams negotiate service architectures.
| Leading Market Players |
|---|
| HERE Technologies |
| TomTom |
| Apple |
| Esri Italia |
| IBM Corporation |
| Cisco Systems |
| Zebra Technologies Corporation |
| Microsoft |
| Others |
Pricing and Supply Chain Analysis
Ultra-wideband positioning adoption is compressing cost curves for centimeter-accuracy hardware while concentrating procurement power among automotive-grade chipset vendors serving Milan's financial district. This technology shift simultaneously erodes legacy Wi-Fi fingerprinting margins and tightens supply control among three dominant semiconductor fabricators.
Pricing Analysis
Warranty and service-bundling unbundling distinguishes vendor tiers, with premium positioning providers including algorithmic impact assessment tooling for EU AI Act compliance while economy tiers strip out legal support. Three-tier pricing structure across premium, standard, and economy levels tracks accuracy thresholds and data residency guarantees. Cost compression in the standard tier is intensifying because mid-market logistics operators demand elastic compute without compliance overhead. Municipal procurement teams show lowest price sensitivity given mandate-driven budgets, while retail beacon operators face acute margin pressure from direct-to-network disintermediation.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based foundries fabricating ultra-wideband chipsets for centimeter-accuracy modules. Hardware assembly draws from China, South Korea, and Vietnam, with final integration clustering in Germany and the Netherlands for EU regulatory proximity. Raw material dependencies include gallium arsenide substrates, precision MEMS components, and rare-earth magnets for antenna arrays. Tariff exposure on semiconductor imports from East Asia threatens margin stability for Italian system integrators. Distribution runs through authorized value-added resellers with smart city certification credentials, bypassing traditional IT distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italian location-based services function as a supply-constrained market where geospatial data science talent scarcity props pricing power for qualified system integrators. Capacity bottlenecks in certified algorithmic impact assessment services sustain premium tier margins.
For Market Incumbents: Lock in municipal procurement relationships through SPID interoperability certification before the Italian Agency for Digital Transformation tightens vendor pool requirements. Acquire boutique compliance consultancies specializing in EU AI Act risk-classification tooling to defend against cloud-native entrants unbundling legal advisory from core positioning services. Vertical integration into ultra-wideband chipset sourcing mitigates Taiwan foundry concentration risk.
For New Entrants and Emerging Players: AI-first wedge positioning for automated spatial decision systems in Florentine museum complexes bypasses entrenched navigation incumbents. Target Rome's tourism corridor indoor positioning gap with multilingual edge-processing solutions that operate offline for international visitors. Go-to-market through direct beacon network operator relationships rather than legacy agency channels.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by global mapping platforms seeking EU AI Act compliance capabilities. Five-to-ten-year viability hinges on algorithmic audit tooling differentiation rather than raw positioning accuracy. Target acquisition archetypes combine geospatial data science talent with existing SPID-certified municipal contracts. Watch cellular triangulation-beacon convergence patent filings as inflection indicator for technology obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Mandates algorithmic impact assessments for smart city procurement eligibility in Milan and Rome. |
| Ultra-Wideband Chipset Supply Agreement | Secures Taiwan foundry allocation for centimeter-accuracy asset tracking in financial districts. |
| SPID Interoperability Integration | Enables municipal procurement compliance with Italy's national digital identity framework. |
| Beacon Network Operator Acquisition | Captures direct retail relationships bypassing disintermediated agency intermediaries. |
| Geospatial Data Science Talent Recruitment | Addresses scarcity in spatial statistics and real-time stream processing for hybrid cloud platforms. |
Research Methodology
Document review covered EU regulatory filings, Italian smart city procurement databases, and hyperscaler capex disclosures, complemented by interviews with municipal IT directors, beacon network operators, logistics procurement leads, and geospatial data scientists. Secondary validation drew from GDPR enforcement actions by Italy's national data protection authority, automotive OEM platform engineering specifications, and cloud provider infrastructure expansion announcements. Bottom-up service type demand modeling triangulated against top-down regional IT spending forecasts.
Segmentation outputs across service type, technology, end user, and deployment architecture informed revenue allocation across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves incorporating EU AI Act implementation timelines and smart city mandate acceleration. Forecast inputs included Bluetooth beacon density trajectories in Venetian retail clusters and fleet optimization algorithm deployment patterns across Mediterranean logistics corridors.
Several conditions sit outside the modeled scope, including unforeseen GDPR enforcement severity shifts, geopolitical disruption to Taiwan semiconductor supply, and breakthrough alternative positioning technologies. Forecasts reflect documented assumptions about regulatory implementation pacing and infrastructure investment continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Europe 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
India Satellite Imagery Services Market
Geographic Information Systems (GIS)
IP Geo-Location Services Market
Geographic Information Systems (GIS)
Spain Location-Based Services Market
Geographic Information Systems (GIS)
Global GIS in Telecom Sector Market
Geographic Information Systems (GIS)
Europe Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
China Geospatial Analytics Market
Geographic Information Systems (GIS)
Saudi Arabia Location-Based Services Market
Geographic Information Systems (GIS)
Canada Geospatial Analytics Market
Geographic Information Systems (GIS)
India Location-Based Services Market
Geographic Information Systems (GIS)
Global Geospatial Solutions Market
Geographic Information Systems (GIS)
Asia Pacific Digital Maps Market
Geographic Information Systems (GIS)
Japan Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Russia Geospatial Analytics Market
Geographic Information Systems (GIS)
Geomarketing Market
Geographic Information Systems (GIS)
Japan Location-Based Services Market