
 Europe Air Separation Unit Market | 2026-2036
Europe Air Separation Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Air Separation Unit Market Foresight
Buyer concentration among European steelmakers and chemical conglomerates is shifting toward long-term on-site gas supply contracts with embedded ASU ownership. Air Liquide SA anchors its position through extensive pipeline networks serving the Antwerp-Rotterdam chemical cluster. Linde PLC leverages proprietary cryogenic technology to sustain margins in large-tonnage oxygen production. Messer Group GmbH competes through specialized nitrogen solutions for food freezing and electronics manufacturing.
Europe Air Separation Unit refers to industrial systems that fractionate atmospheric air into component gases—principally oxygen, nitrogen, and argon—through cryogenic distillation at temperatures below minus 180 degrees Celsius or via pressure swing adsorption using molecular sieves. These units supply high-purity gases for steelmaking, chemical synthesis, medical therapy, and semiconductor fabrication. Cryogenic ASU dominates capacity installations across the region due to superior purity thresholds and economies of scale in baseload operations. PSA ASU segments are gaining traction in decentralized healthcare and small-scale metal fabrication where mobility and lower capital outlays matter more than peak purity. Modular installation configurations are expanding fastest as industrial parks seek phased capacity additions without centralized infrastructure commitments.
EU Green Deal emission benchmarks and REACH chemical safety protocols are tightening product standards for ASU materials and refrigerants used in European manufacturing. ECHA's fluorinated gas restrictions are phasing out certain cooling agents, compelling equipment redesigns across member states. CE marking requirements under the EU's Machinery Directive govern market access for imported ASU components. Stakeholders must monitor how carbon border adjustment mechanisms reshape the cost calculus for imported versus domestically manufactured gas separation equipment.
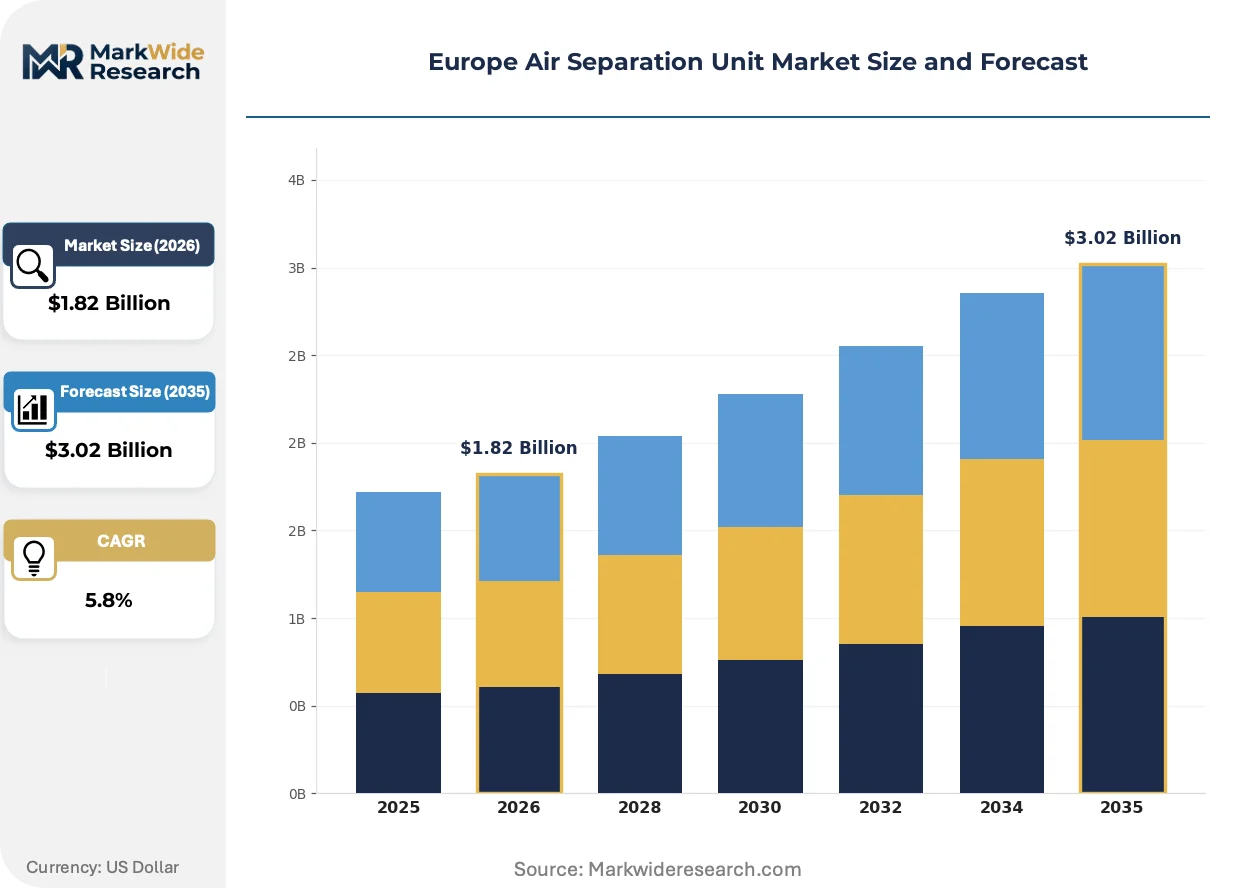
Market Dynamics
Steel decarbonization mandates under the EU Green Deal are forcing industrial gas suppliers to reconfigure on-site oxygen production infrastructure across the Rhine-Ruhr corridor and Polish industrial belts.
Growth Catalysts
- Electric arc furnace expansion:Steelmakers in Germany and Poland are signing long-term oxygen supply contracts tied to scrap-based steelmaking retrofits. Cryogenic ASU installations are scaling to meet baseload demand from these facilities.
- REACH chemical safety protocols:Tighter refrigerant standards are accelerating equipment replacement cycles. ASU manufacturers are capturing upgrade revenue from compliance-driven retrofits.
- Antwerp-Rotterdam pipeline networks:Dedicated nitrogen supply to chemical clusters is locking in captive demand. Integrated pipeline systems are creating infrastructure moats for incumbent suppliers.
Market Restraints
- Fluorinated gas input volatility:ECHA's F-Gas Regulation is constraining cooling agent availability. Equipment redesign costs are compressing margins for modular ASU producers.
- Specialized cryogenic steel concentration:High-grade stainless supply for cold boxes concentrates among Nordic and German metallurgical suppliers. Geographic concentration creates vulnerability to energy price shocks.
- PSA purity ceiling:Pressure swing adsorption cannot match cryogenic thresholds for semiconductor-grade nitrogen. Technical limitation cements cryogenic dominance in electronics manufacturing.
Strategic Opportunities
- Portuguese industrial park greenfield development:Sines industrial zone lacks established gas pipeline infrastructure. Modular ASU configurations can capture phased capacity buildouts without centralized commitments.
- Hydrogen economy convergence:Electrolyzer projects require nitrogen blanketing and oxygen enrichment. ASU suppliers are positioning alongside green hydrogen clusters in the Netherlands and Denmark.
- CSRD disclosure mandates:Corporate sustainability reporting is elevating Scope 3 emissions scrutiny. On-site gas generation is displacing trucked liquid supply for carbon-conscious chemical processors.
Industry Challenges
- Cryogenic welder scarcity:Specialized aluminum welding for cold box fabrication faces talent pipeline gaps. German and Austrian technical institutes are struggling to replace retiring craft specialists.
- CE marking timeline compression:Machinery Directive compliance for imported ASU components is extending project lead times. Certification bottlenecks are delaying modular deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Air Separation Unit Market |
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.02 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryogenic ASU, PSA ASU, Vacuum Pressure Swing Adsorption, Membrane Separation End User: Chemicals, Metals, Energy, Healthcare Technology: Carbon Dioxide Removal, Oxygen Production, Nitrogen Generation, Hydrogen Purification Installation: On-site, Modular, Centralized, Decentralized |
| Companies Covered | Air Products & Chemicals, Inc., SOL SpA, Air Liquide SA, Enerflex Ltd, Taiyo Nippon Sanso Corporation, Linde PLC, Messer Group GmbH, Matheson Tri-Gas Europe GmbH, SIAD Macchine Impianti SpA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Air Separation Unit Market Shifts & Advancements
Digital process control and modular system architecture are converging to reshape how industrial gases are produced and delivered across European manufacturing corridors.
Advanced process control software is integrating machine learning algorithms into cryogenic distillation operations. BASF and Dow chemical complexes in Germany are piloting these systems to optimize argon recovery rates. Real-time sensor integration is compressing energy consumption per ton of separated gas.
EU F-Gas Regulation amendments are phasing down hydrofluorocarbon refrigerants in ASU cooling circuits. Equipment manufacturers are redesigning heat exchangers to accommodate natural refrigerant alternatives. Cryogenic ASU segments in France and Belgium are absorbing the highest compliance costs due to legacy infrastructure density.
Take-or-pay contract structures are displacing spot market purchases among large chemical processors. Air Liquide and Linde are unbundling maintenance services from gas supply agreements in the Netherlands. This shift is most visible in Rotterdam's chemical cluster where buyers seek operational flexibility without capital ownership.
Europe Air Separation Unit Market Segmentation
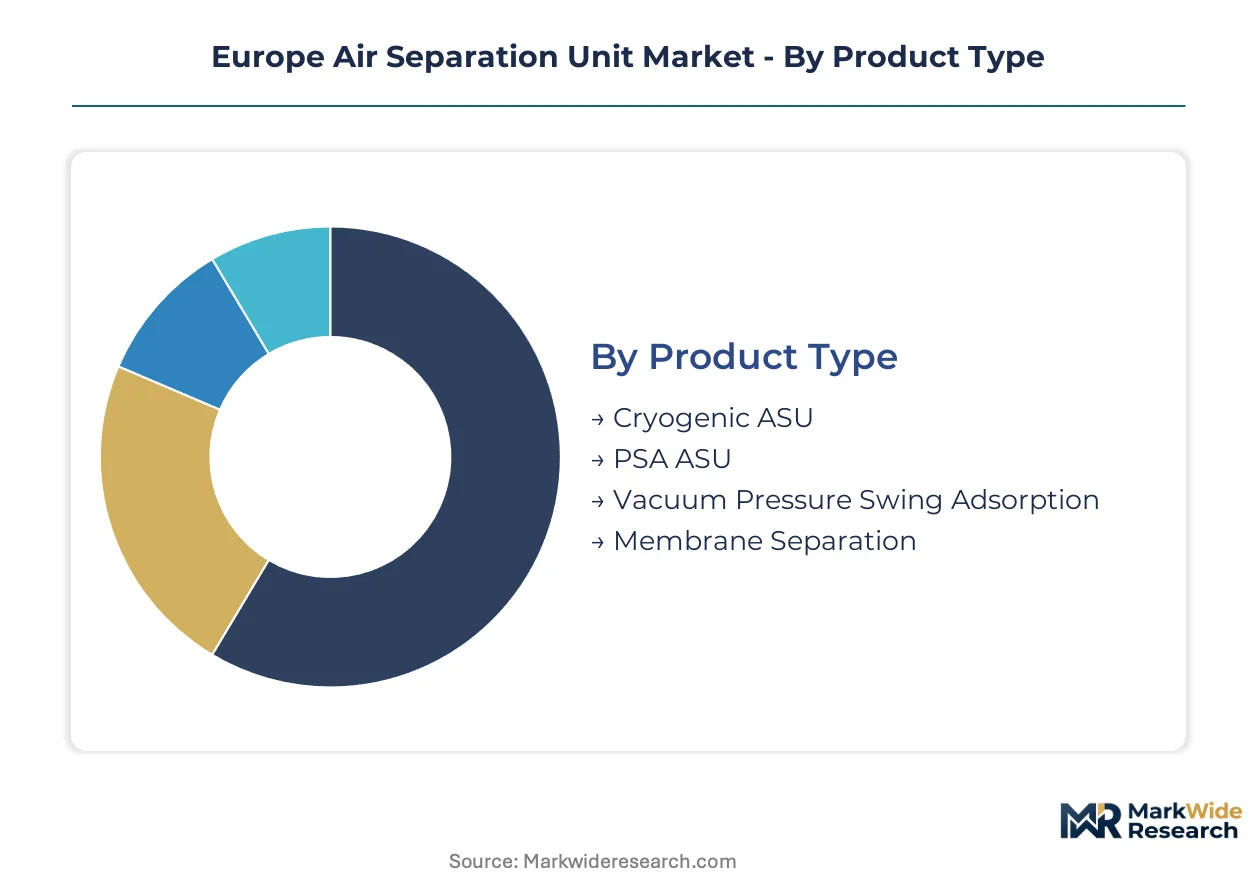
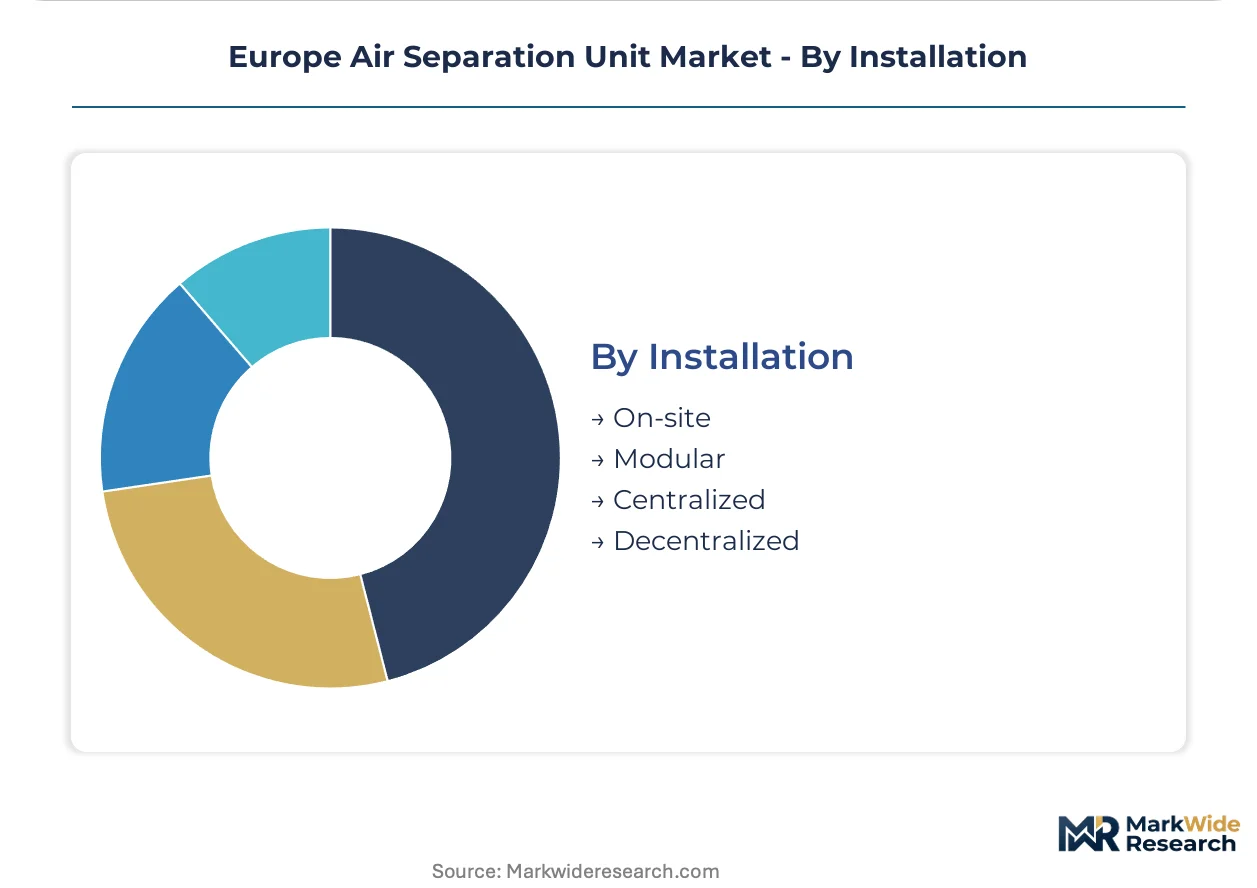
Air separation technology in Europe fragments across four structural dimensions that determine capital intensity, purity thresholds, and customer lock-in duration. Product type and installation mode together dictate whether suppliers capture revenue through equipment sales or long-term gas supply contracts.
Product Type:
Cryogenic systems dominate integrated industrial complexes where purity specifications exceed 99.9 percent, while adsorption technologies serve distributed demand nodes lacking pipeline connectivity.
- Cryogenic ASU:Fractionates air through multi-stage distillation at temperatures below minus 180 degrees Celsius. Rhine-Ruhr steelmakers and Antwerp-Rotterdam chemical clusters anchor demand for these baseload installations. ECHA F-Gas Regulation compliance costs are accelerating equipment replacement cycles among legacy operators.
- PSA ASU:Separates gases via molecular sieve adsorption under pressure swing cycles. Polish metal fabricators and Italian food processors are expanding deployments where mobility outweighs peak purity requirements. REACH refrigerant restrictions pose lighter compliance burdens than cryogenic alternatives.
- Vacuum Pressure Swing Adsorption:Operates at sub-atmospheric desorption pressures for enhanced nitrogen recovery. German electronics manufacturers utilize VPSA for cleanroom blanketing applications.
- Membrane Separation:Deploys hollow-fiber polymer membranes for low-purity oxygen enrichment. Portuguese industrial parks and remote Nordic forestry operations favor these units for sub-90 percent purity requirements.
Volume placements concentrate in Cryogenic ASU; the faster expansion belongs to PSA ASU.
End User:
Customer archetypes span process industries with divergent purity specifications, volume predictability, and contract tenure preferences.
- Chemicals:BASF and Dow complexes in Germany require nitrogen blanketing for reactor inerting and argon for analytical instrumentation. Antwerp-Rotterdam pipeline networks lock in multi-decade supply relationships with embedded ASU ownership.
- Metals:Electric arc furnace operators in Germany and Poland are the dominant oxygen consumers. Scrap-based steelmaking retrofits are displacing blast furnace gas demand across the Rhine-Ruhr corridor.
- Energy:Hydrogen electrolyzer projects in the Netherlands and Denmark require nitrogen for system purging and oxygen enrichment for efficiency gains. Green hydrogen clusters are emerging as a parallel demand vector.
- Healthcare:Hospital networks and home oxygen therapy providers favor PSA units for decentralized medical gas production. CSRD disclosure mandates are elevating preference for on-site generation over trucked liquid supply.
Chemicals commands the largest installed base; Energy is climbing the fastest as electrolyzer buildouts accelerate.
Technology:
Process capabilities within ASU systems align with specific gas output requirements and contaminant removal challenges.
- Carbon Dioxide Removal:Pre-treatment systems extract CO2 and water vapor to prevent cryogenic freezing. EU Green Deal emission benchmarks are tightening specifications for pre-purification unit efficiency.
- Oxygen Production:Distillation columns separate oxygen from nitrogen through boiling point differentials. Steel decarbonization mandates are scaling demand for high-tonnage oxygen supply.
- Nitrogen Generation:Produces inert atmospheres for chemical synthesis and electronics manufacturing. Semiconductor-grade nitrogen requires cryogenic thresholds that PSA cannot achieve.
- Hydrogen Purification:Membrane and cryogenic systems refine hydrogen streams for fuel cell and industrial applications. Dutch hydrogen backbone projects are piloting integrated ASU-hydrogen purification configurations.
Oxygen production retains the deepest capacity footprint; hydrogen purification is gaining share fastest amid electrolyzer deployment.
Installation:
Physical configuration determines capital commitment phasing and operational control distribution between gas supplier and end user.
- On-site:Dedicated ASU assets owned and operated by industrial gas majors at customer premises. Long-term take-or-pay contracts with 15-20 year tenures characterize German steelmaker arrangements.
- Modular:Skid-mounted units enabling phased capacity expansion without centralized infrastructure. Sines industrial zone in Portugal and emerging Eastern European manufacturing parks favor this flexibility.
- Centralized:Large-tonnage facilities feeding pipeline networks and liquid merchant markets. Antwerp-Rotterdam and Rhine-Ruhr corridors host the densest centralized infrastructure.
- Decentralized:Small-scale PSA and membrane units serving single facilities or distributed healthcare nodes. CE marking timeline compression is extending deployment schedules for imported modular components.
Centralized installations anchor revenue stability; modular configurations are expanding most quickly in greenfield industrial zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-grade stainless steel from Nordic and German metallurgical suppliers anchors cryogenic cold box fabrication across European industrial corridors. Energy price volatility in these feedstock regions cascades into ASU equipment costs. Pipeline nitrogen networks and steel decarbonization mandates concentrate demand in specific national manufacturing belts.
Germany
Rhine-Ruhr steelmakers and BASF chemical complexes drive cryogenic oxygen and nitrogen demand. EU Green Deal industrial decarbonization mandates accelerate electric arc furnace retrofits requiring dedicated on-site gas supply. The Antwerp-Rotterdam pipeline network extends into German chemical clusters, locking in multi-decade infrastructure commitments.
Poland
Scrap-based steelmaking expansion and metal fabrication growth propel oxygen consumption across Polish industrial belts. ECHA F-Gas Regulation compliance costs burden legacy cryogenic equipment operators. The Silesian manufacturing corridor hosts emerging modular ASU deployments for phased capacity buildouts.
Netherlands
Rotterdam chemical processors and green hydrogen electrolyzer projects require nitrogen blanketing and oxygen enrichment. CE marking timeline compression under the EU Machinery Directive delays imported component deliveries. The Port of Rotterdam cluster anchors integrated pipeline networks serving BASF and Dow facilities.
France
Legacy cryogenic infrastructure density concentrates F-Gas Regulation compliance costs in French ASU operations. Air Liquide SA maintains extensive pipeline networks serving Lyon and Paris chemical manufacturing zones. Semiconductor-grade nitrogen demand from Grenoble electronics clusters sustains cryogenic technology dominance.
Portugal
Sines industrial zone greenfield development lacks established gas pipeline infrastructure. Modular ASU configurations capture phased capacity buildouts without centralized commitments. National industrial policy supports decentralized gas generation for carbon-conscious processors under CSRD disclosure mandates.
Europe Air Separation Unit Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized nitrogen solutions and modular configurations. The market consolidates around integrated gas suppliers with captive pipeline networks and long-term take-or-pay contracts. Three archetypes dominate: diversified industrial gas majors with infrastructure moats, specialized cryogenic technology licensors, and regional modular fabricators serving decentralized demand. Competitive intensity centers on M&A activity for pipeline network expansion and strategic partnerships with hydrogen electrolyzer developers.
Among Germany-based industrial gas suppliers, Messer Group GmbH exemplifies the specialized nitrogen solutions archetype for food freezing and electronics manufacturing. French-origin diversified majors occupy positions anchored by extensive pipeline networks serving chemical clusters. Japanese-origin industrial gas corporations represent technology licensors with proprietary cryogenic distillation capabilities. Italian machinery specialists and North American diversified gas suppliers round out the competitive set across equipment fabrication and gas supply contract segments.
| Leading Market Players |
|---|
| Air Products & Chemicals, Inc. |
| SOL SpA |
| Air Liquide SA |
| Enerflex Ltd |
| Taiyo Nippon Sanso Corporation |
| Linde PLC |
| Messer Group GmbH |
| Matheson Tri-Gas Europe GmbH |
| SIAD Macchine Impianti SpA |
| Others |
Supply & Pricing Matrix
Long-term take-or-pay contracts from German steelmakers and Rotterdam chemical processors are compressing spot market liquidity and forcing equipment suppliers toward bundled service models that embed maintenance and refrigerant compliance costs into decade-long pricing structures.
Pricing Analysis
Warranty and service bundling now separates incumbent industrial gas majors from modular equipment vendors across European ASU procurement. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with cryogenic cold boxes commanding premiums for ECHA F-Gas Regulation compliance. Cost compression in modular PSA segments is intensifying because CE marking timeline extensions are inflating project overhead. Polish metal fabricators exhibit highest price sensitivity due to fragmented demand, while Antwerp-Rotterdam chemical clusters accept premium positioning for pipeline-integrated supply security.
Supply Chain Analysis
Refurbishment flows for cryogenic cold boxes and heat exchanger cores are creating secondary supply channels that extend asset life cycles and dampen new equipment demand. High-grade stainless steel concentrates in Germany, Finland, and Sweden, with specialized aluminum welding for cold box fabrication drawing from Austrian and German technical institutes. Supply chain risk centers on single-source vulnerability for cryogenic-grade nickel alloys from Nordic metallurgical suppliers. Distribution runs through direct OEM relationships for large-tonnage installations and regional machinery distributors for decentralized PSA deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
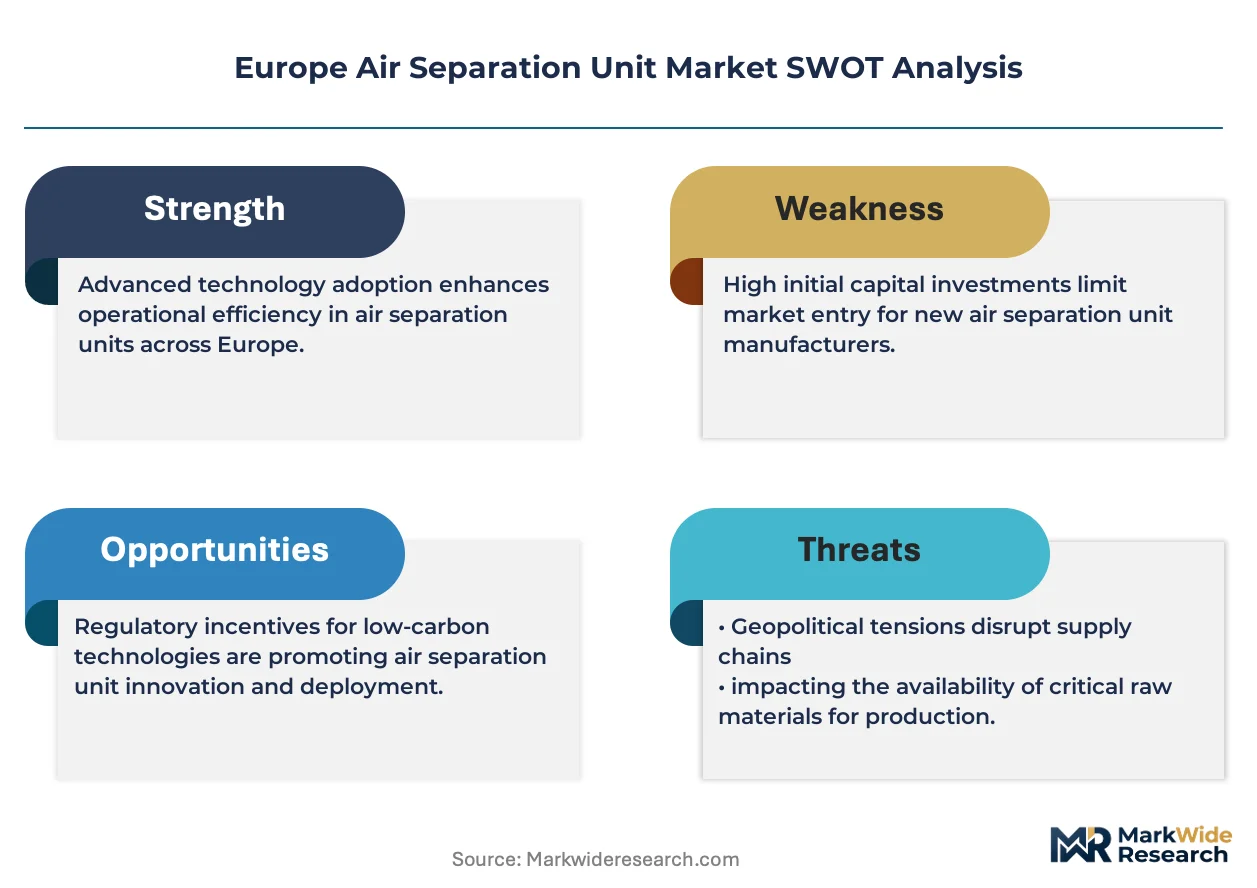
ECHA F-Gas Regulation compliance costs function as a barrier-to-entry moat that favors incumbent industrial gas majors with legacy infrastructure retrofit capabilities over capital-constrained modular entrants.
For Market Incumbents: Deploy backward integration into specialized cryogenic steel supply through offtake agreements with Nordic metallurgical suppliers. Air Liquide and Linde should expand pipeline network density across the Rhine-Ruhr corridor to lock in chemical processor demand before hydrogen electrolyzer projects fragment nitrogen supply relationships. CE marking certification investments will defend against modular competitors facing Machinery Directive timeline compression. For New Entrants and Emerging Players: Enter via Portuguese industrial park greenfield development where absent pipeline infrastructure eliminates incumbent infrastructure moats. Sines industrial zone and Eastern European manufacturing parks offer the most penetrable geographies for skid-mounted modular configurations. Target food freezing and electronics manufacturing segments where Messer Group's specialized nitrogen focus has validated premium positioning for mid-scale deployments. For Investors and Strategic Acquirers: The window for entry favors diversified industrial gas majors with captive pipeline networks over pure-play equipment fabricators. Long-term viability hinges on positioning alongside green hydrogen clusters in the Netherlands and Denmark where electrolyzer buildouts create parallel ASU demand. Monitor ECHA F-Gas Regulation amendment timing as the critical inflection signal for equipment replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cryogenic Steel Supply | Nordic metallurgical offtake agreements secure nickel alloy access against energy price volatility. |
| Pipeline Network Expansion | Rhine-Ruhr corridor density locks in BASF and Dow chemical complexes before hydrogen fragmentation. |
| Modular Configuration Development | Skid-mounted units capture Sines industrial zone greenfield demand without centralized infrastructure. |
| F-Gas Compliance Retrofit Services | Legacy equipment upgrade revenue accelerates as EHA refrigerant restrictions tighten. |
| Hydrogen Cluster Partnership | Electrolyzer nitrogen blanketing contracts in Rotterdam and Denmark diversify beyond steel oxygen demand. |
Research Methodology
Document review covered ECHA regulatory filings, EU customs trade data for cryogenic equipment, and industrial gas major SEC disclosures, complemented by interviews with plant engineers at German steelmakers, procurement leads at Rotterdam chemical processors, and aftermarket service heads at modular ASU fabricators. Secondary validation drew from Cefic chemical industry reports, EU Machinery Directive implementation guidance, and hydrogen project development databases. Bottom-up installation forecasts triangulated against top-down industrial gas demand projections.
Installed base and revenue outputs were generated through multi-dimensional segmentation across product type, end-use industry, and installation configuration, with growth rates derived from capacity addition pipelines and contract tenure analysis. Cryogenic versus PSA technology split, steel decarbonization retrofit timelines, and F-Gas Regulation compliance cost absorption rates served as primary forecast inputs across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Green Deal emission benchmark revisions or prolonged CE marking certification delays. Practitioners should monitor ECHA F-Gas Regulation amendment schedules and Nordic metallurgical supplier energy cost indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Compact Wheel Loaders Market
Others
Hot Air System Market
Others
Hardwood Market
Others
Paper Shredder Market
Others
Semiconductor Gas Filters Market
Others
North America Ultraviolet Disinfection Equipment Market
Others
Inorganic Tin Chemicals Market
Others
Tote Bags Market
Others
Cellular-Connected Laptops Market
Others
Italy 3D Printing Construction Market
Others
Thailand Travel Retail Market
Others
France Location-Based Services Market
Others
Coriolis Meters Market
Others
Insoluble Sulfur Market
Others
Connected Homes Market
Others
Middle East and Africa Electric Vehicle Battery Electrolyte Market