
 Recreational and Vacation Camp Market | 2026-2036
Recreational and Vacation Camp Market Size, Share, and Industry Trends Forecast 2026-2036
Recreational and Vacation Camp Market Insights
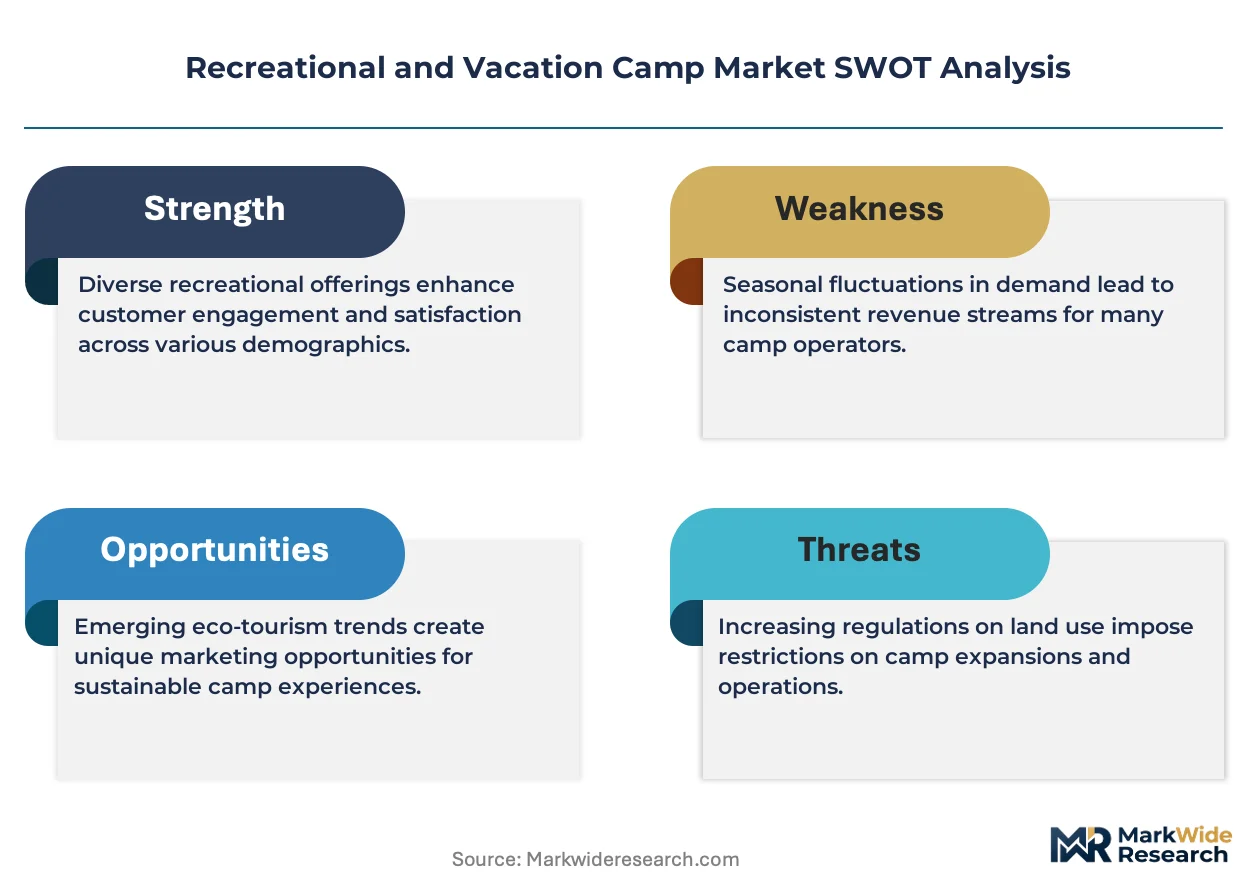
Sustainable timber-frame construction is repositioning capital deployment across the camp development cycle, lowering lifecycle maintenance costs versus traditional stick-built cabins. Great Wolf Lodge leverages its indoor waterpark integration to anchor year-round occupancy in weather-dependent markets. Timber Lake Camp sustains premium positioning through specialized backcountry programming that differentiates it from resort-style competitors. Outward Bound USA dominates expedition-based segments with rigorous safety protocols that extend its brand authority into corporate training contracts.
Recreational and vacation camps comprise organized temporary accommodation facilities offering structured outdoor recreation, educational programming, and communal lodging typically situated in natural or semi-wilderness settings, with capacity ranging from twenty to five hundred guests and operational seasons spanning eight to twenty-four weeks annually. These facilities serve primary commercial purposes of leisure tourism, youth development, and wellness retreat hosting, generating revenue through per-capita weekly fees and ancillary activity charges. Summer camps occupy the largest revenue pool within camp type segmentation, while glamping sites within facility type segmentation command the highest per-night margins due to capital-light site preparation and elevated pricing tolerance among experience-seeking adults. Family-oriented programming across target age group segmentation is expanding fastest, though teen-focused adventure camps retain the most predictable re-enrollment economics.
The U.S. Forest Service Special Use Permit system and state-level health department sanitation codes jointly govern site access and operational compliance, with the former restricting development density on federal lands and the latter mandating potable water and waste management infrastructure that shapes facility design costs. The American Camp Association accreditation standards function as a de facto market access filter, with non-accredited operators facing exclusion from school district vendor lists and insurance premium penalties. Stakeholders must monitor evolving state childcare licensing harmonization efforts, as regulatory fragmentation between jurisdictions currently constrains multi-state operator scaling strategies.
Market Dynamics
Multigenerational family travel preferences are compressing booking windows and forcing operators to reconfigure programming calendars around school district schedules rather than traditional seasonal patterns.
Growth Catalysts
- Special Use Permit streamlining:Proposed U.S. Forest Service administrative reforms are reducing application review timelines for established operators seeking capacity expansions on federal lands.
- Timber-frame construction methods:Engineered wood systems are cutting onsite build times by half versus conventional framing, accelerating capital deployment cycles for new site development.
- Colorado River Basin clustering:Concentrated demand in western states with established outdoor recreation infrastructure is sustaining premium pricing power through limited site availability.
Market Restraints
- Lumber and engineered wood input volatility:Commodity price swings for cross-laminated timber and glulam beams are distorting project feasibility assessments during permitting phases.
- Federal land access concentration:Reliance on U.S. Forest Service permit allocations creates bottleneck risk when environmental review timelines extend unexpectedly.
- State childcare licensing fragmentation:Non-harmonized requirements across jurisdictions force multi-state operators to maintain redundant compliance infrastructure.
Strategic Opportunities
- Corporate wellness retreat expansion:Employer-sponsored outdoor programming represents underpenetrated B2B demand with higher per-capita spend than traditional family bookings.
- Infrastructure Investment and Jobs Act outdoor recreation provisions:Federal trail and access infrastructure spending is improving connectivity to remote camp locations previously deemed inaccessible.
- Mobile glamping unit deployment:Modular luxury tent systems enable rapid market testing in new geographies without permanent capital commitment.
Industry Challenges
- Seasonal workforce retention:Competition from hospitality and logistics sectors for outdoor recreation instructors is compressing available talent pools during peak operating months.
- American Camp Association accreditation timelines:Multi-year preparation requirements for first-time applicants delay market entry and restrict access to school district vendor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recreational and Vacation Camp Market |
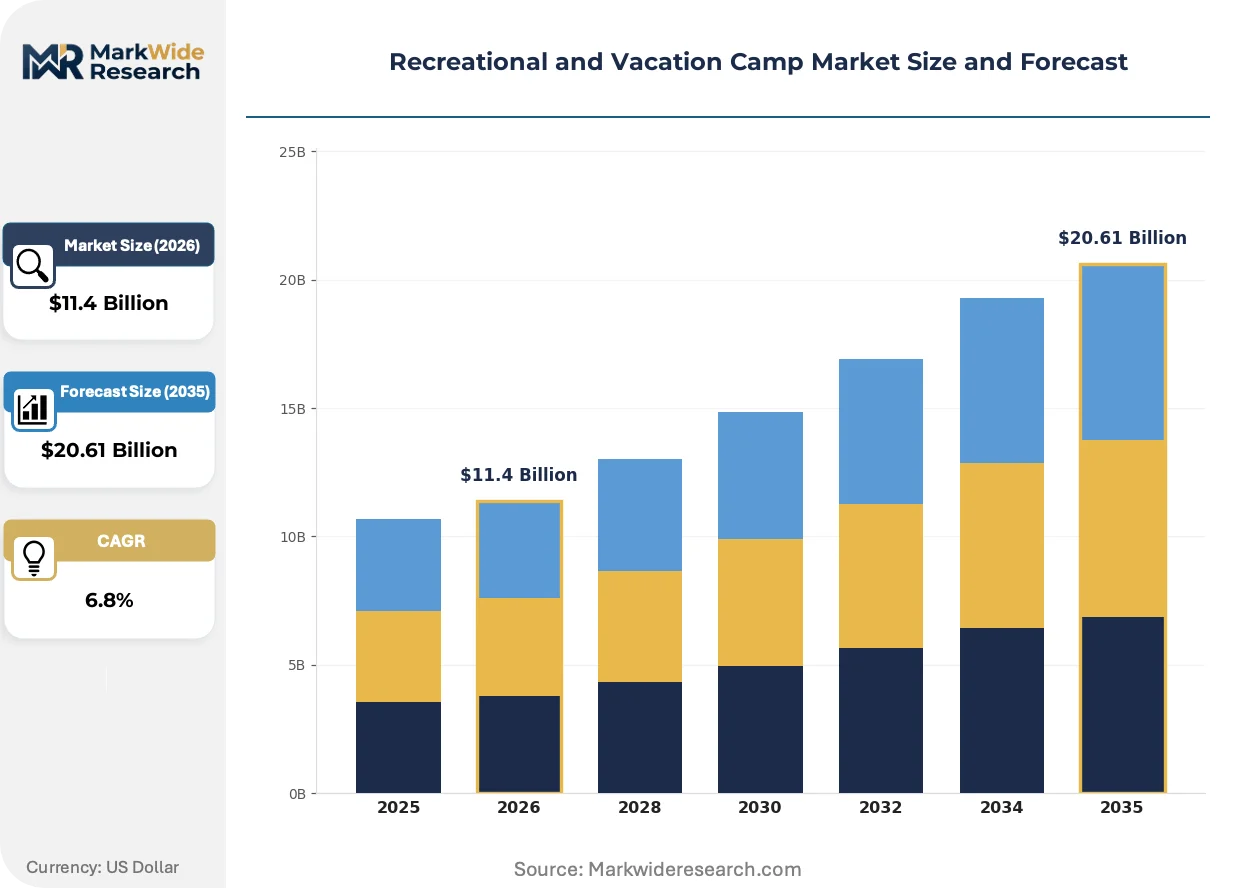
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Camp Type: Summer Camps, Winter Camps, Adventure Camps, Sports Camps Target Age Group: Children, Teens, Adults, Families Camp Offering: Outdoor Activities, Arts & Crafts, Workshops, Educational Programs Facility Type: Cabin Camps, Tent Camps, RV Parks, Glamping Sites |
| Companies Covered | Great Wolf Lodge, Timber Lake Camp, American Camp Association, Camp Cheley, Camp Laurel, Young Men's Christian Association, Camp Starlight, Canyon Ranch Wellness Resorts, Outward Bound USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recreational and Vacation Camp Market Trends and Innovations
Operational technology integration is reshaping how camp facilities manage safety compliance, guest communication, and dynamic pricing across compressed booking windows.
Solar microgrid and battery storage systems are electrifying off-grid power infrastructure for remote camp locations. Western U.S. operators with extended seasonal operations are deploying these systems fastest, cutting diesel generator dependence and enabling year-round climate control in previously seasonal-only facilities. This distributed generation architecture is electrifying site selection flexibility, opening terrain categories previously excluded due to grid connection costs.
The U.S. Forest Service is tightening Special Use Permit environmental compliance standards through revised NEPA review protocols. Operators must now submit comprehensive wildlife impact assessments and water quality monitoring plans before permit approval. Backcountry-focused facilities in the Sierra Nevada and Rocky Mountain regions are responding by hiring dedicated compliance officers and pre-negotiating mitigation banking arrangements.
Direct-to-family booking platforms are disintermediating traditional travel agent and school district referral channels. Parents now research accreditation status, safety records, and specialized programming through aggregator sites before initiating contact. This channel shift is most pronounced in California and Texas metropolitan markets, where digital-native millennial parents dominate household vacation planning decisions.
Recreational and Vacation Camp Market Segmentation
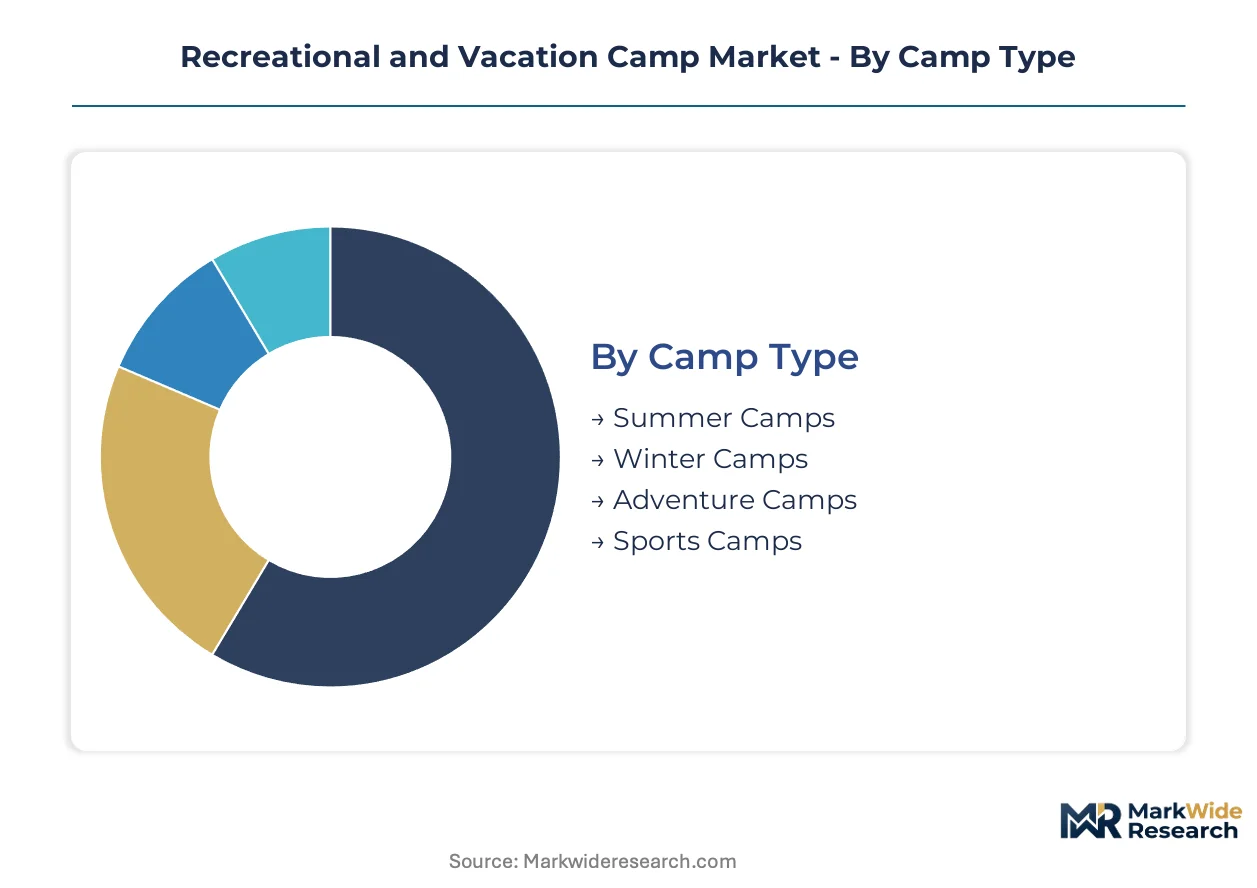
Camp operators configure programming and infrastructure around distinct guest profiles, with facility investments and staffing models varying sharply across segment boundaries. Understanding these divisions clarifies where capital deployment yields differential returns.
Camp Type:
Replacement-cycle dynamics dominate operator capital planning, as programming infrastructure ages unevenly across seasonal and year-round formats.
- Summer Camps:Traditional eight-to-twelve-week operations with permanent dining halls, waterfront facilities, and cabin clusters requiring cyclical refurbishment between seasons. Demand concentrates in the northeastern United States and upper Midwest, where lake-access properties with established school district contracts command premium weekly rates.
- Adventure Camps:Expedition-based programming with mobile equipment caches and minimal fixed infrastructure, enabling rapid relocation to follow permit availability and weather windows. Colorado and Utah operators are expanding backcountry climbing and river-running curricula as federal land access stabilizes.
- Winter Camps:Ski-area adjacent facilities with snowsports instruction and heated lodging infrastructure. Operators leverage existing alpine resort infrastructure rather than standalone development.
- Sports Camps:Specialized athletic programming with field/court specifications and certified coaching staff. NCAA compliance requirements shape curriculum design for teen divisions.
Summer Camps sit at the top of the volume ranking, with Adventure Camps climbing the fastest.
Target Age Group:
Margin profiles diverge sharply across age brackets, with adult and family segments tolerating per-capita spend levels that subsidize youth scholarship programs.
- Families:Multigenerational bookings with flexible lodging configurations and parallel activity tracks for varied fitness levels. Western U.S. operators with accessible trail systems and climate-controlled common spaces are capturing repeat bookings from Texas and California metropolitan households.
- Teens:Adventure-focused programming with higher instructor-to-guest ratios and specialized equipment requirements. Re-enrollment economics remain most predictable in this bracket due to peer-network effects and progression curricula.
- Children:Entry-level outdoor exposure with intensive supervision protocols and simplified activity menus. Accreditation requirements from the American Camp Association function as mandatory market access filters.
- Adults:Wellness retreat and skill-building formats with elevated pricing tolerance and off-peak calendar flexibility. Corporate sponsorship is expanding fastest in this segment.
Families generate the highest absolute revenue contribution, with Adults expanding most quickly as employer wellness budgets redirect toward outdoor programming.
Camp Offering:
Programming mix determines staffing specialization requirements and equipment depreciation schedules, with activity diversity correlating to extended guest stays.
- Outdoor Activities:Hiking, climbing, paddling, and wildlife observation with certified guide requirements and gear inventory management. Sierra Nevada and Rocky Mountain operators are deepening backcountry permit partnerships.
- Educational Programs:STEM and environmental science curricula with structured learning outcomes and school district alignment. California operators leverage proximity to research institutions for curriculum development.
- Arts & Crafts:Studio-based programming with supply chain dependencies and lower capital intensity. Functions as weather contingency across all facility types.
- Workshops:Skill-intensive formats with visiting instructor contracts and specialized equipment. Photography and wilderness medicine offerings command premium add-on pricing.
Outdoor Activities anchor the volume ranking, with Educational Programs climbing the fastest as school district partnerships formalize.
Facility Type:
Capital deployment flexibility varies dramatically, with permanent structures locking in location decisions while mobile formats enable rapid market testing.
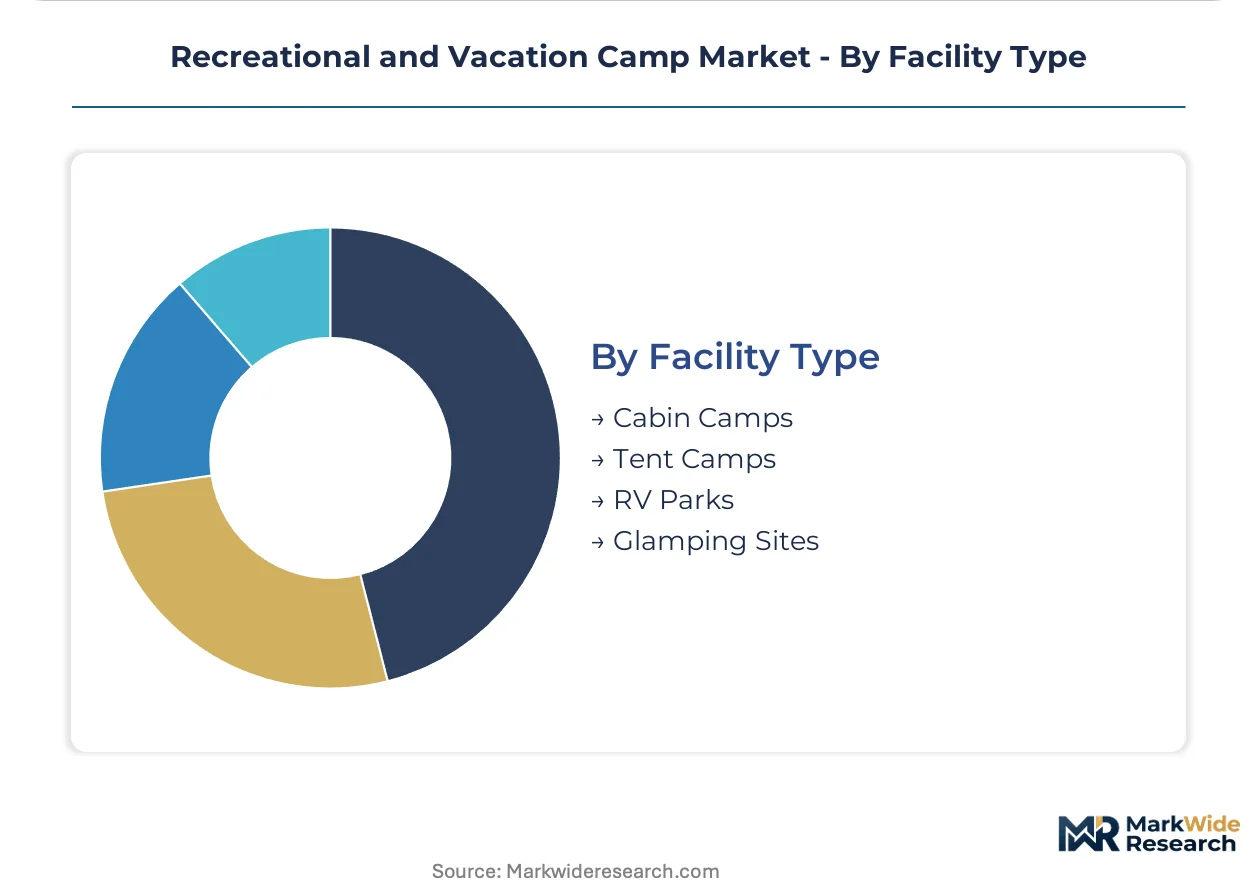
- Glamping Sites:Elevated platform tents or yurts with climate control, private bath facilities, and minimal foundation requirements. Colorado and California operators are deploying modular units to test demand in new geographies without permanent commitment.
- Cabin Camps:Timber-frame or conventional construction with centralized dining and sanitation infrastructure. Lifecycle maintenance costs favor engineered wood systems over stick-built alternatives.
- Tent Camps:Platform tent villages with shared central facilities and seasonal installation/removal cycles. Lowest barrier to entry for new operators.
- RV Parks:Utility hookup infrastructure with minimal programming overlay. Competes with hospitality sector on convenience rather than experience differentiation.
Cabin Camps sit at the top of the volume ranking, with Glamping Sites climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Colorado River Basin anchors North American camp development, with dense operator clusters around Denver, Salt Lake City, and Phoenix metropolitan areas driving permit competition and premium pricing dynamics.
United States
Multigenerational family bookings from Texas and California metropolitan households concentrate demand in western states with established outdoor recreation infrastructure. The U.S. Forest Service Special Use Permit system constrains expansion velocity through extended environmental review timelines. Colorado operators in the Front Range corridor leverage proximity to federal land access points to sustain premium weekly rates through limited site availability.
Canada
Provincial park concession systems in British Columbia and Ontario generate stable seasonal revenue pools for established operators with multi-decade leaseholds. Parks Canada administration of national park commercial activity permits imposes seasonal operating windows that shape capital deployment cycles. The Rocky Mountain sub-region spanning Alberta and British Columbia hosts the densest cluster of backcountry-focused adventure camp facilities.
Germany
Forest kindergarten traditions and state-subsidized youth travel programs sustain demand for educational outdoor programming. The Federal Agency for Nature Conservation enforces habitat protection standards that limit new facility development in protected landscapes. Bavarian operators in the Alpine foothills command premium positioning through specialized mountaineering curricula and hut-to-hut expedition networks.
Australia
Coastal and alpine national park access drives seasonal camp programming concentrated in New South Wales and Victoria. The Parks and Wildlife Service permit allocation system prioritizes educational and conservation-aligned operators for site access. Queensland's Sunshine Coast and hinterland regions host expanding glamping operations targeting domestic wellness tourism demand.
United Kingdom
Activity center licensing through the Adventure Activities Licensing Authority shapes operational compliance costs for commercial outdoor providers. The Lake District and Scottish Highlands concentrate backcountry-focused facilities leveraging long-distance trail connectivity. English operators in Devon and Cornwall are expanding family-oriented coastal programming to capture domestic staycation demand patterns.
Recreational and Vacation Camp Market Competitive Landscape
Global majors compete with regional champions across programming specialization and site access dimensions, producing a tiered structure where scale-driven indoor resort operators coexist with expedition-focused backcountry specialists. The vendor base separates into three strategic archetypes: integrated resort developers with year-round climate-controlled infrastructure, accreditation-dependent youth development specialists with school district contract relationships, and mobile glamping operators with asset-light deployment models. Dominant competitive moves include federal permit pre-negotiation to secure expansion sites and timber-frame construction partnerships to compress development timelines.
Within the integrated resort tier, Great Wolf Lodge anchors year-round occupancy strategies through indoor waterpark integration, while Timber Lake Camp occupies a position among established accreditation-dependent operators with specialized backcountry programming. Outward Bound USA exemplifies the expedition-based specialist archetype, extending brand authority from youth development into corporate training contract segments. These three entities represent distinct capital deployment philosophies across the facility-type spectrum.
| Leading Market Players |
|---|
| Great Wolf Lodge |
| Timber Lake Camp |
| American Camp Association |
| Camp Cheley |
| Camp Laurel |
| Young Men's Christian Association |
| Camp Starlight |
| Canyon Ranch Wellness Resorts |
| Outward Bound USA |
| Others |
Pricing and Supply Chain Analysis
NEPA review protocol tightening gates qualified timber-frame suppliers and premium-tier weekly rate access for western U.S. operators seeking federal land permits. Input-cost pass-through dynamics intensify as cross-laminated timber and glulam beam volatility compresses margin buffers across the development cycle. Three-tier pricing structure across premium, standard, and economy levels stratifies by American Camp Association accreditation status and backcountry programming depth. Cost compression in the standard tier intensifies because engineered wood commodity swings distort project feasibility during permitting phases. School district contract holders exhibit lowest price sensitivity, while independent family bookings through direct platforms show highest elasticity.
Pricing Analysis
Input-cost pass-through from engineered wood systems intensifies margin pressure across the camp development cycle. Three-tier pricing structure across premium, standard, and economy levels stratifies by American Camp Association accreditation status and backcountry programming depth. Cost compression in the standard tier intensifies because engineered wood commodity swings distort project feasibility during permitting phases. School district contract holders exhibit lowest price sensitivity, while independent family bookings through direct platforms show highest elasticity.
Supply Chain Analysis
Cross-laminated timber supply rests on Pacific Northwest and Southeastern U.S. producers with Canadian softwood lumber import exposure. Engineered wood systems, diesel generator sets, and modular tent platforms anchor capital deployment dependencies. Single-source vulnerability concentrates in specialized glulam beam fabricators serving timber-frame construction. Distribution runs through regional outdoor recreation equipment distributors with direct-to-operator procurement channels expanding fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds as a regulatory compounder with Infrastructure Investment and Jobs Act outdoor recreation provisions accelerating federal trail access expansion. Deepen vertical integration into timber-frame construction partnerships to compress development timelines against U.S. Forest Service permit bottlenecks. Pre-negotiate mitigation banking arrangements to secure Sierra Nevada and Rocky Mountain expansion sites before NEPA review protocol tightening accelerates. Accelerate American Camp Association accreditation investment to defend school district contract access against emerging mobile glamping operators.
For Market Incumbents: Deepen vertical integration into timber-frame construction partnerships to compress development timelines against U.S. Forest Service permit bottlenecks. Pre-negotiate mitigation banking arrangements to secure Sierra Nevada and Rocky Mountain expansion sites before NEPA review protocol tightening accelerates. Accelerate American Camp Association accreditation investment to defend school district contract access against emerging mobile glamping operators.
For New Entrants and Emerging Players: Begin with corporate wellness retreat programming in Texas and California metropolitan feeder markets where employer outdoor budgets remain underpenetrated. Deploy mobile glamping units for rapid demand testing in Colorado River Basin corridors without permanent capital commitment. Leverage direct-to-family booking platforms to disintermediate traditional school district referral channels.
For Investors and Strategic Acquirers: Roll-up economics work for regional accreditation-dependent operators because American Camp Association certification creates defensible moats against unaccredited competitors. Target established northeastern and upper Midwest summer camp properties with cyclical refurbishment needs and entrenched school district relationships. Watch U.S. Forest Service Special Use Permit streamlining progress as the inflection signal for western expansion velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Timber-Frame Construction Partnership | Engineered wood systems cut onsite build times by half versus conventional framing methods. |
| Federal Permit Pre-Negotiation | Mitigation banking arrangements secure Sierra Nevada and Rocky Mountain expansion sites ahead of competitors. |
| Corporate Wellness Retreat Expansion | Employer-sponsored outdoor programming accesses higher per-capita spend than traditional family bookings. |
| Mobile Glamping Unit Deployment | Modular luxury tent systems enable rapid market testing in new geographies without permanent capital commitment. |
| American Camp Association Accreditation Investment | Multi-year certification preparation unlocks school district vendor networks and insurance premium advantages. |
Research Methodology
Bottom-up family booking modeling reconciled against top-down federal permit allocation tracking forms the analytical core of this study. Primary interviews with camp operators, U.S. Forest Service permit administrators, American Camp Association accreditation directors, timber-frame construction contractors, and school district procurement officers combined with secondary validation from U.S. Forest Service Special Use Permit databases, American Camp Association accreditation records, state health department sanitation code filings, and outdoor recreation trade association membership directories. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity.
Input-output matrix framing connects camp type, target age group, camp offering, and facility type segmentation dimensions across the projection horizon. CAGRs derive from permit allocation velocity, replacement-cycle capital deployment patterns, and multigenerational travel preference shifts. Forecast inputs incorporate U.S. Forest Service administrative reform timelines and engineered wood commodity price trajectory assumptions.
Caveats apply where U.S. Forest Service environmental review timeline extensions or state childcare licensing harmonization failures could materially shift the outlook. Forecasts reflect assumptions about permit streamlining progress and timber input cost stabilization. A small set of named triggers including NEPA protocol enforcement intensity and lumber futures volatility warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
UK Student Accommodation Market
Accommodation
China Tourism and Hotel Market
Accommodation
Bed and Breakfast Accommodation Market
Accommodation
Netherlands Hospitality Industry Market
Accommodation
France Online Accommodation Market
Accommodation
Global Travel Accommodation Market
Accommodation
United Kingdom Hospitality Market
Accommodation
Hostel Market
Accommodation
Romania Hospitality Market
Accommodation
Luxury Hotel Market
Accommodation
Japan Online Accommodation Market
Accommodation
Airport Lounges Market
Accommodation
Croatia Hospitality Market
Accommodation
Hong Kong Hospitality Industry Market
Accommodation
France Hospitality Market
Accommodation
Japan Hospitality Market