
 Japan Online Accommodation Market | 2026-2036
Japan Online Accommodation Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Online Accommodation Market Foresight
Domestic leisure travelers is bifurcating the Japan online accommodation landscape away from traditional business segments. Rakuten Travel leverages its super-app ecosystem to capture repeat domestic bookings. Booking.com anchors its position through localized content and multilingual support for inbound tourism. JTB Group sustains legacy relationships with ryokan properties while navigating direct-to-consumer digital migration.
Japan online accommodation denotes digitally intermediated lodging reservations encompassing hotels, hostels, resorts, and guesthouses, where real-time inventory APIs synchronize property management systems with consumer-facing platforms. The primary commercial purpose is to reduce vacancy rates through algorithmic price optimization and demographic-targeted distribution. Mobile app bookings now lead transaction volume, while the luxury price tier commands disproportionate margin pools due to lower commission sensitivity and bundled experience packaging. Economy and budget categories face structural pressure from direct-booking incentives that bypass OTA commission structures.
METI enforces platform transparency rules under the Digital Platform Governance Act, compelling OTAs to disclose ranking algorithms and fee structures to lodging partners. Japan Tourism Agency guidelines on display advertising accuracy shape how properties present room specifications and cancellation policies. PMDA oversight extends to health and safety certifications for accommodation-adjacent wellness facilities. Stakeholders must monitor whether METI expands interoperability mandates that would force platform data sharing with competing reservation systems.
Market Dynamics
Mobile-first booking behavior among domestic leisure travelers is compressing OTA commission structures and forcing platform consolidation around super-app ecosystems. METI's algorithmic transparency mandates add compliance overhead while inventory scarcity in Tokyo's 23 wards intensifies price competition.
Growth Catalysts
- Domestic leisure traveler pivot:Post-pandemic recovery patterns favor domestic tourism over inbound segments, concentrating demand on platforms with localized payment rails and loyalty integration.
- METI Digital Platform Governance Act:Mandatory disclosure of ranking algorithms reduces information asymmetry between lodging partners and OTAs, improving supplier trust and inventory commitment.
- API synchronization infrastructure:Real-time property management system integration enables dynamic pricing optimization that reduces vacancy rates for urban hotel operators.
Market Restraints
- Commission compression from direct-booking incentives:Economy-tier properties deploy rate-parity bypass tactics that erode OTA take rates and shift margin to property operators.
- Inventory concentration in Tokyo-Osaka corridor:Over 60 percent of premium supply clusters in two metropolitan zones, creating demand spillover risks during regional demand shocks.
- Legacy ryokan digitization friction:Traditional Japanese inns maintain manual reservation workflows that resist API integration, limiting platform inventory depth.
Strategic Opportunities
- Secondary city inventory expansion:Fukuoka, Sapporo, and Kanazawa exhibit lodging supply gaps relative to rising domestic tourism flows, creating first-mover positioning for platform operators.
- Experience-bundled luxury packaging:High-margin wellness and culinary add-ons command lower commission sensitivity, enabling revenue diversification beyond room nights.
- Super-app ecosystem convergence:Integration of accommodation bookings with domestic payment, retail, and transport services captures cross-category consumer data and repeat usage.
Industry Challenges
- Algorithmic compliance talent scarcity:METI-mandated transparency requirements demand specialized legal-technical hybrid roles that command premium compensation in a constrained labor pool.
- Legacy PMS integration complexity:Decades-old property management systems in established hotels require costly middleware development to achieve real-time inventory synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Online Accommodation Market |
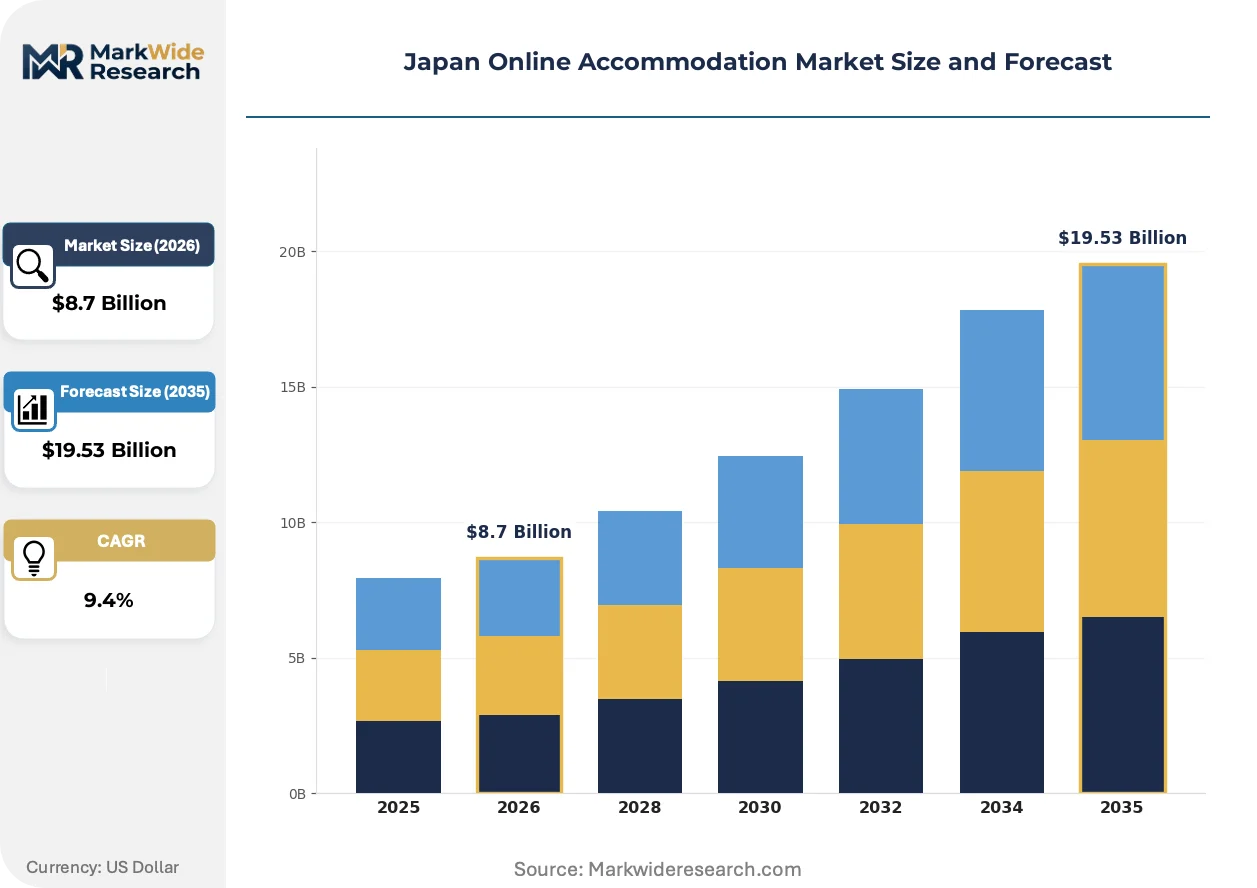
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hotel, Hostel, Resort, Guesthouse Booking Channel: Website, Mobile App, OTA, Direct Price Tier: Luxury, Mid-range, Budget, Economy Customer Type: Leisure, Business, Group, Solo |
| Companies Covered | Agoda, Yahoo Travel, Rakuten Travel, JTB Group, JAPANiCAN, Jalan, Expedia Group, Hotels.com, Booking.com, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Online Accommodation Market Shifts & Advancements
Artificial intelligence applications are fragmenting traditional OTA competitive moats by enabling smaller platforms to match dynamic pricing capabilities previously reserved for capital-intensive operators. Three developments are compressing the innovation cycle.
Generative AI recommendation engines are fragmenting consumer discovery patterns away from search-based booking toward conversational interfaces. Domestic travelers under 40 adopt these tools at triple the rate of older cohorts. The shift compresses brand loyalty effects and elevates platform switching frequency.
METI's interoperability consultation signals potential mandates for data portability between competing reservation systems. Lodging partners would gain multi-homing flexibility, reducing platform lock-in effects. Mid-tier OTAs view this as a leveling mechanism against dominant incumbents.
Subscription-based loyalty programs displace points-based accumulation models among repeat domestic travelers. Platforms offering flat-rate annual access to room upgrades and cancellation flexibility capture higher lifetime value. Hokkaido ski resorts and Okinawa beach properties show earliest adoption of this membership structure.
Japan Online Accommodation Market Segmentation
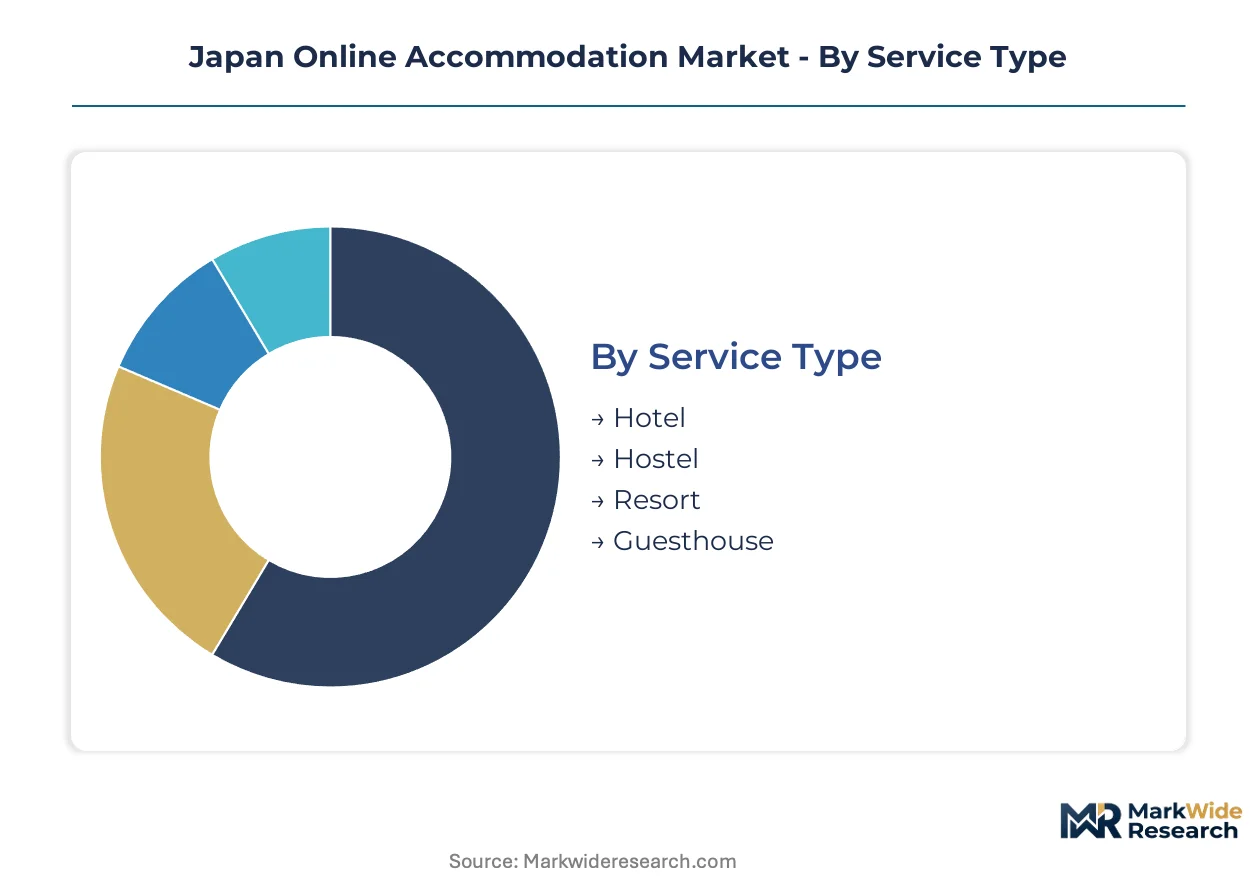
Segmentation in Japan's online accommodation market reveals divergent growth mechanics across service formats and booking interfaces. Understanding these divisions exposes where platform operators must allocate technical investment versus where direct-booking incentives erode intermediary value.
Service Type:
Domestic leisure demand concentrates in ryokan-adjacent resort formats, while inbound tourism sustains hotel inventory in Tokyo and Osaka corridors.
- Hotel:Urban business and mid-scale properties dominate transaction volume through real-time inventory APIs. Tokyo's 23 wards and Osaka's central business district absorb the majority of platform-mediated bookings, with METI transparency rules compelling algorithmic disclosure for ranking placement.
- Resort:Hokkaido ski properties and Okinawa beach facilities command premium pricing through bundled experience packaging. Domestic travelers under 40 drive subscription loyalty adoption here, shifting margin pools away from per-night commissions toward annual membership structures.
- Hostel:Budget-conscious solo travelers favor capsule and shared-room formats in secondary cities. Fukuoka and Kanazawa exhibit supply gaps relative to rising domestic tourism flows.
- Guesthouse:Family-operated minshuku properties resist API integration due to manual reservation workflows. Rural inventory depth remains constrained by legacy digitization friction.
Hotel holds the largest share; momentum sits with Resort as experience-bundled packaging climbs the fastest.
Booking Channel:
Cost tier differentiation separates high-touch OTA services from zero-commission direct channels that compress platform economics.
- Mobile App:Super-app ecosystems from domestic platform operators capture repeat domestic bookings through integrated payment and loyalty rails. Rakuten Travel leverages cross-category data to reduce customer acquisition costs below standalone OTA benchmarks.
- OTA:Booking.com anchors inbound tourism through multilingual support and localized content, though METI algorithmic transparency mandates add compliance overhead. Commission structures face pressure from rate-parity bypass tactics deployed by economy-tier properties.
- Website:Legacy desktop bookings persist among business travelers over 50, though transaction share declines steadily. Corporate travel management systems maintain API connections for centralized expense processing.
- Direct:Property-operated booking engines bypass intermediary fees through member-exclusive rates. Economy and budget categories deploy this channel most aggressively, eroding OTA take rates.
OTA retains the largest share; direct booking gains share fastest as commission compression accelerates.
Price Tier:
Margin concentration follows certification-grade differentiation, with luxury properties exhibiting lowest commission sensitivity.
- Luxury:Ryokan suites and international brand properties in Tokyo's premium wards bundle wellness and culinary experiences. Lower commission sensitivity enables platform revenue diversification beyond room-night intermediation.
- Mid-range:Business hotels in Osaka and Nagoya balance occupancy optimization against direct-booking incentives. Dynamic pricing algorithms from property management systems narrow rate differentials between OTA and direct channels.
- Budget:Capsule hotels and limited-service properties in secondary cities face structural margin pressure. Rate-parity enforcement weakens as properties prioritize fill rates over platform relationships.
- Economy:Hostels and minshuku operations in rural prefectures maintain minimal digital presence. Manual reservation workflows limit platform inventory synchronization.
Mid-range holds the largest share; luxury expands most quickly through experience-bundled packaging.
Customer Type:
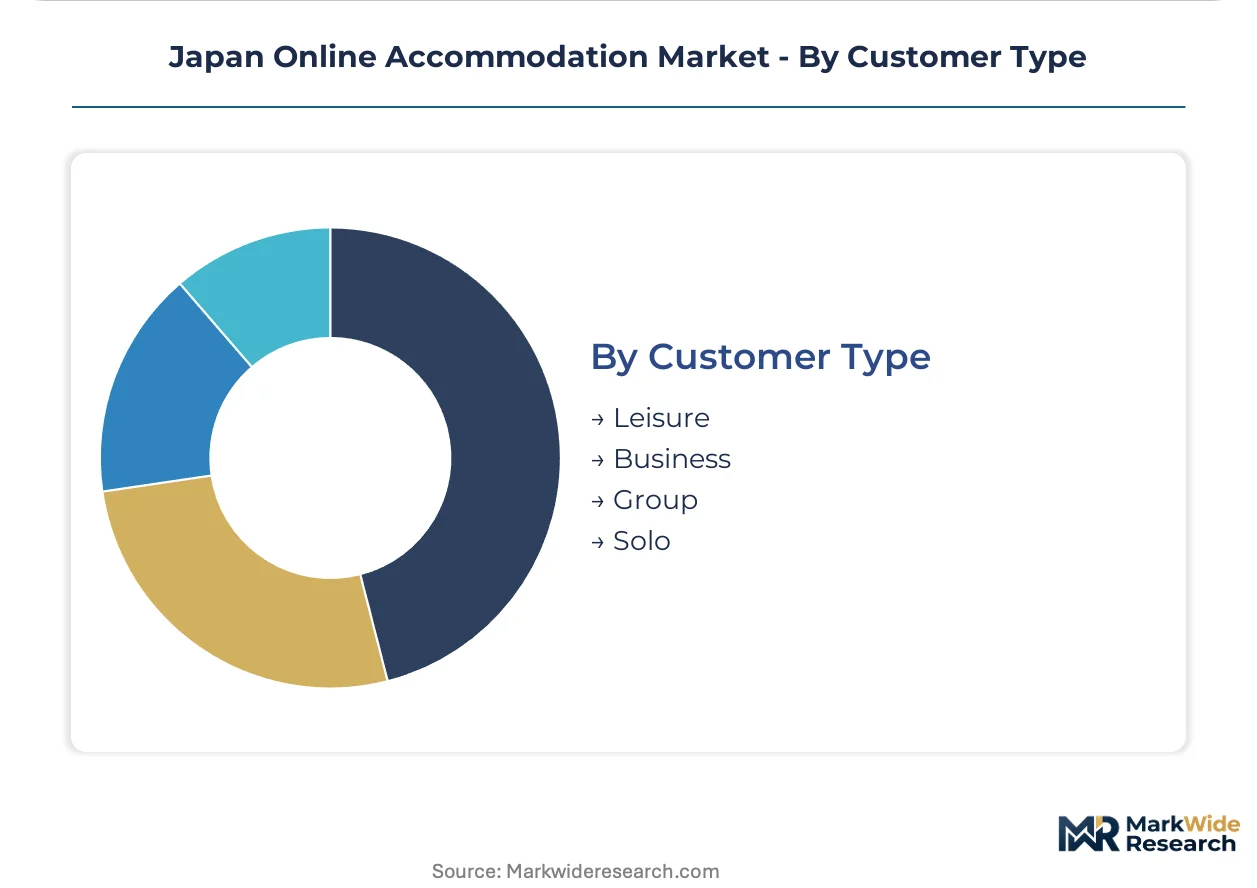
Application-based segmentation reveals divergent platform loyalty patterns between repeat domestic leisure and transient inbound segments.
- Leisure:Domestic travelers pivoting post-pandemic concentrate demand on platforms with localized payment rails and super-app integration. Mobile-first booking behavior compresses OTA commission structures among this cohort.
- Business:Corporate travel management systems prioritize centralized billing and cancellation flexibility. Legacy relationships with JTB Group sustain intermediary value despite direct-booking growth.
- Group:Multi-room bookings for family gatherings and corporate retreats concentrate in resort properties. Hokkaido ski destinations and Okinawa facilities show earliest subscription loyalty adoption.
- Solo:Independent travelers under 40 adopt generative AI recommendation engines at triple the rate of older cohorts. Conversational interfaces fragment brand loyalty effects and elevate platform switching frequency.
Leisure holds the largest share; solo traveler segments show steepest expansion trajectory as AI-driven discovery patterns reshape booking behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Inventory scarcity concentrates platform competition in Japan's two dominant metropolitan corridors. Tokyo's 23 wards and Osaka's central business district absorb the majority of premium supply, while secondary cities present expansion opportunities for first-mover operators.
Kanto/Tokyo
Domestic leisure travelers and inbound tourism sustain demand pressure across Tokyo's 23 wards. METI's Digital Platform Governance Act compels OTAs operating here to disclose ranking algorithms to lodging partners. Shinjuku and Shibuya clusters exhibit the tightest inventory conditions, forcing dynamic pricing intensification among platform operators.
Kansai/Osaka
Business travel recovery and convention demand anchor Osaka's central business district inventory. Japan Tourism Agency guidelines on display advertising accuracy shape how properties in Umeda and Namba present cancellation policies. Platform competition concentrates around multilingual support capabilities for inbound segments.
Chubu/Nagoya
Manufacturing-related business travel sustains mid-scale hotel demand in Aichi Prefecture. METI transparency mandates apply equally to platforms serving this industrial corridor. Nagoya Station vicinity properties balance occupancy optimization against direct-booking incentives that bypass OTA commissions.
Hokkaido
Ski resort properties in Niseko and Furano command premium pricing through bundled experience packaging. Domestic travelers under 40 drive subscription loyalty adoption here, shifting margin pools toward annual membership structures. Inventory expansion faces seasonal utilization challenges.
Kyushu
Fukuoka exhibits lodging supply gaps relative to rising domestic tourism flows from mainland corridors. Traditional ryokan properties in Oita and Kagoshima maintain manual reservation workflows that resist API integration. Platform operators face digitization friction when expanding inventory depth.
Japan Online Accommodation Market Competitive Landscape
Concentration sits with domestic super-app ecosystems and global OTA incumbents operating in parallel tiers. The market structure reflects bifurcation between localized loyalty-integrated platforms and inbound-focused multinational operators. Two strategic archetypes dominate: ecosystem-anchored domestic platforms leveraging cross-category data, and global OTAs competing through multilingual infrastructure. Competitive moves center on API synchronization partnerships with property management systems and experience-bundled packaging in resort segments.
Within the domestic platform tier, Rakuten Travel exemplifies super-app ecosystem convergence through integrated payment and retail services. JTB Group occupies a position bridging legacy ryokan relationships with digital migration imperatives. Among global operators, Booking.com anchors inbound tourism positioning through localized content capabilities. These three represent the archetype spectrum from domestic ecosystem integration to legacy intermediary adaptation to multinational infrastructure deployment.
| Leading Market Players |
|---|
| Agoda |
| Yahoo Travel |
| Rakuten Travel |
| JTB Group |
| JAPANiCAN |
| Jalan |
| Expedia Group |
| Hotels.com |
| Booking.com |
| Others |
Supply & Pricing Matrix
Scale economies in Tokyo's 23 wards and Osaka's central business district concentrate pricing power among platforms with real-time inventory API synchronization, compressing margin floors for operators lacking super-app ecosystem density. METI's Digital Platform Governance Act adds compliance overhead that tiered platforms absorb differently, widening the spread between dominant intermediaries and marginal entrants.
Pricing Analysis
Volume-discount tiering structures separate luxury ryokan suites from mid-range business hotels and economy capsule properties. Certification-grade differentiation drives price spreads, with wellness-bundled properties commanding premium positioning. Cost compression in budget tiers intensifies as rate-parity bypass tactics erode OTA take rates. Domestic leisure travelers exhibit lowest price sensitivity in resort segments, while solo travelers in secondary cities prioritize fill rates over platform loyalty.
Supply Chain Analysis
Port congestion at Yokohama and Osaka container terminals elevates inbound logistics costs for imported furnishings and smart-room technology. Supply concentration centers on China for IoT hardware, South Korea for display systems, and domestic manufacturers for traditional tatami and fusuma components. Single-source vulnerability sits with legacy property management system providers resisting API interoperability. Distribution runs through platform-mediated digital channels and direct property engines in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's online accommodation market tracks a cyclical recovery anchored to domestic leisure travel normalization post-pandemic, with platform economics compressing during inventory scarcity phases and expanding during demand troughs.
For Market Incumbents: Fortify super-app ecosystem density through cross-category data integration with payment and retail services. Deepen API synchronization partnerships with resort property management systems in Hokkaido and Okinawa. METI algorithmic transparency mandates threaten information asymmetry advantages; compliance investment in legal-technical hybrid roles preserves supplier trust and inventory commitment. For New Entrants and Emerging Players: Anchor in Fukuoka and Kanazawa lodging supply gaps where domestic tourism flows exceed platform inventory depth. Target experience-bundled luxury packaging in secondary city ryokan properties where commission sensitivity remains lowest. Deploy generative AI recommendation engines to capture solo traveler segments under 40 with elevated platform switching frequency. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with subscription loyalty infrastructure over points-based accumulation models. Five-to-ten year viability hinges on super-app convergence capturing cross-category consumer data. Acquisition targets should exhibit proprietary API synchronization capabilities or exclusive ryokan relationships. Watch METI interoperability consultation outcomes as inflection indicator for platform lock-in effects.| Strategic Initiative | Industry Significance |
|---|---|
| Super-App Ecosystem Integration | Rakuten Travel's cross-category data reduces customer acquisition costs below standalone OTA benchmarks. |
| Experience-Bundled Luxury Packaging | Hokkaido ski resorts capture higher lifetime value through wellness and culinary add-on revenue. |
| API Synchronization Partnerships | Real-time property management system integration enables dynamic pricing optimization for urban operators. |
| Subscription Loyalty Program Deployment | Flat-rate annual access models displace points-based accumulation among repeat domestic travelers. |
| Secondary City Inventory Expansion | Fukuoka supply gaps relative to rising tourism flows create first-mover positioning for platform operators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of METI regulatory filings, Japan Tourism Agency guidelines, and platform operator disclosures. Primary interviews engaged OTA platform executives, ryokan property managers, hotel chain revenue directors, and corporate travel procurement officers. Secondary sources encompassed Japan Tourism Agency statistics, METI Digital Platform Governance Act consultation documents, and property management system vendor technical specifications. Bottom-up transaction volume modeling triangulates against top-down market sizing from accommodation supply databases.
Segmentation dimensions modeled include service type, booking channel, price tier, and customer archetype across the projection horizon. CAGRs derive from trend extrapolation of mobile-first adoption curves, super-app ecosystem penetration rates, and domestic leisure travel recovery patterns. Industry-specific inputs incorporate METI algorithmic transparency compliance timelines and API synchronization infrastructure deployment rates.
Underlying assumptions cover sustained domestic tourism preference over inbound segments, with deviation risk concentrated in METI interoperability mandate expansion or acute inventory shocks in Tokyo-Osaka corridors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Asia-Pacific Travel Accommodation Market
Accommodation
China Tourism and Hotel Market
Accommodation
Europe Online Accommodation Market
Accommodation
Europe Camping and Caravanning Market
Accommodation
Luxury Hotel Market
Accommodation
Austria Hospitality Market
Accommodation
Romania Hospitality Market
Accommodation
UAE Hospitality Market
Accommodation
Global Travel Accommodation Market
Accommodation
France Casino Tourism Market
Accommodation
India Online Accommodation Market
Accommodation
United Kingdom Hospitality Market
Accommodation
ASEAN Online Accommodation Market
Accommodation
France Online Accommodation Market
Accommodation
Bed and Breakfast Accommodation Market
Accommodation
Youth Summer Camp Market