
 US Student Accommodation Market | 2026-2036
US Student Accommodation Market Size, Share, and Industry Trends Forecast 2026-2036
US Student Accommodation Market Insights
A shortage of skilled construction labor and property management talent is redrawing development timelines across university towns. American Campus Communities leverages its national build-to-core pipeline to sustain delivery velocity in supply-constrained markets. Greystar Student Housing anchors its portfolio through vertically integrated operations spanning development, construction, and asset management. The Scion Group differentiates through purpose-built product positioned near tier-one research institutions.
US student accommodation encompasses purpose-built residential assets designed for enrolled students, typically featuring furnished units, shared common areas, study spaces, and integrated security systems with electronic access control and fire suppression meeting NFPA 101 standards. The primary commercial purpose is to generate stabilized rental income through academic-year lease structures aligned to university calendars. Private dormitories command premium rents near flagship public campuses where on-campus bed deficits persist. Studio apartments represent the fastest-growing product type as privacy preferences intensify among upper-division and graduate cohorts. Shared apartments retain volume leadership across price-sensitive undergraduate segments.
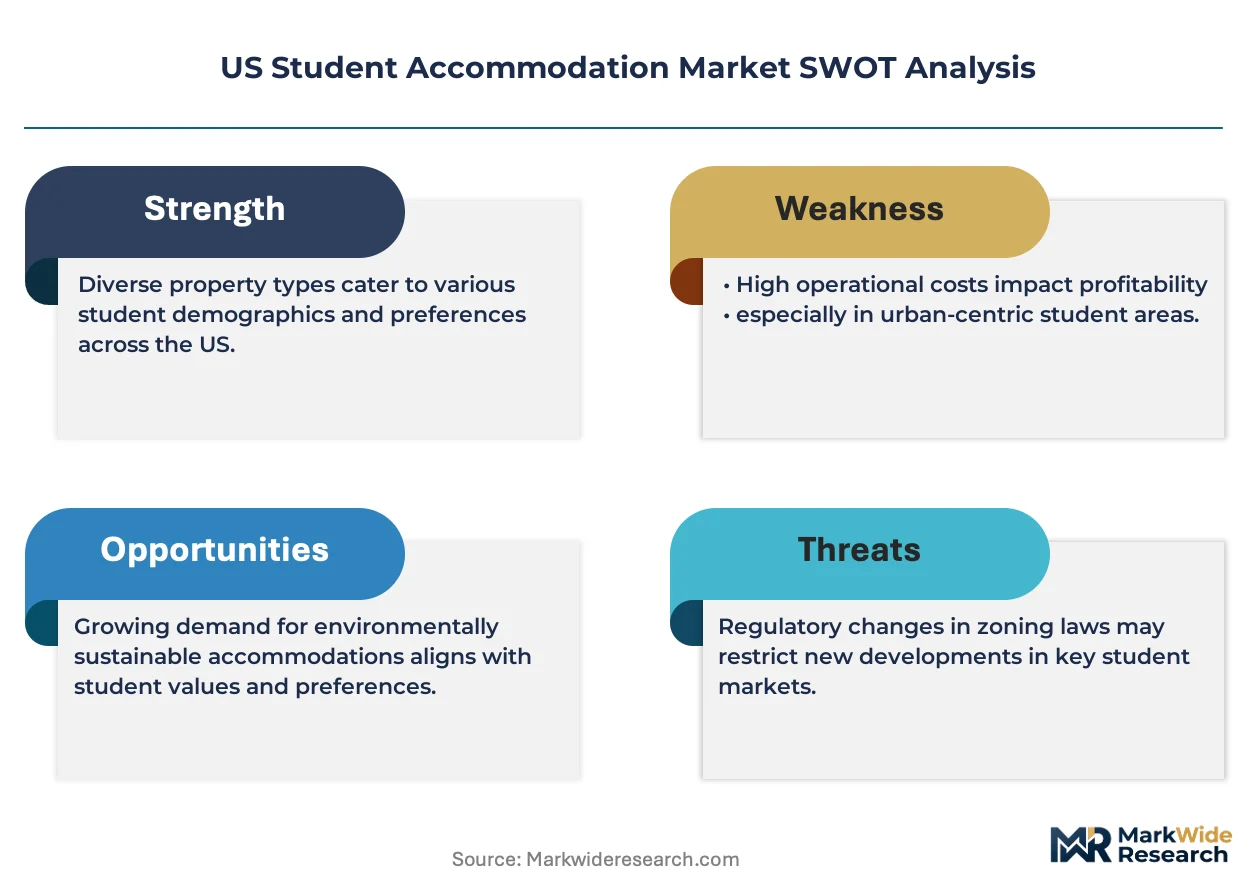
The Department of Education's Title IV program integrity rules shape off-campus housing partnerships by conditioning institutional referrals on compliance frameworks. State-level building codes and local zoning ordinances govern density, parking ratios, and fire safety standards that developers must satisfy before certificate of occupancy. The Department of Housing and Urban Development's fair housing enforcement creates compliance obligations around disability access and marketing practices. Stakeholders must monitor evolving municipal inclusionary housing requirements that could impose affordability set-asides on new developments near public university systems.
Market Dynamics
Title IV eligibility rules are restructuring how developers finance student housing projects, forcing institutional partnerships to comply with Department of Education referral frameworks before capital deployment.
Growth Catalysts
- Enrollment Surge Mechanics:Public university systems in Texas and Florida are expanding graduate programs faster than on-campus housing construction, creating bed deficits that private developers fill.
- NFPA 101 Alignment:Fire safety standards for student housing are tightening, advantaging purpose-built assets with integrated suppression systems over converted multifamily stock.
- Research Institution Clustering:Tier-one universities are concentrating R&D funding, drawing graduate cohorts that prefer studio product near campus cores.
Market Restraints
- Labor Scarcity:Skilled construction trades in university towns are insufficient to match development timelines, extending pre-lease windows and carrying costs.
- Zoning Density Caps:Municipal parking ratio requirements and height restrictions limit bed counts on infill sites near flagship campuses.
- Interest Rate Sensitivity:Floating-rate construction debt exposes developers to Federal Reserve policy shifts that compress yield-on-cost spreads.
Strategic Opportunities
- Graduate Housing Undersupply:Purpose-built product for post-baccalaureate students remains sparse near research-intensive institutions in the Southeast and Southwest.
- Inclusionary Housing Integration:Municipal affordability set-asides near public university systems create mixed-income structures that diversify revenue streams.
- Smart Access Convergence:Mobile credentialing and IoT building management systems are reducing operating overhead while commanding rent premiums.
Industry Challenges
- Property Management Talent Gap:Student housing operations require specialized leasing velocity and turn management expertise that competes with conventional multifamily for personnel.
- Certificate of Occupancy Delays:Local fire marshal inspections and HUD fair housing compliance reviews are extending delivery schedules into academic-year start dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Student Accommodation Market |
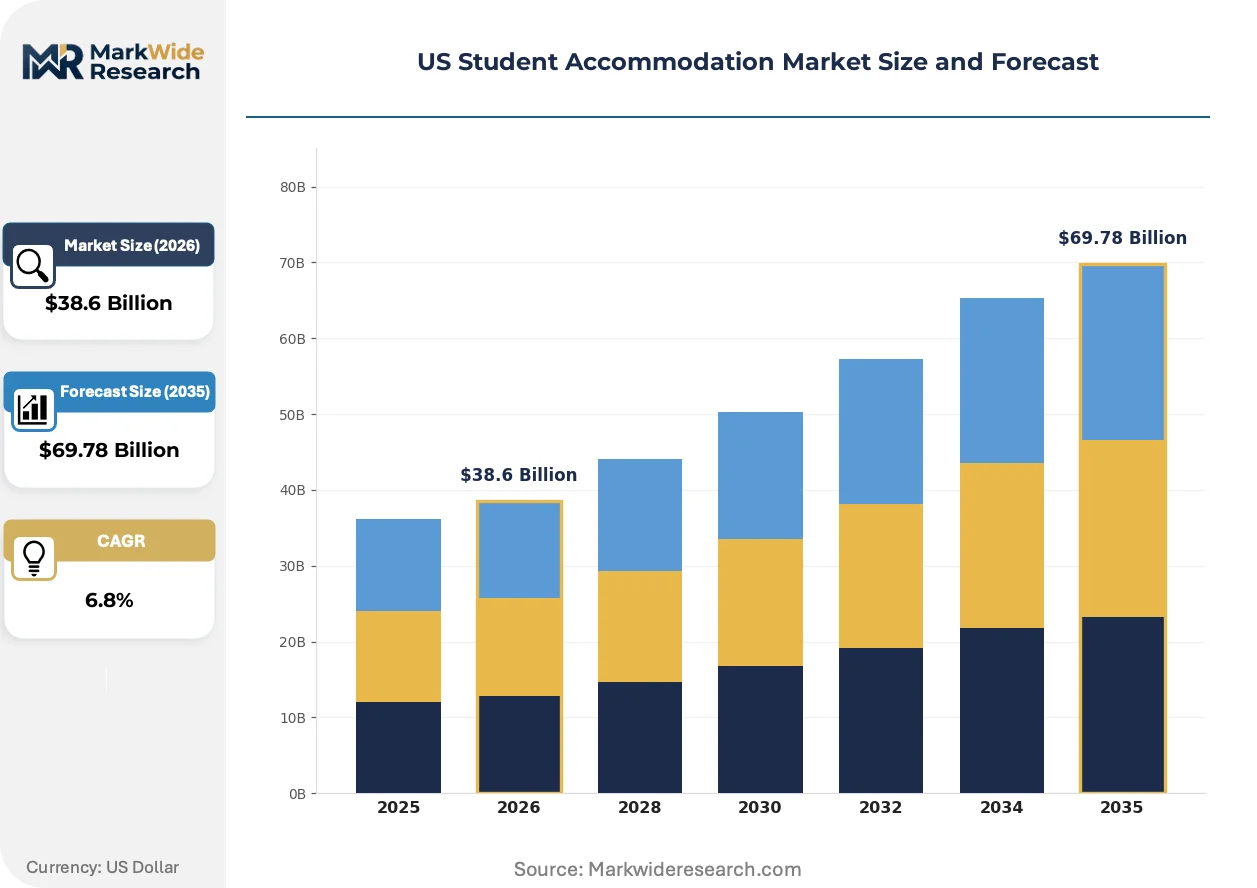
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Campus Housing, Private Dormitories, Shared Apartments, Studio Apartments End User: Undergraduate Students, Graduate Students, International Students, Exchange Students Facility Type: Traditional Dormitories, Apartment-Style Dormitories, Off-Campus Housing, Co-Living Spaces Size: Small Units, Medium Units, Large Units, Luxurious Units |
| Companies Covered | American Campus Communities, Greystar Student Housing, The Scion Group, Core Spaces, Landmark Properties, Campus Advantage, Aspen Heights Partners, Asset Living, PeakMade Real Estate, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Student Accommodation Market Trends and Innovations
Physical security infrastructure and lease administration systems are converging, compressing operating models while elevating resident experience expectations. Developers are repositioning around technology-enabled service delivery.
Mobile access control is decomposing traditional key management in student housing assets. Upper-division and graduate residents expect smartphone credentialing for unit entry, amenity access, and package retrieval. This technology is decomposing front-desk staffing models and enabling 24-hour self-service operations that reduce per-bed operating expense.
The Department of Education's Title IV program integrity framework is tightening institutional referral requirements. Universities must document compliance with off-campus housing partners or risk federal financial aid eligibility. Private dormitory operators near flagship public campuses are restructuring partnership agreements to satisfy audit protocols and secure preferred vendor status.
Academic-year lease structures are compressing revenue recognition windows and amplifying summer vacancy risk. Graduate programs with 12-month calendars are displacing traditional September-to-May patterns in select submarkets. Operators near research-intensive institutions in Texas and Florida are piloting flexible-term contracts to capture visiting scholars and post-doctoral researchers outside standard enrollment cycles.
US Student Accommodation Market Segmentation
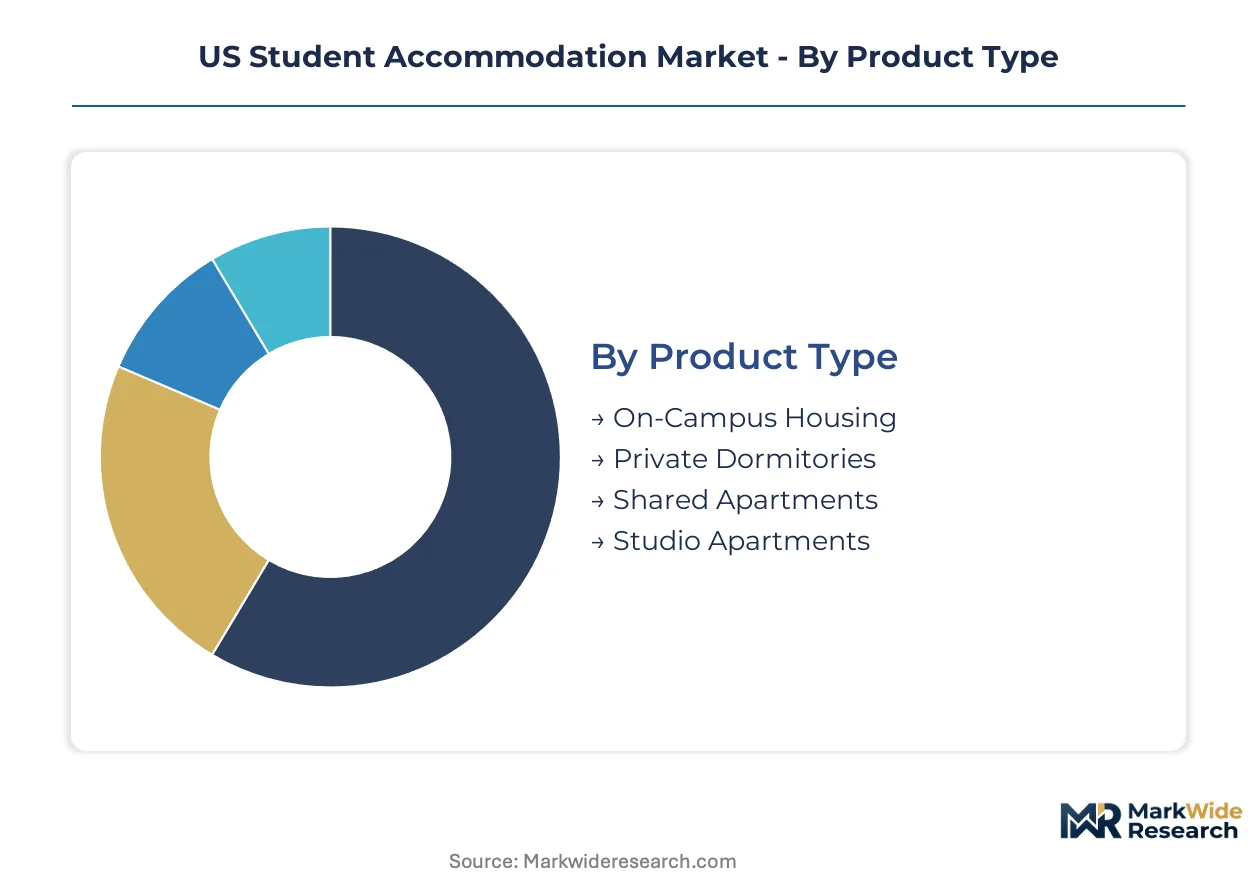
Segmentation in US student accommodation reveals how product design, user demographics, and facility economics create distinct investment profiles. Developers allocate capital across these dimensions based on proximity to specific university tiers and enrollment compositions.
Product Type:
Geographic concentration varies sharply across product categories, with certain formats dominating specific state university systems while others serve export-driven international enrollment hubs.
- On-Campus Housing:University-owned residence halls featuring shared bathrooms and communal study lounges. Demand concentrates in Texas and Florida public systems where enrollment growth outpaces state capital construction budgets, forcing housing departments into public-private partnership structures.
- Private Dormitories:Purpose-built assets with institutional management contracts and academic-year lease alignment. The steepest expansion runs through studio-heavy developments near tier-one research institutions in the Southeast, where graduate program expansion creates year-round occupancy demand.
- Shared Apartments:Multi-bedroom configurations with individual leases and common area amenities. Price-sensitive undergraduate segments in Midwestern college towns sustain volume leadership here.
- Studio Apartments:Single-occupancy units with kitchenettes and dedicated study zones. Privacy preferences among upper-division cohorts are accelerating development near medical and law school campuses.
On-Campus Housing commands the established base. The steepest expansion runs through Studio Apartments.
End User:
Cost tier segmentation separates premium-pay graduate segments from price-constrained undergraduate markets, with international enrollment creating export-linked demand volatility.
- Undergraduate Students:Traditional four-year and community college enrollees seeking furnished housing with bundled utilities. Volume leadership persists across all product types due to absolute enrollment scale.
- Graduate Students:Post-baccalaureate cohorts with 12-month calendar needs and higher willingness-to-pay for privacy. Research-intensive universities in Texas and Florida are drawing expanding cohorts that prefer studio product near campus cores.
- International Students:Visa-holding enrollees requiring immediate move-in ready housing with documentation support services. Concentrated demand clusters near institutions with established OPT and STEM extension pipelines.
- Exchange Students:Short-term semester or year-abroad participants needing flexible lease terms. This segment creates seasonal occupancy spikes that operators address through academic-calendar pricing structures.
Undergraduate Students command the established base. The steepest expansion runs through Graduate Students.
Facility Type:
Application-based segmentation tracks how facility design serves distinct operational models, from institutional oversight to independent off-campus management.
- Traditional Dormitories:Corridor-style layouts with shared bathrooms and centralized dining facilities. Public university systems in the Southwest retain this format for first-year housing mandates.
- Apartment-Style Dormitories:Suite configurations with private bedrooms and shared living spaces. Upper-division and graduate preferences are displacing traditional formats near research campuses.
- Off-Campus Housing:Privately developed assets without institutional ownership or direct management. Title IV compliance requirements are restructuring partnership agreements between universities and these operators.
- Co-Living Spaces:High-amity assets with curated community programming and flexible lease structures. Urban infill sites near private universities in the Northeast are seeing concentrated development interest.
Traditional Dormitories command the established base. The steepest expansion runs through Apartment-Style Dormitories.
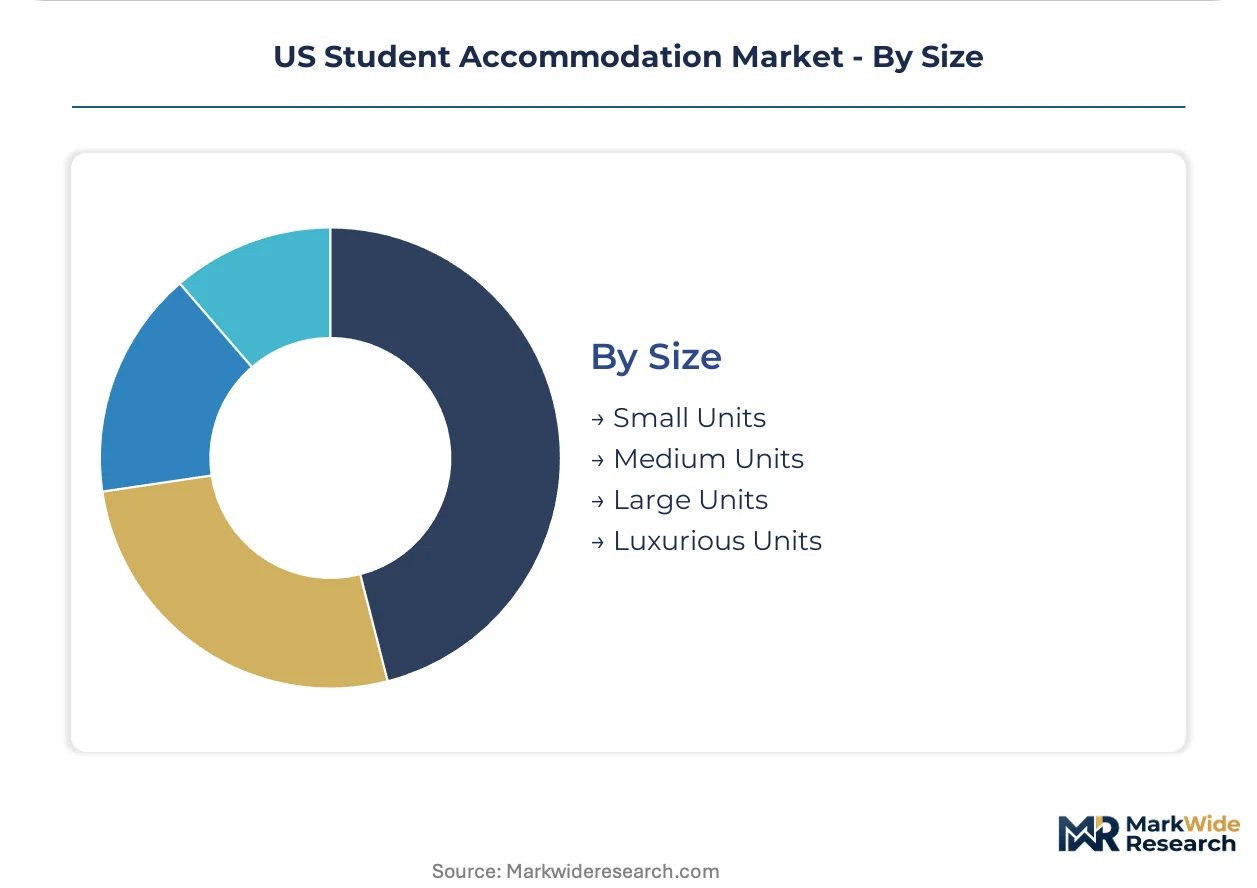
Size:
Customer-type segmentation aligns unit specifications with enrollment stage and household income, creating tiered pricing architectures across the same geographic markets.
- Small Units:Compact studios and one-bedroom configurations optimized for single occupancy. Graduate and international student demand concentrates in university-adjacent infill where land costs limit unit footprints.
- Medium Units:Two-bedroom and modest three-bedroom layouts serving roommate-matched undergraduate cohorts. This segment captures volume leadership across price-sensitive markets in the Midwest and South.
- Large Units:Four-bedroom and larger configurations with multiple bathrooms and expanded common areas. Family housing needs near graduate programs with married student populations sustain select submarkets.
- Luxurious Units:Premium-finish assets with resort-style amenities and concierge services. International enrollment at elite private institutions supports this segment in coastal metropolitan areas.
Medium Units command the established base. The steepest expansion runs through Small Units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Department of Education's Title IV eligibility rules anchor development financing across US university towns, with state-level enrollment growth dictating where private capital deploys most aggressively.
Texas
Public university systems in Texas are expanding graduate programs faster than on-campus housing construction, creating persistent bed deficits near flagship campuses. State building codes and local zoning ordinances govern density caps and parking ratios that developers must satisfy. Austin and College Station concentrate the steepest development activity, with purpose-built studio product rising near research-intensive institutions.
Florida
Enrollment surges at public universities in Florida outpace state capital construction budgets, forcing housing departments into public-private partnership structures. Municipal fire safety standards and HUD fair housing enforcement create compliance obligations around disability access. Gainesville and Tallahassee anchor concentrated development interest, with operators piloting flexible-term contracts for visiting scholars.
California
Graduate cohorts at University of California and California State University campuses demonstrate higher willingness-to-pay for privacy, accelerating studio development near campus cores. State environmental review processes and local inclusionary housing requirements impose affordability set-asides on new developments. Berkeley and Westwood represent high-barrier submarkets where land costs limit unit footprints.
North Carolina
Research-intensive institutions in North Carolina are concentrating R&D funding, drawing graduate cohorts that prefer apartment-style product near campus. State-level building codes align with NFPA 101 fire safety standards for student housing assets. Chapel Hill and Raleigh-Durham concentrate development velocity, with purpose-built assets featuring integrated suppression systems commanding rent premiums.
Massachusetts
Tier-one private universities in Massachusetts sustain demand for premium-finish assets with resort-style amenities among international enrollment. The state's architectural access board enforces disability compliance standards stricter than federal baselines. Cambridge and Boston represent supply-constrained infill markets where mobile credentialing and IoT building management systems reduce operating overhead.
US Student Accommodation Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the US student accommodation market. National build-to-core pipelines sustain delivery velocity for scale operators with captive construction capabilities. Three archetypes dominate: vertically integrated developers with in-house asset management, purpose-built specialists targeting tier-one research institutions, and platform operators aggregating third-party management contracts. Competitive intensity centers on securing preferred vendor status through Title IV-compliant institutional partnerships and accelerating pre-lease velocity through technology-enabled service delivery.
Within the integrated developer tier, American Campus Communities, Greystar Student Housing, and The Scion Group occupy positions that exemplify contrasting strategic postures. American Campus Communities represents the national scale archetype with build-to-core pipeline depth. Greystar Student Housing anchors portfolio stability through backward integration across development, construction, and asset management functions. The Scion Group exemplifies the research-institution specialist model, concentrating purpose-built product near flagship public campuses where graduate program expansion creates year-round occupancy demand.
| Leading Market Players |
|---|
| American Campus Communities |
| Greystar Student Housing |
| The Scion Group |
| Core Spaces |
| Landmark Properties |
| Campus Advantage |
| Aspen Heights Partners |
| Asset Living |
| PeakMade Real Estate |
| Others |
Pricing and Supply Chain Analysis
Pre-lease windows stretching 180 days ahead of academic-year starts compress developer pricing power while amplifying carrying cost exposure in supply-constrained university towns. This lead-time structure concentrates pricing leverage with vertically integrated operators who control construction velocity through captive labor pipelines.
Pricing Analysis
Rent spreads between Austin and Tallahassee versus Midwestern college towns reach 40-60% for comparable studio product, reflecting enrollment growth differentials and bed deficit severity. Three-tier pricing structure across premium, standard, and economy levels dominates, with privacy premiums for graduate-focused studios and bundled utility discounts for undergraduate shared units. Pricing pressure stems from floating-rate construction debt exposure and extended certificate-of-occupancy timelines that compress yield-on-cost spreads. Undergraduate cohorts in price-sensitive Midwestern markets exhibit highest rent elasticity, while international graduate students near tier-one research campuses demonstrate lowest price sensitivity.
Supply Chain Analysis
Strategic pre-positioning of modular bathroom pods and pre-fabricated wall assemblies dominates over just-in-site delivery, as fire marshal inspection bottlenecks and labor scarcity make schedule certainty paramount. Manufacturing concentrates in Mexico for steel framing components, Texas for concrete and masonry materials, and Southeast Asia for electronic access control systems. Construction inputs draw from lumber futures markets, copper wiring contracts, and fire-rated door assemblies with NFPA 101 certification. Single-source vulnerability runs through specialized student housing property management software platforms. Distribution runs through national general contractors with university-town experience, regional subcontractors with certified trade labor, and captive development arms of integrated operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among a shrinking set of national student housing operators with Title IV-compliant institutional partnerships, squeezing regional developers without preferred vendor status.
For Market Incumbents: Secure preferred vendor status through Department of Education compliance frameworks before competitors consolidate institutional referral relationships. Defend delivery velocity by deepening backward integration into skilled trade labor pools in Texas and Florida growth markets. Threat substitution from university-owned P3 structures demands preemptive partnership restructuring. For New Entrants and Emerging Players: Graduate housing service gaps near research-intensive campuses in the Southeast and Southwest represent the most penetrable white-space opportunity. Target flexible-term contract capabilities for visiting scholars and post-doctoral researchers outside standard academic calendars. Go-to-market execution should anchor through direct university housing department relationships rather than third-party broker channels. For Investors and Strategic Acquirers: Carve-out targets emerge from university endowment real estate portfolios and distressed regional developers with entitled land positions near flagship public campuses. Long-term viability centers on operators with demonstrated Title IV compliance infrastructure and technology-enabled operating expense reduction. Watch Federal Reserve policy direction as the inflection signal for construction debt availability and yield-on-cost threshold resets.| Strategic Initiative | Industry Significance |
|---|---|
| Title IV Compliance Infrastructure Investment | Department of Education referral frameworks condition institutional partnership eligibility and preferred vendor status. |
| Modular Construction Scale-Up | Pre-fabricated bathroom pods and wall assemblies compress delivery schedules amid skilled labor scarcity. |
| Graduate Housing Product Expansion | Studio-heavy developments near research-intensive universities capture 12-month occupancy demand and privacy premiums. |
| Smart Access Technology Deployment | Mobile credentialing and IoT building management reduce front-desk staffing overhead while commanding rent premiums. |
| Flexible-Term Contract Piloting | Visiting scholar and post-doctoral researcher segments displace traditional September-to-May lease patterns. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with student housing developers, university housing officers, property management executives, and construction contractors. Secondary validation drew from Department of Education Title IV program integrity guidance, state-level building code databases, HUD fair housing enforcement records, and university enrollment statistics. Bottom-up bed-count modeling across identified development pipelines was triangulated against top-down market sizing from institutional investment flow tracking.
Across the analysis window, forecasts were constructed through segmented demand modeling by product type, end-user cohort, facility format, and state-level enrollment trajectory. CAGRs were derived from enrollment growth projections, historical bed delivery velocity, and capital deployment patterns observed through construction permit databases. Key inputs included graduate program expansion timelines, public-private partnership announcement tracking, and municipal zoning capacity assessments.
Forecasts assume regulatory continuity in Department of Education Title IV eligibility regimes and Federal Housing Administration multifamily financing standards; material policy shifts would require re-modeling. Specific risks include municipal inclusionary housing mandate expansion, fire safety code amendments, and interest rate volatility affecting construction debt availability. Revision becomes warranted when pre-lease velocity or certificate-of-occupancy timelines cross thresholds that materially alter yield-on-cost assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
China Online Accommodation Market
Accommodation
Peer to Peer Accommodation Market
Accommodation
ASEAN Online Accommodation Market
Accommodation
Africa Hotel Market
Accommodation
Capsule Hotels Market
Accommodation
Germany Student Accommodation Market
Accommodation
Sri Lanka Hospitality Industry Market
Accommodation
Japan Hospitality Market
Accommodation
Asia-Pacific Travel Accommodation Market
Accommodation
Europe Online Accommodation Market
Accommodation
Hong Kong Hospitality Industry Market
Accommodation
Casino Hotel Market
Accommodation
Bed and Breakfast Accommodation Market
Accommodation
Asia-Pacific Student Accommodation Market
Accommodation
Hostel Market
Accommodation
Global Travel Accommodation Market