
 Hotel Market | 2026-2036
Hotel Market Size, Share, and Industry Trends Forecast 2026-2036
Hotel Market Analysis
Business travel recovery is consolidating around premium extended-stay and boutique properties as corporate travel policies favor longer, fewer trips. Marriott International leverages its Bonvoy ecosystem to sustain direct booking share against online travel agencies. Hilton Worldwide anchors North American corporate accounts through concentrated convention-adjacent assets. Jin Jiang International competes on domestic scale across China's provincial capitals.
Hotels are commercial lodging establishments offering temporary accommodation with varying service intensities, typically organized by room inventory, amenity tiers, and operational standards such as star ratings or brand-affiliated quality protocols. Their primary commercial purpose is monetizing room nights through yield management systems that balance occupancy against average daily rate across seasonal and event-driven demand cycles. Luxury and extended-stay service types command disproportionate margin pools as business travelers and affluent tourists prioritize consistent service delivery over price sensitivity. Boutique properties within customer type segmentation are capturing growth from experience-seeking tourists who reject standardized brand formats. Standard room inventory still dominates absolute volume but faces compression as accessible and deluxe categories respond to aging demographics and premiumization trends.
FDA food code standards, EPA energy efficiency mandates, and OSHA workplace safety requirements shape US hotel construction and operational compliance costs. The EU Green Deal and CSRD reporting obligations in Europe are forcing asset owners to retrofit existing properties or absorb higher financing costs for non-compliant stock. Stakeholders must monitor how divergent regulatory timelines across Washington, Brussels, and Beijing affect cross-border investment flows and brand standardization costs.
Market Dynamics
Smart room technology integration and LEED certification mandates in the United States are forcing asset owners to reallocate capital toward retrofitting existing properties rather than greenfield development, compressing traditional development timelines and elevating operational compliance costs across premium inventory tiers.
Growth Catalysts
- Extended-stay demand:Corporate travel policies now favor longer, fewer trips, concentrating bookings around premium extended-stay formats with kitchen amenities and workspace configurations.
- Domestic tourism infrastructure:China's tier-one cities are absorbing demand as provincial capitals expand convention capacity and high-speed rail connectivity.
- EPA energy efficiency mandates:Stricter building performance standards are accelerating HVAC and lighting upgrades in existing US properties, creating retrofit service revenue streams.
Market Restraints
- Labor cost volatility:Housekeeping and front-desk wage pressures in urban US markets are compressing operating margins at midscale properties with limited pricing power.
- Supply concentration risk:Smart lock and in-room IoT hardware sourcing concentrates among a handful of East Asian contract manufacturers, exposing brands to semiconductor allocation delays.
- Technical limitation:Legacy property management systems lack API interoperability with newer guest-facing mobile applications, forcing expensive middleware investments.
Strategic Opportunities
- Underpenetrated wellness integration:Sleep optimization technology and circadian lighting systems remain nascent in standard inventory, offering differentiation in competitive urban markets.
- EU Green Deal retrofit financing:European asset owners can access subsidized green bonds for energy efficiency upgrades, lowering hurdle rates for sustainable renovation projects.
- Channel innovation:Direct booking platforms with loyalty currency integration are capturing share from online travel agencies, reducing commission burdens.
Industry Challenges
- Certification timeline compression:LEED v4.1 documentation requirements demand specialized consultants, extending pre-opening schedules by four to six months.
- Integration complexity:Property management system migrations to cloud-native architectures disrupt daily operations and require temporary staff augmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hotel Market |
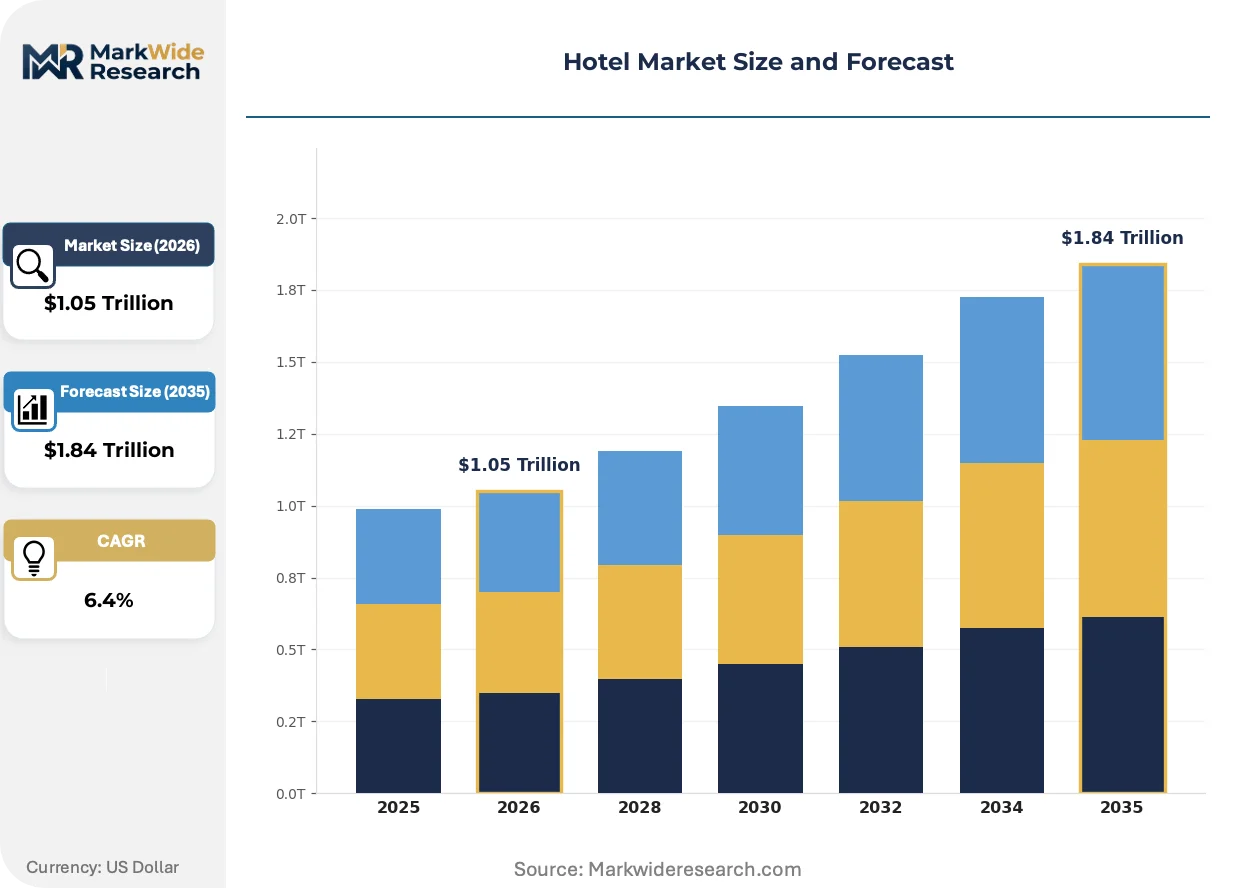
| Market Size in 2026 | $1.05 Trillion |
| Market Size in 2035 | $1.84 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Luxury, Budget, Boutique, Extended Stay Customer Type: Business Travelers, Tourists, Group Bookings, Families Room Type: Suite, Standard, Deluxe, Accessible Amenity Offering: Free Wi-Fi, Fitness Center, Spa Services, Conference Rooms |
| Companies Covered | Marriott International, Hilton Worldwide, H World Group (Huazhu), Wyndham Hotels & Resorts, InterContinental Hotels Group (IHG), Accor, Hyatt Hotels Corporation, Jin Jiang International, Radisson Hotel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hotel Market Emerging Trajectories
Technology deployment is fragmenting traditional service delivery models while regulatory pressure accelerates capital rotation toward sustainable inventory. Demand concentration patterns are shifting as corporate travel policies and leisure preferences diverge.
Mobile key and in-room voice assistant technology is decentralizing front-desk functions across full-service and select-service properties. Business travelers and experience-seeking tourists now expect seamless smartphone-based check-in and environmental control. This capability compression is reducing labor allocation at reception while elevating IT infrastructure spending.
The EU Green Deal and CSRD reporting obligations are mandating granular energy and carbon disclosure from European hotel operators. Asset owners must install submetering systems and upgrade building envelopes to avoid financing penalties. Premium urban properties in Germany and France are absorbing the highest compliance costs while capturing green-certified rate premiums.
Corporate procurement departments are consolidating preferred supplier agreements with extended-stay brands offering consistent workspace amenities and centralized billing. Traditional transient business hotels face volume displacement as travel managers negotiate master contracts with three to five national extended-stay flags. This concentration is most visible in the United States, where per-diem optimization drives contract terms.
Hotel Market Segmentation
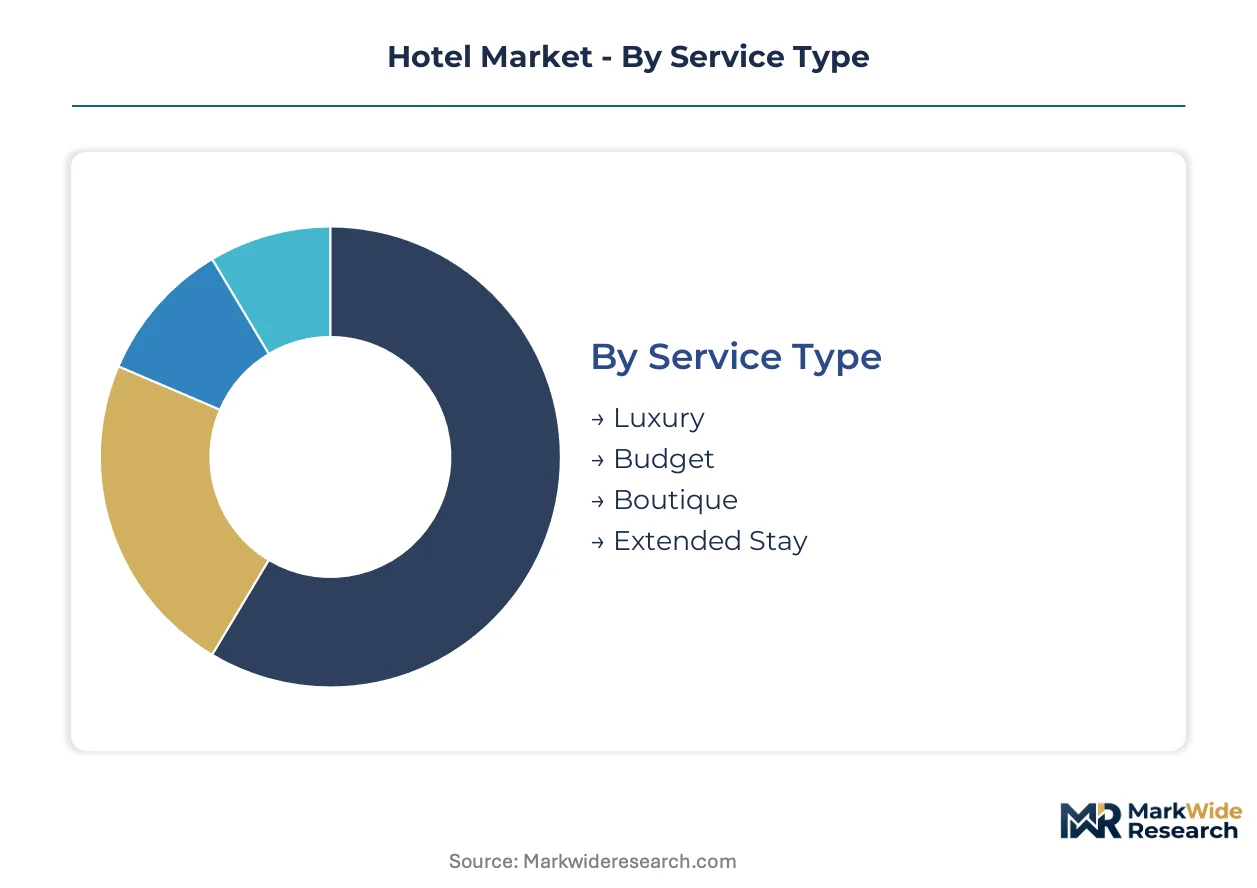
Hotel segmentation separates properties by service intensity, guest profile, and physical configuration. These dimensions determine capital allocation, operational staffing models, and revenue management complexity. Owners and operators use category boundaries to benchmark performance and target investment.
Service Type:
Service intensity and nightly rate positioning separate buyers with divergent margin expectations and loyalty behaviors.
- Luxury:Full-service properties with concierge, fine dining, and personalized guest relations command the highest ADR premiums. Demand concentrates in gateway cities and resort destinations where affluent tourists and corporate entertainment budgets sustain rate floors. LEED certification and wellness amenities now function as table stakes rather than differentiators.
- Extended Stay:Kitchen-equipped suites with weekly housekeeping and workspace configurations capture corporate relocation and project-based travel. Extended-stay formats in the United States absorb displaced demand from traditional business hotels as procurement departments negotiate master contracts.
- Budget:Limited-service properties with stripped amenity sets compete on absolute price. Franchisee-operated roadside and suburban locations serve price-sensitive leisure travelers and truck fleet accommodations.
- Boutique:Design-forward independent or soft-branded properties emphasize localized experience over standardized service protocols. Urban clusters in Shanghai, Berlin, and Austin attract experience-seeking tourists rejecting chain formats.
Luxury leads volumes today; Extended Stay is gaining share fastest.
Customer Type:
Booking patterns and length-of-stay distributions determine distribution channel mix and cancellation policy design.
- Business Travelers:Midweek demand concentration with centralized billing and negotiated rate floors. Corporate travel managers in Germany and the United States now favor extended-stay formats for assignments exceeding five nights.
- Tourists:Leisure-driven demand with high price elasticity and OTA dependency. Domestic tourism infrastructure expansion in China's tier-one cities redirects outbound volume toward provincial destinations.
- Group Bookings:Convention and wedding blocks with compressed booking windows and attrition clauses. Convention-adjacent assets in Las Vegas and Orlando compete on ballroom capacity and guest room blocks.
- Families:Multi-room demand with amenity requirements spanning pool access, connecting rooms, and dining flexibility. Orlando and Anaheim cluster concentration reflects theme park adjacency premiums.
Business Travelers anchor rate floors; Tourists drive absolute volume expansion.
Room Type:
Square footage and configuration flexibility determine upgrade revenue potential and accessibility compliance costs.
- Suite:Separate living and sleeping areas with premium furnishings command ADR multiples over standard inventory. Corporate extended-stay demand in London and New York sustains suite occupancy during midweek compression.
- Standard:Single-room inventory with bathroom and basic workspace dominates absolute keys across midscale and economy tiers. Renovation cycles now mandate USB charging and streaming-capable televisions as baseline specifications.
- Deluxe:Oversized standard rooms with upgraded bath amenities and floor placement premiums. Aging demographics in Japan and Germany drive demand for accessible luxury without full suite configuration.
- Accessible:ADA-compliant and equivalent international standard rooms with roll-in showers and visual alarm systems. Regulatory mandates in the United States and European accessibility directives expand required inventory percentages.
Standard rooms dominate key counts; Suites capture disproportionate profit contribution.
Amenity Offering:
Fixed-cost infrastructure investments separate properties competing on convenience versus experience.
- Free Wi-Fi:Ubiquitous baseline expectation with bandwidth tiering as the new differentiation vector. Business travelers in Singapore and Dubai now expect symmetric upload speeds for video conferencing.
- Fitness Center:Cardio and strength equipment with 24-hour access increasingly standard across select-service tiers. Peloton and Technogym partnerships signal premium positioning in urban markets.
- Spa Services:Treatment rooms and licensed therapy staff with revenue per available treatment hour metrics. Resort properties in Bali and Scottsdale capture destination wellness tourism premiums.
- Conference Rooms:Flexible meeting space with AV infrastructure and catering capabilities. Hybrid meeting technology upgrades now required to retain corporate account contracts.
Free Wi-Fi is universal baseline; Spa Services deliver the steepest expansion trajectory in resort positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Las Vegas and Orlando anchor North American hospitality infrastructure with concentrated convention capacity and entertainment-anchored demand. Property owners in these clusters face divergent regulatory pressures and capital allocation timelines across major national markets.
United States
EPA energy efficiency mandates and LEED certification requirements are accelerating HVAC retrofits in legacy urban properties. The Inflation Reduction Act subsidizes green building upgrades, lowering hurdle rates for sustainable renovation in gateway cities. Manhattan and Miami Beach clusters absorb the highest compliance costs while capturing rate premiums from corporate accounts.
China
Domestic tourism infrastructure expansion in tier-one cities redirects outbound volume toward provincial destinations. The Ministry of Ecology and Environment enforces dual carbon goals that constrain new construction permits in Beijing and Shanghai. H World Group and Jin Jiang International compete on scale across the Yangtze River Delta and Pearl River Delta corridors.
Germany
Corporate procurement departments consolidate preferred supplier agreements with extended-stay formats offering centralized billing. The EU Green Deal and CSRD reporting obligations mandate granular energy disclosure from Frankfurt and Munich operators. Bavarian asset owners access subsidized green bonds for building envelope upgrades.
United Arab Emirates
Luxury hospitality demand concentrates in Dubai's entertainment and convention corridor with sustained entertainment-anchored bookings. MOHAP hospitality licensing standards and Dubai Municipality green building codes elevate pre-opening compliance costs. The Palm Jumeirah and Downtown Dubai clusters capture premium leisure and corporate entertainment segments.
Japan
Aging demographics drive demand for accessible luxury inventory without full suite configuration. METI building efficiency standards and Tokyo Metropolitan Government carbon disclosure rules accelerate smart room technology deployment. Osaka and Kyoto clusters compete on inbound tourism recovery and domestic business travel consolidation.
Hotel Market Vendor Landscape
Strategic partnerships dominate the current landscape as operators seek technology integration and distribution scale. The vendor base organizes around three tiers: global brand portfolios with loyalty ecosystems, regional scale players with domestic density, and independent boutique operators with design differentiation. Portfolio diversification and direct booking platform investment represent the primary competitive vectors as commission burdens from online travel agencies compress net operating income.
Within the global brand portfolio tier, Marriott International and Hilton Worldwide exemplify loyalty-anchored distribution strategies. Hilton Worldwide occupies a position among North American corporate account holders with convention-adjacent asset concentration. Jin Jiang International represents the regional scale archetype with provincial density across China's domestic market.
| Leading Market Players |
|---|
| Marriott International |
| Hilton Worldwide |
| H World Group (Huazhu) |
| Wyndham Hotels & Resorts |
| InterContinental Hotels Group (IHG) |
| Accor |
| Hyatt Hotels Corporation |
| Jin Jiang International |
| Radisson Hotel Group |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between LEED Gold properties and legacy unbranded inventory manifests in both rate premiums and capital sourcing structures. Premium assets command corporate account rate floors through verified sustainability credentials while drawing from green bond markets, whereas standard inventory faces financing penalties and compressed ADR from procurement departments optimizing per-diem budgets.
Pricing Analysis
Input-cost pass-through from HVAC retrofit mandates and smart lock hardware shortages runs through extended-stay rate structures faster than luxury segments. Three-tier pricing structure across premium, standard, and economy levels differentiates on LEED certification status and Bonvoy-tier loyalty currency rather than pure square footage. Pricing pressure stems from labor cost volatility in urban housekeeping markets, compressing margins at midscale properties with limited corporate contract coverage. Budget franchisees exhibit highest price sensitivity, while extended-stay corporate accounts demonstrate inelastic demand for workspace-amenity bundles.
Supply Chain Analysis
Workforce availability constraints in Guangdong and Zhejiang provinces concentrate smart lock and in-room IoT hardware manufacturing among three dominant contract suppliers. Semiconductor allocation delays from Taiwan and South Korean chip fabricators feed into six-month hardware delivery backlogs for property management system upgrades. Raw material dependencies span lithium-ion batteries for mobile key infrastructure, rare earth elements for LED circadian lighting systems, and copper wiring for submetering installations. Single-source vulnerability in East Asian electronics manufacturing exposes brands to tariff escalation risks. Distribution runs through brand-affiliated procurement consortia and third-party hospitality FF&E specialists serving independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where corporate travel policy shifts toward extended-stay formats concentrate demand around premium specifications with kitchen amenities and workspace configurations.
For Market Incumbents: Hedge against OTA commission erosion by accelerating direct booking platform investment with integrated loyalty currency redemption. Defensive consolidation moves include acquiring regional extended-stay flags to anchor master corporate contracts, and retrofitting legacy urban assets to LEED v4.1 standards before financing penalties harden. Labor cost volatility in housekeeping operations represents the primary margin threat; automation of front-desk functions through mobile key deployment offers partial offset. For New Entrants and Emerging Players: Capture white-space in wellness-integrated urban boutique formats where sleep optimization technology and circadian lighting remain underdeployed. The most penetrable segment is domestic tourism infrastructure in China's tier-two provincial capitals with convention capacity expansion. Go-to-market positioning should emphasize localized experience design over standardized brand protocols, leveraging soft-brand affiliations for distribution scale without full loyalty ecosystem investment. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented independent boutique operators lack capital access for green retrofit compliance. Long-term viability favors assets with LEED certification and extended-stay revenue mix above forty percent of room nights. Acquisition targets should display convention-adjacency or high-speed rail connectivity premiums. Watch corporate procurement department RFP timing as inflection signal for extended-stay contract concentration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| LEED Certification Retrofit | Unlocks green bond financing and corporate account rate premiums in gateway cities. |
| Direct Booking Platform Launch | Reduces OTA commission burden while capturing Bonvoy-tier loyalty currency engagement. |
| Extended-Stay Format Expansion | Aligns with corporate travel policy shifts toward longer, fewer trips with workspace amenities. |
| Smart Room Technology Integration | Addresses EPA energy mandates while differentiating against legacy property management systems. |
| Wellness Amenity Differentiation | Captures experience-seeking tourist premiums through sleep optimization and circadian lighting. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hotel development executives, asset management directors, corporate travel procurement managers, and sustainability compliance officers with secondary validation. SEC 10-K filings from publicly traded lodging REITs, EPA energy performance benchmarking data, EU CSRD disclosure repositories, and China Ministry of Ecology and Environment permitting records anchored supply-side assessment. Bottom-up property-level revenue modeling and top-down national tourism expenditure flows were triangulated against brand-reported key counts.
Segment-weighting across service type, customer profile, and regional regulatory cluster determined analytical framework construction. Modeled dimensions included luxury versus extended-stay versus boutique positioning, business traveler versus leisure tourist demand mix, and LEED certification tier against legacy inventory. CAGRs were derived from occupancy rate trajectory analysis combined with average daily rate elasticity estimates across the projection horizon. Forecast inputs incorporated high-speed rail connectivity expansion timelines and corporate travel policy survey data from Germany and United States procurement departments.
Regulatory timeline divergence between Washington, Brussels, and Beijing, semiconductor allocation volatility for IoT hardware, and labor cost strike frequency in urban housekeeping markets are the dominant revision risks. Forecasts reflect assumptions around business travel recovery velocity and green financing subsidy continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Netherlands Hospitality Industry Market
Accommodation
Glamping Market
Accommodation
Croatia Hospitality Market
Accommodation
China Online Accommodation Market
Accommodation
France Hospitality Market
Accommodation
Luxury Hotel Market
Accommodation
Canada Hospitality Market
Accommodation
Asia-Pacific Travel Accommodation Market
Accommodation
Russia Online Accommodation Market
Accommodation
Extended Stay Hotel Market
Accommodation
UK Student Accommodation Market
Accommodation
Europe Online Accommodation Market
Accommodation
Sweden Hospitality Market
Accommodation
In-Flight Catering Services Market
Accommodation
US Recreational and Vacation Camp Market
Accommodation
Italy Online Accommodation Market