
 Asia-Pacific Student Accommodation Market | 2026-2036
Asia-Pacific Student Accommodation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Student Accommodation Market Insights
Premium purpose-built student housing is unwinding the region's legacy dormitory stock. Mapletree Investments dominates Singapore's institutional-grade portfolio through captive development pipelines. Frasers Hospitality leverages its serviced-apartment expertise to compete in hybrid student-living formats across Southeast Asian capitals. Nest Student Housing specializes in tech-enabled operations that differentiate its Melbourne and Sydney assets.
Asia-Pacific student accommodation comprises dedicated residential assets designed for enrolled learners, typically featuring study pods, high-speed bandwidth infrastructure, and communal amenity programming to support academic retention and wellness outcomes. Purpose-built facilities command the deepest margin pools where developers integrate construction, management, and lease underwriting under single ownership. Shared flats and studios lead transaction volume across client segments, while international students represent the fastest-growing demand cohort as visa processing reforms in Australia and Canada redirect enrollment flows toward Asia-Pacific destinations.
Australia's Foreign Investment Review Board, China's Ministry of Education dormitory standards, and India's RERA compliance frameworks collectively shape development timelines and capital structures for new supply. Australia's FIRB screening raises equity thresholds for offshore developers, while China's GB standards mandate fire-safety and density specifications that constrain conversion economics. Stakeholders must monitor visa policy oscillations between English-speaking destination countries to calibrate pipeline timing and pricing power across the region's university corridors.
Market Dynamics
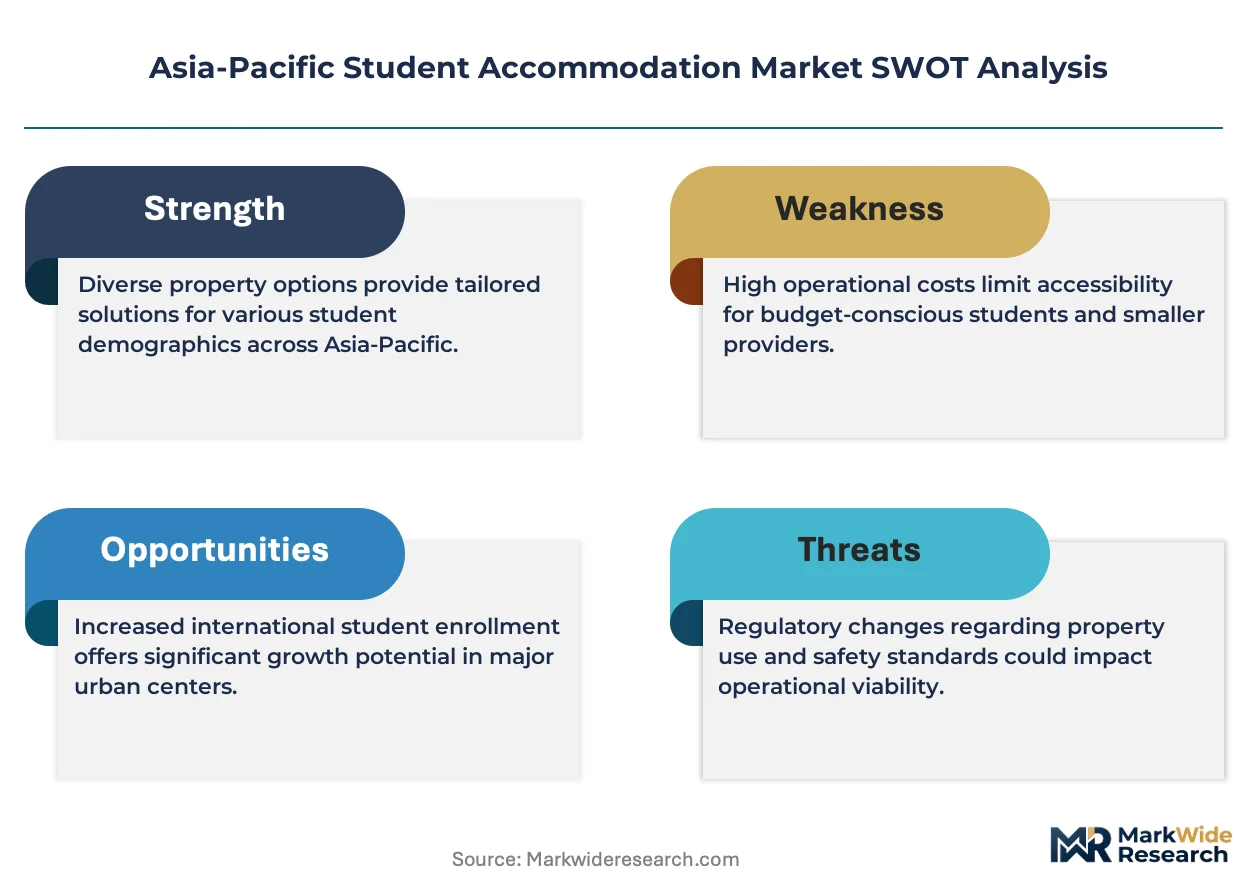
TRAI's building connectivity mandates are decomposing legacy dormitory economics across Indian university corridors, forcing asset owners to retrofit bandwidth infrastructure or surrender pricing power to tech-enabled competitors.
Growth Catalysts
- Visa processing reforms:Australian and Canadian policy adjustments redirect international enrollment flows toward Melbourne, Sydney, and Chinese university cities, concentrating demand in purpose-built supply.
- TRAI connectivity mandates:India's regulator requires minimum broadband standards in multi-tenant buildings, accelerating smart-housing retrofits that upgrade rental yields across Delhi and Bangalore corridors.
- Hybrid living formats:Serviced-apartment operators deploy flexible-lease products that capture postgraduate and research-student segments underserved by traditional semester-aligned contracts.
Market Restraints
- Construction cost volatility:Steel and concrete input fluctuations in Southeast Asian markets compress development margins before lease stabilization.
- FIRB screening thresholds:Australia's Foreign Investment Review Board raises equity requirements for offshore developers, constraining capital formation for new Melbourne and Sydney supply.
- GB standards compliance:China's fire-safety and density specifications limit conversion economics for aging dormitory stock in tier-two university cities.
Strategic Opportunities
- Underpenetrated Indian corridors:Hyderabad, Pune, and Chennai university clusters lack institutional-grade supply, creating first-mover positioning for integrated developers.
- Wellness amenity convergence:Biophilic design principles merge with mental-health programming to differentiate premium assets in Australian metropolitan hubs.
- RERA compliance frameworks:India's real estate regulations standardize disclosure requirements, reducing due-diligence friction for institutional capital deployment.
Industry Challenges
- Asset-management skill scarcity:Student-housing operations require specialized leasing, retention, and community-programming expertise absent in conventional residential property management.
- Legacy system integration:Retrofitting smart-access and energy-management platforms into 1990s-era dormitories demands complex electrical and data infrastructure reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Student Accommodation Market |
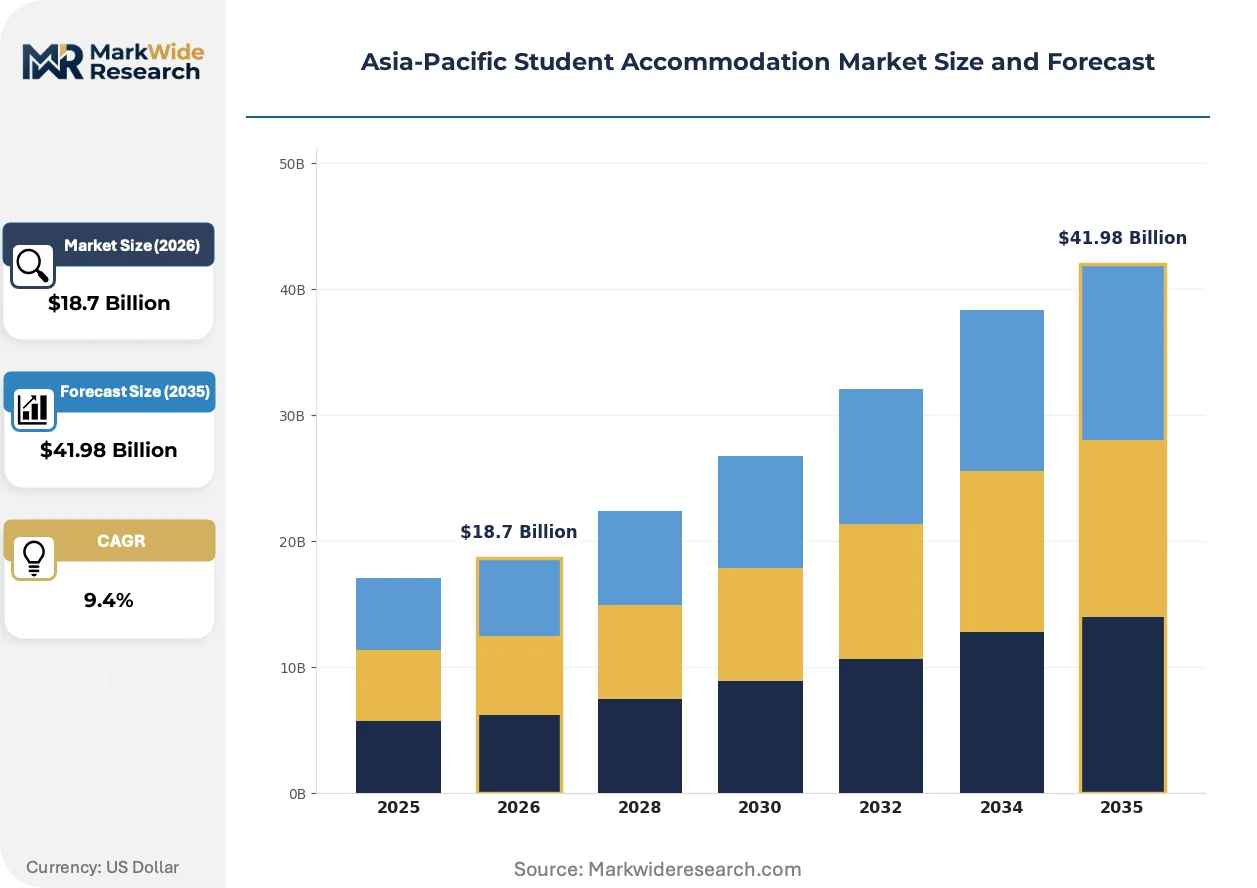
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Shared Flats, Dormitories, Studios, Apartments Client Type: International Students, Domestic Students, Exchange Students, Graduate Students Facility Type: Private Housing, University-Owned, Purpose-Built, Off-Campus Pricing Model: Monthly Rent, Annual Lease, Pay-As-You-Go, All-Inclusive |
| Companies Covered | Mapletree Investments, STUHO, Nest Student Housing, Prime Student Living, My Student Villa, Frasers Hospitality, The Student Housing Company Asia, Uninest Student Residences, Crown Student Living, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Student Accommodation Market Trends and Innovations
Digital infrastructure is rewiring competitive advantage in Asia-Pacific student accommodation, compressing the gap between basic shelter and technology-integrated living environments.
IoT-enabled building management systems are decomposing traditional facility-cost structures across Australian purpose-built portfolios. Melbourne and Sydney operators deploy sensor networks for predictive maintenance and energy optimization, reducing per-bed operating expenditure. This technology compression enables mid-market assets to match premium-tier service levels without equivalent staffing ratios.
China's GB standards for student dormitory fire safety and density specifications are tightening conversion economics for aging stock. Developers in Beijing and Shanghai face extended approval timelines when retrofitting pre-2010 buildings to current codes. The policy friction concentrates new supply in greenfield developments with captive construction pipelines rather than adaptive reuse projects.
Lease-term flexibility is displacing rigid semester-aligned contracts across Southeast Asian capitals. Postgraduate researchers and exchange students demand monthly or quarterly arrangements that traditional university housing cannot accommodate. Singapore and Kuala Lumpur private operators capture this cohort through serviced-apartment hybrids with premium pricing power.
Asia-Pacific Student Accommodation Market Segmentation
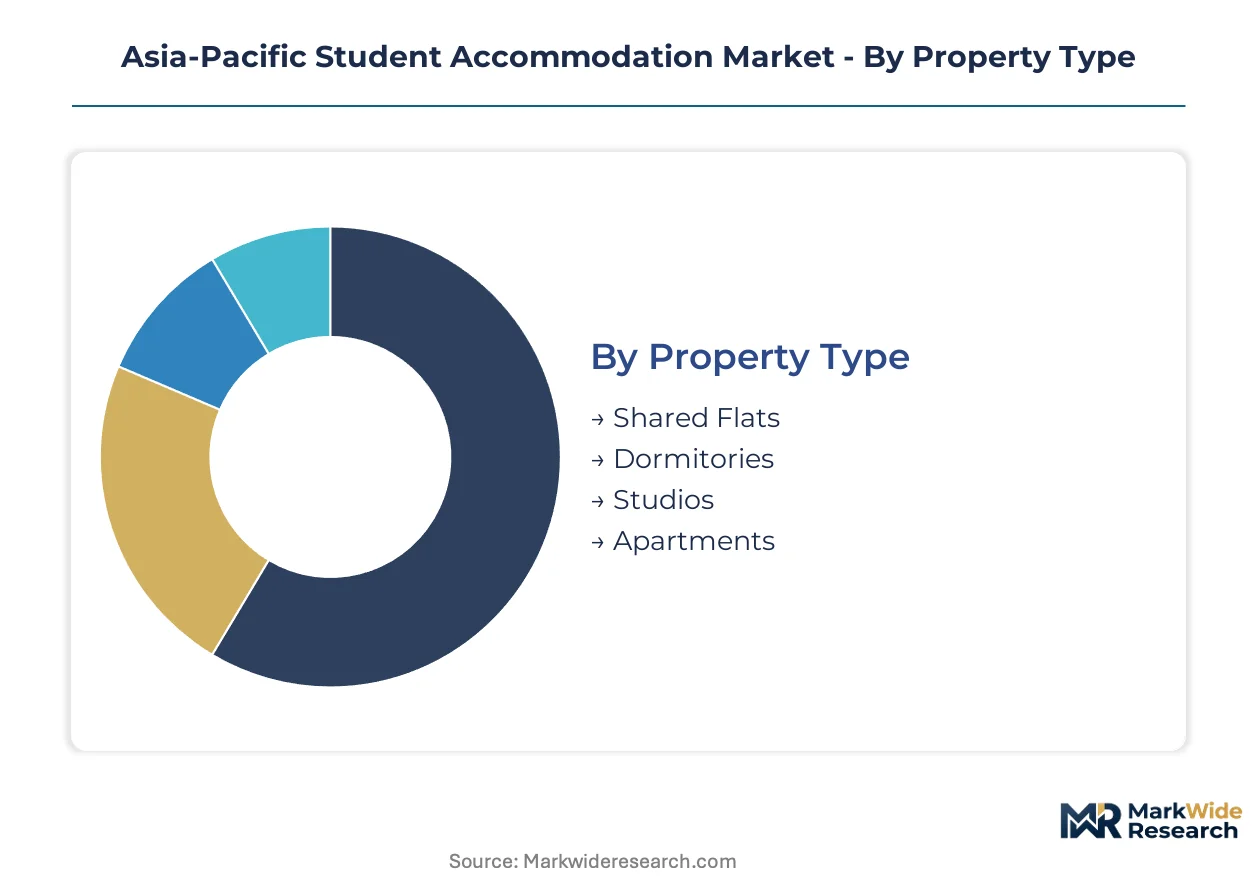
Segmentation in Asia-Pacific student accommodation reveals how capital allocation, regulatory exposure, and operational complexity vary across asset configurations. Investors use these boundaries to match risk tolerance with yield profiles across Melbourne towers, Bangalore retrofits, and Shanghai greenfield developments.
Property Type:
Shared flats face the most intense substitution pressure from purpose-built studios as students prioritize privacy over cost savings in Australian and Chinese corridors.
- Shared Flats:Multi-bedroom configurations with communal kitchens and bathrooms dominate legacy university housing across Indian tier-two cities. Delhi and Bangalore operators struggle to maintain occupancy as bandwidth infrastructure lags TRAI-mandated standards.
- Dormitories:High-density bunk-style arrangements characterize aging stock in Chinese university cities, where GB standards compliance costs deter private capital from retrofitting pre-2010 assets.
- Studios:Self-contained single-occupancy units command premium pricing in Melbourne and Sydney through integrated study pods and en-suite amenities.
- Apartments:Multi-room configurations serve postgraduate cohorts and research students requiring longer-term stability in Singapore and Kuala Lumpur.
Shared flats retain volume leadership; studios hold the steepest expansion curve.
Client Type:
Cost tier stratification separates visa-dependent international enrollees from state-subsidized domestic populations across the region's pricing architecture.
- International Students:Visa-carrying enrollees from South Asia and Southeast Asia concentrate demand in Melbourne, Sydney, and Chinese university corridors. Australian FIRB screening and Canadian policy redirections are accelerating enrollment flows toward Asia-Pacific destinations.
- Domestic Students:Nationals accessing state-subsidized or family-supported housing dominate volume in Indian and Chinese markets, where university-owned supply still captures majority share.
- Exchange Students:Short-term program participants drive seasonal occupancy volatility in Singapore and Kuala Lumpur, where operators deploy flexible-lease products to capture this cohort.
- Graduate Students:Research-degree candidates require extended tenures and dedicated study infrastructure, creating demand for premium purpose-built assets in Australian metropolitan hubs.
Domestic students anchor volume baselines; international students are climbing the fastest as visa reforms redirect enrollment flows.
Facility Type:
Margin concentration varies sharply between captive university supply and third-party operated assets, with ownership structure determining pricing power and capital efficiency.
- Private Housing:Independently operated residential stock ranges from informal landlord arrangements to institutional-grade portfolios in Australian cities, where regulatory clarity supports yield compression.
- University-Owned:Campus-adjacent dormitories controlled by academic institutions dominate Chinese and Indian markets, though aging infrastructure constrains rental growth.
- Purpose-Built:Integrated development pipelines combining construction, management, and lease underwriting deliver the deepest margin pools across Melbourne, Sydney, and Singapore.
- Off-Campus:Third-party assets located beyond university boundaries capture price-sensitive segments in Bangalore and Hyderabad, where transport connectivity determines occupancy rates.
Purpose-built assets command margin leadership; off-campus supply is gaining share fastest in underpenetrated Indian corridors.
Pricing Model:
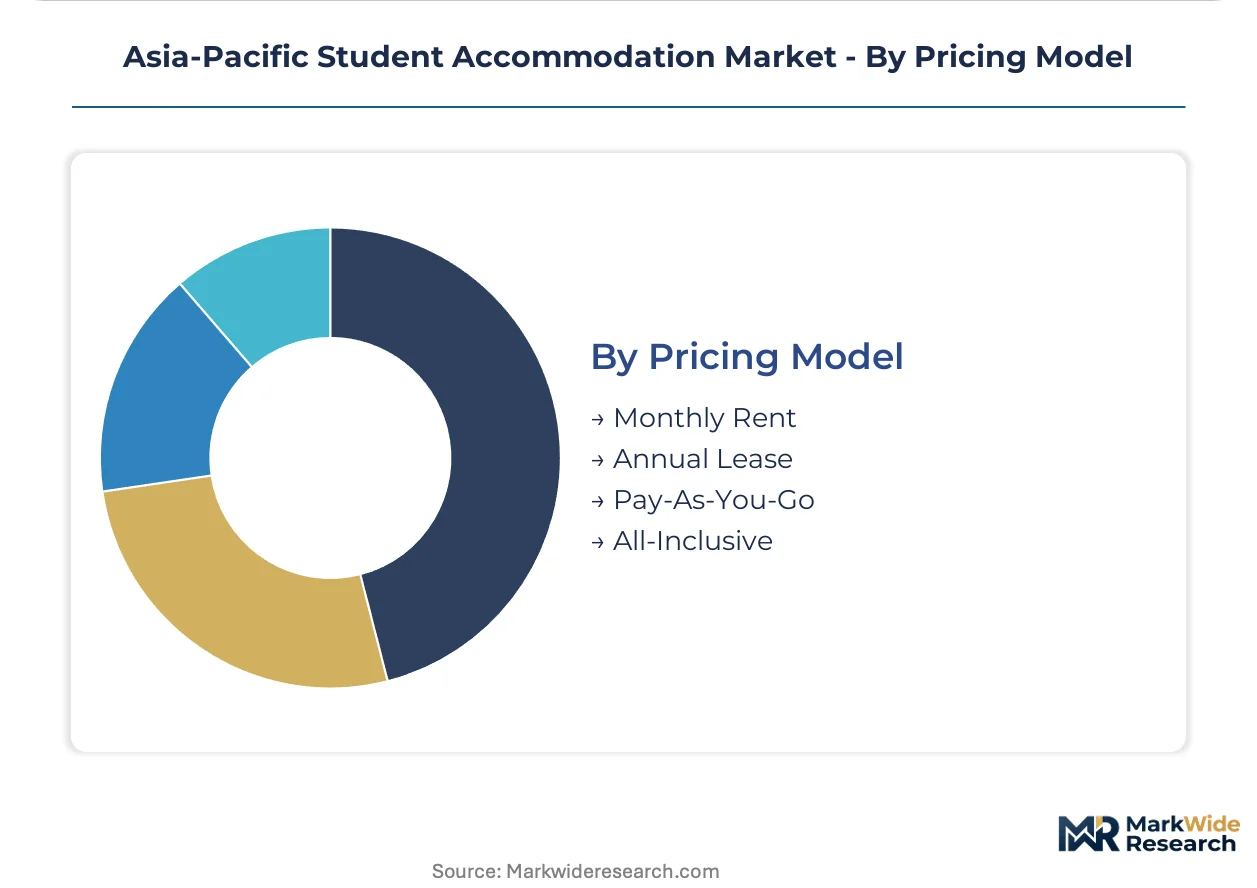
Customer type and lease duration preferences are fragmenting traditional semester-aligned contracts across Southeast Asian capitals.
- Monthly Rent:Short-cycle payments accommodate exchange students and research visitors in Singapore and Kuala Lumpur, where serviced-apartment operators deploy premium pricing.
- Annual Lease:Full-academic-year commitments dominate Australian and Chinese institutional contracts, providing revenue predictability for purpose-built developers.
- Pay-As-You-Go:Usage-based arrangements for amenities and utilities are emerging in tech-enabled Melbourne and Sydney assets with IoT metering infrastructure.
- All-Inclusive:Bundled rent covering utilities, internet, and programming commands premium positioning in premium-tier Australian developments targeting wellness-focused segments.
Annual leases retain structural dominance; monthly arrangements are expanding most quickly as postgraduate and exchange cohorts reshape demand patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in Australian metropolitan corridors and Chinese university cities, where institutional capital flows into purpose-built developments. Indian corridors are emerging as retrofit battlegrounds as connectivity mandates force bandwidth upgrades. Southeast Asian capitals are fragmenting toward hybrid serviced-apartment formats.
Australia
Melbourne and Sydney absorb the bulk of international student visa flows redirected from Canadian processing backlogs. FIRB screening raises offshore equity thresholds, constraining new supply timelines. Purpose-built towers in Southbank and Parramatta capture premium pricing through integrated wellness programming.
China
Beijing and Shanghai university clusters face tightening GB standards for fire safety and density specifications. Developers abandon pre-2010 dormitory conversions for greenfield pipelines with captive construction control. Xiong'an New Area and Guangzhou Science City are emerging as planned campus zones with institutional-grade supply mandates.
India
Hyderabad, Pune, and Chennai university corridors lack institutional-grade stock, creating first-mover positioning for integrated developers. TRAI mandates minimum broadband standards in multi-tenant buildings, accelerating smart-housing retrofits. Bangalore's Whitefield and Koramangala clusters are seeing yield compression as tech-enabled competitors displace legacy landlords.
Singapore
Mapletree Investments dominates institutional-grade portfolios through captive development pipelines in one-north and Buona Vista education zones. The city-state's university-industry integration policies concentrate demand in research-corridor adjacencies. Flexible-lease hybrids capture postgraduate researchers underserved by semester-aligned contracts.
Malaysia
Kuala Lumpur private operators deploy serviced-apartment formats with monthly lease terms for exchange-student volatility. Iskandar Malaysia's EduCity corridor is attracting cross-border enrollment from Indonesia and Vietnam. Bandar Sunway and Subang Jaya sub-markets are seeing pricing power shift toward tech-enabled off-campus supply.
Asia-Pacific Student Accommodation Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Purpose-built specialists with integrated pipelines command margin pools, while serviced-apartment operators capture premium pricing through lease flexibility. Three archetypes dominate: institutional developers with captive construction, hospitality hybrids leveraging serviced-apartment expertise, and tech-enabled operators retrofitting bandwidth infrastructure. Consolidation is accelerating through portfolio acquisitions and joint ventures with university endowments.
Within the institutional developer tier, Mapletree Investments exemplifies captive pipeline control through Singapore-based education zone developments. Frasers Hospitality represents the hospitality-hybrid archetype, deploying serviced-apartment formats across Southeast Asian capitals. Nest Student Housing anchors the tech-enabled vector, differentiating Australian assets through IoT-integrated operations in Melbourne and Sydney corridors.
| Leading Market Players |
|---|
| Mapletree Investments |
| STUHO |
| Nest Student Housing |
| Prime Student Living |
| My Student Villa |
| Frasers Hospitality |
| The Student Housing Company Asia |
| Uninest Student Residences |
| Crown Student Living |
| Others |
Pricing and Supply Chain Analysis
Tech-enabled bandwidth infrastructure substitution for legacy electrical systems simultaneously redistributes supply geography toward Indian smart-housing retrofit clusters and compresses pricing economics for dormitory operators facing TRAI compliance deadlines. Melbourne and Sydney developers capture margin premiums through integrated IoT platforms that displace conventional facility-management cost structures.
Pricing Analysis
Australia's FIRB screening dictates the pricing tier structure across purpose-built assets, elevating equity thresholds for offshore capital and concentrating premium pricing power among domestic institutional developers with captive pipelines. Three-tier pricing structure across premium, standard, and economy levels separates wellness-programmed towers from bandwidth-compliant mid-market stock and aging university-owned dormitories. Cost compression in economy tiers intensifies because legacy landlords absorb TRAI-mandated retrofit expenses without revenue recovery mechanisms. International students exhibit lowest price sensitivity where visa processing backlogs constrain alternative destination choices; domestic students in Indian tier-two cities anchor volume at price-sensitive baselines.
Supply Chain Analysis
Steel and concrete input volatility through Southeast Asian construction markets underwrites margin unpredictability for greenfield developments before lease stabilization. Supply concentration centers on China for prefabricated modular components, Australia for structural steel, and India for bandwidth infrastructure hardware. Raw material dependencies rest on iron ore shipments, cement clinker, and fiber-optic cabling. Single-source vulnerability from Chinese modular suppliers exposes developers to extended approval timelines under tightening GB standards. Distribution runs through university-adjacent land assembly channels controlled by institutional developers with captive construction management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific student accommodation is approaching a platform-economics inflection where IoT-enabled building management systems create interoperability layers between previously siloed asset operators and university enrollment systems.
For Market Incumbents: Fortify margin pools through backward integration into captive construction pipelines rather than third-party development contracts. Threats from tech-enabled competitors with sensor-network cost advantages demand certification investment in TRAI-compliant bandwidth infrastructure. Channel control over university partnership agreements represents the critical defensive lever against hospitality-hybrid entrants. For New Entrants and Emerging Players: Differentiate on lease-term flexibility to capture postgraduate researchers and exchange students underserved by semester-aligned contracts. Hyderabad, Pune, and Chennai university corridors present the most penetrable geography given institutional-grade supply scarcity. Go-to-market execution should prioritize serviced-apartment hybrids with monthly arrangements and premium amenity programming. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated developers with captive construction and management capabilities. Long-term viability across the projection horizon rests on pipeline depth in Australian metropolitan hubs and Indian retrofit corridors. Acquisition target archetypes include tech-enabled operators with established IoT platforms and university joint-venture relationships. The signal to watch as inflection indicator is visa processing reform velocity between English-speaking destination countries redirecting enrollment flows.| Strategic Initiative | Industry Significance |
|---|---|
| Bandwidth Infrastructure Retrofit | TRAI mandates force smart-housing upgrades that displace legacy dormitory economics across Indian corridors. |
| Purpose-Built Pipeline Expansion | Captive development control in Melbourne and Sydney captures FIRB-screened capital and premium pricing. |
| Flexible-Lease Product Launch | Monthly arrangements capture postgraduate researchers underserved by traditional semester contracts. |
| University Joint Venture | Partnerships with endowments secure land access and enrollment visibility in underpenetrated clusters. |
| Wellness Amenity Integration | Biophilic design and mental-health programming differentiate premium assets in Australian metropolitan hubs. |
Research Methodology
A standing panel of student housing asset managers, university facilities directors, international enrollment officers, and TRAI compliance consultants provided ongoing calibration across primary interview cycles. Secondary validation drew from Australian FIRB regulatory filings, Chinese GB standards documentation, Indian RERA disclosure databases, and university enrollment statistics. Bottom-up bed-count modeling across Melbourne, Sydney, Bangalore, and Shanghai corridors triangulated against top-down capital flow analysis from institutional investment trackers.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include property type, client visa status, facility ownership structure, and pricing contract duration. CAGRs were derived from enrollment flow projections, supply pipeline tracking, and yield compression patterns in tech-enabled assets. Forecast inputs incorporated visa processing reform scenarios and construction cost indices for steel and concrete.
The analysis sits within stated boundaries; outcomes outside sustained international enrollment growth and stable regulatory enforcement would require recalibration. Forecasts reflect documented assumptions regarding FIRB screening thresholds, TRAI compliance timelines, and GB standards evolution. Practitioners should keep alternative scenarios live as visa policy oscillations between destination countries and construction input volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Underwater Hotels Market
Accommodation
Peer to Peer Accommodation Market
Accommodation
Netherlands Hospitality Industry Market
Accommodation
Russia Online Accommodation Market
Accommodation
Japan Hospitality Market
Accommodation
France Online Accommodation Market
Accommodation
Hostel Market
Accommodation
China Online Accommodation Market
Accommodation
Bed and Breakfast Accommodation Market
Accommodation
Global Travel Accommodation Market
Accommodation
Sweden Hospitality Market
Accommodation
Luxury Hotel Market
Accommodation
US Student Accommodation Market
Accommodation
Extended Stay Hotel Market
Accommodation
Airport Sleeping Pods Market
Accommodation
Alternative Accommodation Market