
 Italy Online Accommodation Market | 2026-2036
Italy Online Accommodation Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Online Accommodation Market Outlook
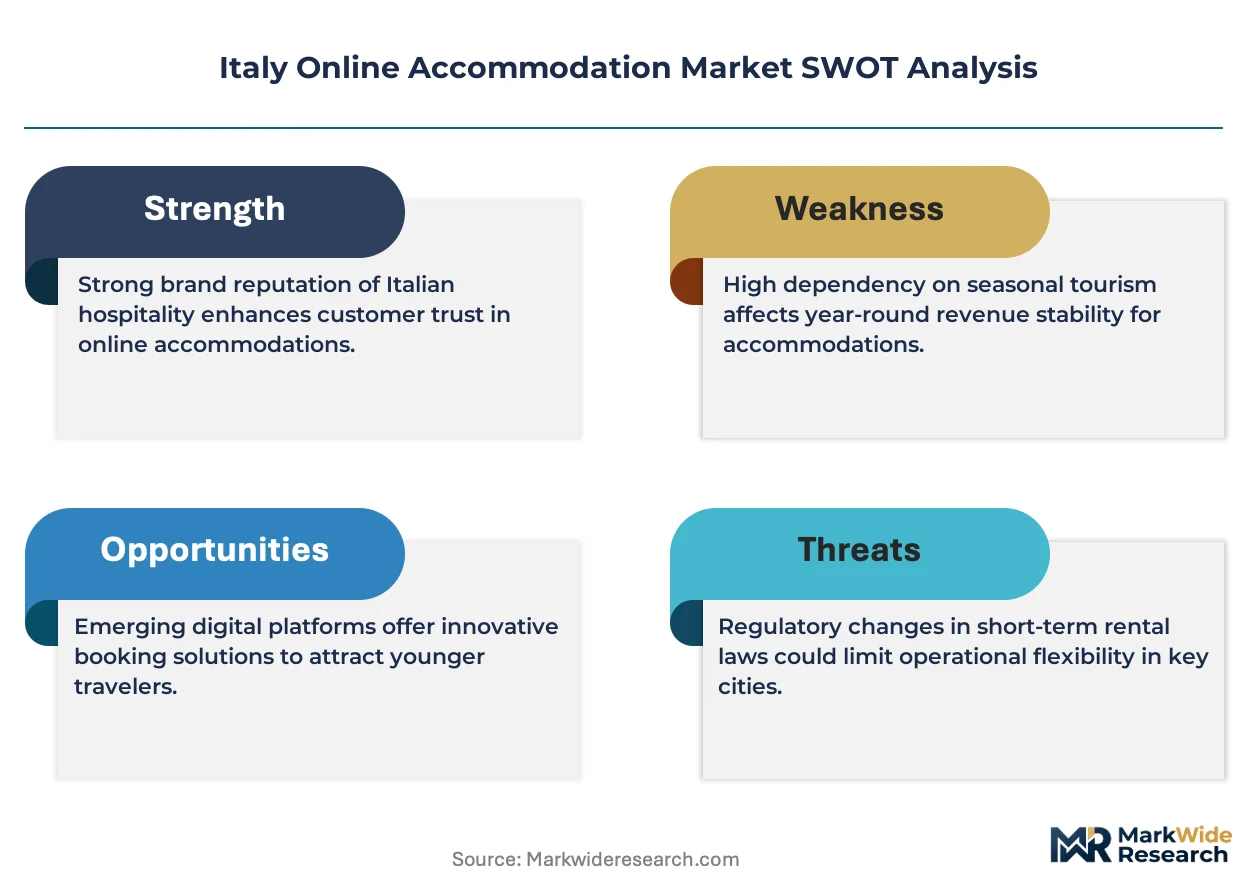
Tuscan agritourism operators are repositioning inventory toward direct-booking engines to reduce commission exposure to intermediaries. Booking Holdings leverages its scale across multiple Italian city clusters to sustain rate parity enforcement. Airbnb anchors supply in Rome and Florence through host acquisition programs that compete with traditional hotel channels.
Italy online accommodation encompasses digitally intermediated lodging transactions spanning hotels, vacation rentals, hostels, and bed-and-breakfast properties, typically confirmed through real-time availability APIs and instant confirmation protocols. The sector functions as a distribution infrastructure connecting fragmented property supply with segmented traveler demand across leisure, business, and group categories. Vacation rentals command expanding share in coastal provinces where supply elasticity exceeds urban hotel constraints. Online travel agencies dominate transaction volume, though direct bookings gain structural ground as property management systems integrate native payment processing.
Italy's Agenzia delle Entrate enforces automated data transmission requirements for short-term rental platforms, while EU Digital Services Act obligations impose content moderation duties on listing aggregators. These frameworks elevate compliance costs for cross-border operators while creating operational barriers for unregistered hosts. Stakeholders must monitor enforcement consistency between national tax authorities and municipal rental registries as registration mandates proliferate across major destination cities.
Market Dynamics
Italy's online accommodation sector is being restructured by the collision of mobile-first booking behavior with tightening municipal rental registration mandates. Platform operators now face simultaneous pressure to reduce friction in the reservation journey while absorbing compliance costs from fragmented local enforcement regimes.
Growth Catalysts
- EU Digital Services Act:Platform accountability requirements are accelerating investment in automated content moderation and host verification systems, improving listing quality and traveler trust metrics.
- Mobile payment infrastructure:Instant confirmation protocols enabled by native payment processing in property management systems are compressing booking abandonment rates among domestic leisure travelers.
- Rome historic center supply scarcity:Concentrated demand in UNESCO-protected zones sustains premium rate floors that attract institutional capital into vacation rental aggregation.
Market Restraints
- Agenzia delle Entrate data transmission mandates:Automated reporting requirements for short-term rental platforms impose fixed compliance costs that disproportionately burden small-scale host networks.
- Coastal province supply elasticity:Vacation rental inventory expansion in seasonal markets creates occupancy volatility that compresses yield management effectiveness for yield-dependent operators.
- Rate parity enforcement:Booking Holdings' scale advantages across Italian city clusters limit pricing autonomy for independent properties seeking direct-booking channel differentiation.
Strategic Opportunities
- Sicily's underpenetrated digital channel:Lower OTA penetration rates in southern provinces create white space for direct-booking engine deployment by agritourism and boutique property operators.
- Milan business district extended-stay conversion:Corporate travel pattern shifts toward blended leisure-business trips enable repositioning of traditional hotel inventory into serviced apartment formats.
- Tuscan agritourism PMS convergence:Integration of channel management with native payment processing and CRM modules enables commission reduction strategies previously accessible only to scaled urban operators.
Industry Challenges
- Municipal registration registry fragmentation:Non-standardized host identification requirements across Rome, Florence, Milan and Bologna create operational complexity for multi-city platform operators.
- Legacy property management system migration:Independent bed-and-breakfast operators face capex barriers and technical integration friction when transitioning from manual reservation ledgers to real-time availability APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Online Accommodation Market |
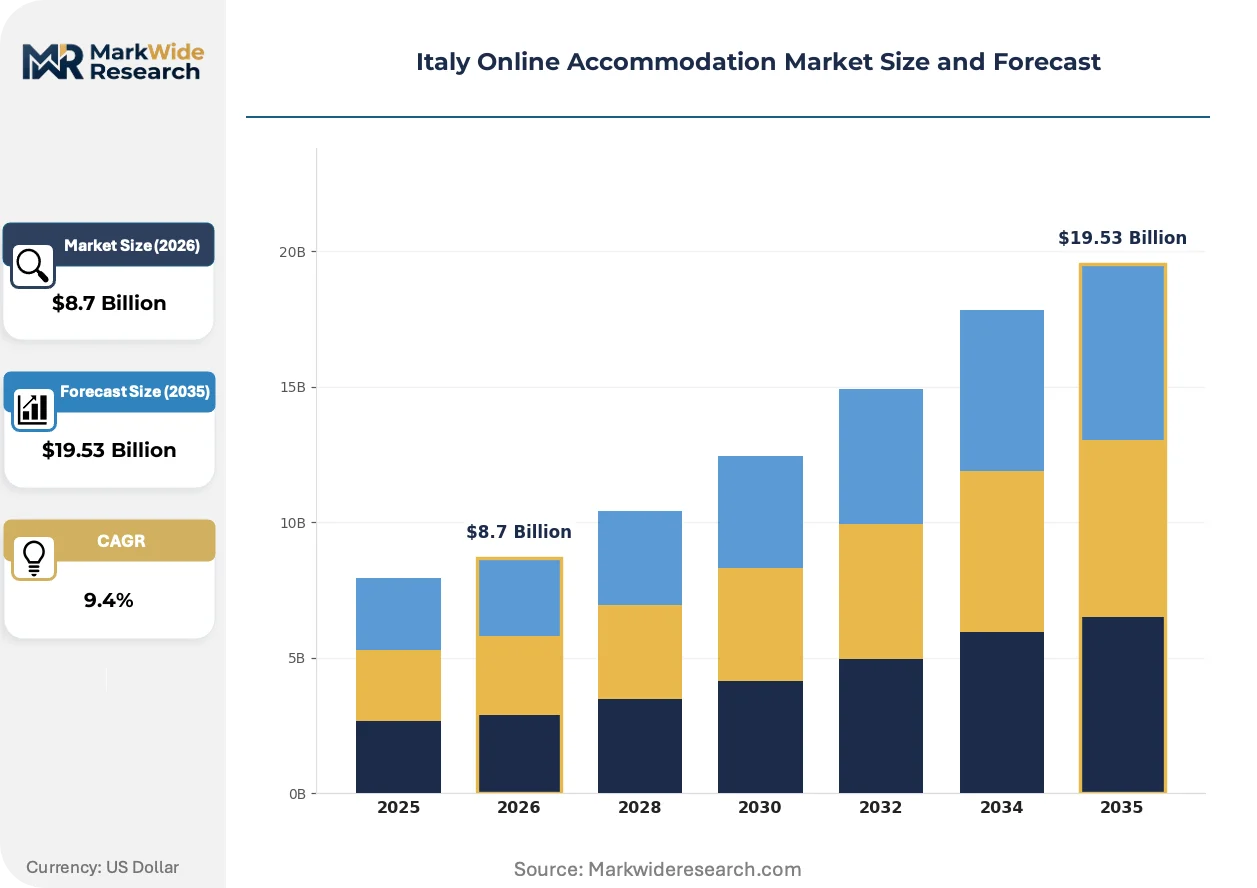
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hotels, Hostels, Vacation Rentals, Bed & Breakfasts Distribution Channel: Online Travel Agencies, Direct Bookings, Meta-Search Engines, Mobile Apps Price Tier: Luxury, Mid-Range, Economy, Budget Customer Type: Leisure Travelers, Business Travelers, Group Travelers, Families |
| Companies Covered | Booking Holdings, Airbnb, Expedia, Tripadvisor, Agoda, Bookings for You, Vrbo, Lastminute.com, Trivago, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Online Accommodation Market Strategic Shifts
Platform economics in Italian online accommodation are being reconfigured by three converging forces: embedded payment infrastructure, regulatory data transparency mandates, and the unbundling of distribution from property management. These shifts are compressing intermediary margins while elevating operational complexity for host networks.
Artificial intelligence-driven dynamic pricing engines are integrating real-time demand signals from event calendars, flight search data, and competitive rate monitoring to automate revenue optimization. Mid-scale hotel operators in Milan and Rome are adopting these tools most aggressively, displacing static seasonal rate cards. The technology is integrating previously siloed data streams into unified decision architectures that compress response latency to demand shocks.
Italy's implementation of EU Digital Services Act content moderation obligations is imposing new operational burdens on listing aggregators. Platform operators must now maintain human oversight capabilities for algorithmic content flagging systems, elevating fixed cost structures. Vacation rental segments in Florence and Venice face the most acute compliance pressure due to higher concentrations of contested listings in historic preservation zones.
Domestic leisure travelers are abandoning desktop-first booking patterns in favor of mobile-native reservation flows with embedded identity verification. Younger demographic segments in particular are bypassing traditional OTA interfaces for property-branded applications with loyalty program integration. This behavioral pivot is most visible in coastal provinces where repeat visitation patterns support direct relationship cultivation between hosts and guests.
Italy Online Accommodation Market Segmentation
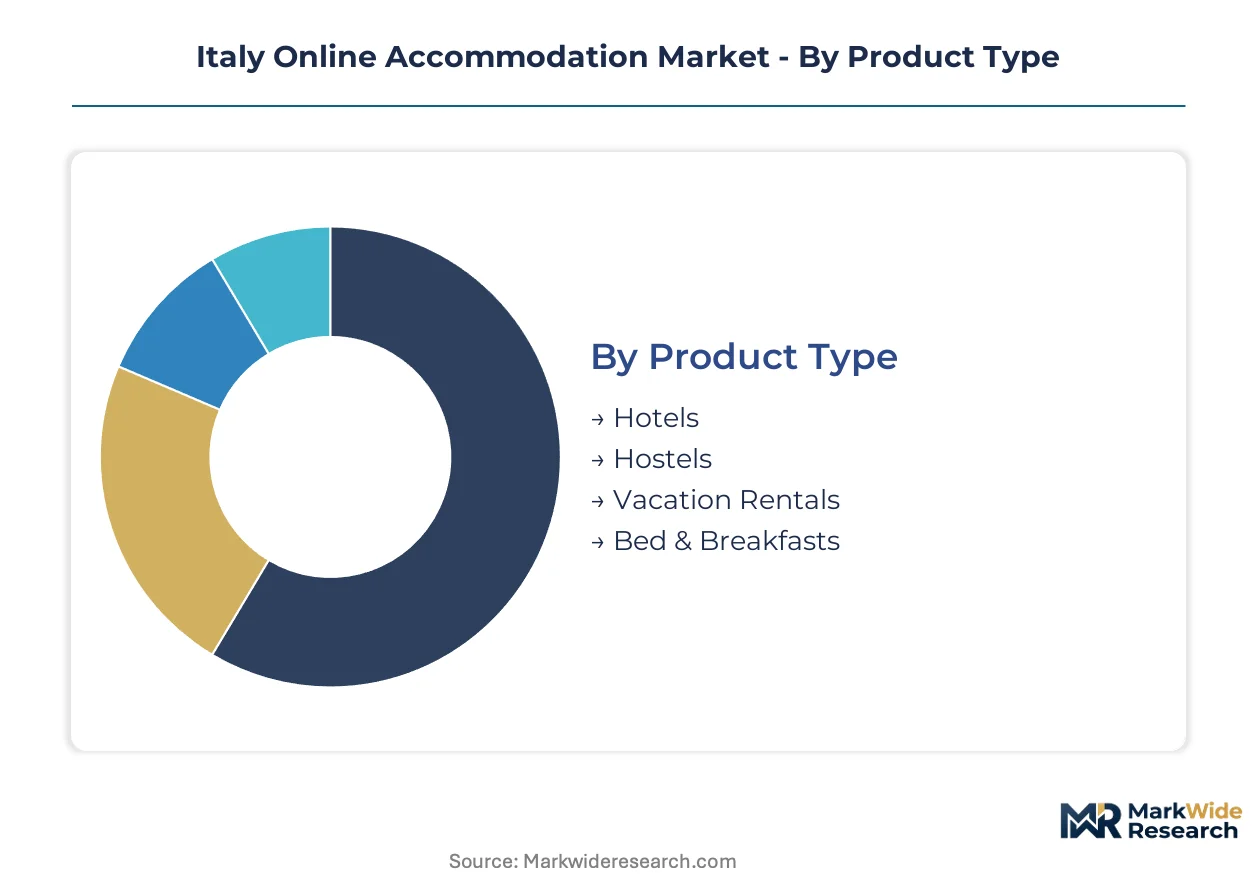
Segmentation in Italian online accommodation reveals divergent margin structures and booking behaviors across property types and customer profiles. Distribution channel selection and price tier positioning directly determine commission exposure and revenue capture efficiency for operators across Rome, Milan, and coastal provinces.
Product Type:
Standardized inventory with centralized yield management contrasts against fragmented supply requiring host-level pricing autonomy across this category.
- Hotels:Properties with real-time availability APIs and property management system integration dominate transaction volume in Milan's business district and Rome's historic center. Revenue management teams deploy dynamic pricing engines that compress response latency to demand shocks from flight search data and event calendars.
- Vacation Rentals:Furnished apartments and homes listed through host-acquisition programs supply elasticity exceeds urban hotel constraints in coastal provinces. Municipal registration registry fragmentation across Florence, Venice, and Bologna creates operational complexity for multi-city platform operators managing these listings.
- Hostels:Shared accommodation formats target younger demographic segments with mobile-native booking patterns and embedded identity verification protocols.
- Bed & Breakfasts:Small-scale independent operators face capex barriers migrating from manual reservation ledgers to real-time availability APIs.
Leading the category by volume: Hotels. Expanding most quickly: Vacation Rentals.
Distribution Channel:
Commission structures and customer acquisition costs vary sharply across intermediated versus direct booking pathways.
- Online Travel Agencies:Booking Holdings and similar platforms enforce rate parity across Italian city clusters, limiting pricing autonomy for independent properties. Scale advantages sustain transaction volume dominance despite rising commission rates.
- Direct Bookings:Native payment processing in property management systems enables commission reduction strategies for Tuscan agritourism and boutique operators. Loyalty program integration supports repeat visitation cultivation in coastal provinces.
- Meta-Search Engines:Aggregator interfaces compress booking abandonment rates through instant confirmation protocol visibility.
- Mobile Apps:Property-branded applications capture domestic leisure travelers abandoning desktop-first patterns, particularly in Sicily's underpenetrated digital channel.
Highest transaction volume: Online Travel Agencies. Fastest share gain: Direct Bookings.
Price Tier:
Rate floors and yield management sophistication stratify sharply across this dimension.
- Luxury:UNESCO-protected zone scarcity in Rome's historic center sustains premium pricing power for five-star properties with concierge-integrated booking engines.
- Mid-Range:Three and four-star hotels in Milan's business district face pressure from extended-stay conversion trends blending corporate and leisure demand patterns.
- Economy:Limited-service properties compete on location proximity to transport hubs rather than amenity differentiation.
- Budget:Hostel and basic vacation rental inventory targets price-sensitive leisure travelers with minimal service inclusion.
Steepest rate compression: Budget. Strongest pricing power: Luxury.
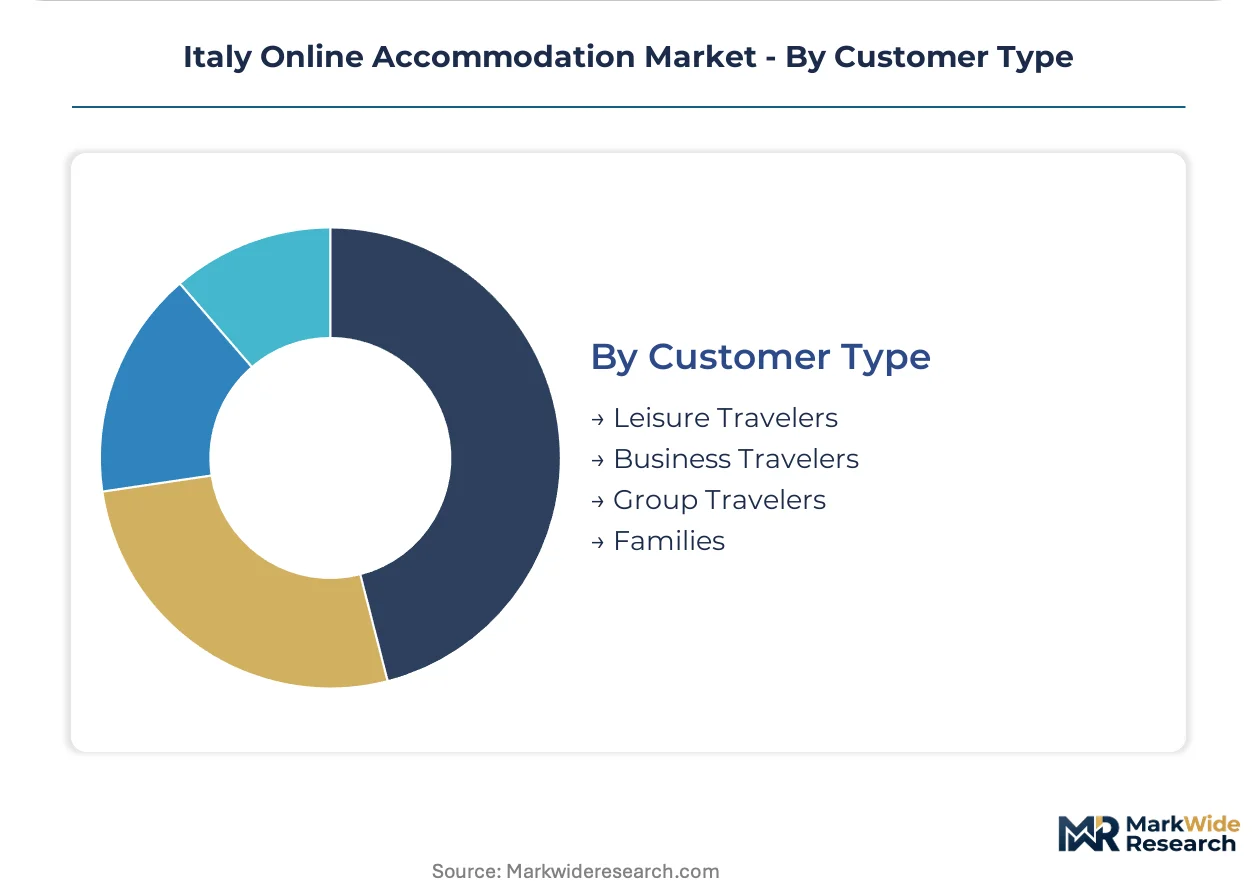
Customer Type:
Booking lead times and cancellation flexibility requirements diverge substantially across traveler motivations.
- Leisure Travelers:Domestic segments drive mobile-first platform migration with instant confirmation protocol expectations. Coastal province repeat visitation supports direct relationship cultivation between hosts and guests.
- Business Travelers:Corporate account negotiated rates concentrate in Milan's business district and Rome's EUR district, with blended leisure-business trip patterns enabling serviced apartment format repositioning.
- Group Travelers:Wedding and event blocks require inventory holding capabilities that strain real-time availability API architectures.
- Families:Multi-room vacation rental demand peaks in coastal provinces where supply elasticity accommodates flexible arrival patterns.
Dominant volume contributor: Leisure Travelers. Steepest behavioral shift: Business Travelers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tuscany's agritourism estates and Rome's UNESCO-protected historic fabric anchor Italy's accommodation supply geography, with digital distribution infrastructure concentrating in northern commercial corridors.
Lombardy
Milan's business district generates sustained corporate demand for extended-stay inventory and serviced apartment conversions. The region's Agenzia delle Entrate field office enforces automated data transmission protocols for short-term rental platforms. Bergamo and Brescia satellite cities expand secondary inventory pools as remote work patterns disperse booking volume.
Lazio
Rome's historic center supply scarcity sustains premium rate floors across five-star and boutique segments. Municipal rental registries impose host identification requirements distinct from national tax frameworks. EUR district properties capture blended leisure-business demand through repositioned hotel inventory.
Tuscany
Agritourism operators in Chianti and Val d'Orcia drive direct-booking engine adoption to reduce OTA commission exposure. Regional tourism authorities coordinate with national regulators on host verification standards. Florence's dense historic core concentrates vacation rental supply where preservation zoning limits hotel expansion.
Veneto
Venice lagoon tourism sustains seasonal demand volatility across vacation rental and boutique hotel inventory. Provincial authorities enforce distinct registration mandates for historic center properties versus mainland supply. Verona and Padua business travel corridors anchor mid-range hotel yield management sophistication.
Sicily
Coastal provinces from Taormina to Agrigento exhibit underpenetrated OTA coverage relative to northern benchmarks. Island-specific tax reporting requirements create compliance friction for cross-border platform operators. Palermo and Catania urban cores attract direct-booking investment from agritourism and boutique property networks.
Italy Online Accommodation Market Competitive Environment
Global majors compete with regional champions across distribution technology and host acquisition dimensions, producing a tiered structure where scale advantages concentrate transaction volume while specialization sustains margin pockets. The vendor base separates into three archetypes: multinational OTA platforms with rate parity enforcement capabilities, vacation rental specialists with host-network density, and regional booking engines with direct-relationship cultivation. Dominant competitive moves include M&A consolidation of property management system providers and vertical integration into native payment processing infrastructure.
Among US-based platform operators, Booking Holdings and Airbnb occupy positions at opposite ends of the intermediary spectrum, with the former exemplifying scale-driven OTA consolidation and the latter representing host-network aggregation. Expedia anchors a third archetype as a diversified travel conglomerate with cross-product bundling capabilities. These three entities collectively represent the competitive tension between transaction volume capture and host relationship ownership that defines sector dynamics.
| Leading Market Players |
|---|
| Booking Holdings |
| Airbnb |
| Expedia |
| Tripadvisor |
| Agoda |
| Bookings for You |
| Vrbo |
| Lastminute.com |
| Trivago |
| Others |
Value Chain & Pricing Dynamics
Horizontal integration between property management systems and native payment processing anchors supply positioning while compressing intermediary margins across Italian urban and coastal markets. Booking Holdings' scale advantages sustain rate parity enforcement that limits independent properties' pricing autonomy, particularly in Milan's business district and Rome's historic center where supply scarcity concentrates.
Pricing Analysis
Commission bundling versus unbundled direct-booking alternatives stratifies pricing structures across distribution channels. Three-tier pricing separates luxury concierge-integrated properties from mid-range dynamic yield-managed inventory and economy limited-service formats. Pricing pressure stems from Booking Holdings' rate parity enforcement across Italian city clusters. Budget hostel and basic vacation rental segments exhibit highest price sensitivity, while UNESCO-protected zone luxury properties maintain lowest elasticity due to supply constraints.
Supply Chain Analysis
Logistics and last-mile connectivity costs concentrate supply chain leverage with platform operators possessing dense host networks in Rome, Florence, and Milan. Property management system providers draw from cloud infrastructure, payment gateway APIs, and identity verification services. Single-source vulnerability rests on Booking Holdings' transaction volume dominance. Distribution runs through online travel agency intermediaries, direct-booking engines, and meta-search aggregators to fragmented property endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is intensifying as platform operators pursue captive control over payment processing infrastructure to reduce third-party dependency and capture margin leakage.
For Market Incumbents: Anticipate regulatory fragmentation across municipal rental registries as Agenzia delle Entrate mandates proliferate. Defensive consolidation should prioritize backward integration into property management system providers and channel management technology. Rate parity enforcement remains the critical lever for maintaining transaction volume dominance against direct-booking growth. For New Entrants and Emerging Players: EU Digital Services Act implementation in Italy opens a window for compliance-focused platform positioning. White-space targets include Sicily's underpenetrated digital channel and Tuscan agritourism direct-booking engine deployment. Go-to-market execution should emphasize native payment processing integration to reduce commission exposure. For Investors and Strategic Acquirers: Exit pathways concentrate in property management system consolidation and vacation rental aggregation platforms. Long-term viability favors operators with integrated payment infrastructure and host verification capabilities. Watch municipal registration enforcement consistency as the inflection signal for compliance cost trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Property Management System Integration | Native payment processing reduces Booking Holdings commission exposure for Tuscan agritourism operators. |
| Host Verification Infrastructure | Automated identity systems satisfy EU Digital Services Act content moderation obligations in Florence and Venice. |
| Direct-Booking Engine Deployment | Loyalty program integration captures domestic leisure travelers abandoning desktop-first patterns in Sicily. |
| Dynamic Pricing Engine Adoption | Milan and Rome mid-scale hotels compress response latency to demand shocks from event calendars. |
| Extended-Stay Format Conversion | Milan business district inventory repositioning captures blended leisure-business corporate travel patterns. |
Study Parameters
Independent corroboration across property management system providers, online travel agency executives, and regional tourism authority officials underwrites the qualitative findings. Primary interviews with revenue management directors at Milan and Rome hotel operators, channel managers at Tuscan agritourism estates, and compliance officers at short-term rental platforms combined with secondary validation from Agenzia delle Entrate regulatory filings, EU Digital Services Act implementation documents, and property technology vendor disclosures. Bottom-up transaction volume estimates and top-down market sizing triangulate to produce convergent figures.
Comparable historical booking patterns across domestic leisure, business, and group traveler segments anchored the forecast window to observed behavioral shifts. The analytical framework models property type, distribution channel, price tier, and customer type segmentation dimensions throughout the forecast period. CAGRs derive from trend extrapolation adjusted for regulatory enforcement intensity and mobile payment infrastructure penetration. Forecast inputs incorporate host registration mandate proliferation rates and direct-booking engine adoption curves.
The model assumes a particular technology adoption path; alternative pathways for artificial intelligence-driven dynamic pricing would alter the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and platform compliance cost absorption. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Airport Sleeping Pods Market
Accommodation
Bed and Breakfast Accommodation Market
Accommodation
Germany Student Accommodation Market
Accommodation
Casino Hotel Market
Accommodation
Recreational and Vacation Camp Market
Accommodation
Asia-Pacific Travel Accommodation Market
Accommodation
France Hospitality Market
Accommodation
In-Flight Catering Services Market
Accommodation
United States Online Accommodation Market
Accommodation
Glamping Market
Accommodation
Switzerland Hospitality Market
Accommodation
Africa Hotel Market
Accommodation
Underwater Hotels Market
Accommodation
US Recreational and Vacation Camp Market
Accommodation
US Student Accommodation Market
Accommodation
China Tourism and Hotel Market