
 North America Dermal Fillers Market | 2026-2036
North America Dermal Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dermal Fillers Market Analytics
Licensed injector availability is reorganizing competitive dynamics across the North America dermal fillers landscape. Galderma sustains broad portfolio coverage across hyaluronic acid and biostimulatory categories. AbbVie Inc. leverages its Allergan Aesthetics infrastructure to control distribution through direct physician channels. Merz Pharma specializes in ultrasound-compatible filler formulations that differentiate its Radiesse and Belotero lines.
North America dermal fillers comprise injectable gel or suspension formulations, primarily hyaluronic acid cross-linked with BDDE or similar agents at concentrations of 20–25 mg/mL, designed for subdermal or supraperiosteal placement to restore facial volume or correct contour deficiencies. Hyaluronic acid products dominate current volume due to reversibility with hyaluronidase and established safety profiles, while poly-L-lactic acid segments capture premium positioning in collagen biostimulation for gradual volume restoration. Application demand skews toward wrinkle reduction and facial contouring, with lip enhancement representing a faster-growing subset driven by social media visibility and younger demographic entry.
FDA Center for Devices and Radiological Health regulates dermal fillers as Class III medical devices requiring PMA or 510(k) clearance, while Health Canada Medical Devices Bureau imposes comparable licensing standards that filter market entrants by clinical evidence burden. The EU MDR and its indirect influence on multinational manufacturers raise documentation requirements that cascade into North American quality systems. Stakeholders must monitor state-level scope-of-practice expansions allowing non-physician injectors, as these rulings reshape addressable provider bases and training investment priorities.
Market Dynamics
Licensed injector scope-of-practice expansions across US states and Canadian provinces are redistributing demand toward non-physician providers, compressing traditional physician-channel margins while enlarging total addressable patient volume.
Growth Catalysts
- FDA 510(k) clearance pathway acceleration:Streamlined review timelines for hyaluronic acid modifications are shortening product development cycles. Manufacturers file predicate device comparisons rather than full PMA submissions, reducing regulatory burden for line extensions.
- Social media-driven aesthetic awareness:Platform visibility of before-and-after outcomes normalizes procedure acceptance among 25-34 year-old demographics. Instagram and TikTok content reduces patient education costs for clinics.
- Metropolitan corridor concentration:California, Texas, and Florida absorb disproportionate procedure volume due to disposable income density and celebrity culture proximity. Urban clustering enables injector specialization and higher throughput economics.
Market Restraints
- BDDE cross-linker supply concentration:Three chemical manufacturers control global BDDE production, creating input vulnerability for hyaluronic acid filler makers. Price volatility in pharmaceutical-grade raw materials compresses formulation margins.
- Health Canada licensing timelines:Comparable clinical evidence requirements to FDA PMA processes delay Canadian market entry by 18-24 months post-US approval. Smaller manufacturers lack capital to pursue parallel submissions.
- Reversible substitute preference:Hyaluronidase-enabled correction of hyaluronic acid outcomes limits biostimulatory filler penetration. Poly-L-lactic acid and calcium hydroxylapatite face adoption headwinds from irreversibility concerns.
Strategic Opportunities
- Underpenetrated Canadian provinces:Quebec and Atlantic Canada exhibit lower procedure density per capita than Ontario and British Columbia. French-language training programs and provincial billing code expansion unlock provider base growth.
- Ultrasound-guided placement protocols:Real-time visualization technology reduces vascular occlusion risk and enables supraperiosteal precision. Integration with existing filler portfolios differentiates high-end service tiers.
- State-level scope-of-practice liberalization:Nurse practitioner and physician assistant injection authority expansions in Arizona, Colorado, and Nevada enlarge addressable provider pools. Training certification programs capture recurring revenue streams.
Industry Challenges
- Injector credentialing standardization gaps:No federal or harmonized state requirements for dermal filler training hours create quality variance. Malpractice exposure concentrates in practices with high staff turnover.
- Cold chain distribution complexity:Temperature-sensitive hyaluronic acid formulations require validated logistics from manufacturing through clinic storage. Last-mile failures degrade product performance and trigger adverse event reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dermal Fillers Market |
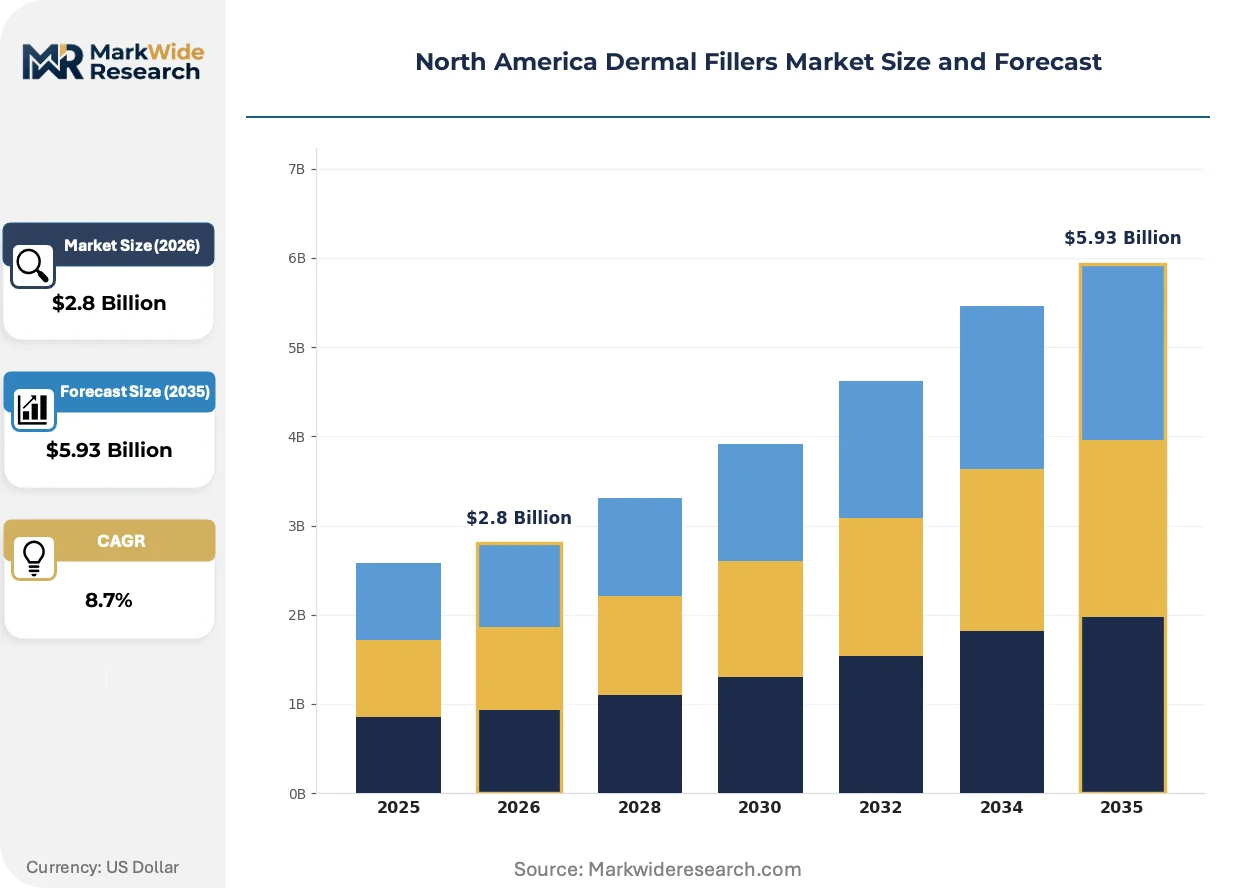
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyaluronic Acid, Calcium Hydroxylapatite, Poly-L-lactic Acid, Polymethyl Methacrylate Application: Facial Contouring, Wrinkle Reduction, Lip Enhancement, Volume Restoration End User: Dermatology Clinics, Medical Spas, Cosmetic Surgeons, Hospitals Distribution Channel: Direct Sales, Online Sales, Retail Pharmacies, Distributors |
| Companies Covered | AbbVie Inc., Galderma, Merz Pharma, Revance Therapeutics Inc., Suneva Medical, Prollenium Medical Technologies, Sinclair Pharma, Teoxane Laboratories, Croma-Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dermal Fillers Market Evolving Landscape
Formulation science and placement precision technologies are converging to elevate safety profiles and expand anatomical treatment zones beyond traditional nasolabial fold applications.
Cohesive polydensified matrix technology is displacing conventional monophasic hyaluronic acid fillers in lip and perioral applications. Dermatology clinics in Los Angeles and Miami adopt these formulations for their reduced Tyndall effect and natural tissue integration. The technology is displacing legacy products in premium service tiers where visible correction quality drives referral volume.
Health Canada's Medical Devices Bureau tightened post-market surveillance requirements for biostimulatory fillers in 2023, mandating five-year safety follow-up protocols. Manufacturers must maintain active patient registries or face license suspension. Poly-L-lactic acid segments absorb disproportionate compliance cost, accelerating consolidation toward integrated aesthetic companies with regulatory infrastructure.
Subscription-based maintenance programs are replacing per-procedure pricing in high-volume Texas and Florida markets. Clinics bundle annual touch-up schedules with loyalty discounts, capturing predictable cash flow while locking patient relationships. This model concentrates most visibly in multi-location dermatology groups competing against medspa chains for recurring revenue.
North America Dermal Fillers Market Segmentation
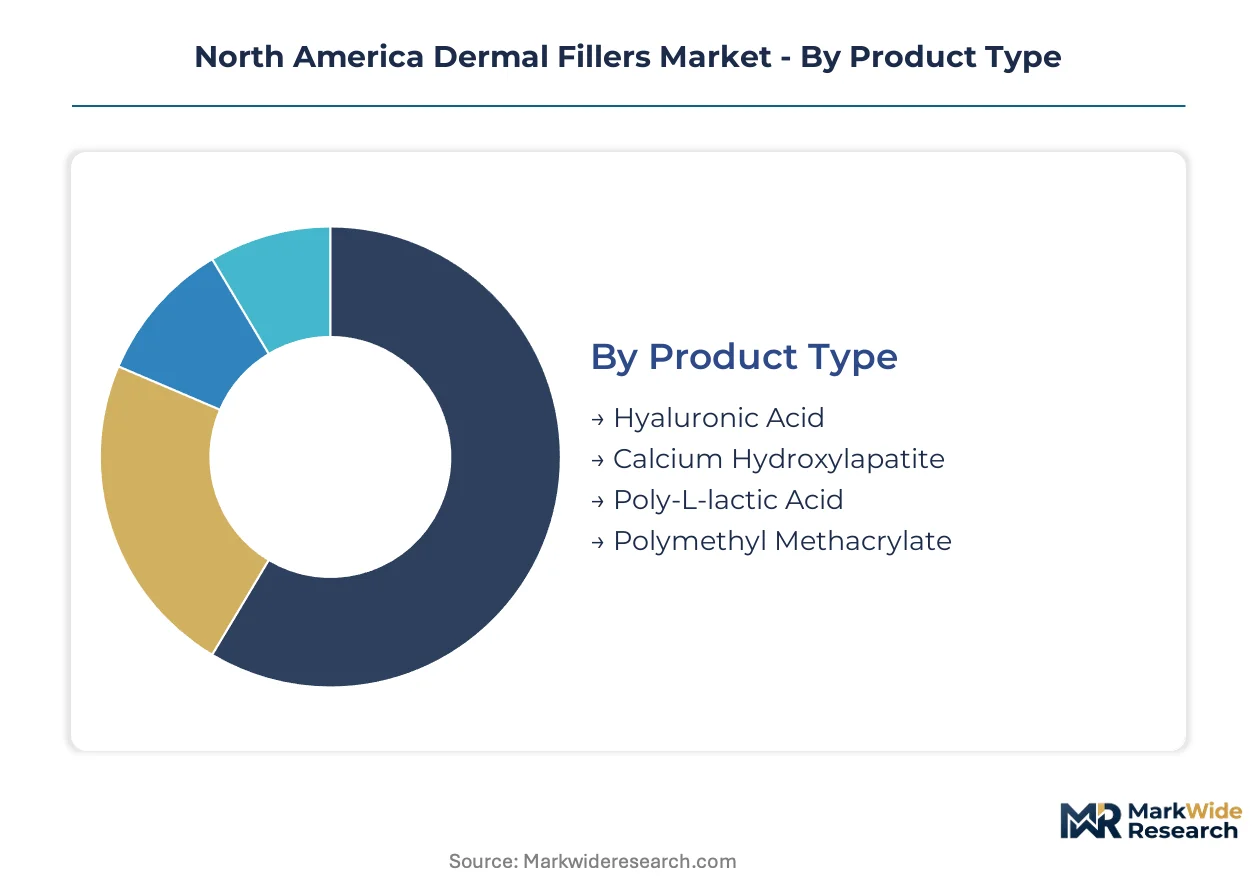
Product differentiation across dermal filler categories determines reimbursement pathways, injector training requirements, and adverse event liability exposure. FDA PMA versus 510(k) clearance distinctions segment commercialization timelines and capital requirements.
Product Type:
FDA Center for Devices and Radiological Health classifies hyaluronic acid fillers through 510(k) predicate pathways while mandating PMA submissions for permanent implant categories, creating divergent evidence burdens across this segmentation.
- Hyaluronic Acid:Cross-linked formulations with BDDE or similar agents at 20–25 mg/mL concentrations dominate procedural volume. Reversibility via hyaluronidase injection concentrates demand in California, Texas, and Florida metropolitan corridors where correction flexibility reduces patient hesitation and malpractice exposure.
- Calcium Hydroxylapatite:Microsphere suspensions in carboxymethylcellulose gel provide immediate volume plus collagen biostimulation. Ultrasound-guided placement protocols in high-end dermatology practices differentiate Radiesse positioning against reversible alternatives.
- Poly-L-lactic Acid:Biostimulatory collagen induction requires serial injection sessions over months. Health Canada five-year safety follow-up mandates impose disproportionate compliance costs.
- Polymethyl Methacrylate:Permanent microsphere implants face PMA pathway requirements and irreversibility constraints limiting addressable patient pool.
Established volume favors Hyaluronic Acid; emerging adoption favors Calcium Hydroxylapatite.
Application:
Procedure reimbursement coding and social media visibility patterns concentrate demand unevenly across anatomical treatment zones.
- Facial Contouring:Cheek and jawline sculpting using supraperiosteal placement techniques commands premium pricing in Los Angeles and Miami celebrity-adjacent markets. Ultrasound visualization technology enables safer deep-plane injection.
- Wrinkle Reduction:Nasolabial fold correction represents the original FDA-approved indication with mature reimbursement pathways. Volume concentrates in established dermatology practices with legacy patient bases.
- Lip Enhancement:Platform-driven aesthetic normalization among 25-34 year-old demographics expands fastest. Cohesive polydensified matrix formulations displace conventional products in perioral applications.
- Volume Restoration:Temple and midface hollowing correction targets older demographics with higher disposable income. Poly-L-lactic acid positioning dominates gradual restoration protocols.
Platform visibility elevates Lip Enhancement trajectory; clinical tradition stabilizes Wrinkle Reduction share.
End User:
Scope-of-practice liberalization across Arizona, Colorado, and Nevada redistributes patient flow toward non-physician injectors.
- Dermatology Clinics:Board-certified specialists control complex facial contouring and complication management. California concentration enables subspecialization in ultrasound-guided protocols.
- Medical Spas:Nurse practitioner and physician assistant injection authority expansions enlarge addressable provider pools in Texas and Florida. Subscription maintenance programs concentrate in multi-location chains.
- Cosmetic Surgeons:Surgical practices integrate fillers into comprehensive facial rejuvenation workflows. Higher price tolerance supports biostimulatory product adoption.
- Hospitals:Academic medical centers concentrate reconstructive and post-traumatic applications. Training program affiliation creates downstream referral pipelines.
Volume gravity centers on Dermatology Clinics; provider base expansion favors Medical Spas.
Distribution Channel:
Cold chain requirements and counterfeiting risks shape channel economics across temperature-sensitive formulations.
- Direct Sales:Manufacturer-to-physician relationships control product authenticity and enable training program bundling. AbbVie and Galderma field organizations dominate this channel.
- Online Sales:E-commerce penetration remains constrained by temperature validation and prescription requirements. Health Canada and FDA import enforcement limits gray market volume.
- Retail Pharmacies:Compounding pharmacy partnerships serve custom formulation niches outside standard cleared indications. Regulatory exposure concentrates in state-level pharmacy board jurisdictions.
- Distributors:Regional medical device distributors extend reach into underserviced Canadian provinces and US secondary markets. Inventory carrying costs compress margins for smaller manufacturers.
Channel control concentrates through Direct Sales; geographic coverage expansion depends on Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Devices and Radiological Health anchors the regulatory framework for the United States, while Health Canada Medical Devices Bureau imposes parallel licensing requirements that filter market entry. Metropolitan corridor concentration across California, Texas, and Florida absorbs disproportionate procedure volume due to disposable income density and celebrity culture proximity.
United States
California, Texas, and Florida dominate procedural volume through dermatology clinic clustering in Los Angeles, Miami, and Dallas-Fort Worth. FDA 510(k) clearance pathways for hyaluronic acid modifications shorten development cycles for line extensions. Arizona, Colorado, and Nevada have expanded nurse practitioner and physician assistant injection authority, redistributing patient flow toward non-physician providers.
Canada
Ontario and British Columbia exhibit the highest procedure density per capita, driven by Toronto and Vancouver metropolitan demand. Health Canada licensing timelines delay market entry by 18-24 months post-US approval, filtering smaller manufacturers. Quebec and Atlantic Canada remain underpenetrated, with French-language training programs and provincial billing code expansion unlocking provider base growth.
Mexico
Mexico City Metro concentrates aesthetic procedure demand among affluent demographics seeking cost-advantaged alternatives to US pricing. The country's national pharmaceutical regulator maintains device registration requirements that parallel FDA standards without full equivalency recognition. Nuevo León and Jalisco host emerging medical tourism corridors serving cross-border patients from Texas and California.
North America Dermal Fillers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the North America dermal fillers landscape. The upper tier controls distribution through direct physician channels and field organizations that bundle training programs with product supply. Below this, mid-scale specialists concentrate on ultrasound-compatible formulations or biostimulatory categories. Competitive moves center on portfolio diversification across hyaluronic acid and poly-L-lactic acid segments, plus geographic expansion into underpenetrated Canadian provinces.
Among integrated multinational players, AbbVie Inc. and Galderma occupy positions exemplifying the direct-channel archetype with broad portfolio coverage. Merz Pharma represents the specialist tier focused on differentiated formulation technologies. These three entities anchor the competitive structure through their respective control of physician relationships, cross-category presence, and ultrasound-guided placement protocols.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Galderma |
| Merz Pharma |
| Revance Therapeutics Inc. |
| Suneva Medical |
| Prollenium Medical Technologies |
| Sinclair Pharma |
| Teoxane Laboratories |
| Croma-Pharma |
| Others |
Value Network & Pricing Analysis
Direct-to-physician distribution contracts lock in multi-year supply commitments for hyaluronic acid filler manufacturers while anchoring price visibility against raw material volatility. These arrangements concentrate procurement power among integrated players with validated cold chain infrastructure, compressing margin flexibility for mid-scale competitors in California, Texas, and Florida corridor markets.
Pricing Analysis
Long-term offtake agreements between manufacturers and dermatology clinic networks dominate procurement, substituting spot-market exposure with predictable unit economics. Pricing stratifies across premium, standard, and economy tiers based on cross-linker concentration and ultrasound compatibility certification. Cost compression in standard-tier hyaluronic acid segments is intensifying because BDDE input concentration among three chemical suppliers limits negotiation leverage. Medical spa chains exhibit highest price sensitivity due to subscription maintenance program economics, while celebrity-adjacent Los Angeles and Miami clinics absorb premium-tier markups with minimal volume elasticity.
Supply Chain Analysis
Cold chain inventory requirements enforce 48-72 hour lead time constraints from manufacturing through clinic delivery, degrading product performance when temperature validation fails. Pharmaceutical-grade hyaluronic acid fermentation draws from South Korean and Chinese biotech suppliers, while BDDE cross-linker production rests on German and Japanese chemical manufacturers. Single-source vulnerability concentrates in BDDE inputs where pharmaceutical-grade specification limits qualified suppliers. Distribution runs through manufacturer field organizations bundled with training certification programs, bypassing third-party logistics for temperature-sensitive final-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through FDA PMA and 510(k) clearance pathways constructs formidable defensive moats, as clinical evidence requirements and quality system investments filter sub-scale entrants from sustained market participation.
For Market Incumbents: Secure exclusive injector training partnerships with expanding nurse practitioner scope-of-practice states including Arizona, Colorado, and Nevada. Deepen backward integration into BDDE cross-linker supply through strategic chemical manufacturer alliances, neutralizing raw material concentration risk that threatens formulation margins. For New Entrants and Emerging Players: Anchor in Quebec and Atlantic Canada provinces where French-language training gaps and delayed Health Canada licensing have suppressed competitive density. Target ultrasound-guided placement protocol certification as the most penetrable differentiation vector, leveraging real-time visualization technology adoption in high-end dermatology practices. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale specialists with Health Canada regulatory infrastructure already established, capturing 18-24 month acceleration advantage over US-only manufacturers seeking Canadian expansion. Watch state-level scope-of-practice liberalization velocity as inflection indicator for addressable provider base expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Streamlined predicate device comparisons shorten hyaluronic acid line extension timelines versus full PMA submissions. |
| Ultrasound-Guided Placement Training | Real-time visualization certification differentiates service tiers and reduces vascular occlusion liability exposure. |
| Subscription Maintenance Program Launch | Annual touch-up bundling captures predictable cash flow and locks patient relationships against medspa competition. |
| Health Canada Licensing Investment | Parallel submission capability unlocks Ontario and British Columbia procedure density ahead of US-only competitors. |
| BDDE Supplier Alliance Formation | Long-term offtake agreements with German and Japanese chemical manufacturers neutralize raw material price volatility. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with board-certified dermatologists, nurse practitioner injectors, medical spa operators, and manufacturer regulatory affairs directors. Secondary validation drew from FDA 510(k) and PMA filings, Health Canada Medical Devices Bureau licensing records, state scope-of-practice legislative databases, and GPO procurement contracts. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data across the analysis window.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmented demand curves by product type, application anatomy, end-user facility category, and distribution channel. CAGRs were derived from regression analysis against demographic penetration rates and disposable income elasticity. Forecast inputs incorporated social media platform engagement metrics as leading indicators for 25-34 year-old demographic entry, plus state-level scope-of-practice expansion timelines.
Material uncertainties — regulatory pathway delays, BDDE supply disruptions, and adverse event cluster responses — sit outside the modeled envelope. Forecasts reflect documented assumptions about licensed injector availability growth and Health Canada licensing timeline convergence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Breast Reconstruction and Augmentation Market
Medical Aesthetics
Lip Augmentation Market
Medical Aesthetics
Hair Transplant Market
Medical Aesthetics
Japan Hair Transplant Market
Medical Aesthetics
Europe Medical Aesthetic Devices Market
Medical Aesthetics
Germany Facial Aesthetics Market
Medical Aesthetics
Japan Laser Hair Removal Market
Medical Aesthetics
China Hair Transplant Market
Medical Aesthetics
Global Medical Aesthetic Devices Market
Medical Aesthetics
Medical Aesthetics Market
Medical Aesthetics
Cosmetic Threads Market
Medical Aesthetics
Facial Injectables Market
Medical Aesthetics
Photoelectric Medical Beauty Equipment Market
Medical Aesthetics
Lip Filler Market
Medical Aesthetics
Cosmetic Laser Market
Medical Aesthetics
Gum Lift Market