
 Gold Kiwifruit Market | 2026-2036
Gold Kiwifruit Market Size, Share, and Industry Trends Forecast 2026-2036
Gold Kiwifruit Market Analytics
New Zealand's controlled-release SunGold licensing program is expanding faster than any competing varietal pipeline. Zespri Group Limited leverages its proprietary G3 and G9 cultivar rights to dominate premium export channels. Dole plc anchors North American retail distribution through long-term supermarket contracts. Seeka Kiwifruit Industries Limited sustains contract growing and post-harvest infrastructure across the Bay of Plenty and Te Puke regions.
Gold kiwifruit denotes the Actinidia chinensis species with yellow flesh, characterized by higher vitamin C content and lower acidity than green-fleshed Hayward varieties, typically harvested at soluble solids concentrations above 6.5 degrees Brix for optimal storage life. Fresh product type occupies the dominant value share due to per-unit premiums and shorter supply chains, while juiced and puree segments compete for processor offtake from grade-B and surplus fruit. Specialty store distribution channels lead margin capture in urban centers, though supermarket volume locks in producer cash flow predictability.
New Zealand's Ministry for Primary Industries enforces strict phytosanitary export standards under the Kiwifruit Export Regulations, while China's SAMR and GB food safety standards govern import inspection and domestic retail labeling. The EU's MDR and food contact material rules shape packaging compliance for European-bound shipments. Stakeholders must monitor cultivar patent expiration timelines and regional planting right disputes to anticipate supply redistribution.
Market Dynamics
Proprietary cultivar licensing regimes are compressing supply elasticity across the gold kiwifruit value chain, concentrating varietal control within tightly held intellectual property frameworks that reshape competitive entry economics.
Growth Catalysts
- Provincial Agricultural Modernization:China's Sichuan and Shaanxi provinces deploy state-directed capital into protected cultivation infrastructure, accelerating domestic planting scale under centralized planning frameworks.
- Vitamin C Positioning:Functional food demand from health-conscious retail segments pulls yellow-fleshed varieties ahead of commodity green cultivars in premium produce aisles.
- Phytosanitary Harmonization:New Zealand's MPI export certification alignment with China's GB food safety standards reduces border inspection friction and accelerates customs clearance velocity.
Market Restraints
- Input Cost Volatility:Pollination-dependent orchard economics face acute vulnerability to honeybee colony health fluctuations and contracted hive rental rate spikes.
- Supply Concentration Risk:Zespri's controlled-release G3 and G9 licensing creates single-point varietal dependency for premium export volume, constraining producer switching options.
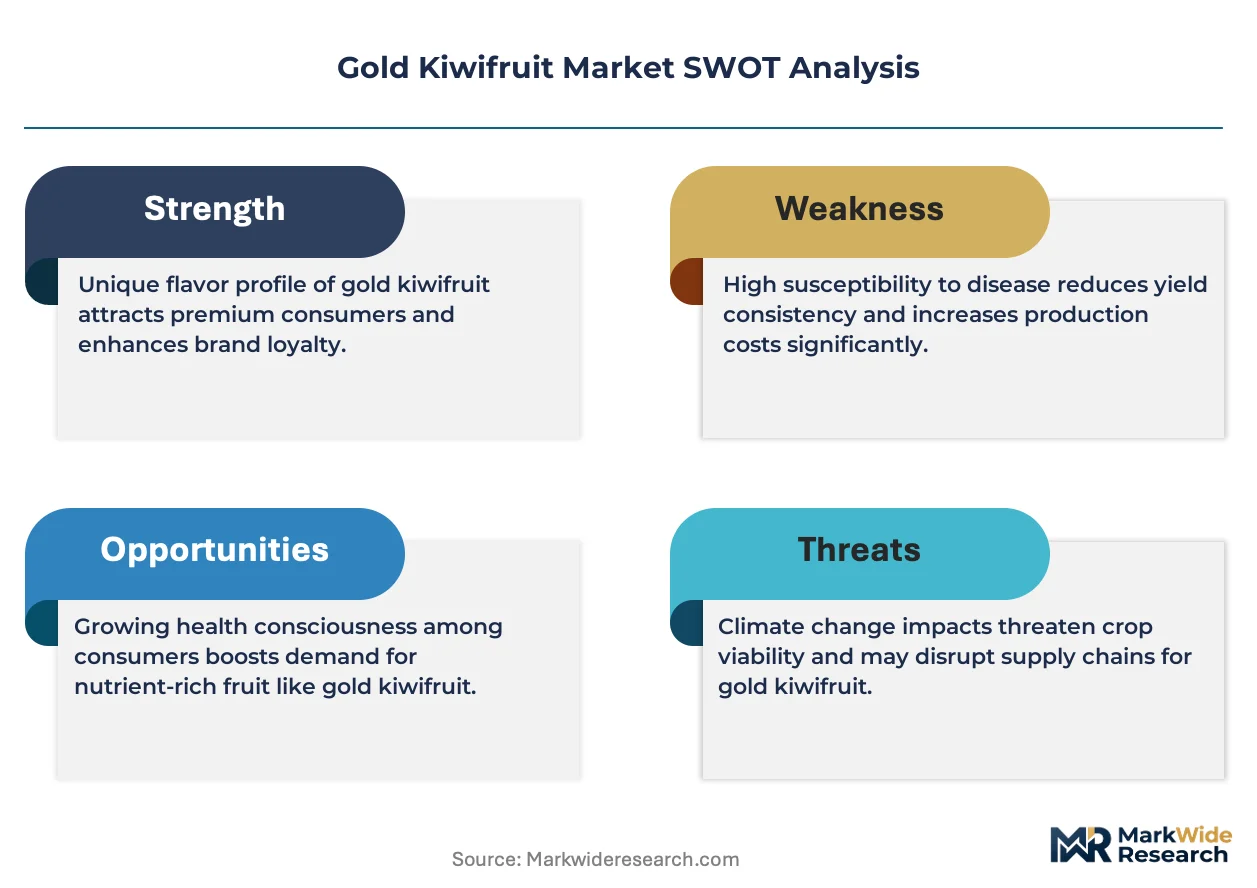
- Technical Limitation:Psa bacterial canker susceptibility in susceptible cultivar lines forces continuous breeding investment and protected structure capital deployment.
Strategic Opportunities
- Underpenetrated Geography:India's organized retail fresh fruit infrastructure remains nascent, creating first-mover positioning for branded premium kiwifruit introductions.
- Emerging Application:Freeze-dried snack and nutraceutical extract channels absorb grade-B fruit offtake, diversifying processor revenue streams beyond bulk juice concentrate.
- Regulatory Tailwind:China's dual carbon goals accelerate provincial subsidies for solar-powered cold storage and renewable-powered controlled atmosphere facilities.
Industry Challenges
- Cultivar Patent Complexity:Expiring PVR protections and overlapping regional planting right claims generate litigation exposure across multiple jurisdictions.
- Post-Harvest Skill Scarcity:Mastery of ethylene management and controlled atmosphere protocols for long-haul shipping remains concentrated among experienced Te Puke technicians.
- Capex Intensity:Orchard conversion to protected structures and automated sorting infrastructure demands sustained capital commitment across multi-year development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gold Kiwifruit Market |
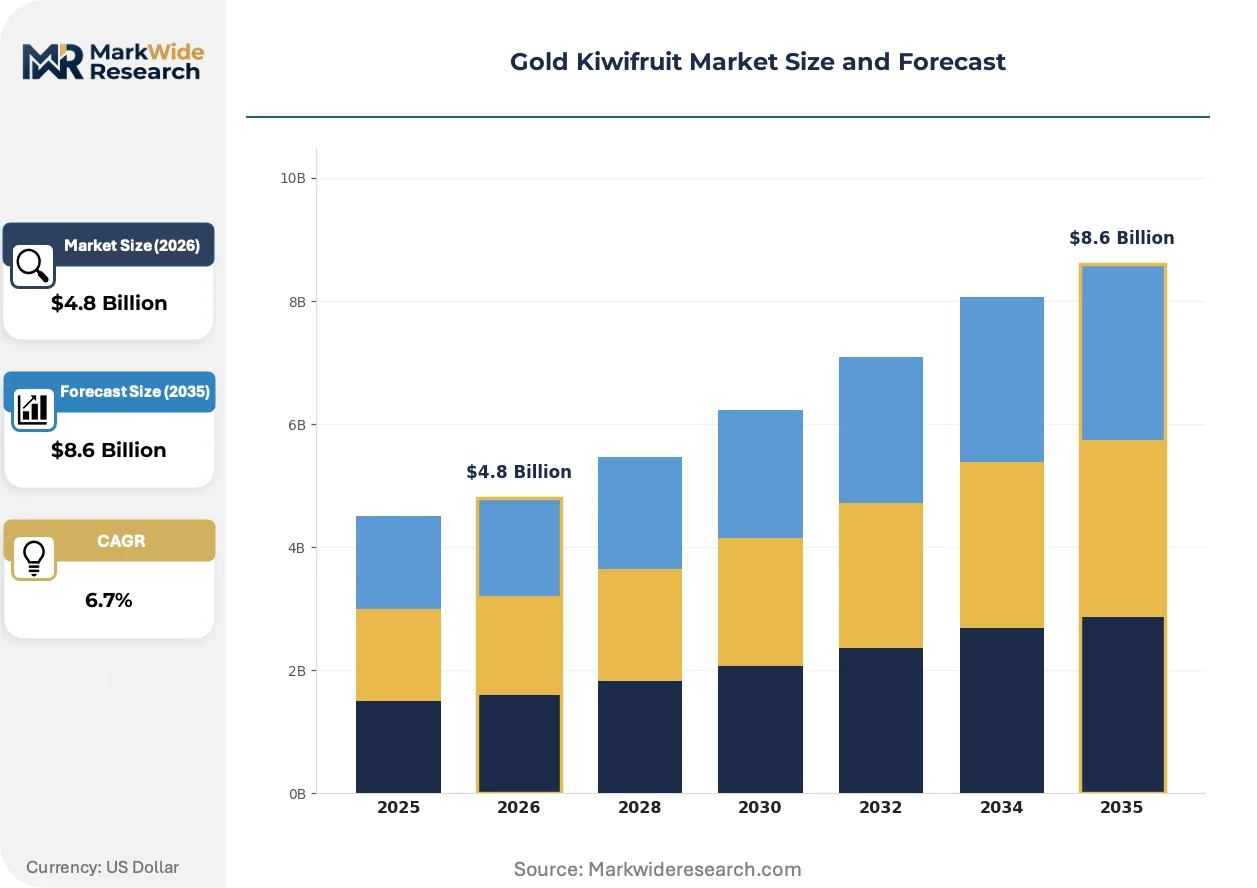
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Dried, Juiced, Puree Distribution Channel: Online, Supermarket, Hypermarket, Specialty Store End User: Food Service, Retail, Exporters, Processors Packaging Type: Plastic Containers, Cardboard Boxes, Bulk Packaging, Pouches |
| Companies Covered | Zespri Group Limited, Dole plc, Del Monte Fresh Produce N.A. Inc., Seeka Kiwifruit Industries Limited, Apata Group Limited, DMS Progrowers Limited, Eastpack Limited, Calavo Growers Inc., Chiquita Brands International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gold Kiwifruit Market Evolving Landscape
Biological crop protection and precision orchard management systems are displacing conventional chemical input regimes, while digital traceability platforms reshape buyer-producer information asymmetry.
Robotic pollination systems using electrostatic pollen application are overtaking traditional honeybee dependency in high-labor-cost growing regions. New Zealand's Bay of Plenty operators pilot autonomous pollinator drones to compress flowering-window labor requirements. This mechanization is overtaking seasonal migrant worker programs as the dominant pollination modality for scale orchards.
China's SAMR enforcement of stricter pesticide maximum residue limits under revised GB standards forces exporter protocol adjustments. New Zealand MPI certification documentation now requires expanded metabolite testing panels for China-bound shipments. European-bound fruit faces parallel pressure from EU Green Deal farm-to-fork pesticide reduction targets.
Direct-to-retailer procurement contracts are displacing traditional wholesaler intermediation in urban Chinese distribution. Supermarket chains in Shanghai and Beijing negotiate exclusive varietal access with licensed growers, compressing margin capture by legacy import agents. This channel consolidation concentrates volume commitment risk with fewer buyer entities.
Gold Kiwifruit Market Segmentation
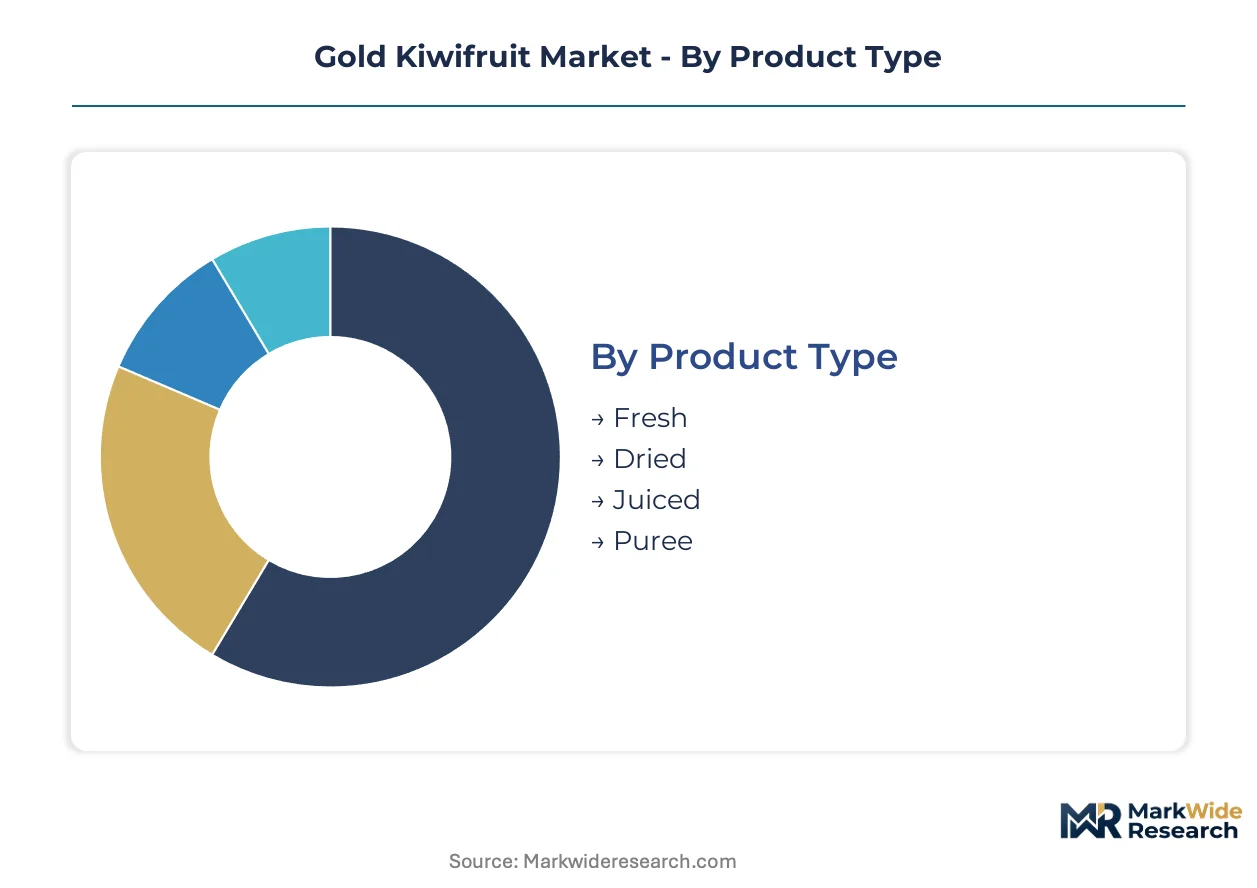
Segmentation in gold kiwifruit markets reveals how value capture diverges across handling intensity, channel control, and buyer sophistication. Each dimension exposes distinct margin structures and capital requirements.
Product Type:
Upgrade cycles from commodity green varieties to premium yellow-fleshed cultivars reshape volume allocation across processing tiers.
- Fresh:Whole fruit sold at soluble solids above 6.5 degrees Brix commands per-unit premiums through shorter supply chains. Retail consumers in China's tier-one cities absorb dominant import volume, pulled by vitamin C positioning and lower acidity profiles.
- Juiced:Grade-B and surplus fruit diversion into single-strength and concentrate formats competes for processor offtake. Exporters in New Zealand's Bay of Plenty region anchor bulk shipment contracts to Asian beverage manufacturers.
- Dried:Slice and whole-fruit dehydration extends shelf life for snack channels with reduced cold chain dependency.
- Puree:Aseptic and frozen formats serve ingredient demand from bakery and dairy applications.
Fresh sits at the top of the volume ranking, with Juiced climbing the fastest.
Distribution Channel:
Cost tier stratification separates capital-light digital entrants from infrastructure-heavy physical retail networks.
- Specialty Store:Urban produce boutiques in Shanghai and Beijing negotiate exclusive varietal access, capturing margin through curated assortment and provenance storytelling. Direct procurement contracts displace legacy import agents, concentrating volume commitment risk with fewer buyer entities.
- Supermarket:Long-term produce supply agreements lock in cash flow predictability for licensed growers. Dole plc anchors North American retail distribution through multi-year category management contracts.
- Hypermarket:High-volume, low-margin throughput demands standardized grading and palletized logistics.
- Online:E-commerce fresh produce platforms require last-mile cold chain investment and impulse-purchase packaging redesign.
Supermarket channels dominate volume throughput, with Specialty Store expanding most quickly.
End User:
Application maturity separates established retail consumption from emerging food service integration.
- Retail:Health-conscious household purchasing drives premium varietal uptake through branded packaging and portion-controlled formats. China's SAMR labeling enforcement shapes domestic retail presentation standards.
- Food Service:Restaurant and hospitality procurement emphasizes consistent sizing and plate-ready presentation. Processors in Sichuan province scale protected cultivation to serve centralized kitchen demand.
- Exporters:Licensed growers under Zespri's controlled-release program serve phytosanitary-compliant shipment protocols.
- Processors:Nutraceutical extract and freeze-dried snack manufacturers absorb grade-B fruit offtake, diversifying revenue beyond bulk juice concentrate.
Retail commands the value share, with Food Service gaining share fastest.
Packaging Type:
Supply concentration in corrugated and flexible formats reflects downstream customer scale and handling automation.
- Cardboard Boxes:Standardized export cartons with ventilation apertures dominate long-haul ocean freight. EU MDR food contact material rules govern European-bound shipment compliance.
- Plastic Containers:Clamshell and rigid formats serve retail-ready presentation with reduced bruising incidence.
- Bulk Packaging:Bin and tote systems optimize processor intake efficiency at receiving facilities.
- Pouches:Flexible retail formats target convenience-oriented single-serve consumption occasions.
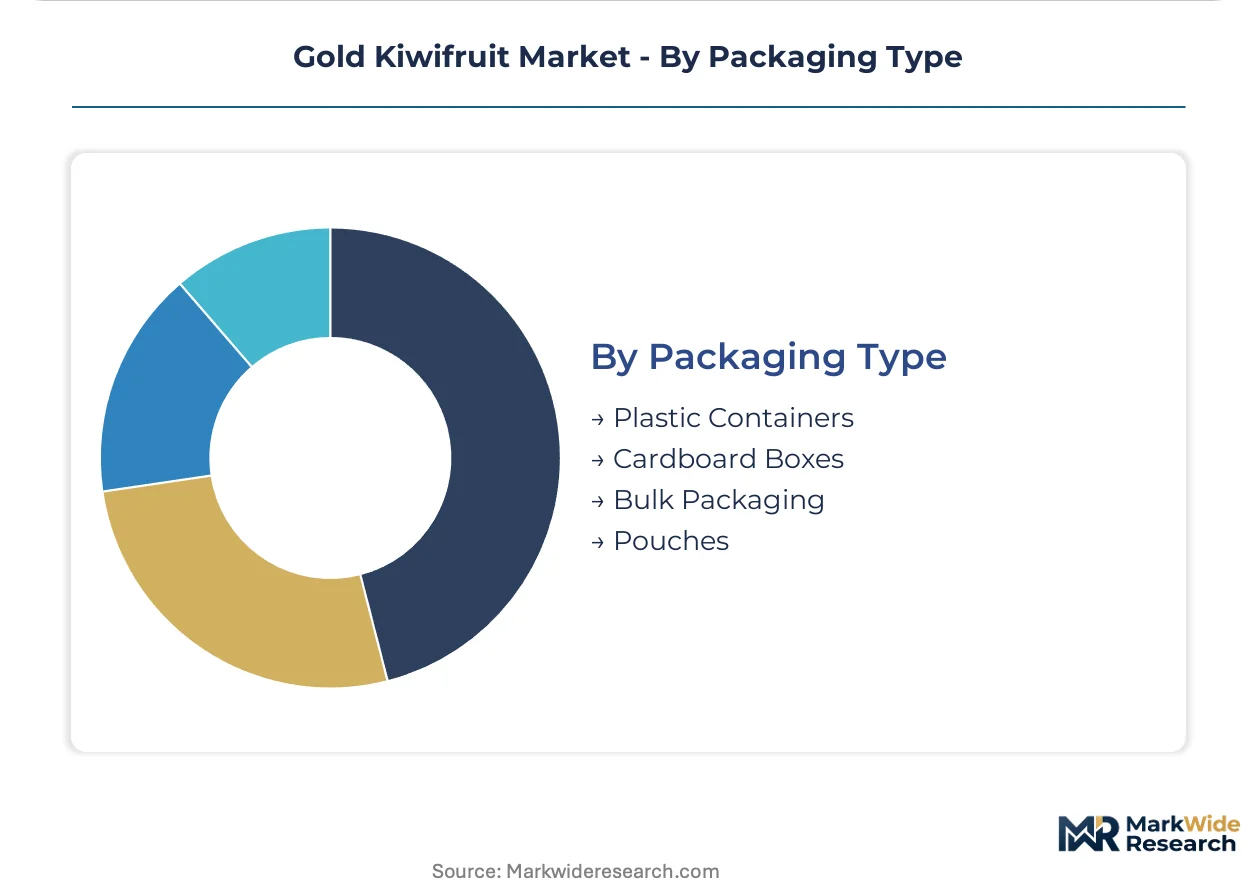
Cardboard Boxes sit at the top of the volume ranking, with Plastic Containers climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand's export licensing system generates premium capture that Chinese domestic plantings struggle to replicate, while European and North American markets absorb differentiated varietal access through distinct regulatory pathways.
New Zealand
Zespri's controlled-release G3 and G9 programs concentrate varietal control within the Bay of Plenty and Te Puke orchard clusters. New Zealand's Ministry for Primary Industries enforces phytosanitary certification under Kiwifruit Export Regulations that align with destination market protocols. Te Puke technicians maintain concentrated expertise in ethylene management and controlled atmosphere protocols for long-haul shipment.
China
Sichuan and Shaanxi provinces scale protected cultivation infrastructure under state-directed agricultural modernization capital deployment. China's SAMR enforces revised GB food safety standards with expanded pesticide metabolite testing panels for import inspection. Shanghai and Beijing supermarket chains negotiate direct procurement contracts that displace legacy import agent intermediation.
United States
Health-conscious retail consumers in California and Northeast corridor markets absorb premium yellow-fleshed varieties through branded produce programs. The USDA and FDA jointly oversee import phytosanitary compliance and fresh produce safety protocols. Dole plc anchors North American retail distribution through multi-year category management contracts with national supermarket chains.
European Union
German and Dutch wholesale distribution hubs channel premium kiwifruit into retail networks across Northern Europe. The EU's MDR food contact material rules and Green Deal farm-to-fork pesticide reduction targets shape packaging and residue compliance requirements. Italian and Spanish Mediterranean ports serve as entry points for Southern European market penetration.
India
Organized retail fresh fruit infrastructure in Mumbai and Delhi remains nascent, creating positioning opportunities for branded premium introductions. The Food Safety and Standards Authority of India governs import labeling and maximum residue limits under FSSAI standards. Maharashtra and Karnataka states demonstrate early protected cultivation adoption for domestic kiwifruit production scaling.
Gold Kiwifruit Market Competitive Landscape
New Zealand producers anchor the premium-tier licensing system; multinational fresh produce specialists hold volume distribution across North American and European retail channels. Market structure concentrates varietal control within tightly held intellectual property frameworks while fragmenting downstream logistics and retail execution. Two strategic archetypes dominate: proprietary cultivar licensors with breeding program depth, and integrated produce marketers with supermarket contract scale. Competitive moves center on controlled-release licensing expansion and direct-to-retailer procurement contract negotiation.
Within the proprietary cultivar tier, Zespri Group Limited and Seeka Kiwifruit Industries Limited exemplify the New Zealand-based licensing and contract growing model. Among multinational produce marketers, Dole plc occupies a position representing integrated retail distribution capability. These three entities anchor distinct competitive vectors: varietal control, domestic infrastructure, and global channel access.
| Leading Market Players |
|---|
| Zespri Group Limited |
| Dole plc |
| Del Monte Fresh Produce N.A. Inc. |
| Seeka Kiwifruit Industries Limited |
| Apata Group Limited |
| DMS Progrowers Limited |
| Eastpack Limited |
| Calavo Growers Inc. |
| Chiquita Brands International Inc. |
| Others |
Value Network & Pricing Analysis
Honeybee hive rental rate indices cascade through pollination-dependent orchard economics into tiered fruit grading premiums, compressing margins at the grower level while concentrating pricing power with licensed cultivar holders and direct-procurement retail chains.
Pricing Analysis
Retailer markup layers dominate final shelf price architecture, with direct-to-retailer procurement contracts in Shanghai and Beijing eliminating legacy import agent margins. Three-tier pricing structure across premium export-grade, domestic protected-cultivation, and commodity processor-intake levels separates Zespri-licensed SunGold from Sichuan greenhouse production and grade-B juice concentrate feedstock. Pricing pressure stems from rapid domestic planting scale-up in Shaanxi and Sichuan provinces under state subsidy programs. Food service buyers exhibit highest price sensitivity due to standardized sizing requirements and plate-ready presentation costs, while specialty store channels absorb premium positioning with lowest elasticity.
Supply Chain Analysis
Grade-B and surplus fruit flows into processor offtake channels, with aseptic puree and freeze-dried snack manufacturing creating circular revenue streams from otherwise discarded inventory. Geographic supply concentrates in New Zealand's Bay of Plenty, China's Sichuan and Shaanxi provinces, and Italy's Emilia-Romagna kiwifruit districts. Input dependencies rest on honeybee pollination services, controlled atmosphere cold storage infrastructure, and proprietary G3/G9 cultivar licensing. Single-source vulnerability runs through Zespri's intellectual property control over premium yellow-fleshed genetics. Distribution runs through direct supermarket chain procurement in tier-one Chinese cities, long-term category management contracts with North American retailers, and wholesale auction platforms at European entry ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gold kiwifruit market compounds steadily through health-conscious retail demand pull and proprietary cultivar scarcity economics that sustain premium capture across multi-year orchard development cycles.
For Market Incumbents: Extend controlled-release licensing coverage into emerging protected-cultivation regions before patent cliff exposure materializes. Deepen backward integration into pollination service provision to hedge honeybee colony health volatility. Fortify direct-to-retailer procurement relationships in China's tier-one cities against domestic planting scale-up threats.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in India's nascent organized retail infrastructure offers first-mover positioning for branded yellow-fleshed introductions. Target Maharashtra and Karnataka state greenhouse development zones with technical partnership models that transfer protected cultivation expertise. Pursue freeze-dried snack and nutraceutical extract channels to absorb grade-B fruit offtake without competing for fresh export licensing access.
For Investors and Strategic Acquirers: Asymmetric upside sits with contract growing and post-harvest infrastructure operators in New Zealand's Te Puke region who capture tolling revenue regardless of cultivar patent ownership transitions. Five-to-ten year viability hinges on ethylene management technical concentration and controlled atmosphere protocol mastery that resists rapid replication. Monitor provincial agricultural modernization capital deployment rates in Sichuan and Shaanxi as inflection signals for supply redistribution timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Cultivar Licensing Expansion | Zespri's controlled-release G3/G9 programs tighten intellectual property control over premium export volume. |
| Protected Cultivation Scale-Up | Sichuan and Shaanxi provincial subsidies accelerate domestic planting under centralized agricultural modernization frameworks. |
| Direct-to-Retailer Procurement | Shanghai and Beijing supermarket chains displace legacy import agents through exclusive varietal access negotiations. |
| Robotic Pollination Deployment | Bay of Plenty operators pilot autonomous drones to compress flowering-window labor requirements and reduce honeybee dependency. |
| Grade-B Value Recovery | Freeze-dried snack and nutraceutical extract channels diversify processor revenue beyond bulk juice concentrate offtake. |
Research Methodology
Bottom-up retail consumption modeling reconciled against top-down orchard planting and export volume tracking forms the analytical core of this study. Primary interviews with licensed growers, post-harvest facility operators, supermarket category buyers, and MPI phytosanitary certification officers combined with secondary validation from New Zealand Kiwifruit Export Regulations documentation, China's SAMR GB standards filings, EU MDR food contact material compliance records, and Bay of Plenty regional trade statistics. Triangulation across supply-side capacity assessments and demand-side channel audits ensures dimensional consistency.
Input-output matrices map cultivar licensing releases, protected cultivation capital deployment, and retail channel procurement contract velocity against consumption projections across the analysis window. Segmentation dimensions span product type, distribution channel, end user, and packaging format, with regional regulatory cluster and phytosanitary protocol alignment as cross-cutting variables. CAGRs derive from orchard maturation curves, licensing expansion schedules, and provincial agricultural modernization investment trajectories rather than extrapolated historical trends.
Caveats apply where Psa bacterial canker outbreaks, honeybee colony collapse events, or cultivar patent litigation rulings could materially shift the outlook. Forecasts embed assumptions regarding phytosanitary harmonization continuity and provincial subsidy program persistence. Practitioners should monitor MPI-SAMR protocol alignment negotiations and Sichuan greenhouse development permit issuance rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Europe Freeze-Dried Fruits and Vegetable Market
Fruits and Vegetables
Guanabana Market
Fruits and Vegetables
Global Hass Avocado Market
Fruits and Vegetables
Frozen Fruits Market
Fruits and Vegetables
Vietnam Fruits and Vegetables Market
Fruits and Vegetables
Sudachi Market
Fruits and Vegetables
Goji Berries Market
Fruits and Vegetables
Global Fresh Berries Market
Fruits and Vegetables
Avocado Puree Market
Fruits and Vegetables
United Arab Emirates Fruits and Vegetables Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market
Fruits and Vegetables
North Africa Table Olives Market
Fruits and Vegetables
Oman Fruits and Vegetables Market
Fruits and Vegetables
Button Mushroom Products Market
Fruits and Vegetables
Peach Extract Market
Fruits and Vegetables
Fruit Puree Market