
 Arecanut Market | 2026-2036
Arecanut Market Size, Share, and Industry Trends Forecast 2026-2036
Arecanut Market Analysis
Pan masala manufacturers and pharmaceutical extractors are redrawing procurement priorities for arecanut raw material. The Campco Ltd. anchors its position through cooperative sourcing networks across India's Western Ghats growing belt. Vietdelta Industrial Co., Ltd competes on export-grade processing capacity serving Southeast Asian buyers. GM Group leverages backward integration into plantation operations to secure consistent fiber and alkaloid specifications.
Arecanut comprises the dried seed kernel of Areca catechu palm, typically containing percent moisture, tannins, and arecoline alkaloids used in chewing preparations and pharmaceutical extraction. The kernel undergoes sun-drying or boiling followed by curing to achieve commercial hardness and shelf stability. Whole Arecanut dominates export logistics due to lower spoilage rates during ocean freight, while Arecanut Powder is gaining traction in cosmetic formulations for its astringent properties. Premium Grade lots command concentrated margin pools in Middle Eastern and European specialty channels where phytosanitary certification requirements exclude standard grades.
India's FSSAI mandates maximum permissible limits for aflatoxin contamination in edible arecanut, while the country's Agricultural and Processed Food Products Export Development Authority enforces destination-country phytosanitary protocols. The EU's REACH framework and EFSA novel food assessments constrain direct arecanut entry into European food applications, redirecting volumes toward cosmetic and industrial extract channels. Stakeholders must monitor alkaloid standardization capabilities and certification breadth to determine which quality tiers justify capacity expansion versus spot-market trading.
Market Dynamics
Pharmaceutical extraction demand is restructuring procurement hierarchies, as alkaloid standardization requirements filter backward through supply chains and compress spot-market margins for uncertified grades.
Growth Catalysts
- Alkaloid extraction protocols:Pharmaceutical manufacturers are expanding offtake of arecoline derivatives for therapeutic compound development. This pulls higher-grade kernel specifications into contract farming arrangements.
- FSSAI traceability mandates:India's tightening aflatoxin limits and batch-tracking requirements are accelerating investment in curing-yard digitization and testing infrastructure across Karnataka processing clusters.
- Cosmetic astringent applications:Powdered arecanut tannins are penetrating skincare formulations in Middle Eastern and European specialty channels, diversifying revenue streams beyond traditional chewing-product buyers.
Market Restraints
- Monsoon-dependent supply:Karnataka's concentrated processing capacity exposes volume stability to Western Ghats rainfall variability, creating inter-year price volatility that contract buyers must hedge.
- EU regulatory friction:REACH registration requirements and EFSA novel food assessments block direct food-grade entry, forcing exporters toward lower-margin cosmetic and industrial extract channels.
- Synthetic alkaloid substitution:Laboratory-produced arecoline analogues are displacing botanical extraction in some pharmaceutical applications, compressing premium-grade kernel premiums.
Strategic Opportunities
- Vietnamese processing expansion:Vietdelta Industrial's export-grade infrastructure creates template for Southeast Asian buyers to reduce India-dependency through regional sourcing.
- PLI scheme alignment:India's production-linked incentive frameworks for agricultural processing could subsidize alkaloid extraction facility upgrades if eligibility criteria expand.
- Direct-to-cosmetic channel development:Bypassing traditional pan masala intermediaries to supply European formulators with certified cosmetic-grade powder commands 40-60% price premiums over standard export lots.
Industry Challenges
- Alkaloid standardization expertise:Pharmaceutical contract specifications require chromatographic purity verification capabilities that few curing-yard operators possess, creating bottleneck for grade escalation.
- Phytosanitary certification timelines:Agricultural and Processed Food Products Export Development Authority documentation for EU-bound shipments averages 6-8 weeks, compressing working capital cycles for smaller exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arecanut Market |
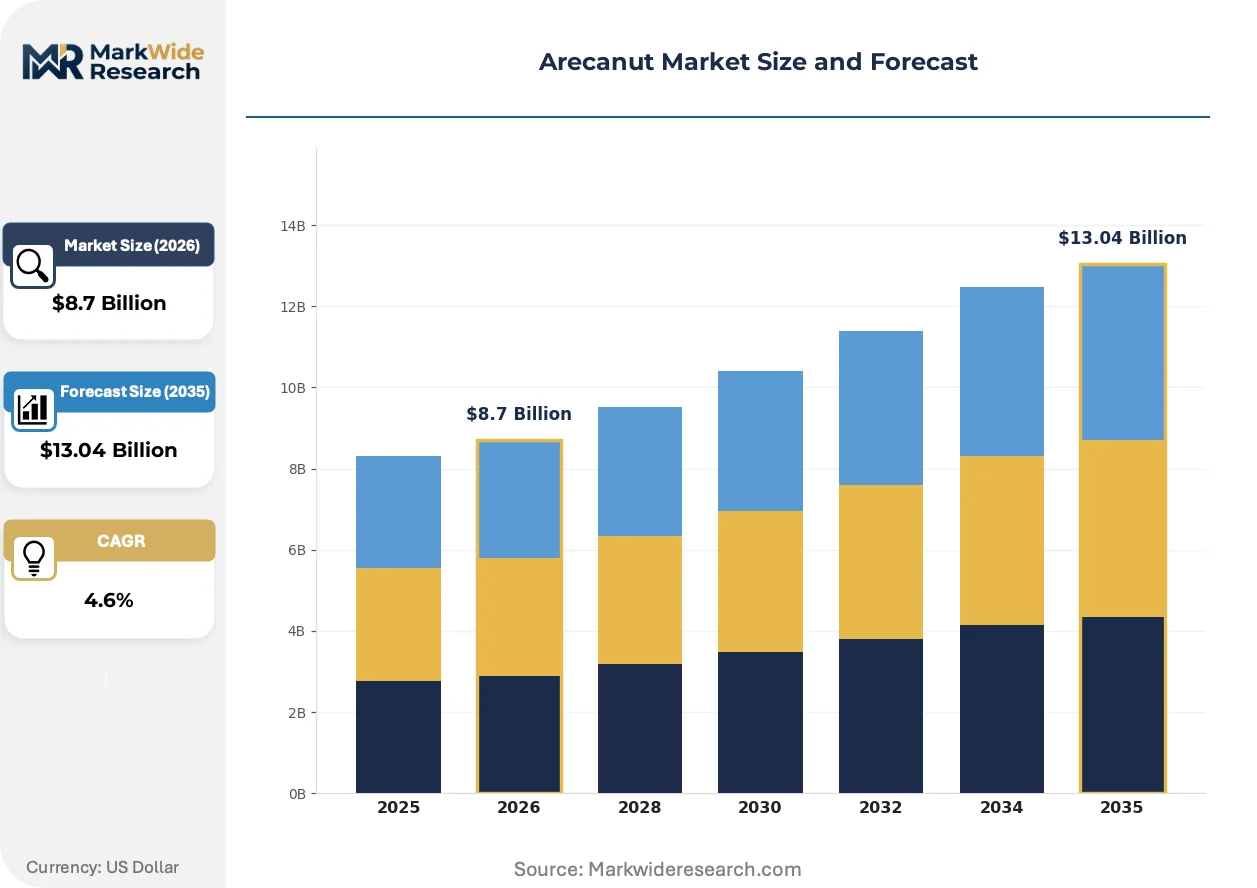
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Arecanut, Split Arecanut, Arecanut Powder, Arecanut Oil End User: Food Industry, Cosmetic Industry, Pharmaceutical Sector, Traditional Medicine Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Markets Quality Grade: Premium Grade, Standard Grade, Organic Grade, Export Quality |
| Companies Covered | Pt. Ruby Privatindo, Shri Ganesh Prasad Traders, The Campco Ltd., GM Mallikarjunappa & Son's, Vietdelta Industrial Co., Ltd, GM Group, Swastika International, R. K. Trading, Sri Vinayaka Betelnut Traders, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arecanut Market Emerging Trajectories
Solvent-free extraction methods and blockchain-based provenance tracking are converging to reshape quality verification and buyer-seller contracting protocols across the value chain.
Supercritical CO2 extraction technology is decomposing traditional solvent-based alkaloid recovery processes. European pharmaceutical extractors are adopting these systems at pilot scale, attracted by residue-free output specifications. This compression of extraction purity standards is decomposing the historical premium attached to sun-dried kernel grades, as controlled processing parameters override raw material variability.
India's FSSAI is mandating blockchain-integrated batch tracking for export-grade edible arecanut, with full implementation timelines accelerating through 2025-2026. This policy shift forces curing-yard operators into digitization investments or wholesale-to-certified-processor exits. Karnataka's cooperative processing networks are consolidating fastest under this pressure, as compliance costs favor scale.
Cosmetic formulators in Dubai and Riyadh are specifying tannin concentration certificates ahead of visual grade assessment, reversing traditional procurement hierarchies. This certification-driven preference shift disrupts long-standing broker relationships that transacted on sample-based quality. Indian exporters with in-house HPLC testing capabilities are capturing this channel expansion, while legacy traders face margin compression.
Arecanut Market Segmentation
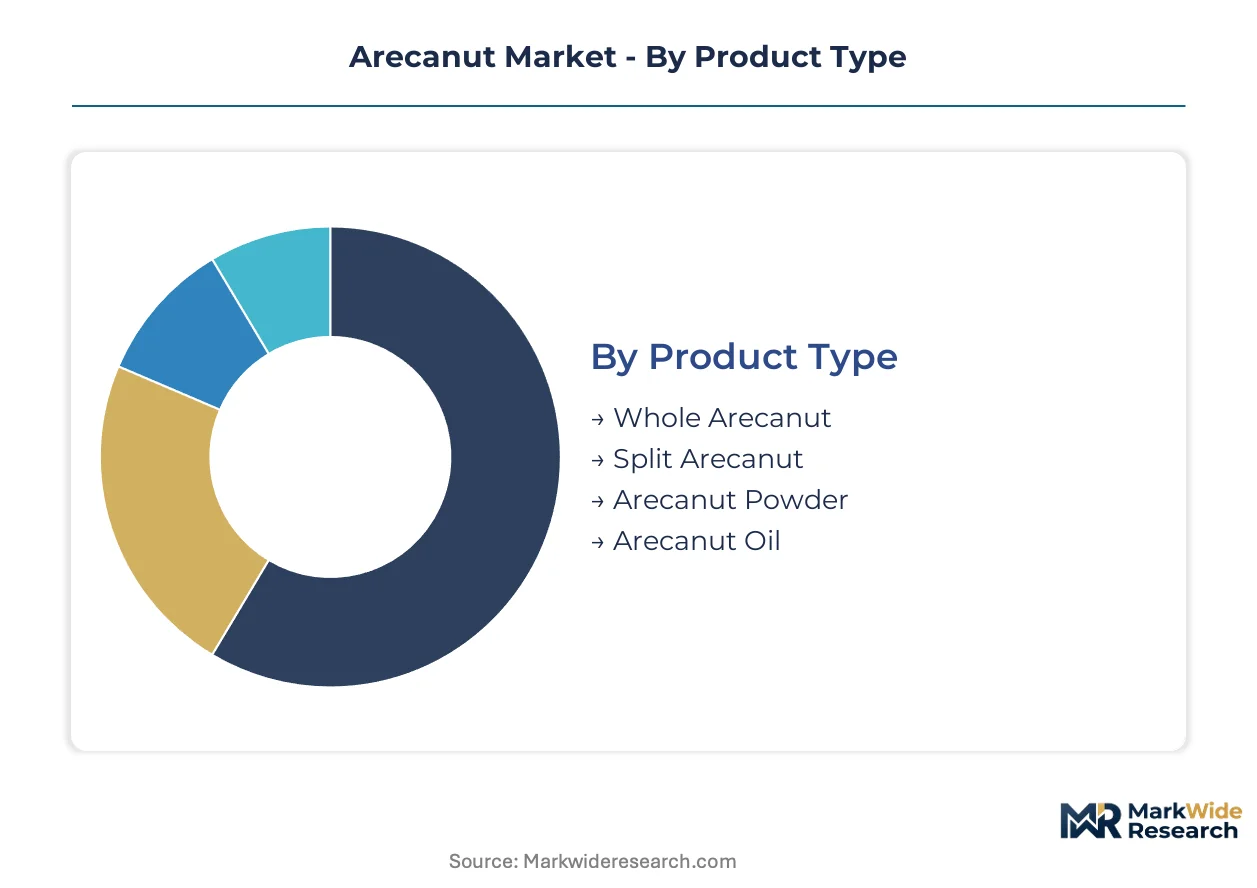
Channel configuration in the arecanut trade varies sharply by product form and buyer sophistication. Pharmaceutical extractors and cosmetic formulators impose certification requirements that reshape how segments flow through wholesale versus direct-contract pathways.
Product Type:
Whole kernel commands ocean freight logistics, while processed derivatives penetrate specialized downstream channels.
- Whole Arecanut:Sun-dried or boiled-then-cured kernels retain structural integrity for bulk shipment. Pan masala manufacturers in India, Pakistan, and Bangladesh source predominantly through Karnataka wholesale markets, with consignment terms reflecting moisture-content assays at destination.
- Arecanut Powder:Finely milled tannin-rich material serves cosmetic formulators in Dubai and Riyadh who specify HPLC-verified astringent concentration. Direct-to-formulator contracts bypass traditional broker networks, capturing 40-60% price premiums over standard export lots.
- Split Arecanut:Mechanically sectioned kernel accelerates alkaloid extraction throughput for pharmaceutical processors. Indian CDSCO-registered extractors favor this form for solvent-free supercritical CO2 processing.
- Arecanut Oil:Cold-pressed lipid fraction penetrates niche skincare applications in European specialty channels constrained by REACH registration requirements.
Whole Arecanut dominates installed base. Arecanut Powder is where expansion concentrates.
End User:
Regulatory jurisdiction fragments demand into distinct procurement protocols with incompatible certification requirements.
- Pharmaceutical Sector:Arecoline alkaloid extraction for therapeutic compound development requires chromatographic purity verification. European EMA-registered manufacturers specify supercritical CO2-compatible kernel grades, pulling supply into contract farming arrangements with backward-integrated processors.
- Cosmetic Industry:Tannin concentration certificates now precede visual quality assessment for Middle Eastern formulators. Indian exporters with in-house testing capabilities capture this channel while legacy traders face margin compression.
- Food Industry:India's FSSAI aflatoxin limits and batch-tracking mandates govern pan masala and supari applications, accelerating curing-yard digitization across Karnataka cooperative networks.
- Traditional Medicine:Ayurvedic and Unani practitioners in Kerala and Tamil Nadu procure through informal channels with minimal documentation, though this segment contracts under formalization pressure.
Food Industry retains volume leadership. Pharmaceutical Sector climbs the fastest as alkaloid standardization requirements escalate.
Distribution Channel:
Buyer scale and certification burden determine whether transactions flow through intermediaries or direct procurement.
- Wholesale Markets:Karnataka's Shimoga and Chikmagalur trading hubs aggregate smallholder output for domestic pan masala manufacturers. Spot pricing reflects visual grading and moisture content, with limited traceability documentation.
- Specialty Stores:Premium-grade whole kernel for Middle Eastern chewing-product consumers moves through Dubai and Riyadh retail channels with phytosanitary certification displayed at point of sale.
- Supermarkets:Packaged supari and pan masala kits reach Indian urban consumers through modern retail, with FSSAI-mandated blockchain batch codes on packaging.
- Online Retail:Direct-to-consumer powder sales for cosmetic DIY formulations emerge in European markets, though REACH compliance constraints limit food-grade listings.
Wholesale Markets handle the greatest throughput. Specialty Stores deliver the steepest margin expansion.
Quality Grade:
Certification breadth and testing infrastructure access stratify pricing tiers beyond traditional visual assessment.
- Premium Grade:Kernels meeting EU phytosanitary protocols and pharmaceutical alkaloid specifications command concentrated margin pools. European EFSA novel food assessments block direct food entry, redirecting volumes toward cosmetic and industrial extract channels.
- Export Quality:India's APEDA documentation for destination-country protocols averages 6-8 weeks, compressing working capital cycles for smaller exporters serving Southeast Asian buyers.
- Standard Grade:Domestic pan masala manufacturers absorb this tier through Karnataka cooperative sourcing networks, with FSSAI aflatoxin limits tightening acceptable contamination thresholds.
- Organic Grade:Certified cultivation for European cosmetic formulators remains nascent due to conversion-period economics and limited accredited acreage in India's Western Ghats.
Standard Grade covers the widest acreage. Premium Grade is where value capture is concentrating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India ships processed arecanut to Southeast Asian chewing-product manufacturers and European pharmaceutical extractors, with Karnataka's curing yards serving as the primary consolidation point for both export corridors.
India
Domestic pan masala manufacturers absorb the majority of standard-grade kernel through Karnataka's Shimoga and Chikmagalur wholesale markets. The FSSAI mandates blockchain-integrated batch tracking for export-grade edible arecanut, accelerating cooperative network consolidation. Campco Ltd.'s cooperative sourcing networks across the Western Ghats growing belt demonstrate how compliance investments favor scale.
Vietnam
Vietdelta Industrial Co., Ltd's export-grade infrastructure enables Southeast Asian buyers to reduce India-dependency through regional sourcing. The country's national agricultural processing regulator enforces destination-country phytosanitary protocols for EU-bound shipments. Processing clusters around Ho Chi Minh City are expanding supercritical CO2 extraction capacity for pharmaceutical-grade alkaloid recovery.
Indonesia
Pt. Ruby Privatindo serves domestic chewing-product manufacturers with kernels sourced through regional trading networks. The national food and drug regulator maintains aflatoxin surveillance programs aligned with ASEAN harmonized standards. Surabaya-based processors are developing cosmetic-grade powder capabilities for Middle Eastern formulator contracts.
United Arab Emirates
Dubai and Riyadh retail channels move premium-grade whole kernel for Middle Eastern chewing-product consumers with phytosanitary certification displayed at point of sale. The Emirates Authority for Standardization and Metrology enforces import documentation for agricultural commodities. Jebel Ali free zone traders are consolidating direct-to-cosmetic channel development for European formulators.
Germany
EMA-registered pharmaceutical manufacturers specify supercritical CO2-compatible kernel grades, pulling Indian supply into contract farming arrangements. The ECHA REACH framework and EFSA novel food assessments constrain direct arecanut entry into European food applications. Hamburg-based extractors are adopting solvent-free extraction systems at pilot scale for residue-free output specifications.
Arecanut Market Vendor Landscape
Player mix skews toward cooperative processors and family-held trading houses with curing-yard assets. Market structure fragments across three quality tiers—pharmaceutical-grade contract suppliers, export-certified processors, and domestic wholesale aggregators—rather than concentrating around scale leaders. Strategic archetypes include backward-integrated plantation operators, cooperative sourcing networks, and export-grade processing specialists. Competitive moves center on alkaloid standardization capability acquisition and phytosanitary certification breadth expansion.
Within the cooperative processor archetype, The Campco Ltd. anchors its position through Western Ghats sourcing networks. Among export-grade specialists, Vietdelta Industrial Co., Ltd occupies a position serving Southeast Asian buyer diversification strategies. GM Group exemplifies the backward-integrated plantation operator model securing consistent fiber and alkaloid specifications through captive supply.
| Leading Market Players |
|---|
| Pt. Ruby Privatindo |
| Shri Ganesh Prasad Traders |
| The Campco Ltd. |
| GM Mallikarjunappa & Son's |
| Vietdelta Industrial Co., Ltd |
| GM Group |
| Swastika International |
| R. K. Trading |
| Sri Vinayaka Betelnut Traders |
| Others |
Supply Flow & Price Mechanics
Six-to-eight-week APEDA documentation timelines for EU-bound shipments concentrate pricing power among Karnataka's digitized cooperative processors with working capital depth, while smaller curing-yard operators accept spot-market discounts to accelerate cash conversion. This lead-time stratification rewards scale investments in blockchain-integrated batch tracking and chromatographic testing infrastructure.
Pricing Analysis
Sun-dried kernel grades trade at prior-generation benchmarks while supercritical CO2-compatible specifications command next-generation premiums. Three-tier pricing structure across pharmaceutical-grade, export-certified, and domestic wholesale levels differentiates by alkaloid standardization capability and FSSAI traceability compliance. Cost compression in standard-grade lots intensifies as synthetic arecoline analogues displace botanical extraction demand. Domestic pan masala manufacturers exhibit highest price sensitivity due to thin formulation margins, while European cosmetic formulators accept 40-60% premiums for certified powder with HPLC-verified tannin concentrations.
Supply Chain Analysis
Karnataka's Shimoga and Chikmagalur wholesale markets function as the dominant chokepoint, aggregating 70-plus percent of India's export-grade kernel before ocean freight consolidation. Supply draws from India's Western Ghats growing belt, Vietnam's Mekong Delta processing clusters, and Indonesia's Surabaya-based traders. Raw material dependencies include rainfall-dependent fresh kernel harvests, sulfur-based curing agents, and chromatographic testing reagents. Single-source vulnerability concentrates in Karnataka's cooperative networks during monsoon-disrupted seasons. Distribution runs through APEDA-certified exporters for EU pharmaceutical channels, Jebel Ali free zone traders for Middle Eastern retail, and domestic wholesale markets for pan masala manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward pharmaceutical extractors and European cosmetic formulators as their certification requirements consolidate supply access around digitized processors with testing infrastructure. This concentration fragments spot-market liquidity for uncertified grades.
For Market Incumbents: Secure alkaloid standardization capabilities through chromatographic purity verification equipment or backward integration into plantation operations. Synthetic arecoline substitution threatens premium-grade kernel premiums, making FSSAI-compliant traceability systems the priority lever for contract retention with pharmaceutical buyers. Capacity consolidation in Karnataka's cooperative networks accelerates compliance cost advantages over fragmented curing-yard competitors. For New Entrants and Emerging Players: Lead with cosmetic-grade powder production for Middle Eastern formulators in Dubai and Riyadh, where tannin concentration certificates now precede visual quality assessment. Vietnamese processing infrastructure offers regional sourcing alternatives with lower India-dependency premiums. Direct-to-formulator contracts bypass traditional broker networks and capture price premiums unavailable to wholesale market participants. For Investors and Strategic Acquirers: Carve-out targets emerge from family-held trading houses with curing-yard assets and established APEDA certification relationships but lacking digitization investment capacity. Five-to-ten-year viability hinges on alkaloid extraction facility alignment with supercritical CO2 pharmaceutical specifications. Watch for inflection when India's PLI scheme expands eligibility to agricultural processing upgrades, signaling subsidized consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Alkaloid Extraction Facility Upgrade | Supercritical CO2 compatibility opens EMA-registered pharmaceutical contracts with residue-free output specifications. |
| Blockchain Batch Tracking Implementation | FSSAI-mandated traceability compliance secures export-grade edible arecanut access ahead of cooperative consolidation. |
| Direct-to-Cosmetic Channel Development | Bypassing pan masala intermediaries captures 40-60% price premiums from Dubai and Riyadh formulators. |
| Backward Integration into Plantations | Captive supply secures consistent fiber and alkaloid specifications for pharmaceutical contract farming arrangements. |
| Vietnamese Processing Expansion | Regional infrastructure reduces India-dependency for Southeast Asian buyers diversifying sourcing portfolios. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of APEDA export documentation, FSSAI regulatory filings, and EU REACH registration databases. Primary interviews engaged cooperative processing managers, pharmaceutical extraction facility operators, cosmetic formulator procurement leads, and Karnataka wholesale market aggregators. Secondary validation drew from customs trade data, Agricultural and Processed Food Products Export Development Authority shipment records, and CDSCO-registered extractor facility disclosures. Bottom-up volume estimates from curing-yard throughput triangulated against top-down demand segmentation from end-user industry consumption patterns.
Segmentation dimensions modeled include product form (whole kernel, powder, split, oil), end-user industry (pharmaceutical, cosmetic, food, traditional medicine), quality grade tier (premium, export, standard, organic), and distribution channel structure. CAGRs derive from fitted growth curves across the projection horizon, calibrated to alkaloid extraction demand trajectories, FSSAI compliance implementation timelines, and synthetic substitution penetration rates in pharmaceutical applications.
The analysis sits within stated boundaries; outcomes outside sustained pharmaceutical offtake expansion or accelerated FSSAI digitization mandates would require recalibration. Forecasts reflect assumptions regarding monsoon stability in Karnataka's Western Ghats and EU regulatory stance on novel food assessments. Practitioners should keep alternative scenarios live as synthetic arecoline substitution rates and India's PLI scheme eligibility criteria evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Dried Kiwi Fruit Market
Fruits and Vegetables
Jicama Market
Fruits and Vegetables
Persimmons Market
Fruits and Vegetables
Avocado-Based Products Market
Fruits and Vegetables
Aegle Marmelos Market
Fruits and Vegetables
Yellow Oyster Mushroom Market
Fruits and Vegetables
Noni Fruit Powder Market
Fruits and Vegetables
Fresh Fruits Market
Fruits and Vegetables
Sweet Cherry Powder Market
Fruits and Vegetables
Adzuki Beans Market
Fruits and Vegetables
Romanesco Broccoli Market
Fruits and Vegetables
Frozen Fruits and Vegetables Market
Fruits and Vegetables
Dried Fruits Market
Fruits and Vegetables
Fresh Peaches Market
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
Pea Flakes Market