
 Aronia Berries Market | 2026-2036
Aronia Berries Market Size, Share, and Industry Trends Forecast 2026-2036
Aronia Berries Market Intelligence
Functional beverages is restructuring demand patterns across the Aronia Berries Market as polyphenol-enriched drinks displace conventional antioxidant formulations. Sawmill Hollow Family Farm anchors North American supply through direct-to-manufacturer channel control. BerryPharma AG differentiates via pharmaceutical-grade extraction standards for dietary supplement clients. Xi'an Victar Bio-Tech Corp. dominates Asian raw material flows through backward integration into cultivated berry sources.
Aronia berries (Aronia melanocarpa) constitute small, dark pome fruits containing anthocyanins exceeding 1,500 mg per 100 g fresh weight, with industrial processing targeting pigment stability and shelf-life extension for commercial applications. Powdered extract commands premium positioning due to standardized polyphenol content and extended ambient stability. Functional beverages represent the fastest-growing application as clean-label antioxidant claims drive reformulation cycles. Juice concentrate maintains volume leadership in European manufacturing channels where bulk procurement patterns persist.
FDA GRAS self-affirmation requirements and EFSA health claim substantiation protocols jointly govern market access for berry-derived ingredients in North America and Europe. USDA Organic certification and EU Organic Regulation 2018/848 further segment pricing tiers across export channels. Stakeholders must monitor evolving Novel Food dossier requirements for emerging extraction technologies before committing capital to capacity expansion.
Market Dynamics
Functional beverage formulators are capturing shelf space from legacy antioxidant suppliers as polyphenol-rich formulations displace conventional synthetic additives across retail channels.
Growth Catalysts
- EFSA health claim substantiation protocols:Validated antioxidant claims enable premium positioning for berry-derived concentrates in European dietary supplement channels.
- Clean-label reformulation cycles:Beverage manufacturers are replacing synthetic colorants with anthocyanin-rich natural pigments to meet retailer clean-label mandates.
- Poland-Germany processing corridor:Concentrated extraction capacity across these two markets reduces logistics costs for bulk juice concentrate buyers.
Market Restraints
- EU Novel Food dossier requirements:Emerging extraction technologies face 12-18 month approval timelines before commercial deployment.
- Input cost volatility:Organic cultivation certification costs fluctuate with USDA Organic and EU Organic Regulation 2018/848 audit frequency changes.
- Substitution threat:Elderberry and bilberry extracts compete for identical polyphenol positioning in functional beverage formulations.
Strategic Opportunities
- Pharmaceutical-grade extraction standards:Dietary supplement clients are migrating toward GMP-certified supply chains previously serving nutraceutical markets.
- Asian cultivated berry sources:Backward integration into controlled cultivation reduces wild-harvest variability for pigment standardization.
- Direct-to-manufacturer channel control:Farm-level bypass of commodity brokers captures margin previously lost to intermediaries.
Industry Challenges
- Anthocyanin stability expertise:Formulation chemists with pH-dependent pigment protection experience command premium compensation in tight labor markets.
- Dual certification complexity:Simultaneous USDA Organic and EU Organic Regulation 2018/848 compliance requires parallel documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aronia Berries Market |
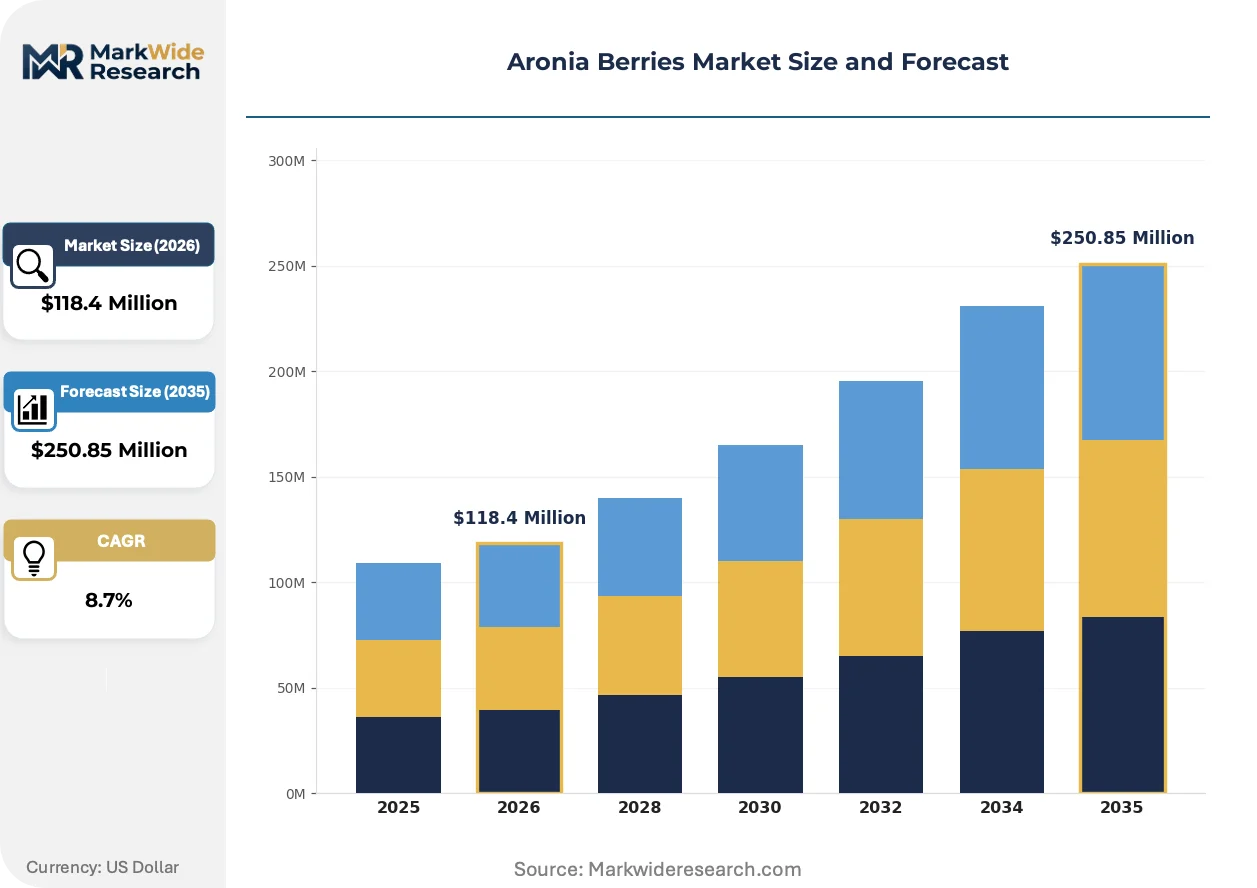
| Market Size in 2026 | $118.4 Million |
| Market Size in 2035 | $250.85 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Berries, Frozen Berries, Juice Concentrate, Powdered Extract Application: Dietary Supplements, Functional Beverages, Natural Food Coloring, Cosmetics End User: Nutrition Manufacturers, Beverage Producers, Cosmetic Brands, Herbal Medicine Providers Packaging Type: Plastic Containers, Glass Bottles, Sachets, Drum Barrels |
| Companies Covered | Cedar Gardens LLC, Sawmill Hollow Family Farm, Superberries, Xi’an Victar Bio-Tech Corp., BerryPharma AG, Aronia Original Naturprodukte GmbH, Bellbrook Berry Farm, Artemis International, Prairie Berries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aronia Berries Market Strategic Shifts & Innovations
Extraction technology advances and regulatory clarity around novel food applications are compressing development cycles for berry-derived functional ingredients.
Low-temperature vacuum extraction is modularizing production economics for small-batch pigment concentrates. Regional processors in Poland and Germany are adopting skid-mounted units to serve craft beverage clients without capital-intensive central facilities. This distributed model is modularizing supply chain risk away from single-site concentration.
EFSA's evolving guidance on polyphenol-specific health claims is forcing reformulation documentation standards. Manufacturers must now maintain batch-level anthocyanin assays to support substantiation dossiers. Dietary supplement brands serving German and French markets are responding by locking multi-year supply agreements with audited extraction partners.
Buyer consolidation among functional beverage multinationals is compressing supplier qualification timelines. Mid-sized berry processors face compressed payment terms as purchasing power concentrates among three to four North American formulators. This concentration is most visible in direct procurement contracts replacing spot-market spot buying for organic-certified raw material.
Aronia Berries Market Segmentation
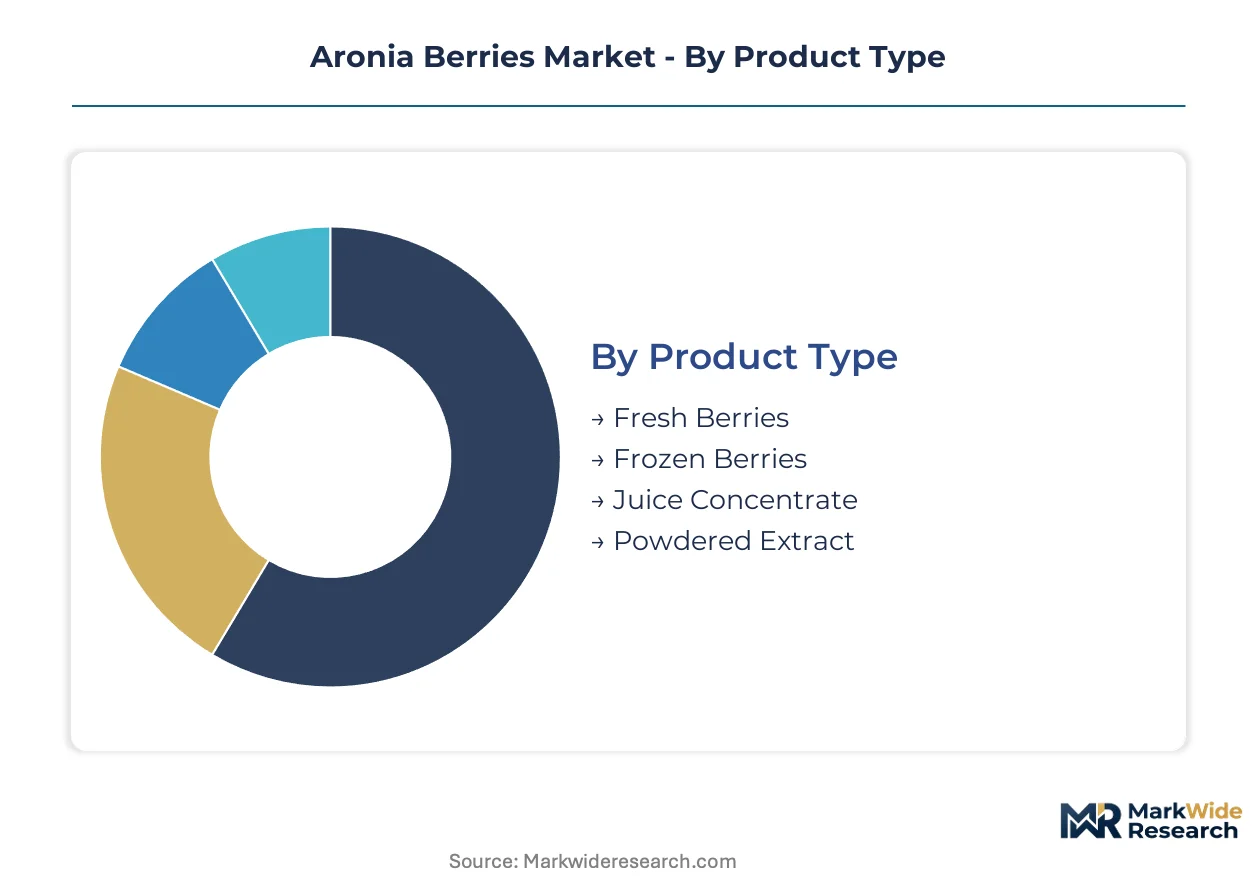
Aronia berry processors must align product formats with distinct supply chain economics and shelf-life requirements. Each segment category carries different margin structures and regulatory burdens that shape capital allocation decisions.
Product Type:
Upgrade cycles from bulk commodity formats toward standardized extracts are compressing margins for legacy processors while rewarding pigment-stability investments.
- Powdered Extract:Standardized anthocyanin content exceeding 25% by dry weight enables precise dosing in pharmaceutical-grade capsules. Polish and German extraction houses report strongest demand pull from dietary supplement brands seeking EFSA-substantiated antioxidant claims.
- Juice Concentrate:Bulk liquid format dominates European manufacturing procurement through the Poland-Germany processing corridor, where brix-standardized concentrates serve natural food coloring clients requiring volume scale.
- Fresh Berries:Perishable format with 7-10 day cold-chain windows limits distribution radius to 400km from cultivation sites.
- Frozen Berries:IQF processing preserves cellular integrity for smoothie manufacturers and bakery ingredient channels.
Juice concentrate sits at the top of the volume ranking, with powdered extract climbing the fastest.
Application:
Cost tier separation between premium-positioned supplement channels and commodity beverage inputs is widening as clean-label mandates intensify.
- Functional Beverages:Anthocyanin-rich formulations displace synthetic colorants in sports drinks and wellness shots. North American formulators now specify batch-level polyphenol assays to support retailer clean-label mandates.
- Dietary Supplements:Capsule and tablet manufacturers demand GMP-certified supply chains with validated stability data for FDA GRAS self-affirmation dossiers.
- Natural Food Coloring:pH-stable pigment systems serve confectionery and dairy applications requiring heat-process tolerance.
- Cosmetics:Topical antioxidant claims drive small-batch procurement from Korean and French skincare formulators.
Dietary supplements command premium pricing tiers, while functional beverages are gaining share fastest among application channels.
End User:
Customer type concentration among multinational beverage conglomerates is forcing mid-tier processors toward specialized certification investments.
- Beverage Producers:Direct procurement contracts now specify dual USDA Organic and EU Organic Regulation 2018/848 certification with 18-month supply commitments.
- Nutrition Manufacturers:GMP-audited extraction partners lock multi-year agreements to secure pharmaceutical-grade raw material flows.
- Cosmetic Brands:Clean beauty positioning requires cruelty-free and vegan certification overlays beyond organic standards.
- Herbal Medicine Providers:Traditional medicine channels in Germany and Austria prioritize wild-harvest provenance documentation.
Beverage producers anchor procurement volume, with nutrition manufacturers expanding contract coverage most aggressively.
Packaging Type:
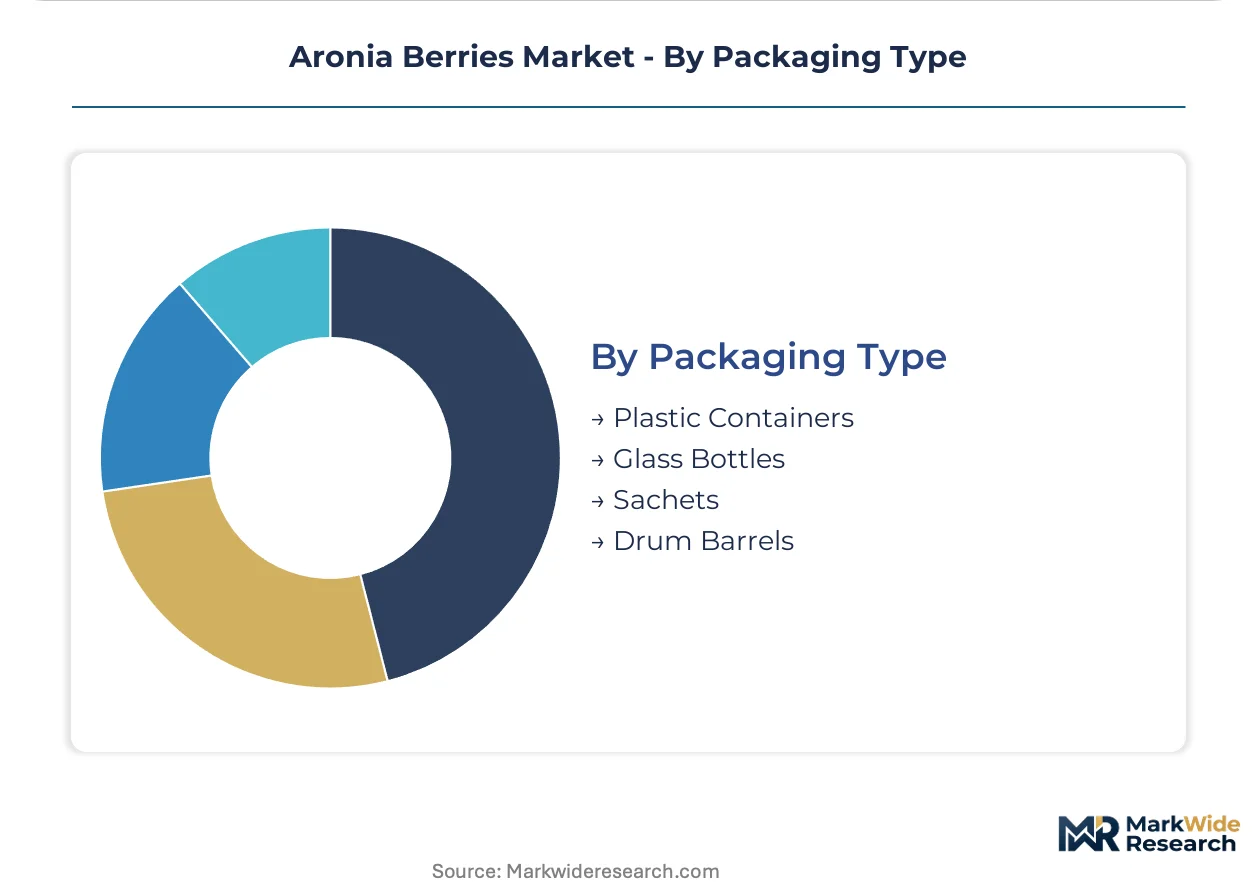
Supply concentration in drum barrels for bulk concentrate flows contrasts with sachet modularization serving craft beverage experimentation.
- Drum Barrels:Stainless steel and food-grade polymer drums handle 200-250 liter volumes for intercontinental juice concentrate shipments.
- Sachets:Single-serve powder portions enable sample distribution and subscription-model supplement brands.
- Glass Bottles:Amber glass protects light-sensitive anthocyanins in premium retail juice positioning.
- Plastic Containers:HDPE and PET formats serve frozen berry retail packs through supermarket distribution.
Drum barrels dominate intercontinental logistics, with sachets showing steepest expansion trajectory in direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Poland-Germany processing corridor anchors industrial demand for aronia berry concentrates, with extraction capacity clustering around Poznań and Hamburg serving bulk beverage manufacturers across the continent.
Poland
Organic cultivation expansion in Greater Poland Voivodeship supplies raw material to Poznań-based extraction houses. EU Organic Regulation 2018/848 compliance costs shape farm-level investment decisions. The Wielkopolska region concentrates juice concentrate production for German beverage formulators seeking brix-standardized inputs.
Germany
EFSA-substantiated antioxidant claims drive dietary supplement procurement from Hamburg and Berlin extraction facilities. Germany's Federal Office of Consumer Protection and Food Safety enforces Novel Food dossier requirements for emerging extraction technologies. Bavaria's natural food coloring sector absorbs mid-grade concentrate volumes for confectionery applications.
United States
FDA GRAS self-affirmation protocols govern ingredient market access for Iowa and Nebraska cultivation clusters. The USDA Organic certification program segments pricing tiers across export-oriented supply chains. Sawmill Hollow Family Farm in Iowa anchors North American supply through direct-to-manufacturer channel structures bypassing commodity brokers.
China
Backward integration into Shaanxi Province cultivated berry sources reduces wild-harvest variability for pigment standardization. The National Medical Products Administration oversees dietary supplement ingredient registrations for export markets. Xi'an-based processors dominate Asian raw material flows through captive cultivation contracts.
Canada
Prairie cultivation in Saskatchewan and Manitoba serves North American frozen berry demand through IQF processing infrastructure. Health Canada regulates natural health product claims for antioxidant positioning in supplement channels. Manitoba's Interlake region concentrates organic-certified farm supply for US cross-border procurement.
Aronia Berries Market Key Industry Players
Direct-to-manufacturer channel control dominates the current landscape as farm-level operators bypass commodity intermediaries. The vendor base fragments across cultivation specialists, extraction houses, and integrated berry-pharma hybrids. Three archetypes define competitive positioning: backward-integrated cultivator-processors, GMP-certified extraction specialists, and regional cooperative aggregators. Capacity expansion in low-temperature vacuum extraction and geographic expansion into Asian cultivated sources represent the dominant competitive moves reshaping supply structures.
Among North American farm-level operators, Sawmill Hollow Family Farm anchors direct procurement relationships with beverage manufacturers. BerryPharma AG exemplifies the pharmaceutical-grade extraction archetype serving GMP-audited dietary supplement channels. Xi'an Victar Bio-Tech Corp. occupies the Asian supply position through Shaanxi Province cultivation integration.
| Leading Market Players |
|---|
| Cedar Gardens LLC |
| Sawmill Hollow Family Farm |
| Superberries |
| Xi'an Victar Bio-Tech Corp. |
| BerryPharma AG |
| Aronia Original Naturprodukte GmbH |
| Bellbrook Berry Farm |
| Artemis International |
| Prairie Berries Inc. |
| Others |
Cost & Logistics Intelligence
Functional beverage formulators now concentrate procurement power across North America and Europe, compressing supplier margins through direct-to-manufacturer contract structures that bypass traditional commodity broker layers.
Pricing Analysis
Distributor margin compression defines current pricing dynamics as farm-level operators like Sawmill Hollow Family Farm establish direct procurement relationships with beverage manufacturers. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade—USDA Organic and EU Organic Regulation 2018/848 compliance commands tier-one positioning—while volume scale discounts intensify price competition for bulk juice concentrate flows. Pricing pressure stems from buyer consolidation among three to four North American formulators demanding extended payment terms. Nutrition manufacturers show least price sensitivity due to pharmaceutical-grade extraction requirements, while natural food coloring clients exhibit highest elasticity.
Supply Chain Analysis
Anthocyanin-rich raw material supply rests on Poland, Germany, and China's Shaanxi Province cultivation clusters, with Poland's Greater Poland Voivodeship and Germany's Hamburg extraction corridor anchoring European pigment flows. Input dependencies include organic-certified berry cultivation, low-temperature vacuum extraction equipment, and pH-stable pigment stabilization chemistries. Single-source vulnerability concentrates in the Poznań-Hamburg processing corridor where bulk concentrate buyers lack immediate alternatives. Distribution runs through drum barrel intercontinental shipments for juice concentrate and IQF cold-chain logistics for frozen berry retail packs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Poland's lower EU Organic Regulation 2018/848 compliance costs and Germany's premium EFSA-substantiated claim positioning.
For Market Incumbents: To counter elderberry and bilberry substitution threats in functional beverage formulations, BerryPharma AG and similar extraction houses should deepen backward integration into controlled Shaanxi Province cultivation while locking multi-year supply agreements with GMP-audited dietary supplement clients. Channel control investments in direct-to-manufacturer procurement portals capture margin previously lost to commodity intermediaries.
For New Entrants and Emerging Players: Enter via craft beverage experimentation channels where sachet-format powdered extract demand outstrips supply from regional Polish processors adopting skid-mounted vacuum extraction units. The cosmetics segment in Korean and French skincare markets offers penetrable white-space with small-batch cruelty-free certification requirements. A clean beauty positioning overlay beyond organic standards unlocks premium pricing tiers.
For Investors and Strategic Acquirers: Functional beverage multinationals are the most active acquirer in this space, seeking captive supply of polyphenol-standardized inputs. Long-term viability across the analysis window hinges on extraction technology IP and dual-certification documentation systems. Watch EFSA guidance evolution on polyphenol-specific health claims as the inflection signal for premium positioning sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivated Sources | Shaanxi Province captive berry contracts reduce wild-harvest variability for pigment standardization. |
| GMP Certification Investment | Hamburg and Berlin extraction facilities secure pharmaceutical-grade dietary supplement channel access. |
| Direct-to-Manufacturer Channel Launch | Iowa farm-level operators bypass commodity brokers to capture intermediary margin. |
| Dual Certification Documentation Systems | Parallel USDA Organic and EU Organic Regulation 2018/848 compliance unlocks transatlantic pricing tiers. |
| Low-Temperature Vacuum Extraction Scale-Up | Skid-mounted modular units in Poznań serve craft beverage clients without central facility capital. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with extraction house technical directors, beverage manufacturer procurement leads, organic certification auditors, and dietary supplement regulatory affairs specialists. Secondary validation drew from FDA GRAS notification databases, EFSA Novel Food dossier filings, USDA Organic certification records, and EU Organic Regulation 2018/848 compliance registries. Bottom-up cultivation area estimates and top-down extraction capacity assessments were triangulated against trade flow data.
Rate-of-change decomposition anchored the analytical framework across the projection horizon, modeling volume and value trajectories by product type, application channel, end-user category, and regional regulatory cluster. CAGRs were derived from segmented growth rate assumptions calibrated to buyer consolidation patterns and clean-label reformulation cycle intensity. Forecast inputs incorporated EFSA health claim substantiation timeline probabilities and organic certification audit frequency changes.
Inputs from extraction facility operators and certification bodies were available through the study window; gaps in emerging extraction technology commercial deployment data introduce uncertainty bands around novel food approval timeline assumptions. Forecasts reflect documented assumptions regarding buyer concentration trajectories and substitution threat intensities. Regulatory guidance evolution in Brussels and Washington warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Fresh Pumpkin Market
Fruits and Vegetables
Citrus Pulp Market
Fruits and Vegetables
Chile Fruits and Vegetables Market
Fruits and Vegetables
Guanabana Market
Fruits and Vegetables
Haskap Berry Powder Market
Fruits and Vegetables
Brined Vegetable Market
Fruits and Vegetables
Raisins Market
Fruits and Vegetables
Pea Flakes Market
Fruits and Vegetables
South America Lime Market
Fruits and Vegetables
Dried Grapes Market
Fruits and Vegetables
Vegetable Puree Market
Fruits and Vegetables
Japan Fresh Fruits Market
Fruits and Vegetables
South Africa Fruits and Vegetables Market
Fruits and Vegetables
Mexico Lime Market
Fruits and Vegetables
Global Dehydrated Onion Flakes Market
Fruits and Vegetables
Tropical Fruit Puree Market