
 Middle East and Africa Sweet Potatoes Market | 2026-2036
Middle East and Africa Sweet Potatoes Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Sweet Potatoes Market Foresight
Cassava flour is decoupling from traditional sweet potato starch applications in Nigerian baked goods, altering input cost structures for regional processors. McCain Foods Limited leverages its frozen vegetable infrastructure to sustain distribution across South African retail chains. Dole Food Company, Inc. anchors procurement networks in East African growing belts. The J.R. Simplot Company specializes in varietal selection for industrial fry lines.
Sweet potatoes in the Middle East and Africa comprise tuberous roots of Ipomoea batatas, typically containing 15-20% starch and 2-3% fiber by dry weight, with flesh pigmentation determined by anthocyanin or beta-carotene concentration; they serve primarily as carbohydrate sources for human consumption, processed starch, and animal nutrition. Orange Flesh varieties dominate fresh consumption channels due to established consumer preference for beta-carotene richness, while Snack Production represents the fastest-expanding end-use segment as extruded and fried formats gain shelf space in Egyptian and Kenyan supermarkets. Food Processing occupies the deepest margin pool, where vacuum-sealed Retail Packaging commands premium positioning in Gulf retail environments.
South Africa's Department of Agriculture enforces phytosanitary certification on imported planting material, while Saudi Arabia's SFDA monitors pesticide residue thresholds in fresh produce entering domestic distribution. Nigeria's National Agency for Food and Drug Administration and Control sets labeling standards for processed sweet potato products. Stakeholders must monitor evolving varietal registration requirements across multiple national agriculture ministries to secure uninterrupted market access.
Market Dynamics
South Africa's phytosanitary certification regime is compressing import windows for planting material, forcing regional processors to localize sourcing or absorb extended lead times for certified stock.
Growth Catalysts
- SFDA pesticide monitoring:Saudi Arabia's residue threshold enforcement is accelerating adoption of integrated pest management protocols among Egyptian exporters seeking Gulf retail placement.
- Street food formalization:Nigeria's Lagos-Abuja corridor vendors are consolidating procurement through registered cooperatives, creating predictable offtake volumes for orange-flesh processors.
- Vacuum-sealed retail formats:Extended shelf-life packaging technology is enabling premium positioning in UAE hypermarkets previously limited to loose tuber sales.
Market Restraints
- Input cost volatility:Fertilizer price swings tied to natural gas benchmarks are destabilizing cultivation economics for smallholders across Ethiopia's Rift Valley.
- Supply concentration risk:East African propagation material relies on a narrow germplasm base, amplifying disease susceptibility across Kenya's highland growing belts.
- Starch substitution:Cassava flour is capturing share in Nigerian baked goods, eroding traditional sweet potato starch offtake from industrial bakeries.
Strategic Opportunities
- East African procurement networks:Uganda's emerging commercial farming zones offer untapped volume potential for processors seeking alternatives to South African supply.
- Extruded snack formats:Fried and puffed products are gaining shelf space in Kenyan supermarkets, creating new product development lanes beyond fresh and frozen.
- NAFDAC labeling harmonization:Nigeria's processed product standards are converging with Codex frameworks, reducing multi-market compliance burdens for regional exporters.
Industry Challenges
- Varietal registration timelines:National agriculture ministries across multiple jurisdictions maintain non-harmonized approval processes, delaying commercial deployment of improved cultivars.
- Post-harvest handling infrastructure:Cold chain gaps between farmgate and processing facilities in Tanzania's Southern Highlands are elevating spoilage rates and quality downgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Sweet Potatoes Market |
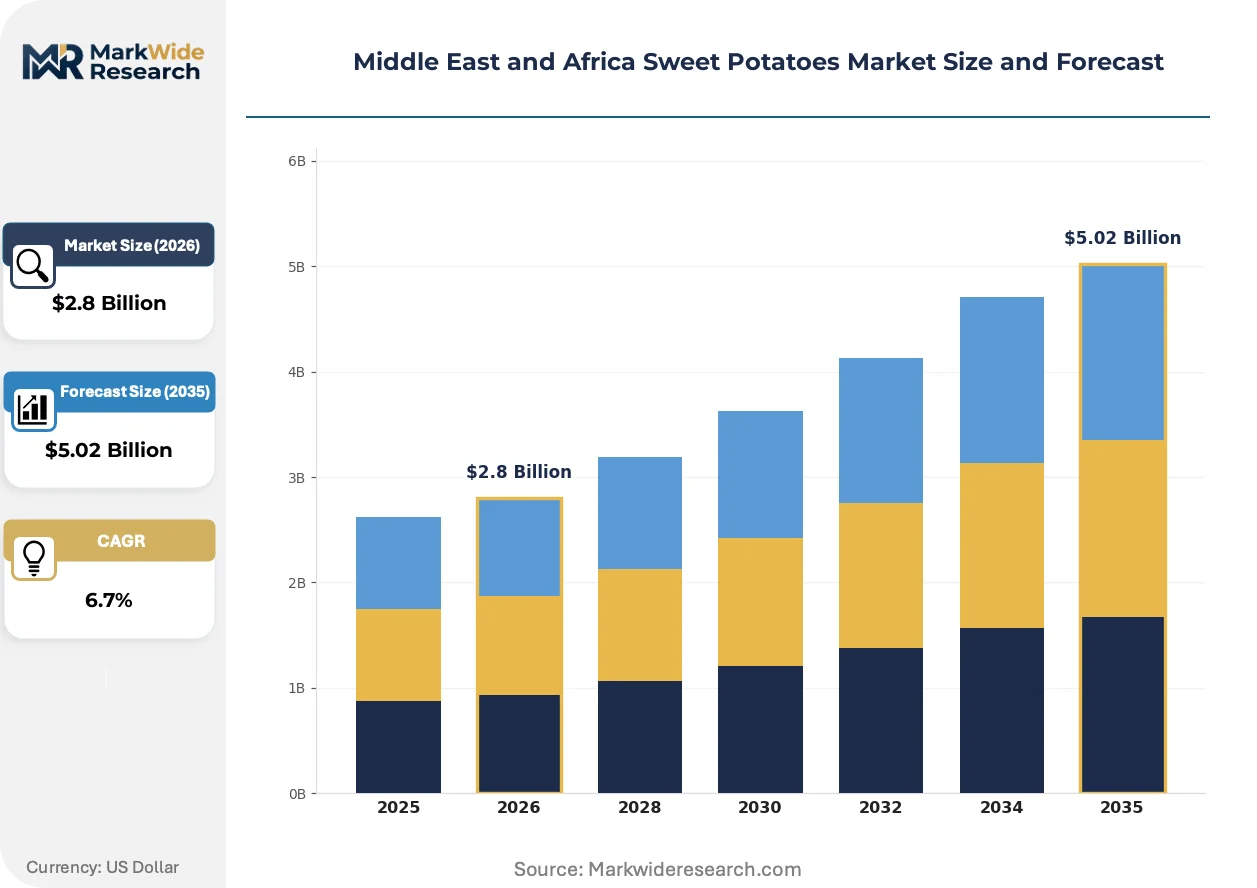
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orange Flesh, Purple Flesh, White Flesh, Yellow Flesh End Use: Food Processing, Fresh Consumption, Animal Feed, Snack Production Distribution Channel: Supermarkets, Online Retail, Farmers Markets, Wholesalers Packaging Type: Bulk Packaging, Retail Packaging, Vacuum Packaging, Tray Packaging |
| Companies Covered | Nestlé, Birds Eye Ltd, McCain Foods Limited, Dole Food Company, Inc., The J.R. Simplot Company, Lamb Weston Holdings, Inc., Conagra Brands Inc, A.V. Thomas Produce Inc, The Kraft Heinz Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Sweet Potatoes Market Shifts & Advancements
Processing technology upgrades and shifting retail formats are restructuring value capture across the Middle East and Africa sweet potato chain, with implications for input sourcing and end-product specification.
Low-temperature vacuum frying is rewriting snack manufacturing economics by preserving beta-carotene content while achieving the texture profiles demanded by Egyptian and Saudi retail buyers. Quick-service restaurant chains in the Gulf are adopting these processed inputs at accelerating rates. The technology is compressing the quality gap between fresh-cut and industrially produced alternatives.
South Africa's Department of Agriculture phytosanitary framework is tightening documentation requirements for imported planting material, extending border clearance durations. Domestic propagation facilities are scaling certified stock production to bypass import dependency. Smallholder cooperatives in Limpopo and Mpumalanga are absorbing the compliance burden through group certification schemes.
Urban household purchasing is gravitating toward pre-washed, portion-controlled retail packs in Lagos and Nairobi supermarkets, displacing traditional wet-market bulk buying. Quick-service restaurants and meal-kit providers are capturing this demand shift through contracted supply agreements. Kenyan retail chains are reporting the fastest format transition in East African urban centers.
Middle East and Africa Sweet Potatoes Market Segmentation
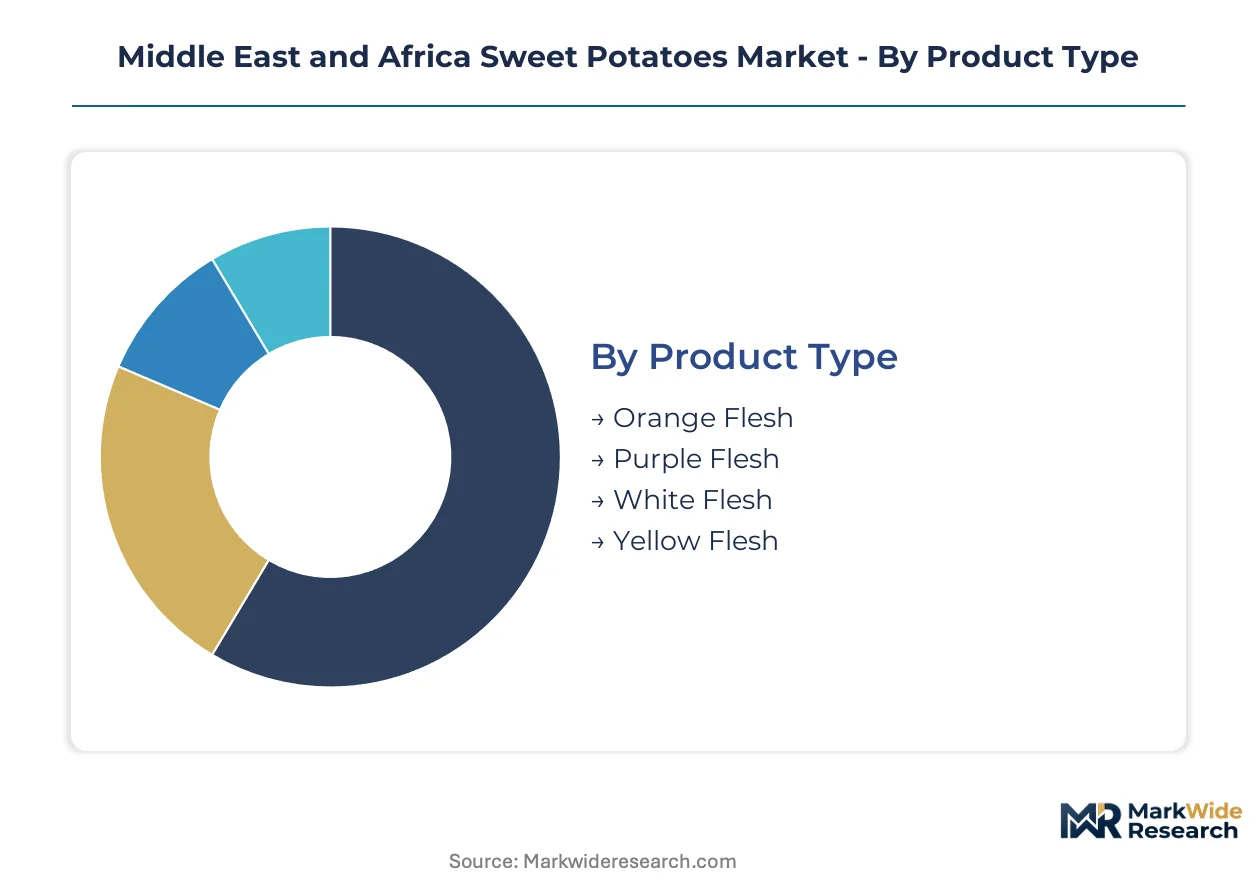
Sweet potato value chains across the Middle East and Africa fragment sharply by pigment chemistry, processing intensity, and retail format sophistication. Procurement patterns in Lagos, Nairobi, and Dubai diverge sufficiently that no single segment configuration dominates regional revenue.
Product Type:
Supply concentration for planting material determines which varieties achieve commercial scale in national programs.
- Orange Flesh:Beta-carotene concentrations reach 8,000-12,000 micrograms per 100 grams, delivering vitamin A precursors for fortified food programs. Nigerian flour millers and Ghanaian school feeding initiatives source this variety through contracted highland farms in Kenya's Nyandarua County. Phytosanitary certification delays for imported vines favor locally adapted cultivars.
- Purple Flesh:Anthocyanin pigmentation creates antioxidant positioning for premium juice and bakery applications. Demand concentrates in Cape Town's health-food retail corridor and UAE expatriate supermarkets seeking differentiation from commodity starches. South African propagation facilities are scaling certified stock to reduce import dependency for this niche.
- White Flesh:Neutral flavor profiles suit starch extraction for industrial adhesives and textile sizing in Egypt's Delta processing zones.
- Yellow Flesh:Intermediate carotenoid levels serve fresh-cut processing for Gulf quick-service restaurant chains requiring consistent fry color.
Orange Flesh absorbs the bulk of installed capacity; Purple Flesh is expanding most quickly.
End Use:
Margin structures vary threefold across the value chain depending on processing depth and certification requirements.
- Food Processing:Vacuum-sealed purees and dehydrated flakes command premium placement in Saudi hypermarkets. Egyptian processors are upgrading to aseptic filling lines to capture this tier. NAFDAC labeling harmonization with Codex standards is reducing multi-market compliance burdens for Nigerian exporters targeting Gulf retail.
- Snack Production:Extruded and vacuum-fried formats are displacing fresh-cut alternatives in Kenyan supermarkets. Low-temperature frying preserves beta-carotene while achieving texture specifications demanded by Saudi retail buyers. Quick-service restaurant chains in Dubai and Riyadh are accelerating procurement of these processed inputs.
- Fresh Consumption:Lagos wet markets and Nairobi's Wakulima wholesale hub still handle the majority of regional volume, though pre-washed retail packs are gaining share.
- Animal Feed:Cull tubers and processing waste supply poultry and swine operations in Ethiopia's Rift Valley, where input cost volatility has destabilized smallholder cultivation economics.
Food Processing captures the deepest margin pool; Snack Production is climbing the fastest.
Distribution Channel:
Channel selection determines cold chain investment requirements and working capital intensity for suppliers.
- Supermarkets:Shoprite, Carrefour, and Spinneys formats in Lagos, Nairobi, and Dubai are consolidating procurement through direct supplier agreements, bypassing traditional wholesale layers. Pre-washed, portion-controlled packs displace loose tuber sales in these formats.
- Wholesalers:Mile 12 Market in Lagos and Wakulima in Nairobi remain the dominant volume channels for food service and informal retail, though formalization pressures are consolidating vendor bases.
- Farmers Markets:Direct farmgate sales persist in Tanzania's Southern Highlands and Uganda's emerging commercial zones, where cold chain gaps elevate spoilage rates.
- Online Retail:Jumia and Noon platforms are piloting fresh produce logistics in Cairo and Johannesburg, constrained by last-mile temperature control.
Wholesalers still handle the majority of regional volume; Supermarkets are gaining share fastest.
Packaging Type:
Packaging technology investment separates premium positioning from commodity pricing in Gulf retail environments.
- Vacuum Packaging:Extended shelf-life formats enable UAE hypermarket placement previously limited to loose sales. Modified atmosphere systems are compressing the quality gap between fresh-cut and industrially processed alternatives.
- Retail Packaging:Pre-washed, netted, or tray formats are displacing bulk buying in Nairobi and Lagos urban supermarkets. Kenyan retail chains report the fastest format transition in East African urban centers.
- Bulk Packaging:Jute and woven polypropylene sacks dominate farmgate and wholesale transactions across Nigeria's Lagos-Abuja corridor.
- Tray Packaging:Portion-controlled formats serve meal-kit providers and quick-service restaurants seeking inventory efficiency.
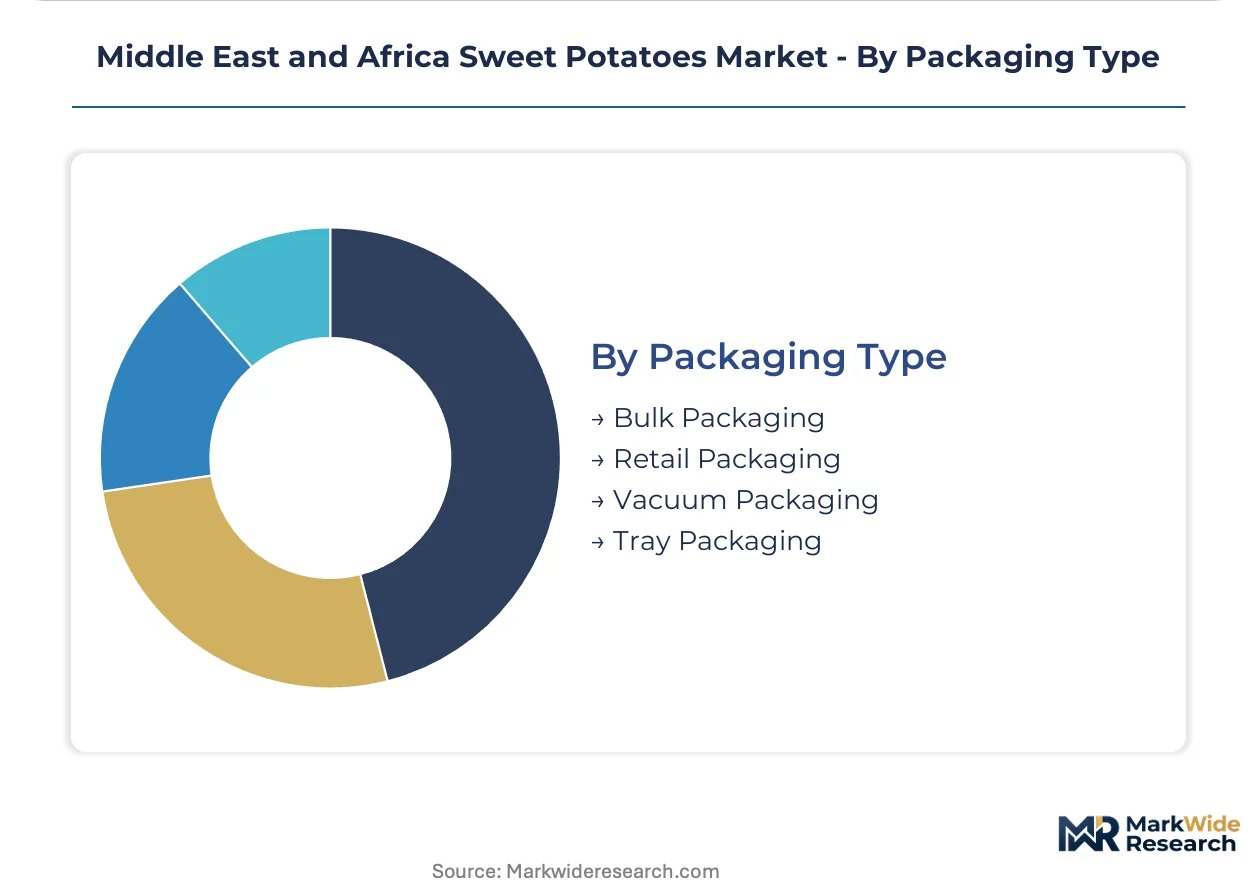
Bulk Packaging still underpins the majority of regional throughput; Vacuum Packaging is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Nigeria's Lagos-Abuja corridor, where street food vendors and quick-service restaurants source orange-flesh varieties for processing into chips and flour. South Africa's Department of Agriculture enforces phytosanitary certification for sweet potato imports, tightening quality benchmarks across the region. Fresh consumption among health-conscious urban households is expanding adoption in Gulf retail environments.
Nigeria
Lagos-Abuja corridor vendors and flour millers drive orange-flesh procurement volumes for chips and fortified food programs. NAFDAC labeling standards for processed sweet potato products are converging with Codex frameworks, easing multi-market compliance. Street food formalization is consolidating procurement through registered cooperatives, creating predictable offtake for processors.
South Africa
Retail chains and frozen vegetable infrastructure sustain distribution across urban centers, with Shoprite formats consolidating direct supplier agreements. The Department of Agriculture, Land Reform and Rural Development enforces phytosanitary certification for imported planting material, extending border clearance durations. Domestic propagation facilities in Limpopo and Mpumalanga are scaling certified stock production to bypass import dependency.
Saudi Arabia
SFDA pesticide residue monitoring is accelerating integrated pest management adoption among Egyptian exporters seeking Gulf retail placement. Quick-service restaurant chains in Riyadh are procuring vacuum-fried processed inputs at accelerating rates. Extended shelf-life packaging technology enables premium positioning in hypermarkets previously limited to loose tuber sales.
Egypt
Delta processing zones utilize white-flesh varieties for starch extraction serving industrial adhesives and textile sizing applications. Low-temperature vacuum frying technology is preserving beta-carotene content while achieving texture specifications demanded by Saudi retail buyers. Egyptian processors are upgrading to aseptic filling lines to capture premium puree and flake tiers.
Kenya
Nairobi's Wakulima wholesale hub and supermarket chains are driving the fastest format transition in East African urban centers toward pre-washed retail packs. Cold chain gaps between farmgate and processing facilities in the highland growing belts are elevating spoilage rates. Extruded and puffed snack products are gaining shelf space in supermarkets, creating new product development lanes beyond fresh and frozen formats.
Middle East and Africa Sweet Potatoes Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with frozen vegetable infrastructure operators holding concentrated positions in South African retail while regional procurement networks anchor East African supply. The competitive structure fragments between multinational food processors with integrated frozen distribution, agricultural trading houses with varietal selection capabilities, and emerging local processors serving snack manufacturing tiers. Two strategic archetypes dominate: scale-driven frozen vegetable specialists leveraging existing cold chain assets, and varietal-focused agricultural suppliers controlling propagation material quality. Capacity expansion in certified stock production and strategic partnerships for extruded snack technology licensing represent the dominant competitive moves reshaping positioning.
Within the scale-driven frozen vegetable tier, McCain Foods Limited and Lamb Weston Holdings, Inc. exemplify infrastructure-heavy positioning, while Dole Food Company, Inc. represents the procurement-network archetype anchoring East African growing belts. The J.R. Simplot Company occupies a specialization position in varietal selection for industrial processing applications. These three companies collectively illustrate how geographic coverage and processing depth determine competitive differentiation across fresh, frozen, and snack manufacturing segments.
| Leading Market Players |
|---|
| Nestlé |
| Birds Eye Ltd |
| McCain Foods Limited |
| Dole Food Company, Inc. |
| The J.R. Simplot Company |
| Lamb Weston Holdings, Inc. |
| Conagra Brands Inc |
| A.V. Thomas Produce Inc |
| The Kraft Heinz Company |
| Others |
Supply & Pricing Matrix
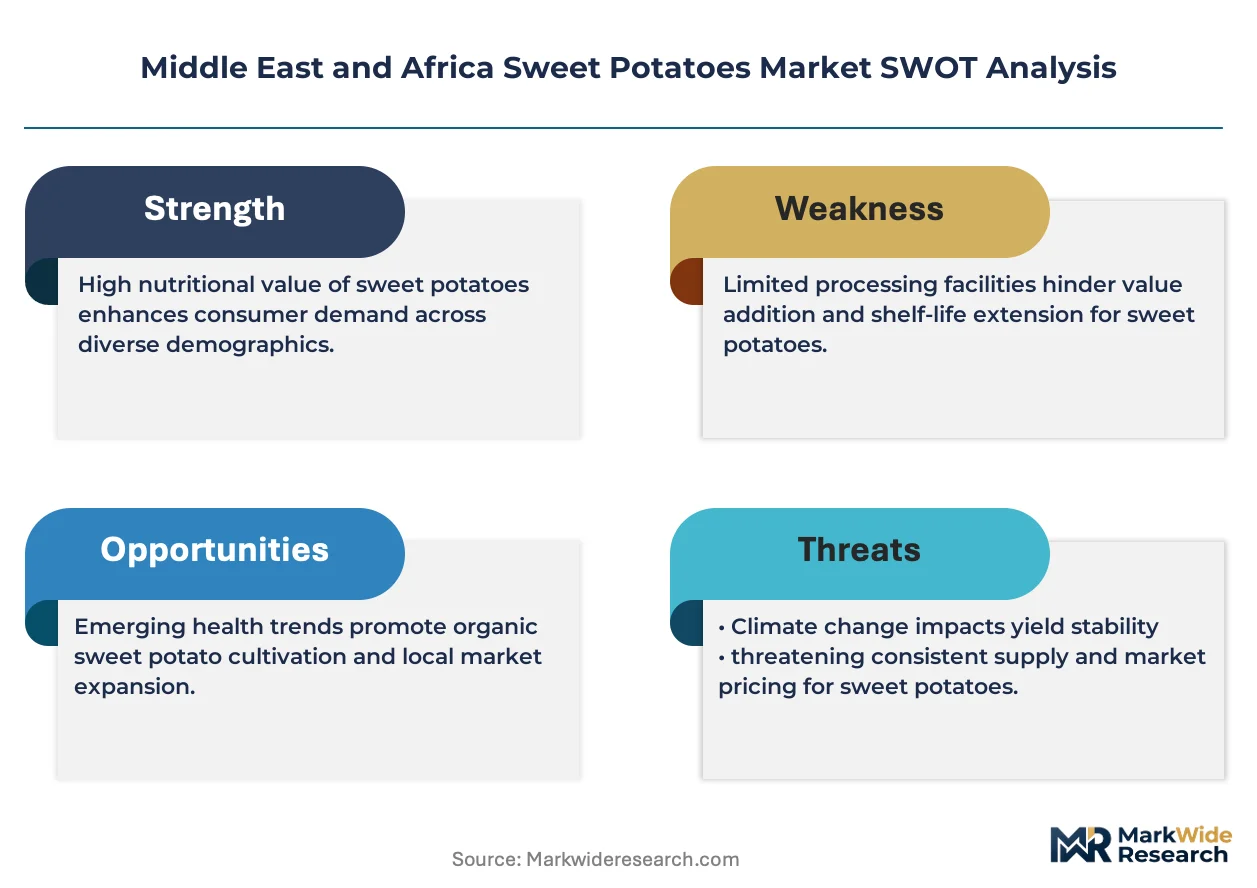
SFDA pesticide residue mandates gate qualified supply access for Egyptian exporters targeting Saudi retail placement, with compliant lots commanding premium positioning in Gulf hypermarkets while non-certified volumes trade at steep discounts to informal channels. This regulatory filter simultaneously concentrates pricing power among integrated pest management adopters and forces marginal operators toward low-margin wet-market sales.
Pricing Analysis
Volume flows through Lagos wet markets at economy tiers while vacuum-sealed retail formats capture premium margins in Dubai and Riyadh hypermarkets. Price differentiation rests on phytosanitary certification status and beta-carotene retention grades, with NAFDAC-labeled Nigerian products bridging Gulf compliance requirements. Cost compression in fresh-cut segments is intensifying because fertilizer price volatility destabilizes Ethiopian smallholder economics. Street food vendors in Nigeria's Lagos-Abuja corridor exhibit highest price sensitivity; Saudi quick-service restaurant chains demonstrate lowest sensitivity due to contracted supply agreements.
Supply Chain Analysis
Reverse-logistics flows for cull tubers and processing waste feed poultry operations in Ethiopia's Rift Valley, creating secondary value capture from primary channel rejections. Propagation material draws from South African certified stock facilities, Kenyan highland nurseries, and Ugandan commercial zones. Single-source vulnerability concentrates in East African germplasm bases with narrow genetic diversity. Distribution runs through Mile 12 Market and Wakulima wholesale hubs for informal retail, with Shoprite and Carrefour formats consolidating direct supplier agreements for formal channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phytosanitary certification delays and input cost volatility are forcing consolidation among non-integrated processors unable to secure certified propagation material or absorb fertilizer price swings.
For Market Incumbents: Extend certified stock production capacity in Limpopo and Mpumalanga to bypass South African import dependency, while locking long-term offtake agreements with Lagos-Abuja corridor cooperatives before street food formalization completes. Cassava flour substitution in Nigerian baked goods threatens traditional sweet potato starch offtake; backward integration into vacuum-fried snack manufacturing captures margin migration toward extruded formats. For New Entrants and Emerging Players: Quick-service restaurant procurement managers represent the most accessible entry channel, as Gulf chains accelerate adoption of low-temperature vacuum-fried inputs and lack established supplier relationships. Target Kenya's supermarket format transition toward pre-washed retail packs, where cold chain gaps between farmgate and processing facilities create quality arbitrage opportunities for operators with temperature-controlled logistics. License extruded snack technology from Egyptian equipment providers to bypass R&D capital requirements. For Investors and Strategic Acquirers: NAFDAC-Codex labeling harmonization completion is the leading indicator that Nigerian processed product exports will accelerate toward Gulf retail placement, signaling acquisition timing for regional processors with compliant infrastructure. Five-to-ten year viability favors vertically integrated operators controlling propagation material quality and frozen distribution assets. Monitor South African Department of Agriculture varietal registration timelines for improved cultivar commercialization signals.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Stock Production Scale-Up | South African propagation facilities bypass import dependency while capturing premium pricing from compliant Gulf buyers. |
| Vacuum-Fried Snack Technology Licensing | Egyptian processors preserve beta-carotene content while meeting Saudi SFDA texture specifications for quick-service restaurant chains. |
| Cooperative Procurement Consolidation | Lagos-Abuja corridor formalization creates predictable offtake volumes for orange-flesh processors targeting flour millers. |
| Aseptic Filling Line Upgrade | Egyptian purees and dehydrated flakes command premium placement in Saudi hypermarkets previously limited to loose tuber sales. |
| East African Procurement Network Expansion | Uganda's emerging commercial zones offer volume alternatives to South African supply concentration risk. |
Research Methodology
Multi-period observation of planting material certification timelines, fertilizer price benchmarks, and retail format transitions anchored the trend analysis, supplemented by interviews with propagation facility managers, NAFDAC compliance officers, supermarket category buyers, quick-service restaurant procurement heads, and cold chain logistics operators. Secondary validation drew from South African Department of Agriculture phytosanitary filings, SFDA pesticide residue monitoring reports, Kenyan retail audit data, and Nigerian customs trade records. Bottom-up cultivation economics modeling triangulated against top-down value chain revenue estimates.
Input-output matrices mapped propagation material flows through certified stock production, processing intensity tiers, and distribution channel structures across the analysis window. Segmentation dimensions included flesh pigmentation chemistry, end-use application depth, packaging technology investment, and regional regulatory cluster. CAGRs derived from volume trajectory modeling against price elasticity coefficients for fresh versus processed formats. Forecast inputs incorporated integrated pest management adoption curves and vacuum-sealed packaging penetration rates.
Several conditions sit outside the modeled scope, including unannounced varietal registration rejections, abrupt fertilizer subsidy withdrawals, and Gulf import quota implementations. Forecasts reflect documented assumptions regarding NAFDAC-Codex harmonization completion and SFDA enforcement consistency. Practitioners should monitor South African border clearance duration trends and Kenyan supermarket private-label expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Brined Vegetable Market
Fruits and Vegetables
Asia Pacific Olive Market
Fruits and Vegetables
Sweet Cherry Powder Market
Fruits and Vegetables
Colombia Fruits and Vegetables Market
Fruits and Vegetables
Oman Fruits and Vegetables Market
Fruits and Vegetables
United States Blueberry Market
Fruits and Vegetables
Dried Fruits Market
Fruits and Vegetables
Kuwait Vegetables and Fruits Market
Fruits and Vegetables
North America Organic Fruits Market
Fruits and Vegetables
Egypt Fruits and Vegetables Market
Fruits and Vegetables
Water Chestnut Market
Fruits and Vegetables
Fresh Strawberry Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market
Fruits and Vegetables
Guava Puree Market
Fruits and Vegetables
Romanesco Broccoli Market
Fruits and Vegetables
Frozen Vegetables Market