
 Japan Electric Car Market | 2026-2036
Japan Electric Car Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Electric Car Market Outlook
Fleet operators are unwinding the historical dominance of private consumer purchases in Japan's electric vehicle demand structure. Toyota Motor Corporation leverages its hybrid-electric heritage to anchor development of solid-state battery platforms. Nissan Motor Co. Ltd. sustains manufacturing scale through its Leaf production base in Oppama. Honda Motor Co. Ltd. competes by specializing in urban mobility formats tailored to Japan's narrow road infrastructure.
Japan electric cars are battery-powered road vehicles engineered for zero tailpipe emissions, typically employing lithium-ion or solid-state electrochemical cells with energy densities exceeding 250 Wh per kilogram. Their primary purpose is to displace internal combustion engine propulsion in passenger and light commercial transport under domestic decarbonization commitments. Sedan configurations currently occupy the largest installed base among vehicle types, though SUVs are capturing incremental share as domestic manufacturers broaden electrified lineups. Solid-state battery technology leads R&D allocation despite lithium-ion sustaining near-term production volume, with fast charging infrastructure representing the fastest-expanding segment within charging networks as highway corridor deployment accelerates.
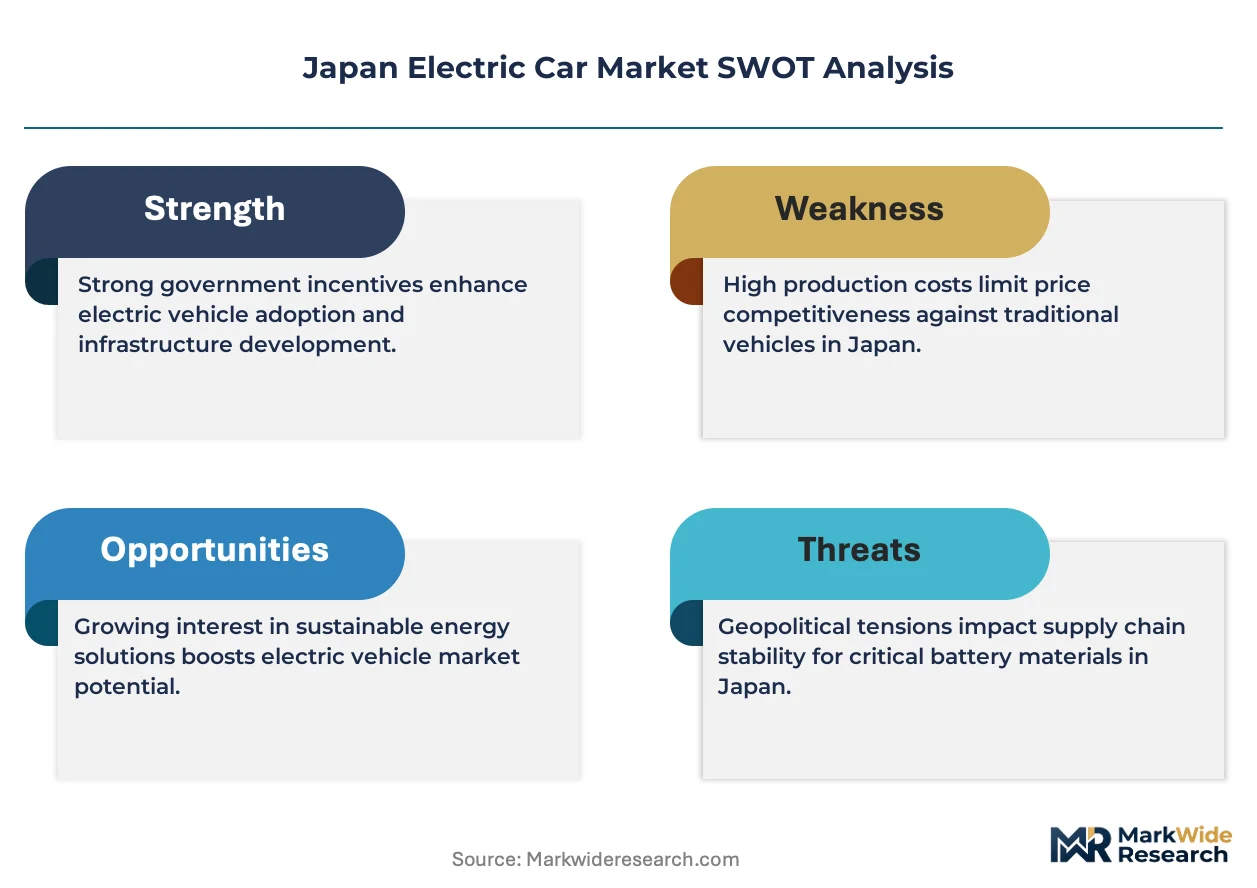
METI's subsidy frameworks, JIS standards for charging interoperability, and the Ministry of Land, Infrastructure, Transport and Tourism's vehicle efficiency regulations collectively shape product specifications and market access conditions for electric vehicle entrants. PMDA-aligned safety protocols for autonomous driving features increasingly influence design requirements as manufacturers integrate advanced driver assistance with electrified platforms. Stakeholders must monitor how METI's next-phase subsidy recalibration and grid interconnection standards reshape total cost of ownership calculations for fleet versus private buyers.
Market Dynamics
Fleet electrification mandates from Japan's Ministry of Land, Infrastructure, Transport and Tourism are compressing private ownership timelines and redirecting manufacturing capacity toward commercial-grade battery platforms with extended duty cycles.
Growth Catalysts
- Charging Infrastructure Density:Highway corridor fast-charging networks along the Tomei and Meishin Expressways reduce range anxiety for intercity commercial routes. METI subsidies accelerate 150kW+ station deployment.
- Corporate Fleet Mandates:Logistics operators in the Greater Tokyo Area face binding carbon intensity targets under Tokyo Metropolitan Government climate ordinances. Battery electric vans and light trucks satisfy last-mile compliance requirements.
- Solid-State R&D Pipelines:Domestic automakers channel Green Innovation Fund capital toward sulfide-based electrolyte manufacturing. Pilot production lines in Kanagawa Prefecture target energy density thresholds above 400 Wh per kilogram.
Market Restraints
- Lithium Import Concentration:Japan sources over 90% of battery-grade lithium from Australian hard-rock spodumene and South American brine operations. Geopolitical friction or export restrictions disrupt cell cost structures.
- Grid Interconnection Backlogs:Utility-scale charging hubs in Osaka and Nagoya face 18-24 month queue delays for high-voltage transformer upgrades. Regional power monopolies prioritize industrial load connections.
- Residual Value Uncertainty:Secondary market liquidity for used battery electric vehicles remains thin. Fleet buyers discount total cost of ownership calculations due to unpredictable depreciation curves.
Strategic Opportunities
- Kyushu Manufacturing Cluster:Semiconductor and battery material suppliers concentrate in Fukuoka and Kumamoto prefectures. Proximity to Asian shipping lanes enables export-oriented solid-state cell production.
- V2G Integration Pilots:Chubu Electric Power and Kansai Electric Power test vehicle-to-grid protocols for grid stabilization services. Fleet operators monetize parked vehicle battery capacity during peak demand periods.
- Compact Urban Formats:Narrow road width restrictions in Kyoto and Kanazawa favor kei-car electric platforms. Domestic manufacturers exploit regulatory exemptions for miniaturized powertrains.
Industry Challenges
- Battery Thermal Management Expertise:Solid-state cell manufacturing requires precision thin-film deposition techniques. Japanese engineering talent pools lack depth in sulfide electrolyte handling protocols.
- Charging Protocol Fragmentation:CHAdeMO and CCS2 standards compete for infrastructure investment. Fleet operators delay procurement decisions pending clarity on dominant connector specifications.
- Software-Defined Vehicle Integration:Legacy tier-one suppliers struggle to deliver over-the-air update architectures. Electrified platforms demand real-time battery management system calibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Electric Car Market |
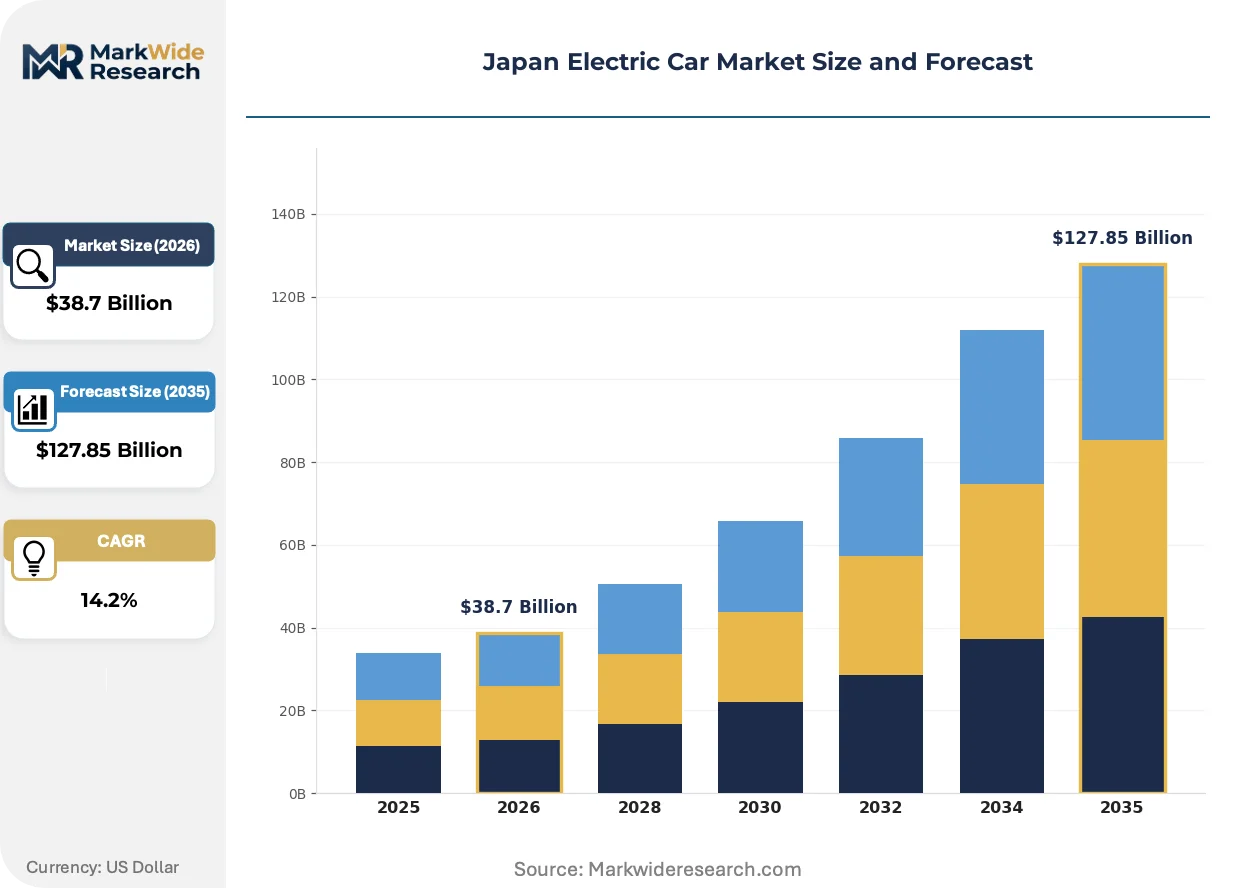
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Battery Technology: Lithium-ion, Solid State, Nickel-metal Hydride, Lithium Polymer Charging Infrastructure: Home Charging, Public Charging, Fast Charging, Wireless Charging End User: Private Consumers, Fleet Operators, Rental Services, Government Agencies |
| Companies Covered | Toyota Motor Corporation, Nissan Motor Co. Ltd., Honda Motor Co. Ltd., Mitsubishi Motors Corporation, Lexus, Subaru Corporation, Mazda Motor Corporation, Suzuki Motor Corporation, Isuzu Motors Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Electric Car Market Strategic Shifts
Battery chemistry platforms are diverging between near-term lithium-ion scale and next-generation solid-state architectures, with regulatory pressure and fleet procurement patterns forcing parallel investment tracks.
Solid-state battery technology is bifurcating development roadmaps across Japanese manufacturers. Sulfide-based electrolyte formulations promise energy density gains and fire-safety improvements over liquid electrolyte cells. Fleet operators in the Kanto region pilot early solid-state packs for high-utilization delivery routes. This technology is bifurcating supplier relationships, as automakers establish captive joint ventures with domestic chemical firms rather than relying on Korean or Chinese cell imports.
METI's Green Innovation Fund disbursement criteria now require domestic manufacturing localization for subsidy eligibility. Battery assembly operations must locate within designated industrial zones to access capital grants. Solid-state pilot lines in Kanagawa and lithium-ion expansion in Tochigi Prefecture respond to this geographic conditionality.
Corporate procurement departments now embed carbon accounting into vehicle acquisition decisions. Total cost of ownership models incorporate Scope 3 emissions liability and fuel price volatility hedges. Fleet management platforms in the Greater Tokyo Area prioritize battery electric vehicles with verified supply chain decarbonization credentials.
Japan Electric Car Market Segmentation
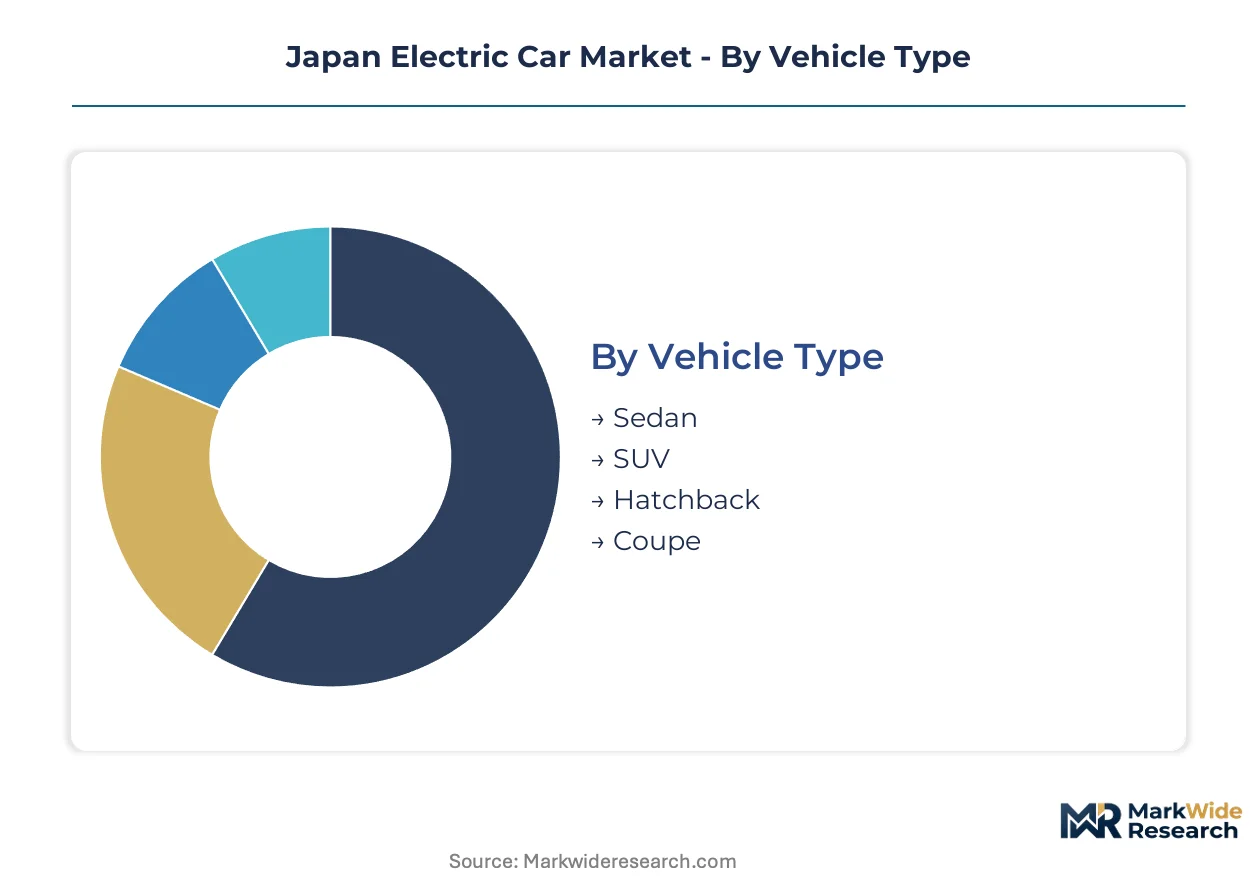
Segmentation in Japan's electric car market reveals how fleet electrification mandates and solid-state R&D investments are reshaping demand patterns across vehicle formats and battery chemistries. Understanding these divisions exposes where procurement budgets concentrate and which technologies command premium positioning.
Vehicle Type:
Domestic demand concentrates on compact formats suited to narrow urban roads, while export-oriented production scales toward larger platforms for North American and European markets.
- Sedan:Four-door passenger configurations with flat-floor battery architectures dominate corporate fleet procurement in the Greater Tokyo Area. Municipal governments in Yokohama and Saitama specify sedan formats for official vehicle replacement programs under carbon neutrality ordinances.
- SUV:Higher ground clearance and expanded cabin volume attract suburban private buyers in Chiba and Kanagawa prefectures. Domestic manufacturers prioritize SUV electrification to capture North American export revenue streams.
- Hatchback:Compact rear cargo access suits last-mile delivery operators in Osaka's dense commercial districts. Kei-car regulatory exemptions enable miniaturized electric powertrains for urban logistics.
- Coupe:Two-door performance variants occupy niche positioning among enthusiast segments. Limited production runs target premium private collectors in Tokyo's Minato Ward.
Sedan configurations hold the largest share; momentum sits with SUV electrification as manufacturers broaden electrified lineups for export markets.
Battery Technology:
Cost tier differentiation separates near-term lithium-ion deployment from premium solid-state development tracks, with chemistry choices directly determining subsidy eligibility under METI frameworks.
- Lithium-ion:Nickel-manganese-cobalt and lithium-iron-phosphate cells sustain current production volume at Oppama and Tahara assembly plants. METI subsidy recalibration favors domestic cell sourcing over Korean or Chinese imports.
- Solid State:Sulfide-based electrolyte formulations target energy density thresholds above 400 Wh per kilogram. Pilot production lines in Kanagawa Prefecture channel Green Innovation Fund capital toward commercialization.
- Nickel-metal Hydride:Legacy chemistry persists in hybrid-electric transition models leveraging Toyota's existing supply chain infrastructure. Cost structures favor entry-level private consumer segments in regional prefectures.
- Lithium Polymer:Pouch cell configurations enable flexible packaging for compact urban vehicle formats. Limited adoption concentrates in kei-car derivatives for Kyoto and Kanazawa narrow-road compliance.
Lithium-ion dominates installed base; solid-state platforms are climbing the fastest as sulfide electrolyte manufacturing matures.
Charging Infrastructure:
Application-specific deployment patterns separate residential overnight charging from commercial fast-charging corridors, with infrastructure density determining fleet procurement feasibility.
- Home Charging:Level 2 AC wallbox installations concentrate in detached suburban housing in Saitama and Chiba prefectures. Tokyo Metropolitan Government building codes now mandate pre-wiring for multi-unit dwellings.
- Public Charging:Destination charging at retail and commercial facilities serves intermittent private user demand. Convenience store operators in the Kanto region deploy 50kW units to capture dwell-time revenue.
- Fast Charging:150kW+ DC highway corridor networks along Tomei and Meishin Expressways reduce range anxiety for intercity commercial routes. METI subsidies accelerate station deployment with CHAdeMO and CCS2 dual-protocol hardware.
- Wireless Charging:Inductive pad systems pilot in taxi fleet applications for Nagoya and Fukuoka municipal transport. Alignment precision requirements limit deployment to fixed-route commercial operations.
Home charging retains the largest installed base; fast charging infrastructure is gaining share fastest as highway corridor deployment accelerates.
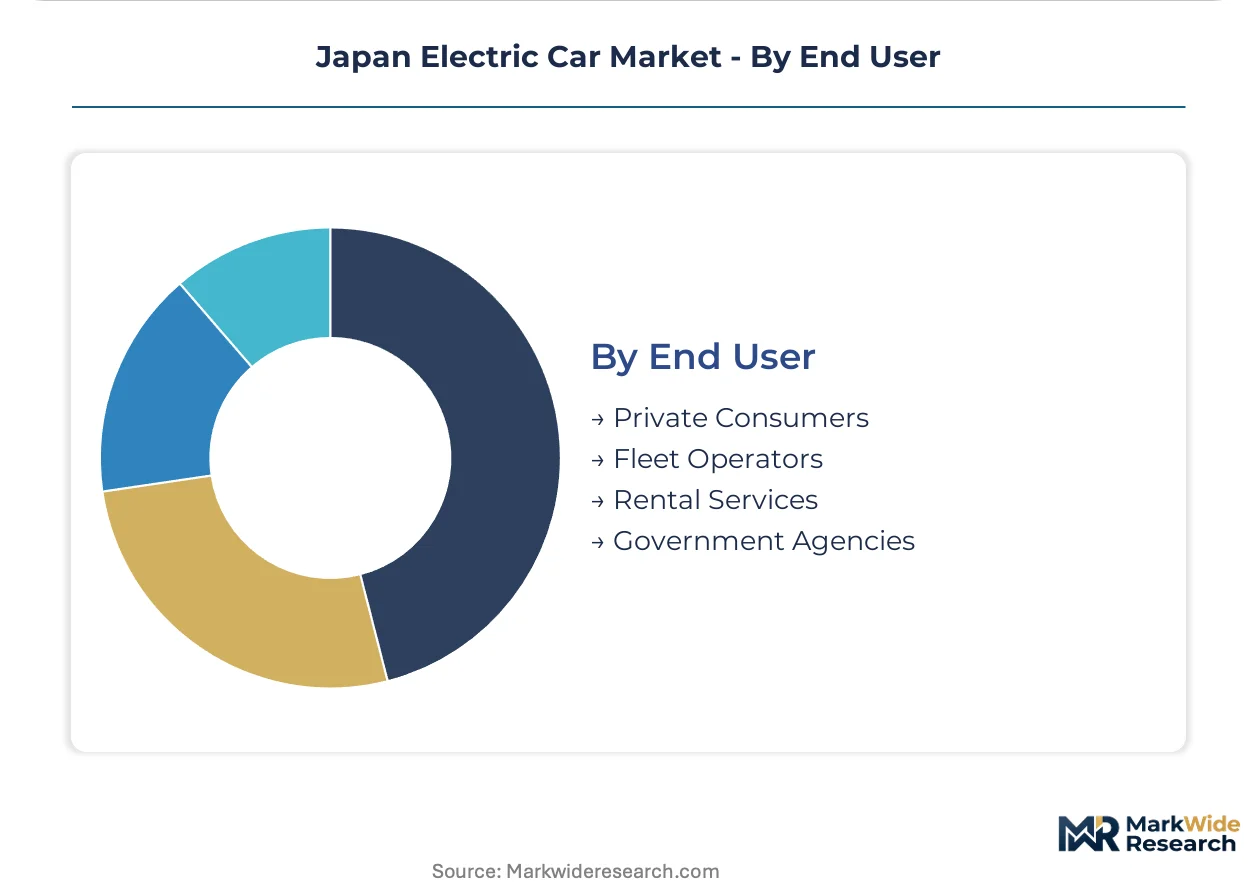
End User:
Customer type segmentation reveals a structural shift from private ownership toward commercial procurement, with carbon accounting integration reshaping acquisition decision frameworks.
- Private Consumers:Individual households in Greater Tokyo Area suburbs prioritize total cost of ownership calculations incorporating residual value uncertainty. Secondary market liquidity constraints suppress demand outside premium income brackets.
- Fleet Operators:Logistics providers face binding carbon intensity targets under Tokyo Metropolitan Government climate ordinances. Battery electric vans and light trucks satisfy last-mile compliance requirements with verified supply chain decarbonization credentials.
- Rental Services:Short-term vehicle providers in Osaka and Nagoya integrate electric models into corporate travel accounts. Charging infrastructure partnerships determine fleet composition feasibility.
- Government Agencies:Municipal and prefectural procurement mandates specify domestic-manufactured electric vehicles for official use. METI Green Innovation Fund eligibility requires domestic assembly localization.
Fleet operators command the steepest expansion trajectory; private consumer segments maintain volume concentration pending residual value clarity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports electric vehicle technology and solid-state battery components to North American and European automotive markets through established trade corridors. Domestic production clusters concentrate in prefectures with legacy manufacturing infrastructure and METI-designated subsidy zones.
Kanto/Tokyo
Fleet electrification mandates from the Tokyo Metropolitan Government drive commercial vehicle procurement in the Greater Tokyo Area. METI's Green Innovation Fund channels capital toward solid-state battery pilot lines in Kanagawa Prefecture. Charging infrastructure density peaks along Tomei Expressway corridors serving intercity logistics routes.
Kansai/Osaka
Grid interconnection backlogs for utility-scale charging hubs create procurement delays for fleet operators in Osaka and Nagoya metropolitan zones. JIS standards for charging interoperability shape hardware specifications across public station deployments. Semiconductor suppliers cluster in Kyoto Prefecture, feeding battery management system component demand.
Chubu/Nagoya
Automotive assembly heritage in Aichi Prefecture sustains lithium-ion production scale at Tahara plant complexes. Toyota Motor Corporation anchors regional employment in hybrid-to-battery electric transition manufacturing. Highway corridor fast-charging networks along Meishin Expressway reduce range anxiety for commercial routes.
Kyushu
Battery material suppliers concentrate in Fukuoka and Kumamoto prefectures near Asian shipping lanes. Proximity to export markets enables solid-state cell production targeting overseas automotive customers. Regional power utilities test vehicle-to-grid protocols for grid stabilization services with municipal fleet operators.
Tohoku
Renewable energy integration challenges in rural prefectures create demand for stationary battery storage paired with electric vehicle charging. METI subsidy recalibration prioritizes domestic manufacturing localization in designated industrial zones. Cold climate performance requirements influence battery thermal management specifications for regional deployment.
Japan Electric Car Market Competitive Environment
Listed leaders compete with private specialists across platform development and battery chemistry dimensions. The market structure consolidates around established automotive conglomerates with captive R&D pipelines and tier-one supplier networks. Three archetypes dominate: legacy full-line manufacturers pivoting from hybrid heritage, kei-car specialists exploiting regulatory exemptions for miniaturized formats, and battery joint ventures securing chemical supply chain control. Competitive moves center on M&A for solid-state electrolyte startups and capacity expansion in METI-designated subsidy zones.
Among Japan-based automotive conglomerates, Toyota Motor Corporation, Nissan Motor Co. Ltd., and Honda Motor Co. Ltd. occupy positions representing distinct strategic postures. Toyota exemplifies the hybrid-to-battery electric transition archetype, leveraging manufacturing scale and supplier relationships developed over three decades of electrified vehicle production. Nissan represents early-mover positioning in mass-market battery electric platforms. Honda sits within the urban mobility specialization tier, targeting narrow-road compliance and compact format dominance. These three entities collectively anchor the competitive structure through their influence over JIS standard development, METI subsidy program design, and charging infrastructure investment priorities.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Nissan Motor Co. Ltd. |
| Honda Motor Co. Ltd. |
| Mitsubishi Motors Corporation |
| Lexus |
| Subaru Corporation |
| Mazda Motor Corporation |
| Suzuki Motor Corporation |
| Isuzu Motors Limited |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for Australian hard-rock spodumene and South American brine lock in lithium supply access for Japanese cell manufacturers while anchoring price visibility against spot market volatility. These arrangements tie METI subsidy eligibility to domestic assembly localization, creating parallel cost pressures for importers lacking captive chemical supply.
Pricing Analysis
Next-generation solid-state platforms command premium positioning above current lithium-ion configurations, with sulfide electrolyte manufacturing costs driving tier separation. Three-tier pricing structure across premium solid-state, standard nickel-manganese-cobalt, and economy lithium-iron-phosphate levels reflects chemistry differentiation and domestic content requirements. Cost compression in entry tiers is intensifying because Korean and Chinese cell imports face METI subsidy exclusion. Fleet operators exhibit highest price sensitivity due to total cost of ownership calculations, while government procurement tolerates premium tiers for domestic assembly compliance.
Supply Chain Analysis
Inventory lead times for battery-grade lithium extend 12-18 months from Australian hard-rock and Chilean brine operations, compressing Japanese cell makers' production flexibility. The supply chain draws from concentrated spodumene mining in Western Australia, brine extraction in Chile's Atacama, and cobalt refining in the Democratic Republic of Congo. Single-source vulnerability in sulfide electrolyte precursors threatens solid-state commercialization timelines. Distribution runs through captive joint ventures between automakers and domestic chemical firms, bypassing merchant cell markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as fleet electrification mandates splinter demand across vehicle formats, battery chemistries, and charging infrastructure archetypes. Corporate carbon accounting integration creates niche specialization openings for suppliers aligning with verified supply chain decarbonization credentials.
For Market Incumbents: Secure captive sulfide electrolyte supply through joint ventures with Kanagawa Prefecture chemical firms before Korean competitors establish equivalent partnerships. Capacity addition in METI-designated subsidy zones preserves subsidy eligibility against emerging entrants lacking domestic assembly footprint. Threat substitution from solid-state platform delays demands accelerated pilot line commissioning. For New Entrants and Emerging Players: Lead with kei-car electric platforms exploiting narrow-road regulatory exemptions in Kyoto and Kanazawa, where domestic incumbents underinvest. Compact urban formats represent the most penetrable segment given infrastructure density constraints on larger vehicles. Go-to-market angle centers on municipal fleet procurement bypassing dealer networks through direct government contracting. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among charging infrastructure operators with highway corridor positioning along Tomei and Meishin Expressways. Long-term viability over a decade horizon rests on V2G integration pilots maturing into grid stabilization service contracts. Acquisition target archetype: solid-state electrolyte startups with thin-film deposition patents. Signal to watch: METI subsidy recalibration timing for domestic manufacturing localization thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Joint Venture | Captive sulfide electrolyte supply secures METI subsidy eligibility for Kanagawa assembly. |
| Highway Corridor Charging Partnership | 150kW+ station deployment along Tomei Expressway anchors fleet operator procurement decisions. |
| Kei-Car Platform Specialization | Narrow-road compliance in Kyoto and Kanazawa exploits regulatory exemption arbitrage. |
| V2G Grid Integration Pilot | Chubu Electric Power protocols monetize parked fleet battery capacity during peak demand. |
| Domestic Assembly Localization | Tochigi and Kanagawa production placement satisfies Green Innovation Fund geographic conditionality. |
Study Parameters
Desk research of METI policy filings, JIS standard documentation, and vehicle registration databases preceded structured interviews with OEM platform engineers, Tier 1 battery procurement leads, fleet operations managers, and charging infrastructure developers. Secondary validation drew from customs trade records, utility interconnection queue data, and prefectural industrial zone investment disclosures. Bottom-up cell cost modeling and top-down fleet penetration scenarios were triangulated against subsidy disbursement trajectories.
Variance decomposition across vehicle class, battery chemistry tier, and end-user archetype shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level adoption curves weighted by METI subsidy phase-out schedules and corporate fleet mandate enforcement intensity. Solid-state manufacturing yield assumptions and lithium contract pricing trajectories fed chemistry-specific volume projections.
Underlying assumptions cover subsidy continuation, sulfide electrolyte yield improvement, and grid interconnection backlog resolution, with deviation risk concentrated in lithium export restrictions and solid-state thermal management failures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Hoverboard Scooter Market
Electric Vehicles
Electric Vehicle Electric Heating Film Market
Electric Vehicles
Electric Vehicle UBI Market
Electric Vehicles
Electric Vehicle Liquid-Cooled Charging Connector Market
Electric Vehicles
Global EV on-Board Chargers Market
Electric Vehicles
RV SLI Battery Market
Electric Vehicles
United States Electric Pick-Up Trucks Market
Electric Vehicles
Electric Vehicle Relay Market
Electric Vehicles
Singapore Electric Vehicle Market
Electric Vehicles
South Africa Electric Cars Market
Electric Vehicles
North America Electric Bus Market
Electric Vehicles
North America E-Bike Market
Electric Vehicles
France Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Global Electric Vehicles Market
Electric Vehicles
Europe Solar E-Bike Market
Electric Vehicles
Electric Vehicle NVH Material Market