
 South Africa Electric Cars Market | 2026-2036
South Africa Electric Cars Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Electric Cars Market Analytics
SABS automotive certification cycles for electric drivetrain compliance is unwinding market access timelines for new entrants. BMW Group leverages its Rosslyn assembly footprint to sustain local production credibility. Volkswagen Group anchors its strategy around modular electric platform adaptation for right-hand-drive markets. Nissan Motor Corporation competes through established Leaf distribution channels and dealer network depth.
An electric car integrates a high-voltage battery pack, typically lithium-ion with nickel-manganese-cobalt or lithium-iron-phosphate cathode chemistry, with one or more electric motors driving the wheels through a single-speed reduction gearbox, eliminating the internal combustion engine and exhaust system entirely. The primary commercial purpose centers on zero-tailpipe-emission personal and fleet mobility with lower energy operating costs versus gasoline or diesel equivalents. SUV configurations currently lead consumer preference in South Africa's electric car segment, commanding premium positioning and larger battery capacities that extend range anxiety buffers. Sedan and hatchback formats attract fleet procurement focused on total cost optimization and urban parking compatibility. Fast charging stations represent the infrastructure segment with the steepest deployment curve, though home charging retains the largest installed base among existing owners.
South Africa's National Regulator for Compulsory Specifications enforces SABS mark requirements that shape battery safety and electromagnetic compatibility standards for all vehicles sold domestically. The Department of Trade, Industry and Competition administers automotive incentive structures that condition market access on local manufacturing commitments and supplier development targets. Stakeholders must monitor how grid reliability constraints and Eskom tariff trajectories interact with charging infrastructure economics to determine viable rollout sequencing outside metropolitan cores.
Market Dynamics
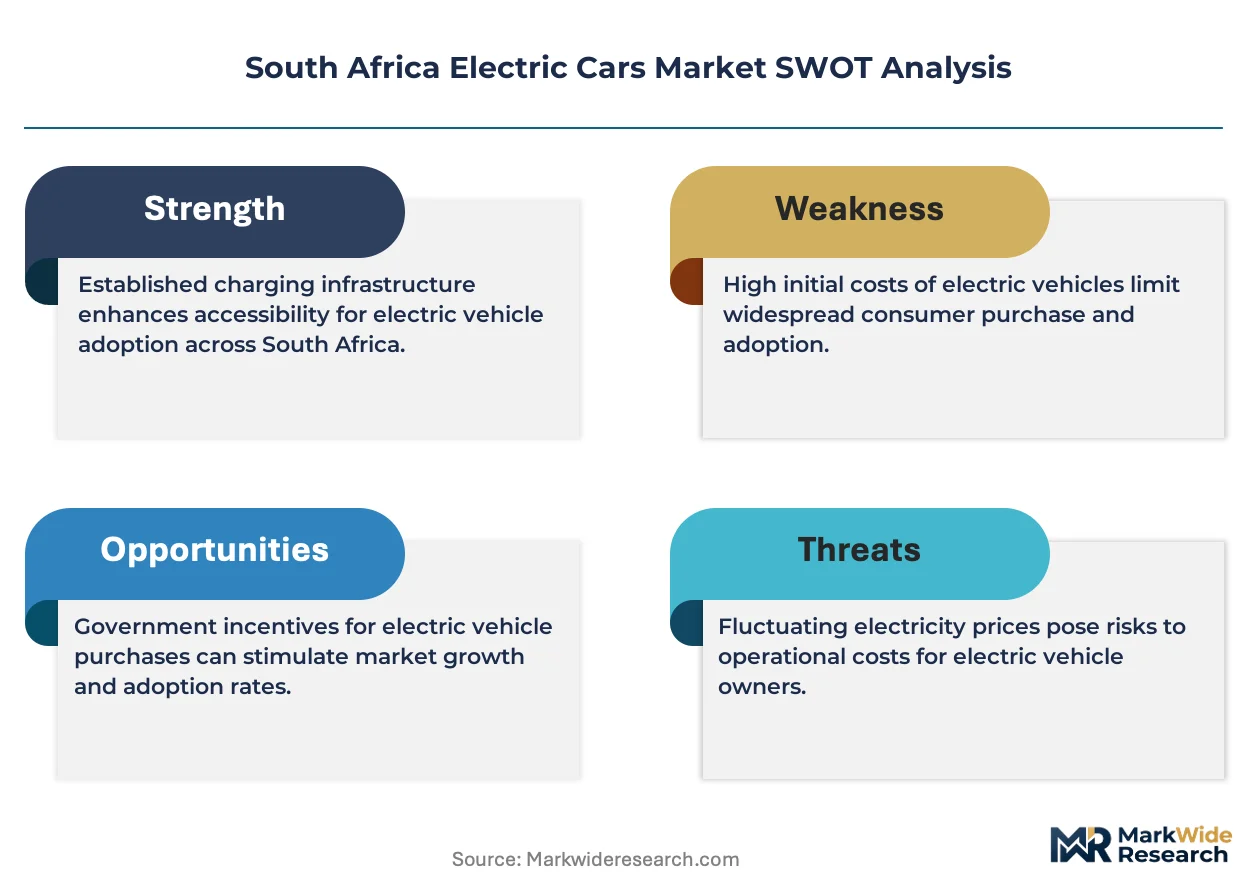
The Automotive Production and Development Programme's local content requirements are redirecting OEM capital toward domestic EV assembly, creating a structural pull that concentrates investment in Gauteng's manufacturing corridor while conditioning market access on supplier development targets.
Growth Catalysts
- APDP Incentive Structure:The Department of Trade, Industry and Competition ties automotive incentive eligibility to local manufacturing commitments, compelling OEMs to establish battery pack assembly within South Africa's industrial hubs.
- Fleet TCO Advantage:Urban logistics operators in Johannesburg and Cape Town metropolitan areas are scaling battery-electric van acquisitions as energy operating costs undercut diesel equivalents across high-mileage duty cycles.
- Fast Charging Deployment:Infrastructure operators are prioritizing DC fast charging station rollouts along the N1 and N3 highway corridors, reducing range anxiety buffers for inter-provincial commercial fleets.
Market Restraints
- Lithium Price Volatility:Cathode material cost fluctuations in nickel-manganese-cobalt chemistry directly compress battery pack economics for entry-segment hatchbacks targeting mass-market penetration.
- Grid Reliability Constraints:Eskom's load-shedding frequency degrades charging infrastructure utilization rates outside metropolitan cores, deterring private investment in rural and secondary city deployment.
- SABS Certification Cycles:The National Regulator for Compulsory Specifications enforces extended electromagnetic compatibility testing timelines that delay new entrant market access by multiple quarters.
Strategic Opportunities
- Eastern Cape Manufacturing:The Coega Industrial Development Zone offers tariff-free import status and dedicated renewable energy supply, positioning Port Elizabeth as a secondary EV assembly node outside Gauteng concentration.
- Right-Hand-Drive Export Platform:South Africa's existing RHD vehicle production base enables OEMs to serve Commonwealth African markets without dedicated plant retooling for left-hand-drive variants.
- Second-Life Battery Storage:Retired automotive lithium-ion packs are converging with solar PV installations in commercial and industrial applications, creating circular economy revenue streams for OEMs and independent operators.
Industry Challenges
- High-Voltage Technician Scarcity:The national technical education pipeline produces insufficient certified electricians capable of servicing 400V+ battery systems, constraining after-sales network expansion.
- Charging-Grid Integration Complexity:Distribution network operators lack standardized interconnection protocols for high-capacity DC fast charging stations, extending utility approval timelines and capex recovery periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Electric Cars Market |
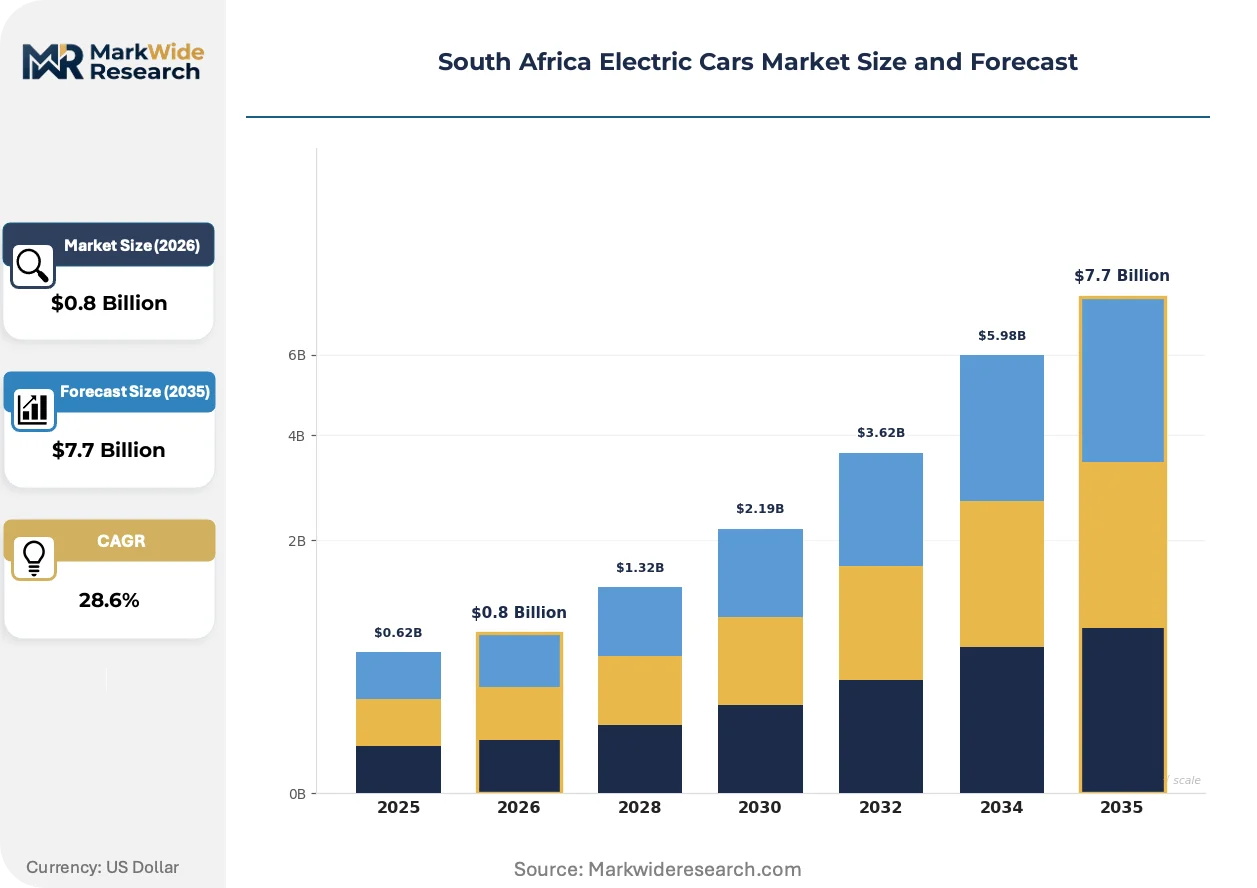
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $7.7 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Hatchback, Coupe Charging Infrastructure: Fast Charging Stations, Home Charging, Public Chargers, Wireless Charging Battery Type: Lithium-Ion, Solid-State, Lead-Acid, Nickel-Metal Hydride Market Player: Local Manufacturers, International Brands, Startups, Importers |
| Companies Covered | Tesla Inc, BMW Group, Volkswagen Group, Nissan Motor Corporation, Mercedes-Benz Group, Hyundai Motor Company, Kia Corporation, Toyota Motor Corporation, Volvo Cars, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Electric Cars Market Evolving Landscape
Electrification is compressing traditional powertrain supply chains while regulatory pressure and shifting procurement patterns restructure how vehicles are specified, financed, and operated across South Africa's automotive value chain.
Lithium-iron-phosphate battery chemistry is displacing nickel-manganese-cobalt configurations in fleet-focused electric vans and entry SUVs. Logistics operators prioritizing cycle life over energy density are specifying LFP packs for urban delivery routes exceeding 200 kilometers daily. This chemistry shift is displacing cobalt-dependent supply chains and compressing cathode material cost exposure for price-sensitive commercial buyers.
The Department of Trade, Industry and Competition is tightening local content thresholds under APDP Phase 2, requiring escalating domestic value-add for incentive retention. OEMs are responding by qualifying South African suppliers for battery pack assembly and electric motor subcomponent production. This regulatory pressure most acutely affects premium SUV segments where import-dependent configurations face margin compression against locally assembled competitors.
Fleet procurement departments are unbundling vehicle acquisition from energy and maintenance contracts, separating capital expenditure from operational expenditure through leasing structures that transfer battery degradation risk to financiers. This model is displacing traditional dealer-finance arrangements in corporate and government fleet channels. The Western Cape provincial government and Johannesburg municipal fleets are pioneering this transition, with energy-as-a-service contracts now standard in public sector tenders.
South Africa Electric Cars Market Segmentation
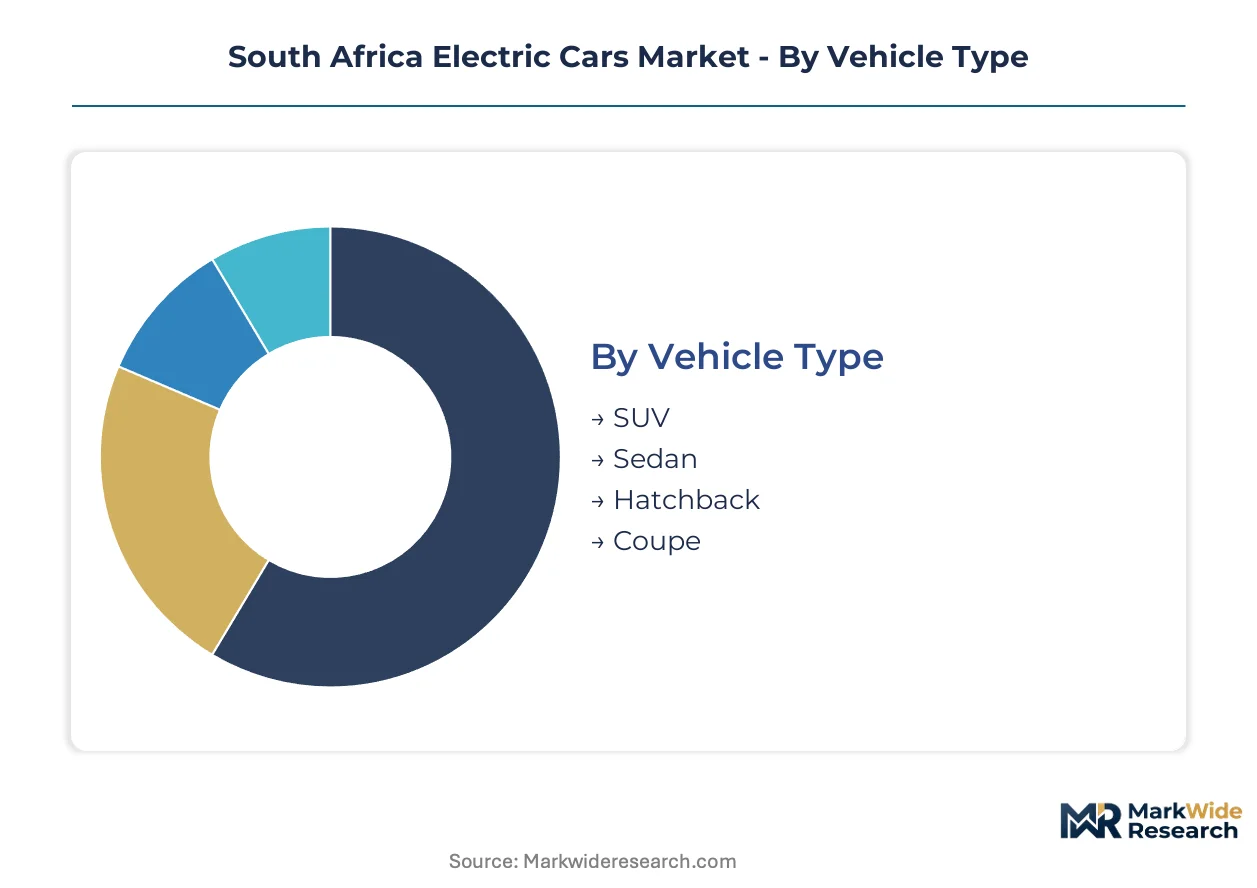
Segmentation in South Africa's electric car market reveals how infrastructure constraints, battery chemistry trade-offs, and regulatory incentives reshape purchasing patterns across consumer and commercial channels. Understanding these divides exposes where capital is concentrating and which technology bets carry the highest stakes.
Vehicle Type:
Premium positioning and larger battery configurations concentrate margin pools in higher-body-style segments where range anxiety buffers justify price premiums.
- SUV:Higher ground clearance and larger battery bay capacity accommodate 75kWh+ packs that extend inter-provincial range. Gauteng province's suburban buyers dominate early adoption, drawn by status signaling and family utility.
- Sedan:Aerodynamic efficiency and lower center of gravity optimize highway energy consumption for corporate fleet procurement. Johannesburg and Cape Town metropolitan operators prioritize sedan formats for executive transport and ride-hailing applications.
- Hatchback:Compact dimensions suit urban parking constraints in dense Pretoria and Durban cores. Fleet managers specify hatchbacks for last-mile delivery where maneuverability outweighs range requirements.
- Coupe:Limited-volume performance variants target affluent early adopters in Sandton and Umhlanga precincts. Niche positioning constrains charging infrastructure operator interest in dedicated corridor deployment.
The dominant share belongs to SUV, while hatchback is closing the gap fastest through fleet procurement standardization.
Charging Infrastructure:
Utilization rates and capital recovery timelines vary sharply by installation location, with highway corridor assets commanding premium pricing power.
- Fast Charging Stations:DC fast chargers along the N1 and N3 corridors enable commercial fleet inter-provincial operations. Eskom tariff structures and grid reliability constraints outside metropolitan cores deter rural rollout sequencing.
- Home Charging:Level 2 AC installations dominate existing owner bases in Johannesburg's northern suburbs and Cape Town's Atlantic seaboard. Residential solar PV pairing reduces effective energy costs for early adopters with rooftop capacity.
- Public Chargers:Shopping mall and workplace deployments concentrate in Gauteng's retail corridors. Slow AC units serve dwell-time charging for suburban commuters with predictable parking durations.
- Wireless Charging:Inductive pad technology remains pilot-stage for premium fleet depots in Port Elizabeth's Coega zone. Standardization gaps between OEM systems limit interoperability and infrastructure investor confidence.
Fast charging stations capture the steepest deployment curve, though home charging retains the largest installed base among existing owners.
Battery Type:
Cathode chemistry selection directly determines cost structures and thermal management requirements across South Africa's temperature extremes.
- Lithium-Ion:Nickel-manganese-cobalt and lithium-iron-phosphate variants constitute virtually all current production. LFP chemistry is displacing NMC in fleet vans where cycle life priorities override energy density requirements.
- Solid-State:Next-generation ceramic electrolyte designs promise enhanced safety margins and faster charging rates. SABS certification timelines for novel cell formats extend market access delays beyond conventional lithium-ion approval cycles.
- Lead-Acid:Low-voltage auxiliary applications persist in legacy vehicle electrification retrofits. Cost sensitivity in informal sector conversions sustains limited demand despite poor energy density.
- Nickel-Metal Hydride:Hybrid-electric vehicle legacy technology retains niche presence in Toyota's local assembly considerations. Full battery-electric transition is displacing NiMH from new vehicle development pipelines.
Lithium-ion configurations command absolute volume dominance, with solid-state positioned as the technology trajectory to watch pending regulatory clearance.
Market Player:
APDP incentive eligibility and local content thresholds reshape competitive positioning between domestic assembly and import-dependent market entry strategies.
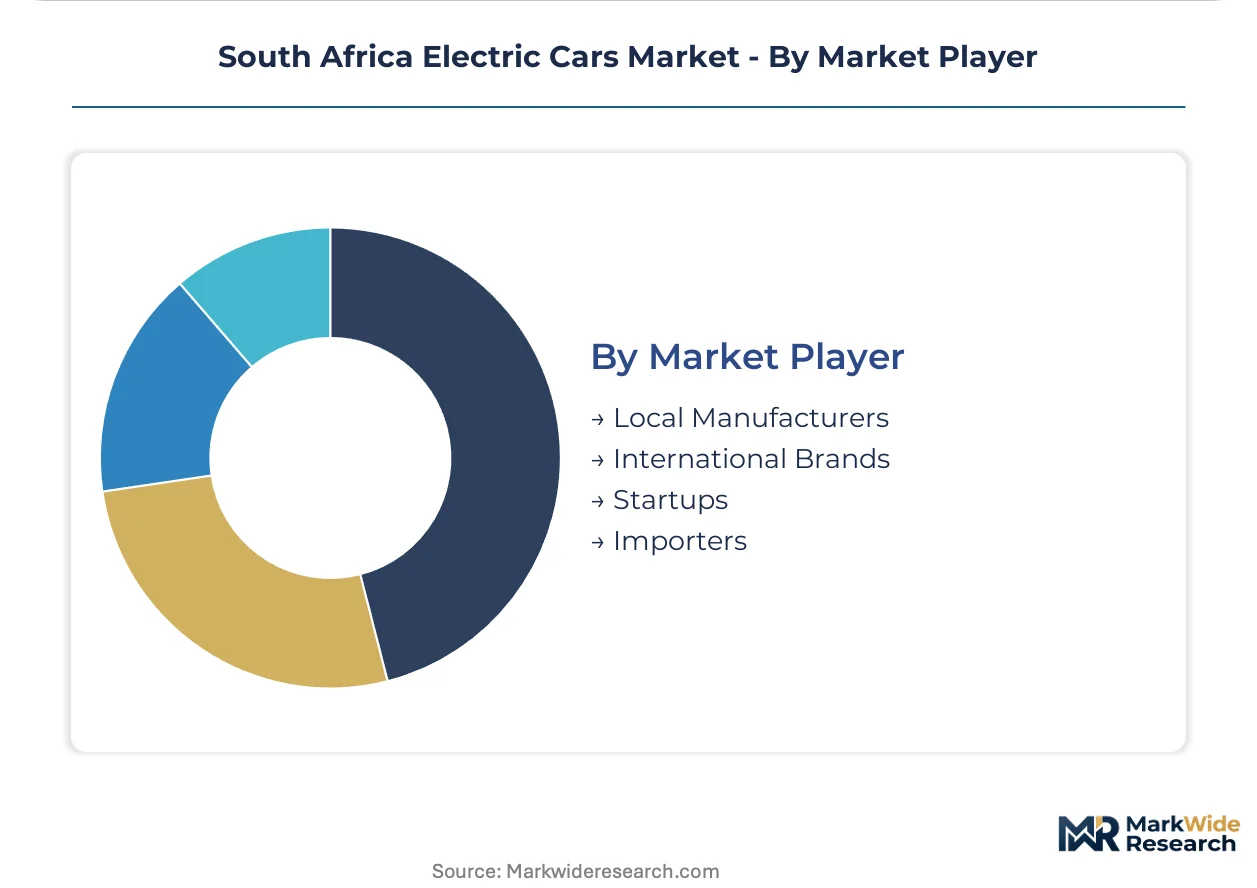
- Local Manufacturers:Rosslyn and Coega assembly plants qualify for Department of Trade, Industry and Competition incentive structures. BMW Group and Volkswagen Group leverage existing footprints to satisfy supplier development targets.
- International Brands:OEMs with established distribution networks navigate SABS electromagnetic compliance testing before market entry. Nissan Motor Corporation competes through Leaf distribution channel depth and dealer network coverage.
- Startups:Domestic EV conversion specialists target informal sector minibus electrification in township transport corridors. Capital constraints and high-voltage technician scarcity limit scale-up velocity.
- Importers:Parallel import channels introduce Chinese-manufactured right-hand-drive variants outside OEM authorized distribution. Warranty and charging standard compatibility gaps create aftermarket service fragmentation.
International brands hold established share leadership, though local manufacturers are expanding most quickly through APDP-compliant assembly investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Automotive Production and Development Programme's local content thresholds redirect OEM investment toward domestic EV assembly, concentrating manufacturing in Gauteng's industrial corridor while conditioning incentive eligibility on supplier development targets.
Gauteng Province
Johannesburg and Pretoria metropolitan areas concentrate the bulk of charging infrastructure deployment and early consumer demand. The Department of Trade, Industry and Competition administers APDP incentive structures that tie market access to local manufacturing commitments. Rosslyn's automotive cluster anchors BMW Group's assembly footprint for right-hand-drive electric vehicle production.
Western Cape
Cape Town's metropolitan fleet operators scale battery-electric van acquisitions as energy operating costs undercut diesel equivalents across high-mileage duty cycles. Provincial government tenders now standardize energy-as-a-service contracts that separate capital expenditure from operational expenditure. The Atlantic seaboard's residential solar PV pairing reduces effective charging costs for early adopters with rooftop capacity.
Eastern Cape
Port Elizabeth's Coega Industrial Development Zone offers tariff-free import status and dedicated renewable energy supply for secondary EV assembly outside Gauteng concentration. The zone's industrial development incentives position it as an alternative manufacturing node for OEMs seeking to diversify beyond the northern provinces. Local content requirements under APDP Phase 2 accelerate supplier qualification for battery pack assembly in the region.
KwaZulu-Natal
Durban's urban core generates hatchback demand from fleet managers prioritizing maneuverability in dense metropolitan parking constraints. Eskom's grid reliability constraints degrade charging infrastructure utilization rates outside metropolitan cores, deterring private investment in rural rollout sequencing. The N3 highway corridor's DC fast charging deployment enables commercial fleet inter-provincial operations between Durban and Johannesburg.
South Africa Electric Cars Market Competitive Landscape
Player mix skews toward established automotive OEMs with existing right-hand-drive production capabilities and local assembly footprints. Market structure concentrates around manufacturers capable of satisfying APDP local content thresholds and SABS certification requirements. Strategic archetypes include premium SUV specialists leveraging larger battery configurations, fleet-focused van providers optimizing total cost of ownership, and modular platform adapters serving multiple body styles. Dominant competitive moves encompass backward integration into battery pack assembly and strategic partnerships with charging infrastructure operators.
Among Germany-based automotive groups, BMW Group and Volkswagen Group exemplify the local manufacturing archetype through their Rosslyn assembly investments and APDP-compliant supplier development programs. Nissan Motor Corporation occupies a position representing established distribution network depth, competing through Leaf channel presence and dealer coverage. Tesla Inc sits within the direct-sales technology disruptor tier, navigating SABS electromagnetic compliance timelines that extend market access delays for new entrants.
| Leading Market Players |
|---|
| Tesla Inc |
| BMW Group |
| Volkswagen Group |
| Nissan Motor Corporation |
| Mercedes-Benz Group |
| Hyundai Motor Company |
| Kia Corporation |
| Toyota Motor Corporation |
| Volvo Cars |
| Others |
Value Network & Pricing Analysis
Long-term battery offtake contracts between OEMs and cathode material suppliers lock in both lithium-ion cell access and price visibility across the analysis window, insulating South African assemblers from spot-market volatility while committing capital to fixed-volume obligations. These arrangements concentrate procurement power among APDP-compliant manufacturers with sufficient scale to negotiate tier-one supplier status.
Pricing Analysis
Certification level creates the primary spread between SABS-compliant assembly and parallel import channels. Three-tier pricing structure across premium SUV, standard sedan, and economy hatchback levels reflects battery capacity differentials and local content thresholds. Cost compression in entry-segment hatchbacks is intensifying because cathode material volatility feeds directly into pack economics. Fleet procurement departments exhibit highest price sensitivity, while individual consumers in Gauteng's northern suburbs absorb premium positioning for range assurance.
Supply Chain Analysis
Inventory lead times for lithium-ion cells extend from East Asian cathode plants through Durban port clearance, compressing working capital cycles for domestic assemblers. Battery cell supply concentrates in China, South Korea, and Japan, with South African pack assembly drawing from imported NMC and LFP cell formats. Nickel and cobalt price volatility constitutes the dominant supply chain risk. Distribution runs through OEM-captive logistics networks serving authorized dealerships, constraining aftermarket parts availability for parallel import channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The national pipeline for high-voltage certified technicians constrains after-sales network expansion, creating a bottleneck that limits market penetration velocity regardless of manufacturing capacity additions.
For Market Incumbents: Consolidate backward integration into battery pack assembly within Gauteng and Eastern Cape industrial zones to satisfy APDP Phase 2 local content thresholds. Lock in long-term offtake agreements with nickel and lithium suppliers before commodity cycle upswings compress margin structures. Prioritize technician training partnerships with technical vocational institutions to preempt service network constraints. For New Entrants and Emerging Players: Differentiate on charging infrastructure interoperability, targeting fleet operators frustrated by proprietary connector fragmentation across incumbent OEM networks. The most penetrable white-space sits in second-life battery storage integration with commercial solar PV installations in Western Cape and KwaZulu-Natal. Pursue energy-as-a-service contract structures that separate hardware acquisition from operational expenditure. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale charging infrastructure operators with established N1 and N3 corridor positioning and utility interconnection approvals in hand. Long-term viability hinges on grid reliability improvement trajectories and Eskom tariff reform momentum. The signal to watch is municipal fleet tender standardization around total-cost-of-ownership metrics versus upfront capital requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures cathode cell volumes from East Asian suppliers for Rosslyn and Coega pack assembly. |
| Charging Infrastructure Partnership | Locks DC fast charging corridor deployment along N1 and N3 highways for fleet range assurance. |
| Platform Standardization | Enables right-hand-drive variants for Commonwealth African export markets without plant retooling. |
| Geographic Manufacturing Footprint | Diversifies assembly capacity to Coega IDZ to reduce Gauteng concentration risk. |
| Software-Defined Vehicle Investment | Supports over-the-air update capability and battery management system optimization for local conditions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SABS certification databases, Department of Trade Industry and Competition incentive disclosures, Eskom tariff filings, and vehicle registration records. Primary interviews engaged OEM platform engineers, Tier 1 supplier procurement leads, charging infrastructure operators, fleet procurement managers, and high-voltage technician training program directors. Bottom-up triangulation across production volume estimates and top-down validation against incentive uptake data ensure consistency.
Segmentation dimensions modeled span vehicle class, battery chemistry configuration, charging infrastructure type, and regional production cluster across the analysis window. CAGRs derive from production capacity buildout schedules, APDP Phase 2 incentive qualification timelines, and fleet replacement cycle assumptions. Forecast inputs incorporate grid reliability improvement scenarios and municipal tender standardization trajectories.
The analysis sits within stated boundaries; outcomes outside sustained APDP incentive continuity or accelerated grid stabilization would require recalibration. Forecasts reflect documented assumptions regarding cathode material cost trajectories and charging infrastructure deployment sequencing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Right Hand Drive Electric Vehicle Market
Electric Vehicles
Electric Transporters Market
Electric Vehicles
Electric Vehicle (EV) Battery Housing Market
Electric Vehicles
China NEV Taxi Market
Electric Vehicles
India Electric Rickshaw Market
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
Busbar for EV Market
Electric Vehicles
Automotive Electric Vehicle Power System Market
Electric Vehicles
Vehicle-To-Grid (V2G) Market
Electric Vehicles
Bus Pantograph Charger Market
Electric Vehicles
Battery Electric Vehicle (BEV) Market
Electric Vehicles
Commercial Vehicle Traction Battery Systems Market
Electric Vehicles
Central and Eastern Europe E-Bike Market
Electric Vehicles
APAC E-Bikes Market
Electric Vehicles
Mexico Electric Bus Market
Electric Vehicles
Global Solar Powered Car Market