
 RV SLI Battery Market | 2026-2036
RV SLI Battery Market Size, Share, and Industry Trends Forecast 2026-2036
RV SLI Battery Market Insights
Dealership service channels is tilting toward bundled battery replacement programs as RV ownership extends beyond traditional warranty periods. Exide Technologies leverages its North American distribution footprint to sustain aftermarket visibility. Clarios anchors its position through private-label partnerships with major RV original equipment manufacturers. East Penn Manufacturing competes on manufacturing scale, operating one of the largest single-site battery production facilities in the region.
RV SLI batteries are engineered for starting, lighting, and ignition functions in recreational vehicles, typically delivering cold cranking amperage ratings between 650 and 1,000 CCA and operating on 12-volt lead-acid or lithium-ion architectures designed to withstand deep-cycle demands and vibration stress during mobile deployment. Lead Acid chemistry dominates installed base economics due to replacement familiarity and recycling infrastructure, though Lithium-ion segments capture margin expansion from weight-sensitive premium motorcoach buyers. Absorbent Glass Mat variants lead technology migration paths where maintenance-free operation commands price premiums in rental fleet applications.
FCC equipment authorization requirements govern integrated battery management electronics, while EPA hazardous waste regulations under the Resource Conservation and Recovery Act shape end-of-life collection and recycling obligations for lead-acid chemistries. California Air Resources Board zero-emission vehicle mandates indirectly pressure SLI suppliers to document supply chain carbon intensity. Stakeholders must weigh chemistry transitions against existing recycling economics and service technician retraining requirements.
Market Dynamics
The RV SLI battery market is experiencing a chemistry transition tension as lithium-ion architectures penetrate premium motorcoach segments while lead-acid retains aftermarket economics through established recycling infrastructure and technician familiarity.
Growth Catalysts
- California's Advanced Clean Trucks Regulation:Fleet operators across the Sun Belt face compliance pressure that accelerates adoption of lower-emission battery chemistries in Class A motorhomes.
- Absorbent Glass Mat Technology:Rental fleet operators prioritize maintenance-free operation, creating pull-through demand for sealed lead-acid variants that reduce field service costs.
- Extended RV Ownership Cycles:Motorhome retention beyond warranty periods generates recurring aftermarket battery replacement demand through dealership service channels.
Market Restraints
- Lead-Acid Recycling Infrastructure Lock-In:Existing EPA hazardous waste collection networks under the Resource Conservation and Recovery Act create switching costs for alternative chemistry adoption.
- Lithium-Ion Raw Material Concentration:Cathode material supply chains concentrate in limited geographies, exposing battery assemblers to input price volatility and geopolitical sourcing risk.
- Cold Cranking Amperage Specification Inertia:Engine starting protocols in legacy RV powertrains limit voltage architecture flexibility, constraining pure lithium drop-in replacement feasibility.
Strategic Opportunities
- Smart Battery Management Integration:FCC equipment authorization requirements for integrated electronics create white space for suppliers offering telematics-enabled state-of-charge monitoring.
- Weight-Sensitive Motorcoach Premiumization:High-end Class A buyers absorb lithium-ion price premiums to achieve chassis weight reduction and extended cycle life.
- Private-Label OEM Partnerships:Battery manufacturers can capture forward-margin positions through exclusive supply arrangements with major RV original equipment manufacturers.
Industry Challenges
- Technician Certification Gaps:Service networks face retraining burdens as high-voltage lithium systems require specialized handling protocols distinct from traditional lead-acid maintenance.
- Supply Chain Carbon Documentation:California Air Resources Board zero-emission vehicle mandates pressure suppliers to establish auditable supply chain carbon intensity metrics without standardized reporting frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RV SLI Battery Market |
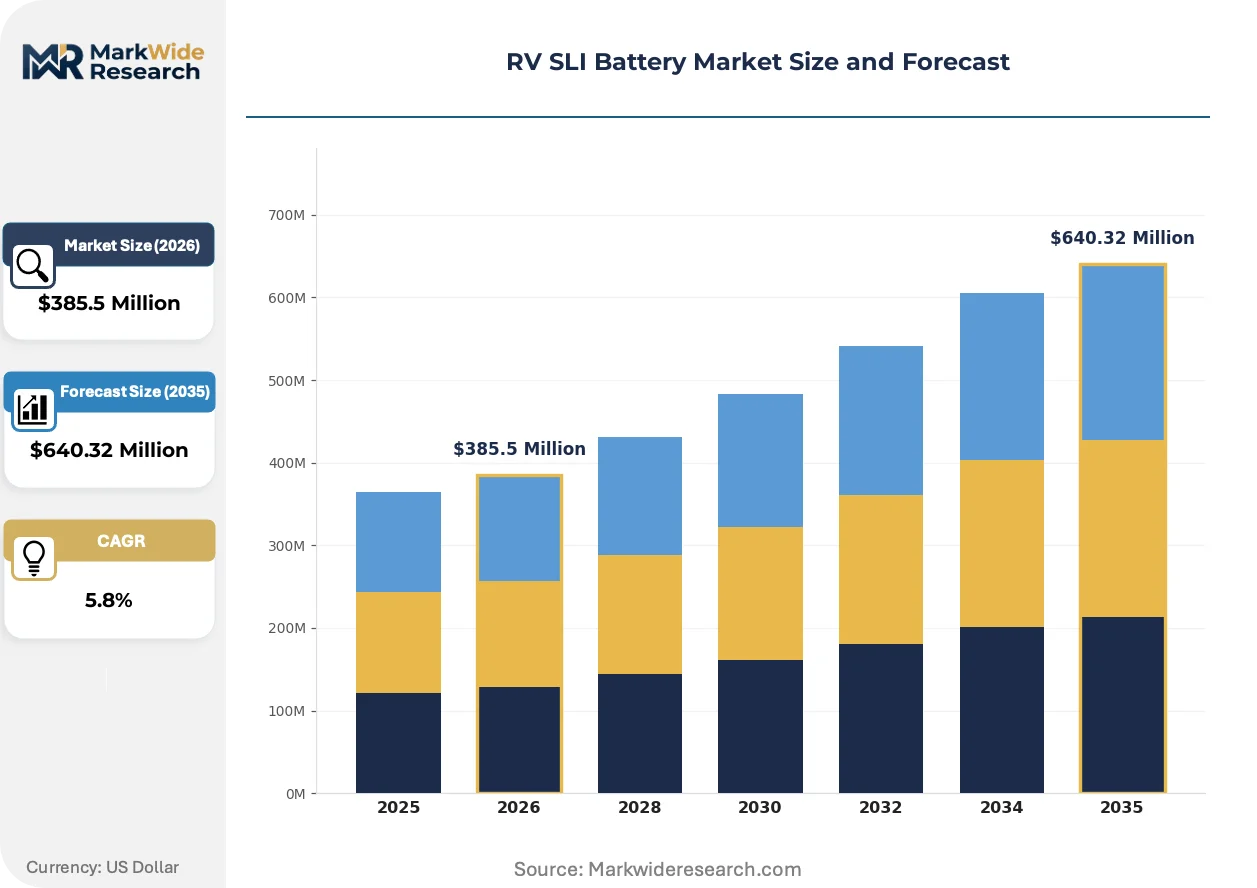
| Market Size in 2026 | $385.5 Million |
| Market Size in 2035 | $640.32 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Recreational Vehicles, Marine Vehicles, Golf Carts, Agricultural Equipment Battery Type: Lead Acid, Lithium-ion, Gel, Absorbent Glass Mat End User: Consumers, Commercial Fleets, Rental Services, Dealerships Technology: Manufacturing, Energy Storage Solutions, Smart Batteries, Hybrid Systems |
| Companies Covered | Exide Technologies, East Penn Manufacturing, Clarios, GS Yuasa, Amara Raja Group, Johnson Controls, EnerSys, Ruiyu Battery, Camel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RV SLI Battery Market Trends and Innovations
Active chemistry hybridization is reshaping product architectures as manufacturers balance performance differentiation against service infrastructure constraints. Three distinct movements define this transition.
Absorbent Glass Mat lead-acid technology is hybridizing with thin-plate pure lead construction to deliver enhanced cycle durability without abandoning existing recycling networks. Rental fleet operators in Arizona and Florida adopt these intermediate solutions to reduce watering labor while avoiding lithium-ion service complexity. The result compresses pure lithium penetration timelines in mid-market motorcoach segments.
EPA hazardous waste regulations under the Resource Conservation and Recovery Act are tightening end-of-life documentation requirements for lead-acid batteries. Battery assemblers must now maintain chain-of-custody records through smelter processing, increasing administrative overhead but reinforcing incumbent recycler relationships. Aftermarket service channels in Texas and California bear the primary compliance burden through manifest tracking systems.
Commercial fleet procurement is consolidating battery specification authority at the national level rather than delegating to regional maintenance managers. Large RV rental operators now mandate single chemistry standards across their Sun Belt depots, displacing fragmented local sourcing. This concentration is most visible among multi-state operators seeking uniform training and inventory economies.
RV SLI Battery Market Segmentation
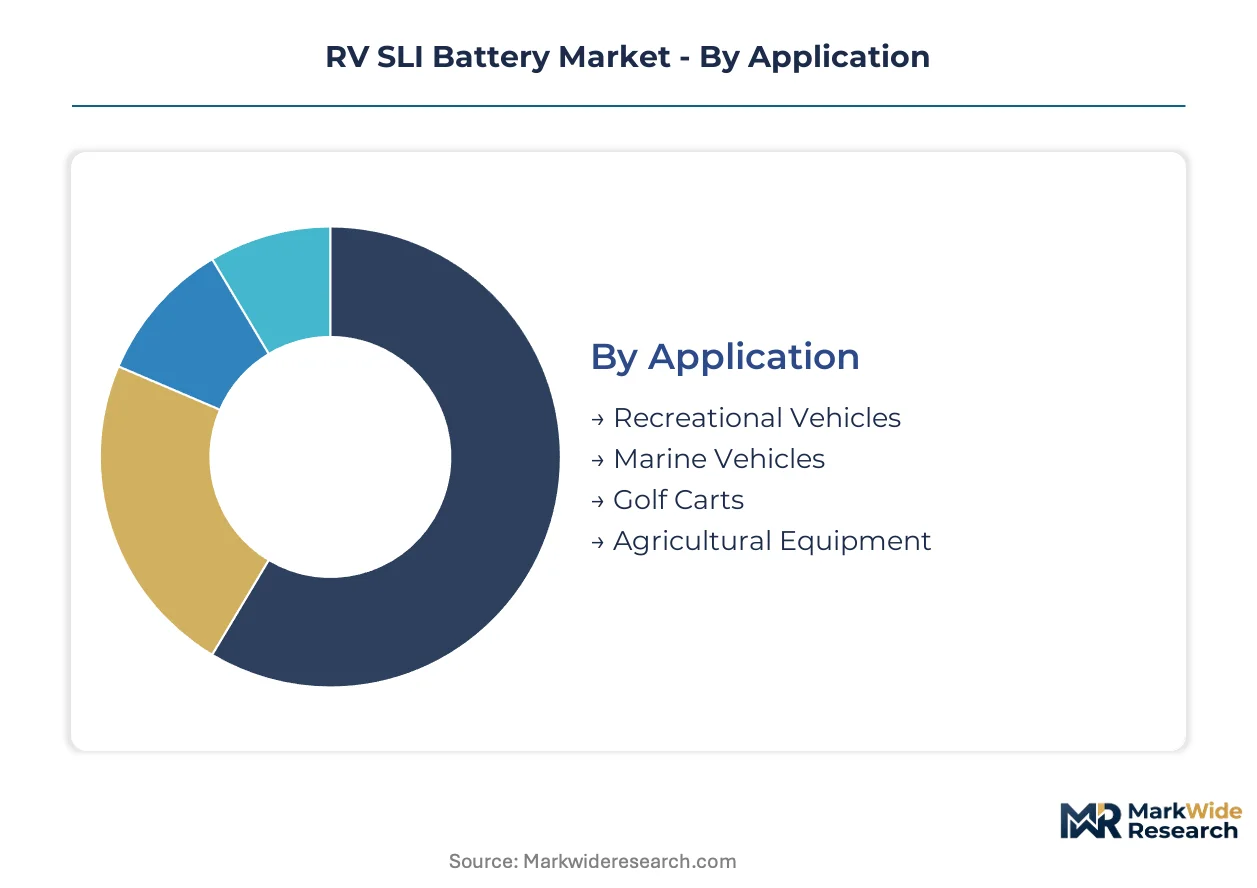
RV SLI battery segmentation reveals distinct performance requirements across mobile power applications. Chemistry selection and end-user procurement patterns create divergent margin structures within each category.
Application:
Application segmentation distinguishes duty cycles, vibration exposure, and depth-of-discharge tolerance across mobile equipment categories.
- Recreational Vehicles:Engine starting, lighting, and ignition functions dominate with cold cranking amperage ratings between 650 and 1,000 CCA. Demand concentrates among Class A motorhome owners in Arizona and Florida where extended boondocking requires reserve capacity tolerance.
- Marine Vehicles:Dual-purpose starting and house loads require sealed construction resisting salt corrosion and bilge exposure. Boatbuilders in the Great Lakes region specify Absorbent Glass Mat variants for maintenance-free operation in confined engine compartments.
- Golf Carts:Deep-cycle duty profiles favor flooded lead-acid economics for fleet replacement at municipal courses and private clubs.
- Agricultural Equipment:Seasonal starting loads and extended idle periods drive replacement cycles in harvester and tractor applications across Midwest farming operations.
Recreational Vehicles holds installed capacity. Marine Vehicles is rotating up the share rankings.
Battery Type:
Cost tier stratification separates mature recycling economics from premium performance architectures.
- Lead Acid:Flooded and sealed variants leverage established EPA hazardous waste collection networks under the Resource Conservation and Recovery Act. Replacement familiarity among independent service technicians sustains aftermarket dominance across price-sensitive consumer segments.
- Lithium-ion:Cathode chemistry variations deliver weight reduction and cycle life extension for premium motorcoach specifications. High-end Class A buyers absorb price premiums to achieve chassis weight targets and extended dry camping autonomy.
- Gel:Electrolyte immobilization suits deep-cycle applications in marine and solar hybrid configurations where spill resistance commands specification priority.
- Absorbent Glass Mat:Thin-plate pure lead construction enhances vibration durability for rental fleet duty cycles. Arizona and Florida operators adopt these intermediate solutions to reduce field service labor without lithium-ion complexity.
Lead Acid commands volume share. Lithium-ion is climbing the fastest on value contribution.
End User:
Customer type determines procurement authority concentration and service channel preferences.
- Commercial Fleets:National procurement consolidation mandates single chemistry standards across multi-state depot networks. Large rental operators standardize on Absorbent Glass Mat to achieve uniform training and inventory economies.
- Consumers:Individual motorhome owners rely on dealership service channels for warranty-adjacent replacement and chemistry upgrade guidance. Extended ownership beyond warranty periods generates recurring aftermarket demand.
- Rental Services:High-utilization duty cycles prioritize maintenance-free operation and predictable replacement intervals. Fleet managers negotiate volume pricing through direct manufacturer relationships.
- Dealerships:Service departments capture margin through bundled battery replacement programs as RV ownership extends beyond traditional warranty coverage.
Commercial Fleets anchor procurement volume. Consumers is expanding most quickly in replacement frequency.
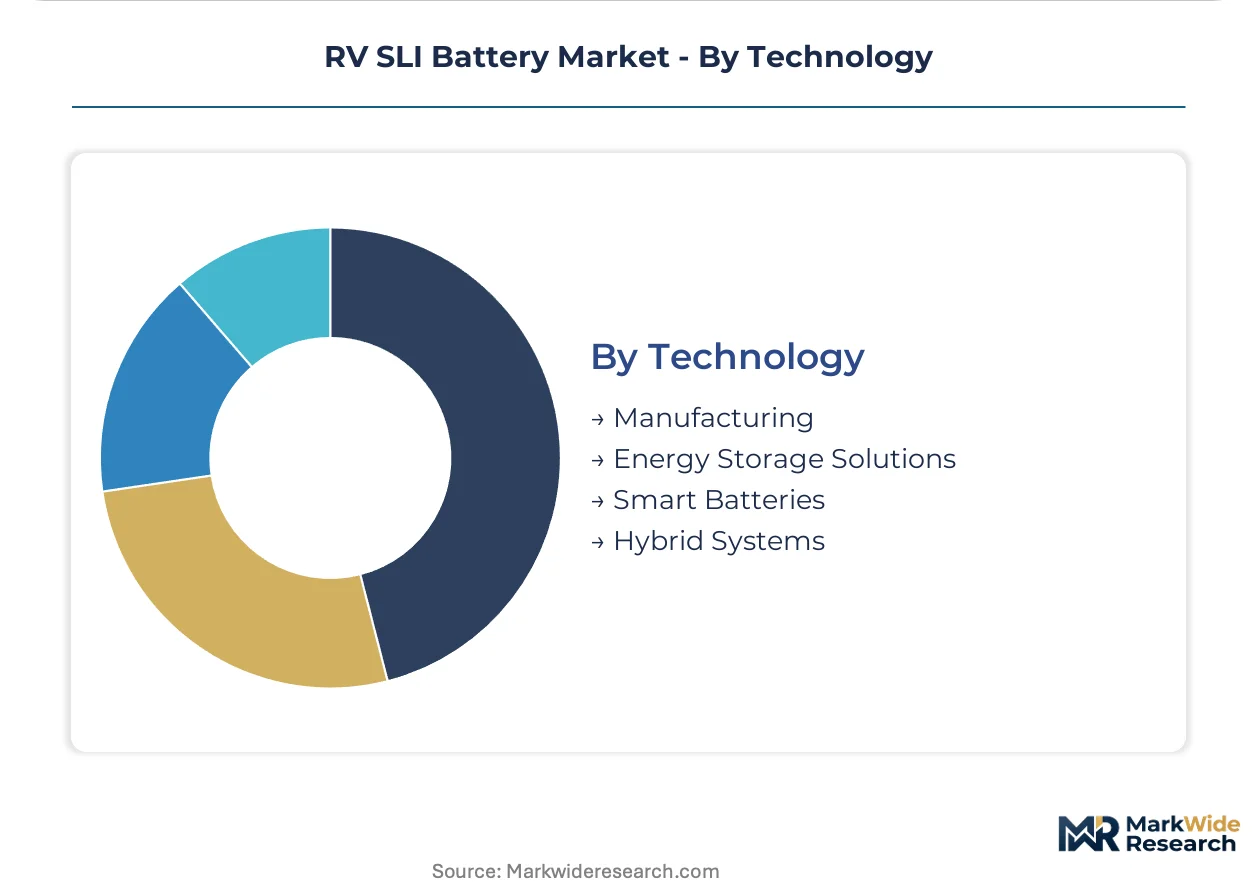
Technology:
Technology maturity separates commodity assembly from integrated electronics and system-level optimization.
- Smart Batteries:Integrated battery management electronics require FCC equipment authorization for telematics-enabled state-of-charge monitoring. Suppliers capture white space through connected diagnostics serving fleet telematics platforms.
- Manufacturing:Plate casting, formation, and assembly operations concentrate in high-volume facilities serving private-label OEM partnerships and aftermarket channels.
- Energy Storage Solutions:Pack-level integration addresses house bank and inverter compatibility for off-grid motorcoach configurations.
- Hybrid Systems:Dual-chemistry architectures combining lead-acid starting with lithium house banks serve specialized overland and expedition vehicle builds.
Manufacturing holds capacity scale. Smart Batteries is gaining share fastest on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where Class A motorhome owners absorb technology premiums, while Canadian operators face compressed margins from cross-border logistics costs and smaller fleet scale.
United States
Class A motorhome demand clusters in Arizona and Florida where extended boondocking drives reserve capacity requirements. EPA hazardous waste regulations under the Resource Conservation and Recovery Act mandate chain-of-custody documentation through smelter processing. The Sun Belt corridor from Phoenix to Tampa anchors aftermarket service channel density for battery replacement programs.
Canada
Seasonal RV usage patterns in British Columbia and Ontario create concentrated spring replacement cycles. Health Canada and Environment Canada administer the Canadian Environmental Protection Act for battery recycling compliance. The Greater Toronto Area hosts distribution hubs serving cross-border fleet operators with standardized Absorbent Glass Mat specifications.
Germany
European motorcoach manufacturers source SLI batteries for export-oriented premium chassis production. REACH regulations govern chemical substance registration for electrolyte formulations and separator materials. Baden-Württemberg's automotive supplier cluster integrates battery logistics into RV OEM supply chains serving North American markets.
China
Domestic RV adoption remains nascent but battery component exports supply global assembler networks. MIIT oversees GB standards for lithium-ion cell safety certification and manufacturing quality. The Yangtze River Delta manufacturing belt produces electrode materials and separator films for international battery packagers.
Mexico
Cross-border commercial fleet operations create demand for standardized battery specifications compatible with US depot networks. SEMARNAT administers hazardous waste regulations aligned with EPA frameworks for lead-acid recycling. Nuevo León's industrial corridor hosts assembly operations serving North American aftermarket distributors.
RV SLI Battery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying cells and materials to branded packagers. The vendor base organizes around three archetypes: multinational battery conglomerates with private-label OEM partnerships, regional manufacturers competing on production scale, and emerging lithium specialists targeting premium motorcoach segments. Consolidation pressures intensify as fleet procurement centralization favors suppliers with national service networks. Strategic moves concentrate on backward integration into electrode materials and captive recycling infrastructure.
Within the multinational tier, Exide Technologies represents the North American distribution footprint archetype, while Clarios exemplifies private-label OEM partnership models. East Penn Manufacturing anchors the scale-driven regional manufacturer position with concentrated single-site production capacity. These three companies collectively illustrate how incumbent lead-acid specialists navigate chemistry transition tensions while defending aftermarket economics through established recycling relationships and technician training networks.
| Leading Market Players |
|---|
| Exide Technologies |
| East Penn Manufacturing |
| Clarios |
| GS Yuasa |
| Amara Raja Group |
| Johnson Controls |
| EnerSys |
| Ruiyu Battery |
| Camel Group |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta manufacturing belt anchors global electrode material supply, with its concentration of separator film and cathode precursor production translating directly into pricing leverage for battery assemblers serving North American RV OEMs. This geographic lock-in amplifies cost pass-through dynamics when lithium carbonate and cobalt sulfate contracts reprice, compressing margins for distributors unable to secure long-term offtake agreements.
Pricing Analysis
Configured-to-order lithium-ion packs for premium Class A motorcoaches command spreads exceeding standard flooded lead-acid replacements by factors tied to cathode chemistry grade and integrated battery management certification tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by cold cranking amperage specification, maintenance-free sealing technology, and telematics integration. Cost compression in mid-market Absorbent Glass Mat segments is intensifying because rental fleet operators consolidate procurement at national scale. Independent motorhome owners exhibit highest price sensitivity, while commercial fleet managers prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for lithium-ion cell imports, forcing battery packagers to qualify alternative electrode material sources in South Korea and Japan. Raw material dependencies center on lithium carbonate from Chilean and Australian brine operations, cobalt hydroxide from the Democratic Republic of Congo, and copper foil rolling capacity concentrated in Chinese coastal provinces. Single-source vulnerability in separator film supply creates chokepoint risk for AGM variants dependent on Japanese polypropylene substrate. Distribution runs through regional battery distributors serving independent service technicians, with national fleet accounts bypassing intermediaries through direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RV SLI battery market functions as a defensive-moat industry where EPA hazardous waste recycling infrastructure under the Resource Conservation and Recovery Act creates regulatory entrenchment that protects incumbent lead-acid specialists from rapid chemistry displacement.
For Market Incumbents: Entrench market position by deepening captive recycling infrastructure partnerships with EPA-authorized smelters, creating switching cost barriers against lithium-ion challengers. Add thin-plate pure lead capacity at existing single-site manufacturing complexes to defend margin position against intermediate AGM hybrids. The threat of lithium raw material price volatility and technician certification gaps constrains pure lithium penetration timelines. For New Entrants and Emerging Players: Smart battery management integration for telematics-enabled fleet monitoring represents the most penetrable entry point, bypassing entrenched lead-acid recycling relationships. Target commercial rental operators in Arizona and Florida seeking predictive state-of-charge diagnostics without full lithium conversion. Go-to-market execution should emphasize FCC equipment authorization expertise and direct integration with fleet telematics platforms. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electrode material suppliers and battery management system developers over pure cell assemblers. Long-term viability rests on chemistry-agnostic platform capabilities spanning lead-acid optimization and lithium-ion integration. Acquisition targets should demonstrate backward integration into separator substrates or cathode precursor synthesis. The signal to watch is California Air Resources Board zero-emission vehicle mandate expansion into commercial vehicle auxiliary power systems.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Material Backward Integration | Captive lithium iron phosphate precursor production insulates margin from Qinghai and Sichuan spot market swings. |
| Smart Battery Management Platform Launch | FCC-authorized telematics modules enable recurring software revenue from rental fleet state-of-charge monitoring contracts. |
| EPA Recycling Infrastructure Partnership | Exclusive smelter arrangements create compliance moats that delay lithium-ion substitution in aftermarket channels. |
| Private-Label OEM Supply Agreement | Exclusive Class A motorcoach specifications lock forward volume through chassis production cycles at Indiana manufacturing clusters. |
| Technician Certification Program Expansion | High-voltage handling credentials address liability barriers constraining lithium service adoption at independent dealerships. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement directors at multi-state RV rental operators, battery distribution channel managers, EPA-authorized recycling facility operators, and independent service technicians in Sun Belt states. Secondary validation drew from EPA Resource Conservation and Recovery Act enforcement data, FCC equipment authorization filings, California Air Resources Board regulatory dockets, and trade flow records for lithium carbonate and lead scrap. Bottom-up volume estimates from individual application segments were triangulated against top-down manufacturer capacity disclosures.
Calibration against historical replacement cycle data and fleet retention patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include chemistry type, application duty cycle, end-user procurement authority, and regional regulatory cluster. CAGRs were derived from installed base turnover rates, technology substitution curves, and price elasticity assumptions specific to commercial fleet versus consumer replacement behavior. Forecast inputs incorporated California Advanced Clean Trucks regulation compliance timelines and lithium-ion cell cost learning curve trajectories.
Practitioners should monitor cathode material contract repricing and EPA hazardous waste documentation requirement amendments for early signals of margin compression or compliance burden shifts. Forecasts reflect assumptions about technician training pipeline capacity and fleet procurement centralization velocity that could revise trajectory if lithium raw material supply disruptions accelerate chemistry transition timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Loader Rickshaw Market
Electric Vehicles
Electric Vehicle NVH Material Market
Electric Vehicles
Global Electric Light Commercial Vehicles Market
Electric Vehicles
Pedelec Market
Electric Vehicles
Electric Bus Market
Electric Vehicles
High-Performance Electric Sports Cars Market
Electric Vehicles
Global Smart Electric Drive Market
Electric Vehicles
Australia Electric Vehicle Market
Electric Vehicles
E-Bike Accessories Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
South America Electric Vehicles Market
Electric Vehicles
Canada Solar E-Bike Market
Electric Vehicles
North America Electric Vehicle Market
Electric Vehicles
EV Transmission System Market
Electric Vehicles
Automotive Intelligent Battery Sensor Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market