
 Electric Vehicle Liquid-Cooled Charging Connector Market | 2026-2036
Electric Vehicle Liquid-Cooled Charging Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Liquid-Cooled Charging Connector Market Insights
Fleet operator consolidation around megawatt-scale charging hubs is restructuring procurement patterns across the value chain. Tesla sustains technology leadership through proprietary connector ecosystems and vertical control over charging hardware. Huber+Suhner specializes in high-frequency cable assemblies that withstand continuous thermal cycling at extreme power densities. Sumitomo Electric Industries anchors Asian supply chains with advanced liquid-cooled conductor architectures.
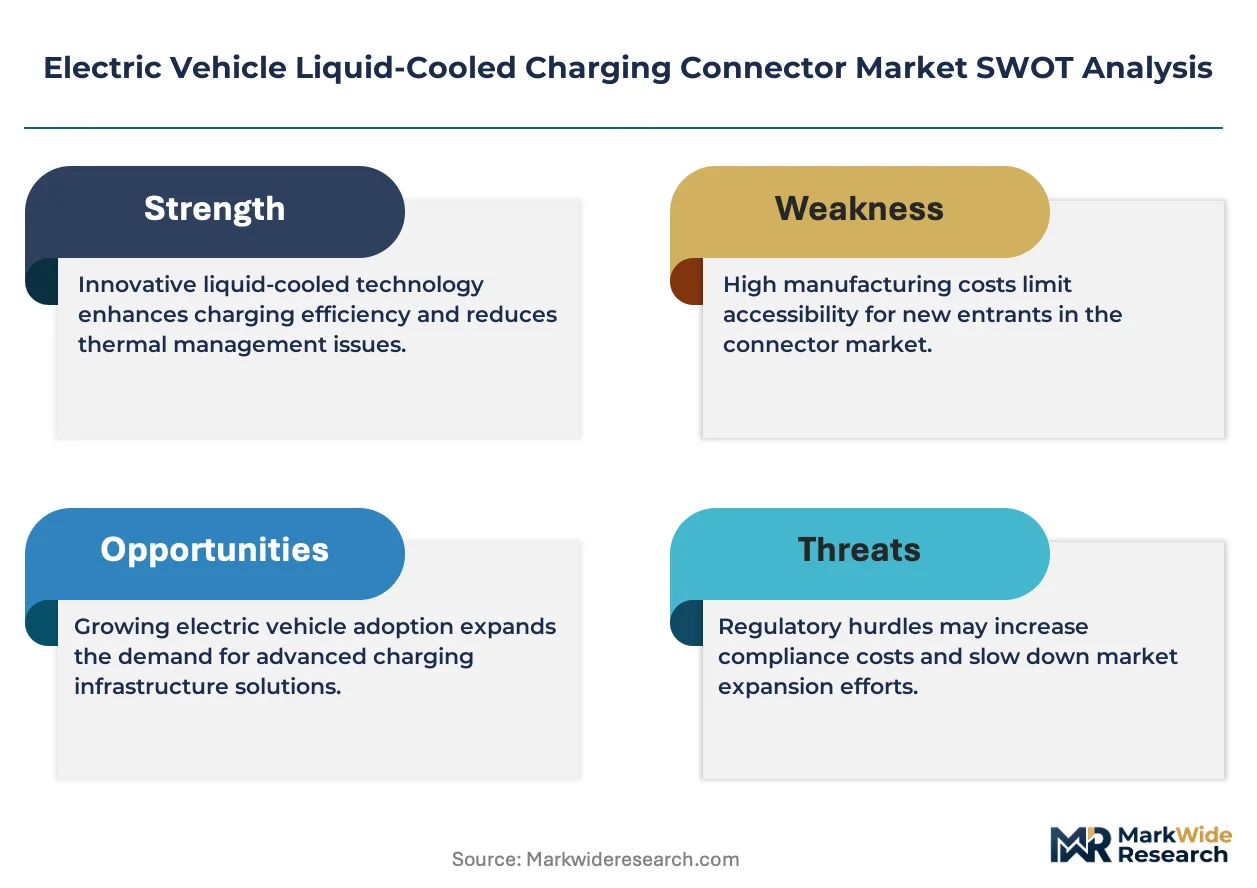
An electric vehicle liquid-cooled charging connector is a thermally managed electrical interface that circulates dielectric fluid through internal channels to dissipate heat generated during high-current energy transfer, typically rated for 500 A continuous operation at 1000 V DC. Its primary purpose is to enable safe, sustained ultra-fast charging without thermal degradation of contact surfaces or insulation systems. DC connectors command premium positioning due to their critical role in public fast-charging networks where downtime costs dominate operator economics. Fleet operators represent the fastest-growing end-user category as logistics electrification demands predictable turnaround times incompatible with passive-cooled hardware limitations.
The EU Green Deal and F-Gas Regulation shape European product standards by mandating lower-global-warming-potential coolants and circular design requirements for thermal management components. China's MIIT enforces GB/T connector interoperability standards that dictate physical dimensions and communication protocols for domestic charging infrastructure deployment. Stakeholders must monitor evolving thermal interface material specifications and coolant chemistry restrictions as regulatory bodies tighten environmental performance thresholds for charging equipment.
Market Dynamics
Fleet electrification timelines are compressing procurement cycles for liquid-cooled charging hardware, forcing connector manufacturers to prioritize thermal endurance certifications over incremental cost reductions.
Growth Catalysts
- EU F-Gas Regulation:Mandates for lower-global-warming-potential coolants accelerate R&D investment in dielectric fluid formulations compatible with existing cable architectures.
- Logistics electrification:Heavy-duty fleet operators demand 350 kW+ continuous operation capabilities that passive-cooled connectors cannot sustain.
- China's eastern coastal provinces:Dense ultra-fast charging network deployment by domestic OEMs creates concentrated demand for GB/T-compliant liquid-cooled interfaces.
Market Restraints
- Copper and aluminum price volatility:Conductor material costs constitute 35-45% of bill-of-materials, exposing margins to commodity exchange fluctuations.
- Asian supply concentration:Advanced liquid-cooled conductor architectures depend on specialized extrusion capabilities concentrated in Japanese and South Korean cable facilities.
- Proprietary connector ecosystems:Tesla's closed hardware standards fragment procurement volumes and prevent economies of scale for standardized component suppliers.
Strategic Opportunities
- India's logistics corridors:National highway electrification programs create first-mover advantage for suppliers establishing local assembly partnerships.
- Vehicle-to-grid integration:Bidirectional liquid-cooled connectors enable fleet operators to monetize stationary battery assets during dwell periods.
- EU Green Deal circular design mandates:Modular connector architectures with replaceable thermal interface components qualify for extended producer responsibility incentives.
Industry Challenges
- Multiphysics simulation expertise:Coupled thermal-electric-mechanical modeling capabilities remain scarce among connector engineering teams.
- UL 2251 and IEC 62196-6 certification timelines:Extended validation cycles for 500 A continuous rating tests delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Liquid-Cooled Charging Connector Market |
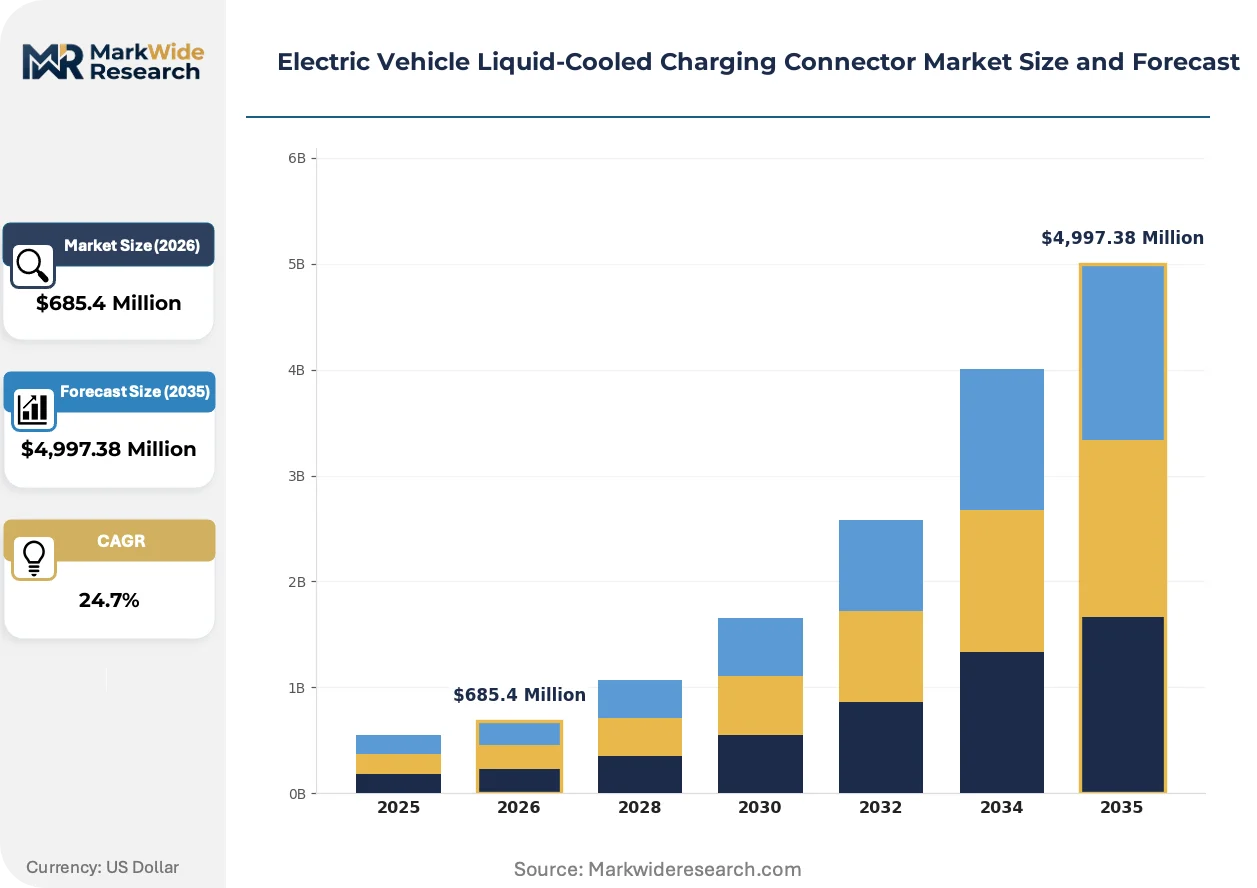
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $4,997.38 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Connector, DC Connector, Combo Connector, Fast Charger Connector End User: Passenger Vehicles, Commercial Vehicles, Buses, Fleet Operators Installation: On-Street, Residential, Commercial, Industrial Technology: Contact Cooling, Liquid Cooling, Air Cooling, Hybrid Systems |
| Companies Covered | Tesla, ITT Cannon, Phoenix Contact, Huber+Suhner, TE Connectivity, ABB, Brugg Cables, Sumitomo Electric Industries, Yazaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Liquid-Cooled Charging Connector Market Trends and Innovations
Silicone-based dielectric fluids are replacing mineral oil coolants in next-generation cable assemblies, driven by fire-safety regulations and thermal stability requirements at extreme power densities.
Immersion-cooled contact architectures are overtaking traditional jacket-cooled designs in heavy-duty fleet applications. These systems eliminate thermal interface resistance between conductors and coolant. Commercial vehicle OEMs in Germany and the Netherlands specify immersion-cooled connectors for megawatt-scale charging hubs. The technology is overtaking conventional approaches by enabling sustained 600 A operation without contact degradation.
China's MIIT enforcement of GB/T 20234.4 interoperability standards is mandating unified communication protocols across domestic charging networks. Connector manufacturers must integrate CAN-based vehicle-infrastructure communication modules. Domestic OEMs and infrastructure operators are accelerating compliance certification to maintain network access privileges.
Lifecycle service contracts are displacing transactional hardware sales in European fleet procurement. Operators negotiate fixed-cost-per-charging-event agreements that bundle connector replacement, coolant monitoring, and thermal performance guarantees. This model concentrates in German and French logistics electrification programs where total-cost-of-ownership transparency dominates capital allocation decisions.
Electric Vehicle Liquid-Cooled Charging Connector Market Segmentation
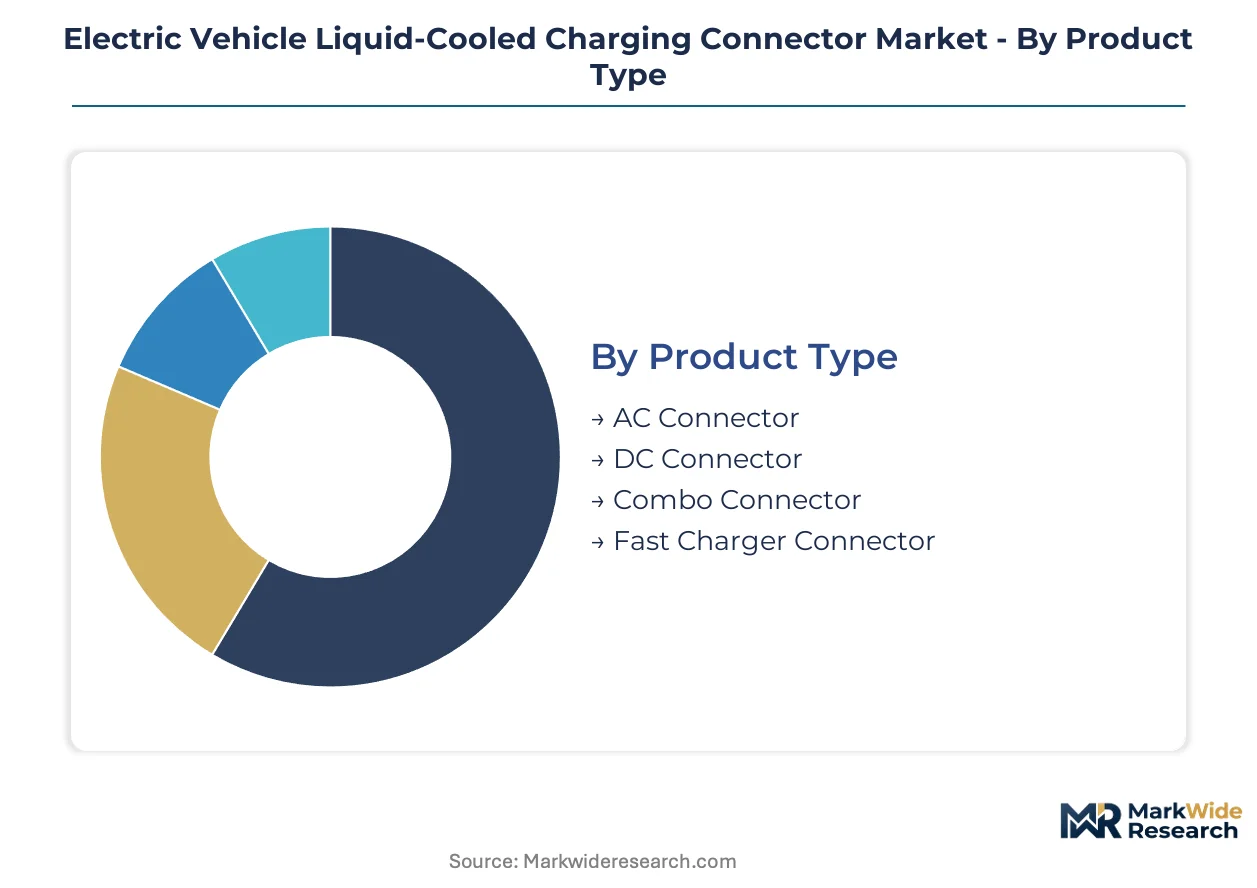
Liquid-cooled charging connectors segment across multiple technical and commercial dimensions that dictate thermal performance requirements, certification pathways, and procurement economics. Product architecture, end-use duty cycles, installation environment, and cooling methodology each impose distinct constraints on connector design and supplier qualification.
Product Type:
UL 2251 and IEC 62196-6 certification requirements vary sharply across connector architectures, with DC and combo variants demanding extended thermal cycling validation that AC designs bypass.
- DC Connector:Engineered for direct current energy transfer at 500 A continuous operation with integrated liquid cooling channels. Public fast-charging networks in Germany and the Netherlands specify these interfaces for 350 kW+ hubs where downtime costs dominate operator economics.
- Combo Connector:Combines AC and DC pins within a unified housing, enabling single-plug compatibility across charging speeds. European fleet operators prioritize combo architectures to simplify vehicle-side inlet standardization and reduce spare parts inventory.
- AC Connector:Passive thermal management suffices for lower-current residential and workplace charging. These connectors avoid liquid cooling complexity and associated maintenance protocols.
- Fast Charger Connector:Optimized for ultra-high-power dispensing with reinforced contact materials and enhanced dielectric fluid circulation rates. China's eastern coastal provinces deploy these at NIO and BYD megawatt-scale charging stations.
DC Connector sits at the top of the volume ranking, with Combo Connector climbing the fastest.
End User:
Cost tiering separates premium thermal endurance specifications for heavy-duty cycles from economy-grade hardware for intermittent residential use.
- Fleet Operators:Logistics electrification programs demand predictable turnaround times incompatible with passive-cooled limitations. These buyers negotiate lifecycle service contracts bundling connector replacement, coolant monitoring, and thermal performance guarantees.
- Commercial Vehicles:Heavy-duty trucks and delivery vans require sustained 350 kW+ operation during depot charging windows. German and Dutch commercial vehicle OEMs specify immersion-cooled architectures for megawatt-scale hub compatibility.
- Buses:Transit electrification mandates drive overnight depot charging infrastructure with standardized connector interfaces.
- Passenger Vehicles:Private ownership patterns favor lower-duty connectors with intermittent thermal loads and minimal liquid cooling complexity.
Fleet Operators command the steepest expansion trajectory, with Commercial Vehicles holding the largest installed base.
Installation:
Application environment dictates IP rating requirements, mechanical protection classes, and thermal management system redundancy levels.
- Industrial:Megawatt-scale charging hubs in logistics corridors require redundant cooling loops and continuous thermal monitoring. India's national highway electrification programs target these installations for first-mover supplier partnerships.
- Commercial:Retail and workplace charging locations balance accessibility with moderate power delivery, deploying mid-tier liquid-cooled connectors for 150-350 kW service.
- On-Street:Urban curbside infrastructure faces vandalism exposure and space constraints, driving compact connector form factors with simplified maintenance access.
- Residential:Single-family and multi-unit dwellings rarely exceed 22 kW delivery, eliminating liquid cooling necessity in most jurisdictions.
Industrial installations lead capital deployment, with Commercial sites expanding most quickly.
Technology:
Maturity curves separate proven jacket-cooled architectures from emerging immersion-cooled designs competing for heavy-duty fleet qualification.
- Liquid Cooling:Circulates dielectric fluid through internal channels to dissipate heat generated during high-current transfer. This approach dominates public fast-charging networks where continuous operation at 1000 V DC and 500 A is mandatory.
- Hybrid Systems:Integrates liquid cooling for high-current pins with passive management for signal contacts, optimizing cost-performance for mid-power applications.
- Contact Cooling:Direct conductor-to-coolant interfaces eliminate thermal interface resistance, enabling sustained 600 A operation in next-generation heavy-duty specifications.
- Air Cooling:Passive convection suffices for low-duty cycles below 150 kW, avoiding fluid maintenance but limiting sustained power delivery.
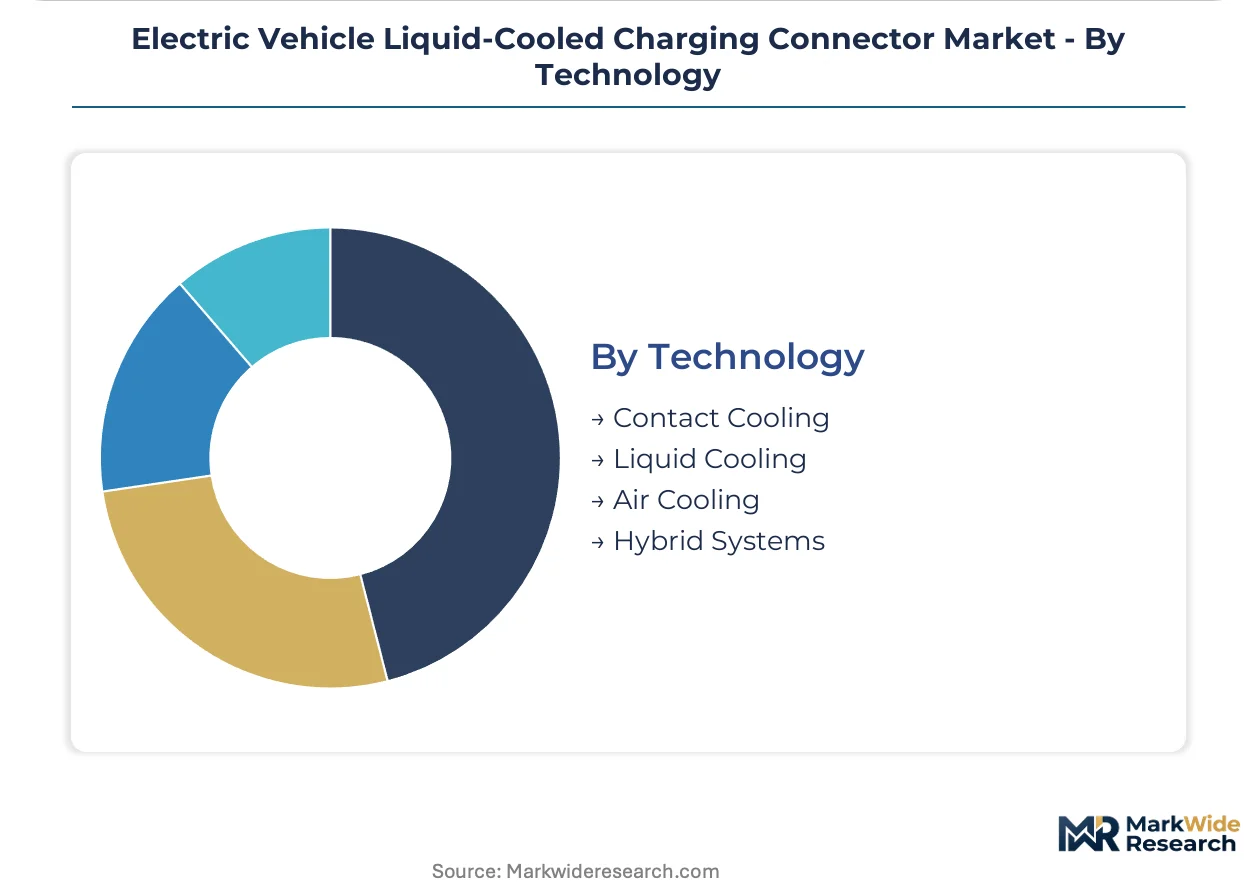
Liquid Cooling maintains dominant share, with Contact Cooling gaining share fastest among next-generation architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern coastal provinces concentrate liquid-cooled connector deployment at triple the density of Germany's logistics corridors, while India's nascent highway electrification programs lag both markets by approximately five years in procurement scale.
China
NIO, BYD, and Tesla operate dense ultra-fast charging networks across Shanghai, Jiangsu, and Zhejiang provinces. MIIT enforces GB/T 20234.4 interoperability standards that dictate physical dimensions and communication protocols for domestic infrastructure. The Yangtze River Delta cluster hosts concentrated manufacturing capacity for liquid-cooled cable assemblies serving both domestic OEMs and export markets.
Germany
Commercial vehicle OEMs specify immersion-cooled connectors for megawatt-scale charging hubs serving heavy-duty fleet electrification. The KBA enforces type approval requirements under EU F-Gas Regulation mandates for lower-global-warming-potential coolants. North Rhine-Westphalia and Bavaria host logistics corridor electrification programs where fleet operators negotiate lifecycle service contracts bundling connector replacement and thermal performance guarantees.
United States
Tesla sustains proprietary connector ecosystems through vertical control over charging hardware and closed technical standards. NHTSA coordinates with industry on high-power charging safety protocols while state-level ZEV mandates accelerate fleet procurement timelines. California's Central Valley freight corridors and Texas logistics hubs represent the densest concentrations of liquid-cooled infrastructure deployment outside China.
Netherlands
National ICE phase-out mandates force connector upgrades to handle 350 kW+ power levels across Rotterdam and Amsterdam port logistics networks. The Dutch Environmental Ministry enforces circular design requirements for thermal management components under extended producer responsibility frameworks. The Randstad metropolitan cluster concentrates procurement volumes for European fleet operators demanding predictable turnaround times.
India
National highway electrification programs create first-mover advantage opportunities for suppliers establishing local assembly partnerships. The Ministry of Road Transport and Highways coordinates with CEA on charging infrastructure standards for logistics corridors connecting Delhi-Mumbai and Chennai-Bengaluru. Maharashtra and Gujarat host pilot deployments where thermal endurance certifications outweigh incremental cost considerations in procurement decisions.
Electric Vehicle Liquid-Cooled Charging Connector Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across liquid-cooled connector supply chains, creating tiered competitive dynamics where scale advantages clash with thermal engineering depth. The vendor base fragments across cable assembly specialists, contact system engineers, and integrated charging hardware providers. Three archetypes dominate: automotive OEMs with captive charging ecosystems, electrical component conglomerates with cross-industry thermal management expertise, and specialized cable manufacturers with continuous extrusion capabilities for high-frequency conductor architectures. Competitive moves concentrate on backward integration into coolant formulation and strategic partnerships with fleet operators for lifecycle service contracting.
Within the automotive OEM tier, Tesla exemplifies closed-ecosystem positioning through proprietary connector standards and captive infrastructure deployment. Among diversified electrical component manufacturers, TE Connectivity and ABB occupy positions spanning industrial automation, energy distribution, and transportation electrification. Huber+Suhner represents the specialized cable assembly archetype, with Swiss-based operations focused on high-frequency interconnect systems. Sumitomo Electric Industries anchors Asian supply chains as a Japan-based integrated cable and connector manufacturer. ITT Cannon and Phoenix Contact exemplify the contact system engineering specialist model, with US and German origins respectively, serving multi-industry demand for harsh-environment electrical interfaces.
| Leading Market Players |
|---|
| Tesla |
| ITT Cannon |
| Phoenix Contact |
| Huber+Suhner |
| TE Connectivity |
| ABB |
| Brugg Cables |
| Sumitomo Electric Industries |
| Yazaki |
| Others |
Pricing and Supply Chain Analysis
Copper and aluminum conductor materials, comprising 35-45% of liquid-cooled connector bills-of-materials, flow from commodity exchanges through Japanese and South Korean cable extrusion facilities before stratifying into premium-certified and economy-grade procurement tiers for fleet operators and infrastructure deployers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for GB/T-compliant cable assemblies. Three-tier pricing structure across premium-certified, standard-grade, and economy-tier levels separates UL 2251-validated immersion-cooled architectures from basic jacket-cooled alternatives. Price differentiation hinges on thermal endurance certification tier and volume procurement scale. Margins are tightening in the standard-grade segment due to oversupply of jacket-cooled capacity. Fleet operators exhibit lowest price sensitivity, prioritizing lifecycle service bundling over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with advanced liquid-cooled conductor extrusion capabilities concentrated in Japan, South Korea, and select Chinese coastal provinces. Raw material dependencies center on high-purity copper rod, fluorinated dielectric fluids, and ceramic-filled thermal interface compounds. Supply chain risk manifests as tariff exposure on cable assemblies sourced from concentrated Asian manufacturing nodes. Distribution runs through Tier 1 charging hardware integrators and direct OEM supply agreements to megawatt-scale hub operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement decisions increasingly favor thermal endurance certifications over incremental cost reductions as fleet electrification compresses hardware replacement cycles.
For Market Incumbents: Extend backward integration into dielectric fluid formulation to capture margin from silicone-based coolant transitions mandated by EU F-Gas Regulation. Deepen captive supply of high-frequency cable extrusion capacity to defend against emerging Asian competitors. Prioritize certification investment in immersion-cooled architectures before UL 2251 validation timelines lengthen further. For New Entrants and Emerging Players: Direct-to-fleet digital procurement platforms offer the lowest-friction route to bypass incumbent distributor relationships. White-space concentrates in India's national highway electrification programs and secondary logistics corridors where thermal performance guarantees outweigh brand recognition. Target local assembly partnerships with Maharashtra and Gujarat infrastructure operators as the most penetrable entry vector. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized cable assembly expertise overlaps with insufficient scale to fund standalone certification programs. The five-to-ten year viability window favors acquisition of mid-cap contact system engineers with existing IEC 62196-6 validation rather than greenfield capability builds. Monitor GB/T 20234.4 compliance certification timelines as the critical inflection signal for network access privileges in China's domestic market.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coolant Formulation | Captures margin from EU F-Gas Regulation-driven silicone fluid transitions. |
| Immersion-Cooled Architecture Certification | Enables 600 A continuous operation bids for German megawatt-scale fleet hubs. |
| Local Assembly Partnership in India | Positions suppliers for national highway electrification program procurement windows. |
| Lifecycle Service Contracting Model | Aligns revenue streams with German fleet operator total-cost-of-ownership transparency requirements. |
| GB/T 20234.4 Communication Module Integration | Maintains network access for NIO and BYD ultra-fast charging deployments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged charging infrastructure procurement managers at fleet operators, thermal engineering leads at connector manufacturers, and regulatory affairs specialists navigating EU F-Gas and GB/T compliance pathways. Secondary validation drew from MIIT standard filings, KBA type approval databases, UL certification directories, and customs trade records for liquid-cooled cable assemblies. Bottom-up connector deployment estimates triangulated against top-down infrastructure investment forecasts.
Historical reference periods anchored projections across the analysis window to observed procurement cycles and certification timeline data. Segmentation dimensions modeled include product architecture, end-user duty cycle, installation environment, and cooling methodology. CAGRs derived from coupled growth-rate analysis across fleet electrification timelines and thermal power density requirements. Forecast inputs incorporated MIIT enforcement schedules for GB/T 20234.4 and evolving UL 2251 thermal cycling validation protocols.
The model assumes a particular technology adoption path; alternative pathways for solid-state thermal interface materials would alter the outlook. Forecasts reflect assumptions around fleet operator consolidation timelines and coolant chemistry regulatory trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Asia-Pacific Electric Vehicle Market
Electric Vehicles
Electric Tuk-Tuks Market
Electric Vehicles
Vietnam Solar E-Bike Market
Electric Vehicles
Battery-Only Electric Bus Market
Electric Vehicles
South America Automotive High Performance Electric Vehicles Market
Electric Vehicles
France Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Europe Electric Bus Market
Electric Vehicles
Electric Vehicle Air Conditioning Market
Electric Vehicles
North America Automotive Battery Thermal Management System Market
Electric Vehicles
GCC Electric Vehicle Market
Electric Vehicles
Electric Vehicle Skateboard Chassis Market
Electric Vehicles
North America Electric Bus Market
Electric Vehicles
Central and Eastern Europe E-Bike Market
Electric Vehicles
Middle East Electric Vehicle Market
Electric Vehicles
EV Thermal System Market
Electric Vehicles
E-Bike Smart Systems Market