
 North America Almond Milk Market | 2026-2036
North America Almond Milk Market Size, Share, and Industry Trends Forecast 2026-2036
North America Almond Milk Market Insights
Organic certification tier is collapsing the boundary between premium health-store positioning and mainstream grocery penetration. Blue Diamond Growers leverages its cooperative grower network to sustain raw almond supply security across the Southwest. Califia Farms LLC differentiates through refrigerated plant-based beverage innovation, while Danone S.A. competes via its Silk brand's national retail distribution density.
Almond milk is an aqueous emulsion produced by blending soaked almond kernels with water, then filtering to achieve target solids content between two and four percent, with commercial formulations adding calcium carbonate, vitamin D2, and gellan gum for suspension stability and nutritional parity with dairy milk. The unsweetened segment anchors volume in households managing sugar intake, while foodservice demand for barista-specific formulations concentrates margin pools in tetra pack and bottle formats with optimized foaming proteins. Organic product type commands shelf-space premiums in health stores, though flavored variants extend trial conversion in conventional retail channels.
The U.S. FDA oversees plant-based milk labeling standards, while USDA Organic certification governs ingredient sourcing claims, and Canada's CFIA enforces bilingual nutritional labeling and dairy alternative standards that shape cross-border product formulation decisions. California's agricultural water regulations and the FDA's forthcoming guidance on nutrient disclosure requirements will force reformulation investments and supply chain documentation upgrades. Stakeholders must monitor how state-level water pricing policies intersect with almond orchard expansion limits to assess long-term input cost trajectories.
Market Dynamics
Water scarcity in California's Central Valley is forcing almond processors to relocate blending facilities toward Great Lakes water districts, fragmenting the historical co-location of orchards and manufacturing plants that defined the industry's cost structure.
Growth Catalysts
- CFIA Bilingual Labeling Standards:Canada's enforcement of French-English nutritional disclosure creates formulation standardization that simplifies cross-border production runs for U.S. processors serving both markets.
- Barista-Grade Emulsion Technology:High-pressure homogenization systems producing stable microfoam are unlocking foodservice volume in specialty coffee chains across Toronto and Vancouver.
- California Agricultural Water Pricing:Tiered groundwater extraction fees are accelerating orchard retirement programs that release experienced processing labor into the plant-based beverage workforce.
Market Restraints
- Almond Pollination Cost Volatility:Commercial bee colony rental rates for February bloom periods have tripled since 2018, concentrating margin pressure on small-scale cooperative processors.
- FDA Nutrient Disclosure Uncertainty:Pending guidance on comparative protein labeling against dairy creates reformulation hesitation and frozen packaging redesign cycles.
- Oat Milk Substitution:Neutral-flavored oat bases with lower water footprints are capturing shelf space in Midwest conventional retail channels previously dominated by almond.
Strategic Opportunities
- USDA Organic Certification Pipeline:Accelerated audit timelines for transitioning California orchards offer first-mover positioning in Costco and Whole Foods premium tiers.
- Direct-to-Institution Distribution:K-12 school district procurement in Texas and Florida represents untapped volume for shelf-stable tetra pack formats meeting federal meal pattern requirements.
- Blockchain-Enabled Provenance Tracking:Integration of irrigation source verification with retailer ESG reporting requirements is opening price premiums in corporate cafeteria contracts.
Industry Challenges
- Emulsion Stability Expertise Gap:Food science PhD hiring competition from pharmaceutical and cultivated meat sectors is delaying R&D timelines for clean-label gellan gum replacements.
- Legacy ERP Integration:Organic certification documentation requirements are crashing against outdated inventory management systems at mid-sized co-packers throughout the San Joaquin Valley.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Almond Milk Market |
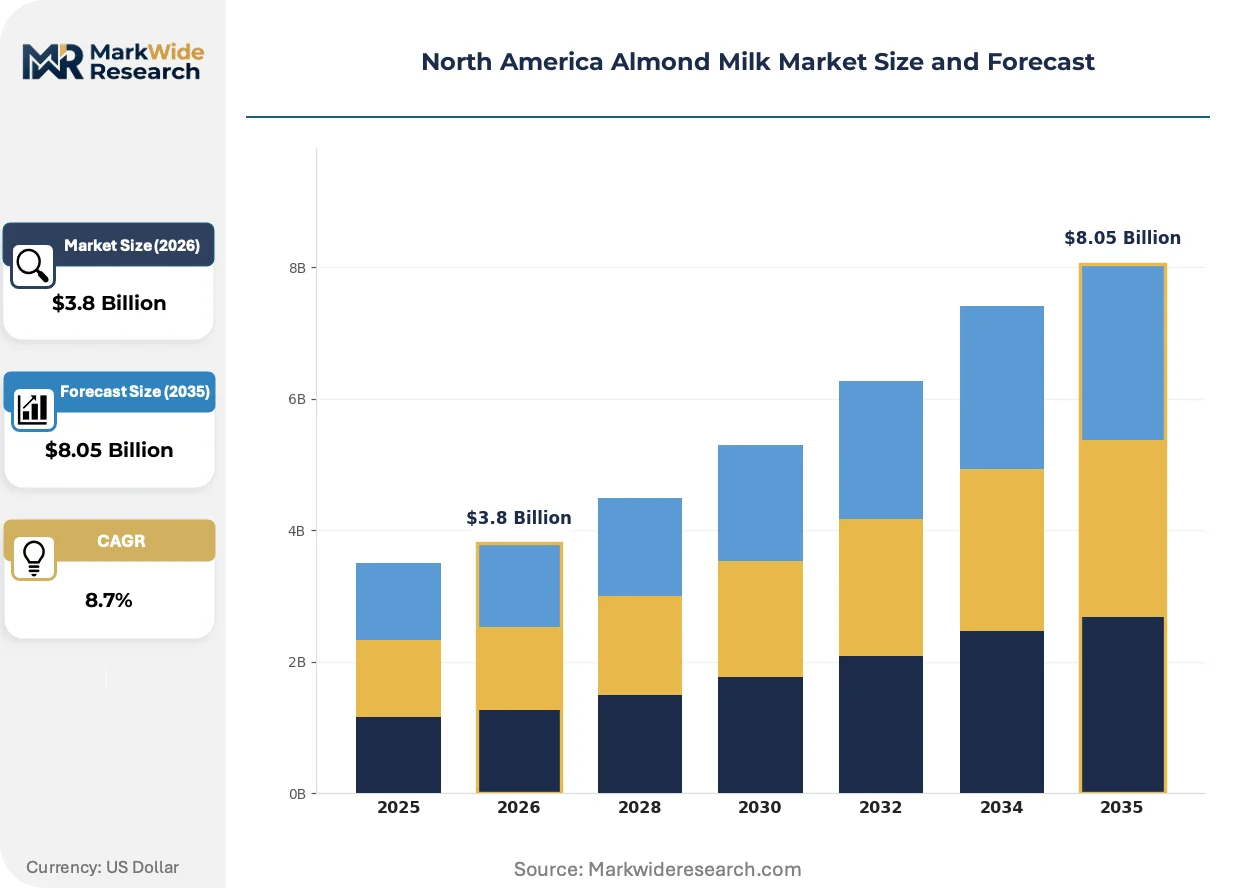
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unsweetened, Sweetened, Flavored, Organic Packaging Type: Cartons, Bottles, Pouches, Tetra Packs Distribution Channel: Retail, E-commerce, Direct Sales, Foodservice End User: Households, Cafes, Restaurants, Health Stores |
| Companies Covered | SunOpta Inc., Pacific Foods of Oregon LLC, Blue Diamond Growers, MALK Organics LLC, Elmhurst 1925, Danone S.A., The Hain Celestial Group Inc., Three Trees Foods Inc., Califia Farms LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Almond Milk Market Trends and Innovations
Reformulation priorities are pivoting from sugar reduction to protein fortification as nutritional parity claims face heightened scrutiny from both regulators and performance-oriented consumers.
High-pressure processing (HPP) is supplanting traditional thermal pasteurization in refrigerated almond milk lines. Premium California brands are adopting cold-pressure treatment to extend refrigerated shelf life without the cooked flavor notes that plague UHT products. This shift is compressing the addressable market for aseptic carton specialists while expanding contract manufacturing demand at HPP tolling facilities in Wisconsin and Pennsylvania.
The U.S. FDA's forthcoming guidance on plant-based milk nutrient disclosure standards is mandating explicit protein comparison callouts against dairy equivalents. Manufacturers must now reformulate with added pea or fava protein to meet disclosure thresholds or accept disadvantageous labeling. The unsweetened segment faces the steepest compliance burden, as clean-label positioning previously excluded fortification additives now required for parity claims.
Foodservice procurement is consolidating around specification-standardized barista blends that perform identically across espresso machine brands. Independent café owners in Montreal and Austin are abandoning house-made nut milks for contract-manufactured concentrates with guaranteed foaming performance. This standardization is eroding the competitive differentiation that local production once provided while locking volume into multi-year supply agreements with national distributors.
North America Almond Milk Market Segmentation
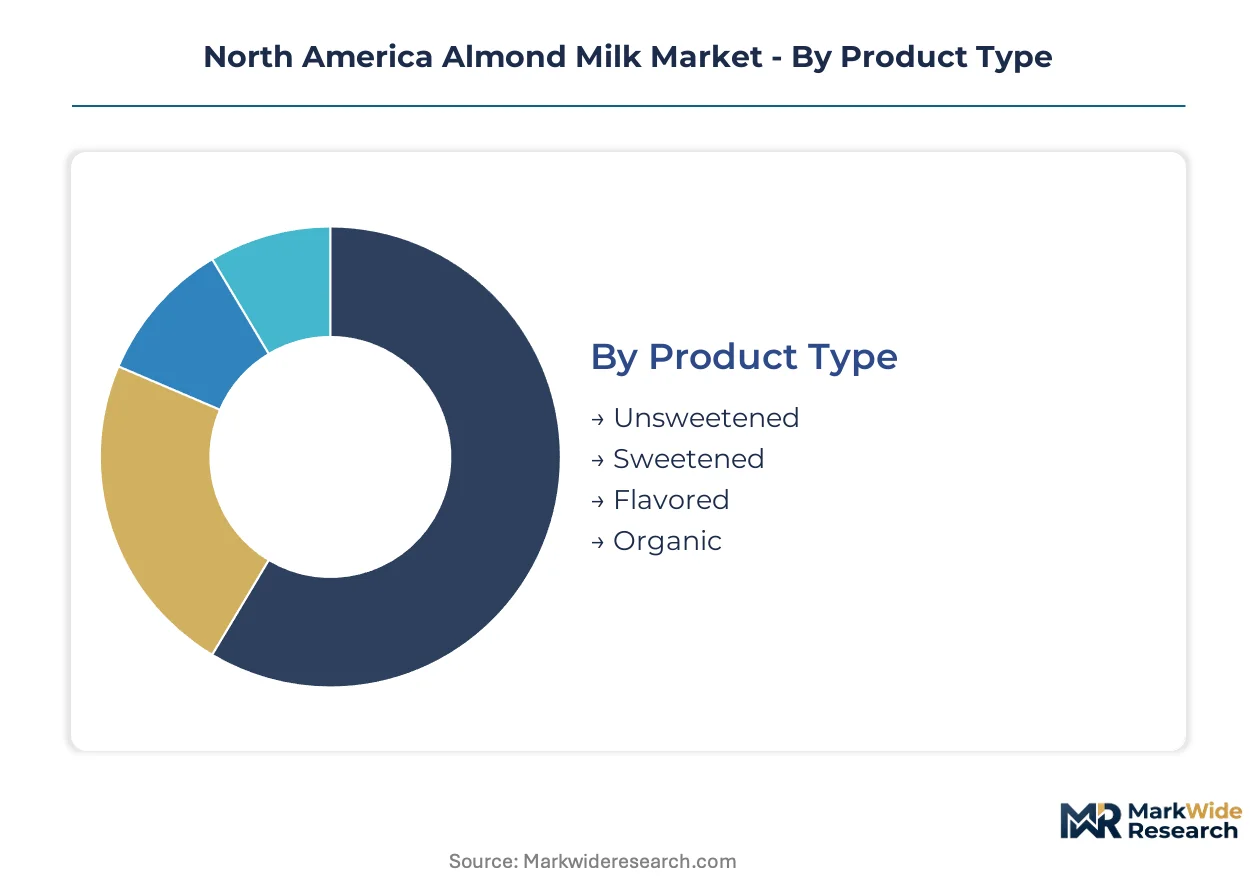
Almond milk segmentation in North America reflects divergent regulatory pressures across the U.S.-Canada border. FDA disclosure standards and CFIA bilingual labeling requirements force distinct formulation and packaging strategies for each segment tier.
Product Type:
FDA nutrient disclosure standards differentiate protein fortification requirements across sweetness and certification tiers.
- Unsweetened:Formulations between two and four percent almond solids with no added sugars anchor diabetic and ketogenic diet adherence. California households managing metabolic health conditions drive volume through Costco and Kroger conventional dairy aisles.
- Organic:USDA-certified sourcing commands shelf-space premiums in Whole Foods and Sprouts. Transitioning orchards in California's Central Valley face accelerated audit timelines that constrain supply elasticity.
- Sweetened:Cane sugar or monk fruit formulations target trial conversion in conventional retail channels previously resistant to plant-based alternatives.
- Flavored:Vanilla and chocolate variants extend pediatric acceptance and coffeehouse customization demand.
Unsweetened handles the majority of throughput; Organic is expanding most quickly on share.
Packaging Type:
Cost tier differentiation separates aseptic shelf-stable from refrigerated cold-chain dependent formats.
- Cartons:Gable-top refrigerated cartons dominate conventional grocery dairy case placement. Wisconsin and Pennsylvania cold-press tolling facilities service premium California brands seeking extended shelf life without thermal degradation.
- Tetra Packs:Aseptic brick formats unlock K-12 school district procurement in Texas and Florida meeting federal meal pattern requirements for shelf-stable distribution.
- Bottles:PET and glass containers signal premium positioning in convenience retail and grab-and-go foodservice.
- Pouches:Flexible single-serve formats target travel and outdoor recreation channels with reduced shipping cube efficiency.
Cartons handle the majority of throughput; Tetra Packs are gaining share fastest.
Distribution Channel:
Customer type concentration splits between institutional procurement standardization and fragmented household trial behavior.
- Retail:Conventional grocery and mass merchandiser placement depends on slotting fee negotiations and dairy-alternative aisle expansion. Canadian bilingual packaging requirements simplify cross-border production runs for U.S. processors.
- Foodservice:Specialty coffee chains in Toronto and Vancouver specify barista-grade emulsion stability for microfoam performance. Multi-year supply agreements with national distributors lock volume away from independent café house-made alternatives.
- E-commerce:Subscription replenishment models concentrate in coastal metropolitan areas with established plant-based consumption patterns.
- Direct Sales:Cooperative processor networks in California's San Joaquin Valley maintain legacy relationships with institutional buyers.
Retail handles the majority of throughput; Foodservice is climbing the fastest on share.
End User:
Application maturity separates established household consumption from emerging foodservice standardization.
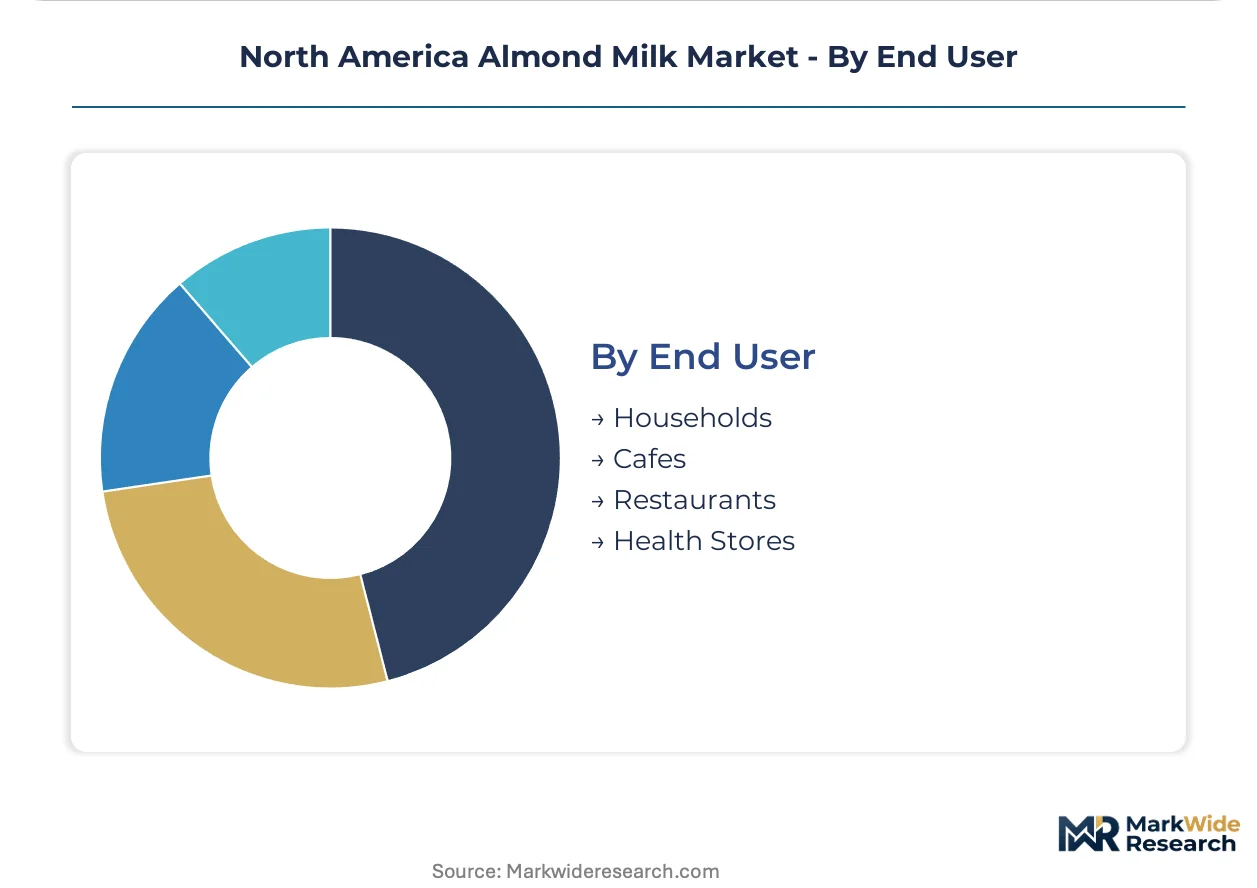
- Households:Repeat purchase patterns concentrate in California, Texas, and Florida metropolitan statistical areas. Sugar intake management drives unsweetened format loyalty.
- Cafes:Independent operators in Montreal and Austin abandon house-made nut milks for contract-manufactured concentrates with guaranteed foaming proteins across espresso machine brands.
- Restaurants:Casual dining chains test almond milk as a default dairy alternative in kids' meal programs.
- Health Stores:Natural products retailers maintain organic and fortified SKU depth unavailable in conventional grocery.
Households handle the majority of throughput; Cafes are expanding most rapidly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across North American markets. Canadian institutional buyers exhibit the greatest sensitivity to procurement costs, while California households prioritize organic certification premiums over sticker price.
United States
California households managing metabolic health conditions drive unsweetened format volume through Costco and Kroger conventional dairy aisles. The FDA's forthcoming nutrient disclosure standards mandate explicit protein comparison callouts against dairy equivalents. San Joaquin Valley processing clusters face accelerated orchard retirement programs releasing experienced labor into plant-based beverage manufacturing.
Canada
Specialty coffee chains in Toronto and Vancouver specify barista-grade emulsion stability for microfoam performance across espresso machine brands. CFIA bilingual labeling requirements create formulation standardization that simplifies cross-border production runs for U.S. processors. Montreal independent café operators are abandoning house-made nut milks for contract-manufactured concentrates with guaranteed foaming proteins.
Mexico
Conventional retail channels in Mexico City and Guadalajara metropolitan areas show emerging trial conversion for sweetened almond milk variants. The country's national food safety regulator enforces nutritional labeling standards that shape import documentation requirements for U.S. processors. Northern border states concentrate cross-border logistics infrastructure supporting refrigerated distribution into Texas and Arizona retail networks.
North America Almond Milk Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America almond milk market. Cooperative processors with captive almond supply chains dominate cost-efficient volume production, while refrigerated innovation specialists command premium positioning through cold-pressure processing capabilities. The competitive terrain separates into three strategic archetypes: legacy agricultural cooperatives, venture-backed beverage innovators, and diversified multinational dairy-alternative portfolios. Dominant competitive moves include backward integration into orchard assets and multi-year supply agreements locking foodservice volume away from regional independents.
Among U.S.-based agricultural cooperatives, Blue Diamond Growers exemplifies the captive supply archetype through its Southwest grower network. Califia Farms LLC occupies a position within the refrigerated innovation tier, while Danone S.A. anchors the multinational portfolio diversification strategy through its Silk brand's national retail distribution density.
| Leading Market Players |
|---|
| SunOpta Inc. |
| Pacific Foods of Oregon LLC |
| Blue Diamond Growers |
| MALK Organics LLC |
| Elmhurst 1925 |
| Danone S.A. |
| The Hain Celestial Group Inc. |
| Three Trees Foods Inc. |
| Califia Farms LLC |
| Others |
Pricing and Supply Chain Analysis
Sixty-day almond inventory cycles in California Central Valley processors tie working capital exposure directly to water-rights auction volatility, concentrating pricing power among cooperatives with captive orchard networks while forcing independent blenders toward spot-market almond procurement at freight-advantaged Great Lakes locations.
Pricing Analysis
After-sales revenue from barista-grade technical service contracts drives lifetime value differentiation between national distributors and regional independents. Three-tier pricing structure across premium organic, standard conventional, and economy private-label levels anchors the market, with USDA certification and cold-pressure processing capability as primary price differentiation drivers. Pricing pressure stems from oat milk substitution in Midwest conventional retail, squeezing almond milk slotting fee negotiations. Canadian institutional buyers exhibit greatest price sensitivity due to CFIA compliance cost pass-through, while California households show least sensitivity, prioritizing organic certification premiums.
Supply Chain Analysis
Inbound logistics costs from Port of Oakland container congestion and refrigerated rail capacity constraints into Texas distribution hubs concentrate supply chain risk assessment. Geographic supply concentration centers on California, with secondary processing emerging in Wisconsin and Pennsylvania HPP tolling facilities. Raw material dependencies rest on bee colony rental services for February almond bloom, groundwater extraction permits, and gellan gum stabilizer sourcing. Single-source vulnerability in California orchard pollination services threatens margin stability. Distribution runs through national foodservice distributors locking multi-year barista-blend volume, bypassing fragmented independent café procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as drought-driven orchard retirement programs release experienced processing labor into plant-based beverage manufacturing, resetting input cost trajectories.
For Market Incumbents: Consolidate cooperative grower networks through accelerated organic certification pipelines for transitioning Central Valley orchards, securing first-mover positioning in Costco and Whole Foods premium tiers. Lock foodservice volume through multi-year supply agreements with national distributors, neutralizing oat milk substitution threat in specialty coffee chains. Prioritize backward integration into irrigation-source-verified orchard assets to meet retailer ESG reporting requirements.
For New Entrants and Emerging Players: Foodservice technical service gaps in K-12 school district procurement represent the most penetrable white space, with Texas and Florida shelf-stable tetra pack volume untapped by incumbent barista-grade specialists. Target direct-to-institution distribution bypassing retail slotting fee barriers. Enter through USDA Organic certification acceleration services for transitioning orchards, capturing audit timeline compression premiums.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because cooperative processor networks with captive almond supply chains face generational ownership transitions, creating acquisition targets with embedded water-rights value. Monitor FDA nutrient disclosure guidance finalization as inflection signal for protein fortification reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchards | Captive almond supply secures water-rights value amid California groundwater pricing tiers. |
| USDA Organic Certification Pipeline | Accelerated audit timelines unlock Costco and Whole Foods premium shelf placement. |
| Barista-Grade Emulsion Technology Investment | High-pressure homogenization systems lock specialty coffee chain volume in Toronto and Vancouver. |
| Direct-to-Institution Distribution Buildout | K-12 school district procurement in Texas and Florida bypasses retail slotting fee concentration. |
| Blockchain-Enabled Provenance Tracking | Irrigation source verification opens corporate cafeteria ESG premium pricing. |
Research Methodology
The analysis maps unsweetened, organic, sweetened, and flavored product tiers alongside carton, tetra pack, bottle, and pouch packaging formats, each validated through plant-based beverage R&D directors, cooperative processor operations managers, national foodservice distributor category buyers, and K-12 school district procurement officers. Primary interview findings triangulate against FDA guidance documents, USDA Organic certification databases, CFIA bilingual labeling standards, Nielsen retail audit data, and California agricultural water pricing regulatory filings. Bottom-up volume modeling from processor capacity utilization rates reconciles with top-down category spend analysis.
Consistency checks against almond solids pricing indices and bee colony rental rate benchmarks validate projection outputs across the analysis window. Segmentation dimensions include product sweetness tier, organic certification status, packaging cold-chain dependency, distribution channel concentration, and end-use application maturity. CAGRs derive from processor capacity expansion announcements, orchard retirement program timelines, and foodservice contract renewal patterns. Forecast inputs incorporate FDA nutrient disclosure guidance implementation trajectory and California groundwater extraction fee escalation schedules.
Underlying assumptions cover drought persistence in California Central Valley, stable CFIA bilingual labeling enforcement, and oat milk substitution velocity in conventional retail, with deviation risk concentrated in FDA protein comparison disclosure stringency and pollinator colony health volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Chickpea Milk Market
Dairy Alternatives
Coconut Milk Derivatives Market
Dairy Alternatives
Dairy Free Yogurt Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
Hemp Milk Market
Dairy Alternatives
Coconut Yogurt Market
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
Global Vegan Sour Cream Market
Dairy Alternatives
Asia-Pacific Sour Milk Drinks Market
Dairy Alternatives
North America Non-Dairy Cheese Market
Dairy Alternatives
Low-Calorie Cream Market
Dairy Alternatives
Savory Yogurt Market
Dairy Alternatives
Protein Ice Cream Market
Dairy Alternatives
Vegan Ice Cream Market
Dairy Alternatives
On-The-Go Yoghurt Market
Dairy Alternatives
Dairy Whiteners Market