
 Japan Cloud Robotics Market | 2026-2036
Japan Cloud Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Cloud Robotics Market Insights
Subscription-based software layers is restructuring how Japanese manufacturers procure robotics capabilities, shifting capital expenditure to operational models. Fanuc Corporation leverages its FIELD system to connect machine tools with cloud analytics for predictive maintenance. Yaskawa Electric Corporation anchors its competitive stance through deep integration of its MOTOMAN robots with edge-cloud hybrid architectures.
Cloud robotics fuses distributed computing, sensor networks, and real-time data pipelines to extend robot cognition beyond onboard processing limits. Systems typically operate with sub-100 millisecond latency thresholds for motion control, while offloading mapping, learning, and diagnostics to centralized or federated cloud nodes. Industrial robots dominate current deployment value, though collaborative robots represent the fastest-expanding segment as SMEs adopt pay-per-use cloud orchestration. Hybrid cloud deployments command premium positioning by balancing data sovereignty requirements with scalable compute access.
METI's Industrial Cybersecurity Framework and JIS standards under the Japanese Industrial Standards Committee shape product certification pathways and data governance obligations for connected robot systems. PMDA oversight intersects where cloud robotics penetrates surgical and rehabilitation healthcare applications, adding clinical validation layers. Stakeholders must monitor evolving cross-border data flow restrictions and their impact on multi-tenant cloud architectures serving Japanese manufacturing bases.
Market Dynamics
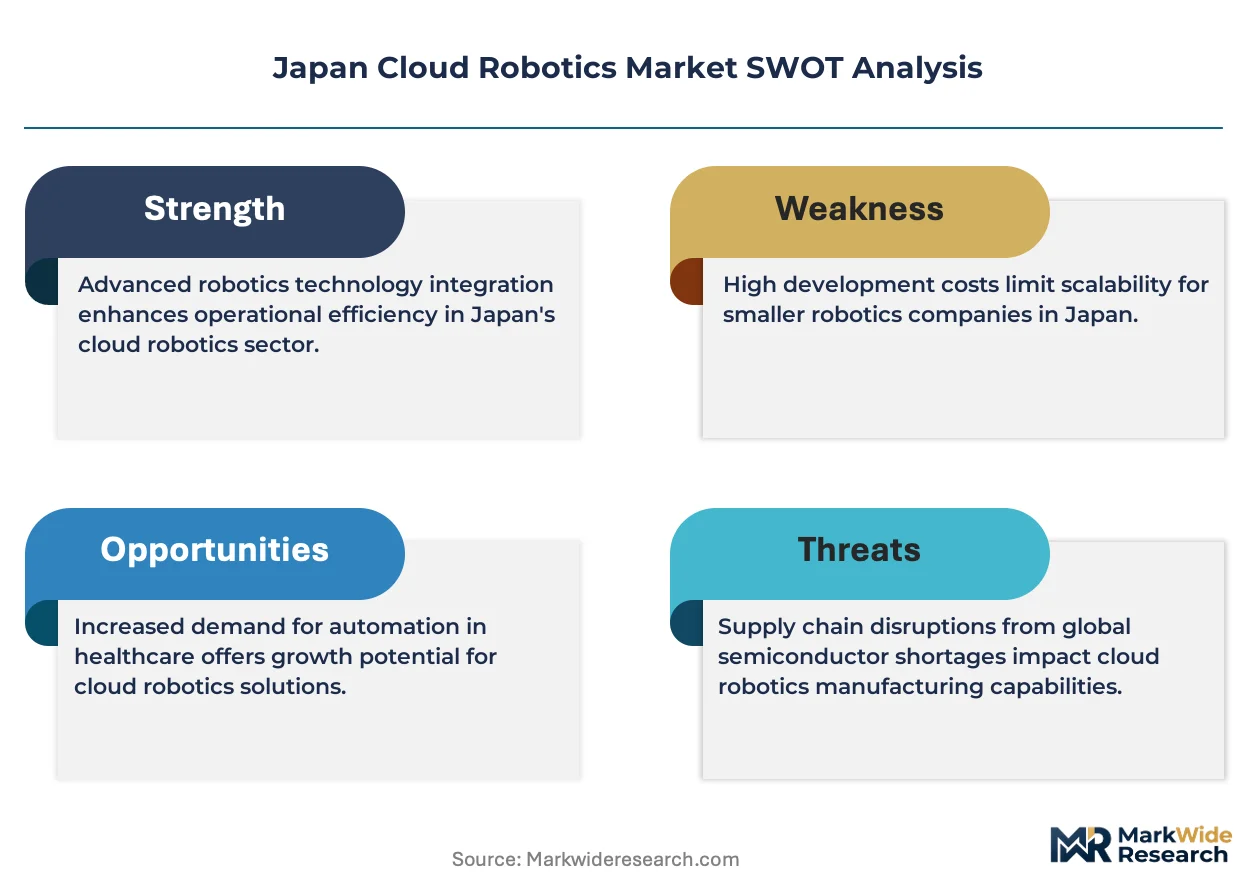
Japan's cloud robotics sector is undergoing structural reconfiguration as METI's Society 5.0 policy framework mandates data interoperability standards that force robot OEMs to abandon proprietary cloud silos. This regulatory pressure is compressing vendor consolidation timelines and reshaping how industrial automation capabilities are monetized across Japanese manufacturing bases.
Growth Catalysts
- Industrial Value Chain Initiative:METI's data-sharing standards accelerate robot-to-cloud integration across automotive and electronics assembly lines, reducing deployment friction for multi-vendor environments.
- Edge-cloud hybrid architectures:Sub-100 millisecond latency thresholds for motion control enable real-time offloading of mapping and diagnostics, expanding robot cognition beyond onboard processing limits.
- Kanto industrial corridor concentration:Smart factory investments cluster around Tokyo and Yokohama, creating dense demand nodes that justify localized cloud infrastructure buildout.
Market Restraints
- Cross-border data flow restrictions:Evolving Japanese regulations on multi-tenant cloud architectures create compliance overhead for foreign platform providers serving domestic manufacturing bases.
- Legacy system integration costs:Brownfield facilities in Osaka and Nagoya face capital-intensive retrofitting to connect existing machine tools with cloud analytics layers.
- Specialized edge computing hardware:Dependence on imported semiconductor components for low-latency gateways exposes deployment timelines to supply volatility.
Strategic Opportunities
- SME pay-per-use orchestration:Collaborative robot subscription models penetrate undercapitalized precision manufacturing in Kyoto and Aichi prefectures.
- PMDA clinical validation pathways:Cloud robotics penetration into surgical and rehabilitation applications opens healthcare revenue streams beyond industrial automation.
- 5G private network convergence:Ultra-reliable low-latency communication enables new motion control architectures for autonomous mobile robots in warehouse logistics.
Industry Challenges
- Industrial cybersecurity certification:METI's framework imposes rigorous product validation timelines that delay market entry for new cloud-connected robot systems.
- Multi-vendor interoperability engineering:JIS standards compliance requires specialized integration expertise that outstrips current systems integrator capacity in regional manufacturing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Cloud Robotics Market |
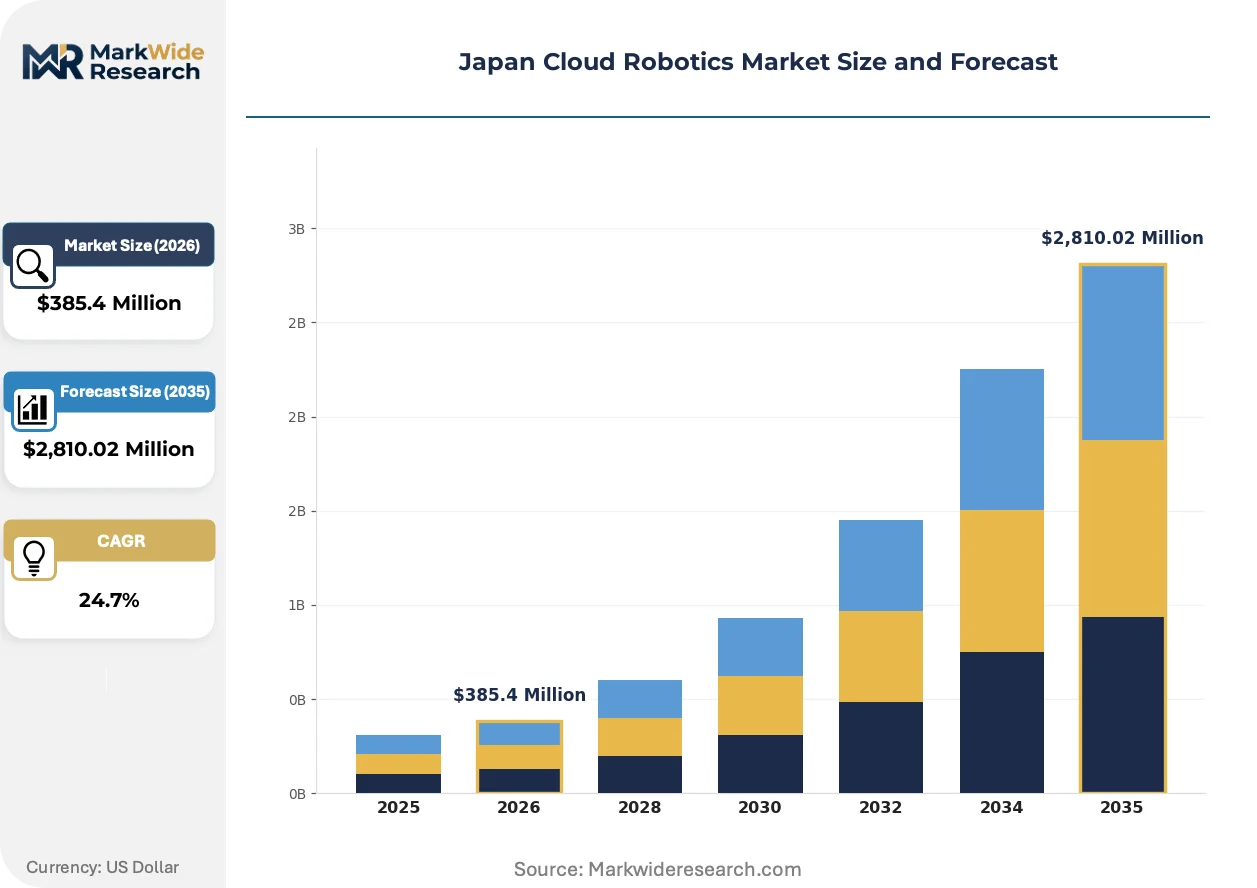
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $2,810.02 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Robots, Service Robots, Collaborative Robots, Humanoid Robots Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Edge Computing Application: Manufacturing, Healthcare, Logistics, Agriculture End User: Enterprises, SMEs, Government, Research Institutions |
| Companies Covered | Fanuc Corporation, Yaskawa Electric Corporation, Mitsubishi Electric Corporation, Omron Corporation, Kawasaki Robotics, Mujin Inc., Hitachi, Fujitsu, TRI-AD, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Cloud Robotics Market Trends and Innovations
Cloud robotics architectures are pivoting from centralized processing toward federated edge nodes that balance computational offload with data sovereignty requirements. This structural shift is redefining competitive differentiation around latency performance and hybrid deployment flexibility rather than raw cloud storage scale.
Distributed computing frameworks are converging with real-time sensor fusion pipelines to extend robot cognition beyond onboard GPU constraints. Tier-1 automotive suppliers in Aichi Prefecture are deploying these architectures for predictive quality control at weld stations. The technology is converging with digital twin simulation layers to compress commissioning cycles for new production lines.
METI's Industrial Cybersecurity Framework is mandating encryption standards and access control protocols for all connected robot systems operating in critical infrastructure sectors. Equipment vendors must now embed security-by-design principles into firmware development cycles. Healthcare robotics manufacturers face additional PMDA oversight layers that extend clinical validation timelines before commercial deployment.
Japanese manufacturers are unbundling traditional capex-heavy robot procurement into operational expenditure models tied to uptime guarantees and throughput metrics. Systems integrators in the Kanto region now offer subscription-based orchestration platforms that include cloud analytics and remote monitoring. This restructuring is most visible among mid-tier electronics assemblers seeking to reduce balance-sheet exposure to automation assets.
Japan Cloud Robotics Market Segmentation
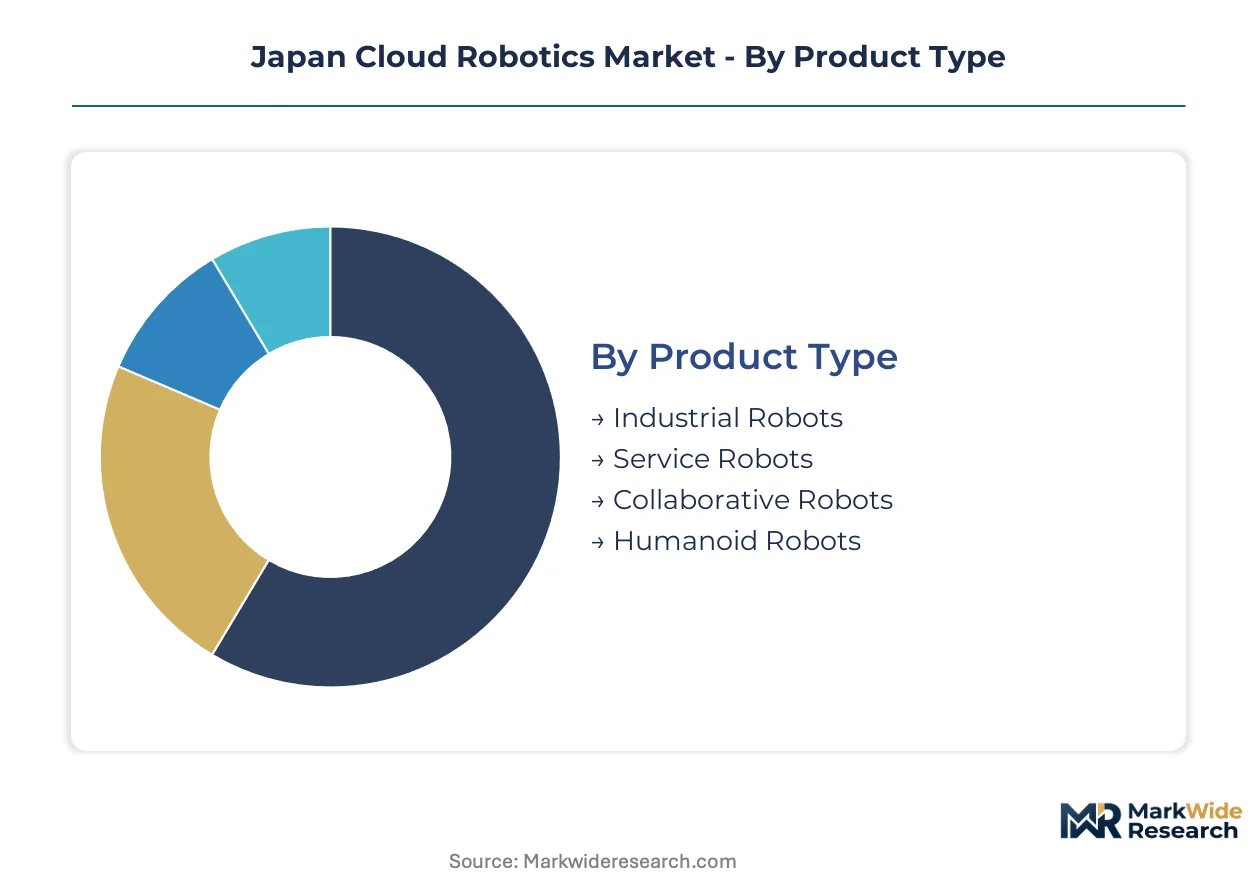
Cloud robotics segmentation in Japan reveals how deployment architecture and end-user scale determine procurement patterns. Product type and application boundaries are blurring as METI's interoperability standards force modular system designs across automotive and electronics manufacturing corridors.
Product Type:
Supply concentration around motion control subsystems favors established industrial categories, though collaborative and humanoid platforms are capturing specialized demand niches.
- Industrial Robots:Six-axis articulated arms and SCARA configurations dominate automotive welding and electronics assembly. Aichi Prefecture's Toyota supplier ecosystem absorbs the majority of cloud-connected deployments for predictive maintenance integration.
- Service Robots:Autonomous mobile platforms for facility management and inspection leverage cloud-based SLAM mapping. Demand clusters in Tokyo's commercial real estate sector where 5G private networks enable real-time fleet coordination.
- Collaborative Robots:Expanding most quickly among Kyoto precision manufacturers seeking pay-per-use orchestration without capital commitment.
- Humanoid Robots:Experimental deployments in eldercare facilities and retail reception roles, constrained by PMDA validation pathways for physical human interaction.
Today's leader: Industrial Robots. Tomorrow's challenger: Collaborative Robots.
Deployment:
Cost tier differentiation separates premium hybrid architectures from standardized public cloud offerings, with edge computing commanding specialized hardware premiums.
- Hybrid Cloud:Balances data sovereignty requirements with scalable compute access through localized edge nodes. Kanto manufacturers prefer this architecture for sensitive process data retention alongside cloud analytics offload.
- Edge Computing:Sub-100 millisecond latency thresholds enable real-time motion control without full cloud dependency. Semiconductor component supply constraints from imported gateway hardware limit deployment velocity.
- Private Cloud:Defense contractors and medical device manufacturers mandate air-gapped infrastructure for cybersecurity compliance.
- Public Cloud:Lowest entry cost for SME robotics-as-a-service providers in Osaka's logistics startup cluster.
Hybrid Cloud commands current deployment value. Edge Computing represents the steepest expansion trajectory as 5G private networks proliferate.
Application:
Volume concentration in manufacturing creates margin pressure, while healthcare and logistics applications sustain premium pricing through specialized validation requirements.
- Manufacturing:Automotive and electronics assembly lines generate the bulk of cloud robotics value. Tier-1 suppliers in Yokohama industrial corridors deploy federated edge architectures for weld quality prediction.
- Healthcare:Surgical robotics and rehabilitation systems face PMDA clinical validation layers that extend commercialization timelines. Osaka university hospitals pilot cloud-connected exoskeletons for stroke recovery.
- Logistics:Autonomous mobile robots in warehouse environments leverage cloud-based fleet optimization. Nagoya port automation projects drive demand for multi-robot coordination platforms.
- Agriculture:Precision spraying and harvesting robots in Hokkaido integrate weather data APIs through cloud middleware.
Manufacturing anchors current revenue. Healthcare offers the highest margin expansion potential.
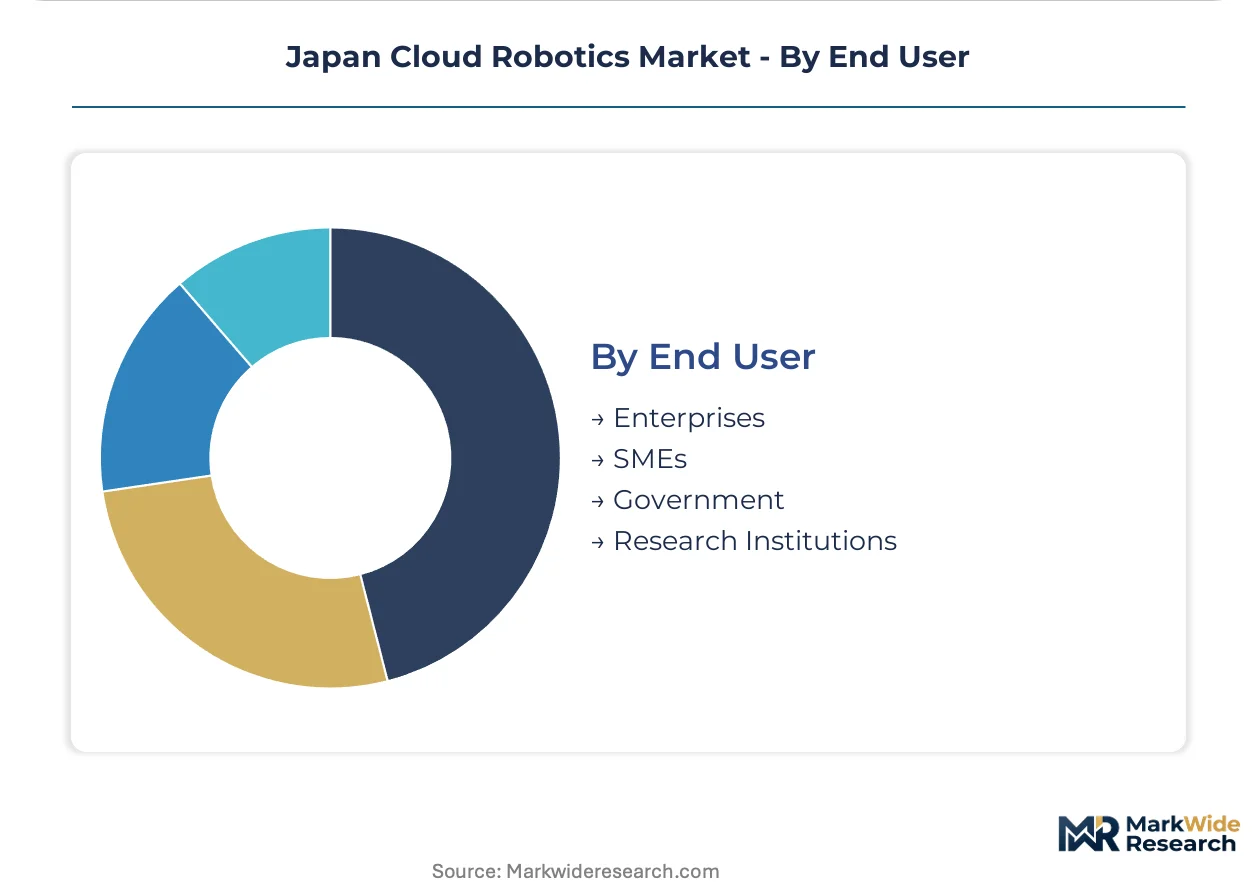
End User:
Customer type maturity separates enterprise procurement sophistication from SME reliance on subscription orchestration models.
- Enterprises:Tier-1 automotive and electronics manufacturers deploy integrated cloud robotics platforms with dedicated systems integrator relationships. These buyers negotiate uptime guarantees and throughput-based service level agreements.
- SMEs:Mid-tier precision manufacturers in Kyoto and Aichi prefectures adopt collaborative robot subscriptions to avoid balance-sheet automation exposure.
- Government:METI-funded smart city pilots in Tokyo and disaster response robotics programs drive public sector procurement.
- Research Institutions:University robotics labs in Tsukuba and Osaka access cloud compute grants for algorithm development without infrastructure capital.
Enterprises dominate deployment scale. SMEs are gaining share fastest through operational expenditure restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where Japanese manufacturers deploy cloud-connected robotics, with compliance-cost differentials between prefectures driving investment toward METI-designated smart factory zones and away from legacy industrial basins facing steeper retrofitting burdens.
Kanto/Tokyo
Tokyo and Yokohama industrial corridors absorb the majority of cloud robotics investment, driven by dense automotive and electronics manufacturing clusters. METI's Society 5.0 implementation grants prioritize Kanto-based facilities for federated edge-cloud pilot programs. Toyota and Nissan tier-1 suppliers in Kanagawa Prefecture deploy predictive maintenance systems through localized cloud nodes.
Kansai/Osaka
Osaka's brownfield machinery sector faces capital-intensive integration costs for legacy equipment connectivity. The Industrial Value Chain Initiative provides co-funding for SME robotics-as-a-service adoption in Kyoto precision manufacturing. Osaka port automation projects drive demand for multi-robot coordination platforms with cloud-based fleet optimization.
Chubu/Nagoya
Aichi Prefecture's Toyota supplier ecosystem dominates industrial robot deployment volume for welding and assembly applications. METI's data interoperability standards force Nagoya-based OEMs to abandon proprietary cloud silos in favor of open-architecture systems. Tier-1 automotive suppliers deploy federated edge architectures for real-time quality prediction at weld stations.
Kyushu
Semiconductor and automotive component manufacturers in Fukuoka leverage Kyushu's lower operational costs for cloud infrastructure hosting. JIS standards compliance requirements shape product certification pathways for robotics vendors serving this emerging manufacturing hub. Samsung and TSMC supplier networks in Kumamoto drive specialized demand for collaborative robot orchestration.
Hokkaido
Precision agriculture robotics in Hokkaido integrate weather data APIs through cloud middleware for spraying and harvesting automation. METI regional revitalization programs subsidize cloud-connected farm equipment deployment to offset labor shortages. Sapporo-based agritech startups pilot subscription-based robot services for dairy and crop operations.
Japan Cloud Robotics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated industrial automation providers commanding premium positioning in enterprise deployments while software-centric entrants capture SME orchestration revenue. Market structure concentrates around three strategic archetypes: legacy motion-control conglomerates with captive cloud platforms, pure-play robotics software vendors, and systems integrators offering subscription-based managed services. Dominant competitive moves include backward integration into edge computing hardware and strategic partnerships with telecommunications providers for 5G private network deployment.
Within the legacy industrial tier, Fanuc Corporation and Yaskawa Electric Corporation exemplify the motion-control-to-cloud transition archetype, each leveraging decades of installed base relationships to anchor subscription software revenue. Mujin Inc. occupies a position representing the pure-play software-native competitor, unburdened by legacy hardware manufacturing overhead. These three entities collectively illustrate how competitive positioning in Japanese cloud robotics increasingly depends on balancing data sovereignty capabilities with scalable compute access rather than traditional robot hardware specifications.
| Leading Market Players |
|---|
| Fanuc Corporation |
| Yaskawa Electric Corporation |
| Mitsubishi Electric Corporation |
| Omron Corporation |
| Kawasaki Robotics |
| Mujin Inc. |
| Hitachi |
| Fujitsu |
| TRI-AD |
| Others |
Pricing and Supply Chain Analysis
Tier-1 automotive OEMs in Aichi and Kanagawa prefectures anchor procurement volume, concentrating pricing power around subscription-based orchestration models with uptime-guaranteed service level agreements rather than traditional capital expenditure structures.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for edge computing gateways and motion control semiconductors. Three-tier pricing structure across premium, standard, and economy levels separates Fanuc FIELD-enabled predictive maintenance bundles from basic cloud connectivity tiers. Cost compression in SME-targeted collaborative robot subscriptions is intensifying because software-native entrants like Mujin undercut legacy hardware bundling. Mid-tier precision manufacturers in Kyoto exhibit highest price sensitivity, while defense contractors and medical device manufacturers accept premium positioning for air-gapped private cloud compliance.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Toyota and Nissan tier-1 suppliers, while systems integrators in Kanto distribute subscription orchestration to SME clusters. Component manufacturing concentrates in Taiwan, South Korea, and China for low-latency semiconductors, precision sensors, and industrial-grade networking hardware. Japanese cloud robotics supply chains draw from imported edge gateways, domestic servo motor production, and Taiwanese GPU acceleration modules. Single-source vulnerability in advanced node semiconductor fabrication exposes deployment timelines to foundry allocation constraints. Distribution runs through authorized systems integrator partnerships for enterprise accounts and robotics-as-a-service platforms for pay-per-use SME adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's cloud robotics market represents a late-cycle quality story where METI's Society 5.0 interoperability mandates are shifting procurement toward certified, security-validated premium platforms over commodity hardware.
For Market Incumbents: Acquire specialized edge computing hardware capabilities to secure latency performance differentiation against software-native challengers. Deepen backward integration into semiconductor gateway design to mitigate foundry allocation risk. METI's Industrial Cybersecurity Framework certification investment is the critical defensive lever to extend incumbent positioning. For New Entrants and Emerging Players: Federated learning architectures for predictive quality control offer the most penetrable wedge into Aichi automotive supplier ecosystems. White-space concentration exists in Kyoto precision manufacturing SME clusters seeking pay-per-use orchestration without capital commitment. Nagoya port automation and Osaka logistics corridors present secondary expansion targets. Go-to-market execution should anchor through 5G private network partnerships with NTT Docomo or KDDI. For Investors and Strategic Acquirers: Industrial automation conglomerates with captive cloud platforms are the most active acquirer in this space, seeking software-native capabilities to complement hardware installed bases. Long-term viability centers on data sovereignty-compliant hybrid architectures balancing edge latency with cloud scale. Acquisition target archetype: pure-play robotics software vendors with METI certification progress and established systems integrator channel relationships. The signal to watch is PMDA clinical validation pathway advancement for surgical robotics, indicating healthcare revenue diversification beyond industrial automation.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Hardware Acquisition | Secures sub-100 millisecond latency performance for motion control against software-native competitors. |
| METI Cybersecurity Certification Investment | Accelerates product validation timelines for critical infrastructure sector access under Japanese Industrial Standards Committee oversight. |
| 5G Private Network Partnership | Enables ultra-reliable low-latency communication architectures for autonomous mobile robot fleet coordination in warehouse logistics. |
| SME Subscription Platform Launch | Captures Kyoto and Aichi precision manufacturing demand through operational expenditure models reducing balance-sheet automation exposure. |
| PMDA Clinical Validation Pathway | Opens healthcare revenue streams in surgical robotics and rehabilitation systems beyond industrial automation applications. |
Research Methodology
Direct dialogue with robotics OEM product managers, systems integrator technical leads, METI policy officers, and Tier-1 automotive procurement directors grounded qualitative findings. Secondary validation drew from METI white papers, JIS standards documentation, PMDA regulatory filings, and Industrial Value Chain Initiative technical specifications. Bottom-up deployment estimates triangulated against top-down market sizing from cloud infrastructure spend disclosures and robot installation records.
Segmentation outputs across product type, deployment architecture, application vertical, and end-user scale informed the analytical framework throughout the projection horizon. CAGRs were derived from installed base expansion rates, cloud connectivity penetration curves, and subscription revenue conversion assumptions. Key forecast inputs included 5G private network deployment timelines, METI smart factory subsidy allocation patterns, and cross-border data flow regulatory evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply chain normalization, PMDA validation timeline compression, and multi-tenant cloud architecture compliance interpretations. Forecasts reflect assumptions around METI interoperability standard adoption velocity and SME pay-per-use model penetration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
AGV Intelligent Management Systems Market
Robotics and Automation
Global Autonomous Mobile Robot Market
Robotics and Automation
Delta Robotics Market
Robotics and Automation
Consumer Robotics Market
Robotics and Automation
Thailand Cloud Robotics Market
Robotics and Automation
Robotic Flexible Washer Market
Robotics and Automation
Robotics Software Platforms Market
Robotics and Automation
Metal Fabrication Robots Market
Robotics and Automation
Underwater Drone Market
Robotics and Automation
Global Robot Kitchen Market
Robotics and Automation
North America Agricultural Robots and Mechatronics Market
Robotics and Automation
Robotic Process Automation in BFSI Market
Robotics and Automation
Global Underwater Robotics Market
Robotics and Automation
Humanoid Robot Market
Robotics and Automation
Robotics-Ready Fulfillment Center Design and Integration Services Market
Robotics and Automation
GCC AUV Market