
 Italy Biopesticides Market | 2026-2036
Italy Biopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Biopesticides Market Foresight
Multi-source procurement of microbial active ingredients is broadening among Italian formulators seeking supply resilience against seasonal fermentation bottlenecks. Koppert Biological Systems leverages its Dutch parent network to sustain domestic distribution of beneficial nematodes for vineyard soil treatments. BASF SE competes through granular formulation capacity anchored near Milan's logistics corridor. Novonesis differentiates with specialized bacteria strains for olive grove pest management.
Biopesticides comprise living organisms or naturally derived substances that suppress agricultural pests through biological mechanisms such as antagonism, parasitism, or induced plant resistance, typically requiring preservation of colony-forming units above threshold levels for efficacy. These products serve commercial growers seeking residue-compliant crop protection aligned with EU maximum residue limits for export-bound produce. Bacteria-based formulations lead volume demand in Italian tomato and pepper protected cultivation, while plant extracts command premium positioning in organic wine grape programs. Liquid formulations dominate application flexibility across mechanized spraying infrastructure, though granular carriers gain traction in soil-incorporation protocols for perennial orchards.
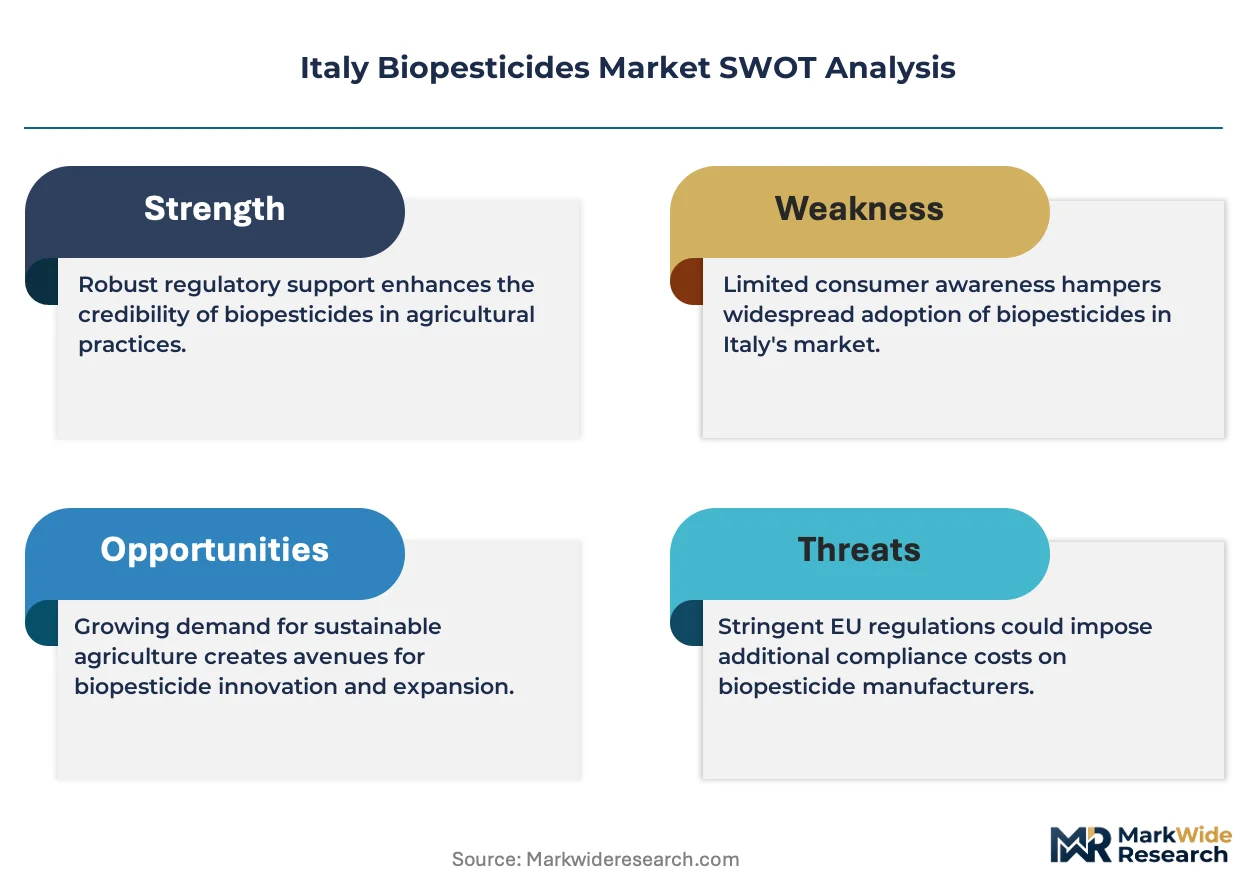
Italy's Ministry of Health coordinates biopesticide authorization under EU Regulation 1107/2009, with SINAB maintaining the national organic input registry that governs commercial access. REACH compliance shapes import requirements for non-microbial co-formulants, while the EU F-Gas Regulation indirectly redirects investment toward biological alternatives in controlled-environment agriculture. Stakeholders must monitor pending revisions to buffer zone requirements that could restrict conventional synthetic applications and expand addressable hectares for biological substitutes.
Market Dynamics
The EU Green Deal's Farm to Fork strategy compresses pesticide reduction timelines, forcing Italian vineyard operators and vegetable growers to accelerate biological control adoption before synthetic product buffers contract.
Growth Catalysts
- EU Green Deal pesticide reduction mandates:The Farm to Fork strategy establishes binding reduction targets that accelerate biopesticide registration timelines through streamlined authorization pathways under EU Regulation 1107/2009.
- Vineyard biological control expansion:Tuscany and Piedmont wine producers deploy microbial antagonists against downy mildew to meet organic certification requirements for export-bound premium wine.
- Protected cultivation bacteria demand:Tomato and pepper greenhouse operators in the Po Valley adopt Bacillus-based formulations to manage soil-borne pathogens while maintaining residue compliance.
Market Restraints
- Microbial fermentation supply concentration:Active ingredient production clusters in Dutch and Danish fermentation facilities, exposing Italian formulators to seasonal bottlenecks and currency-adjusted input volatility.
- REACH compliance friction for co-formulants:Non-microbial additives face extended safety data requirements under ECHA registration protocols, delaying product reformulation cycles by 18-24 months.
- Performance inconsistency against synthetic benchmarks:Living organism formulations require precise humidity and temperature windows that compressed application windows in Mediterranean climates cannot always accommodate.
Strategic Opportunities
- Olive grove bacteria specialization:Southern Apulia and Calabria orchards present underpenetrated hectares for Xylella fastidiosa management using strain-specific bacterial antagonists.
- Granular carrier soil-incorporation protocols:Perennial orchard operators seek slow-release biological formulations that reduce annual application labor costs through single-season incorporation.
- SINAB organic input registry expansion:Pending revisions to national organic certification standards will broaden commercially eligible biological active ingredient categories beyond current microbial limits.
Industry Challenges
- Colony-forming unit preservation expertise:Formulators struggle to recruit fermentation technologists capable of maintaining viable cell counts through Italy's summer distribution chain.
- Buffer zone compliance complexity:Vineyard operators face operational friction integrating biological spray schedules with pending revisions to minimum distance requirements for conventional synthetic applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Biopesticides Market |
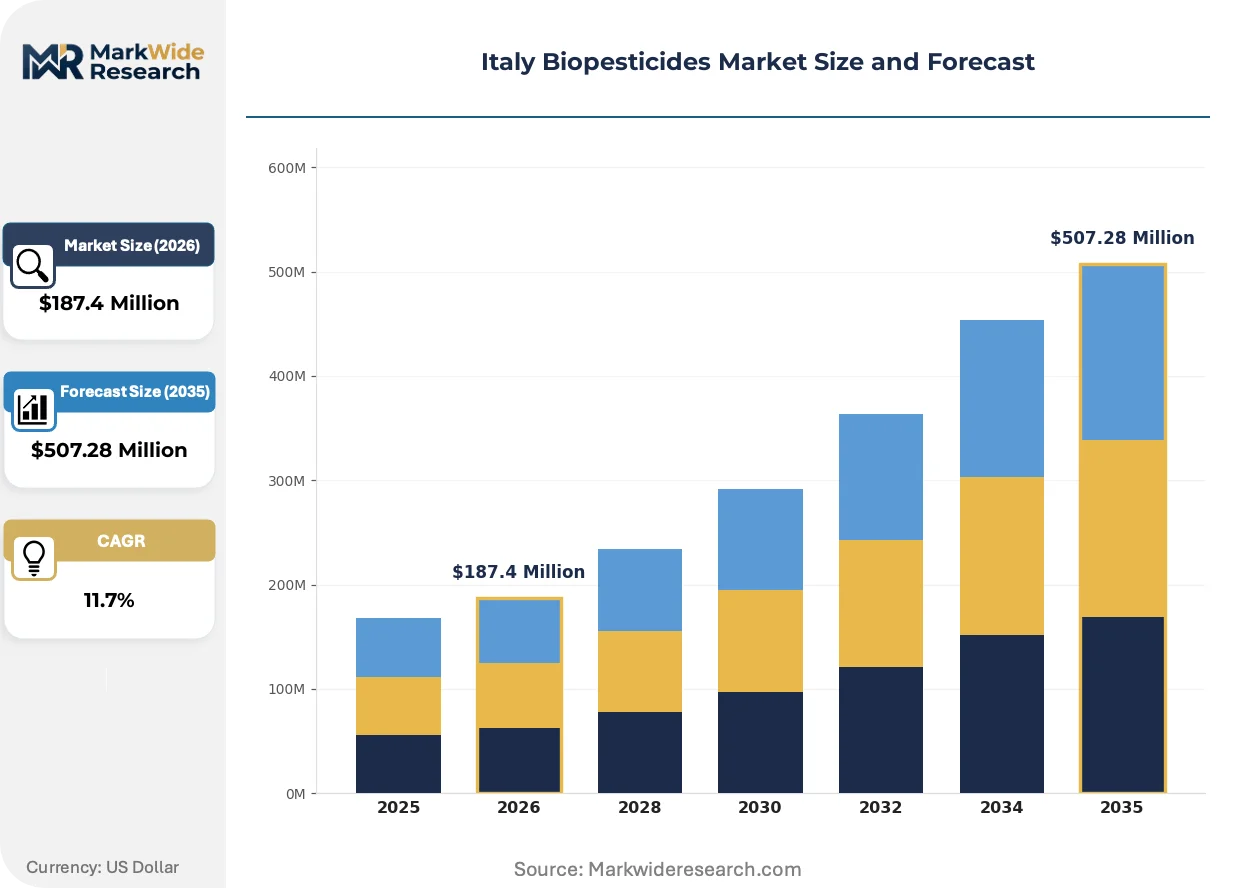
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nematodes, Bacteria, Fungi, Plant Extracts Application: Agricultural Crops, Horticultural Crops, Turf, Ornamental Plants Formulation: Granular, Liquid, Powder, Concentrate Distribution Channel: Online Retailers, Agricultural Stores, Distributors, Dealers |
| Companies Covered | Koppert Biological Systems, Novonesis, Lallemand Inc, BASF SE, Corteva Agriscience, Syngenta AG, Bayer CropScience AG, Valagro, Certis Europe, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Biopesticides Market Shifts & Advancements
Italian agriculture confronts a technology transition where biological efficacy validation, regulatory acceleration mechanisms, and procurement recalibration are compressing traditional crop protection adoption curves.
RNA interference technology is decentralizing pest management authority from centralized chemical manufacturers toward regional biotech laboratories and university research stations. Southern European vineyard cooperatives pilot sprayable dsRNA formulations against specific Lepidoptera pests. This molecular approach is decentralizing intellectual property control and shortening development cycles for localized pest pressures.
The EU F-Gas Regulation redirects controlled-environment agriculture investment toward biological alternatives by phasing out synthetic fumigants in greenhouse operations. Italian tomato and pepper protected cultivation facilities face accelerated compliance deadlines that compress equipment retrofit timelines. Northern Italian districts around Verona respond by integrating bacterial soil drenches into climate-controlled irrigation systems.
Buyer concentration among large-scale cooperative processors is reshaping procurement specifications for residue-compliant produce. Bologna-area vegetable packing houses now mandate biological pre-harvest intervals for supplier certification. This contractual pressure is most visible in the Emilia-Romagna processing tomato segment, where concentrate exporters require documented biological program adherence for EU retail channel access.
Italy Biopesticides Market Segmentation
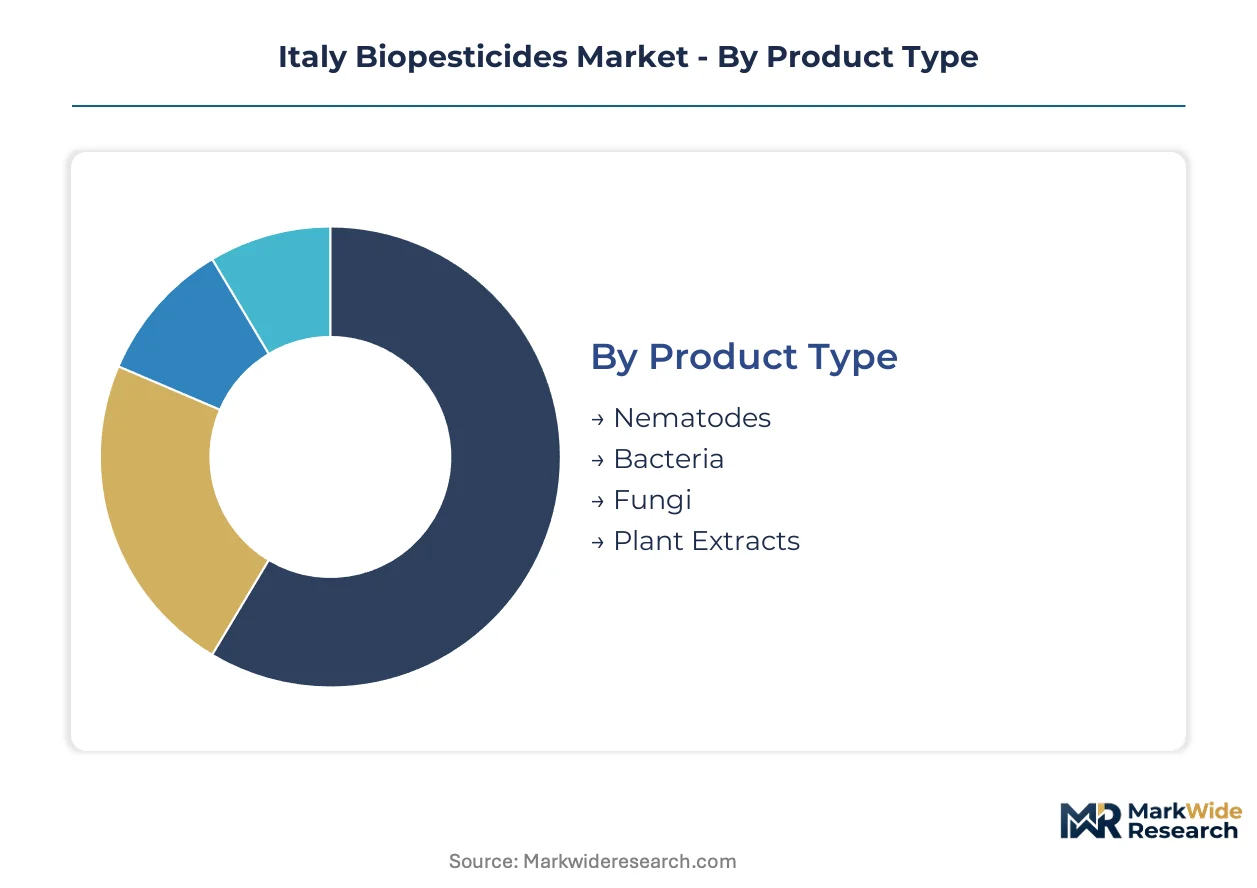
Biopesticide segmentation in Italy reflects divergent technical requirements across Mediterranean cropping systems, with formulation chemistry and target pest biology dictating viable product architectures for vineyard, greenhouse, and orchard operators.
Product Type:
Microbial taxonomy determines storage stability, application timing, and host specificity in Italian distribution networks.
- Bacteria:Bacillus-based formulations dominate protected cultivation in the Po Valley, where greenhouse operators deploy soil drenches against Pythium and Phytophthora root rot. Tomato and pepper growers around Bologna specify colony-forming unit thresholds above 10^9 CFU per gram to ensure viable inoculum through summer application windows. Demand concentrates in year-round protected systems where repeated cropping intensifies pathogen pressure.
- Fungi:Trichoderma and Beauveria strains command premium positioning in organic wine programs, with Piedmont vineyard cooperatives integrating mycoparasitic antagonists into downy mildew management protocols. These formulations require precise humidity maintenance during storage, forcing distributors to invest in climate-controlled warehousing near Milan's logistics corridor.
- Nematodes:Beneficial Steinernema and Heterorhabditis species target soil-dwelling insect larvae in orchard replant scenarios.
- Plant Extracts:Azadirachtin and pyrethrin-based botanicals serve residue-sensitive export channels.
Bacteria leads on scale; fungi leads on momentum.
Application:
Crop value per hectare and certification requirements segment addressable demand across Italian agricultural districts.
- Agricultural Crops:Vineyard biological programs in Tuscany and Piedmont anchor volume, with DOCG-designated producers mandating documented microbial antagonist use for organic export certification. Downy mildew pressure in humid vintage years accelerates replacement of copper-based alternatives.
- Horticultural Crops:Greenhouse tomato and pepper operations around Verona integrate bacterial soil treatments into hydroponic and substrate systems, driven by EU retailer residue specifications. Protected cultivation permits year-round application scheduling that living organisms require.
- Turf:Golf course and sports field maintenance in Lombardy adopts entomopathogenic nematodes for chafer grub management.
- Ornamental Plants:Nursery stock producers in Liguria deploy fungal biopesticides against whitefly and thrips in export-bound container production.
Agricultural crops commands revenue concentration; horticultural crops posts the steepest expansion trajectory.
Formulation:
Physical state dictates equipment compatibility and labor economics across mechanized versus manual application contexts.
- Liquid:Suspension concentrates and oil dispersions dominate mechanized spraying infrastructure in northern Italy's arable districts, permitting tank-mix flexibility with foliar fertilizers. Emulsion stability requirements shape co-formulant selection under REACH compliance protocols.
- Granular:Clay and peat-based carriers gain adoption in perennial orchards, where single-season soil incorporation reduces annual labor costs. Apulia olive growers specify slow-release matrices that maintain viable inoculum through dry summer conditions.
- Powder:Wettable powders persist in smallholder segments with backpack sprayer infrastructure.
- Concentrate:Ultra-high potency formulations reduce transport costs for export-oriented formulators.
Liquid formulation leads on installed equipment base; granular climbs the fastest on labor cost reduction.
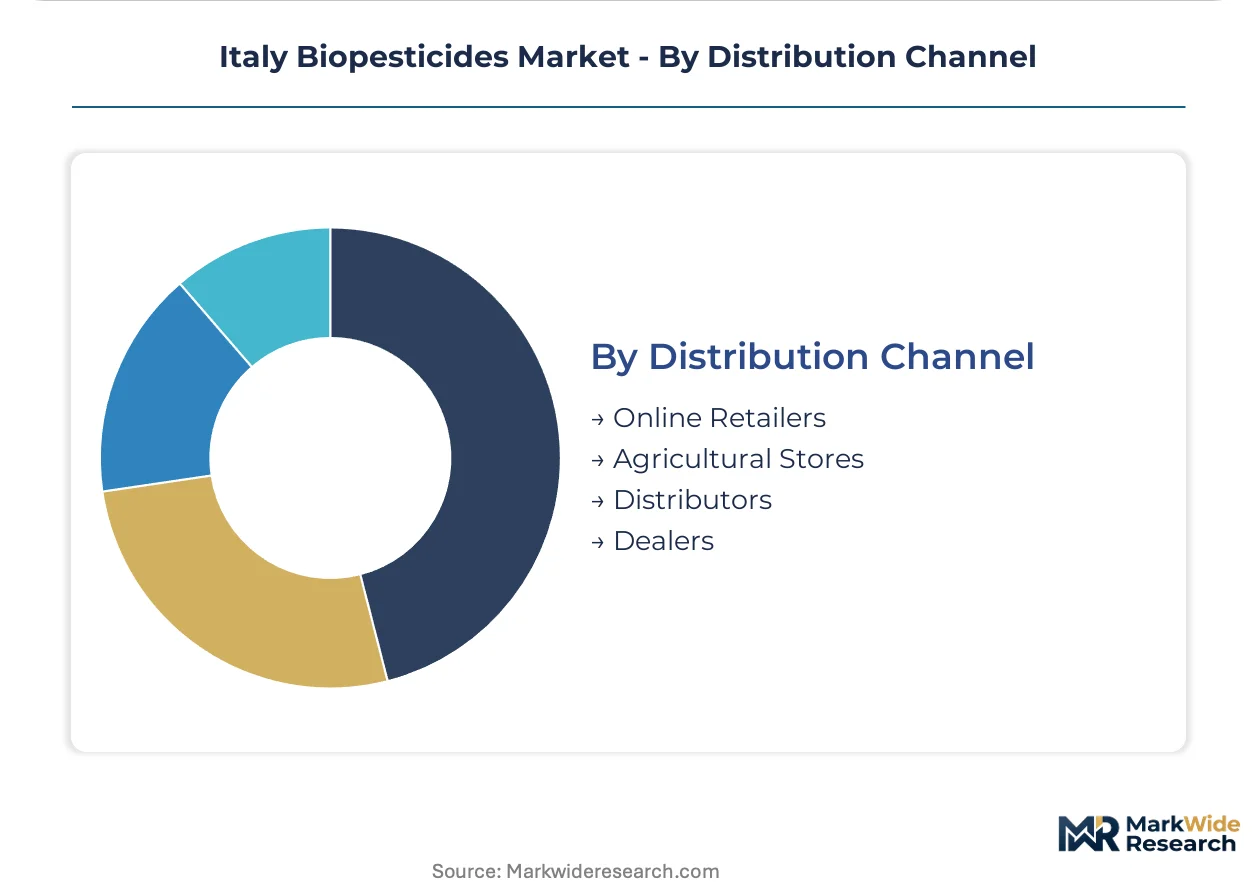
Distribution Channel:
Buyer scale and technical service requirements fragment route-to-market structures across Italian agricultural input supply chains.
- Distributors:Regional agricultural supply cooperatives in Emilia-Romagna and Veneto aggregate demand from fragmented vegetable growers, providing technical advisory on biological program timing. These intermediaries maintain cold chain integrity for living organism products through dedicated storage protocols.
- Agricultural Stores:Independent retail points in smaller municipalities serve hobby farmers and specialty crop producers with lower volume requirements.
- Dealers:Equipment-integrated sales channels bundle biopesticide recommendations with sprayer calibration services.
- Online Retailers:Direct-to-farm platforms emerge for standardized bacterial formulations with extended shelf stability.
Distributors anchor volume throughput; online retailers gain share fastest on convenience positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is concentrating biopesticide production in jurisdictions with streamlined EU Regulation 1107/2009 compliance pathways. Italian formulators exploit this cost-of-compliance gap by sourcing active ingredients from Dutch and Danish fermentation clusters while maintaining domestic formulation capacity near Milan's logistics corridor.
Lombardy
Granular formulation capacity anchors in the Milan logistics corridor where BASF SE maintains production infrastructure. The EU F-Gas Regulation redirects greenhouse investment toward bacterial soil treatments. Verona-area protected cultivation facilities integrate Bacillus-based drenches into climate-controlled irrigation systems for year-round tomato and pepper production.
Piedmont
Wine producers in DOCG-designated zones deploy Trichoderma mycoparasites against downy mildew pressure. The EU Green Deal's Farm to Fork pesticide reduction mandates accelerate biological control adoption ahead of synthetic buffer zone contractions. Vineyard cooperatives around Alba and Asti mandate documented microbial antagonist use for organic export certification to German and Swiss retail channels.
Emilia-Romagna
Processing tomato exporters around Bologna face contractual pressure from concentrate buyers mandating biological pre-harvest intervals. REACH compliance requirements for co-formulants delay product reformulation cycles. Vegetable packing houses in the Po Valley now require documented biological program adherence for EU retail channel access.
Apulia
Olive grove operators confront Xylella fastidiosa pressure with limited strain-specific bacterial antagonist penetration. Pending revisions to SINAB organic input registry standards will broaden eligible biological active ingredient categories. Southern orchards present underpenetrated hectares for slow-release granular matrices that maintain viable inoculum through dry summer conditions.
Tuscany
Organic wine certification requirements drive microbial antagonist demand in Chianti and Brunello production zones. The Ministry of Health coordinates authorization timelines that favor established microbial categories over novel strain submissions. Vineyard operators in humid vintage years accelerate copper replacement with biological downy mildew management protocols.
Italy Biopesticides Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized bacteria strain development for olive grove and vineyard applications. The market structure fragments across multinational agrochemical divisions, dedicated biological specialists, and regional fermentation subcontractors. Three archetypes dominate: integrated agrochemical conglomerates with biological portfolios, pure-play microbial specialists with strain libraries, and distribution-anchored service providers with technical advisory capacity. Competitive moves concentrate on multi-source procurement arrangements and granular formulation capacity expansion.
Within the microbial specialist tier, Koppert Biological Systems and Novonesis exemplify divergent strategic positions. Koppert leverages its Dutch parent network to sustain domestic distribution of beneficial nematodes for vineyard soil treatments. Novonesis occupies a specialization position anchored to bacteria strain development for olive grove pest management. BASF SE represents the integrated agrochemical archetype with granular formulation capacity near Milan's logistics corridor. These three companies illustrate how geographic origin and corporate structure shape competitive positioning without requiring identical capability investments.
| Leading Market Players |
|---|
| Koppert Biological Systems |
| Novonesis |
| Lallemand Inc |
| BASF SE |
| Corteva Agriscience |
| Syngenta AG |
| Bayer CropScience AG |
| Valagro |
| Certis Europe |
| Others |
Supply & Pricing Matrix
Fermentation technologist scarcity in the Po Valley widens pricing-tier spreads between premium viable-cell formulations and economy-grade alternatives. Labor-cost differentials between Dutch-Danish active ingredient clusters and Italian domestic formulation capacity compress margins for mid-tier products while sustaining premium positioning for strain-specialized offerings.
Pricing Analysis
Distributor margins absorb the primary cost compression from REACH compliance delays for co-formulants. Three-tier pricing structure across premium, standard, and economy levels separates SINAB-registered organic inputs from conventional biologicals and generic microbial formulations. Pricing pressure stems from currency-adjusted input volatility in fermentation-derived actives. Smallholder vegetable growers in Emilia-Romagna exhibit highest price sensitivity, while DOCG vineyard cooperatives accept premium positioning for export certification compliance.
Supply Chain Analysis
Freight costs from Dutch and Danish fermentation facilities to Milan's logistics corridor dictate active ingredient landed pricing. Italian formulators draw from concentrated microbial production in the Netherlands, Denmark, and Germany, with secondary sourcing from Spanish fermentation subcontractors. Single-source vulnerability concentrates in Steinernema nematode strains controlled by Koppert's Dutch parent network. Distribution runs through regional agricultural supply cooperatives that maintain cold chain integrity for living organism products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy Biopesticides Market functions as a stable compounder anchored by the EU Green Deal's binding pesticide reduction mandates, which institutionalize biological control demand across vineyard and protected cultivation sectors.
For Market Incumbents: Acquire granular formulation capacity near perennial orchard districts to lock in soil-incorporation protocol adoption. Consolidate multi-source procurement arrangements with Danish and Dutch fermentation clusters to hedge currency exposure. Defend against emerging pure-play microbial specialists by deepening SINAB registry relationships that accelerate authorization timelines for novel strain submissions. For New Entrants and Emerging Players: Capture underpenetrated olive grove hectares in Apulia and Calabria through Xylella fastidiosa-specific bacterial antagonist development. Target vineyard cooperatives in Tuscany seeking copper replacement protocols for humid vintage years. Pursue equipment-integrated distribution partnerships that bundle biological recommendations with precision application services. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fermentation subcontractors with strain libraries but limited formulation infrastructure. The five-to-ten year viability window favors pure-play microbial specialists over integrated agrochemical divisions facing portfolio cannibalization. Watch SINAB organic input registry revision timing as the inflection signal for eligible active ingredient category expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Acquisition | Consolidates intellectual property control for Xylella-specific bacterial antagonists in southern orchards. |
| Granular Formulation Capacity Expansion | Captures labor-cost reduction demand from perennial olive and vineyard operators seeking single-season incorporation. |
| SINAB Registry Relationship Investment | Accelerates authorization timelines under EU Regulation 1107/2009 for novel microbial categories. |
| Cold Chain Distribution Partnership | Secures viable-cell preservation through climate-controlled warehousing near Milan's logistics corridor. |
| Regional Fermentation Subcontracting | Diversifies active ingredient sourcing beyond Dutch-Danish concentration to mitigate currency volatility. |
Research Methodology
Bottom-up vineyard and greenhouse operator modeling reconciled against top-down fermentation capacity tracking forms the analytical core of this study. Primary interviews with formulation technologists, agricultural cooperative procurement managers, SINAB registry officials, and vineyard certification coordinators combined with secondary validation from EU Regulation 1107/2009 authorization databases, REACH compliance filings, and Italian Ministry of Health registration records. Triangulation between demand-side adoption metrics and supply-side production capacity ensures cross-verified outputs.
Historical trendline analysis of biological control penetration rates in DOCG-designated wine zones and Po Valley protected cultivation facilities established baseline growth patterns. Segmentation modeling across microbial taxonomy, crop application, physical formulation, and distribution channel dimensions generated discrete growth trajectories across the projection horizon. CAGRs derived from vintage-year weather variability correlations and EU F-Gas Regulation compliance deadlines for greenhouse operators.
Underlying measurement precision varies by segment; bacteria-based formulations in protected cultivation carry tighter precision than olive grove nematode applications due to established colony-forming unit standardization. Forecasts reflect assumptions regarding SINAB registry revision timing and EU Green Deal enforcement intensity that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Spain Biopesticides Market
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
Global Feed Phytogenics Market
Bio-Agriculture
Mycelium Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
US Bio Pesticides Market
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
North America Agricultural Biologicals Market
Bio-Agriculture
Mycorrhiza-Based Biofertilizer Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
Brazil Biopesticides Market
Bio-Agriculture
GCC Biofertilizer Market
Bio-Agriculture
Bionematicides Market
Bio-Agriculture
Europe Biological Organic Fertilizer Market
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
Australia Biopesticides Market