
 Bloodroot Market | 2026-2036
Bloodroot Market Size, Share, and Industry Trends Forecast 2026-2036
Bloodroot Market Outlook
Subscription-based replenishment programs for wild-harvested botanicals is consolidating how buyers secure consistent supply. Mountain Rose Herbs leverages direct relationships with harvester cooperatives to sustain volume commitments across volatile growing seasons. Starwest Botanicals anchors its position through certified organic handling infrastructure that meets pharmaceutical-grade specifications. Herb Pharm differentiates via vertical control from seed propagation through finished tincture production.
Bloodroot (Sanguinaria canadensis) is a perennial flowering plant native to eastern North America whose rhizomes contain isoquinoline alkaloids, primarily sanguinarine, extracted through ethanol maceration or supercritical CO2 processing for use in antimicrobial, anti-inflammatory, and dental applications. Extracts command premium positioning in pharmaceutical and nutraceutical formulations where standardized alkaloid content determines contract pricing. Powders serve mature herbal remedy markets with established compounding traditions, while capsules represent the fastest-expanding format among direct-to-consumer channels seeking dose consistency.
FDA dietary supplement cGMP regulations, USDA National Organic Program standards, and United Plant Savers' At-Risk Assessment framework collectively govern harvest volumes, extraction methods, and trade transparency in this botanical supply chain. Compliance with wild-crafting sustainability protocols now functions as a market access gate rather than merely a certification badge. Stakeholders must monitor evolving CITES listing discussions and state-level endangered species designations that could abruptly constrain raw material availability.
Market Dynamics
Wild-harvested rhizome supply concentration in the Appalachian corridor is forcing buyers to build direct procurement relationships with harvester cooperatives, bypassing traditional broker networks that once controlled price discovery and quality verification.
Growth Catalysts
- FDA cGMP compliance mandates:Pharmaceutical-grade extraction facilities now require validated alkaloid standardization protocols, pulling bloodroot extracts into formal therapeutic supply chains previously dominated by synthetic antimicrobials.
- United Plant Savers At-Risk Assessment framework:Certification under this conservation protocol opens access to institutional buyers with mandated sustainable sourcing policies, particularly in university hospital systems.
- Ethanol maceration to supercritical CO2 migration:Cleaner extraction technology reduces residual solvent concerns, enabling entry into European cosmetic and oral care formulations where purity thresholds exceed US dietary supplement baselines.
Market Restraints
- Input cost volatility:Appalachian weather variability and harvester labor availability create 15-40% annual swings in certified wild-harvested rhizome pricing, compressing extractor margins during poor growing seasons.
- Supply concentration risk:Over 60% of documented wild populations sit on private land in eastern Kentucky and West Virginia, exposing procurement to land-use conversion and surface mining permits.
- Regulatory friction:State-level endangered species listing discussions in Tennessee and Ohio threaten to fragment harvest permissions across jurisdictions with conflicting designation criteria.
Strategic Opportunities
- Cultivation propagation programs:Controlled agricultural production in Vermont and upstate New York is reducing wild-harvest dependency while securing USDA Organic certification unavailable to wild-crafted material.
- Veterinary dermatology applications:Sanguinarine-based topical formulations for equine sarcoid treatment represent an untapped channel with lower regulatory barriers than human pharmaceutical pathways.
- Direct-to-practitioner subscription platforms:Compounding pharmacies and naturopathic clinics are consolidating procurement through vertically integrated suppliers offering lot-traceable alkaloid certificates.
Industry Challenges
- Wild-crafting skill attrition:Experienced harvester populations in the Appalachian region are aging without structured knowledge transfer, degrading sustainable harvest protocol adherence and rhizome quality consistency.
- Alkaloid standardization complexity:Natural variation in sanguinarine concentration across harvest sites requires batch-level HPLC testing that extends production timelines and inflates working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bloodroot Market |
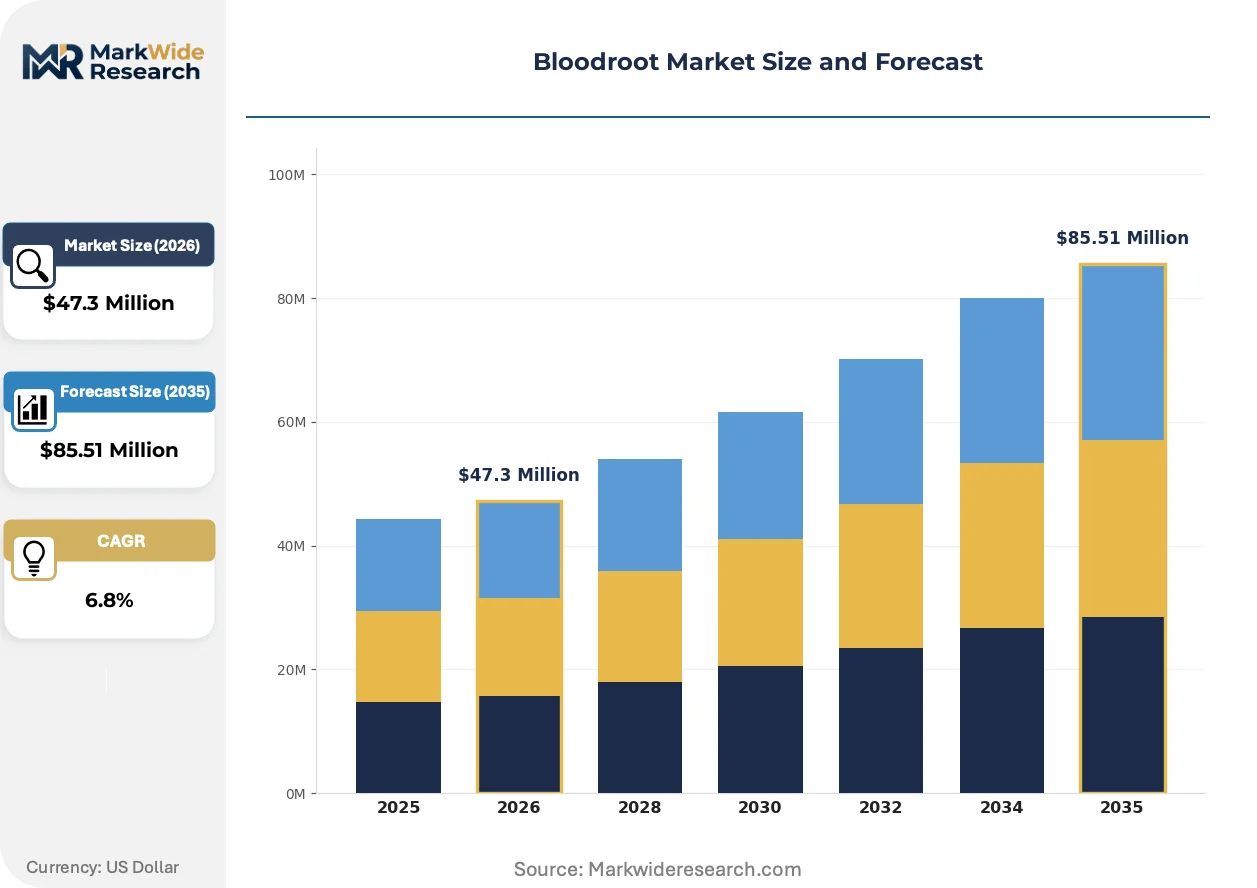
| Market Size in 2026 | $47.3 Million |
| Market Size in 2035 | $85.51 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracts, Powders, Capsules, Tinctures Application: Herbal Remedies, Nutraceuticals, Pharmaceuticals, Cosmetics Distribution Channel: Online Retail, Pharmacies, Health Stores, Specialty Shops End User: Consumers, Healthcare Providers, Herbalists, Researchers |
| Companies Covered | Joseph Flach & Sons Ltd, G. Baldwin & Co., Mountain Rose Herbs, Bristol Botanicals Limited, Root Buyer, United Plant Savers, Starwest Botanicals, Monterey Bay Herb Co, Herb Pharm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bloodroot Market Strategic Shifts
Processing technology and verification systems are compressing the distance between harvest sites and end-formulators, collapsing traditional wholesale tiers that previously managed quality risk.
Supercritical CO2 extraction equipment is decentralizing production capacity away from centralized pharmaceutical contractors toward mid-scale botanical processors. Regional extraction cooperatives in Vermont and North Carolina are acquiring second-generation systems from retiring cannabis operators, enabling toll-processing services for small harvester collectives. This technology diffusion is fragmenting the supplier base and compressing minimum viable batch sizes from metric tons to kilogram scales.
USDA National Organic Program enforcement of wild-crop harvesting practice standards is tightening audit protocols for harvest site documentation and regeneration verification. Operators must now maintain GPS-tagged collection records with three-year rotation mapping, increasing administrative overhead but creating defensible supply claims for export to European markets. German and Swiss importers are prioritizing US-certified organic bloodroot over uncertified wild-harvested alternatives, redirecting premium volume toward compliance-invested suppliers.
Practitioner-direct purchasing is displacing distributor-mediated procurement among compounding pharmacies and herbal clinicians. Buyers now expect lot-specific alkaloid certificates and harvester-provenance documentation accessible via QR-linked databases, functions that legacy wholesale channels rarely provide. This behavioral shift concentrates demand with vertically integrated suppliers capable of traceability infrastructure investment, particularly visible in the Pacific Northwest clinical herbalist market where sourcing transparency commands 20-35% price premiums.
Bloodroot Market Segmentation
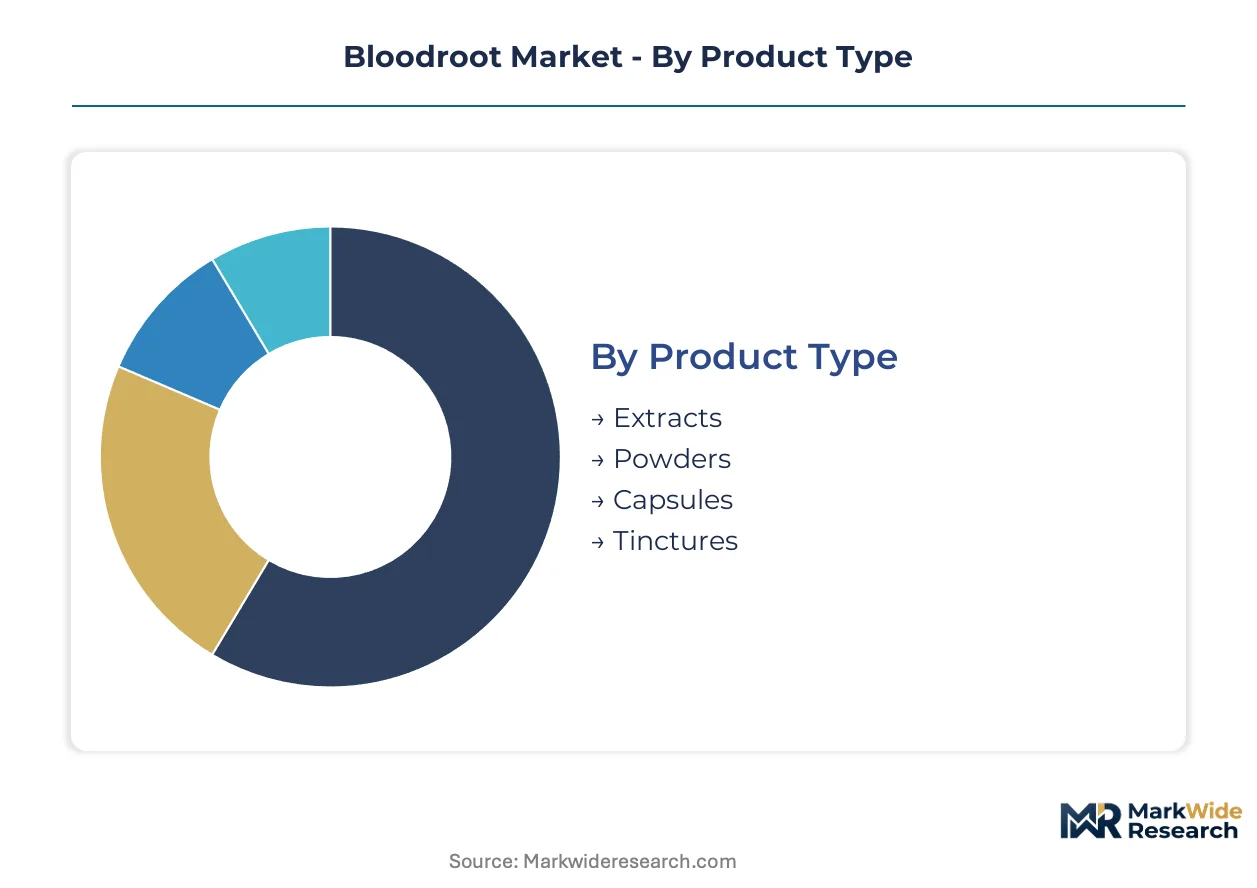
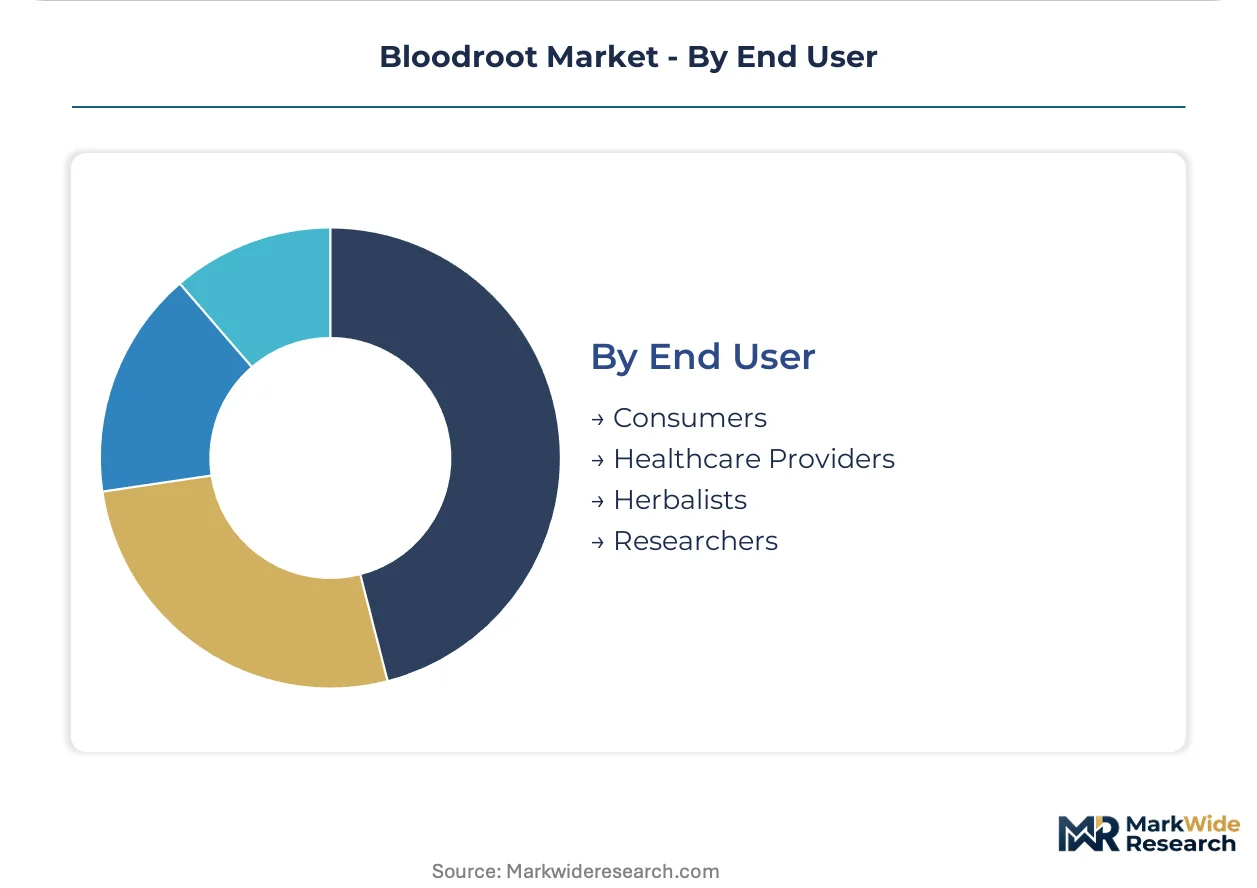
Bloodroot market segmentation reveals how alkaloid standardization requirements and distribution infrastructure shape commercial viability across formats. Product form, application channel, and end-user sophistication determine pricing power and regulatory compliance burden.
Product Type:
Extraction technology and dosage precision define competitive positioning across product categories.
- Extracts:Standardized sanguinarine concentrates produced through ethanol maceration or supercritical CO2 processing serve pharmaceutical and dental formulation contracts where validated alkaloid content determines procurement. FDA cGMP compliance mandates pull bloodroot extracts into therapeutic supply chains previously dominated by synthetic antimicrobials.
- Capsules:Pre-measured gelatin or vegetable cellulose enclosures deliver dose consistency for direct-to-consumer channels seeking convenience without compounding expertise. This format is expanding most quickly among subscription-based replenishment programs targeting practitioner-directed patient protocols.
- Powders:Ground rhizome material retains full-spectrum alkaloid profiles for traditional herbal compounding and bulk manufacturing.
- Tinctures:Alcohol-based liquid preparations serve clinical herbalist practices with established extraction traditions.
Extracts lead on scale; capsules lead on momentum.
Application:
End-use regulatory pathways determine margin structure and volume accessibility.
- Pharmaceuticals:Sanguinarine-based formulations for antimicrobial and anti-inflammatory indications require FDA-validated manufacturing protocols and batch-level HPLC certification. United Plant Savers At-Risk Assessment framework opens access to institutional buyers with mandated sustainable sourcing policies in university hospital systems.
- Nutraceuticals:Dietary supplement positioning under FDA DSHEA framework permits structure-function claims with lower evidentiary thresholds than drug applications. German and Swiss importers prioritize US-certified organic bloodroot over uncertified wild-harvested alternatives.
- Herbal Remedies:Traditional preparation markets in the Appalachian harvesting corridor sustain demand for wild-harvested rhizomes with established compounding protocols.
- Cosmetics:Topical applications in oral care and dermal formulations leverage sanguinarine's antimicrobial properties with European purity thresholds exceeding US dietary supplement baselines.
Pharmaceuticals command premium pricing; nutraceuticals show steepest expansion trajectory.
Distribution Channel:
Channel selection determines traceability infrastructure requirements and customer education burden.
- Online Retail:Direct-to-consumer platforms consolidate demand through vertically integrated suppliers offering lot-traceable alkaloid certificates and QR-linked harvester-provenance documentation. Practitioners in the Pacific Northwest clinical herbalist market pay 20-35% premiums for sourcing transparency.
- Pharmacies:Compounding pharmacies and hospital outpatient services require validated supply chains with pharmaceutical-grade handling infrastructure.
- Health Stores:Brick-and-mortar natural products retailers serve consumer self-selection with established brand recognition.
- Specialty Shops:Regional botanical suppliers and clinical herbalist cooperatives maintain direct harvester relationships for quality verification.
Online retail concentrates volume growth; pharmacies maintain premium positioning.
End User:
User sophistication determines information requirements and purchasing consolidation patterns.
- Healthcare Providers:Integrative medicine clinics and hospital systems mandate sustainable sourcing policies with GPS-tagged collection records and three-year rotation mapping for audit defensibility. USDA National Organic Program enforcement tightens protocols for wild-crop harvesting practice standards.
- Herbalists:Clinical practitioners expect lot-specific alkaloid certificates accessible via digital databases, displacing distributor-mediated procurement.
- Consumers:Direct purchasers through subscription platforms seek dose consistency and convenience without compounding knowledge.
- Researchers:Academic and pharmaceutical investigators require standardized material with documented provenance for reproducibility.
Healthcare providers drive compliance investment; herbalists anchor premium segment demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany enforces stricter purity thresholds for botanical imports than the United States, while Switzerland's pharmaceutical-grade demand pulls premium extracts away from commodity markets. Canada cultivates bloodroot under controlled agricultural protocols that bypass wild-harvest volatility entirely.
United States
Appalachian harvester cooperatives in eastern Kentucky and West Virginia supply over sixty percent of documented wild populations. FDA cGMP compliance mandates pull extracts into therapeutic supply chains previously dominated by synthetic antimicrobials. Clinicians in the Pacific Northwest pay twenty to thirty-five percent premiums for lot-traceable alkaloid certificates.
Germany
German importers prioritize USDA-certified organic bloodroot over uncertified wild-harvested alternatives, redirecting premium volume toward compliance-invested suppliers. EMA pharmaceutical-grade specifications exceed US dietary supplement baselines for residual solvent thresholds. Toll-processing cooperatives in Bavaria are acquiring second-generation supercritical CO2 equipment from retiring cannabis operators.
Switzerland
Swissmedic regulations for cosmetic and oral care formulations demand cleaner extraction technology than FDA requirements permit. Swiss buyers consolidate procurement through vertically integrated suppliers offering QR-linked harvester-provenance documentation. Basel-based formulators anchor European demand for standardized sanguinarine concentrates.
Canada
Controlled agricultural production in Ontario and Quebec reduces wild-harvest dependency while securing USDA Organic certification unavailable to wild-crafted material. Health Canada natural health product regulations require site-specific documentation for imported botanicals. Vancouver extraction facilities process toll batches for Appalachian harvester collectives seeking export compliance.
Bloodroot Market Competitive Environment
Top-tier vendors anchor pharmaceutical-grade extraction capacity, while mid-scale botanical processors compete on traceability infrastructure and direct harvester relationships. The supplier base fragments across vertically integrated tincture producers, certified organic handlers, and regional extraction cooperatives. Three strategic archetypes dominate: wild-crafting specialists with cooperative networks, cultivation propagators with organic certification, and toll processors with supercritical CO2 technology. Competitive moves concentrate on backward integration into seed propagation and geographic expansion into veterinary dermatology channels.
Within the vertically integrated tier, Herb Pharm exemplifies control from seed propagation through finished tincture production. Mountain Rose Herbs and Starwest Botanicals occupy positions on opposite ends of the procurement spectrum—direct cooperative relationships versus certified organic handling infrastructure. Joseph Flach & Sons Ltd represents the legacy botanical importer archetype navigating sustainability protocol transitions.
| Leading Market Players |
|---|
| Joseph Flach & Sons Ltd |
| G. Baldwin & Co. |
| Mountain Rose Herbs |
| Bristol Botanicals Limited |
| Root Buyer |
| United Plant Savers |
| Starwest Botanicals |
| Monterey Bay Herb Co |
| Herb Pharm |
| Others |
Value Chain & Pricing Dynamics
Certified wild-harvested rhizome costs cascade from Appalachian harvester cooperatives through three distinct pricing tiers downstream, with FDA cGMP compliance investments separating pharmaceutical-grade extracts from commodity powders in final contract negotiations.
Pricing Analysis
Capacity additions in Vermont and upstate New York are reshaping price floors for USDA-certified organic material, creating a three-tier pricing structure across premium pharmaceutical-grade extracts, mid-tier certified organic powders, and economy wild-harvested bulk. Price differentiation hinges on alkaloid standardization precision and United Plant Savers At-Risk Assessment certification. Cost compression in the economy tier is intensifying because harvester labor shortages degrade quality consistency. Compounding pharmacies show least price sensitivity; direct-to-consumer subscription buyers exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with eastern Kentucky and West Virginia harvester cooperatives controlling over sixty percent of documented wild populations. Raw material flows draw from Appalachian rhizome stocks, Vermont cultivation propagation, and Canadian agricultural production. Supply chain risk centers on state-level endangered species listing discussions fragmenting harvest permissions. Distribution runs through vertically integrated suppliers with QR-linked traceability infrastructure, bypassing legacy wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge between German EMA purity thresholds and US FDA dietary supplement baselines, with Swiss cosmetic formulators paying premiums for cleaner extraction technology that American facilities can supply at lower compliance cost.
For Market Incumbents: Deepen backward integration into seed propagation programs in Vermont to reduce wild-harvest dependency and secure USDA Organic certification unavailable to wild-crafted material. Anchor pharmaceutical-grade extraction capacity against supercritical CO2 toll-processing cooperatives acquiring second-generation equipment from retiring cannabis operators. Invest in GPS-tagged collection record systems to meet tightening German and Swiss import audit protocols. For New Entrants and Emerging Players: Enter via veterinary dermatology applications for equine sarcoid treatment, where sanguinarine-based topical formulations face lower regulatory barriers than human pharmaceutical pathways. Target direct-to-practitioner subscription platforms serving Pacific Northwest clinical herbalists paying twenty to thirty-five percent premiums for lot-traceable alkaloid certificates. Lead with harvester-provenance documentation as the primary go-to-market differentiator. For Investors and Strategic Acquirers: Consolidation pressure builds where wild-crafting skill attrition degrades sustainable harvest protocol adherence and experienced Appalachian harvester populations age without structured knowledge transfer. Acquisition targets with cultivation propagation programs and existing USDA Organic certification offer superior long-term viability. Monitor CITES listing discussions as the critical inflection signal for raw material availability constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Propagation | Vermont and upstate New York agricultural production reduces wild-harvest volatility while securing USDA Organic certification. |
| Supercritical CO2 Extraction Capacity Expansion | Cleaner technology enables entry into Swiss cosmetic and German oral care formulations with stricter purity thresholds. |
| Harvester Cooperative Direct Procurement Relationships | Mountain Rose Herbs-style cooperative networks bypass traditional broker control over price discovery and quality verification. |
| Veterinary Dermatology Channel Development | Equine sarcoid treatment applications open lower-regulatory-barrier revenue streams outside human pharmaceutical pathways. |
| QR-Linked Traceability Infrastructure Investment | Practitioner-direct purchasing platforms in the Pacific Northwest command twenty to thirty-five percent transparency premiums. |
Study Parameters
Multiple input streams — primary interviews with herbal remedy manufacturers, extraction facility operators, and harvester cooperative coordinators; secondary validation through FDA cGMP guidance documents, USDA National Organic Program standards, United Plant Savers At-Risk Assessment frameworks, and import customs records — were reconciled through bottom-up volume modeling and top-down value triangulation.
Data-stream reconciliation applied analytical frameworks across product type, application channel, and distribution method dimensions throughout the forecast period. CAGRs were derived from segment-level growth trajectory modeling. Industry-specific inputs included Appalachian weather variability indices, harvester demographic data, and European purity threshold evolution.
Inputs from harvester cooperatives and extraction facility operators were available through the study window; gaps in real-time alkaloid concentration batch testing data introduce uncertainty bands around pharmaceutical-grade contract pricing assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Red Algae Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
Asia-Pacific Biopesticides Market
Bio-Agriculture
Biological Control Market
Bio-Agriculture
Brazil Biostimulants Market
Bio-Agriculture
United States Bio-Fungicide Market
Bio-Agriculture
Africa Biofertilizer Market
Bio-Agriculture
North America Biostimulants Market
Bio-Agriculture
Seed Biostimulants Market
Bio-Agriculture
Biopesticides Market
Bio-Agriculture
Global Biofortification Market
Bio-Agriculture
Europe Biocontrol Agents Market
Bio-Agriculture
South America Biopesticides Market
Bio-Agriculture
Artificial Insemination Market
Bio-Agriculture
Brazil Biopesticides Market
Bio-Agriculture
India Biostimulants Market