
 Face Cream Market | 2026-2036
Face Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Face Cream Market Analytics
Clinical-grade efficacy is reorganizing competitive dynamics in face cream, as consumers trade up from basic moisturizers to dermatologist-validated formulas. L'Oréal leverages its R&D infrastructure to anchor premium positioning across multiple continents. Estée Lauder Companies sustains brand equity through heritage luxury channels. Beiersdorf competes with science-driven claims in the sensitive-skin niche.
A face cream is a semi-solid emulsion formulated with oil-in-water or water-in-oil systems, typically containing humectants, emollients, and active concentrations between 0.5% and 5% for functional ingredients, designed to hydrate, protect, or treat facial skin. Anti-aging creams with retinol command the highest margin pools due to clinical substantiation requirements and premium pricing power, while moisturizers remain the volume anchor across mass and prestige tiers. Hyaluronic acid formulations lead ingredient-led growth as consumers prioritize visible hydration claims, and natural extracts face supply-chain volatility that constrains scaling.
The FDA oversees cosmetic safety labeling in the United States, while REACH and the EU Cosmetics Regulation govern ingredient disclosure and banned substance lists across Europe, forcing reformulation cycles that raise compliance costs but also create barriers for unverified entrants. China's NMPA and GB standards add another layer of testing mandates for imported face creams. Stakeholders must monitor tightening microplastic restrictions and evolving clean-beauty definitions that threaten legacy preservative systems.
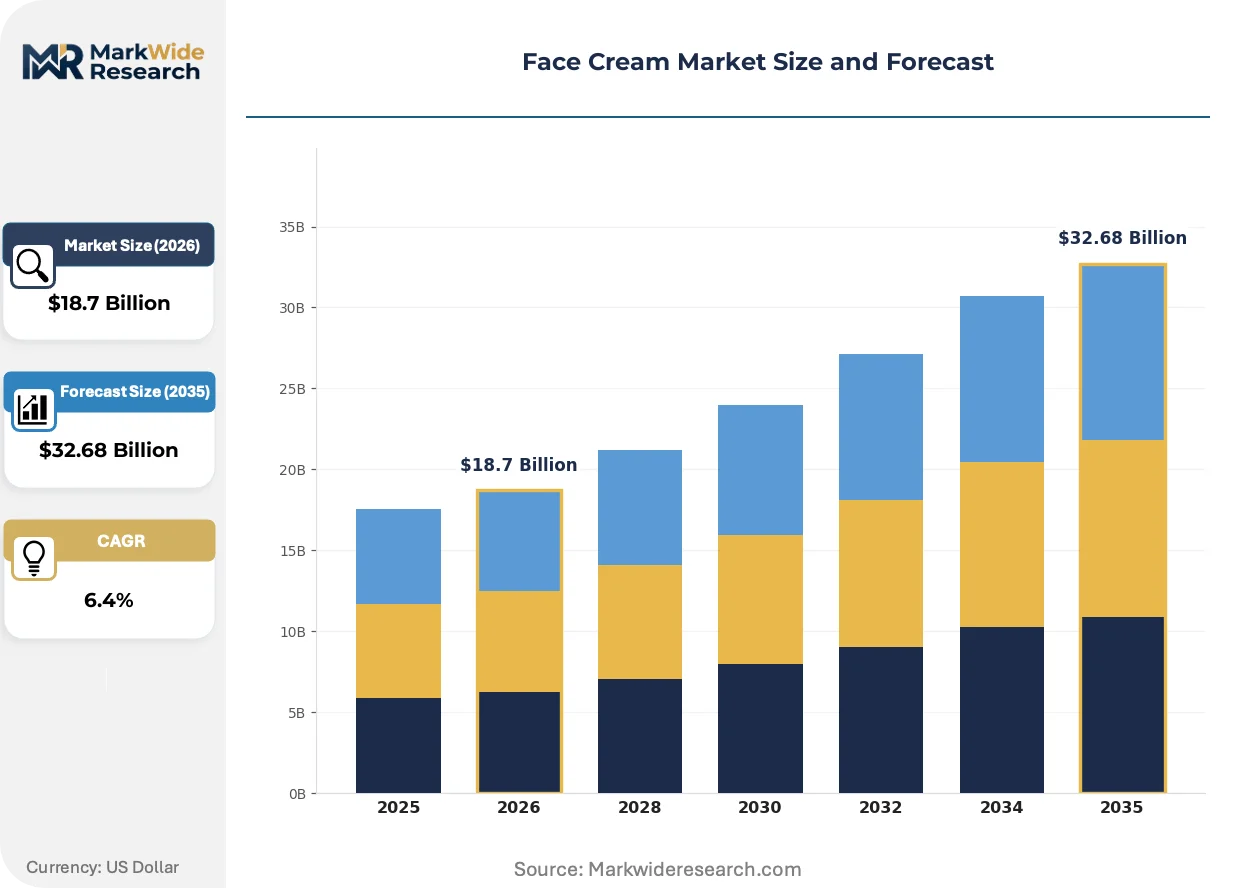
Market Dynamics
Clinical validation requirements are compressing R&D timelines across the face cream sector, as dermatologist endorsement replaces traditional marketing claims as the primary purchase driver. Formulators must now substantiate efficacy through peer-reviewed studies before securing retail placement.
Growth Catalysts
- Men's grooming expansion:Male consumers in the United States and South Korea are adopting multi-step skincare routines, creating incremental demand for specialized facial moisturizers and anti-aging solutions.
- REACH compliance premium:EU Cosmetics Regulation adherence enables European brands to command price premiums in export markets where ingredient transparency is valued.
- Retinol stabilization advances:Encapsulation technologies extend active shelf life, allowing broader distribution of clinical-grade formulations through mass retail channels.
Market Restraints
- Natural extract volatility:Botanical ingredient sourcing faces climate-driven supply disruptions, particularly for shea butter from West African cooperatives and rosehip oil from Chilean harvests.
- Preservative system reformulation costs:Clean-beauty definitions are forcing abandonment of established paraben and formaldehyde-releasing chemistries, raising manufacturing complexity.
- Microplastic restriction timelines:The EU's tightening limits on synthetic polymers in rinse-off products are extending to leave-on face creams, requiring texture modifier replacements.
Strategic Opportunities
- India's tier-two cities:Underpenetrated urban centers beyond Mumbai and Delhi present whitespace for dermatologist-dispensed and pharmacy-channel face cream expansion.
- Biotechnology convergence:Fermentation-derived actives and lab-grown collagen are enabling novel claims that bypass traditional agricultural supply chains.
- SAMR pathway optimization:Streamlined registration procedures for imported cosmetics in China reduce time-to-market for compliant foreign brands.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in emulsion stability and active compatibility is concentrating among senior professionals nearing retirement.
- Clinical trial capacity bottlenecks:Dermatological testing facilities face backlogs for efficacy substantiation, delaying product launches by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Face Cream Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Anti-Aging Creams, Sunscreens, Specialty Creams Ingredient: Hyaluronic Acid, Retinol, Niacinamide, Natural Extracts Packaging Type: Tubes, Jars, Pumps, Sachets Target Audience: Women, Men, Teens, Sensitive Skin |
| Companies Covered | Estée Lauder Companies, Johnson & Johnson, L'Oréal, Shiseido, Coty, Procter & Gamble, Beiersdorf, Amorepacific, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Face Cream Market Evolving Landscape
Personalization technologies are dissolving the mass-market uniform formulation model, replacing it with adaptive systems that respond to individual skin microbiome profiles and environmental exposure patterns.
Microbiome-targeted ingredients are fragmenting the traditional moisturizer category. Brands incorporating live cultures and prebiotic fibers attract consumers with sensitive skin conditions. L'Oréal's research subsidiaries and independent biotech suppliers are scaling fermentation capacity to meet this demand. The technology is compressing margins for conventional emulsion-based products that lack functional differentiation.
REACH substance restrictions are forcing ingredient substitution cycles across European manufacturing. The ban on certain UV filters and fragrance allergens requires reformulation of legacy products. Asian export-dependent brands are establishing EU-based R&D centers to accelerate compliance. Sensitive-skin and pediatric segments face the steepest adaptation costs due to narrower approved ingredient lists.
Direct-to-consumer subscription models are capturing repeat purchase loyalty previously held by department store counters. Digital-native brands bypass traditional retail markups through owned e-commerce platforms. South Korean and United States-based entrants lead this channel shift. Dermatologist-backed lines are following suit, launching telemedicine-integrated replenishment programs.
Face Cream Market Segmentation
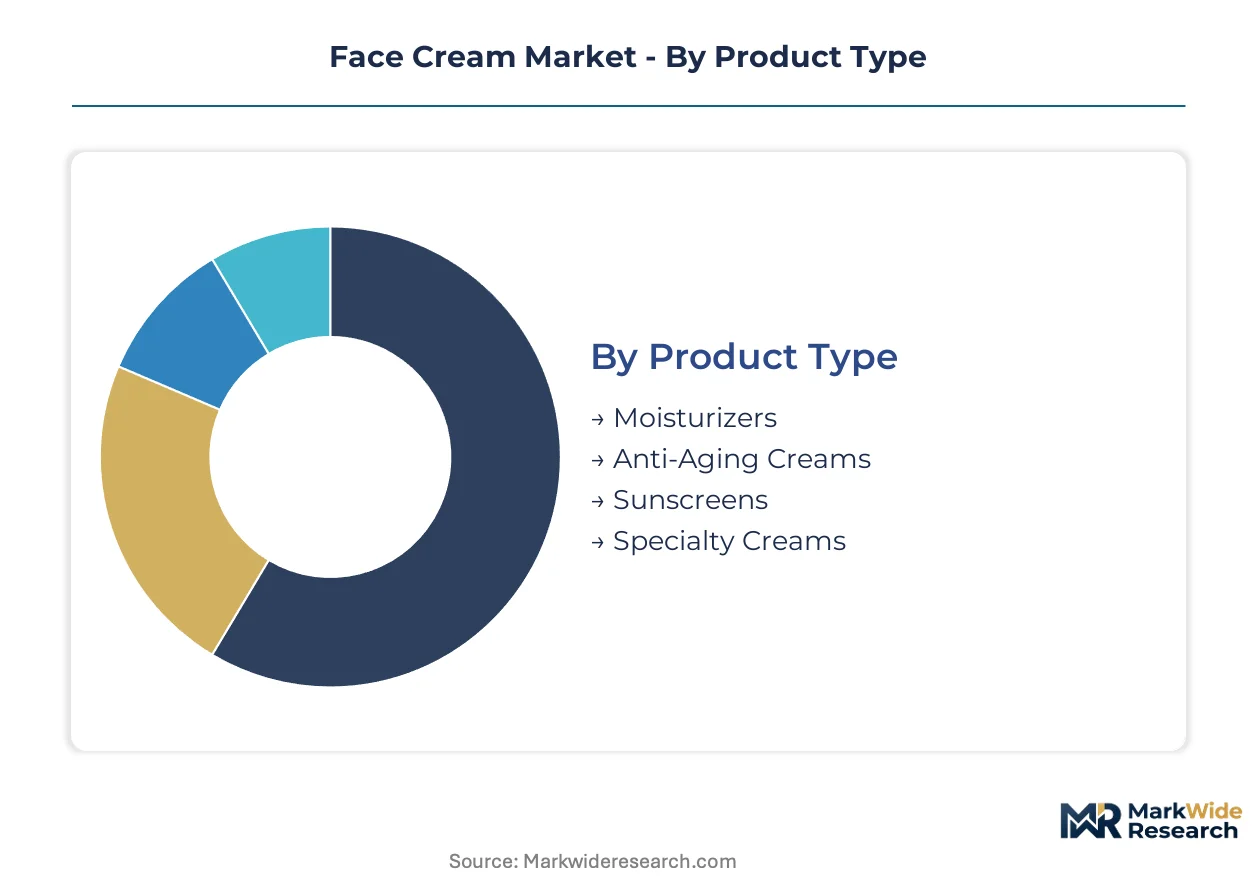
Face cream segmentation reveals how formulation science, distribution channels, and consumer demographics intersect to create distinct margin profiles. Manufacturers align R&D investment with channel-specific performance requirements rather than pursuing uniform product architectures.
Product Type:
Channel mix varies sharply by product type, with prestige retailers favoring anti-aging formulations while mass channels anchor volume through basic moisturizers.
- Moisturizers:Water-in-oil and oil-in-water emulsions with humectant concentrations between 2% and 10% form the volume foundation. United States mass retail and pharmacy channels concentrate demand here, driven by replacement purchase frequency and lower trial barriers for new entrants.
- Anti-Aging Creams:Retinol-stabilized and peptide-complex formulations command premium shelf placement in department stores and dermatology clinics. South Korea's duty-free channels and United States med-spa retail concentrate demand, propelled by clinical substantiation requirements that filter out undercapitalized competitors.
- Sunscreens:SPF-integrated daily wear creams with photostabilized organic filters. Beach and outdoor recreation markets in Australia and coastal United States drive seasonal demand spikes.
- Specialty Creams:Melasma-targeted, rosacea-specific, and post-procedure recovery formulations. Dermatologist dispensing in Germany and France anchors this niche.
By volume, Moisturizers leads. By growth pace, Anti-Aging Creams is ahead.
Ingredient:
Cost tier stratification separates commodity humectants from biotechnology-derived actives, with fermentation capacity constraints limiting supply elasticity at the premium end.
- Hyaluronic Acid:Cross-linked and multi-molecular weight variants enable layered hydration claims. Chinese manufacturing clusters supply raw material, though European pharmaceutical-grade purification commands price premiums in German and Swiss markets.
- Retinol:Encapsulation technologies and esterified derivatives improve tolerability profiles. United States clinical skincare channels concentrate demand, constrained by stability testing backlogs that extend launch timelines.
- Niacinamide:2% to 5% concentration ranges dominate brightening and barrier-repair positioning. Southeast Asian e-commerce platforms drive volume acceleration.
- Natural Extracts:Centella asiatica, green tea polyphenols, and fermented botanicals. Climate volatility in Madagascar and Chile constrains reliable sourcing.
By volume, Hyaluronic Acid leads. By margin expansion, Retinol is climbing the fastest.
Packaging Type:
Application method shapes preservation requirements and unit economics, with airless systems commanding manufacturing investment that smaller formulators cannot replicate.
- Tubes:Laminated and mono-material structures dominate travel-size and masstige positioning. European recycling infrastructure favors aluminum-plastic hybrids.
- Jars:Wide-mouth glass and heavy-wall PET signal luxury positioning. South Korean and French heritage brands anchor demand here.
- Pumps:Airless and metered-dose systems protect retinol and vitamin C stability. United States dermocosmetic lines mandate this format.
- Sachets:Single-use foil and biodegradable film samples drive trial conversion in Indian and Indonesian pharmacy channels.
By volume, Tubes leads. By sustainability-driven replacement, Pumps is gaining share fastest.
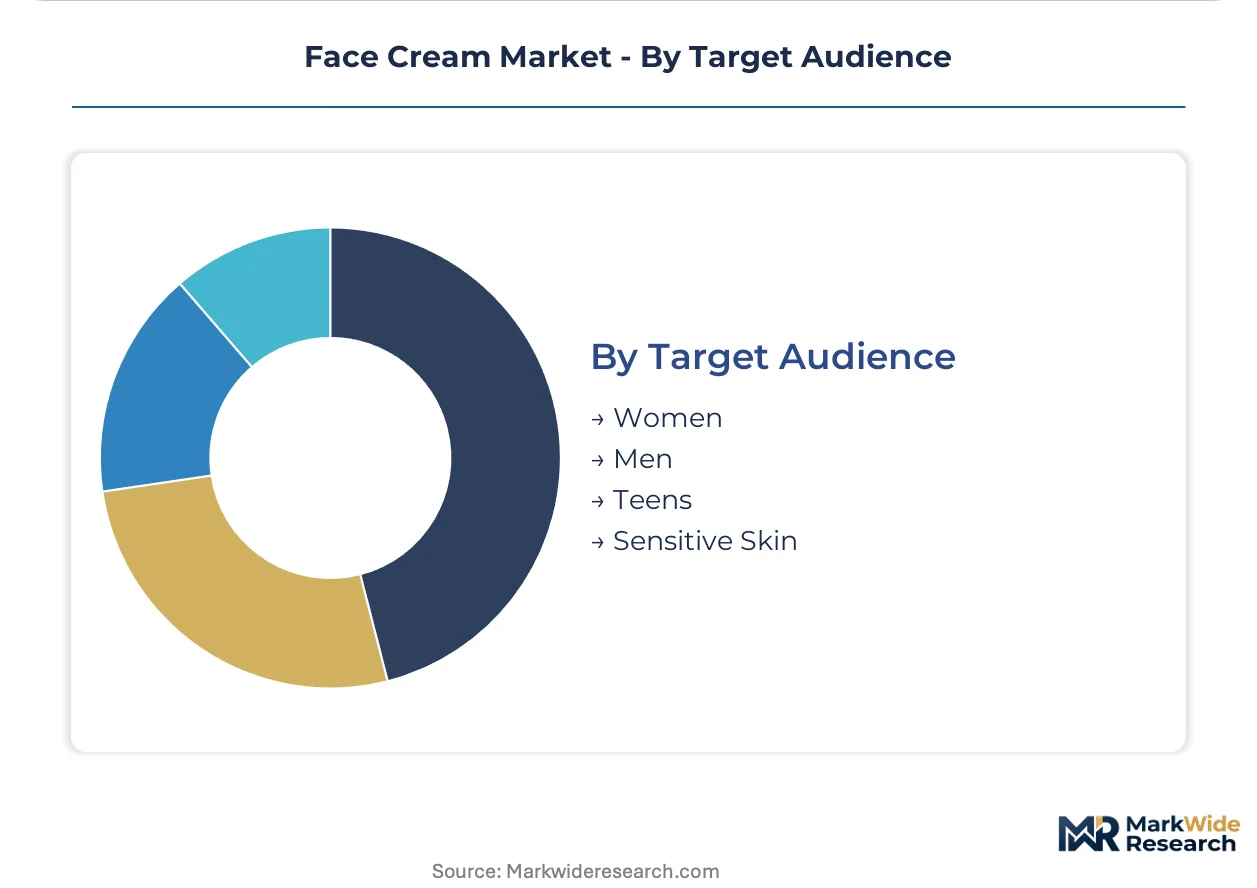
Target Audience:
Customer type determines marketing spend allocation, with male-skincare acquisition costs running higher but lifetime value expanding as routine complexity increases.
- Women:Multi-step regimen adherence supports serum-cream layering and premium pricing. United States and Japanese department store counters concentrate mature demographic spending.
- Men:Simplified two-step routines with combined moisturizer-SPF formats. South Korean grooming culture and United States direct-to-consumer subscription models drive expansion.
- Teens:Acne-safe, non-comedogenic formulations with social media-native branding. TikTok-commerce integration in United Kingdom and United States shapes purchase journeys.
- Sensitive Skin:Fragrance-free, minimal-ingredient lists with dermatological validation. French pharmacy and German drugstore channels anchor this segment.
By volume, Women leads. By routine expansion potential, Men shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation R&D clusters concentrate in France, the United States, Japan, and South Korea, with each geography cultivating distinct competitive advantages through regulatory specialization and channel infrastructure. Clinical validation capabilities and dermatologist network density determine market access trajectories across these territories.
United States
Direct-to-consumer subscription models and telemedicine-integrated replenishment programs drive channel innovation. FDA cosmetic safety labeling requirements mandate rigorous documentation for active ingredient claims. New York City and Los Angeles anchor dermocosmetic brand headquarters, with med-spa retail networks expanding clinical-grade distribution.
France
Heritage pharmacy channels and luxury department store counters sustain premium positioning for sensitive-skin formulations. REACH and EU Cosmetics Regulation compliance enables export price premiums to transparency-conscious markets. Paris and Lyon concentrate fermentation-derived active research facilities serving microbiome-targeted product lines.
Japan
Multi-step regimen adherence supports serum-cream layering architectures with sophisticated texture engineering. METI and PMDA oversight governs quasi-drug classifications for whitening and anti-aging claims. Tokyo and Osaka anchor heritage brand flagships, with Kansai region suppliers specializing in hyaluronic acid purification.
South Korea
Male grooming culture and duty-free channel dominance create distinct demand segmentation for specialized facial moisturizers. MFDS regulates functional cosmetics with accelerated approval pathways for innovative delivery systems. Seoul Capital Area concentrates K-beauty brand headquarters, with Busan-Ulsan clusters handling fermentation capacity expansion.
Germany
Dermatologist dispensing networks and drugstore pharmacy channels anchor sensitive-skin and pediatric segment distribution. ECHA REACH enforcement drives preservative system reformulation cycles with compliance cost barriers for entrants. Hamburg and Berlin host R&D centers for Asian export-dependent brands establishing EU regulatory capabilities.
Face Cream Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the face cream sector. Prestige heritage houses anchor clinical validation infrastructure and dermatologist network relationships. Mass-market conglomerates leverage scale economies in raw material procurement and manufacturing. Biotechnology specialists occupy emerging niches in fermentation-derived actives and microbiome-targeted formulations. Competitive dynamics center on M&A activity consolidating dermatologist-dispensed channels and strategic partnerships securing alternative preservative system supply.
Among heritage luxury houses, Estée Lauder Companies and L'Oréal exemplify the clinical-validation archetype through sustained R&D infrastructure investment. Beiersdorf occupies a position within the science-driven sensitive-skin specialization tier. These three anchors demonstrate how regulatory compliance capabilities and dermatologist endorsement networks create defensive positioning against digital-native entrants.
| Leading Market Players |
|---|
| Estée Lauder Companies |
| Johnson & Johnson |
| L'Oréal |
| Shiseido |
| Coty |
| Procter & Gamble |
| Beiersdorf |
| Amorepacific |
| Unilever |
| Others |
Value Network & Pricing Analysis
Encapsulation technology adoption for retinol stabilization is displacing conventional emulsion systems, simultaneously shifting manufacturing gravity toward South Korean and United States fermentation clusters while compressing margins for brands lacking active-compatibility expertise. This substitution dynamic concentrates pricing power with biotechnology-integrated formulators and fragments procurement leverage among legacy commodity emulsion suppliers.
Pricing Analysis
EU REACH compliance dictates the pricing tier structure across the face cream sector, separating dermatologist-validated premium formulations from mass-market alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with clinical substantiation requirements and brand heritage commanding the widest spreads. Cost compression in the natural extracts tier is intensifying because climate-driven supply disruptions in West Africa and Chile constrain reliable shea butter and rosehip oil procurement. Pharmacy-channel buyers in Germany and France exhibit the highest price sensitivity, while United States med-spa and South Korean duty-free segments absorb premium markups with minimal elasticity.
Supply Chain Analysis
Strategic stockpiling of hyaluronic acid raw material dominates inventory strategy among European formulators responding to Chinese purification facility lead time volatility. Manufacturing concentrates in China for pharmaceutical-grade hyaluronic acid purification, France for fermentation-derived active research, and South Korea for encapsulation technology integration. Supply chain vulnerability rests on single-source dependency for retinol encapsulation polymers from Japanese specialty chemical suppliers. Distribution runs through dermatologist dispensing networks in Germany, direct-to-consumer platforms in the United States, and pharmacy channels across France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemistry expertise is concentrating among senior professionals nearing retirement, creating a capability bottleneck that threatens R&D continuity across mid-tier manufacturers. This scarcity dynamic elevates the strategic value of captive technical talent and biotechnology partnerships.
For Market Incumbents: Fortify dermatologist endorsement networks through telemedicine-integrated replenishment programs before digital-native competitors capture United States and South Korean subscription loyalty. Acquire fermentation capacity in the Seoul Capital Area to secure microbiome-active supply chains against biotech specialist encroachment. Deepen backward integration into encapsulation polymer production to reduce Japanese supplier dependency.
For New Entrants and Emerging Players: Telemedicine-integrated skincare consultation gaps in India's tier-two cities offer white-space penetration before L'Oréal and Estée Lauder establish pharmacy-channel density. Target male grooming routine expansion in United States direct-to-consumer channels with simplified moisturizer-SPF hybrid formats. Leverage social media-native branding on TikTok-commerce platforms to capture teen segment trial conversion in the United Kingdom.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed dermatology clinic networks possessing captive dispensing relationships and patient loyalty data. Long-term viability hinges on biotechnology convergence capabilities across the extended horizon. Monitor fermentation capacity expansion announcements from Seoul and Busan-Ulsan clusters as inflection indicators for microbiome-targeted formulation leadership.
| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Partnership | Fermentation-derived active access bypasses agricultural supply chain volatility in Madagascar and Chile. |
| Direct-to-Consumer Launch | Owned e-commerce platforms capture repeat purchase loyalty from United States department store erosion. |
| EU REACH Compliance Investment | Regulatory adherence enables export price premiums to transparency-conscious Asian markets. |
| Dermatologist Network Expansion | Clinical validation infrastructure filters out undercapitalized competitors in German dispensing channels. |
| Encapsulation Technology Licensing | Retinol stability extension opens mass retail distribution previously restricted to clinical channels. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with formulation chemists, dermatology clinic procurement managers, retail category buyers, and biotechnology R&D directors; and secondary validation against EU REACH substance restriction databases, FDA cosmetic labeling guidance, NMPA registration filings, and customs trade records for hyaluronic acid and retinol derivative flows. Bottom-up segmentation modeling triangulated against top-down market sizing from raw material consumption patterns.
Across the analysis window, forecasts applied multi-dimensional segmentation by product type, ingredient technology, packaging format, target demographic, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for substitution elasticities between natural and biotechnology-derived actives, with specific inputs from encapsulation technology adoption curves and dermatologist dispensing channel expansion rates.
Underlying assumptions cover sustained REACH enforcement stringency and stable male grooming routine adoption in South Korea and the United States, with deviation risk concentrated in climate-driven botanical ingredient supply disruptions and formulation chemist retirement waves. Revision becomes warranted when biotechnology fermentation capacity expansion crosses thresholds that materially alter active ingredient cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Natural Baby Skin Care Products Market
Cosmetics & Skincare
Baby Skincare Market
Cosmetics & Skincare
Herbal Soap Market
Cosmetics & Skincare
Botanical Skin Care Ingredients Market
Cosmetics & Skincare
Private Label Cosmetics Manufacturing Service Market
Cosmetics & Skincare
Temporary Tattoo Market
Cosmetics & Skincare
UK Lip Care Products Market
Cosmetics & Skincare
Eye Shadow Market
Cosmetics & Skincare
Tinted Cosmetics Market
Cosmetics & Skincare
Lip Oil Market
Cosmetics & Skincare
K-Beauty Products Market
Cosmetics & Skincare
Moisturizing Spray Market
Cosmetics & Skincare
Mushroom Cosmetics Market
Cosmetics & Skincare
BB Cream Market
Cosmetics & Skincare
Qatar Cosmetic Products Market
Cosmetics & Skincare
Bangladesh Face Wash Market