
 Setting Spray Market | 2026-2036
Setting Spray Market Size, Share, and Industry Trends Forecast 2026-2036
Setting Spray Market Analytics
Specialty store distribution is reshaping how setting spray brands reach consumers, with curated beauty retail creating immersive testing environments that online channels cannot replicate. L'Oréal leverages its global manufacturing footprint to sustain shelf presence across prestige and mass-tier doors. The Estée Lauder Companies anchors its portfolio strength through professional artist endorsements and backstage visibility at fashion weeks.
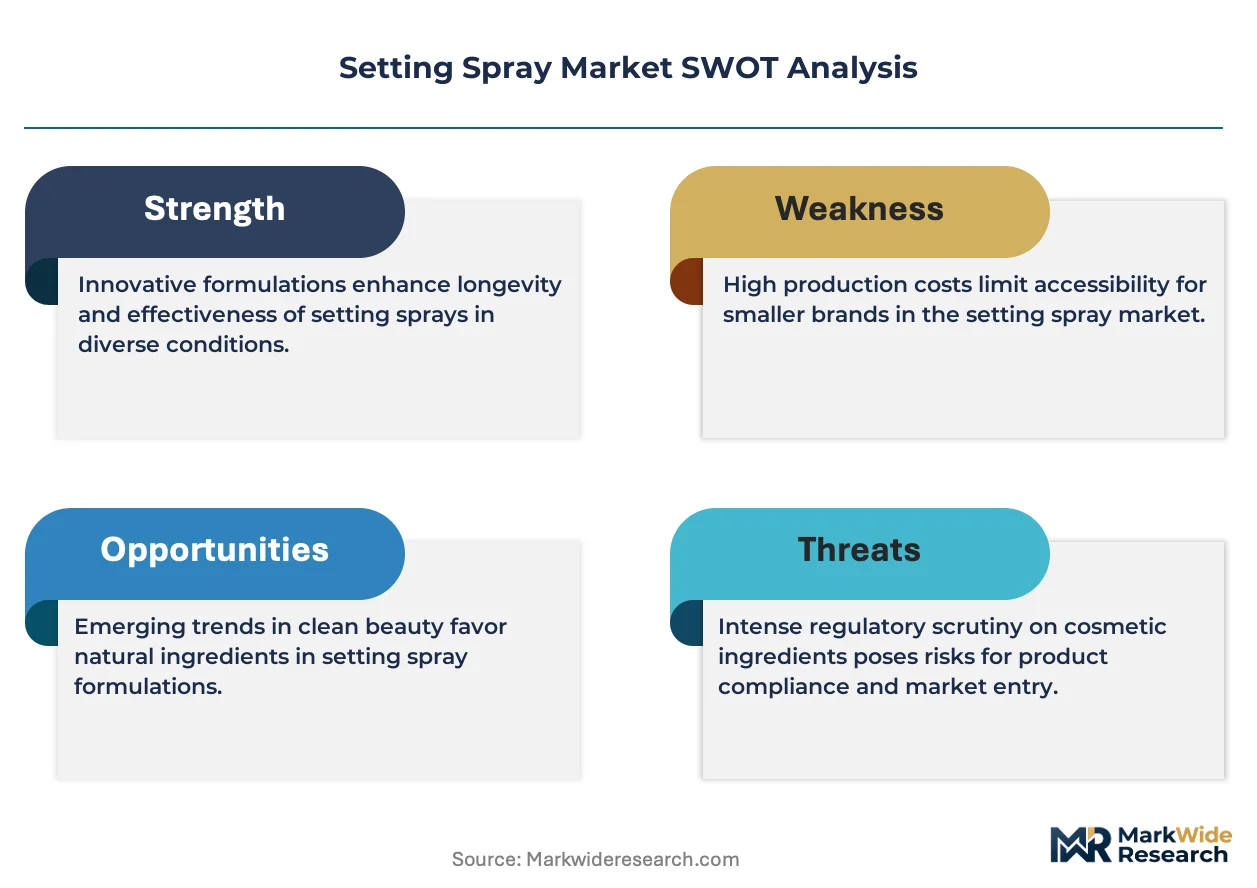
Setting spray constitutes a cosmetic fixative formulation, typically comprising film-forming polymers suspended in aqueous or alcoholic bases with humectants and preservatives, designed to extend makeup wear time by creating a breathable barrier against environmental stressors. Matte finish variants dominate volume due to universal compatibility with diverse skin types and climate conditions, while alcohol-free formulations represent the fastest-expanding segment as consumers with sensitive skin prioritize barrier-friendly ingredients. Water-based sprays command premium positioning in professional channels where artists require fast-drying, non-irritating options for client application.
FDA oversight of cosmetic labeling under the Modernization of Cosmetics Regulation Act and EU REACH chemical restrictions collectively elevate compliance costs for cross-border formulation standardization. BIS certification requirements in India add another layer of testing burden for imported setting spray products seeking access to that market. Stakeholders must monitor evolving preservative bans and clean beauty certification schemes as these frameworks increasingly determine which formulations gain retail placement in priority markets.
Market Dynamics
EU REACH's tightening preservative concentration limits are forcing simultaneous reformulation across alcohol-based and water-based product lines, compressing development cycles while elevating compliance expenditure for cross-border portfolios.
Growth Catalysts
- Film-forming polymer innovation:Next-generation breathable polymers developed for professional makeup artists in film and television production enable extended wear claims without occlusive skin feel, expanding addressable use cases.
- United States prestige retail expansion:Social commerce integration through platforms like TikTok Shop and Instagram Checkout is converting discovery into immediate purchase, shortening the path from awareness to trial.
- Alcohol-free formulation demand:Sensitive-skin consumers are migrating toward barrier-friendly humectant bases, creating volume expansion in dermatologist-recommended channels.
Market Restraints
- Preservative input cost volatility:REACH-mandated phenoxyethanol restrictions and pending MIT/CMIT bans in Europe are forcing costly preservative system overhauls with limited qualified alternatives.
- Supply concentration in Asian polymer feedstocks:Film-forming agent production clusters in China and South Korea create geographic vulnerability to export licensing delays and shipping cost spikes.
- Technical limitation in alcohol-free drying speed:Water-based formulations require 40-60% longer dry-down times versus ethanol bases, limiting professional artist adoption for time-pressured backstage environments.
Strategic Opportunities
- Underpenetrated India market:BIS certification requirements have filtered import competition, creating first-mover advantage for domestic manufacturing investments or joint ventures with local contract manufacturers.
- Clean beauty certification convergence:EWG Verified and Sephora Clean standards are merging procurement criteria, enabling single-formulation qualification for multiple retail banners.
- Climate-adaptive positioning:Humidity-resistant and pollution-barrier claims address Southeast Asian urban consumers in Bangkok, Jakarta, and Manila where environmental stressors accelerate makeup degradation.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise spanning polymer science, skin microbiome compatibility, and regulatory compliance is concentrated among senior professionals approaching retirement.
- Dual certification timeline compression:Simultaneous FDA MoCRA compliance and EU REACH dossier preparation for preservative alternatives is stretching quality assurance bandwidth.
- Legacy spray valve integration:Fine-mist actuator technology from aerosol suppliers requires recalibration for water-based viscosity profiles, creating manufacturing yield inconsistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Setting Spray Market |
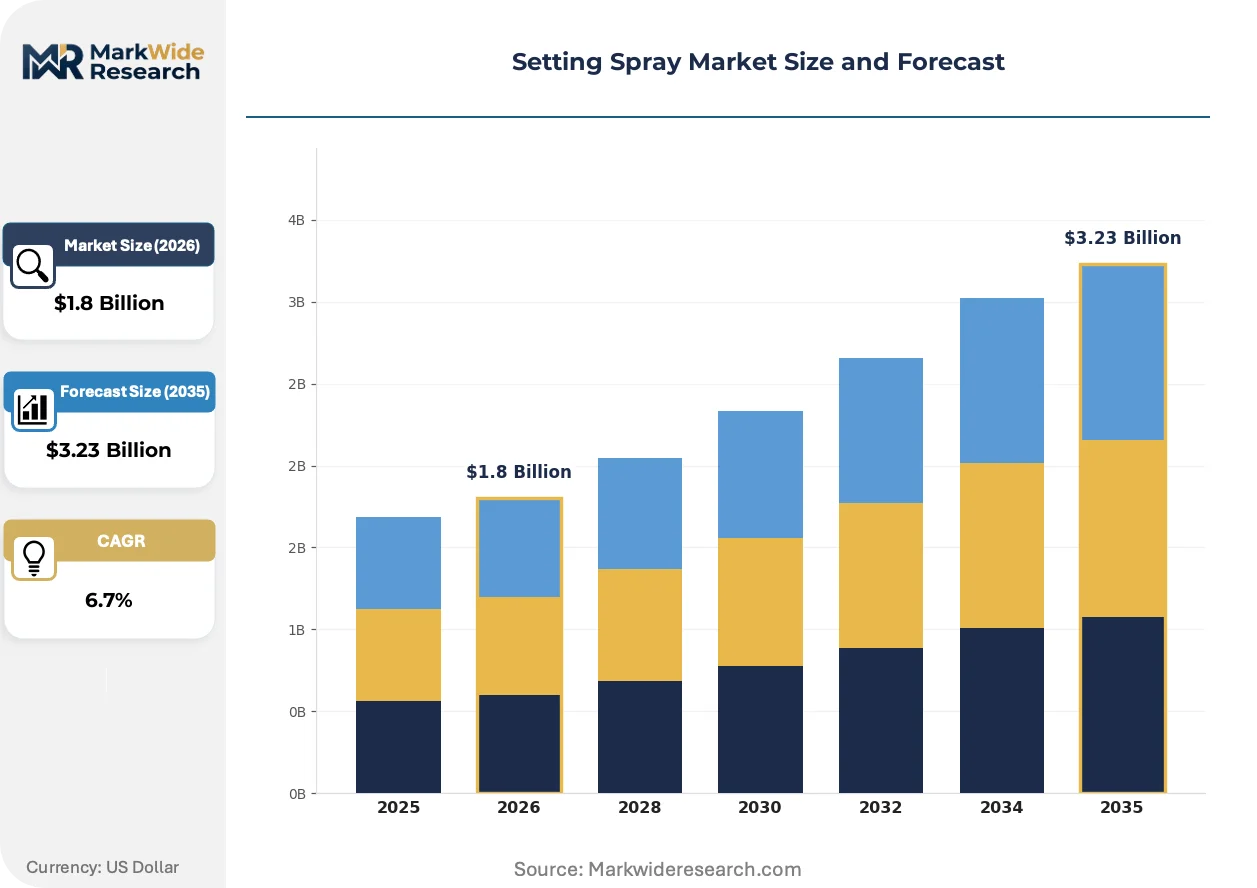
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Matte Finish, Dewy Finish, Long-Lasting, Hydrating Distribution Channel: Online Retail, Specialty Stores, Department Stores, Drugstores End User: Professional Artists, Everyday Users, Influencers, Makeup Enthusiasts Formulation Type: Alcohol-Free, Water-Based, Oil-Based, Silicone-Based |
| Companies Covered | Urban Decay, Sugar Cosmetics, The Estée Lauder Companies, Swiss Beauty, Lakme Cosmetics, L'Oréal, Rare Beauty, Faces Canada, e.l.f. Cosmetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Setting Spray Market Evolving Landscape
Hybrid formulation architectures are dissolving the traditional boundary between skincare and makeup fixatives, with multifunctional products now delivering barrier support alongside wear extension.
Biopolymer film-forming technology derived from fermented corn sugars is hybridizing conventional petrochemical-derived fixative performance with biodegradability credentials. Professional makeup artists in film production are piloting these materials for talent with silicone sensitivity. The structural consequence is compression of the clean-premium price gap as biopolymer production scales.
EU REACH Annex V amendments restricting isothiazolinone preservatives are forcing preservative system diversification toward organic acids and caprylyl glycol blends. Industrial consequence includes extended stability testing protocols and reformulation costs equivalent to 12-18 month development cycles. Water-based professional sprays targeting backstage fashion week applications are most affected, with suppliers accelerating phenethyl alcohol adoption.
Social commerce discovery-to-purchase loops are collapsing traditional retail trial behavior, with consumers in the United States and United Kingdom purchasing full-size setting sprays based solely on algorithmic video content. Prestige beauty retailers are responding with virtual try-on integration and augmented reality filter partnerships. This shift is most visible among Gen Z demographics in urban coastal markets where in-store counter traffic has declined 30-40% versus pre-pandemic baselines.
Setting Spray Market Segmentation
Segmentation in the setting spray market reveals how formulation chemistry, purchase context, and user expertise create distinct competitive arenas. Each dimension carries divergent margin profiles and regulatory exposure, demanding portfolio architecture that spans multiple category positions simultaneously.
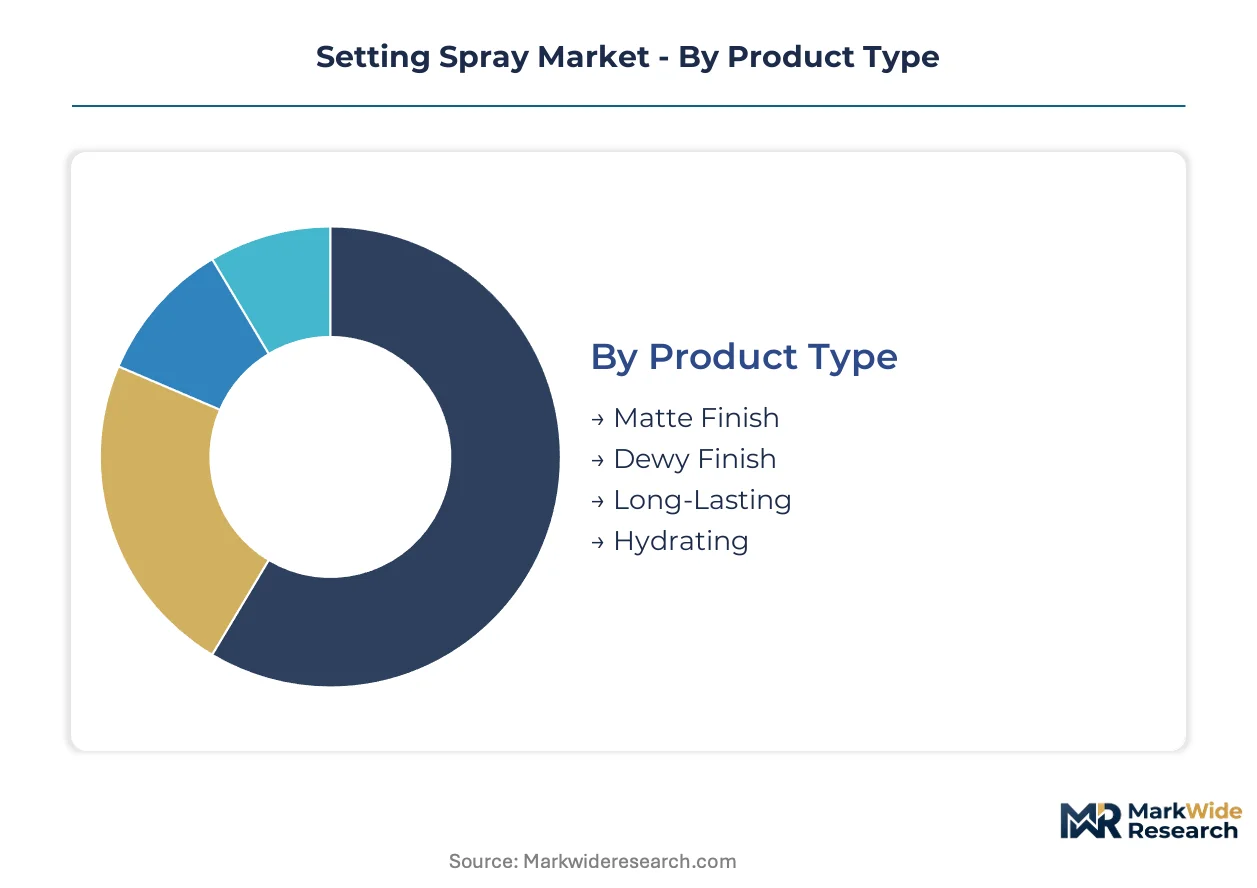
Product Type:
Use-case spectrum spans from universal daily wear to specialized performance environments, with finish chemistry determining climate compatibility and skin-type addressability.
- Matte Finish:Silica-based oil-absorbing polymers create a flat, non-reflective surface that controls sebum breakthrough in humid conditions. Demand concentrates most intensely in the United States among consumers in subtropical coastal states where humidity accelerates makeup degradation.
- Long-Lasting:Cross-linked film-forming agents deliver 12-16 hour wear claims through flexible polymer networks that resist mechanical transfer. Professional makeup artists in film and television production anchor volume here, driven by production schedules that prohibit touch-up intervals.
- Dewy Finish:Glycerin and squalane humectant bases impart luminous skin-like radiance preferred by editorial photographers and social content creators.
- Hydrating:Hyaluronic acid and ceramide-infused formulations target barrier-compromised skin segments in dermatologist-recommended channels.
Established volume favors matte finish; emerging adoption favors hydrating.
Distribution Channel:
Cost tier stratification separates experiential high-touch retail from algorithmic discovery platforms, with margin structure inversely correlating to customer acquisition efficiency.
- Specialty Stores:Curated beauty retail with immersive testing environments and trained consultant staff commands premium price realization. Sephora and Ulta Beauty in the United States concentrate prestige volume through exclusive shade and size configurations unavailable elsewhere.
- Online Retail:TikTok Shop and Instagram Checkout integration collapses discovery-to-purchase latency, converting algorithmic video content into immediate transactions without physical trial.
- Department Stores:Counter-based service models retain relevance for gift purchasing and loyalty program redemption among older demographics.
- Drugstores:Mass-tier placement through CVS and Walgreens captures convenience-driven replenishment with compressed margin but scaled volume.
Volume concentrates in specialty stores; steepest expansion trajectory belongs to online retail.
End User:
Application expertise creates segmentation by technique sophistication and purchase authority, from institutional procurement to individual trial behavior.
- Professional Artists:Film, television, and fashion week makeup artists specify performance-grade formulations with batch consistency and rapid dry-down requirements. This segment anchors premium pricing and influences consumer aspiration through backstage visibility.
- Everyday Users:Mass-market consumers prioritizing routine integration and value-per-use metrics drive volume scale across drugstore and online channels.
- Influencers:Content creators with platform-scale audiences function as hybrid end-users and distribution nodes, with product seeding replacing traditional advertising for awareness generation.
- Makeup Enthusiasts:Hobbyist collectors with high category engagement and low brand loyalty drive SKU proliferation and limited-edition velocity.
Professional artists anchor margin structure; influencer-mediated discovery is gaining share fastest.
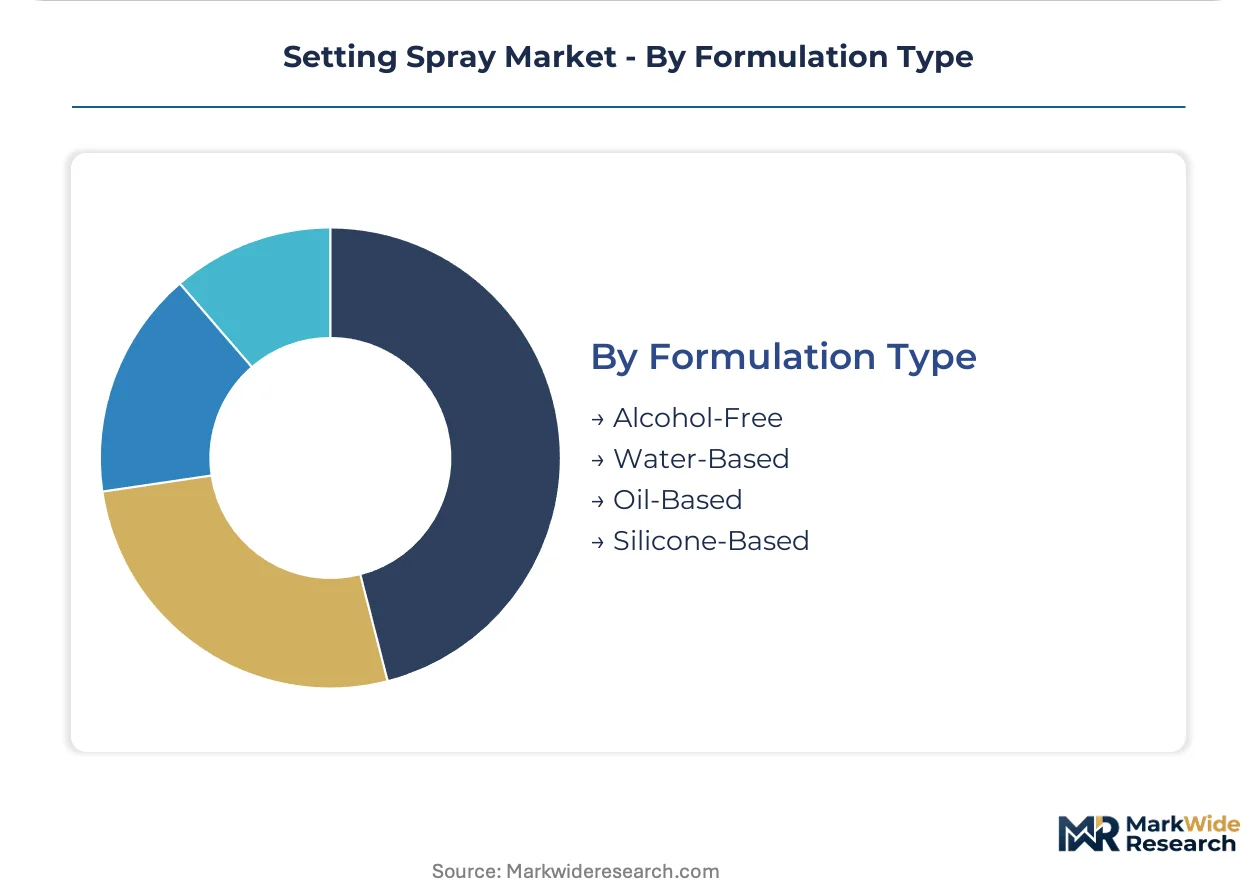
Formulation Type:
Base chemistry determines regulatory classification, skin compatibility profile, and manufacturing equipment requirements, with water-based systems commanding technical premium.
- Water-Based:Aqueous polymer dispersions with fast-evaporating humectant carriers deliver non-irritating application suitable for sensitive skin and professional client work. EU REACH preservative restrictions are compressing development cycles for this segment as phenoxyethanol alternatives undergo extended safety testing.
- Alcohol-Free:Propylene glycol and caprylyl glycol preservative bases address barrier-friendly positioning for dermatologist-recommended and clean beauty certified lines.
- Silicone-Based:Cyclopentasiloxane and dimethicone carriers create occlusive films with superior transfer resistance for stage and screen applications.
- Oil-Based:Squalane and jojoba ester formulations target mature skin segments with diminished natural sebum production.
Water-based formulations dominate professional channels; alcohol-free is expanding most quickly in sensitive-skin positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH Annex V amendments are tightening preservative concentration limits across cosmetic formulations, forcing simultaneous reformulation in multiple jurisdictions and elevating compliance expenditure for multinational portfolios. The United States anchors volume through prestige retail expansion and social commerce integration, while India's BIS certification requirements filter import competition. Film and television production clusters in specific metropolitan areas are driving professional-grade demand.
United States
Prestige beauty retail expansion through Sephora and Ulta Beauty doors, combined with TikTok Shop and Instagram Checkout integration, converts algorithmic discovery into immediate purchase. FDA oversight under the Modernization of Cosmetics Regulation Act elevates labeling compliance costs for cross-border formulation standardization. Los Angeles and New York City concentrate film and television production makeup artist demand for extended-wear professional formulations.
Germany
EU REACH chemical restrictions and ECHA-mandated preservative bans are compressing development cycles for alcohol-based and water-based product lines simultaneously. The country's national cosmetic regulator enforces strict dossier preparation requirements for preservative alternatives. Frankfurt and Munich host professional makeup artist training institutions that influence formulation specifications for European fashion week applications.
India
BIS certification requirements for imported cosmetics have filtered competition, creating first-mover advantage for domestic manufacturing investments. The country's national standards body mandates extended testing protocols that add 6-12 months to market entry timelines. Maharashtra and Karnataka concentrate contract manufacturing capacity for setting spray production serving both domestic consumption and regional export.
South Korea
Film-forming polymer feedstock production clusters create geographic concentration in advanced fixative ingredient supply. The Ministry of Food and Drug Safety regulates cosmetic functional claims with specific documentation requirements for extended-wear positioning. Seoul anchors K-beauty innovation pipelines that increasingly influence global formulation trends in barrier-friendly and climate-adaptive positioning.
United Kingdom
Social commerce discovery-to-purchase loops are collapsing traditional retail trial behavior among Gen Z demographics in urban coastal markets. The Office for Product Safety and Standards enforces post-Brexit cosmetic regulation divergence from EU REACH frameworks. London concentrates influencer-mediated marketing activity and backstage fashion week visibility that drives professional artist endorsement value.
Setting Spray Market Competitive Landscape
On the supply side, the industry is structured around three distinct tiers: multinational beauty conglomerates with global manufacturing footprints, mid-scale regional specialists with curated distribution, and digital-native challengers leveraging direct-to-consumer velocity. Strategic archetypes include the portfolio-diversified conglomerate, the professional-channel anchor, and the algorithmic-growth native. Dominant competitive moves center on preservative system reformulation for regulatory compliance and social commerce platform integration for discovery-to-purchase conversion.
Within the multinational conglomerate tier, L'Oréal and The Estée Lauder Companies exemplify supply-side scale advantages that sustain shelf presence across prestige and mass-tier doors simultaneously. Among digital-native specialists, Rare Beauty occupies a position defined by platform-native discovery mechanics and influencer-mediated community building. e.l.f. Cosmetics represents the mass-tier efficiency archetype, anchoring value-positioned volume through drugstore and online retail integration.
| Leading Market Players |
|---|
| Urban Decay |
| Sugar Cosmetics |
| The Estée Lauder Companies |
| Swiss Beauty |
| Lakme Cosmetics |
| L'Oréal |
| Rare Beauty |
| Faces Canada |
| e.l.f. Cosmetics |
| Others |
Value Network & Pricing Analysis
Guangdong Province's film-forming polymer production clusters determine downstream pricing leverage for setting spray manufacturers, with capacity utilization rates in Shenzhen and Dongguan directly translating to input cost volatility for brands sourcing cross-linked fixative agents. This geographic concentration creates asymmetric bargaining power where polymer feedstock availability shapes finished goods margin structures more than brand equity or retail positioning.
Pricing Analysis
Certification level creates the primary spread between premium and mass-tier positioning, with EU REACH-compliant and Sephora Clean-certified formulations commanding substantial markups over conventional alternatives. Three-tier pricing structure across prestige, professional, and mass-market levels segments buyers by application expertise rather than volume scale alone. Cost compression in the mass tier is intensifying because drugstore chains are consolidating shelf-space negotiations, while professional artists demonstrate lowest price sensitivity due to production-budget procurement authority.
Supply Chain Analysis
Export licensing controls on advanced polymer synthesis equipment limit technology transfer to emerging manufacturing hubs, constraining capacity expansion outside established production centers. Film-forming agent supply concentrates in China, South Korea, and Germany, with humectant carriers and preservative systems drawing from distinct regional specialties. Single-source vulnerability runs through South Korean dimethicone copolyol production, where two suppliers dominate global cosmetic-grade output. Distribution runs through regional contract manufacturers serving prestige beauty houses, with finished goods logistics anchored in free-trade zones near major consumption markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Setting spray demand acceleration reflects regulatory disruption rather than incremental trend adoption, as EU REACH preservative bans and FDA MoCRA labeling requirements simultaneously force formulation overhaul and create first-mover advantage for compliant portfolios.
For Market Incumbents: Pre-empt margin erosion in mass-tier channels by securing captive supply of phenoxyethanol alternatives through backward integration into organic acid preservative production, while accelerating professional-channel certification investments to defend pricing power against clean beauty challengers. The simultaneous compliance burden across multiple jurisdictions compresses development bandwidth, making in-house regulatory expertise a sustainable differentiator. For New Entrants and Emerging Players: Establish a beachhead in India's BIS-certified domestic manufacturing segment, where import filtering creates protected market access for local production investments. Climate-adaptive positioning for Southeast Asian humidity resistance offers the most penetrable white-space, with direct-to-consumer launch through TikTok Shop collapsing traditional retail gatekeeper barriers for algorithmic-native brands. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because compliance capability scarcity concentrates value capture among firms with proven dossier preparation velocity across FDA, ECHA, and BIS frameworks. Acquisition targets should display dual REACH-MoCRA qualification progress and professional artist endorsement networks. The signal to watch is preservative alternative approval timelines at ECHA, which would reset competitive positioning for entire formulation portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Preservative System Reformulation | ECHA-mandated phenoxyethanol restrictions force 12-18 month development cycles for water-based professional sprays. |
| Domestic Manufacturing Investment | BIS certification requirements in India filter import competition and create protected market access for local production. |
| Social Commerce Platform Integration | TikTok Shop and Instagram Checkout collapse discovery-to-purchase latency for Gen Z demographics in coastal US markets. |
| Climate-Adaptive Formulation Development | Humidity-resistant claims address Southeast Asian urban consumers in Bangkok, Jakarta, and Manila. |
| Professional Artist Endorsement Networks | Backstage visibility at fashion weeks and film production sets anchors premium pricing and consumer aspiration. |
Research Methodology
Operator-level perspectives from cosmetic chemists, regulatory affairs specialists at multinational beauty houses, professional makeup artists in film production, and procurement managers at contract manufacturers anchored the qualitative base. These primary inputs combined with secondary validation from ECHA preservative restriction dossiers, FDA MoCRA guidance documents, BIS cosmetic certification protocols, and customs trade data for film-forming polymer feedstocks. Bottom-up formulation cost modeling and top-down retail audit triangulation cross-verified volume and value estimates.
Scenario-bracketing around regulatory approval timelines and social commerce adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include finish chemistry, distribution channel, end-user expertise tier, and formulation base type. CAGRs derived from polynomial trend fitting to historical prestige beauty growth patterns, adjusted for professional-channel expansion rates and clean beauty certification penetration. Climate-adaptive positioning demand and biopolymer feedstock scaling curves served as industry-specific forecast inputs.
Sensitivities concentrate around ECHA preservative ban implementation schedules and TikTok Shop algorithmic policy changes affecting beauty category discoverability. Forecasts reflect documented assumptions on regulatory compliance timelines and platform commerce growth trajectories. Material shifts in REACH Annex V amendment scope or social commerce platform terms of service would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Mascara Applicators Market
Cosmetics & Skincare
Bath Soap Market
Cosmetics & Skincare
Lip Scrub Market
Cosmetics & Skincare
Beauty Sheet Mask Market
Cosmetics & Skincare
North America Bath Soap Market
Cosmetics & Skincare
Face Compact Market
Cosmetics & Skincare
Sports Sun Care Market
Cosmetics & Skincare
Foundation Cream Market
Cosmetics & Skincare
Body Cream Jars Market
Cosmetics & Skincare
Massaging Cosmetic Applicators Market
Cosmetics & Skincare
Natural and Organic Lipstick Market
Cosmetics & Skincare
Eye Makeup Market
Cosmetics & Skincare
Sun Care Products Market
Cosmetics & Skincare
Botanical Skin Care Ingredients Market
Cosmetics & Skincare
China Skincare Market
Cosmetics & Skincare
Mushroom Beauty Products Market