
 Microbiome Cosmetic Products Market | 2026-2036
Microbiome Cosmetic Products Market Size, Share, and Industry Trends Forecast 2026-2036
Microbiome Cosmetic Products Market Foresight
South Korea is rewriting how microbiome cosmetics reach consumers through skin-science clinics and K-beauty export platforms. L'Oréal Paris leverages its dermatological research network to anchor live-culture stabilization protocols across multiple continents. Estée Lauder competes through prestige channel control, while GALLINÉE specializes in pH-optimized prebiotic formulations for sensitive skin profiles. Glowbiotics extends its position via physician-dispensed distribution, a channel that commands premium pricing and repeat purchase loyalty.
Microbiome cosmetic products are topical formulations containing live microorganisms, lysates, or fermented metabolites designed to modulate skin flora composition and barrier function, typically requiring cold-chain or stabilized preservation to maintain bioactivity. These products serve the commercial purpose of translating dermatological microbiome research into consumer-accessible skincare that addresses inflammation, dysbiosis, and moisture retention. Facial creams and serums currently occupy the largest margin pools due to higher unit economics and clinical positioning, while cleansers represent the fastest-growing entry point as consumers seek microbiome-safe daily rituals without stripping natural lipids. The acne treatment application segment leads R&D investment, though skin repair shows accelerating professional endorsement.
Regulators in the United States require FDA oversight for claims crossing into drug territory, while the EU's ECHA and Cosmetics Regulation enforce strict preservative and live-culture safety thresholds that shape formulation feasibility. REACH compliance and emerging CSRD sustainability disclosure rules in Europe are forcing suppliers to document ingredient provenance and biodegradability across extended supply chains. Stakeholders must monitor how classification ambiguity around postbiotics versus cosmetics versus therapeutics will determine market access costs and competitive moats in key jurisdictions.
Market Dynamics
Cold-chain logistics for live-culture preservation is compressing shelf-life economics and forcing formulators toward lyophilized stabilization or synthetic postbiotic alternatives, fundamentally restructuring production cost curves across the category.
Growth Catalysts
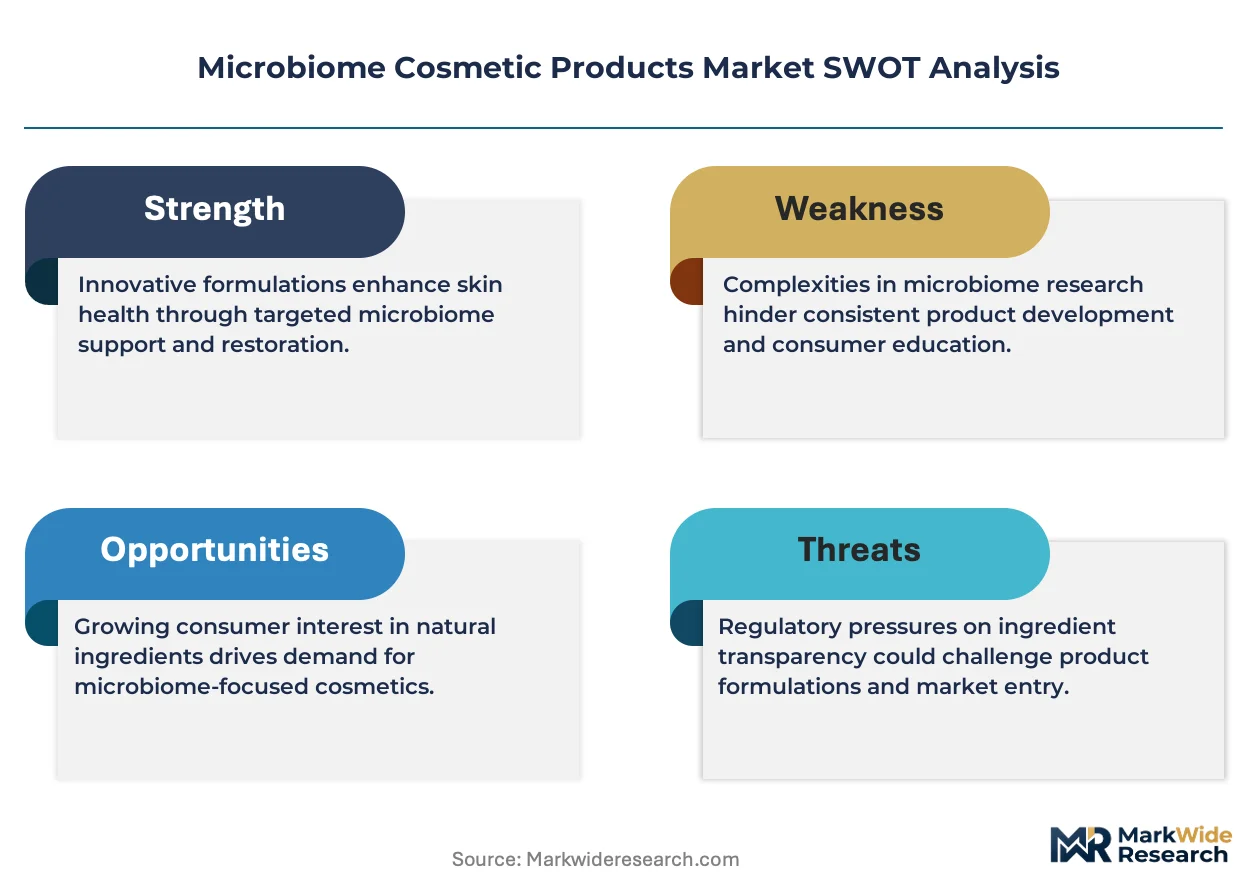
- REACH compliance mandates:The European Union's chemical safety framework under ECHA is accelerating substitution toward clinically validated postbiotic derivatives that meet biodegradability thresholds.
- Dermatology clinic dispensing:Physician-controlled channels in the United States are creating pull-through for premium live-culture serums with documented barrier-repair outcomes.
- Fermentation process advances:Continuous bioreactor technologies are reducing batch-to-batch variability in lysate production, improving manufacturing yields for mid-scale suppliers.
Market Restraints
- Live-culture supply concentration:Probiotic strain banking and master cell line maintenance cluster with a handful of European biotechnology suppliers, creating single-source vulnerability.
- FDA classification friction:The United States regulator's drug-cosmetic boundary enforcement forces costly claim restraint or clinical trial investment for inflammation-modulating formulations.
- Preservative incompatibility:Traditional cosmetic preservation systems inactivate target organisms, requiring expensive reformulation or alternative packaging formats.
Strategic Opportunities
- South Korea skin-science clinics:The K-beauty export platform is creating demand for microbiome-backed ampoules and essences with clinical validation from Seoul-based dermatology research institutes.
- CSRD disclosure rules:The EU's Corporate Sustainability Reporting Directive is rewarding suppliers with documented ingredient provenance across extended supply chains, favoring vertically integrated formulators.
- Scalp microbiome extension:Hair care applications remain underdeveloped relative to facial skincare, offering first-mover positioning for brands with existing live-culture stabilization expertise.
Industry Challenges
- Microbiome assay standardization:Lack of consensus protocols for skin flora characterization complicates clinical substantiation and cross-study comparability.
- Cold-chain infrastructure capex:Distribution networks for temperature-sensitive live cultures require refrigerated warehousing and specialized last-mile logistics that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbiome Cosmetic Products Market |
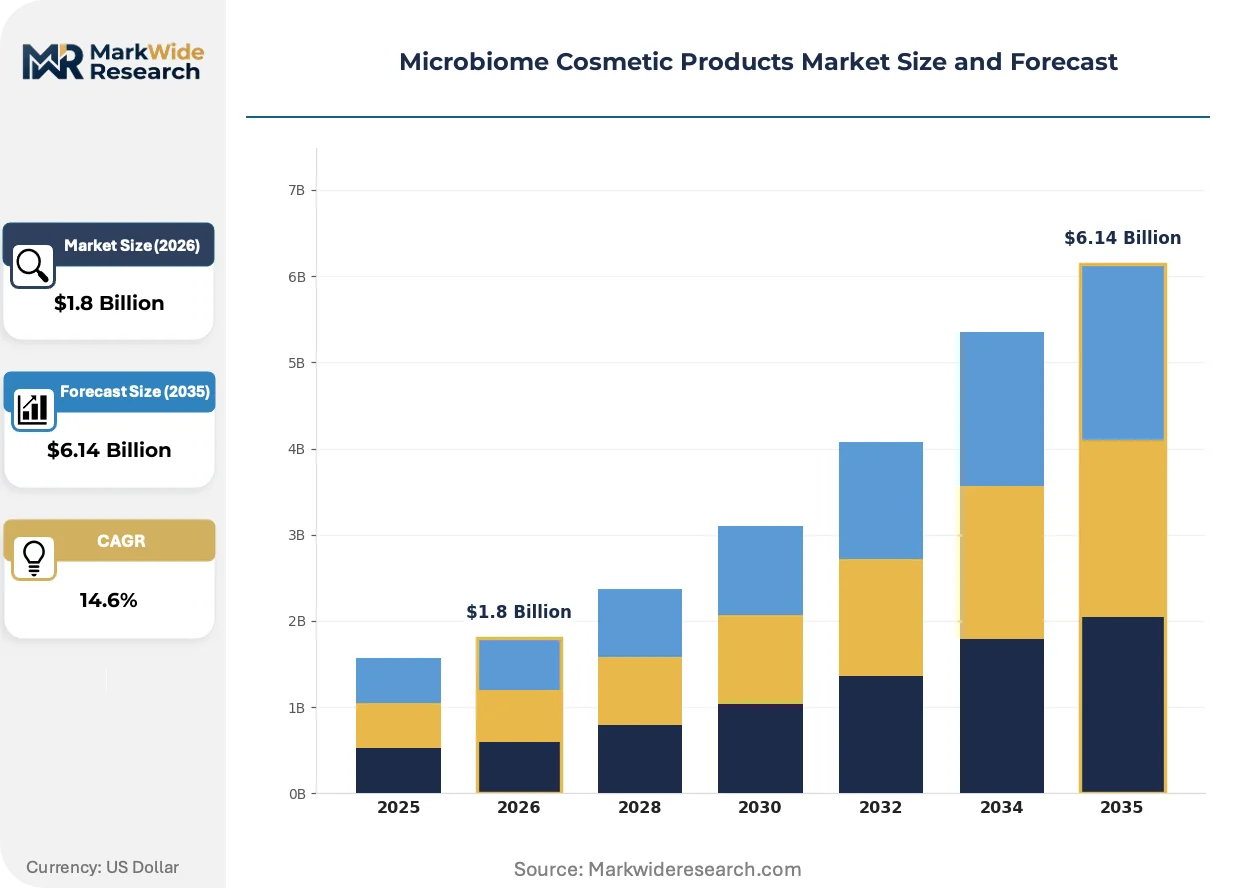
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Creams, Serums, Body Lotions, Cleansers Application: Anti-Aging, Moisturizing, Skin Repair, Acne Treatment End User: Women, Men, Teens, Professionals Distribution Channel: Online Stores, Specialty Retailers, Department Stores, Pharmacies |
| Companies Covered | Johnson & Johnson, Murad, L'Oréal Paris, GALLINÉE, Glowbiotics, La Roche-Posay, Estée Lauder, Phiome, Aveeno, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbiome Cosmetic Products Market Shifts & Advancements
Formulation science is converging with dermatological research protocols, blurring the boundary between cosmetic maintenance and therapeutic intervention. This convergence is reshaping competitive positioning around clinical credibility rather than conventional marketing claims.
Lyophilized live-culture technology is hybridizing freeze-dried probiotic matrices with anhydrous oil bases to circumvent cold-chain requirements. Prestige skincare brands in France and the United States are adopting these formats for travel retail and subscription channels. The technology is hybridizing supply chain economics by collapsing distribution complexity while preserving bioactivity claims.
REACH authorization procedures under ECHA are tightening preservative restrictions and forcing disclosure of fermentation-derived metabolite structures. Formulators must now document biodegradability and aquatic toxicity for postbiotic ingredients previously treated as cosmetic actives. Small and mid-sized suppliers in Germany and the Netherlands are consolidating to share regulatory compliance costs.
Consumer verification behavior is shifting toward third-party certification scanning before purchase, with apps cross-referencing ingredient lists against EWG Skin Deep and similar databases. Direct-to-consumer brands in California and New York are responding with blockchain-traceable supply chain documentation. This pattern concentrates in the United States, where regulatory ambiguity has created information asymmetry that educated buyers seek to close.
Microbiome Cosmetic Products Market Segmentation
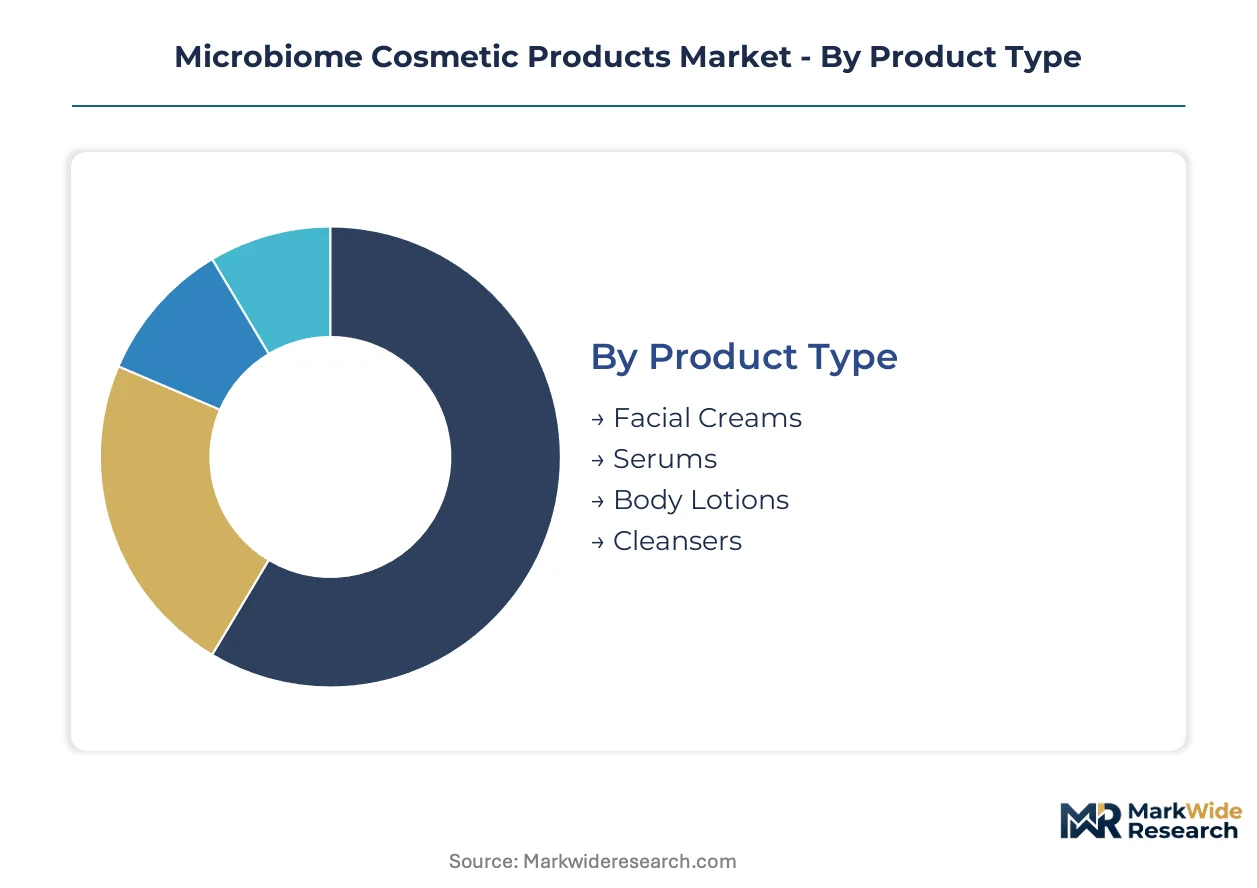
Segmentation in microbiome cosmetics reveals how formulation complexity, clinical positioning, and channel economics create distinct margin architectures across product tiers. Understanding these divides exposes where cold-chain costs, regulatory scrutiny, and consumer education burdens concentrate.
Product Type:
After-sales service intensity varies sharply across formats, with live-culture serums demanding refrigeration support and pH-monitoring guidance that facial creams rarely require.
- Facial Creams:Oil-in-water emulsions incorporating lysates or postbiotic filtrates dominate current shelf space. Demand clusters in United States dermatology clinics and French pharmacy channels where barrier-repair claims command premium positioning.
- Serums:Anhydrous or low-water formulations preserve live-culture viability without continuous refrigeration. Seoul-based skin-science clinics and California direct-to-consumer platforms drive adoption of ampoule formats with documented strain specificity.
- Body Lotions:Lower actives concentration and simpler preservation requirements reduce unit economics but expand addressable volume.
- Cleansers:Surfactant-compatible microbiome-safe formulations avoid lipid-stripping while maintaining foaming performance; fastest-climbing entry point for daily ritual conversion.
Facial creams hold the largest share; momentum sits with cleansers.
Application:
Cost tier stratification separates clinical-grade inflammation modulation from mass-market maintenance claims, with reimbursement-adjacent positioning determining R&D allocation.
- Anti-Aging:Collagen-support claims via microbiome-mediated barrier function attract prestige pricing in Japanese and German markets. Tokyo dermatology institutes and Munich aesthetic clinics validate peptide-postbiotic combinations for photoaging reversal.
- Skin Repair:Post-procedure and compromised-barrier indications require EMA-notified body or FDA-acknowledged clinical substantiation. Demand concentrates in Swissmedic-regulated Swiss clinics and Health Canada-monitored Canadian professional channels.
- Moisturizing:Basic hydration claims with microbiome-friendly positioning compete in saturated mass markets with thinner margins.
- Acne Treatment:Cutibacterium acnes modulation research drives biotech partnerships; regulatory boundary with drug classification limits claim latitude in United States and European Union.
Anti-aging captures the deepest margin pool; skin repair shows steepest expansion trajectory.
End User:
Volume concentration follows demographic penetration curves, with professional segments exhibiting highest lifetime value and lowest price elasticity.
- Women:Core addressable base across all price tiers, with perimenopausal skin-barrier concerns driving lysate serum adoption in United Kingdom and Australian markets.
- Professionals:High-frequency travelers and clinical trial participants seeking TSA-compatible lyophilized formats; concentrated in Singapore and Dubai urban corridors.
- Men:Emerging segment with simplified ritual preferences favoring multi-functional postbiotic moisturizers.
- Teens:Acne-prone cohort with price sensitivity and social media-influenced ingredient scrutiny; TikTok-driven verification behavior strongest in United States.
Women retain dominant volume; professionals deliver highest per-capita spend.
Distribution Channel:
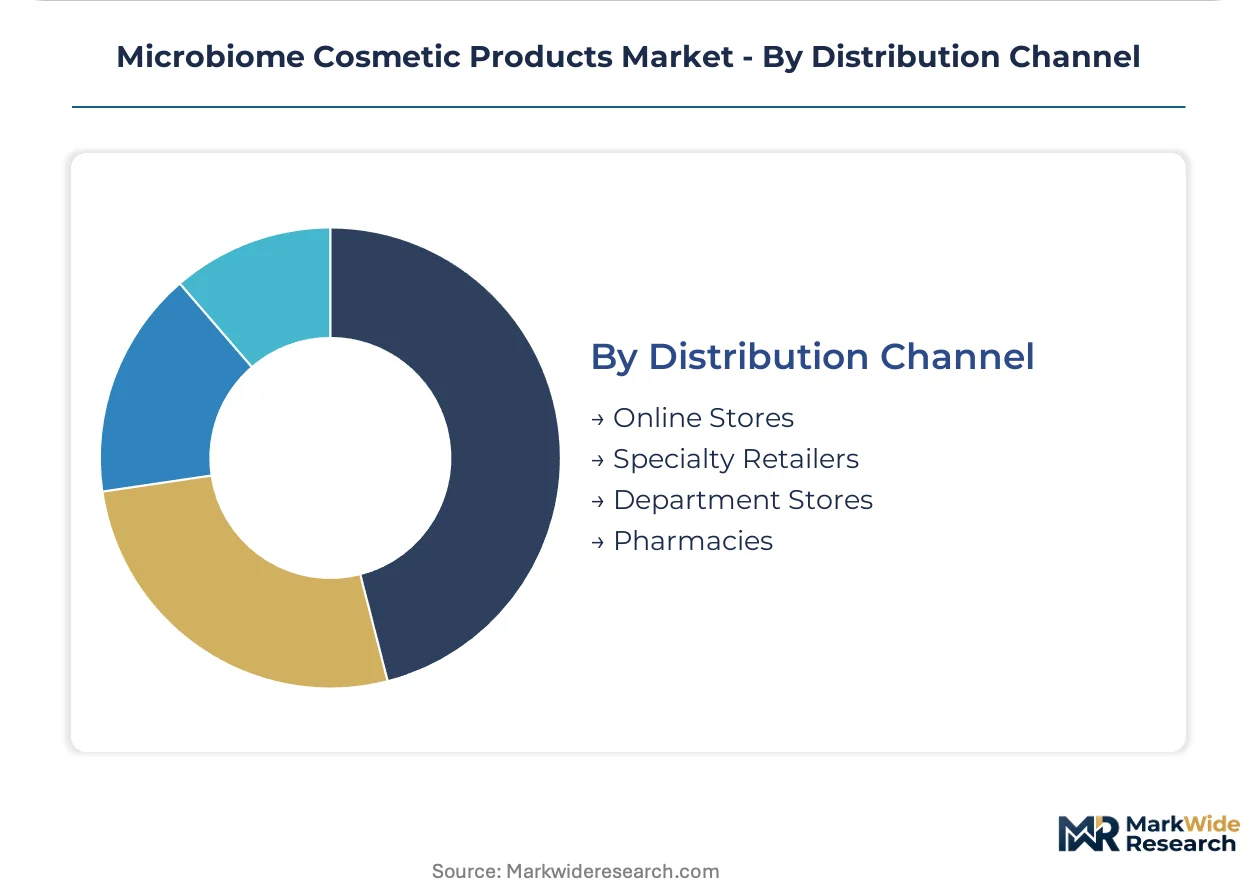
Supply concentration in cold-chain-capable logistics favors channels with refrigerated warehousing investment, disadvantaging traditional department store footprints.
- Specialty Retailers:Sephora and Douglas-operated networks with trained staff capable of explaining live-culture handling. German and French store networks lead staff certification programs for microbiome product consultation.
- Online Stores:Direct-to-consumer cold-chain shipping from centralized bioreactor-proximate fulfillment centers. California and New York headquarters dominate subscription model innovation with temperature-tracked last-mile delivery.
- Pharmacies:EU-regulated para-pharmacy positioning with pharmacist-mediated recommendation; requires REACH-compliant documentation at point of sale.
- Department Stores:Legacy prestige positioning without refrigeration infrastructure; losing share to channels with clinical credibility.
Specialty retailers anchor current volume; online stores gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA classification friction in the United States shapes how microbiome cosmetic claims cross into therapeutic territory, while ECHA's REACH framework in Europe enforces biodegradability thresholds that reshape formulation economics across both continents.
United States
Dermatology-backed direct-to-consumer channels command premium shelf space in specialty retail and professional clinics. FDA oversight forces costly claim restraint or clinical trial investment for inflammation-modulating formulations. California and New York headquarters dominate subscription model innovation with temperature-tracked last-mile delivery for live-culture serums.
South Korea
Skin-science clinics and K-beauty export platforms rewrite how microbiome cosmetics reach consumers through clinical validation from Seoul-based dermatology research institutes. MFDS regulates cosmetic safety while allowing faster market entry for microbiome-backed ampoules. Seoul Capital Area anchors demand for strain-specific essences with documented barrier-repair outcomes.
Germany
REACH-compliant documentation requirements at point of sale concentrate demand in para-pharmacy channels with pharmacist-mediated recommendation. ECHA authorization procedures tighten preservative restrictions and force disclosure of fermentation-derived metabolite structures. Small and mid-sized suppliers in Bavaria and North Rhine-Westphalia consolidate to share regulatory compliance costs.
France
Prestige skincare brands adopt lyophilized live-culture technology for travel retail and subscription channels to circumvent cold-chain requirements. ANSM oversees cosmetic vigilance while French pharmacy networks lead staff certification programs for microbiome product consultation. Paris-based dermatological research anchors live-culture stabilization protocols across multiple continents.
Japan
Collagen-support claims via microbiome-mediated barrier function attract prestige pricing in Tokyo dermatology institutes validating peptide-postbiotic combinations for photoaging reversal. PMDA and METI regulate cosmetic-drug boundaries while encouraging fermentation process advances. Kansai and Chubu industrial clusters supply continuous bioreactor technologies reducing batch-to-batch variability in lysate production.
Microbiome Cosmetic Products Market Competitive Landscape
Prestige conglomerates and microbiome-specialist independents split the market into distinct competitive spheres with divergent channel strategies and clinical credibility architectures. Consolidation pressures concentrate around cold-chain logistics capabilities and REACH-compliant supply chain documentation. Three archetypes dominate: multinational beauty conglomerates with dermatological research networks, dedicated microbiome formulators with pH-optimized prebiotic expertise, and physician-dispensed brands leveraging professional channel control. Dominant competitive moves include M&A to acquire live-culture stabilization capabilities and strategic partnerships with Seoul-based skin-science clinics for clinical validation.
Within the prestige conglomerate tier, L'Oréal Paris and Estée Lauder exemplify scale-driven positioning anchored by dermatological research infrastructure and prestige channel control across multiple continents. Among microbiome-specialist independents, GALLINÉE represents the pH-optimized formulation archetype for sensitive skin profiles, while Glowbiotics occupies a position within physician-dispensed distribution commanding premium pricing and repeat purchase loyalty. These three companies illustrate how competitive differentiation converges on clinical credibility rather than conventional marketing claims.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Murad |
| L'Oréal Paris |
| GALLINÉE |
| Glowbiotics |
| La Roche-Posay |
| Estée Lauder |
| Phiome |
| Aveeno |
| Others |
Supply & Pricing Matrix
European biotechnology suppliers controlling probiotic strain banking and master cell line maintenance capture disproportionate margin pools downstream, with live-culture stabilization protocols commanding premium positioning in United States dermatology clinics and French pharmacy channels.
Pricing Analysis
United States physician-dispensed serums trade at substantial premiums over European para-pharmacy equivalents due to FDA claim-restraint costs and cold-chain infrastructure requirements. Three-tier pricing structure across premium live-culture formats, mid-tier lysate derivatives, and mass-market postbiotic moisturizers separates clinical-grade from maintenance claims. Price differentiation hinges on certification tier and after-sales refrigeration support intensity. Pricing pressure stems from lyophilized format substitution collapsing cold-chain economics, with teen and mass-market segments exhibiting highest price sensitivity while professional channels remain inelastic.
Supply Chain Analysis
Probiotic feedstock production concentrates in Germany, the Netherlands, and France where ECHA-registered fermentation facilities cluster. Raw material dependencies span pharmaceutical-grade growth media, specialized bioreactor components, and cold-chain packaging materials. Single-source vulnerability in European strain banking creates acute exposure to REACH authorization delays. Distribution runs through refrigerated warehousing networks into specialty retail, direct-to-consumer subscription, and clinic dispensing channels with temperature-tracked last-mile protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward dermatology clinic networks and direct-to-consumer platforms as channel consolidation concentrates volume among fewer procurement decision-makers.
For Market Incumbents: Entrench live-culture stabilization capabilities through backward integration into European strain banking assets or exclusive master cell line partnerships. Secure refrigerated warehousing capacity in California and New York metro corridors before logistics providers impose capacity constraints. Threat substitution from synthetic postbiotic alternatives demands preemptive clinical validation investment to preserve premium positioning. For New Entrants and Emerging Players: Scalp microbiome applications in North American and Western European markets offer underpenetrated white space with lower competitive density than facial skincare. Men's simplified-ritual positioning and teen acne-prone segments present accessible entry points with thinner incumbent control. Go-to-market execution should prioritize TikTok-native ingredient transparency storytelling paired with blockchain-traceable supply chain documentation. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale suppliers with REACH-compliant fermentation infrastructure and documented biodegradability credentials across extended supply chains. Long-term viability favors vertically integrated formulators capturing margin compression from cold-chain logistics standardization. Watch for MFDS fast-track approvals in South Korea as inflection signals for clinical validation arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilized Format Development | Eliminates cold-chain dependency while preserving bioactivity claims for travel retail expansion. |
| Seoul Skin-Science Clinic Partnership | Secures MFDS-validated clinical substantiation for K-beauty export platform positioning. |
| REACH-Compliant Supply Chain Documentation | Meets CSRD disclosure rules and ECHA authorization thresholds for EU market access. |
| Physician-Dispensed Channel Expansion | Captures premium pricing and repeat purchase loyalty in FDA-regulated professional settings. |
| Scalp Microbiome Line Extension | Exploits first-mover positioning in hair care applications with existing stabilization expertise. |
Research Methodology
Operator-level perspectives from brand managers, category buyers at specialty retailers, cold-chain logistics coordinators, and dermatology clinic procurement directors anchored the qualitative base. Secondary validation drew from FDA cosmetic registration databases, ECHA REACH authorization filings, MFDS safety assessment records, and customs documentation of fermentation equipment imports. Bottom-up unit economics modeling triangulated against top-down category spend estimates from retail audit data.
Scenario-bracketing around regulatory classification ambiguity and cold-chain infrastructure buildout shaped the analytical framework across the projection horizon. Segmentation dimensions spanned product format, application indication, end-user demographic, and distribution channel with regional regulatory cluster overlays. CAGRs derived from fitted growth curves calibrated to historical adoption patterns in adjacent dermatological cosmetic categories, with specific inputs from bioreactor capacity expansion timelines and REACH authorization processing rates.
Practitioners should monitor ECHA preservative restriction amendments, FDA drug-cosmetic boundary enforcement actions, and lyophilized technology cost curves for early signals requiring forecast revision. Cross-checking against Nielsen retail audit data and clinical trial registration trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Japan Organic Cosmetics Market
Cosmetics & Skincare
Body Cream Jars Market
Cosmetics & Skincare
Cosmetic Mirror Market
Cosmetics & Skincare
Magnetic Fake Eyelashes Market
Cosmetics & Skincare
Global Cosmetic Antioxidant Market
Cosmetics & Skincare
Epigenetic Cosmetic Products Market
Cosmetics & Skincare
Qatar Cosmetic Products Market
Cosmetics & Skincare
Sweden Cosmetics Products Market
Cosmetics & Skincare
K-Beauty Products Market
Cosmetics & Skincare
Mushroom Cosmetics Market
Cosmetics & Skincare
Beauty Sheet Mask Market
Cosmetics & Skincare
Face Wash Market
Cosmetics & Skincare
Mushroom Beauty Products Market
Cosmetics & Skincare
Period Balm Market
Cosmetics & Skincare
Europe Bath Soap Market
Cosmetics & Skincare
Lipstick Market