
 Sun Care Market | 2026-2036
Sun Care Market Size, Share, and Industry Trends Forecast 2026-2036
Sun Care Market Outlook
Mineral filter technology is narrowing the performance gap with chemical UV absorbers, compelling brands to reformulate around zinc oxide and titanium dioxide platforms. L'Oréal S.A. leverages its dermatological research infrastructure to accelerate photostable mineral innovation. Beiersdorf AG anchors its portfolio in European pharmacy channels where regulatory scrutiny of organic filters intensifies. Shiseido Company Ltd. competes through hybrid systems that blend mineral cores with limited chemical boosters for texture optimization.
Sun care encompasses topical photoprotective formulations engineered with UV-absorbing or scattering agents, typically rated by Sun Protection Factor (SPF) to quantify erythemal dose reduction, alongside post-exposure soothing and color-enhancing ancillary products. Manufacturing centers on emulsion stability, photostability testing under ISO 24443 protocols, and broad-spectrum validation against UVA-I degradation. Sunscreens dominate value capture due to daily-use frequency and premium pricing at very high SPF levels, while spray formulations represent the fastest-expanding delivery format driven by convenience demand in outdoor and pediatric segments. After-sun products occupy a mature margin pool with limited innovation differentiation.
The U.S. FDA governs monograph compliance for over-the-counter sunscreens, restricting approved active ingredients and delaying novel filter market entry through prolonged time-and-extent application reviews. The EU's REACH framework and Cosmetics Regulation (EC) No 1223/2009 classify certain chemical UV filters as environmental hazards, accelerating reformulation timelines for brands serving European consumers. Australia's TGA maintains stringent UVA testing standards that exceed many jurisdictions, creating a quality benchmark exporters must meet. Stakeholders must monitor pending FDA monograph modernization and emerging state-level restrictions on reef-toxic actives to anticipate portfolio exposure and geographic prioritization.
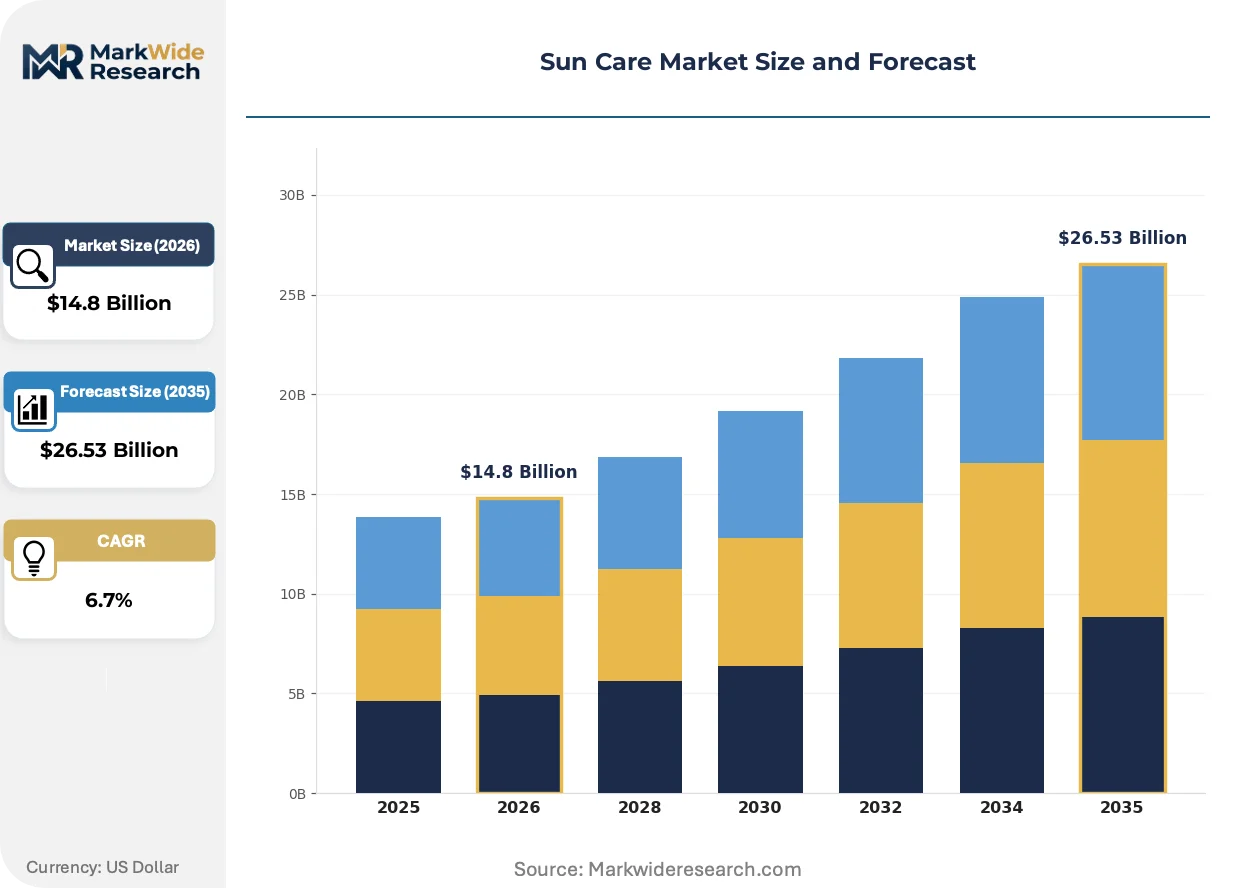
Market Dynamics
The European Union's REACH ban on octinoxate and oxybenzone is forcing a wholesale migration from chemical UV filters to mineral-based platforms, compressing formulation timelines and elevating R&D intensity across the value chain.
Growth Catalysts
- Outdoor recreation expansion:Year-round participation in hiking, cycling, and water sports sustains daily sunscreen application frequency among active consumers in Australia and Brazil.
- REACH environmental classifications:The EU's designation of certain organic filters as aquatic hazards accelerates mineral innovation pipelines and creates first-mover advantages for compliant brands.
- Pediatric spray adoption:Convenience-driven parents increasingly favor aerosol and pump formats for child application, expanding the fastest-growing delivery segment.
Market Restraints
- Zinc oxide supply concentration:Pharmaceutical-grade mineral feedstock production clusters in China, exposing formulators to geopolitical friction and input cost volatility.
- FDA monograph rigidity:The US regulator's time-and-extent application process blocks novel UV filter market entry, delaying photostable innovation for American consumers.
- Texture-performance tradeoff:Mineral platforms inherently whiten and thicken compared to chemical absorbers, limiting aesthetic acceptance in premium daily-wear segments.
Strategic Opportunities
- After-sun functionalization:Post-exposure products incorporating barrier-repair ceramides and antioxidant complexes command margin premiums in pharmacy channels.
- Hybrid system patents:Converging mineral cores with limited chemical boosters enables texture optimization while maintaining regulatory compliance in restrictive jurisdictions.
- Very high SPF positioning:SPF 50+ and 100+ ratings capture disproportionate value despite marginal incremental UVB protection, particularly in Brazil's beauty-conscious consumer base.
Industry Challenges
- Photostability validation capacity:ISO 24443 testing infrastructure remains scarce, creating bottlenecks for broad-spectrum certification and market launch timelines.
- Emulsion stability expertise:Formulating stable oil-in-water systems with high mineral loads demands specialized colloid chemistry talent that commands premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sun Care Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sunscreens, After-Sun Products, Tanning Lotions, Self-Tanners Formulation: Lotion, Cream, Gel, Spray SPF Level: Low SPF, Medium SPF, High SPF, Very High SPF Distribution Channel: Online, Supermarkets, Drugstores, Beauty Stores |
| Companies Covered | L'Oréal S.A., Johnson & Johnson, Beiersdorf AG, Unilever PLC, Procter & Gamble, Shiseido Company Ltd., Kao Corporation, Edgewell Personal Care, Estée Lauder Companies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sun Care Market Strategic Shifts
Formulation science is advancing on three parallel fronts: mineral particle engineering, regulatory arbitrage strategies, and channel-specific product architecture. These developments collectively determine competitive positioning.
Encapsulated zinc oxide with sub-100 nanometer primary particle size is rendering obsolete the whitening effect that historically limited mineral sunscreen aesthetic acceptance. Premium daily-wear brands in Japan and South Korea are accelerating adoption of these transparent mineral platforms. The technology is compressing the performance gap with chemical absorbers and enabling mineral dominance in facial skincare-integrated sun protection.
REACH Annex XVII restrictions on reef-toxic actives are fragmenting global formulation strategies between compliant and non-compliant product variants. Brands serving European consumers must maintain entirely separate SKU portfolios from those distributed in less restrictive markets. The regulatory divergence elevates complexity costs and favors multinationals with dedicated regional R&D infrastructure.
Direct-to-consumer subscription models are capturing recurring revenue from daily sunscreen users who prioritize convenience over retail browsing. Specialty beauty retailers and pharmacy chains are responding with loyalty programs and auto-replenishment features. Brazil and Australia exhibit the highest subscription penetration due to year-round sun exposure sustaining predictable consumption patterns.
Sun Care Market Segmentation
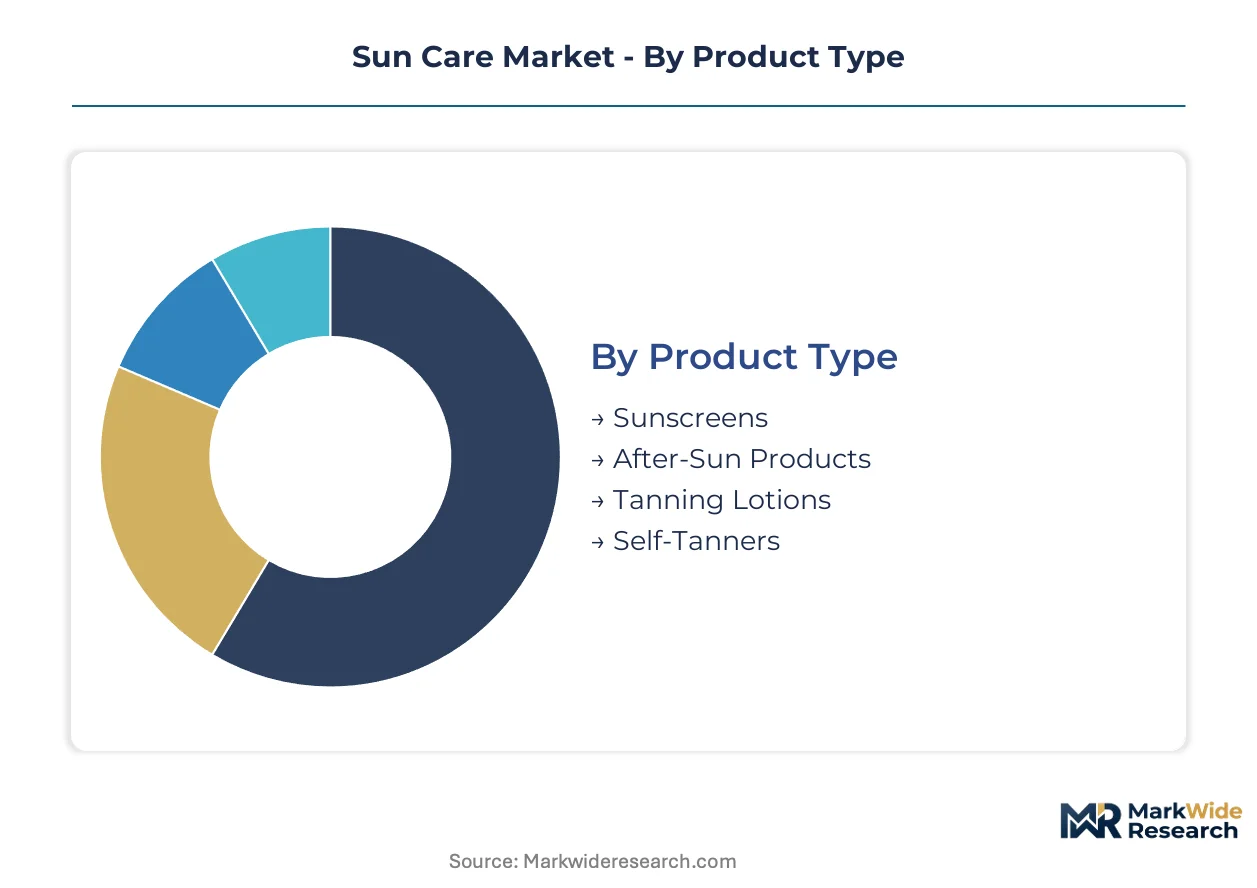
Sun care manufacturers configure product portfolios across four intersecting dimensions that determine pricing power, channel access, and regulatory compliance requirements. Each segmentation axis carries distinct margin profiles and formulation constraints that shape competitive positioning.
Product Type:
After-sales service intensity concentrates in sunscreens and after-sun products where dermatological claims and photostability documentation require ongoing technical support.
- Sunscreens:UV-absorbing or scattering formulations rated by SPF for erythemal dose reduction, demanding ISO 24443 photostability validation and broad-spectrum UVA-I certification. Daily-use frequency in Brazil and Australia sustains premium pricing at very high SPF levels despite marginal incremental UVB protection gains.
- After-Sun Products:Post-exposure soothing formulations incorporating barrier-repair ceramides and antioxidant complexes. Pharmacy channels in Europe command margin premiums for functionalized variants with dermatological positioning.
- Tanning Lotions:Color-enhancing ancillary products with limited innovation differentiation occupying mature margin pools.
- Self-Tanners:Dihydroxyacetone-based formulations delivering UV-free color development.
By volume, sunscreens lead. By growth pace, after-sun functionalization is gaining share fastest.
Formulation:
Cost tier stratification separates premium mineral-engineered creams from mass-market sprays where convenience commands price premiums.
- Lotion:Oil-in-water emulsion systems offering balanced spreadability and hydration, historically dominant in daily facial and body applications. Texture-performance tradeoffs with mineral loads constrain high-SPF lotion development.
- Cream:Thicker, occlusive bases with elevated oil content preferred for dry skin conditions and pediatric segments. European pharmacy channels favor cream vehicles for barrier-repair positioning.
- Gel:Water-based, non-greasy vehicles penetrating oily and acne-prone skin segments in humid climates.
- Spray:Aerosol and pump delivery formats representing the fastest-expanding segment driven by convenience demand in outdoor recreation and pediatric application scenarios.
By volume, lotions retain the largest installed base. By expansion trajectory, spray formats are climbing the fastest.
SPF Level:
Customer type segmentation aligns protection claims with behavioral risk profiles and regulatory classification thresholds.
- Low SPF:SPF ratings below 15 targeting incidental exposure and cosmetic-integrated daily wear. Regulatory scrutiny in Australia and TGA standards limit commercial viability.
- Medium SPF:SPF 15-30 range capturing routine urban commuters in temperate European markets where UVA protection claims dominate purchase decisions.
- High SPF:SPF 30-50 positioning balancing photoprotection with aesthetic acceptability in mass-market distribution.
- Very High SPF:SPF 50+ and 100+ ratings capturing disproportionate value in Brazil's beauty-conscious consumer base despite marginal incremental UVB dose reduction beyond SPF 50.
By volume, high SPF products lead. By margin expansion, very high SPF positioning shows the steepest trajectory.
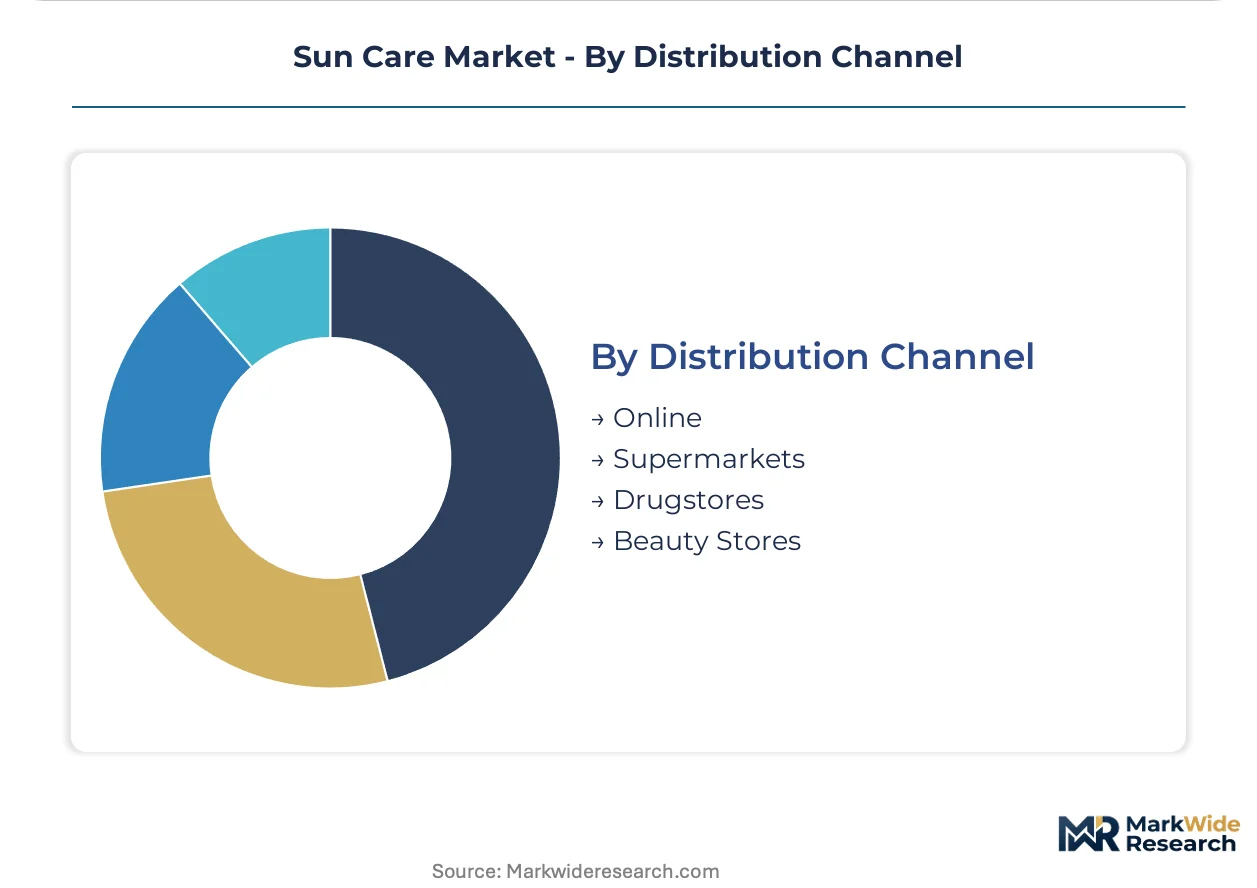
Distribution Channel:
Geography determines channel dominance with direct-to-consumer models penetrating subscription-heavy markets while pharmacy concentration persists in regulatory-stringent jurisdictions.
- Online:Direct-to-consumer and marketplace platforms capturing recurring revenue through subscription models in Brazil and Australia where year-round sun exposure sustains predictable consumption patterns.
- Supermarkets:Mass-market volume channel for standard SPF lotions and sprays with price-competitive positioning.
- Drugstores:Pharmacy-affiliated retail anchoring mineral-based and dermatologically-positioned portfolios in EU markets under REACH environmental compliance pressure.
- Beauty Stores:Premium channel for skincare-integrated facial sunscreens with transparent mineral platforms and hybrid system technologies.
By volume, supermarkets lead. By growth pace, online subscription models are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in sun care formulations reveal divergent regulatory pressures reshaping trade flows. The EU's REACH restrictions on reef-toxic actives are redirecting supply chains toward mineral-based production hubs, while Brazil and Australia sustain import demand for premium SPF platforms through year-round consumption intensity.
United States
Outdoor recreation participation in hiking and water sports sustains daily sunscreen application frequency across coastal states. The FDA's monograph compliance framework restricts approved active ingredients and delays novel UV filter market entry through prolonged time-and-extent application reviews. California's dermatological research clusters in Los Angeles and San Francisco anchor photostable mineral innovation pipelines serving pharmacy and direct-to-consumer channels.
Germany
Pharmacy channel concentration in Berlin and Munich drives demand for dermatologically-positioned mineral platforms. ECHA's REACH Annex XVII classifications of certain organic filters as aquatic hazards accelerate reformulation timelines for brands serving European consumers. The North Rhine-Westphalia chemical manufacturing belt concentrates emulsion stability expertise and ISO 24443 testing infrastructure for broad-spectrum certification.
Brazil
Year-round sun exposure and established beauty culture sustain premium product uptake for very high SPF ratings despite marginal incremental UVB protection. ANVISA maintains alignment with international UVA testing standards while enabling faster novel filter approval than the US FDA. São Paulo's cosmetics formulation clusters anchor production of SPF 50+ and 100+ products capturing disproportionate value in the beauty-conscious consumer base.
Australia
Outdoor lifestyle patterns and skin cancer prevention campaigns maintain per-capita sunscreen consumption among the highest globally. The TGA enforces stringent UVA testing standards that exceed many jurisdictions, creating a quality benchmark exporters must meet. Sydney and Melbourne direct-to-consumer subscription models capture recurring revenue from daily users who prioritize convenience over retail browsing.
Japan
Skincare-integrated facial sun protection drives demand for transparent mineral platforms with sub-100 nanometer particle engineering. METI supports cosmetic innovation through standards harmonization with ASEAN markets, enabling regional export expansion. Tokyo and Osaka R&D clusters accelerate adoption of encapsulated zinc oxide technologies compressing the performance gap with chemical absorbers.
Sun Care Market Competitive Environment
On the supply side, the industry is consolidating around multinationals with dedicated regional R&D infrastructure capable of managing fragmented regulatory compliance. The vendor base stratifies into three tiers: global beauty conglomerates with dermatological research arms, regional pharmacy-channel specialists, and niche mineral-engineering innovators. Dominant competitive moves include strategic partnerships with pharmaceutical-grade mineral feedstock suppliers and technology licensing agreements for encapsulated particle platforms.
Within the global beauty conglomerate tier, L'Oréal S.A. and Beiersdorf AG occupy positions defined by dermatological research infrastructure and European pharmacy channel anchoring respectively. Shiseido Company Ltd. sits within the hybrid innovation archetype, representing convergence strategies between mineral cores and limited chemical boosters. These three exemplify how regulatory arbitrage capabilities and regional formulation expertise determine competitive positioning across REACH-compliant and less restrictive markets.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Johnson & Johnson |
| Beiersdorf AG |
| Unilever PLC |
| Procter & Gamble |
| Shiseido Company Ltd. |
| Kao Corporation |
| Edgewell Personal Care |
| Estée Lauder Companies Inc. |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade zinc oxide production clusters in China expose formulators to geopolitical friction and input cost volatility, concentrating margin capture with brands that have secured long-term mineral feedstock contracts or captive supply arrangements. This upstream concentration forces downstream pricing stratification between mineral-engineered premium tiers and commodity chemical-filter alternatives.
Pricing Analysis
Outdoor recreation enthusiasts anchor a three-tier pricing structure across premium, standard, and economy levels in the sun care market. Price differentiation rests on SPF certification tier and brand dermatological positioning, with very high SPF ratings commanding disproportionate premiums in Brazil despite marginal incremental UVB protection. Pricing pressure stems from REACH-compliant reformulation costs elevating mineral-based product price floors. Mass-market supermarket buyers exhibit highest price sensitivity, while pharmacy-channel consumers demonstrate lowest sensitivity due to clinical efficacy prioritization.
Supply Chain Analysis
Export-control friction around nano-particle manufacturing equipment limits technology transfer for sub-100 nanometer mineral engineering. Geographic supply concentration centers on China for pharmaceutical-grade zinc oxide, Germany for emulsion stability expertise and ISO 24443 testing infrastructure, and Brazil for SPF 50+ formulation clusters. Raw material dependencies include titanium dioxide feedstock, encapsulated particle coatings, and pump-actuator components for spray formats. Single-source vulnerability runs through Chinese mineral refining capacity. Distribution runs through pharmacy chains in REACH-regulated European markets and direct-to-consumer subscription platforms in Australia and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sun care represents a service-attach opportunity where recurring-revenue subscription models and after-sun functionalization with barrier-repair ceramides expand faster than base sunscreen hardware sales. This attach-layer growth justifies portfolio reallocation toward consumable-recurring hybrids.
For Market Incumbents: Build regulatory-arbitrage capabilities as a moat against REACH-compliant SKU fragmentation. Incorporate hybrid mineral-chemical patents to defend texture-optimized positioning against pure-mineral challengers. Deepen backward integration into pharmaceutical-grade zinc oxide supply to offset Chinese feedstock concentration risk. Expand ISO 24443 testing infrastructure ownership to bottleneck competitor certification timelines. For New Entrants and Emerging Players: Establish a beachhead in after-sun functionalization where dermatological claims command pharmacy-channel margin premiums with lower formulation barriers than photostable sunscreen development. Target Brazilian very high SPF positioning where beauty-conscious consumers prioritize protection ratings over texture aesthetics. Pursue direct-to-consumer subscription acquisition with auto-replenishment features capturing predictable consumption from year-round sun exposure markets. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed mineral-engineering specialists possessing encapsulated particle platforms but lacking global distribution reach. Long-term viability favors converged skincare-sun protection players with transparent mineral technology and regional regulatory compliance infrastructure. Watch FDA monograph modernization progress as inflection signal for novel filter approval timelines and competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Mineral Particle Engineering Investment | Sub-100 nanometer zinc oxide platforms compress the aesthetic-performance gap with chemical absorbers in facial skincare integration. |
| REACH-Compliant SKU Portfolio Expansion | Dedicated European product lines capture pharmacy-channel share as ECHA restrictions eliminate reef-toxic chemical filter alternatives. |
| Direct-to-Consumer Subscription Launch | Auto-replenishment models in Brazil and Australia convert predictable year-round consumption into recurring revenue streams. |
| Hybrid System Patent Acquisition | Mineral-core with limited chemical booster formulations enable texture optimization while maintaining regulatory compliance in restrictive jurisdictions. |
| ISO 24443 Testing Infrastructure Buildout | Photostability validation capacity ownership creates certification bottlenecks that delay competitor broad-spectrum product launches. |
Study Parameters
Operator-level perspectives from formulation chemists, pharmacy category buyers, mineral feedstock procurement managers, and dermatological brand managers anchored the qualitative base for this analysis. Primary interview insights were cross-validated against secondary sources including ANVISA regulatory filings, ECHA REACH substance registrations, TGA sunscreen testing guidelines, and customs trade data for zinc oxide and titanium dioxide imports. Bottom-up product-level modeling and top-down market sizing triangulated volume and value estimates.
Scenario-bracketing around regulatory acceleration and mineral supply disruption framed the projection envelope across the analysis window. Segmentation dimensions modeled include product type, formulation vehicle, SPF certification tier, and distribution channel structure. CAGRs were derived from adoption curve analysis and per-capita consumption intensity patterns. Forecast inputs incorporated outdoor recreation participation indices and pediatric spray format penetration trajectories.
Stress conditions across REACH enforcement severity, Chinese export licensing friction, and FDA monograph modernization pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding mineral particle engineering cost curves and subscription model adoption ceilings. Cross-checking against Nielsen retail audit data and pharmacy channel sell-through metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Halal Cosmetics Market
Cosmetics & Skincare
Bangladesh Face Wash Market
Cosmetics & Skincare
Organic Makeup Remover Market
Cosmetics & Skincare
Private Label Cosmetics Manufacturing Service Market
Cosmetics & Skincare
Baby Skincare Market
Cosmetics & Skincare
Tinted Cosmetics Market
Cosmetics & Skincare
Loose Setting Powder Market
Cosmetics & Skincare
Hyaluronic Acid Beauty Products Market
Cosmetics & Skincare
Nail Polish Market
Cosmetics & Skincare
Bath Soap Market
Cosmetics & Skincare
Deodorant Stick Market
Cosmetics & Skincare
Canada Cosmetic Products Market
Cosmetics & Skincare
Magnetic Fake Eyelashes Market
Cosmetics & Skincare
Halal Cosmetic Products Market
Cosmetics & Skincare
Essential Oil Soap Market
Cosmetics & Skincare
Eye Shadow Market