
 GPS Dog Collar Market | 2026-2036
GPS Dog Collar Market Size, Share, and Industry Trends Forecast 2026-2036
GPS Dog Collar Market Analytics
The capital-intensity gap between established wearable manufacturers and software-first startups is collapsing as component costs for GPS modules and cellular modems fall. Garmin leverages its in-house semiconductor design and aviation-grade positioning expertise to sustain premium pricing in the hunting and working dog segments. Tractive competes through aggressive subscription bundling and direct-to-consumer channel control across European markets. FitBark differentiates by integrating veterinary health metrics with location data, occupying a narrow but defensible position in the preventive care ecosystem.
A GPS dog collar is a wearable device that combines satellite positioning receivers, cellular or radio transceivers, and rechargeable power systems to transmit real-time location and activity data to owner-facing mobile applications. These devices typically operate on lithium-polymer batteries with IP67 or higher ingress protection ratings, enabling continuous outdoor use across temperature ranges from minus twenty to fifty degrees Celsius. Smart collars with integrated virtual fencing and health monitoring command the widest margin pools as pet owners trade up from basic tracking devices. Bluetooth-enabled fitness trackers represent the fastest-growing technology segment among urban adopters seeking lower-cost entry points without recurring subscription fees. Online retail channels now dominate volume distribution, though specialty pet stores sustain higher attachment rates for training collar configurations.
FCC Part 15 and Part 27 equipment authorization requirements govern radio-frequency emissions for GPS dog collars sold in the United States, while CE marking under the European Radio Equipment Directive shapes market access across EU member states. Japan's TELEC certification and spectrum allocation rules administered by the Ministry of Internal Affairs and Communications add further compliance layers for Asian market entry. Stakeholders must monitor evolving animal welfare legislation in multiple jurisdictions, as proposed restrictions on static correction features in training collars could force rapid product portfolio restructuring. The critical decision ahead involves balancing subscription revenue models against one-time hardware sales as consumer price sensitivity intensifies across mass retail channels.
Market Dynamics
Subscription-based geofencing services are displacing traditional physical fencing across suburban and exurban communities, compressing hardware replacement cycles while elevating recurring revenue expectations among device manufacturers.
Growth Catalysts
- CE marking under the European Radio Equipment Directive:Harmonized spectrum rules across EU member states reduce testing duplication for manufacturers targeting cross-border distribution, accelerating market entry timelines.
- Cellular LPWAN integration:Low-power wide-area network modules enable extended battery life in rural tracking scenarios where Wi-Fi coverage fails, expanding addressable use cases for working dog breeds.
- Exurban property expansion:Large-lot residential development outside major US metropolitan areas creates concentrated demand for virtual boundary systems that eliminate physical fence installation costs.
Market Restraints
- Lithium-polymer battery supply concentration:Asian cell manufacturers control cathode precursor refining, exposing hardware producers to input cost volatility and extended lead times during supply shocks.
- FCC Part 15 certification complexity:Radio-frequency emission testing for GPS collars requires third-party laboratory validation and administrative filing fees that consume six-figure budgets per product variant.
- Bluetooth fitness tracker substitution:Lower-cost wearable alternatives without cellular subscriptions attract urban adopters seeking basic activity monitoring without recurring fees.
Strategic Opportunities
- Veterinary health data convergence:Integration of biometric sensors with location tracking creates preventive care subscription tiers that capture margin from pet insurance partnerships.
- Direct-to-consumer channel expansion:Bypassing specialty retail intermediaries enables manufacturers to control subscription onboarding and reduce customer acquisition costs through owned digital properties.
- Japan TELEC certification pathway:Early regulatory alignment with Ministry of Internal Affairs and Communications spectrum rules opens access to high-value urban pet ownership markets with limited incumbent competition.
Industry Challenges
- RF engineering talent scarcity:Compact antenna design for multi-band cellular and GPS reception requires specialized expertise concentrated among semiconductor vendors, constraining in-house product development timelines.
- Animal welfare legislation monitoring:Proposed restrictions on static correction features in training collars across multiple US states and EU jurisdictions force continuous product portfolio risk assessment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GPS Dog Collar Market |
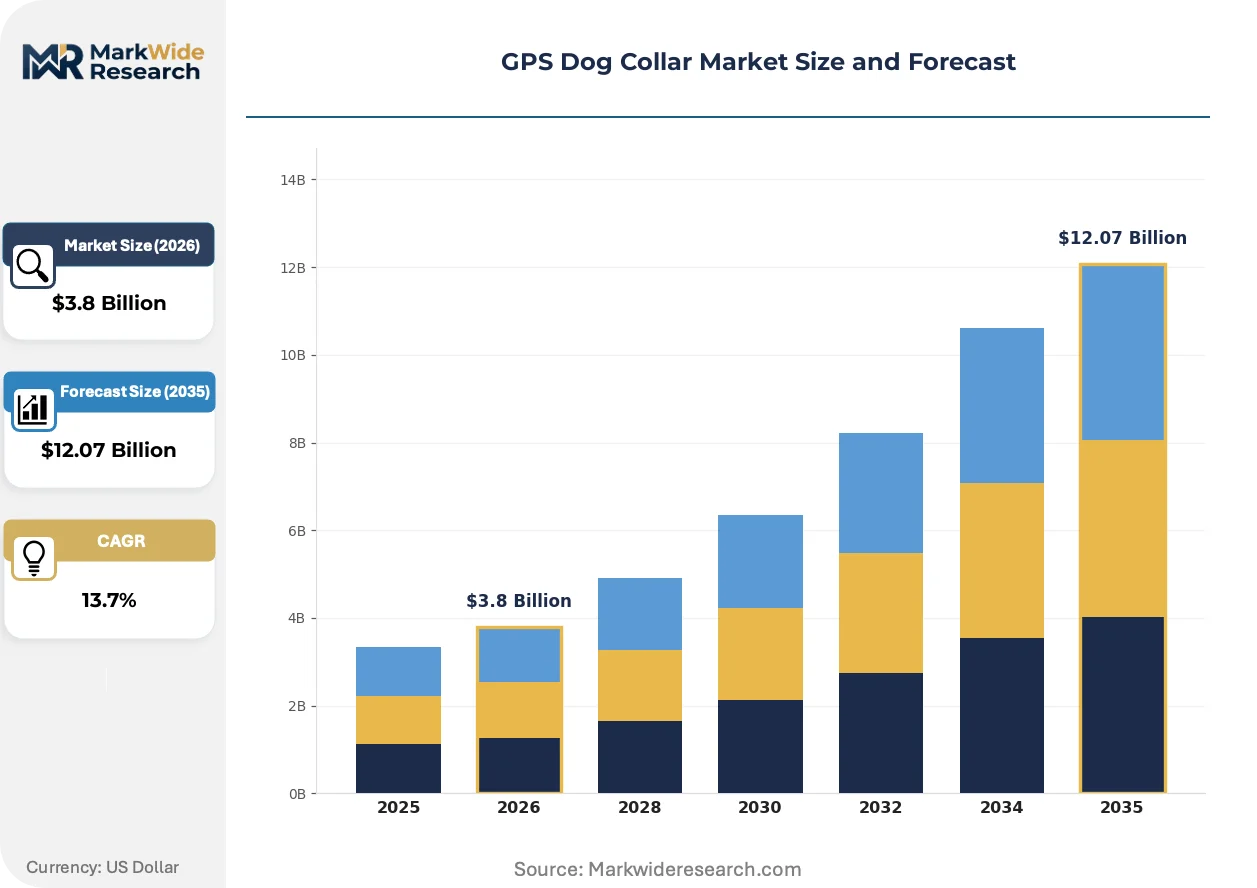
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.07 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Collars, Fitness Trackers, Tracking Devices, Training Collars Technology: GPS, GSM, Bluetooth, Wi-Fi End User: Pet Owners, Dog Trainers, Veterinarians, Pet Retailers Distribution Channel: Online Retail, Specialty Pet Stores, Veterinary Clinics, Mass Merchandisers |
| Companies Covered | Halo Collar, Tractive, Garmin, Satellai, FitBark, SpotOn, Fi Series, Aorkuler, SportDog, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GPS Dog Collar Market Evolving Landscape
Hardware commoditization is compressing margin pools at the device layer while software-enabled service tiers capture expanding share of lifetime customer value, forcing manufacturers to restructure revenue architecture around recurring relationships rather than transactional sales.
Multi-constellation GNSS receivers integrating GPS, GLONASS, and Galileo signals are displacing single-system positioning modules in premium collar configurations. Working dog handlers and hunting breed owners in rural Germany and the United States adopt these devices for sub-meter accuracy in dense canopy cover. The technology is displacing legacy radio-frequency tracking systems that required separate handheld receivers and limited operational range to line-of-sight distances.
Japan's Ministry of Internal Affairs and Communications has tightened spectrum allocation rules for 920 MHz band devices used in pet wearables, extending certification timelines and elevating documentation requirements for foreign manufacturers. Domestic distributors now demand pre-certified modules to avoid import delays, compressing hardware design flexibility. Specialty hunting collar configurations face the steepest compliance burden due to higher transmit power requirements for extended range applications.
Pet owners in suburban United States communities are unbundling after-sales service expectations from hardware purchase decisions, treating subscription geofencing as a standalone utility comparable to home security monitoring. Online retail channels capture volume through comparison shopping tools that emphasize total cost of ownership calculations over upfront device pricing. This behavioral shift is most visible among first-time smart collar adopters aged 25-40 who evaluate products through mobile-native research patterns rather than specialty store consultations.
GPS Dog Collar Market Segmentation
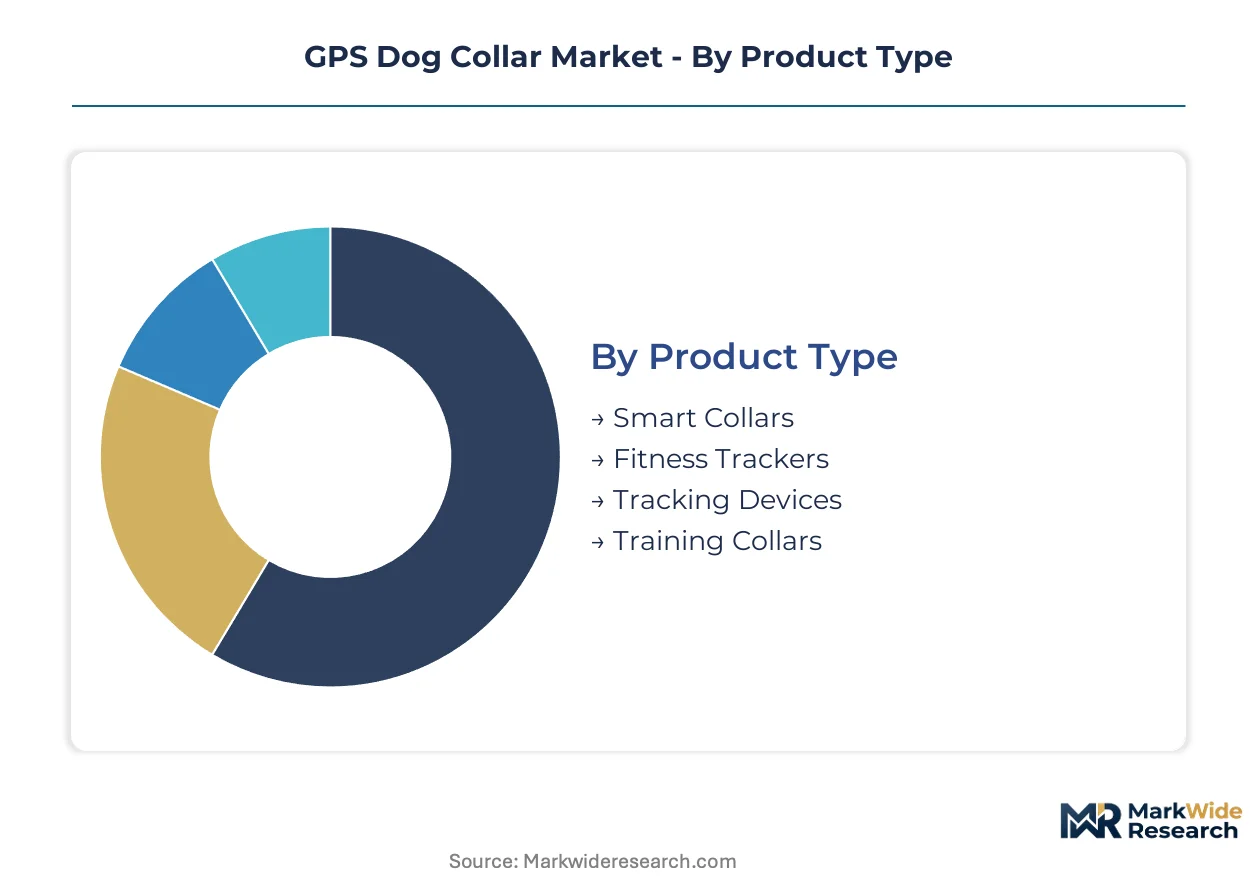
Segmentation reveals how GPS dog collar manufacturers navigate divergent buyer expectations across hardware sophistication, connectivity protocols, and channel economics. Product architecture choices directly determine recurring revenue potential and regulatory exposure.
Product Type:
Bluetooth fitness trackers exert substitution pressure on entry-level tracking devices by eliminating subscription dependencies, forcing smart collar manufacturers to defend premium positioning through integrated health diagnostics.
- Smart Collars:Multi-sensor platforms combine GNSS positioning, accelerometer-based activity classification, and temperature monitoring within IP67-rated enclosures. Suburban working dog owners in the United States concentrate demand here, driven by virtual fencing applications that eliminate physical boundary installation costs.
- Fitness Trackers:Bluetooth-only wearables capture basic activity metrics without cellular connectivity or recurring fees. Urban pet owners across Germany and Japan adopt these for apartment-dwelling breeds where geofencing utility remains limited.
- Tracking Devices:Single-purpose location transmitters with reduced sensor arrays target price-sensitive first-time adopters through mass retail channels.
- Training Collars:Static correction integration faces proposed restrictions across multiple US states and EU jurisdictions, elevating portfolio risk for manufacturers dependent on this configuration.
Tracking devices anchor the volume base while smart collars gain share at the steepest rate.
Technology:
Connectivity protocol selection determines battery endurance, subscription economics, and FCC Part 15 certification complexity across rural and urban deployment scenarios.
- GPS:Multi-constellation receivers integrating GPS, GLONASS, and Galileo signals deliver sub-meter accuracy in dense canopy cover. Hunting breed handlers in rural Germany and the United States drive adoption, displacing legacy radio-frequency systems with line-of-sight limitations.
- GSM:Cellular LPWAN modules enable extended battery life in rural tracking scenarios where Wi-Fi coverage fails. Working dog handlers across exurban United States communities rely on this technology for real-time location transmission beyond Bluetooth range.
- Bluetooth:Low-energy protocols support fitness tracker configurations with multi-year battery life but require smartphone proximity for data retrieval.
- Wi-Fi:Home-network-dependent positioning reduces cellular subscription costs for indoor-outdoor pets in urban environments with reliable router coverage.
GSM anchors the volume base while GPS-enabled configurations climb the fastest as precision requirements intensify among working dog segments.
End User:
Buyer type segmentation exposes divergent willingness-to-pay for preventive health integration versus pure location functionality.
- Pet Owners:Individual consumers represent the dominant demand pool, with working and hunting breed owners exhibiting highest subscription attachment rates for geofencing services.
- Dog Trainers:Professional handlers require ruggedized hardware with extended range capabilities and multi-dog management interfaces for field operations.
- Veterinarians:Clinical adoption concentrates on biometric-integrated collars that feed longitudinal health data into preventive care protocols and insurance partnerships.
- Pet Retailers:Channel intermediaries influence assortment decisions based on attachment rate economics, favoring configurations with training collar upsell potential.
Pet owners anchor the volume base while veterinarians gain share at the steepest rate through insurance-linked preventive care subscriptions.
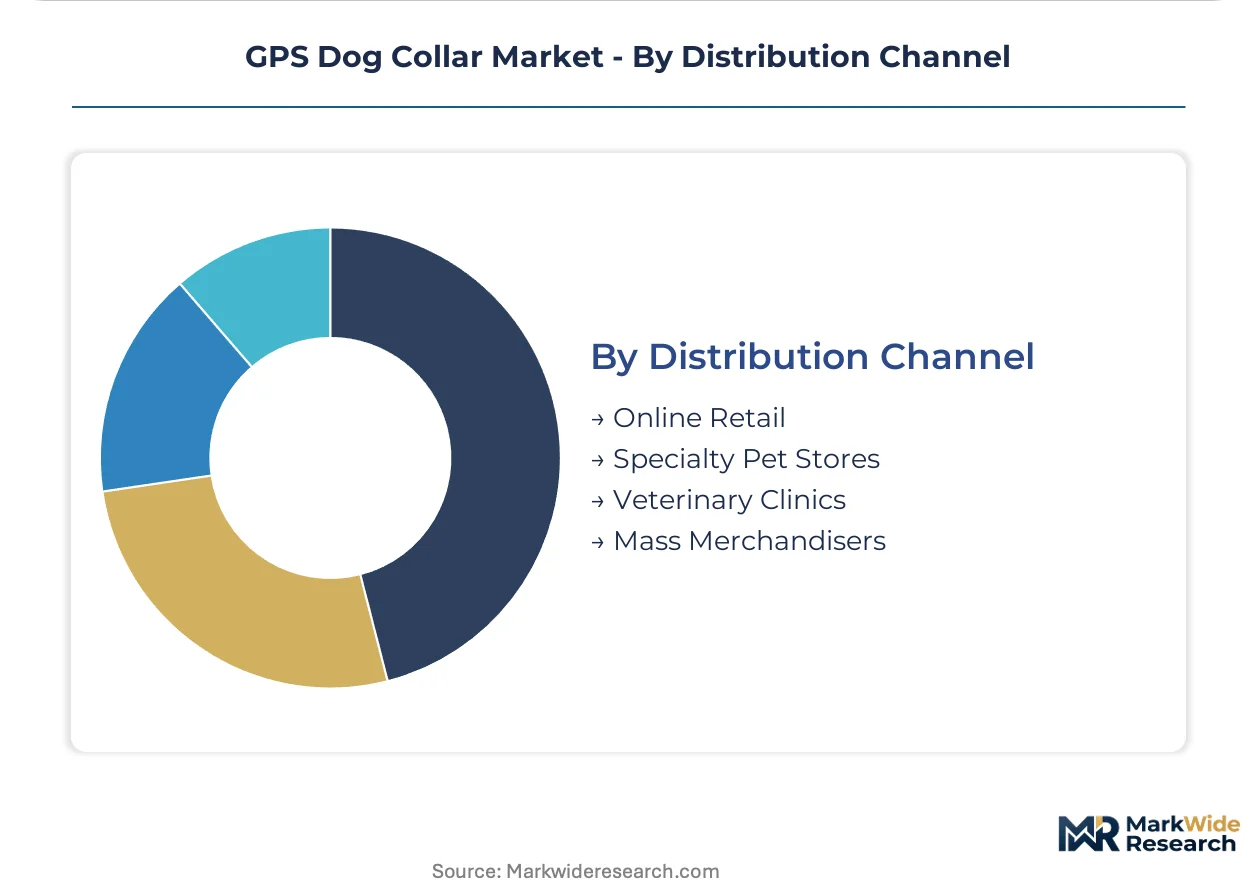
Distribution Channel:
Channel selection determines customer acquisition cost structures and subscription onboarding control for manufacturers restructuring around recurring revenue models.
- Online Retail:Direct-to-consumer platforms dominate volume distribution through comparison shopping tools that emphasize total cost of ownership calculations. First-time adopters aged 25-40 evaluate products through mobile-native research patterns here.
- Specialty Pet Stores:Staff consultation drives higher attachment rates for training collar configurations and premium smart collar upsells.
- Veterinary Clinics:Clinical endorsement channels support biometric-integrated collar adoption with health data credibility.
- Mass Merchandisers:Price-focused retail formats concentrate Bluetooth fitness tracker volume with minimal subscription conversion.
Online retail anchors the volume base while veterinary clinics gain share at the steepest rate through health data integration credibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where working dog handlers pay premiums for sub-meter accuracy, while Japanese buyers face compressed margins from extended TELEC certification timelines that elevate compliance costs for foreign entrants.
United States
Exurban property expansion across Texas and Florida drives concentrated demand for virtual boundary systems that eliminate physical fence installation costs. FCC Part 15 and Part 27 equipment authorization requirements govern radio-frequency emissions, forcing six-figure testing budgets per product variant. Atlanta and Dallas-Fort Worth anchor distribution clusters where specialty pet stores sustain higher attachment rates for training collar configurations.
Germany
Hunting breed owners in Bavaria and Baden-Württemberg adopt multi-constellation GNSS receivers for dense canopy cover precision. CE marking under the European Radio Equipment Directive harmonizes spectrum rules across EU member states, reducing testing duplication for cross-border distribution. Munich and Stuttgart concentrate veterinary clinic channels that support biometric-integrated collar adoption with health data credibility.
Japan
Urban pet owners in Tokyo and Osaka favor Bluetooth fitness trackers for apartment-dwelling breeds where geofencing utility remains limited. METI and the Ministry of Internal Affairs and Communications administer tightened spectrum allocation rules for 920 MHz band devices, extending certification timelines and elevating documentation requirements. Domestic distributors now demand pre-certified modules to avoid import delays.
United Kingdom
Suburban communities across Greater London and the Southeast trade up from basic tracking devices to smart collars with integrated health monitoring. CE marking requirements align with EU regulatory frameworks post-Brexit transition, maintaining market access continuity. Manchester and Birmingham anchor online retail distribution where mobile-native research patterns dominate among first-time adopters aged 25-40.
Canada
Working dog handlers in Alberta and British Columbia prioritize cellular LPWAN modules for rural tracking scenarios where Wi-Fi coverage fails. Health Canada and PMRA oversee device safety standards alongside ISED spectrum regulations for radio-frequency pet wearables. Toronto and Vancouver concentrate specialty retail channels where staff consultation drives premium smart collar upsells.
GPS Dog Collar Market Competitive Landscape
Concentration sits with established wearable manufacturers and software-first startups as component costs for GPS modules and cellular modems collapse the historical capital-intensity gap. The vendor base spans three tiers: aviation-grade positioning specialists commanding premium pricing, aggressive subscription bundlers controlling direct-to-consumer channels, and health data integrators occupying narrow preventive care positions. Dominant competitive moves include strategic partnerships with veterinary insurance providers and geographic expansion through pre-certified module sourcing to compress regulatory timelines.
Within the premium positioning tier, Garmin exemplifies aviation-grade expertise sustained through in-house semiconductor design. Tractive occupies the subscription-first archetype with direct-to-consumer channel control across European markets. FitBark represents health data convergence, integrating biometric sensors with location tracking to capture margin from preventive care ecosystems.
| Leading Market Players |
|---|
| Halo Collar |
| Tractive |
| Garmin |
| Satellai |
| FitBark |
| SpotOn |
| Fi Series |
| Aorkuler |
| SportDog |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements for lithium-polymer cells lock in supply access for GPS collar manufacturers while constraining price visibility against volatile cathode precursor markets. These contract structures tether hardware margins to Asian cell supplier pricing power, compressing flexibility for subscription-first vendors competing on total cost of ownership.
Pricing Analysis
Configured-to-order pricing for multi-constellation GNSS receivers commands substantial premiums over standard Bluetooth fitness tracker configurations. The dominant model runs subscription-tiered SaaS pricing bundled with hardware financing, where price differentiation rests on certification grade (FCC Part 15 vs CE marking tier) and vertical integration depth. Cost compression in entry-level cellular modules is intensifying because component commoditization accelerates, with urban adopters aged 25-40 exhibiting highest price sensitivity against working dog handlers who absorb premium positioning.
Supply Chain Analysis
Extended lead times for cellular modem chipsets now stretch sixteen to twenty-four weeks, forcing inventory pre-positioning ahead of seasonal demand spikes. Supply concentrates in China for lithium-polymer cell fabrication, Taiwan for GNSS receiver silicon, and Vietnam for final assembly enclosures. Hardware producers draw from rare earth magnet suppliers for compact antenna motors and ceramic substrate vendors for RF shielding. Single-source vulnerability in Qualcomm and MediaTek cellular baseband allocation elevates disruption risk. Distribution runs through direct-to-consumer platforms and veterinary clinic channels with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPS dog collar penetration remains below fifteen percent of addressable pet households, positioning the market as an early-cycle expansion story justified by accelerating subscription attachment among working breed owners replacing physical fencing.
For Market Incumbents: Consolidate subscription revenue architecture around veterinary health data partnerships before Bluetooth fitness trackers capture urban price-sensitive volume. Defend against software-first entrants by deepening in-house semiconductor design capabilities that sustain aviation-grade positioning premiums. Prioritize certification investment in Japan TELEC pathways to preempt regulatory delays that compress foreign entrant margins. For New Entrants and Emerging Players: Differentiate on preventive care integration by targeting veterinarians as channel gatekeepers for biometric-integrated collar adoption. The most penetrable white-space sits in exurban United States communities where cellular LPWAN coverage gaps create demand for hybrid connectivity solutions. Pursue direct-to-consumer launch with owned digital properties that control subscription onboarding and reduce customer acquisition costs relative to mass retail intermediaries. For Investors and Strategic Acquirers: Health data convergence specialists with veterinary insurance partnerships represent the highest-conviction acquisition archetype for long-term viability within a five-to-ten-year window. Monitor static correction legislation across multiple US states and EU jurisdictions as the critical inflection signal; material restrictions would force portfolio restructuring and elevate software-only subscription models. Revision becomes warranted when proposed training collar bans cross legislative thresholds in jurisdictions representing over twenty percent of hardware revenue exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Insurance Partnership | Biometric data integration with pet insurers captures recurring preventive care subscription revenue pools. |
| Direct-to-Consumer Channel Expansion | Owned digital properties reduce customer acquisition costs and control subscription onboarding workflows. |
| Pre-Certified Module Sourcing | Japan TELEC pre-certified cellular modules compress regulatory timelines and accelerate market entry. |
| Multi-Constellation GNSS Integration | Sub-meter accuracy in dense canopy cover sustains premium pricing among hunting breed handlers. |
| Software-Only Subscription Pivot | Pure SaaS geofencing models hedge against proposed static correction bans in training collar configurations. |
Research Methodology
A standing panel of veterinary clinic procurement managers, specialty pet store category buyers, RF engineering leads at semiconductor vendors, and cellular carrier IoT partnership directors provided ongoing calibration across the study. Primary interviews with device manufacturers and subscription service operators combined with secondary validation against FCC equipment authorization databases, CE marking registries, and customs trade data for lithium-polymer cell imports. Bottom-up unit economics modeling triangulated against top-down addressable pet household penetration estimates.
Consistency checks validated volume and value outputs against external benchmarks including veterinary practice management software adoption curves and pet insurance policy growth trajectories. The analytical framework segmented across product architecture tiers, connectivity protocol types, buyer archetypes, and regional regulatory clusters throughout the projection horizon. CAGRs derived from fitted adoption curves incorporating working dog breed registration data and exurban property development permits as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FCC Part 15 enforcement, CE marking harmonization, and Japan TELEC spectrum allocation; material policy shifts would require re-modeling. Specific risks include lithium-polymer supply shocks, proposed static correction bans, and cellular carrier IoT pricing restructuring. Revision becomes warranted when proposed training collar restrictions achieve legislative passage in multiple jurisdictions simultaneously.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Dental Health Market
Pet Care Products
Small Dog Harness Market
Pet Care Products
India Pet Clothing Market
Pet Care Products
Pet Food Pulverizer Market
Pet Care Products
Pet Supplement Market
Pet Care Products
Taiwan Pet Food Market
Pet Care Products
Elevated Dog Bowls Market
Pet Care Products
Fresh and Frozen Dog Food Market
Pet Care Products
Cat Scratchers and Trees Market
Pet Care Products
Aquarium Market
Pet Care Products
Dog Carrier Bags Market
Pet Care Products
Pet Smart Tracker Market
Pet Care Products
North America Functional Pet Treat Market
Pet Care Products
China Pet Clothing Market
Pet Care Products
Asia-Pacific Pet Treats Market
Pet Care Products
Dog Food Market