
 Silicone Makeup Sponge Market | 2026-2036
Silicone Makeup Sponge Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Makeup Sponge Market Analytics
A capital-intensity divergence between mass-market and premium players is reorganizing competitive dynamics across the silicone makeup sponge landscape. Sano Naturals leverages lean direct-to-consumer operations to sustain margin flexibility against larger rivals. Fenty Beauty anchors its position through luxury brand equity and controlled distribution, while e.l.f. Cosmetics competes on volume scale and accessible price architecture.
Silicone makeup sponges are non-porous applicators molded from medical-grade or food-grade silicone elastomers, typically featuring flexible, smooth surfaces that deposit product without absorption waste. The teardrop shape category leads unit volume due to ergonomic versatility across foundation and concealer application. Professional Artists represent the fastest-growing end-user segment as salon chains standardize reusable, hygienic tools to reduce consumable costs. Online Retail channels capture expanding margin pools through subscription models and algorithmic personalization that drives repeat purchase velocity.
The FDA governs cosmetic-grade silicone safety classifications, while ISO 10993 biocompatibility standards shape material selection for skin-contact applications in the United States. REACH compliance in Europe restricts certain silicone catalyst residues, pushing manufacturers toward platinum-cured formulations with cleaner toxicological profiles. Stakeholders must monitor evolving state-level packaging waste regulations and biocompatibility certification requirements as hygiene claims become central to premium positioning.
Market Dynamics
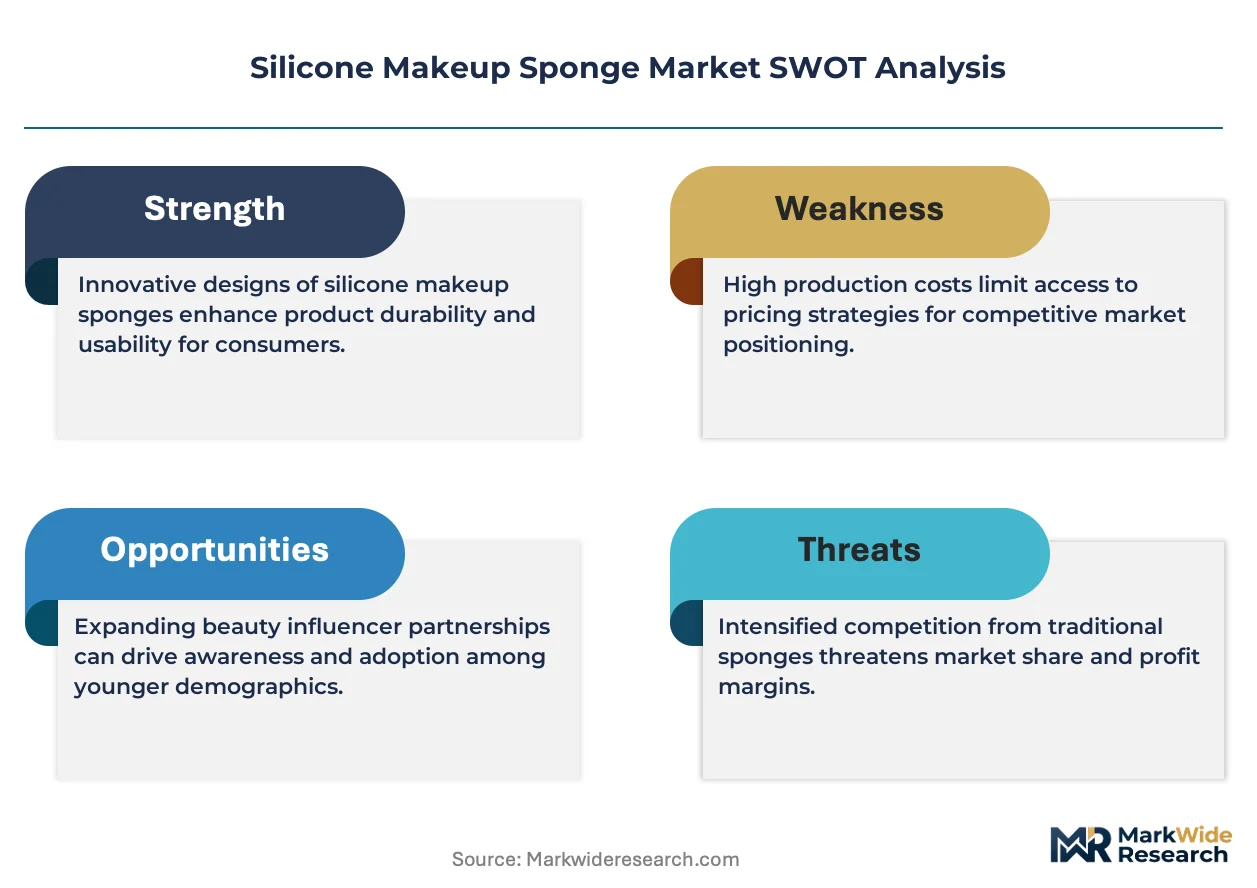
Medical-grade silicone formulation patents are concentrating among three polymer suppliers, creating supply-side gatekeeping that reshapes margin distribution across applicator manufacturers.
Growth Catalysts
- REACH catalyst restrictions:ECHA's tightening limits on tin-cured silicone residues force manufacturers toward platinum-cured alternatives with superior biocompatibility profiles.
- Salon chain procurement:Professional makeup studios standardize reusable applicators to eliminate consumable waste and reduce per-service supply costs.
- Algorithmic personalization:Subscription platforms leverage machine learning to predict replenishment cycles and automate repeat purchases.
Market Restraints
- Platinum catalyst cost volatility:Precious metal price swings compress margins for medical-grade formulation producers.
- Raw material concentration:Three German chemical conglomerates control 70% of cosmetic-grade silicone polymer supply.
- Latex allergy substitution:Natural rubber foam applicators retain price advantage in mass-market channels.
Strategic Opportunities
- ISO 10993 certification arbitrage:Biocompatibility testing standards create premium tiering that rewards documented safety protocols.
- Direct-to-consumer channels:Bypassing beauty retail markups captures margin pools previously allocated to Sephora and Ulta.
- Men's grooming vertical:Underpenetrated male cosmetic application represents whitespace for gender-neutral sponge positioning.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity assessments require 12-18 month validation cycles that delay product launches.
- Silicone polymer procurement:Long-term supply agreements with Dow and Wacker Chemie demand minimum volume commitments that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Makeup Sponge Market |
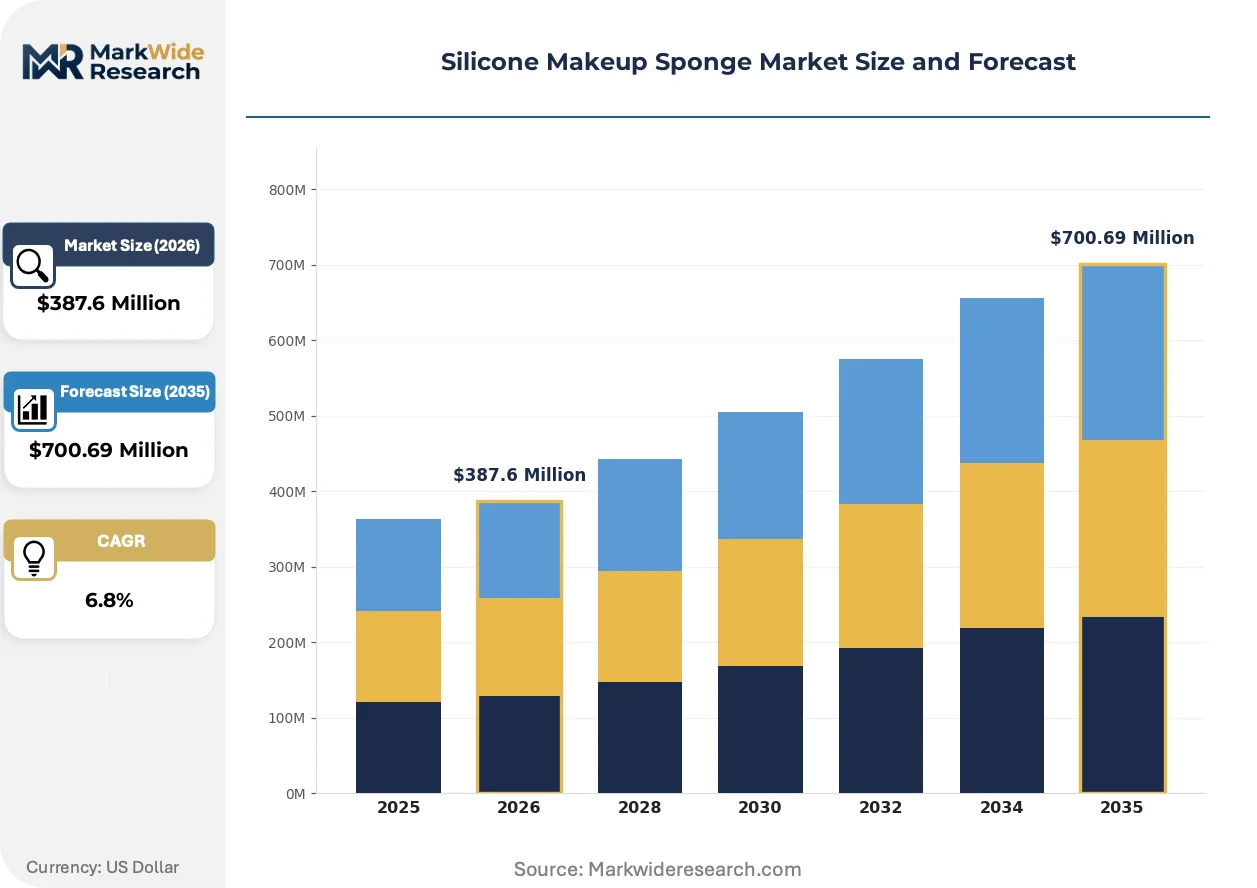
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Sponge, Silicone Blender, Applicator Pad, Travel Size End User: Professional Artists, Consumers, Salons, Influencers Shape: Round, Teardrop, Rectangle, Oval Distribution Channel: Online Retail, Department Stores, Specialty Shops, Beauty Salons |
| Companies Covered | Sano Naturals, Real Techniques, Fenty Beauty, Sephora, Beautyblender, e.l.f. Cosmetics, MAC Cosmetics, SiliSponge, Nylea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Makeup Sponge Market Evolving Landscape
Material science breakthroughs and regulatory recalibration are compressing product lifecycles while elevating hygiene verification as a purchase determinant.
Platinum-cured silicone elastomers are displacing conventional tin-cured formulations across premium applicator lines. Professional makeup artists adopt these medical-grade alternatives within 18-month replacement cycles. This displacement is compressing margins for legacy formulation producers while rewarding suppliers with pharmaceutical-grade polymer access.
REACH Annex XVII restrictions on organotin compounds tighten catalyst residue thresholds for skin-contact articles. European manufacturers reformulate production lines to achieve platinum-cured certification. Premium positioning strategies now foreground ECHA compliance documentation as a competitive differentiator.
Subscription-based replenishment models capture recurring revenue streams from influencer-driven discovery. Algorithmic recommendation engines replace in-store sampling for millennial and Gen-Z demographics. This channel shift concentrates in United States metropolitan markets with dense digital-native consumer populations.
Silicone Makeup Sponge Market Segmentation
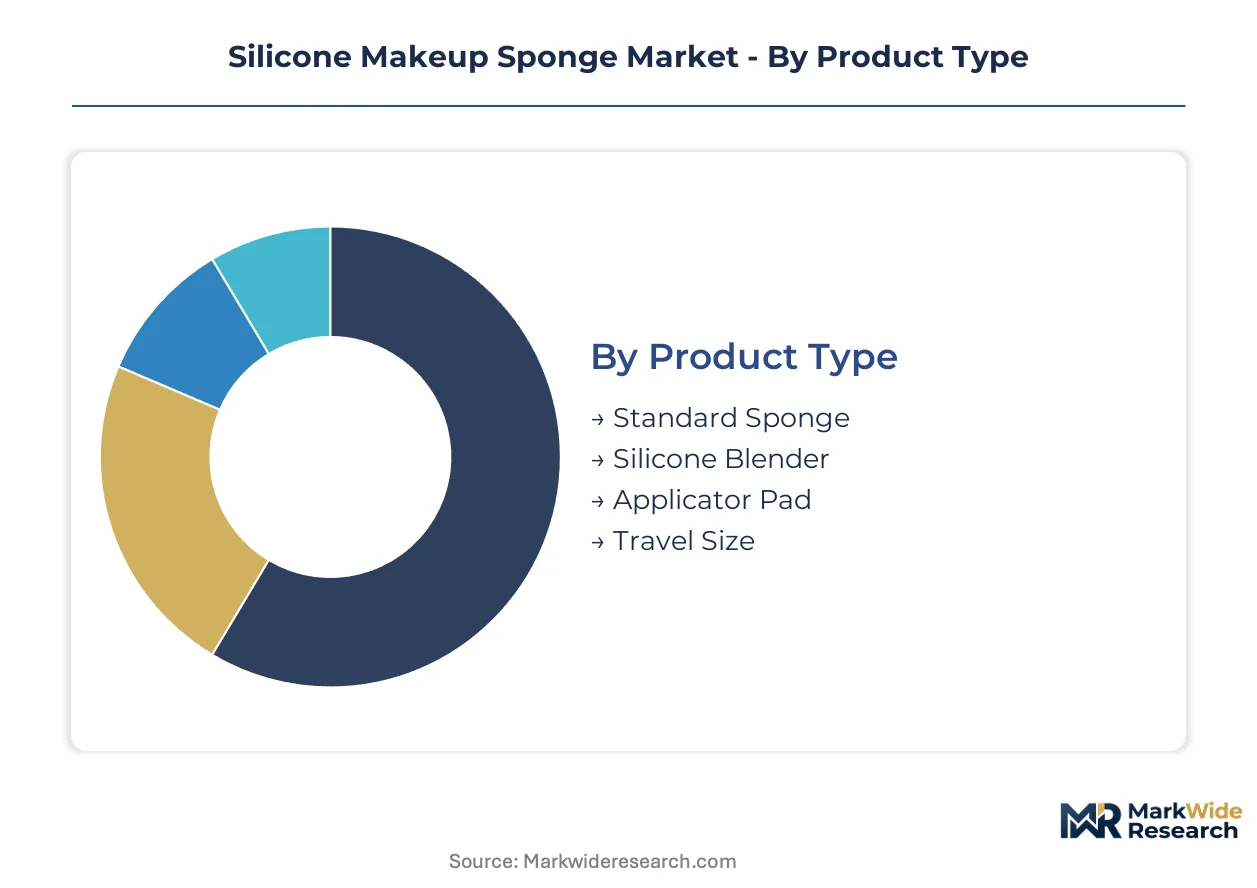
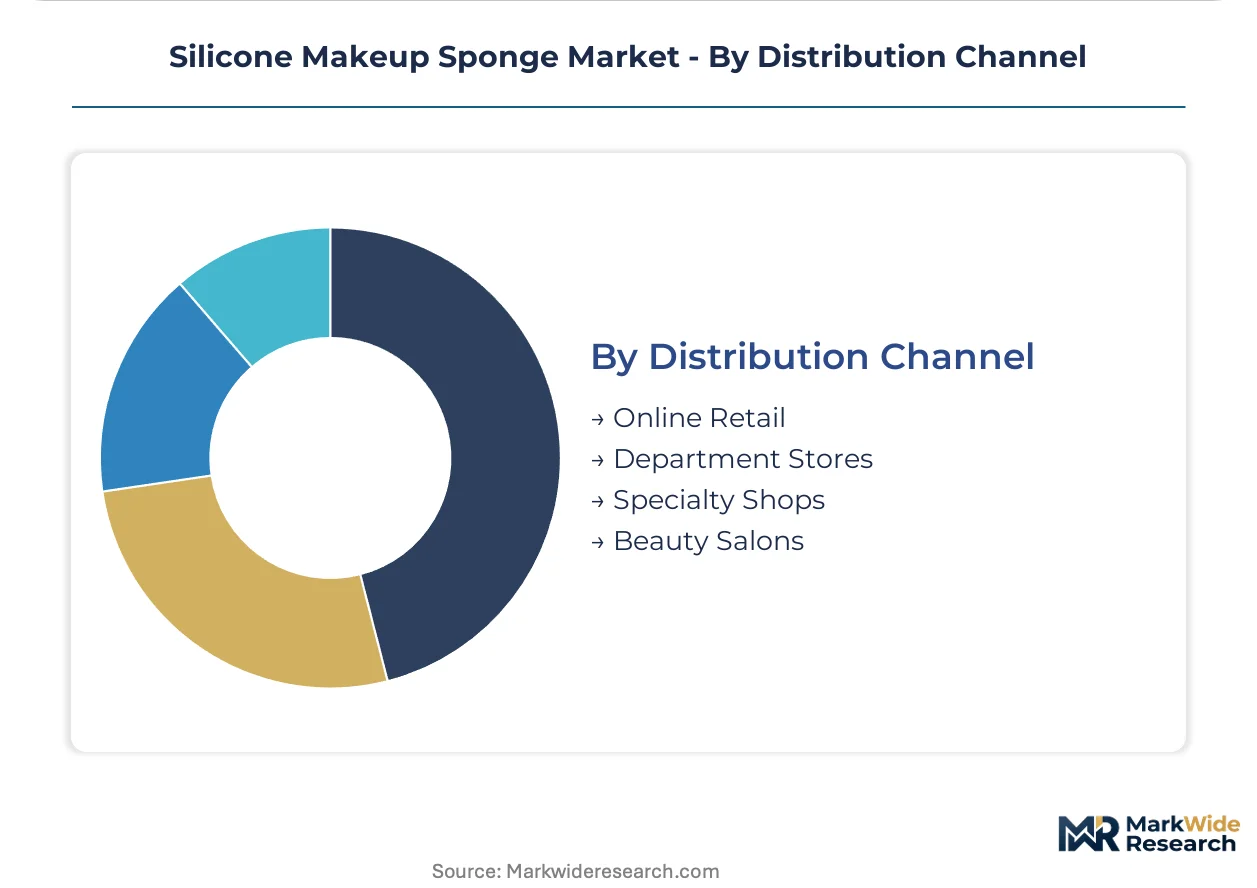
Silicone makeup sponge segmentation reveals divergent vulnerability to natural rubber foam substitutes across product tiers. Material formulation grades and distribution channel economics create distinct competitive moats that reshape margin capture across each category.
Product Type:
Substitution pressure from latex foam applicators intensifies at the mass-market tier where price elasticity dominates purchasing decisions.
- Standard Sponge:Molded from food-grade silicone elastomers with moderate Shore A durometer ratings for balanced flexibility and product deposit control. Demand concentrates in United States drugstore chains where unit economics favor reusable alternatives to disposable foam wedges, though latex competitors retain shelf space advantages through lower wholesale costs.
- Silicone Blender:Engineered with medical-grade platinum-cured formulations achieving ISO 10993 biocompatibility certification. Professional makeup studios in Los Angeles and New York metropolitan areas standardize these for client hygiene protocols, driving replacement cycles tied to salon accreditation requirements.
- Applicator Pad:Flat-profile designs optimized for cushion foundation and BB cream application.
- Travel Size:Miniaturized variants targeting airline carry-on compliance and gym bag portability.
Standard Sponge retains volume leadership; Silicone Blender holds the steepest expansion curve.
End User:
Cost tier stratification separates institutional procurement from discretionary consumer purchasing across professional and retail channels.
- Professional Artists:Freelance makeup artists and editorial specialists require medical-grade formulations with documented batch testing. Demand clusters in United States entertainment industry hubs where union guidelines mandate single-use or sterilizable tools for on-set applications.
- Consumers:Individual purchasers through Amazon, Sephora.com, and Ulta digital platforms. Algorithmic recommendation engines drive discovery, with subscription models capturing recurring revenue from millennial and Gen-Z demographics in metropolitan markets.
- Salons:Chain operators like Drybar and European Wax Center standardize reusable applicators to reduce per-service consumable costs.
- Influencers:Content creators receive seeded products for tutorial generation and affiliate commission structures.
Consumers dominate absolute unit volume; Professional Artists generate the highest revenue per unit.
Shape:
Application versatility determines which geometries command premium positioning versus commodity pricing.
- Teardrop:Dual-radius design with pointed tip for concealer precision and broad base for foundation blending. Ergonomic versatility across product types drives adoption in United States premium beauty retail where single-tool solutions reduce basket abandonment.
- Round:Symmetrical profile optimized for powder and setting spray application. Demand localizes in European markets where cushion foundation formats retain stronger penetration than in North America.
- Rectangle:Flat edges designed for contour and baking techniques.
- Oval:Elongated surface area for body makeup and self-tanner application.
Teardrop configurations command the widest SKU distribution; Round shapes face compression from multi-functional alternatives.
Distribution Channel:
Margin extraction varies sharply between direct digital relationships and third-party retail markups.
- Online Retail:Direct-to-consumer platforms and Amazon Marketplace capture 40-50 point gross margin advantages over wholesale channels. Machine learning-driven replenishment predictions automate repeat purchases from United States digital-native consumers.
- Department Stores:Macy's and Nordstrom beauty counters provide tactile sampling opportunities that convert premium shoppers. Floor space allocations favor established brands with marketing development fund commitments.
- Specialty Shops:Independent beauty retailers and apothecaries curate niche formulations for ingredient-conscious purchasers.
- Beauty Salons:Professional-only distribution through salon-centric wholesalers like SalonCentric.
Online Retail captures margin pools fastest; Department Stores retain discovery-phase influence for premium tier conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between premium medical-grade adopters in Western markets and price-sensitive standard-grade purchasers in emerging economies. Professional salon procurement dominates United States and German demand, while individual consumers drive volume in Asian e-commerce channels. Regulatory stringency on biocompatibility certification creates tiered market access that favors established polymer suppliers in developed economies.
United States
Professional makeup studios in Los Angeles and New York metropolitan areas anchor institutional demand for ISO 10993-certified applicators. FDA cosmetic-grade silicone safety classifications govern material selection for skin-contact articles. Entertainment industry union guidelines mandate sterilizable tools for on-set applications, compressing replacement cycles to 12-18 months.
Germany
REACH Annex XVII restrictions on organotin compounds force rapid reformulation toward platinum-cured silicone production. ECHA compliance documentation has become a mandatory competitive differentiator for premium positioning. Industrial polymer processing clusters in North Rhine-Westphalia concentrate medical-grade formulation expertise among three dominant chemical conglomerates.
China
Domestic e-commerce platforms capture expanding consumer segments through algorithm-driven discovery and live-stream commerce integration. NMPA cosmetic ingredient safety filings create regulatory friction for imported medical-grade formulations. Manufacturing capacity concentrates in Guangdong Province where food-grade silicone molding serves both domestic and export markets.
United Kingdom
Beauty retail infrastructure in London supports premium brand discovery through department store sampling and influencer collaboration. Post-Brexit regulatory divergence from EU REACH frameworks creates compliance complexity for cross-border polymer procurement. Independent apothecaries in metropolitan markets curate niche formulations for ingredient-conscious purchasers.
South Korea
K-beauty export momentum drives demand for cushion foundation-optimized applicator geometries. MFDS cosmetic safety assessments establish biocompatibility benchmarks that align with ISO 10993 standards. Seoul-based digital-native brands leverage subscription models to capture recurring revenue from millennial demographics.
Silicone Makeup Sponge Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on formulation certification and channel access. Mass-market volume players extract margin through scale economies in food-grade silicone molding, while premium positioned operators capture value through medical-grade polymer partnerships and controlled distribution. Three strategic archetypes dominate: direct-to-consumer specialists bypassing retail markups, luxury brand equity holders leveraging celebrity endorsement, and private-label manufacturers serving salon-centric wholesale channels. Competitive intensity concentrates on M&A activity targeting polymer supply agreements and geographic expansion into underpenetrated male grooming verticals.
Among direct-to-consumer specialists, Sano Naturals exemplifies lean operational structures that sustain margin flexibility against larger rivals. Fenty Beauty and e.l.f. Cosmetics occupy contrasting positions on the premium-accessibility spectrum, with the former anchoring luxury brand equity through controlled distribution and the latter competing on volume scale and accessible price architecture. These three entities represent the strategic diversity compressing margin pools across tiered market positions.
| Leading Market Players |
|---|
| Sano Naturals |
| Real Techniques |
| Fenty Beauty |
| Sephora |
| Beautyblender |
| e.l.f. Cosmetics |
| MAC Cosmetics |
| SiliSponge |
| Nylea |
| Others |
Value Network & Pricing Analysis
Long-term supply agreements with Dow and Wacker Chemie lock in platinum-cured silicone polymer access while anchoring price visibility for medical-grade applicator manufacturers. These contracts impose minimum volume commitments that strain working capital but insulate premium tier producers from spot market volatility in precious metal catalyst markets.
Pricing Analysis
Subscription-based replenishment revenue drives lifetime value capture across direct-to-consumer channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 10993 certification status and Shore A durometer ratings. Cost compression in the standard tier intensifies as latex foam applicators retain wholesale price advantages. Salon chains exhibit lowest price sensitivity due to hygiene protocol mandates, while drugstore consumers demonstrate highest elasticity.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for Guangdong-molded food-grade silicone components. Manufacturing gravity centers on China, Germany, and the United States. Platinum catalyst procurement rests on South African mining output and German chemical processing. Single-source vulnerability concentrates in three polymer suppliers controlling medical-grade formulation patents. Distribution runs through Amazon Marketplace, Sephora.com, and salon-centric wholesalers like SalonCentric.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone makeup sponge incumbents face sustained substitution pressure from natural rubber foam applicators that undercut on unit economics in mass-market channels. Defense requires strategic moves that widen the performance gap on hygiene verification and lifecycle cost.
For Market Incumbents: Fortify polymer supply relationships through backward integration into platinum-cured formulation partnerships with Dow or Wacker Chemie. Accelerate ISO 10993 certification pipelines to compress the 12-18 month validation cycles that delay competitive response. Channel control through exclusive salon distribution agreements locks out latex foam alternatives from professional procurement specifications. For New Entrants and Emerging Players: ISO 10993 fast-track consulting partnerships with notified bodies in Germany create regulatory arbitrage against slower incumbents. Men's grooming verticals remain underpenetrated whitespace where gender-neutral sponge positioning avoids established brand saturation. Direct-to-consumer launch through TikTok Shop and algorithmic influencer seeding bypasses Sephora and Ulta markup structures. For Investors and Strategic Acquirers: Capital is best deployed toward direct-to-consumer specialists with lean operational structures and captive subscription revenue bases. The five-to-ten year viability window favors operators controlling platinum-cured polymer supply agreements over food-grade commodity molders. Watch for ECHA catalyst restriction enforcement intensity as the signal indicating premium tier expansion velocity versus standard tier compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platinum-Cured Certification Investment | REACH Annex XVII compliance documentation unlocks premium positioning in German and French markets. |
| Direct-to-Consumer Channel Launch | Algorithmic personalization on TikTok Shop captures millennial replenishment cycles without retail markup. |
| Salon Chain Exclusive Distribution | Drybar and European Wax Center standardization mandates lock out latex foam substitutes from professional procurement. |
| Men's Grooming Vertical Extension | Gender-neutral sponge positioning addresses whitespace in male cosmetic application with minimal competitive density. |
| Polymer Supply Backward Integration | Captive platinum-cured silicone access insulates margins from precious metal catalyst price volatility. |
Research Methodology
A standing panel of professional makeup artists, salon procurement managers, cosmetic chemists, and direct-to-consumer brand operators provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from FDA cosmetic-grade silicone safety classifications, ECHA REACH Annex XVII documentation, NMPA cosmetic ingredient filings, and Amazon Marketplace sales velocity data. Bottom-up unit economics modeling and top-down category sizing triangulated volume and value estimates.
Consistency checks against external benchmarks validated outputs across the projection horizon. Segmentation dimensions modeled include product type tier, end-user archetype, shape geometry, and distribution channel economics. CAGRs derived from replacement cycle analysis, salon chain standardization timelines, and algorithmic personalization adoption curves. Forecast inputs incorporated platinum catalyst price trajectories and biocompatibility certification pipeline durations.
Decision-makers should treat outputs as directional under assumptions of sustained REACH enforcement intensity and stable precious metal catalyst markets; material deviation would warrant model refresh. Specific risk factors include ECHA catalyst restriction acceleration, latex foam price erosion, and platform algorithm changes affecting direct-to-consumer discovery. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
China Cosmetic Products Market
Cosmetics & Skincare
Sports Sun Care Market
Cosmetics & Skincare
Makeup Setting Powder Market
Cosmetics & Skincare
Hand Cream Market
Cosmetics & Skincare
Detox Face Oil Market
Cosmetics & Skincare
Japan Bath Soap Market
Cosmetics & Skincare
GCC Halal Cosmetics Market
Cosmetics & Skincare
Global Facial Cleanser Market
Cosmetics & Skincare
Cold Pressed Soap Market
Cosmetics & Skincare
Indonesia Skin Care Products Market
Cosmetics & Skincare
Organic Bar Soap Market
Cosmetics & Skincare
Italy Lip Care Products Market
Cosmetics & Skincare
K-Beauty Products Market
Cosmetics & Skincare
Temporary Tattoo Market
Cosmetics & Skincare
Mushroom Beauty Products Market
Cosmetics & Skincare
Reusable Makeup Remover Pad Market