
 United Arab Emirates Cosmetic Products Market | 2026-2036
United Arab Emirates Cosmetic Products Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Cosmetic Products Market Analytics
Personalized beauty subscription services is pivoting how UAE consumers discover and repurchase cosmetic products. Huda Beauty LLC leverages its founder-driven digital ecosystem to sustain direct engagement with regional buyers. L'Oréal S.A. anchors its Gulf operations through dedicated innovation labs in Dubai. Shiseido Company, Limited differentiates via sensorial formulation expertise tailored to Middle Eastern climate conditions.
Cosmetic products encompass chemically formulated preparations applied to the human body for cleansing, beautifying, promoting attractiveness, or altering appearance, typically containing emulsifiers, active ingredients, and preservatives at specified pH and stability thresholds. These products serve personal grooming, professional beauty services, and therapeutic skincare applications across consumer and institutional channels. Skincare commands the largest revenue pool given year-round sun exposure and premium anti-aging positioning in the UAE climate. Fragrance segments occupy disproportionate shelf space in department stores, reflecting cultural significance and gift-purchase behavior. Online Retail channels represent the fastest-growing distribution vector as same-day delivery infrastructure matures across Abu Dhabi and Dubai.
MOHAP enforces cosmetic product registration, labeling compliance, and ingredient safety assessments for all items entering UAE commercial channels. The Emirates Authority for Standardization and Metrology mandates halal certification alignment for products targeting Muslim consumers, while GCC harmonization protocols streamline cross-border market access. Stakeholders must monitor evolving disclosure requirements and certification timelines to secure uninterrupted shelf placement.
Market Dynamics
MOHAP's cosmetic ingredient disclosure mandates are forcing manufacturers to restructure formulation transparency protocols across UAE commercial channels. Professional salon and spa bundling is simultaneously compressing traditional retail velocity while elevating service-integrated product turnover.
Growth Catalysts
- Halal Certification Alignment:Emirates Authority for Standardization and Metrology mandates are opening premium positioning for compliant brands targeting Muslim consumers. GCC harmonization protocols streamline cross-border access into Saudi Arabia, Kuwait, and Oman.
- Same-Day Delivery Infrastructure:Abu Dhabi and Dubai logistics networks mature, enabling online retail channels to capture repurchase cycles previously locked to mall-based discovery.
- Climate-Adapted Formulation:Year-round sun exposure drives anti-aging and protective skincare R&D, with sensorial expertise tailored to Middle Eastern humidity and temperature conditions commanding shelf priority.
Market Restraints
- Import Dependency for Active Ingredients:Specialty chemical supply concentrates in European and East Asian manufacturing hubs, exposing UAE formulators to freight cost volatility and extended lead times.
- MOHAP Registration Timelines:Cosmetic product registration and safety assessment protocols create six-to-twelve month commercialization delays for new market entrants.
- Flagship Real Estate Concentration:Brand visibility depends on Dubai Mall and Mall of the Emirates premium positioning, where occupancy costs filter mid-tier competitors from physical retail.
Strategic Opportunities
- Abu Dhabi Retail Corridor Expansion:Yas Island and Saadiyat Island development creates underpenetrated high-income catchment zones beyond Dubai's saturated flagship zones.
- AI-Driven Personalization:Skin diagnostic tools and algorithmic shade-matching converge with subscription logistics to capture recurring revenue outside traditional retail.
- Professional Channel Integration:Medical spa and dermatology clinic partnerships offer prescription-adjacent credibility and patient trust transfer for clinical-grade cosmetic positioning.
Industry Challenges
- Formulation Chemist Scarcity:Halal-compliant cosmetic chemistry expertise remains concentrated in Southeast Asian and European talent pools, forcing UAE manufacturers into competitive relocation packages.
- Legacy ERP Integration:Batch traceability systems required by MOHAP conflict with decades-old inventory management infrastructure at regional distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Cosmetic Products Market |
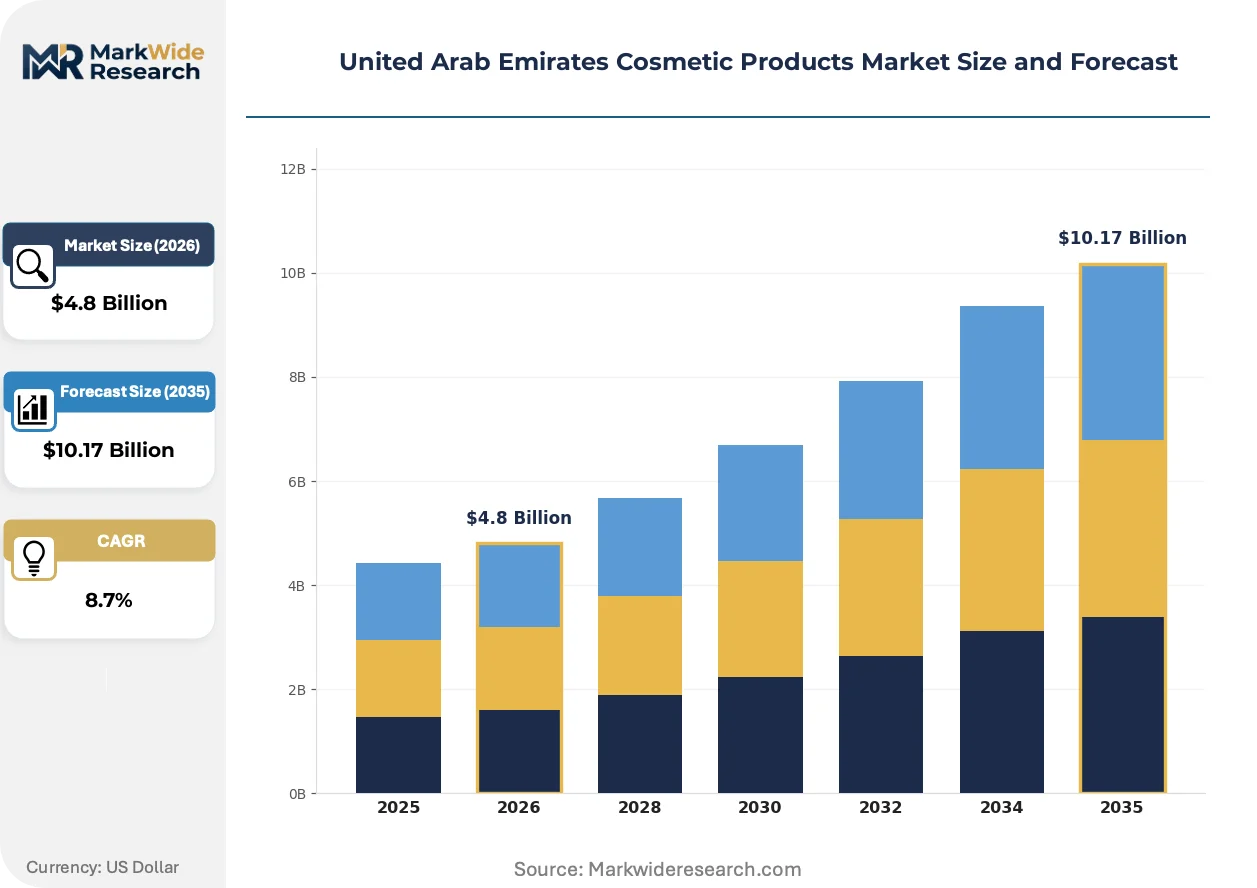
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Haircare, Fragrance End User: Gender-specific, Age-specific, Professional, General Consumer Distribution Channel: Online Retail, Department Stores, Specialty Stores, Supermarkets Price Tier: Luxury, Mid-range, Budget, Premium |
| Companies Covered | Huda Beauty LLC, Scion International LLC, The Estée Lauder Companies, Softcare Cosmetics, Beauty Leaders LLC, L'Oréal S.A., Shiseido Company, Limited, Rūt Essentials, LVMH Moët Hennessy Louis Vuitton, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Cosmetic Products Market Evolving Landscape
Digital-native discovery mechanisms are fragmenting traditional department store gatekeeping across UAE beauty retail. Technology convergence, regulatory tightening, and channel disintermediation now operate as simultaneous restructuring forces.
Biometric skin analysis hardware is unifying diagnostic data capture with personalized regimen recommendations. Medical spa chains and high-end salon groups deploy these systems at point-of-service to compress consultation-to-purchase cycles. The technology is unifying previously separate diagnostic, recommendation, and fulfillment steps into single-visit transactions that displace traditional counter-based sampling.
MOHAP's evolving cosmetic ingredient disclosure mandates now require full supply chain documentation for preservatives, active compounds, and fragrance allergens entering UAE commercial channels. Manufacturers must retrofit labeling systems and reformulate legacy SKUs to maintain shelf placement. Professional salon channels face the steepest compliance burden given their higher product turnover and bundled service complexity.
Subscription-based replenishment is displacing mall-dependent repurchase patterns among UAE consumers with established brand preferences. Direct-to-consumer platforms capture recurring revenue through auto-ship logistics while bypassing department store margin structures. This shift concentrates in Dubai's expatriate professional segments, where time scarcity and digital payment penetration accelerate adoption beyond traditional retail discovery cycles.
United Arab Emirates Cosmetic Products Market Segmentation
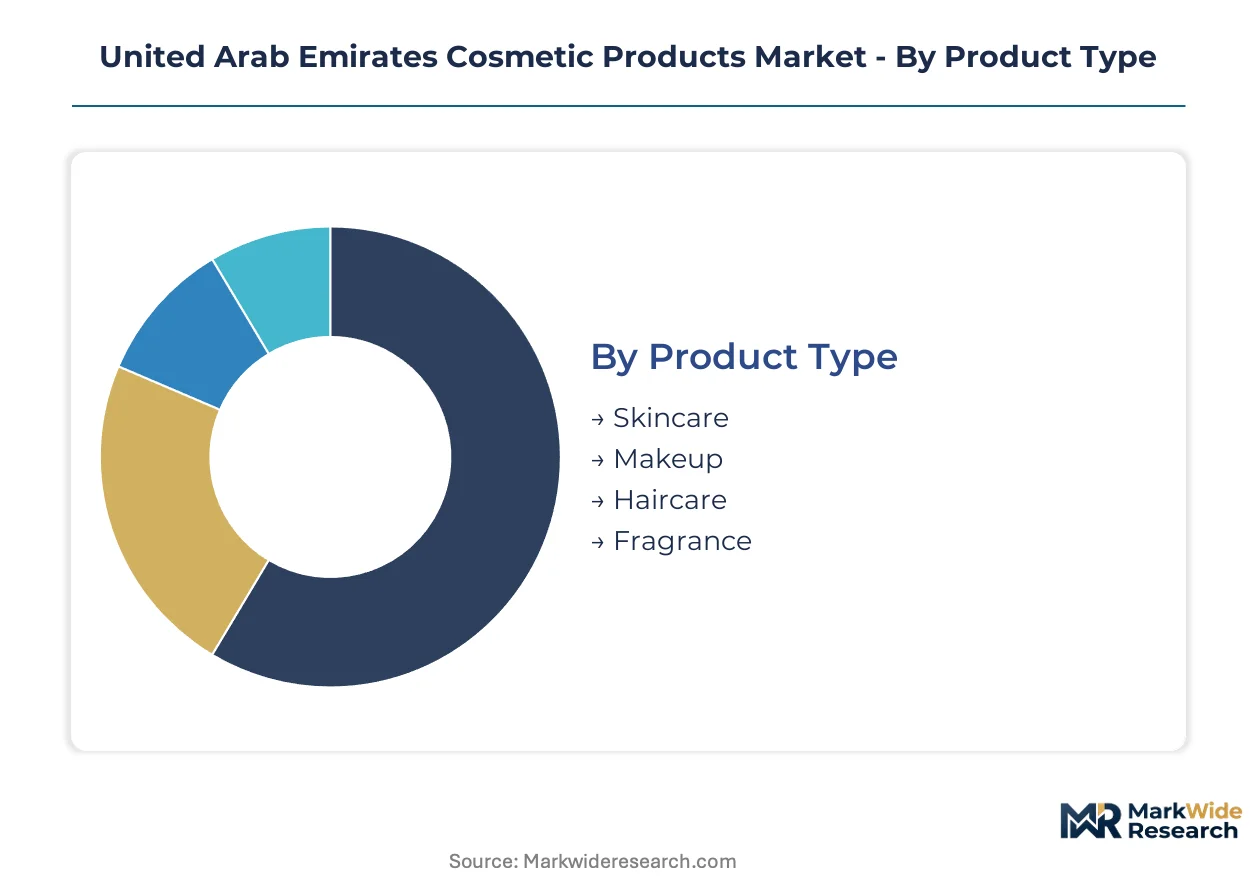
Segmentation reveals how Dubai Mall flagship positioning, MOHAP registration tiers, and halal certification pathways create divergent commercialization economics across UAE cosmetic channels. Distinct buyer profiles and distribution infrastructures reward tailored formulation and channel strategies.
Product Type:
Formulation complexity concentrates in segments requiring climate-adapted chemistry and preservative stability under Gulf humidity conditions.
- Skincare:Emulsion-based preparations with SPF protection and anti-aging actives dominate formulation R&D investment. Demand clusters in Dubai's professional dermatology clinics and medical spa channels where clinical credibility commands price premiums.
- Fragrance:Alcohol-based and oil-concentrated compositions tailored to Middle Eastern olfactory preferences occupy disproportionate retail shelf space. Abu Dhabi and Dubai department stores allocate premium real estate to oud-infused and attar-inspired collections reflecting cultural gift-purchase behavior.
- Makeup:Pigment-stable formulations designed for extended wear in high-temperature, high-humidity environments.
- Haircare:Keratin-focused and scalp-nourishing products addressing hard water mineral deposits and UV-induced damage.
Today's leader: Skincare. Tomorrow's challenger: Fragrance.
End User:
Customer acquisition costs vary sharply across demographic targeting precision and professional channel integration depth.
- Professional:Salon, spa, and clinic practitioners purchasing bulk formulations for service-integrated application. Yas Island and Saadiyat Island medical spa developments are expanding addressable volume for clinical-grade positioning.
- Gender-specific:Segmented marketing targeting male grooming expansion and traditional female beauty routines. Male-focused SKUs are gaining shelf priority in Dubai's online retail channels as subscription logistics mature.
- Age-specific:Generational targeting spanning Gen Z digital-native discovery and anti-aging demand among affluent expatriate professionals.
- General Consumer:Mass-market positioning through supermarket and hypermarket distribution with lower registration burden.
Professional channels capture margin. Gender-specific targeting captures volume expansion.
Distribution Channel:
Channel economics reflect MOHAP traceability requirements and last-mile infrastructure maturity across emirate-level logistics networks.
- Online Retail:Same-day delivery platforms leveraging Abu Dhabi and Dubai fulfillment centers. Auto-ship subscription models are displacing mall-dependent repurchase cycles among time-constrained expatriate professionals.
- Department Stores:Flagship positioning at Dubai Mall and Mall of the Emirates determines brand visibility. Occupancy costs filter mid-tier competitors and concentrate premium brand presence.
- Specialty Stores:Sephora and regional beauty chains offering curated discovery environments.
- Supermarkets:Mass-market access with lower compliance burden and faster inventory turnover.
Department Stores anchor brand equity. Online Retail expands fastest.
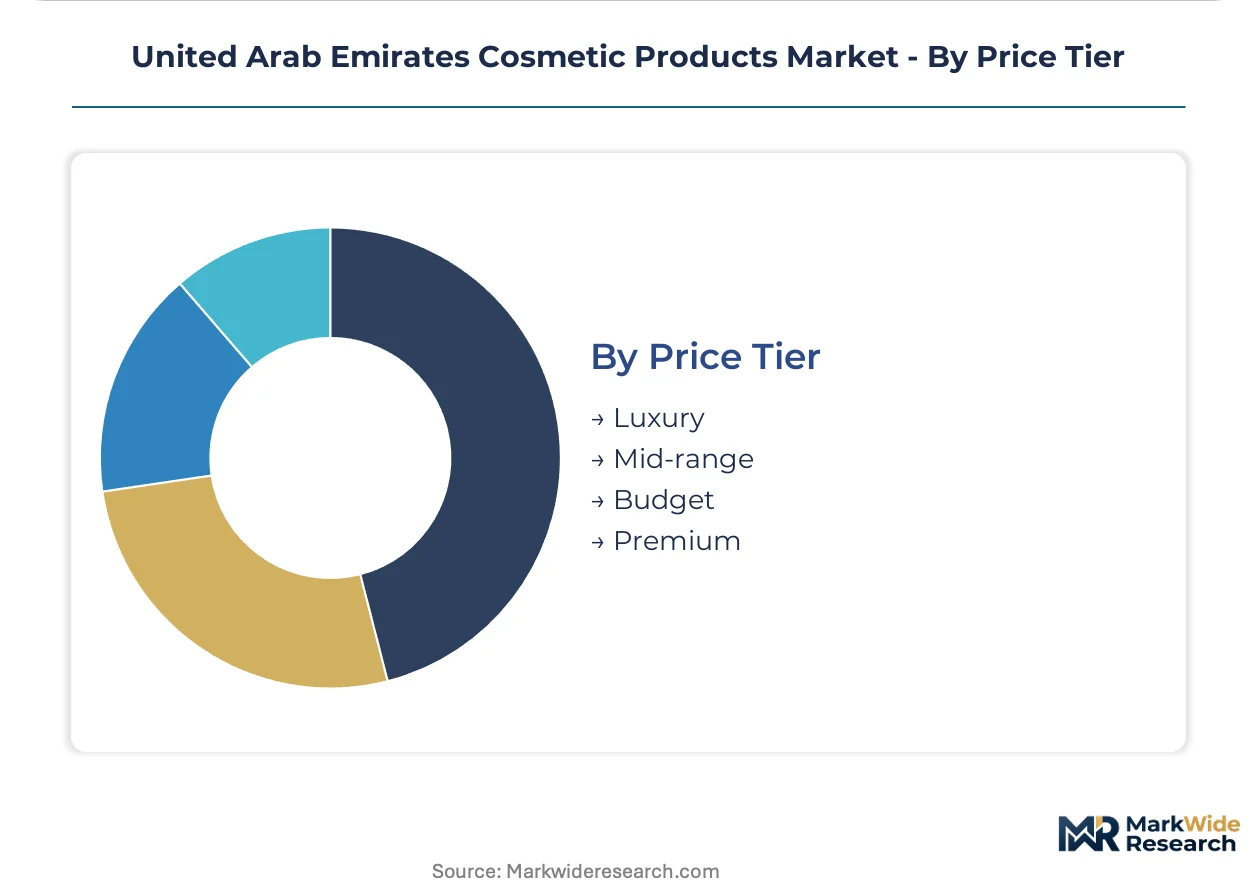
Price Tier:
Pricing stratification aligns with halal certification investment, ingredient sourcing geography, and channel margin structures.
- Luxury:Exclusive oud-based fragrances and clinical-grade skincare with full supply chain documentation. Dubai's high-net-worth expatriate segments and Emirati consumers sustain volume despite premium positioning.
- Premium:Science-backed formulations with halal certification and MOHAP registration transparency. Medical spa partnerships and professional channel bundling support margin defense.
- Mid-range:Accessible quality positioning through specialty retail and emerging online platforms.
- Budget:Price-competitive essentials distributed through supermarket chains with streamlined registration pathways.
Luxury commands margin. Premium scales fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia and the UAE operate divergent cosmetic retail architectures despite shared GCC harmonization protocols. Where Dubai concentrates flagship visibility in mega-mall corridors, Riyadh distributes volume across fragmented retail estates and emerging e-commerce platforms.
Saudi Arabia
Domestic formulation demand is accelerating as the Public Investment Fund backs local manufacturing capacity in the industrial cities of Dammam and Jubail. The Saudi Food and Drug Authority enforces cosmetic registration timelines that currently lag UAE MOHAP processing by four to six months. Jeddah's Red Sea coastal corridor hosts the kingdom's densest cluster of professional salon and medical spa channels.
Qatar
High-net-worth consumption density in Doha sustains disproportionate per-capita spending on luxury fragrance and clinical-grade skincare. The Ministry of Public Health maintains ingredient disclosure standards aligned with UAE MOHAP protocols, easing cross-border product registration. Lusail City's retail development is attracting Dubai-based salon chains seeking expansion beyond saturated Emirates markets.
Kuwait
Traditional souk-based fragrance retail persists alongside modern department store consolidation in Kuwait City. The Public Authority for Industry administers halal certification requirements that diverge slightly from Emirates Authority for Standardization and Metrology benchmarks. The Shuwaikh industrial zone hosts the Gulf's oldest concentration of contract cosmetic manufacturers serving regional brands.
Oman
Underpenetrated professional salon infrastructure is creating first-mover opportunities for UAE-based service brands. The Ministry of Commerce, Industry and Investment Promotion operates simplified import licensing for GCC-registered products. Muscat's Al Seeb and Al Khoud corridors are seeing initial clustering of medical aesthetic clinics previously concentrated in Dubai.
Bahrain
Compact geography enables same-day distribution coverage that supports online retail experimentation at lower logistics cost than larger markets. The National Health Regulatory Authority maintains cosmetic safety assessment protocols modeled on UAE frameworks. Manama's Seef and Juffair districts concentrate the island's professional beauty service capacity and high-income residential catchments.
United Arab Emirates Cosmetic Products Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with international houses dominating premium retail while regional formulators capture professional channel volume. Market structure tilts toward consolidation at the luxury tier and fragmentation in mid-range positioning. Three archetypes define competitive positioning: founder-driven digital-native brands, multinational innovation labs with localized R&D, and Gulf-based contract manufacturers serving private label demand. Geographic expansion through medical spa partnerships and backward integration into halal-certified ingredient sourcing represent the dominant competitive moves.
Within the founder-driven digital-native tier, Huda Beauty LLC anchors regional brand equity through direct consumer engagement. L'Oréal S.A. and Shiseido Company, Limited occupy positions exemplifying multinational scale with localized innovation infrastructure. These three entities represent divergent pathways to market access: organic audience building, dedicated Gulf R&D facilities, and climate-adapted formulation expertise respectively.
| Leading Market Players |
|---|
| Huda Beauty LLC |
| Scion International LLC |
| The Estée Lauder Companies |
| Softcare Cosmetics |
| Beauty Leaders LLC |
| L'Oréal S.A. |
| Shiseido Company, Limited |
| Rūt Essentials |
| LVMH Moët Hennessy Louis Vuitton |
| Others |
Value Network & Pricing Analysis
Luxury-clinical tier bifurcation against mass-market positioning creates divergent margin architectures across UAE cosmetic channels, with halal certification investment and Dubai flagship real estate costs embedding supply-side premiums into price floors while supermarket distribution strips out documentation overhead to compete on accessibility.
Pricing Analysis
Capacity additions in Southeast Asian halal-certified manufacturing hubs are reshaping price floors for mid-range skincare formulations entering UAE channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth, with Emirates Authority for Standardization and Metrology compliance tiers and MOHAP registration transparency driving price differentiation. Pricing pressure stems from same-day delivery logistics cost absorption as online retail channels compete for expatriate professional repurchase cycles. Mass-market supermarket buyers exhibit highest price sensitivity, while medical spa channel purchasers prioritize clinical credibility over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from UAE formulators mandate qualified supplier pools across European active ingredient specialists and Southeast Asian halal-certified chemical manufacturers. Specialty emulsifiers and fragrance compounds draw from France, Germany, and Indonesia, with preservative systems anchored in Swiss and Japanese technical suppliers. Single-source vulnerability concentrates in climate-adapted formulation chemistry expertise, where European talent scarcity exposes manufacturers to competitive relocation cost inflation. Distribution runs through Dubai Jebel Ali port consolidation followed by emirate-level cold-chain logistics to Abu Dhabi and northern emirate retail corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UAE cosmetic products function as a stable compounder anchored by irreversible regulatory tightening that permanently elevates compliance investment floors and filters marginal competitors from commercial channels.
For Market Incumbents: Anchor flagship positioning at Dubai Mall and Mall of the Emirates through lease renewal priority negotiations, as mid-tier competitor filtration from premium real estate creates defensive moats. Deepen backward integration into halal-certified ingredient sourcing to offset European supply chain freight volatility and compress registration timeline exposure. Medical spa partnership density offers patient trust transfer that reinforces clinical-grade pricing power against digital-native challenger brands.
For New Entrants and Emerging Players: Abu Dhabi-based expatriate professionals on Yas Island and Saadiyat Island represent an underserved buyer archetype with established brand preferences but limited flagship retail access. Subscription-based auto-ship logistics targeting time-constrained segments bypasses department store margin structures and captures recurring revenue without real estate overhead. AI-driven skin diagnostic tool integration offers point-of-service credibility compression that accelerates consultation-to-purchase cycles previously locked to counter-based sampling.
For Investors and Strategic Acquirers: Consolidation pressure builds where MOHAP registration expertise and halal certification infrastructure create scale advantages that sub-scale regional formulators cannot replicate. Acquisition targets with captive Gulf distribution relationships and clinical-grade SKU portfolios offer defensive positioning through professional channel bundling. Watch medical spa chain expansion velocity across Oman and Bahrain as inflection indicator for regional service-integrated product demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Infrastructure Investment | Emirates Authority for Standardization and Metrology alignment opens premium Muslim consumer positioning and GCC cross-border access. |
| Medical Spa Channel Partnership | Yas Island and Saadiyat Island clinic density transfers patient trust to clinical-grade cosmetic positioning. |
| AI-Driven Personalization Platform | Skin diagnostic hardware compresses consultation-to-purchase cycles and captures subscription recurring revenue. |
| Same-Day Delivery Logistics Buildout | Abu Dhabi and Dubai fulfillment center maturity enables online retail channel expansion beyond mall-dependent discovery. |
| Backward Integration into Active Sourcing | Southeast Asian halal-certified chemical supplier relationships reduce European freight cost volatility exposure. |
Research Methodology
Bottom-up professional channel and consumer segment modeling reconciled against top-down import volume and registration tracking forms the analytical core of this study. Primary interviews with MOHAP regulatory affairs specialists, Dubai Mall retail leasing directors, medical spa procurement managers, and halal certification consultants combined with secondary validation from Emirates Authority for Standardization and Metrology disclosure filings, MOHAP registration databases, GCC customs trade records, and Abu Dhabi Department of Economic Development retail corridor development plans. Triangulation across these sources ensures segmentation integrity.
Historical trendline analysis of product registration volumes, channel shift patterns, and price tier evolution informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, end user archetype, distribution channel, and price tier, with additional granularity on halal certification status and climate-adapted formulation complexity. CAGRs derive from regression-adjusted trend extrapolation incorporating regulatory timeline assumptions and logistics infrastructure maturity curves specific to UAE emirate-level distribution networks.
Underlying measurement precision varies by segment; online retail channel data carries tighter precision than professional salon estimates due to fulfillment center disclosure requirements. Forecasts reflect assumptions on MOHAP registration processing efficiency, GCC harmonization protocol adoption velocity, and medical spa development pipeline execution. Deviation in halal certification timeline acceleration or European active ingredient supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
China Skincare Market
Cosmetics & Skincare
K-Beauty Products Market
Cosmetics & Skincare
E Commerce Cosmetic and Fragrance Market
Cosmetics & Skincare
Lip Products Pigment Market
Cosmetics & Skincare
Israel Cosmetics Market
Cosmetics & Skincare
Cosmetics Private Label and Contract Manufacturing Market
Cosmetics & Skincare
Makeup Setting Powder Market
Cosmetics & Skincare
Lip Oil Market
Cosmetics & Skincare
Myanmar Skin Care Products Market
Cosmetics & Skincare
UK Lip Care Products Market
Cosmetics & Skincare
Anti-Fatigue Cosmetics Market
Cosmetics & Skincare
Private Label Cosmetics Manufacturing Service Market
Cosmetics & Skincare
UK Eyelash Serum Market
Cosmetics & Skincare
Setting Spray Market
Cosmetics & Skincare
Global Cosmetic Jar Market
Cosmetics & Skincare
Russia Lip Care Products Market