
 Malaysia Skin Care Products Market | 2026-2036
Malaysia Skin Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Skin Care Products Market Insights
Malaysia is narrowing its import dependence on finished skin care goods through expanding domestic manufacturing zones in Selangor and Johor. L'Oréal Group leverages integrated production facilities near Kuala Lumpur to supply Southeast Asian markets with reduced lead times. Beiersdorf AG anchors its regional distribution strategy from Penang-based logistics hubs serving pharmacy and modern trade channels. Skintific competes aggressively on price-performance positioning in the mass serum category through localized formulation labs.
Skin care products encompass topical formulations designed to cleanse, protect, or improve skin condition, typically incorporating active ingredients such as niacinamide, hyaluronic acid, or zinc oxide at specified concentrations for photoprotection or barrier repair. These products serve commercial purposes across daily consumer regimens, clinical dermatology support, and preventive health maintenance against tropical ultraviolet exposure. Moisturizers and sunscreens occupy the largest revenue pools given Malaysia's equatorial climate and year-round humidity that drive consistent replenishment cycles. Serums within the botanical ingredient source segment represent the fastest-expanding margin category as consumers shift toward plant-derived actives with traceable supply chains. The online distribution channel is displacing traditional supermarket placements for trial-sized and subscription-based skin care formats among digital-native demographics.
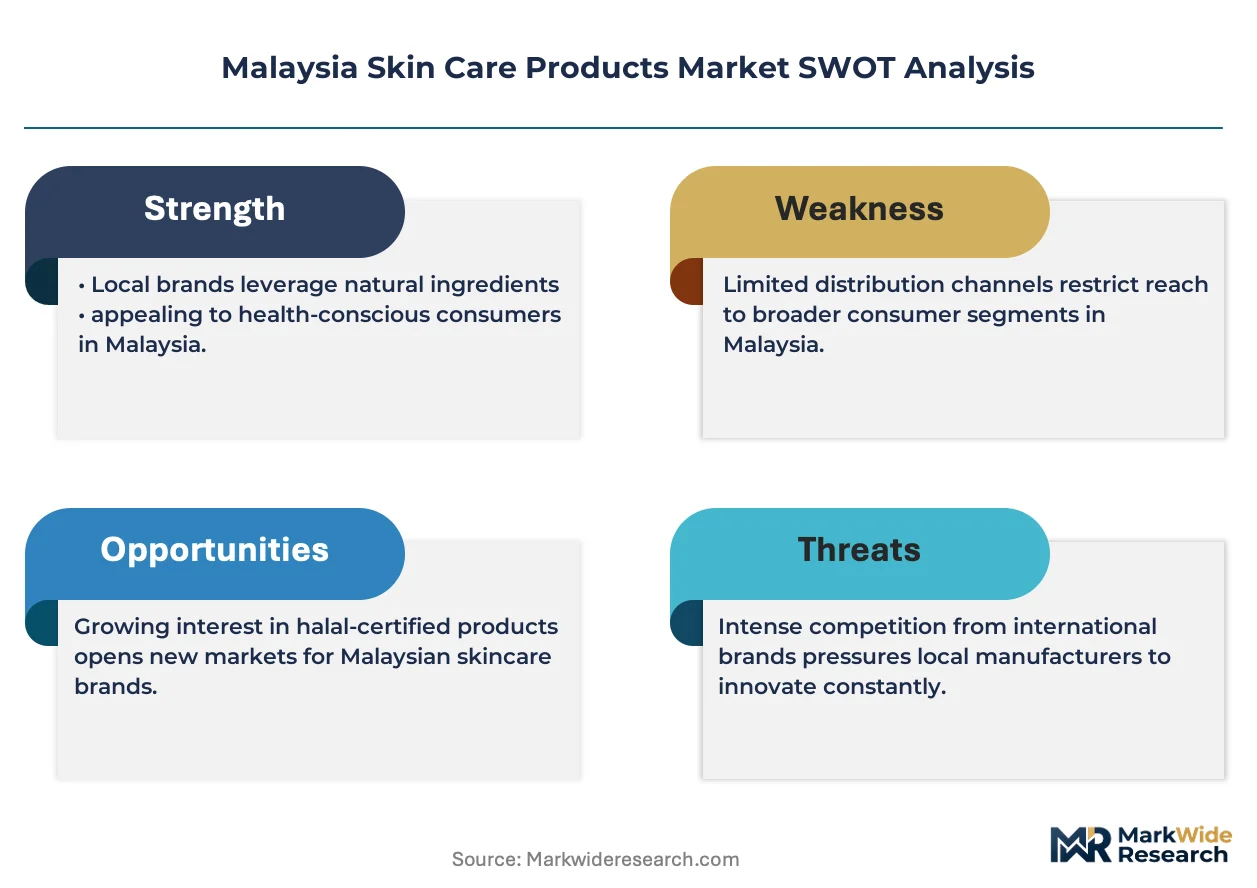
NPRA halal compliance requirements, ASEAN Cosmetics Directive alignment, and Ministry of Health Good Manufacturing Practice standards collectively determine market access thresholds and ingredient permissibility for all commercial skin care offerings in Malaysia. These frameworks elevate compliance costs for synthetic preservative formulations while creating preferential pathways for botanical and naturally sourced product registrations. Stakeholders must monitor evolving halal certification scope expansions into upstream raw material sourcing to anticipate reformulation mandates and supply chain restructuring requirements.
Market Dynamics
NPRA halal certification expansion into upstream raw material sourcing is forcing domestic manufacturers to restructure supply chains around traceable botanical inputs, compressing formulation timelines while elevating compliance costs for synthetic-dependent portfolios.
Growth Catalysts
- ASEAN Cosmetics Directive alignment:Harmonized ingredient standards accelerate cross-border product registrations between Malaysia and neighboring markets, reducing duplicate testing burdens for regional exporters.
- Klang Valley e-commerce density:Concentrated digital-native consumer clusters in Kuala Lumpur and Selangor drive rapid adoption of subscription-based skin care replenishment models.
- Equatorial photoprotection necessity:Year-round tropical ultraviolet exposure sustains baseline demand for zinc oxide and niacinamide formulations across all demographic segments.
Market Restraints
- Halal certification timeline friction:NPRA's extended raw material verification protocols delay product launches by 8-14 months versus conventional synthetic formulations.
- Specialty ingredient import dependence:Concentrated sourcing of botanical actives from Indonesian and Thai agricultural zones exposes margins to climate-driven supply volatility.
- Preservative substitution limitations:Technical gaps in natural antimicrobial efficacy restrict water-based serum shelf life compared to paraben-stabilized alternatives.
Strategic Opportunities
- Johor manufacturing zone expansion:Underutilized production capacity in southern Malaysia offers tariff-advantaged export positioning into Singapore and Indonesian markets.
- Penang pharmacy channel consolidation:Modern trade integration of dermatology-adjacent skin care creates white space for clinical-positioned brands in northern corridor retail.
- PLI scheme adaptation:Malaysia's investment tax incentives for domestic manufacturing favor capital deployment into localized formulation laboratories and halal-certified packaging facilities.
Industry Challenges
- Halal chemist talent scarcity:Limited pool of formulation scientists trained in both cosmetic chemistry and Islamic compliance standards constrains R&D throughput for mid-tier manufacturers.
- Legacy ERP integration:Batch-level traceability requirements for NPRA audits demand supply chain software upgrades that smaller domestic producers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Skin Care Products Market |
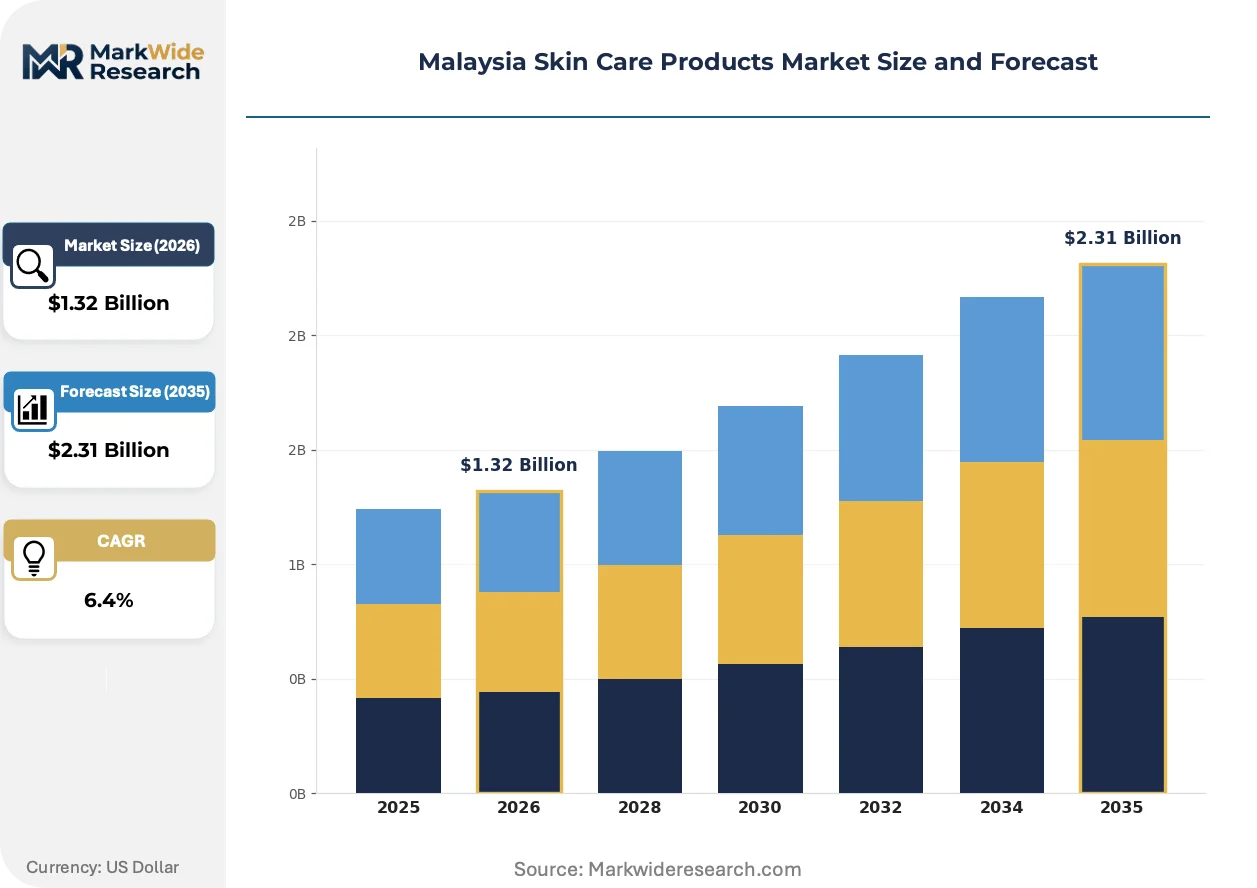
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Cleansers, Sunscreens, Serums Ingredient Source: Natural, Synthetic, Organic, Botanical Target Demographic: Men, Women, Teenagers, Seniors Distribution Channel: Online, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | L'Oréal Group, Procter & Gamble Company, Unilever PLC, Beiersdorf AG, Berjaya Corporation Berhad, Estee Lauder Companies Inc., Shiseido Company Limited, Bio-essence, Skintific, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Skin Care Products Market Trends and Innovations
Formulation science in Malaysia is pivoting toward plant-derived actives with verified halal supply chains, while distribution infrastructure compresses toward direct-to-consumer models that bypass traditional pharmacy counter relationships.
Biotechnology-derived fermentation processes for hyaluronic acid production are migrating from pharmaceutical-grade suppliers to cosmetic-grade manufacturers in Selangor. Domestic brands with localized labs now adopt these inputs at 15-20% cost premiums versus imported alternatives. This migration from synthetic polymer sources to bio-fermented equivalents is compressing price gaps between mass and premium serum tiers.
NPRA's 2024 expansion of halal certification scope into upstream botanical harvesting creates compliance cascades for ingredient importers. The regulation mandates third-party auditing of farming cooperatives in Indonesia and Thailand supplying Malaysian formulators. Small-batch serum producers in Penang face the steepest adaptation costs as they lack procurement scale to absorb audit fees.
Subscription-based replenishment cycles are displacing supermarket impulse purchases among urban millennials in Kuala Lumpur. Digital-native brands capture trial conversions through algorithmic skin assessment tools, then lock recurring revenue via auto-ship programs. This behavioral shift concentrates customer lifetime value in e-commerce channels while eroding traditional modern trade margins.
Malaysia Skin Care Products Market Segmentation
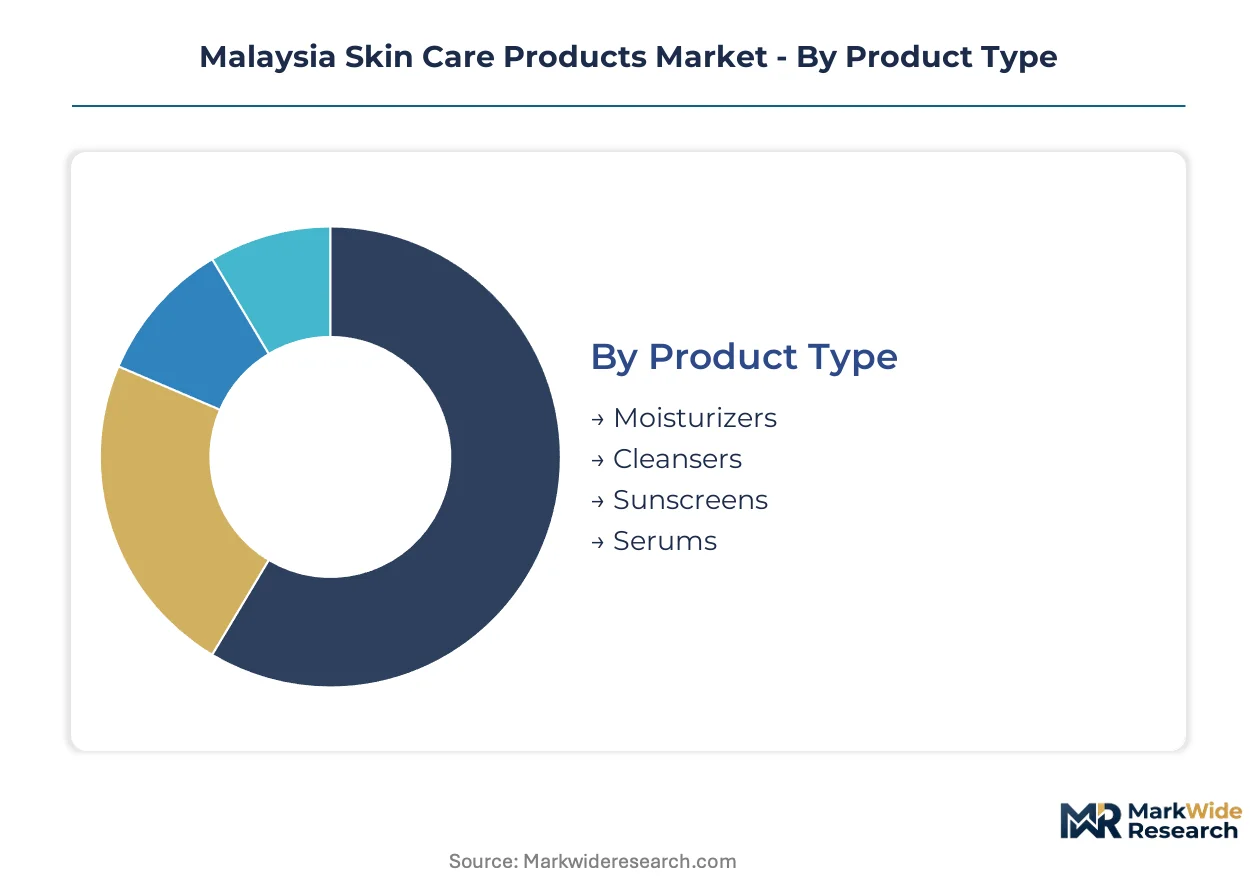
Malaysia's skin care market segments reflect equatorial climate demands and halal compliance requirements that reshape formulation priorities. NPRA certification standards create distinct competitive dynamics across product categories and distribution channels.
Product Type:
Mature categories dominate replenishment cycles while emerging formats capture premium positioning.
- Moisturizers:Water-in-oil emulsions and gel-cream hybrids formulated for tropical humidity sustain baseline volume across mass and prestige tiers. Klang Valley consumers replenish facial moisturizers on 45-60 day cycles driven by year-round perspiration and air-conditioned indoor exposure.
- Sunscreens:Zinc oxide and niacinamide-based mineral formulations command premium shelf space in pharmacy channels, with SPF 50+ PA++++ ratings now standard for urban millennials. NPRA's photoprotection labeling requirements elevate compliance costs for imported chemical filter alternatives.
- Cleansers:Micellar water and low-pH foam formulations address post-sun exposure recovery needs in humid climates.
- Serums:Concentrated active delivery systems in 30ml formats target specific concerns including hyperpigmentation and barrier repair.
Moisturizers handle the majority of throughput; serums are climbing the fastest on margin contribution.
Ingredient Source:
Cost tiers stratify sharply between certified halal botanicals and conventional synthetic alternatives.
- Botanical:Plant-derived actives with traceable Indonesian and Thai agricultural sourcing command 25-40% price premiums in serum and mask categories. NPRA's expanded upstream auditing requirements favor established suppliers with cooperative certification infrastructure.
- Synthetic:Petrochemical-derived emollients and preservatives face formulation restrictions under halal compliance protocols, compressing addressable market share in mass-tier moisturizers and cleansers.
- Natural:Unprocessed mineral and plant extracts without synthetic modification occupy mid-tier positioning between botanical premium and synthetic economy.
- Organic:Certified pesticide-free agricultural inputs with third-party verification attract niche premium positioning in Penang and Kuala Lumpur specialty retail.
Botanical inputs dominate new product launches; synthetic alternatives are losing share fastest to halal-compliant substitutes.
Target Demographic:
Customer type concentration varies dramatically by channel and price positioning.
- Women:Primary decision-makers across all product categories with established multi-step routines driving 70%+ of category expenditure in pharmacies and specialty stores.
- Men:Simplified two-step cleanser-moisturizer regimens expanding fastest through e-commerce trial formats and subscription boxes targeting Selangor professionals.
- Teenagers:Acne-focused formulations with social media-driven discovery patterns concentrating in online and supermarket impulse channels.
- Seniors:Barrier repair and age spot correction products with clinical positioning in pharmacy and dermatology-adjacent retail.
Women account for the largest absolute spend; men are expanding most quickly as digital-native brands reduce trial friction.
Distribution Channel:
Volume concentration tilts toward digital infrastructure while margin capture favors specialized physical formats.
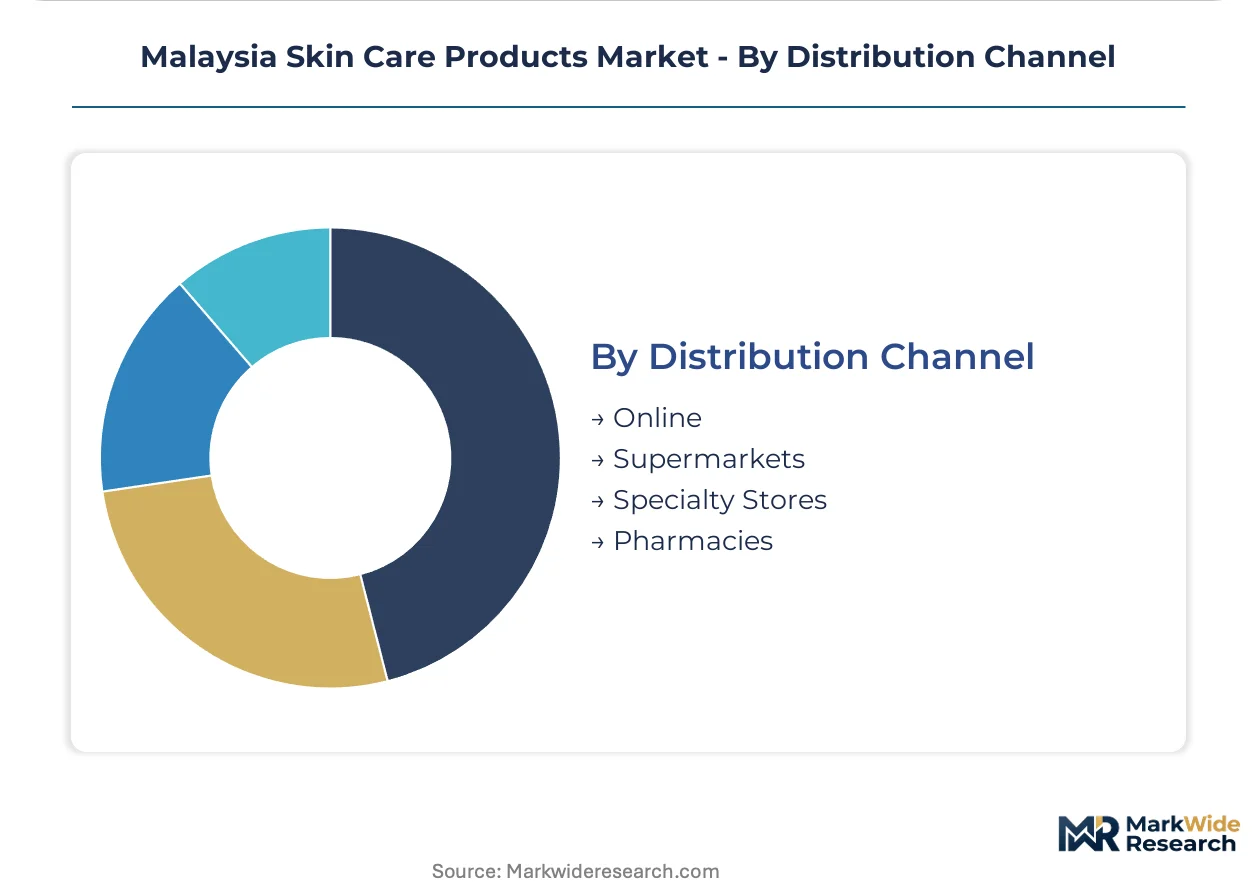
- Online:Algorithmic skin assessment tools and subscription auto-ship programs concentrate customer lifetime value among Kuala Lumpur millennials. Direct-to-consumer brands bypass traditional pharmacy margins while capturing trial-sized conversion data.
- Pharmacies:Clinical-positioned brands with dermatologist endorsement occupy premium shelf space in Guardian and Watsons chains across Penang and Johor.
- Specialty Stores:Experiential retail with in-store skin analysis drives premium serum and sunscreen attachment rates in mid-valley malls.
- Supermarkets:Mass moisturizers and cleansers sustain impulse replenishment in hypermarket formats with compressed margins and high inventory velocity.
Online channels capture the steepest growth trajectory; supermarkets retain the highest absolute transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NPRA's halal certification protocols anchor Malaysia's regulatory environment, creating compliance cascades that reshape sourcing patterns across Southeast Asian supply chains and elevate traceability requirements for botanical inputs.
Selangor
Klang Valley's concentrated e-commerce infrastructure drives subscription-based replenishment adoption among urban millennials. The Ministry of Health's Good Manufacturing Practice standards elevate facility compliance costs for domestic manufacturers. Integrated production zones near Shah Alam supply Southeast Asian markets with compressed lead times.
Penang
Pharmacy channel consolidation in George Town and Bayan Lepas creates white space for clinical-positioned brands. NPRA's expanded upstream auditing requirements favor established suppliers with cooperative certification infrastructure. Logistics hubs serving northern corridor retail anchor regional distribution strategies.
Johor
Underutilized production capacity in Iskandar Malaysia offers tariff-advantaged export positioning into Singapore. Malaysia's PLI scheme tax incentives favor capital deployment into localized formulation laboratories. Manufacturing zones target cross-border supply into Indonesian markets.
Kuala Lumpur
Specialty retail density in mid-valley malls drives premium serum and sunscreen attachment rates. Algorithmic skin assessment tools concentrate customer lifetime value in direct-to-consumer channels. Experiential retail formats displace traditional pharmacy counter relationships.
Malaysia Skin Care Products Market Competitive Landscape
Multinational conglomerates and domestic specialists split the market between scale-driven mass distribution and agile halal-compliant formulation. The vendor base concentrates around integrated production facilities and localized laboratories. Three archetypes dominate: global beauty conglomerates with regional manufacturing hubs, ASEAN-origin specialists with price-performance positioning, and domestic halal-certified laboratories. Competitive moves center on supply chain restructuring around traceable botanical inputs and e-commerce channel capture through subscription auto-ship programs.
Within the multinational tier, L'Oréal Group and Beiersdorf AG exemplify integrated production strategies with facilities anchored near Kuala Lumpur and Penang logistics hubs. Skintific represents the ASEAN-origin specialist archetype, occupying a position in mass serum categories through localized formulation capabilities. These three companies illustrate the competitive tension between scale-driven manufacturing efficiency and agile compliance adaptation to NPRA's evolving halal certification scope.
| Leading Market Players |
|---|
| L'Oréal Group |
| Procter & Gamble Company |
| Unilever PLC |
| Beiersdorf AG |
| Berjaya Corporation Berhad |
| Estee Lauder Companies Inc. |
| Shiseido Company Limited |
| Bio-essence |
| Skintific |
| Others |
Pricing and Supply Chain Analysis
Port Klang's container freight corridors transmit cost volatility directly into Klang Valley retail pricing, compressing margins for imported synthetic formulations while amplifying premium capture for domestic halal-certified botanical producers that bypass tariff exposure and currency fluctuation.
Pricing Analysis
Price spreads between Penang pharmacy channels and Johor mass retail reach 35-45% for identical SPF 50+ formulations, reflecting tiered pricing stratification across premium clinical positioning, standard modern trade placement, and economy supermarket tiers. Certification grade and brand equity drive differentiation, with NPRA halal verification commanding 20-30% shelf price premiums over conventional alternatives. Pricing pressure stems from Indonesian cross-border e-commerce undercutting domestic distributors on serum categories. Teenage segments exhibit highest price sensitivity through social media comparison shopping, while urban professional women in Kuala Lumpur demonstrate lowest sensitivity for dermatologist-endorsed SKUs.
Supply Chain Analysis
Extended 90-120 day payment terms from Guardian and Watsons chains strain working capital for Penang-based serum producers, forcing supply chain finance facility dependence on regional banking partners. Raw material sourcing concentrates in Indonesia, Thailand, and domestic Selangor agricultural zones for botanical actives, with zinc oxide and niacinamide drawing from specialized chemical suppliers in China and South Korea. Single-source vulnerability pervades certified halal botanical harvesting cooperatives subject to climate-driven crop failure. Distribution runs through pharmacy chain consolidation in northern corridors and direct-to-consumer platforms displacing traditional supermarket impulse channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives against Indonesian direct-to-consumer brands undercutting on price-performance positioning in mass serum segments.
For Market Incumbents: Harden formulation IP through captive supply of bio-fermented hyaluronic acid from Selangor biotechnology facilities, eliminating import cost exposure. Deepen pharmacy channel control via exclusive dermatologist endorsement contracts that lock shelf placement against ASEAN-origin specialists. NPRA compliance timeline extensions threaten synthetic-dependent portfolios; accelerate botanical R&D throughput to compress 8-14 month certification cycles. For New Entrants and Emerging Players: Johor's underpenetrated pharmacy modern trade integration offers white space for clinical-positioned brands targeting cross-border Singaporean and Indonesian demand. Capture subscription auto-ship revenue through algorithmic skin assessment tools that bypass incumbent supermarket relationships. Prioritize halal-certified packaging facility investment to exploit PLI scheme tax incentives before capacity saturation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic halal-certified laboratories with integrated formulation capabilities over multinational manufacturing hubs facing compliance restructuring costs. Long-term viability hinges on traceable botanical supply chain control extending to upstream Indonesian farming cooperative certification. Monitor NPRA scope expansion announcements as inflection indicators for forced portfolio reformulation mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Halal-Certified Packaging Facility Investment | PLI scheme tax incentives reduce capital deployment costs for NPRA-compliant domestic producers. |
| Bio-Fermented Active Ingredient Integration | Selangor biotechnology migration compresses 15-20% cost premiums versus imported pharmaceutical-grade alternatives. |
| Pharmacy Channel Exclusive Partnership | Guardian and Watsons consolidation in Penang creates defensible shelf positioning against cross-border e-commerce undercutting. |
| Subscription Auto-Ship Platform Launch | Algorithmic skin assessment tools capture Kuala Lumpur millennial lifetime value while eroding traditional modern trade margins. |
| Upstream Cooperative Certification Control | Third-party auditing of Indonesian and Thai farming operations secures preferential NPRA registration pathways. |
Research Methodology
Cross-validation between primary interviews with NPRA compliance officers, formulation laboratory directors, and pharmacy chain category buyers anchors the qualitative findings against secondary validation from Ministry of Health GMP facility registrations, NPRA halal certification databases, and customs import records for botanical active ingredients. Bottom-up triangulation across 45-60 day replenishment cycle data from Klang Valley retail audit sources converges with top-down market sizing from domestic manufacturing zone capacity disclosures.
Calibration against historical CAGRs from adjacent ASEAN cosmetics markets refines trajectory assumptions across the projection horizon. Segmentation modeling incorporates product type, ingredient source certification tier, target demographic purchasing behavior, and distribution channel margin structure. Forecast inputs include NPRA regulatory scope expansion timelines, e-commerce penetration rates in Selangor urban clusters, and bio-fermentation technology cost curves from pharmaceutical-grade suppliers.
Practitioners should monitor NPRA upstream auditing mandate implementation pace and Indonesian agricultural cooperative certification completion rates for early signals of supply constraint. Forecasts reflect assumptions regarding sustained equatorial photoprotection demand and halal compliance scope stability. Macroeconomic currency fluctuation, regulatory timeline extension, or biotechnology fermentation cost breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Dark Circles Removing Eye Cream Market
Cosmetics & Skincare
Caffeine Eye Creams Market
Cosmetics & Skincare
Cosmetic Mirror Market
Cosmetics & Skincare
China Skincare Market
Cosmetics & Skincare
Philippines Skin Care Products Market
Cosmetics & Skincare
Asia-Pacific Halal Cosmetics Market
Cosmetics & Skincare
Chile Cosmetics Products Market
Cosmetics & Skincare
Global Facial Cleanser Market
Cosmetics & Skincare
Asia-Pacific Face Compact Market
Cosmetics & Skincare
Organic Bar Soap Market
Cosmetics & Skincare
Cosmetics Private Label and Contract Manufacturing Market
Cosmetics & Skincare
Mushroom Beauty Products Market
Cosmetics & Skincare
Body Blurring Cosmetics Market
Cosmetics & Skincare
Marine Hyaluronic Water Cream Market
Cosmetics & Skincare
Silicone Makeup Sponge Market
Cosmetics & Skincare
Hand Cream Market