
 Retinol Eye Cream Market | 2026-2036
Retinol Eye Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Retinol Eye Cream Market Insights
The gap between clinical-strength retinol eye treatments and mass-market alternatives is realigning how brands allocate R&D budgets and retail partnerships. L'Oréal leverages its dermatological science arm to sustain credibility among consumers seeking proven efficacy claims. Shiseido anchors its positioning in Japanese fermentation-derived retinol technologies that command premium shelf placement in Asian and Western markets. RoC Skincare competes through decades-long specialization in stabilized retinol formulations that reduce irritation risk for sensitive eye areas.
Retinol eye cream is a topical cosmetic formulation containing vitamin A derivatives, typically at concentrations between 0.01% and 1.0%, designed to accelerate cellular turnover and stimulate collagen production in the periorbital skin. The product category serves both cosmetic improvement of fine lines and dark circles and dermatologist-supervised treatment of photoaging damage. Moisturizers and serums capture divergent margin structures, with serum formats supporting higher unit economics through concentrated active delivery systems. The anti-aging application segment leads volume while brightening claims are gaining traction among younger demographics seeking preventive rather than corrective solutions. Online retail channels are reshaping competitive dynamics by enabling direct-to-consumer brands to bypass traditional pharmacy and specialty store gatekeepers.
The US FDA oversees retinol concentration claims and cosmetic-drug boundary classifications that determine whether products require pre-market approval or fall under cosmetic labeling rules. The EU Cosmetics Regulation and REACH framework govern ingredient safety assessments and nanomaterial disclosures that affect retinol encapsulation technologies. China's NMPA and GB standards impose additional registration requirements for imported retinol products that influence which formulations multinationals introduce to that market. Stakeholders must monitor evolving regulatory distinctions between cosmetic and quasi-drug status across jurisdictions, as these classifications determine permissible marketing claims and distribution channel access.
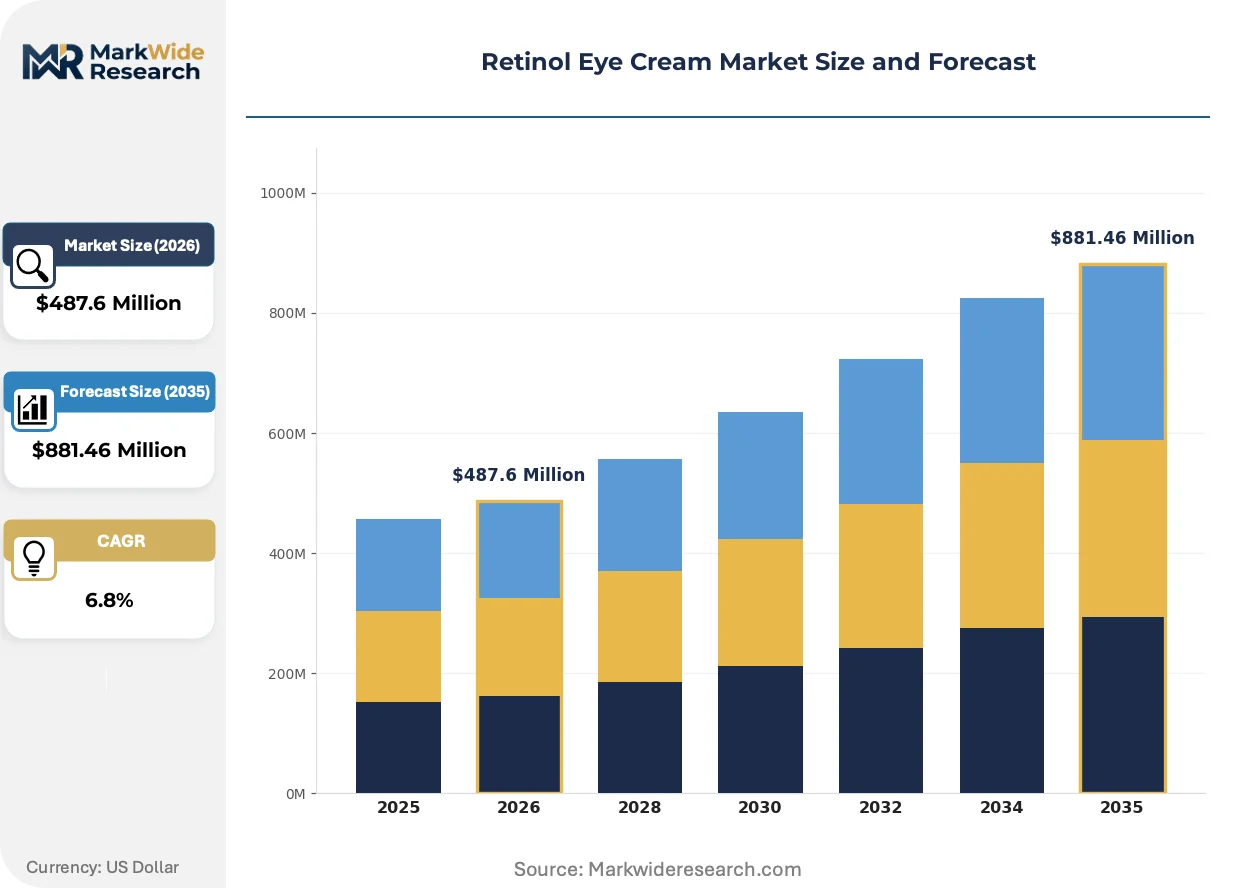
Market Dynamics
Dermatology clinics are professionalizing retinol eye care protocols, creating a bifurcation between clinical-grade dispensing and mass retail that reshapes brand positioning, channel strategy, and pricing architecture across the category.
Growth Catalysts
- Preventive aging demand:Millennial and Gen Z consumers in the United States are adopting retinol eye creams earlier in their skincare routines, expanding the addressable user base beyond traditional corrective aging demographics.
- EU Cosmetics Regulation:Tightened ingredient disclosure rules under this framework are elevating formulation transparency standards, rewarding brands with documented stability data and clean-label credentials.
- Encapsulation technologies:Liposome and polymer-based delivery systems are improving retinol bioavailability while reducing periorbital irritation, enabling higher concentration products for sensitive skin segments.
Market Restraints
- Raw material concentration limits:Regulatory caps on retinol percentages in cosmetic formulations restrict potency claims and create ceiling effects on clinical efficacy positioning.
- Supply chain concentration:Bulk retinol production clusters in China and India, exposing brands to export licensing delays and geopolitical friction affecting active ingredient availability.
- Photodegradation instability:Retinol's molecular sensitivity to light and oxygen necessitates costly stabilization packaging and cold-chain considerations that compress margins.
Strategic Opportunities
- Men's grooming expansion:Underpenetrated male skincare segments in Germany and the United Kingdom present whitespace for gender-neutral retinol eye formulations with simplified messaging.
- Subscription direct-to-consumer models:Replenishment-based ecommerce platforms bypass pharmacy gatekeepers and capture lifetime value through personalized regimen programming.
- Biotechnology convergence:Pairing retinol with microbiome-supporting postbiotics is unifying two active categories into next-generation eye treatments with differentiated positioning.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in retinol stabilization and periorbital tolerability testing commands premium compensation and extends product development timelines.
- Cosmetic-drug boundary navigation:Brands face compliance complexity when efficacy claims approach therapeutic thresholds, requiring legal review across FDA, EMA, and NMPA jurisdictions.
- Clinical substantiation costs:Instrumental measurement of periorbital wrinkle reduction demands expensive panel studies and dermatologist oversight that strain R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retinol Eye Cream Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Gels, Serums, Treatments Application: Anti-Aging, Hydration, Brightening, Dark Circles Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets End User: Women, Men, Professionals, Students |
| Companies Covered | L'Oréal, Shiseido, Procter & Gamble, Paula's Choice, RoC Skincare, Dr. Dennis Gross Skincare, Johnson & Johnson, Pierre Fabre, Kate Somerville, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retinol Eye Cream Market Trends and Innovations
Encapsulation science and biotech-derived alternatives are compressing the traditional trade-off between retinol potency and tolerability, enabling brands to serve irritation-prone consumers without sacrificing efficacy claims.
Microencapsulated retinol using time-release polymer matrices is unifying sustained active delivery with barrier-friendly application, allowing dermatology clinics to recommend higher concentrations for sensitive eye areas previously excluded from retinoid therapy. Prestige and masstige brands are accelerating adoption of this technology to bridge the clinical-mass market divide. The structural consequence is collapsing the historical segmentation between professional-only and over-the-counter retinol eye treatments.
REACH framework updates governing nanomaterial classifications are forcing reformulation of liposomal retinol carriers used in premium eye creams, with ECHA safety assessments extending registration timelines for encapsulated active products. Manufacturers are responding by diversifying delivery technologies toward non-nano alternatives. EU-registered brands face the most significant compliance burden, with some withdrawing complex encapsulation claims pending regulatory clarity.
Subscription-based replenishment programs are displacing traditional pharmacy and department store replenishment cycles, with direct-to-consumer brands capturing repeat purchase loyalty through algorithmic regimen personalization. This channel shift concentrates customer data ownership with emerging players rather than legacy retailers. The United States exhibits the most advanced adoption of this model, though United Kingdom and Australian markets are replicating the infrastructure.
Retinol Eye Cream Market Segmentation
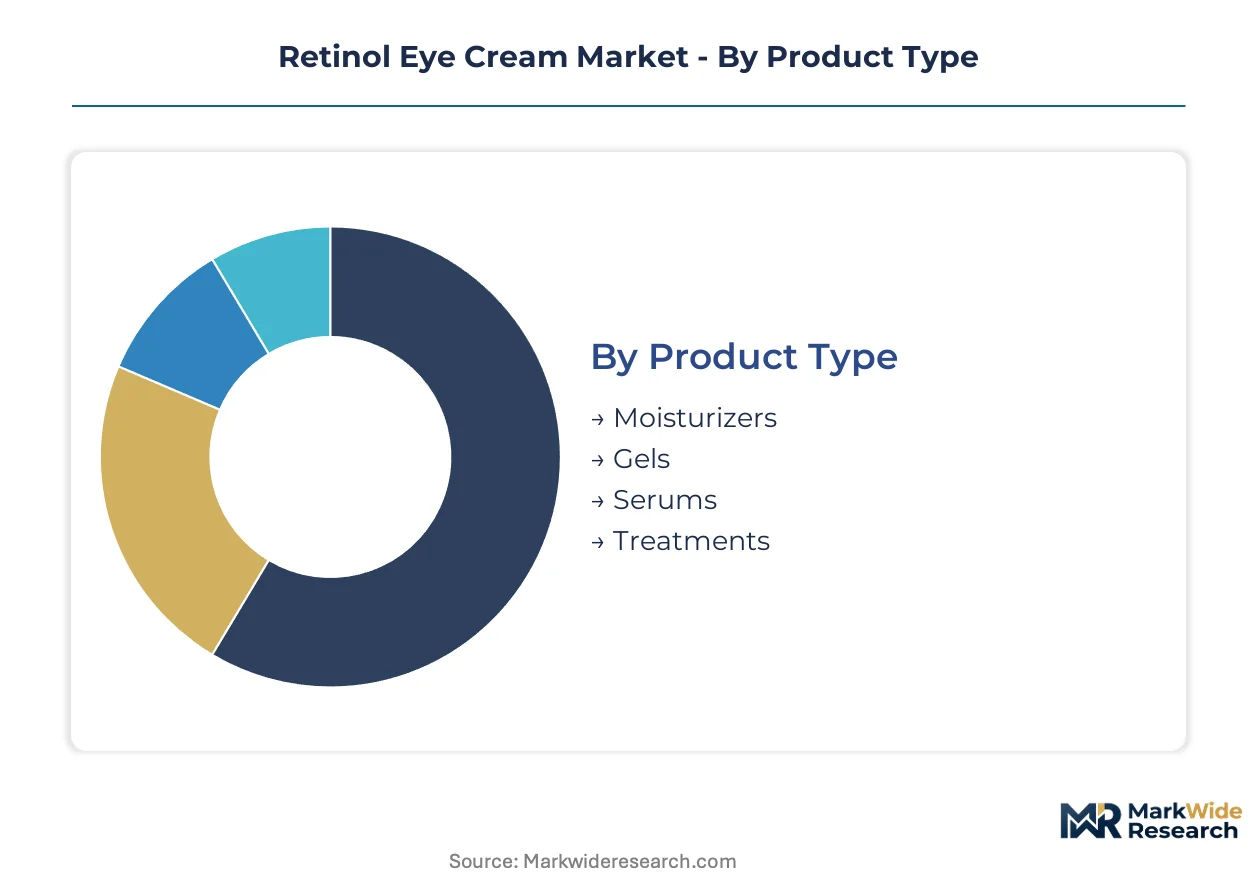
Retinol eye cream segmentation reveals how formulation chemistry, retail channel economics, and user demographics intersect to determine margin capture and brand positioning strategies across the category.
Product Type:
Supply concentration in encapsulated active manufacturing favors formats that can absorb premium stabilization costs without destroying unit economics.
- Moisturizers:Cream-based vehicles combining retinol with occlusive emollients at 0.01% to 0.3% concentrations. Demand clusters in United States mass retail where consumers prioritize tolerability over potency for daily periorbital use.
- Serums:Lightweight, water-based delivery systems enabling higher retinol loadings up to 1.0% through concentrated active suspensions. United States dermatology clinics and prestige e-commerce channels absorb the bulk of volume as consumers seek visible efficacy timelines.
- Gels:Silicone and water-based formulations targeting oil-prone skin with rapid absorption profiles. Asian markets favor gel textures for humid climate compatibility.
- Treatments:Intensive protocols including peel pads and overnight masks with periodic rather than daily application. Professional dispensing channels in Germany and United Kingdom capture specialized usage occasions.
Moisturizers absorb the bulk of installed manufacturing capacity; serums are expanding most quickly through direct-to-consumer subscription platforms.
Application:
Cost tier stratification separates clinical-grade claims from mass-market positioning, with reimbursement-adjacent indications commanding formulation investment priority.
- Anti-Aging:Collagen stimulation and fine line reduction claims supported by instrumental wrinkle measurement studies. United States millennial and Gen Z consumers are driving preventive adoption earlier in skincare routines than previous cohorts.
- Brightening:Melanin inhibition and periorbital luminosity claims targeting hyperpigmentation and dullness. Asian markets, particularly South Korea and Japan, concentrate demand for tone-evening benefits alongside retinol.
- Hydration:Barrier repair and transepidermal water loss reduction through retinol-plus-ceramide combinations. European consumers prioritize this indication given stricter cosmetic-drug boundaries on structural anti-aging claims.
- Dark Circles:Vascular and pigmentary discoloration targeting through retinol paired with caffeine or vitamin K. Clinical validation challenges restrict this segment to prestige pricing tiers.
Anti-Aging commands the deepest R&D investment pools; Brightening is climbing the fastest as Asian formulation influences penetrate Western markets.
Distribution Channel:
Volume concentration in replenishment-driven purchase patterns is reallocating margin capture from traditional retail gatekeepers to data-integrated platform operators.
- Online Retail:Direct-to-consumer and marketplace platforms enabling algorithmic personalization and subscription replenishment. United States consumers exhibit the highest repurchase loyalty through these channels.
- Specialty Stores:Sephora, Ulta, and department store beauty halls providing tactile trial and staffed consultation. These venues retain importance for first-time retinol adopters seeking guidance on concentration selection.
- Pharmacies:Drugstore and apothecary channels emphasizing dermocosmetic credibility and pharmacist recommendation. German and French markets maintain stronger pharmacy dependency than Anglo-American counterparts.
- Supermarkets:Mass grocery and hypermarket placement for entry-level retinol moisturizers at sub-premium price points. Price compression in this channel limits active concentration and packaging sophistication.
Online Retail is capturing the fastest share expansion; Pharmacies retain the highest customer trust scores for sensitive-eye-area product recommendations.
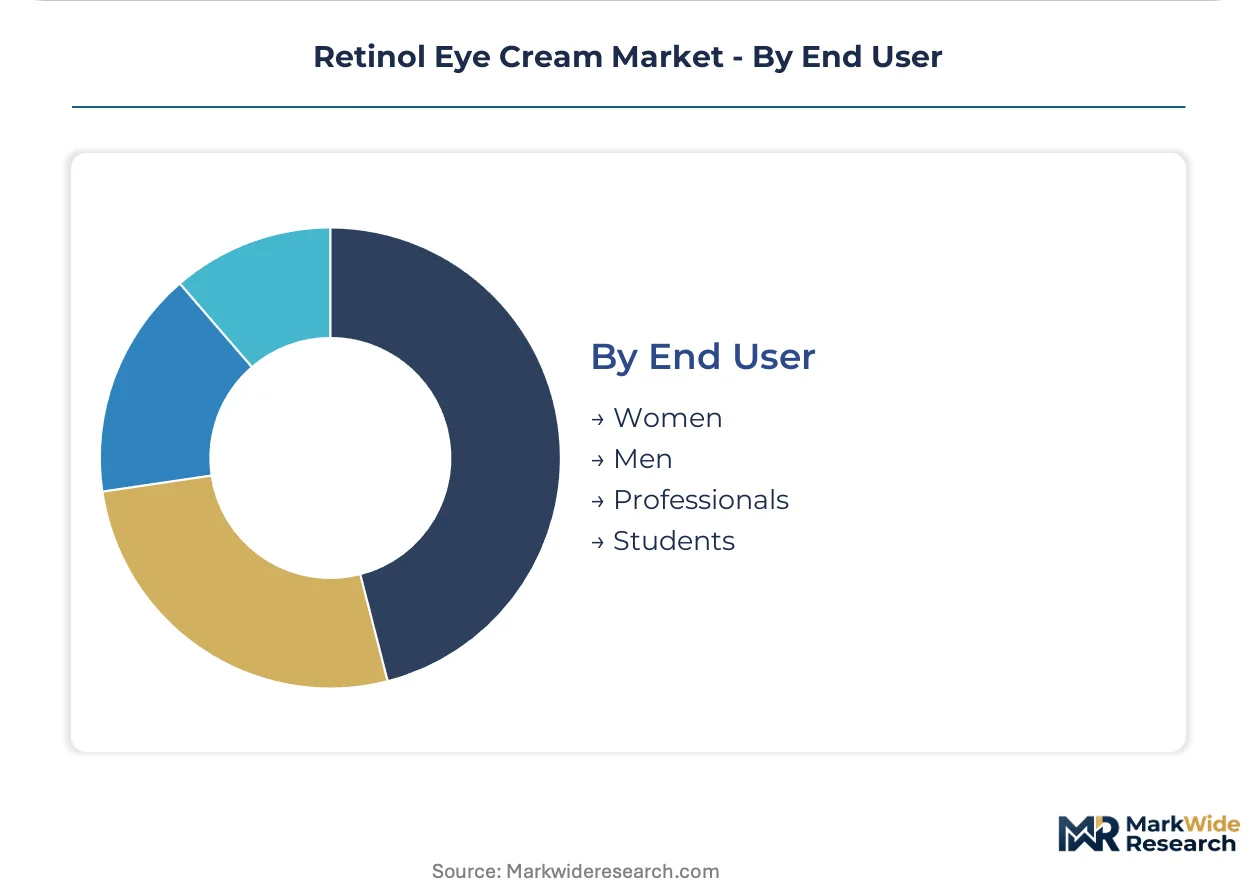
End User:
Customer type diversification is forcing packaging and messaging adaptation as male skincare adoption accelerates and professional segments seek clinical credibility markers.
- Women:Core demographic driving historical category development with established retinol literacy and multi-step routine integration. United States women aged 25-40 represent the densest concentration of preventive anti-aging purchases.
- Men:Underpenetrated segment responding to simplified, gender-neutral positioning in Germany and United Kingdom grooming markets. Texture preferences lean toward gels and lightweight serums over rich creams.
- Professionals:High-income urban consumers prioritizing clinical substantiation and time-efficient application formats. This segment over-indexes on subscription replenishment and premium concentration products.
- Students:Entry-level buyers seeking affordable introduction to retinol through lower-concentration moisturizers and promotional sampling. TikTok and Instagram discovery patterns dominate this cohort's purchase initiation.
Women absorb the bulk of current revenue; Men are gaining share fastest as grooming category boundaries dissolve and male-specific skincare marketing matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York City anchors the densest concentration of dermatology clinic networks and prestige beauty headquarters, driving professional-grade retinol protocol adoption and direct-to-consumer brand incubation across the United States.
United States
Millennial and Gen Z consumers in California and Texas are integrating retinol eye creams into preventive skincare routines earlier than previous cohorts. The FDA oversees cosmetic-drug boundary classifications that determine permissible marketing claims and pre-market approval requirements. Los Angeles and Miami host the fastest-growing subscription-based direct-to-consumer platforms, capturing repeat purchase loyalty through algorithmic regimen personalization.
Germany
Pharmacy-dependent consumers in Bavaria and North Rhine-Westphalia prioritize dermocosmetic credibility and pharmacist recommendations for sensitive-eye-area products. The EU Cosmetics Regulation and REACH framework govern ingredient safety assessments and nanomaterial disclosures affecting retinol encapsulation technologies. Berlin anchors specialized professional dispensing channels for intensive retinol treatment protocols.
Japan
Consumers in Tokyo and Osaka favor gel-textured retinol formulations compatible with humid climate conditions and multi-step skincare routines. The Ministry of Health, Labour and Welfare through PMDA oversees quasi-drug classifications that determine permissible efficacy claims for brightening and anti-aging indications. Kansai region fermentation-derived retinol technologies command premium shelf placement in domestic and export markets.
South Korea
Seoul-based consumers drive demand for tone-evening retinol eye creams combining melanin inhibition with preventive anti-aging benefits. The MFDS regulates cosmetic and functional cosmetic classifications that determine distribution channel access and marketing claim scope. Incheon and Busan host specialized manufacturing clusters for encapsulated active delivery systems serving domestic and Asian export markets.
United Kingdom
London and Manchester consumers exhibit accelerating adoption of subscription replenishment models bypassing traditional pharmacy gatekeepers. The UK retains EU-aligned cosmetics regulations post-Brexit, with MHRA oversight on product safety and labeling requirements. Birmingham hosts emerging direct-to-consumer brand headquarters leveraging algorithmic personalization to capture lifetime customer value.
Retinol Eye Cream Market Competitive Landscape
Capital-heavy producers with captive manufacturing assets compete with asset-light formulation specialists outsourcing stabilization and encapsulation to third-party foundries. The market structure consolidates around three tiers: multinational conglomerates with dermatological science arms, regional specialists in stabilized retinol technologies, and direct-to-consumer challengers leveraging subscription economics. Strategic moves concentrate on biotechnology convergence partnerships and geographic licensing arrangements that bypass regulatory registration barriers in controlled markets.
Within the multinational tier, L'Oréal and Shiseido occupy positions anchoring credibility through dermatological science and fermentation-derived technologies respectively. RoC Skincare exemplifies the specialist archetype with decades-long concentration in stabilized retinol formulations. Among direct-to-consumer challengers, Paula's Choice and Dr. Dennis Gross Skincare represent asset-light models capturing customer data ownership through algorithmic regimen platforms.
| Leading Market Players |
|---|
| L'Oréal |
| Shiseido |
| Procter & Gamble |
| Paula's Choice |
| RoC Skincare |
| Dr. Dennis Gross Skincare |
| Johnson & Johnson |
| Pierre Fabre |
| Kate Somerville |
| Others |
Pricing and Supply Chain Analysis
Captive retinol stabilization capabilities anchor pricing power for brands with in-house encapsulation expertise, while outsourced active sourcing compresses margins through cold-chain packaging costs and third-party formulation fees. L'Oréal's dermatological science arm commands premium shelf placement by controlling polymer-matrix delivery technology internally, whereas direct-to-consumer challengers absorb margin erosion from contract manufacturing markups.
Pricing Analysis
Instrumental wrinkle-reduction outcomes anchor value-based pricing for clinical-grade retinol eye creams, with dermatology clinics dispensing 0.5% to 1.0% concentration serums at substantial premiums over mass-market 0.01% moisturizers. Price differentiation separates FDA-registered quasi-drug formulations from cosmetic-grade alternatives, with EU REACH-compliant encapsulation commanding additional certification premiums. Pricing pressure stems from photodegradation instability forcing costly amber packaging and refrigerated logistics that squeeze unit economics. Students and entry-level buyers exhibit highest price sensitivity, while professionals seeking clinical substantiation tolerate premium positioning.
Supply Chain Analysis
REACH and GB standards certification gating restricts bulk retinol sourcing to qualified suppliers in China, India, and Switzerland, with ECHA nanomaterial assessments extending registration timelines for liposomal carriers. Active ingredient production draws from vitamin A precursor synthesis concentrated in Shandong province and Gujarat state, while polymer encapsulation feedstocks source from German and Japanese specialty chemical foundries. Single-source vulnerability runs through Chinese export licensing delays affecting retinol acetate availability. Distribution runs through cold-chain logistics networks serving pharmacy, specialty store, and direct-to-consumer replenishment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The retinol eye cream market operates as a vertical-integration race, with formulation stabilization expertise and captive encapsulation capacity determining margin capture against contract-manufactured challengers.
For Market Incumbents: Deploy microbiome-convergence R&D to preempt biotechnology entrants from unifying retinol with postbiotic positioning. Acquire specialized stabilization foundries in Germany or Japan to secure polymer-matrix delivery capacity before supply bottlenecks tighten. L'Oréal and Shiseido must consolidate fermentation-derived active sourcing to defend against direct-to-consumer brands algorithmically capturing Gen Z loyalty.
For New Entrants and Emerging Players: Enter via subscription-based replenishment models targeting underpenetrated male grooming segments in Germany and the United Kingdom with gender-neutral gel formulations. White-space concentrates in men's professional skincare routines, where simplified messaging and lightweight textures bypass incumbent cream-dominated positioning. Algorithmic regimen personalization captures lifetime value without pharmacy gatekeeper dependency.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational dermatological science arms seeking encapsulated active capabilities. Long-term viability hinges on regulatory navigation expertise across FDA cosmetic-drug boundaries and EU REACH nanomaterial classifications. Watch for ECHA clarification on liposomal carrier registrations as inflection signal determining which encapsulation technologies retain premium positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Polymer-matrix delivery systems from German foundries enable higher concentration claims with reduced irritation profiles. |
| Direct-to-Consumer Subscription Launch | Algorithmic personalization platforms in Los Angeles and Miami capture repeat purchase loyalty bypassing Sephora gatekeepers. |
| Quasi-Drug Registration Pathway | PMDA and FDA cosmetic-drug boundary navigation unlocks therapeutic efficacy claims for brightening and anti-aging indications. |
| Biotechnology Convergence Partnership | Postbiotic-retinol combinations unify microbiome and retinoid categories for differentiated positioning in Asian markets. |
| Cold-Chain Distribution Expansion | Refrigerated logistics networks serving pharmacy and dermatology clinics preserve photodegradation-sensitive active potency. |
Research Methodology
Trade databases, regulatory filings, and customs records formed the secondary backbone, supplemented by primary interviews with dermatology clinic directors, cosmetic formulation chemists, pharmacy procurement managers, and direct-to-consumer brand operators. Bottom-up triangulation across product-type volume estimates and top-down validation against channel-level revenue flows ensured cross-verification. Segmentation modeling incorporated concentration tier, application indication, distribution format, and regional regulatory cluster dimensions.
Bottom-up demand modeling tracked prescription-adjacent dispensing patterns and mass-market replenishment cycles across the projection horizon, while top-down macro constraints incorporated raw material availability and certification timeline assumptions. CAGRs derived from segment-level growth rate blending weighted by installed manufacturing capacity and channel expansion trajectories. Forecast inputs included EU REACH nanomaterial registration progress and FDA cosmetic-drug boundary enforcement intensity.
Revisions become necessary when ECHA issues definitive liposomal carrier classifications or when Chinese export licensing delays extend beyond baseline assumptions. Forecasts reflect documented stability data availability and clean-label credential penetration rates. A model refresh is warranted upon material change in retinol concentration regulatory caps or photodegradation packaging cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Canada Cosmetic Products Market
Cosmetics & Skincare
Makeup Remover Product Market
Cosmetics & Skincare
Mushroom Cosmetics Market
Cosmetics & Skincare
Cosmetics Private Label and Contract Manufacturing Market
Cosmetics & Skincare
Facial Serum Market
Cosmetics & Skincare
Mascara Applicators Market
Cosmetics & Skincare
Anti-Fatigue Cosmetics Market
Cosmetics & Skincare
Face Compact Market
Cosmetics & Skincare
Sports Sun Care Market
Cosmetics & Skincare
Beauty Facial Mask Market
Cosmetics & Skincare
Probiotic Skin Care Cosmetic Product Market
Cosmetics & Skincare
Makeup Setting Powder Market
Cosmetics & Skincare
Color Cosmetics OEM and ODM Market
Cosmetics & Skincare
Halal Cosmetics Market
Cosmetics & Skincare
China Cosmetic Products Market
Cosmetics & Skincare
Cosmetics OEM and ODM Services Market