
 Automotive Chain Tensioners Market | 2026-2036
Automotive Chain Tensioners Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Chain Tensioners Market Analysis
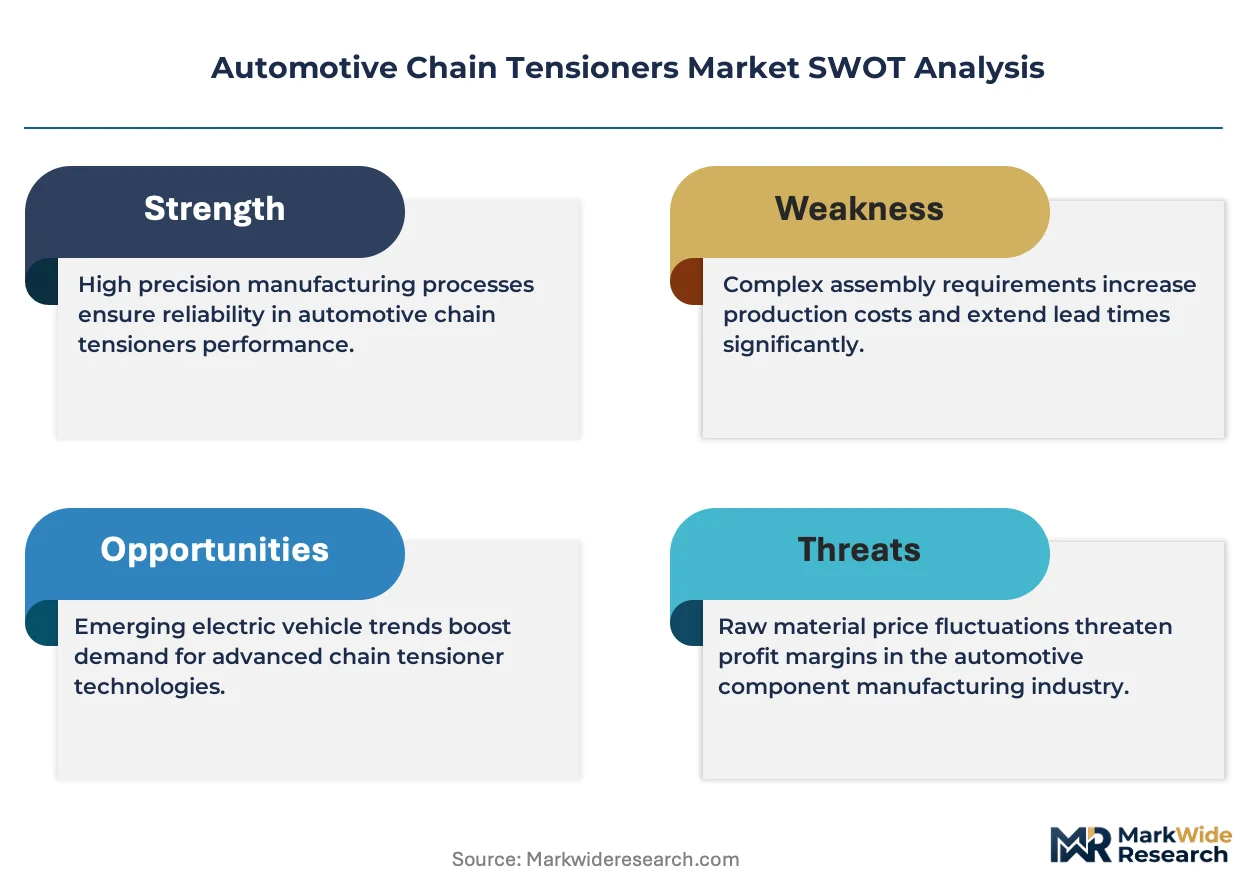
Polymer composite housings are broadening design freedom for chain tensioner manufacturers seeking mass reduction without sacrificing fatigue resistance. Schaeffler Technologies AG & Co. KG leverages captive forging capacity to anchor European supply for high-load hydraulic units. Continental AG competes through integrated mechatronics development that merges tension control with engine management signaling. NSK Ltd. dominates precision bearing integration within Asian OEM supply chains.
An automotive chain tensioner is a force-applying device that maintains optimal slack elimination in engine timing and balance shaft chains, typically incorporating a plunger with return spring, hydraulic pressure chamber, and polymer guide shoe with oil-impregnated sintered metal contact surfaces. Hydraulic tensioners command the largest installed base due to their self-adjusting pressure response across RPM ranges, though automatic tensioners with electromechanical feedback represent the fastest-expanding technology segment as powertrain electrification demands finer chain control. Aftermarket Suppliers occupy a fragmented but margin-rich channel where repair shops prioritize rapid-fit mechanical units over full system replacement.
NHTSA durability standards and EPA emission compliance protocols in the United States tighten tolerance requirements for timing chain systems, directly elevating tensioner specification thresholds. Euro 7 standards through EMA frameworks and China's GB standards via MIIT enforce comparable precision mandates that OEMs must satisfy for type approval. Stakeholders should monitor how powertrain electrification timelines alter chain-versus-belt architecture decisions across passenger and commercial vehicle platforms.
Market Dynamics
Powertrain electrification timelines are compressing chain-versus-belt architecture decisions across passenger and commercial vehicle platforms, forcing tensioner suppliers to hedge R&D portfolios across both technologies while OEMs finalize platform strategies.
Growth Catalysts
- EPA tailpipe regulations:Tightening emission standards in the United States mandate finer timing-system precision, elevating specification thresholds for hydraulic tensioner assemblies in gasoline direct-injection engines.
- Lightweight polymer composites:Material substitution in tensioner housings enables mass reduction without fatigue resistance sacrifice, penetrating German and Japanese commercial vehicle OEM procurement pipelines.
- China's passenger vehicle corridors:Manufacturing concentration around Shanghai and Guangzhou generates concentrated demand for precision-engineered tensioner systems serving domestic EV-to-hybrid transitions.
Market Restraints
- Steel and sintered metal input volatility:Oil-impregnated bearing surfaces depend on powdered metallurgy supply chains concentrated in East Asian forging networks, exposing margin structures to commodity swings.
- Electrification substitution threat:Battery-electric powertrains eliminate timing chains entirely, threatening long-term tensioner demand in passenger segments where BEV penetration accelerates fastest.
- Euro 7 compliance friction:EMA framework precision mandates require costly retooling of hydraulic pressure chamber tolerances, extending type-approval timelines for European suppliers.
Strategic Opportunities
- Aftermarket channel expansion:Repair shops in North America prioritize rapid-fit mechanical units over full system replacement, creating margin-rich white space for specialized distributors.
- Electromechanical feedback convergence:Automatic tensioners integrating sensor arrays with engine management signaling address powertrain electrification demands for real-time chain control.
- India's commercial vehicle upcycle:PLI scheme incentives for automotive component manufacturing attract tensioner assembly localization serving domestic truck and bus production growth.
Industry Challenges
- Mechatronics talent scarcity:Integration of hydraulic, mechanical, and electronic subsystems requires cross-functional engineering capabilities that outpace current workforce development pipelines.
- Dual certification timelines:Simultaneous NHTSA durability validation and EPA emission compliance protocols extend product launch cycles, compressing revenue recognition windows.
- Legacy system integration complexity:Electromechanical tensioner retrofits into existing internal combustion platforms demand backward-compatible mounting geometries that constrain design freedom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Chain Tensioners Market |
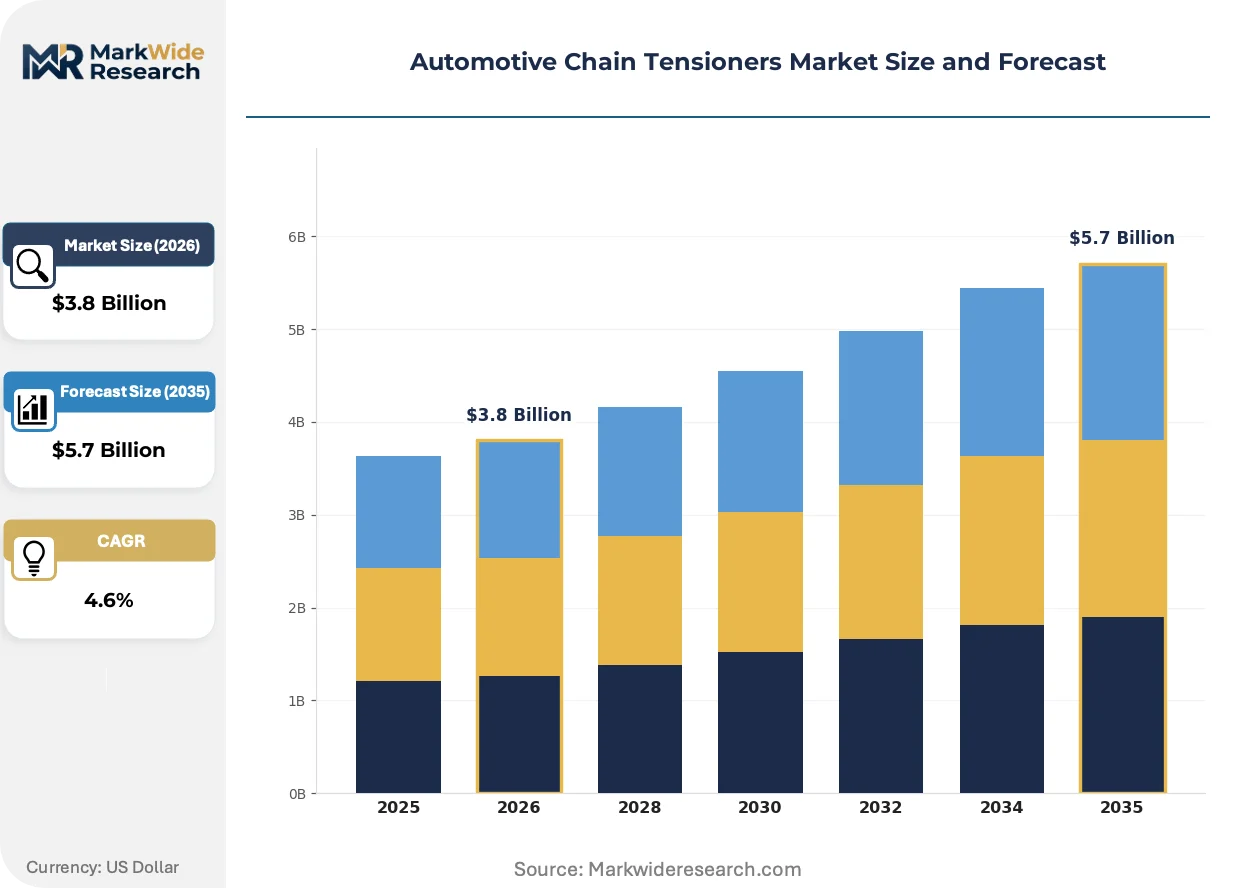
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Tensioners, Mechanical Tensioners, Spring Tensioners, Automatic Tensioners Technology: Electric, Pneumatic, Manual, Hybrid End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Repair Shops Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles |
| Companies Covered | Continental AG, Schaeffler Technologies AG & Co. KG, NSK Ltd., BorgWarner Inc., Gates Corporation, Dayco IP Holdings, Litens Automotive Group, NTN Corporation, ABA Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Chain Tensioners Market Emerging Trajectories
Active material substitution and control-system digitization are redefining tensioner performance benchmarks, while regulatory precision mandates accelerate specification tiering across regional supply chains.
Polymer composite housings are absorbing structural loads previously managed by aluminum castings, enabling 15-30% mass reduction in plunger assemblies. German commercial vehicle OEMs have accelerated validation timelines for these materials in heavy-duty timing systems. The technology is absorbing design responsibility for fatigue-critical applications without expanding forging capacity.
REACH substance restrictions and F-Gas Regulation phase-down schedules in Europe are tightening specifications for hydraulic fluid compatibility in tensioner pressure chambers. Seal material suppliers face reformulation mandates to maintain chemical resistance under new environmental compliance frameworks. Asian OEMs exporting to European markets are pre-emptively adopting these material standards to streamline homologation.
Consolidated procurement by multinational OEMs is compressing supplier qualification cycles and favoring tier-one system integrators over component specialists. Direct sourcing agreements between vehicle manufacturers and precision bearing houses are displacing traditional distributor networks in high-volume programs. This pattern concentrates most visibly in China's Yangtze River Delta manufacturing cluster, where vertical integration into tensioner subassembly production is accelerating.
Automotive Chain Tensioners Market Segmentation
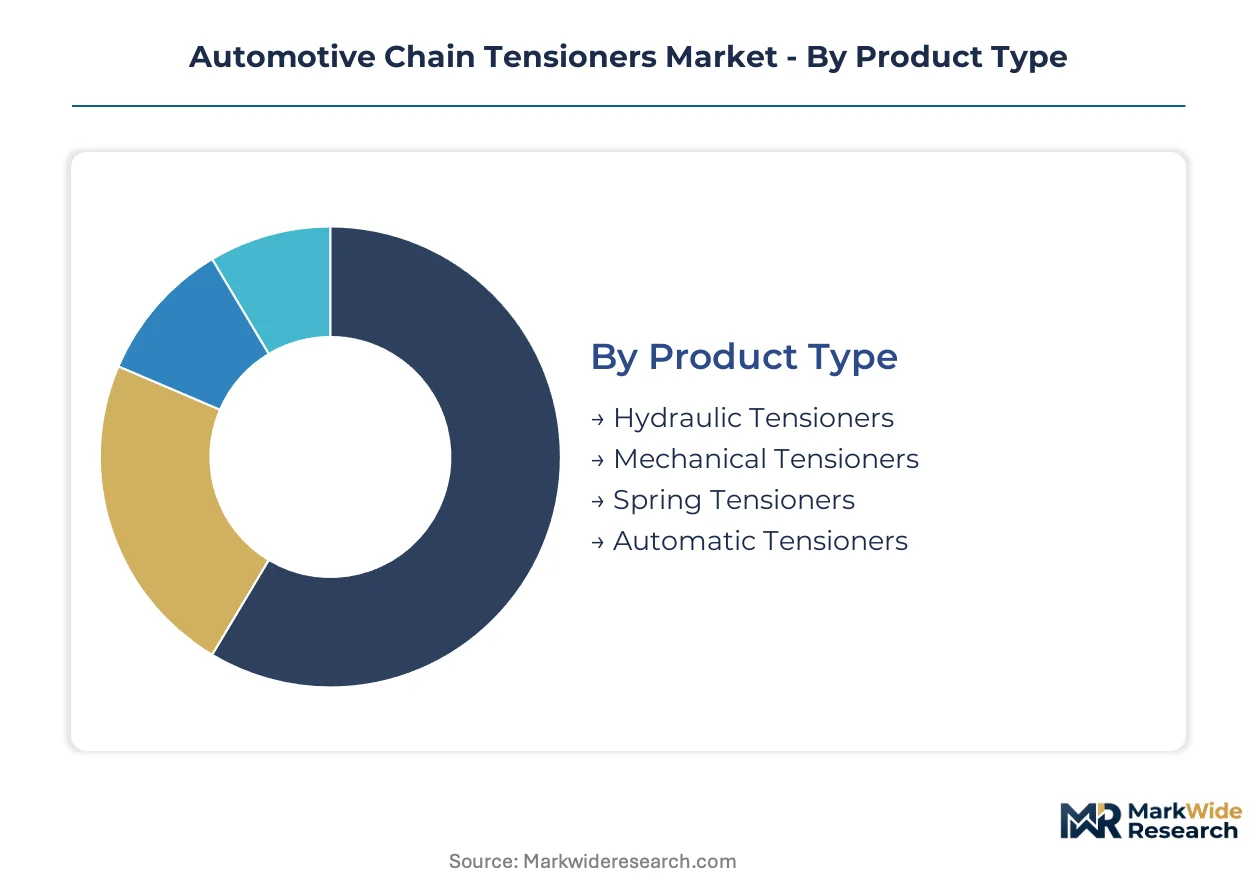
Segmentation in automotive chain tensioners reveals how specification tiers align with powertrain electrification timelines and regional regulatory stringency. Suppliers must calibrate R&D allocation across hydraulic legacy systems and electromechanical architectures to match divergent OEM platform strategies.
Product Type:
Hydraulic and automatic tensioners anchor competing technology philosophies across engine timing applications.
- Hydraulic Tensioners:Self-adjusting pressure chambers respond dynamically to RPM fluctuations, maintaining chain preload across variable valve timing operations. Demand concentrates in German and Japanese commercial vehicle OEM procurement pipelines where Euro 7 and EPA emission mandates require precision timing control for heavy-duty diesel platforms.
- Automatic Tensioners:Electromechanical units integrate sensor feedback with engine management systems, enabling real-time chain tension optimization. China's passenger vehicle manufacturing corridors around Shanghai and Guangzhou are accelerating validation for these systems as hybrid powertrains demand finer control than hydraulic architectures provide.
- Mechanical Tensioners:Fixed-load spring designs serve cost-sensitive aftermarket replacement cycles where repair shops prioritize rapid-fit installation over adaptive performance.
- Spring Tensioners:Baseline coil-spring assemblies occupy legacy internal combustion platforms with stable operating envelopes and minimal variable valve complexity.
Mature deployment sits with hydraulic tensioners in commercial vehicle timing systems. Newer deployment is concentrated in automatic tensioners for hybrid powertrain applications.
Technology:
Control-system sophistication determines which tensioner architectures can satisfy tightening emission compliance protocols.
- Electric:Sensor-integrated actuators enable closed-loop tension management through ECU signaling, supporting the precise chain control demanded by gasoline direct-injection engines under EPA tailpipe regulations. These systems are gaining share fastest in passenger vehicle segments where powertrain electrification requires coordination with battery thermal management.
- Pneumatic:Compressed-air actuation serves auxiliary drive systems in heavy-duty truck applications where hydraulic fluid compatibility with REACH substance restrictions creates compliance friction.
- Manual:Fixed-adjustment designs persist in motorcycle timing applications where packaging constraints and cost thresholds limit electronic integration.
- Hybrid:Combined hydraulic-electromechanical architectures bridge legacy platform compatibility with emerging control requirements, extending product lifecycles for OEMs managing dual certification timelines.
Established production volumes center on pneumatic systems for commercial auxiliary drives. Accelerating specification upgrades are flowing to electric architectures for integrated engine management.
End User:
Channel structure shapes margin capture and technical support requirements across the tensioner value chain.
- OEMs:Direct sourcing agreements with vehicle manufacturers concentrate demand for validated hydraulic and automatic tensioner systems, with qualification cycles compressing under consolidated multinational procurement.
- Aftermarket Suppliers:Fragmented distributor networks serve repair shops prioritizing rapid-fit mechanical units, creating margin-rich white space in North American replacement channels.
- Vehicle Assemblers:Contract manufacturing arrangements in China's Yangtze River Delta cluster drive localized subassembly production for domestic and export programs.
- Repair Shops:Independent service providers favor mechanical tensioner replacements over full system retrofits, limiting electromechanical penetration in the installed base.
Volume concentration aligns with OEM direct sourcing for new vehicle programs. Margin expansion opportunities sit with aftermarket suppliers serving repair shop replacement cycles.
Application:
Powertrain architecture decisions across vehicle categories determine chain-versus-belt selection and tensioner specification intensity.
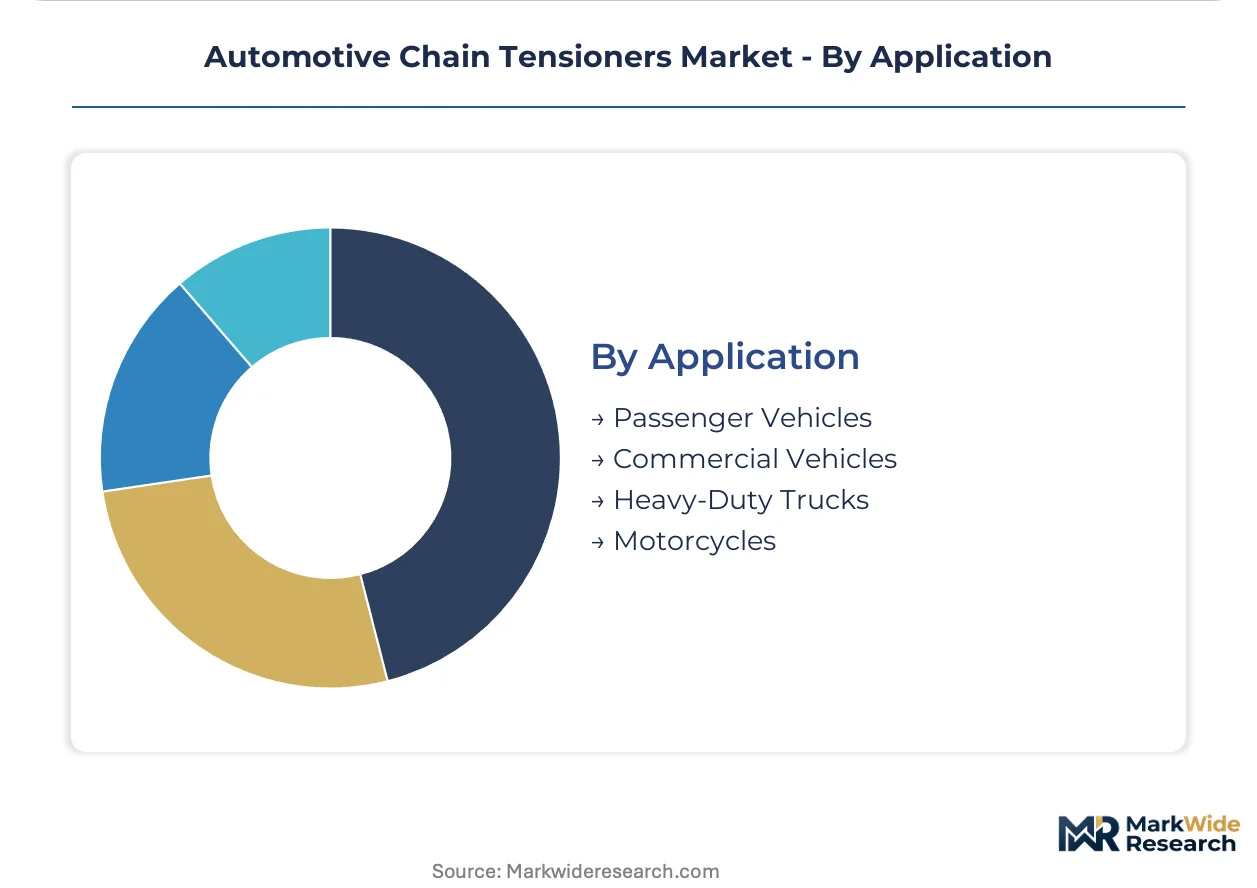
- Passenger Vehicles:Hybrid and gasoline direct-injection platforms demand automatic tensioners with electromechanical feedback, though battery-electric substitution threatens long-term chain elimination in this segment.
- Commercial Vehicles:Heavy-duty diesel timing systems in German and Japanese OEM fleets rely on hydraulic tensioners with polymer composite housings to satisfy mass reduction targets without fatigue resistance sacrifice.
- Heavy-Duty Trucks:Long-haul applications prioritize durability-validated hydraulic units meeting NHTSA endurance standards, with seal materials reformulating for F-Gas Regulation phase-down compliance.
- Motorcycles:Compact packaging and cost thresholds sustain manual and spring tensioner architectures with minimal electronic integration.
Specification intensity peaks in commercial vehicle applications where emission mandates drive timing precision. Vulnerability to electrification substitution concentrates in passenger vehicle segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Passenger vehicle manufacturing corridors in China concentrate demand for precision-engineered tensioner systems, while commercial vehicle OEM procurement pipelines in Germany and Japan drive specification intensity for heavy-duty hydraulic units.
China
Domestic EV-to-hybrid transitions in passenger vehicle segments accelerate validation timelines for automatic tensioners with electromechanical feedback. MIIT's GB standards enforcement through type-approval protocols tightens tolerance requirements for timing-system precision. Manufacturing clusters around Shanghai and Guangzhou generate concentrated demand for localized subassembly production serving both domestic and export programs.
Germany
Commercial vehicle OEMs expand procurement of lightweight tensioner assemblies with polymer composite housings to satisfy mass reduction targets without fatigue resistance sacrifice. KBA-administered Euro 7 compliance protocols mandate costly retooling of hydraulic pressure chamber tolerances for type approval. Industrial concentration in Bavaria and Baden-Württemberg anchors European supply for high-load hydraulic units serving heavy-duty diesel platforms.
United States
Gasoline direct-injection engine penetration under EPA tailpipe regulations elevates specification thresholds for hydraulic tensioner assemblies with finer timing-system precision. NHTSA durability standards extend product validation cycles for tensioner systems in heavy-duty truck applications. Repair shops across North American aftermarket channels prioritize rapid-fit mechanical units over full system replacement, creating margin-rich distributor opportunities.
Japan
METI-industrial policy alignment supports precision bearing integration within Asian OEM supply chains for hybrid powertrain applications. JIS standards enforcement maintains quality benchmarks for oil-impregnated sintered metal contact surfaces in tensioner guide shoes. Manufacturing corridors in the Chubu region around Nagoya concentrate subassembly production for both domestic commercial vehicle OEMs and export programs.
India
Commercial vehicle upcycle in truck and bus production attracts tensioner assembly localization under PLI scheme incentives for automotive component manufacturing. BIS certification requirements for timing-system components extend supplier qualification timelines for multinational OEMs entering domestic procurement pipelines. Industrial clusters in Maharashtra and Tamil Nadu concentrate vehicle assembler contract manufacturing arrangements serving regional replacement demand.
Automotive Chain Tensioners Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated procurement by multinational OEMs compressing supplier qualification cycles and favoring tier-one system integrators. Three strategic archetypes dominate: European precision forging houses with captive capacity, Asian bearing specialists integrating upstream component production, and North American aftermarket distributors capturing margin-rich replacement channels. Competitive moves center on backward integration into polymer composite housing production and geographic expansion into India's PLI-incentivized manufacturing corridors.
Among European-based system integrators, Schaeffler Technologies AG & Co. KG and Continental AG occupy positions exemplifying the precision-forging and mechatronics-integration archetypes respectively. NSK Ltd. represents the Asian bearing-specialist model with upstream control over precision component supply chains. These three companies anchor the competitive structure through differentiated technology positioning rather than scale-driven cost competition.
| Leading Market Players |
|---|
| Continental AG |
| Schaeffler Technologies AG & Co. KG |
| NSK Ltd. |
| BorgWarner Inc. |
| Gates Corporation |
| Dayco IP Holdings |
| Litens Automotive Group |
| NTN Corporation |
| ABA Automotive |
| Others |
Supply Flow & Price Mechanics
Precision forging talent concentration in Bavaria and Baden-Württemberg feeds labor-cost differentials that separate premium hydraulic tensioner pricing from economy mechanical alternatives. Euro 7 compliance investments widen spreads between certified and non-certified supplier tiers.
Pricing Analysis
Volume concentrates in OEM contract volumes while margin capture sits with aftermarket mechanical units. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Pricing pressure stems from steel and sintered metal input volatility compressing margin structures in hydraulic assemblies. Aftermarket repair shops exhibit highest price sensitivity, while German commercial vehicle OEMs prioritize fatigue resistance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from multinational OEMs mandate multi-supplier qualification across Germany, China, and Japan for polymer composite housings and precision bearing components. Raw material dependencies center on oil-impregnated sintered metals, powdered metallurgy feedstock, and REACH-compliant seal polymers. Single-source vulnerability concentrates in East Asian forging networks for high-load hydraulic pressure chambers. Distribution runs through tier-one system integrators directly to OEM platform engineering teams, bypassing traditional component distributors in high-volume programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where Euro 7 precision mandates create a barrier-to-entry moat for suppliers with validated hydraulic pressure chamber tolerances and KBA type-approval track records.
For Market Incumbents: Deepen captive forging capacity in European industrial corridors to anchor supply security for high-load hydraulic units serving German commercial vehicle OEMs. Retool polymer composite housing production lines to capture mass reduction procurement from Japanese heavy-duty platforms. Battery-electric substitution in passenger segments threatens long-term volume; hedge R&D portfolios across electromechanical feedback architectures.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in North American aftermarket channels offers white-space entry for rapid-fit mechanical tensioner specialists. Target repair shop distributor networks with margin-rich replacement cycles where full system retrofits face resistance. India's PLI-incentivized manufacturing corridors present localization opportunities serving domestic truck and bus production growth.
For Investors and Strategic Acquirers: The window for entry favors precision bearing houses with upstream component control and established Asian OEM supply chain relationships. Long-term viability hinges on powertrain electrification timelines altering chain-versus-belt architecture decisions. Monitor EPA tailpipe regulation enforcement intensity as the inflection signal for timing-system precision upgrade cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Composite Housing Production | Captures mass reduction value previously extracted by aluminum casting suppliers serving German OEMs. |
| Electromechanical Feedback Architecture Development | Addresses hybrid powertrain demands from Shanghai and Guangzhou manufacturing corridors. |
| India PLI Scheme Manufacturing Localization | Positions assembly capacity to serve domestic commercial vehicle upcycle in Maharashtra and Tamil Nadu. |
| REACH-Compliant Seal Material Reformulation | Ensures hydraulic fluid compatibility for European market access under F-Gas Regulation phase-down schedules. |
| Aftermarket Channel Distributor Partnership | Captures margin-rich replacement demand from North American repair shops prioritizing rapid-fit installation. |
Methodological Framework
Document review covered vehicle production databases, IHS Markit registration data, and SEC filings from tier-one suppliers, complemented by interviews with OEM platform engineers, Tier 1 procurement leads, aftermarket distributors, and polymer composite material specialists. Secondary validation drew from EPA emission compliance protocols, Euro 7 EMA framework documentation, and MIIT GB standards enforcement records. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Output specifications span unit volume and value projections across hydraulic, automatic, mechanical, and spring tensioner architectures. Segmentation dimensions encompass product type, control technology sophistication, end-user channel structure, and application intensity by vehicle class. CAGRs derive from regression analysis against powertrain electrification timelines and regulatory compliance investment cycles. Forecast inputs incorporate OEM platform standardization roadmaps and aftermarket replacement frequency assumptions.
Underlying measurement precision varies by segment; hydraulic tensioner volumes in commercial vehicle applications carry tighter precision than emerging electromechanical architectures in hybrid passenger platforms. Forecasts embed assumptions regarding Euro 7 implementation timelines and China's EV-to-hybrid transition velocity. Deviation in battery-electric penetration rates or REACH substance restriction enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Crankshaft Position Sensor Market
Powertrain
EV Drivetrain Systems Market
Powertrain
Automotive Engine Market
Powertrain
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market
Powertrain
Tachometer Market
Powertrain
Global Automotive Engine Cover Market
Powertrain
Automotive Drivetrain Market
Powertrain
Gasoline Direct Injection (GDI) System Market
Powertrain
Automotive Retrofit Electric Vehicle Powertrain Market
Powertrain
Transmission Control System Market
Powertrain
Transmission Oil Pumps Market
Powertrain
Global Automotive Torque Converter Market
Powertrain
Fuel Injection Systems Market
Powertrain
South Korea Automotive Engine Oils Market
Powertrain
Europe Internal Combustion Engines Market
Powertrain
North America Torque Vectoring Market