
 Physical Access Control Market | 2026-2036
Physical Access Control Market Size, Share, and Industry Trends Forecast 2026-2036
Physical Access Control Market Outlook
Buyer concentration among healthcare organizations and government facilities is hardening as procurement shifts toward integrated enterprise platforms. ASSA ABLOY leverages its architectural hardware dominance to anchor multi-site hospital contracts across Europe. dormakaba Group specializes in electronic locking systems that compete on interoperability with existing building management infrastructure. Johnson Controls sustains technology leadership in cloud-based access platforms through its building automation integration.
Physical access control encompasses electromechanical and electronic systems that authenticate identity through credentials, biometrics, or cryptographic tokens to authorize entry at secured perimeters, typically operating on 125 kHz low-frequency or 13.56 MHz high-frequency RFID protocols with AES-128 encryption standards. These systems serve critical commercial and institutional functions by creating audit trails, enforcing time-based permissions, and integrating with video surveillance and intrusion detection networks. Biometric systems now lead product-type expansion as fingerprint, iris, and facial recognition modules displace card-based credentials in high-assurance environments. Cloud-based solutions represent the fastest-growing installation category by decoupling capital expenditure from scalability, while on-premises solutions retain margin concentration in defense and critical infrastructure sectors where data sovereignty requirements prevail.
FDA cybersecurity guidance for connected medical devices, the EU AI Act's risk-classification framework for biometric identification, and GDPR Article 9 special-category data protections collectively reshape product development roadmaps and market access conditions for vendors serving European healthcare and government verticals. NIST SP 800-63 digital identity guidelines and FICAM federal identity credentialing standards further constrain architecture choices in US federal deployments. Stakeholders must monitor regulatory divergence between European algorithmic accountability requirements and US sector-specific cybersecurity mandates when selecting biometric modality investments and cloud-hosting jurisdictions.
Market Dynamics
Healthcare organizations across Germany, France, and the United Kingdom are consolidating procurement around integrated enterprise platforms, compressing vendor selection cycles and favoring suppliers with architectural hardware-to-software continuity. This buyer concentration is forcing mid-tier specialists to either deepen platform partnerships or retreat to niche credential manufacturing.
Growth Catalysts
- EU AI Act risk-classification framework:Biometric authentication vendors serving European healthcare verticals face mandatory algorithmic transparency requirements, accelerating compliant product development and creating first-mover advantages for certified systems.
- Cloud-based access platforms:Decoupled capital expenditure models are expanding addressable markets among mid-size commercial real estate operators previously excluded by on-premises infrastructure costs.
- German hospital consolidation wave:Multi-site healthcare networks in Germany are standardizing physical access control across estate portfolios, generating bundled contract opportunities for platform-integrated suppliers.
Market Restraints
- Semiconductor supply concentration:13.56 MHz high-frequency RFID transponder production concentrates among East Asian foundries, exposing European system integrators to lead-time volatility and tariff exposure.
- GDPR Article 9 special-category data friction:Biometric template storage triggers heightened consent and purpose-limitation requirements, extending sales cycles for facial recognition deployments in French and UK corporate environments.
- AES-128 encryption standard obsolescence risk:Quantum computing advancement threatens current cryptographic credential protocols, creating technical debt anxiety among defense and critical infrastructure buyers.
Strategic Opportunities
- Interoperability with building management infrastructure:Electronic locking systems that natively integrate with HVAC and energy management platforms capture retrofit opportunities in aging European commercial stock.
- Mobile credential convergence:Smartphone-based access tokens combining Bluetooth Low Energy and NFC protocols are penetrating mid-market office deployments in the United Kingdom where card credential replacement cycles accelerate.
- Federal identity credentialing tailwinds:FICAM standards adoption across US civilian agencies creates exportable architecture templates for vendors seeking transatlantic healthcare and government vertical expansion.
Industry Challenges
- Cybersecurity-physical security skill convergence:Enterprise buyers demand unified threat assessment across IT and OT domains, yet vendor field engineering teams rarely possess dual-competency certifications in network security and electromechanical systems.
- Multi-modal biometric integration complexity:Fingerprint-iris-facial recognition fusion architectures require specialized calibration expertise that strains installation partner capacity, delaying project commissioning and eroding margin on fixed-price contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Physical Access Control Market |
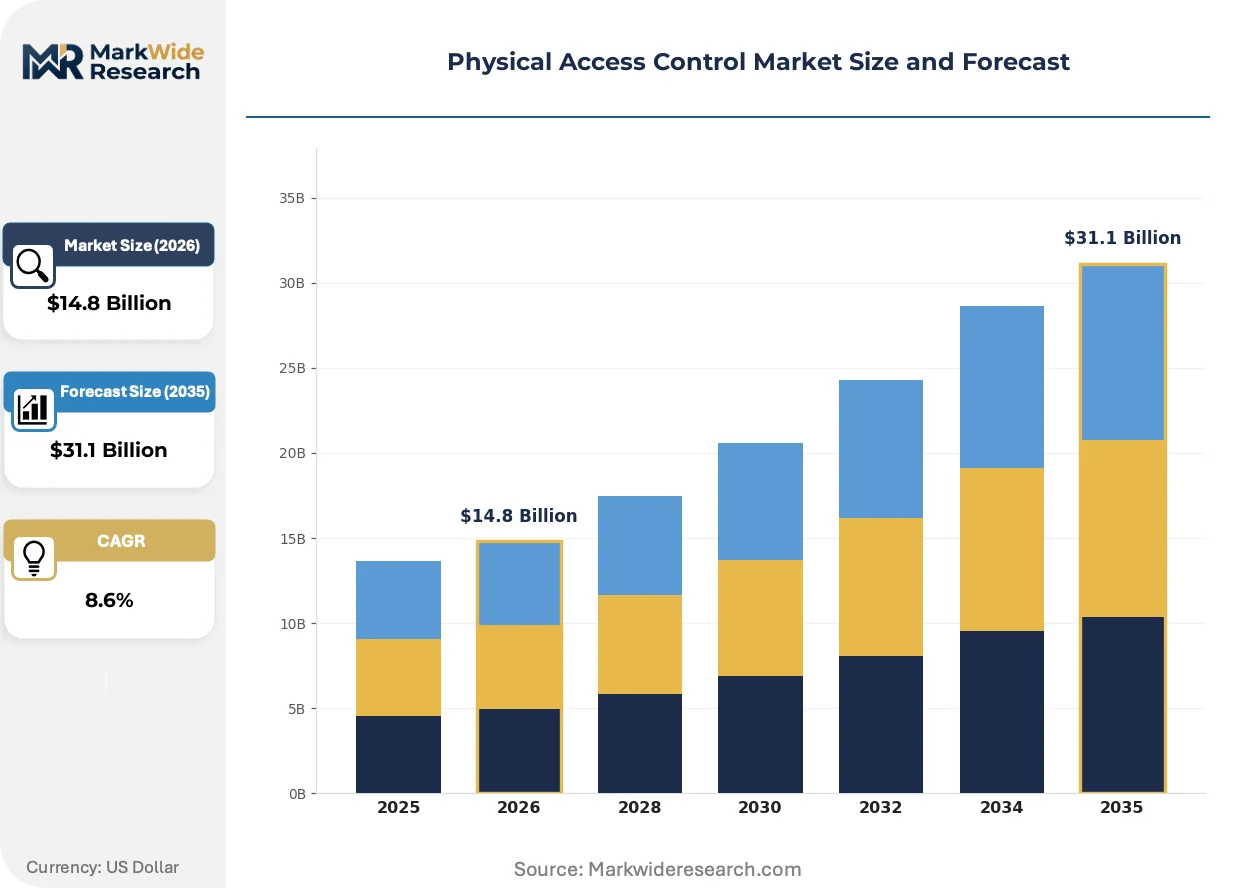
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Card-Based Systems, Biometric Systems, Keypad Systems, RFID Solutions End User: Corporate Offices, Government Facilities, Educational Institutions, Healthcare Organizations Technology: Physical Key Systems, Electronic Locking Systems, Turnstile Technology, Intercom Systems Installation Type: Standalone Systems, Integrated Systems, Cloud-Based Solutions, On-Premises Solutions |
| Companies Covered | ASSA ABLOY, dormakaba Group, Johnson Controls, Allegion plc, Honeywell International Inc., Bosch Security Systems, Nedap N.V., Suprema Inc., Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Physical Access Control Market Strategic Shifts
Biometric credential architectures are fragmenting into componentized subsystems, enabling healthcare and government buyers to mix fingerprint, iris, and facial recognition modules within unified policy engines rather than accepting monolithic vendor stacks.
Edge-computing access controllers with localized biometric template matching are modularizing system architecture, allowing German hospital networks to distribute authentication processing across campus edge nodes rather than centralizing sensitive data. Mid-size UK commercial landlords are adopting these distributed configurations to reduce cloud dependency while maintaining audit trail centralization. The shift is compressing traditional hierarchical network designs into flat, resilient topologies.
GDPR enforcement actions by CNIL in France and ICO in the United Kingdom are hardening consent documentation requirements for biometric enrollment, forcing vendors to embed granular purpose specification and retention-limitation workflows into enrollment software. Healthcare facilities face heightened scrutiny of patient-facing biometric deployments, prompting redesign of opt-in interfaces and data-destruction protocols. The regulatory pressure is diverting R&D resources from accuracy optimization toward compliance automation.
Subscription-based access control procurement is displacing capital-heavy perpetual licensing among French and UK corporate security departments, with buyers prioritizing predictable operational expenditure over depreciated asset ownership. System integrators are responding by unbundling hardware supply from software licensing and managed services, creating tiered monthly pricing tied to door count and feature activation. The model shift concentrates recurring revenue with platform vendors while commoditizing installation labor.
Physical Access Control Market Segmentation
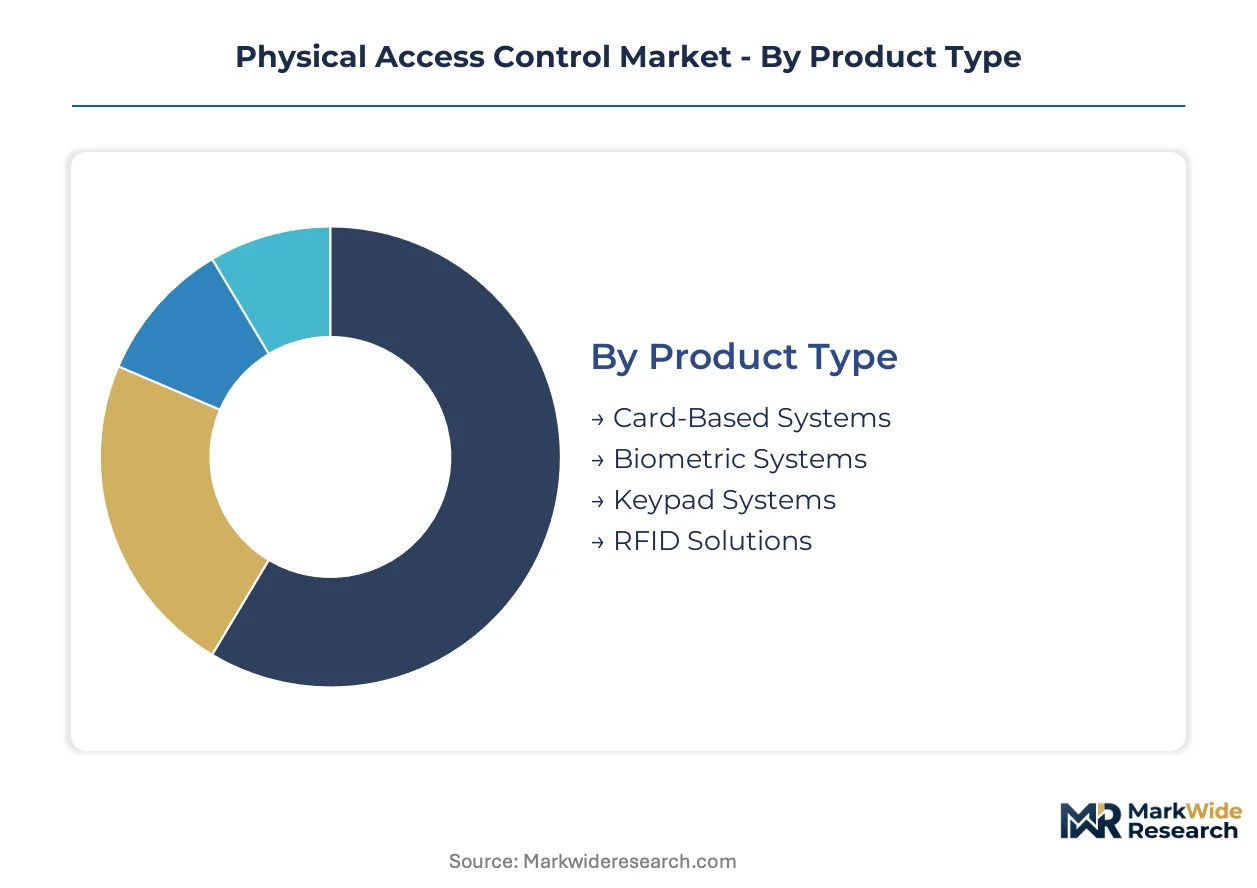
Physical access control segmentation reveals divergent technology maturities and procurement economics across credential architectures. Vendor R&D allocation and system integrator margin structures vary sharply by product category and installation topology.
Product Type:
Component supply concentrates among semiconductor foundries for credential transponders and biometric sensor modules.
- Card-Based Systems:125 kHz low-frequency and 13.56 MHz high-frequency RFID credentials dominate legacy estate renewals. German hospital networks and UK government facilities maintain substantial installed bases despite biometric displacement pressure.
- Biometric Systems:Fingerprint, iris, and facial recognition modules authenticate identity through physiological characteristics without credential transfer. Healthcare organizations across France and the United Kingdom are consolidating procurement around these systems for patient-data protection, though GDPR Article 9 compliance extends sales cycles.
- Keypad Systems:PIN-entry devices persist in cost-constrained commercial deployments where credential management overhead exceeds breach-risk tolerance.
- RFID Solutions:Contactless token architectures span access cards, key fobs, and wearable form factors with AES-128 encryption protocols.
Card-based systems absorb the bulk of installed capacity; biometric systems are expanding most quickly.
End User:
Procurement scale and security-assurance requirements concentrate demand among institutional buyers with regulatory exposure.
- Corporate Offices:Mid-size commercial real estate operators in the United Kingdom are decoupling capital expenditure from scalability through subscription-based access platforms. Mobile credential convergence with Bluetooth Low Energy and NFC protocols accelerates card replacement cycles.
- Government Facilities:Federal identity credentialing standards constrain architecture choices in US deployments, while EU AI Act risk-classification frameworks mandate algorithmic transparency for biometric systems serving European government verticals.
- Educational Institutions:Campus-wide standardization across multi-building estates favors integrated enterprise platforms with centralized policy management.
- Healthcare Organizations:Patient-data protection requirements and FDA cybersecurity guidance for connected medical devices reshape product roadmaps. German hospital consolidation generates bundled contract opportunities for platform-integrated suppliers.
Government facilities absorb the bulk of installed capacity; healthcare organizations are climbing the fastest.
Technology:
Margin concentration follows integration depth with building automation infrastructure.
- Physical Key Systems:Mechanical credential architectures persist in residential and small commercial segments where electronic infrastructure investment is uneconomical.
- Electronic Locking Systems:Electromechanical actuators with networked communication modules anchor multi-site contracts for architectural hardware suppliers. Native interoperability with HVAC and energy management platforms captures retrofit opportunities in aging European commercial stock.
- Turnstile Technology:Pedestrian flow control systems integrate credential readers with physical barriers for high-throughput environments including transportation hubs and stadium venues.
- Intercom Systems:Audio-visual visitor verification complements access control at perimeter points requiring human-in-the-loop authorization decisions.
Electronic locking systems absorb the bulk of installed capacity; cloud-integrated credential platforms are gaining share fastest.
Installation Type:
Customer IT maturity and data sovereignty requirements determine topology selection across defense, healthcare, and commercial verticals.
- Standalone Systems:Door-level controllers with localized credential databases serve small-footprint deployments without network infrastructure dependencies.
- Integrated Systems:Unified policy engines connecting access control with video surveillance and intrusion detection networks serve enterprise security operations centers.
- Cloud-Based Solutions:Decoupled capital expenditure models expand addressable markets among mid-size operators previously excluded by on-premises infrastructure costs. Edge-computing controllers with localized biometric template matching reduce latency while maintaining audit trail centralization.
- On-Premises Solutions:Data sovereignty requirements prevail in defense and critical infrastructure sectors where sensitive biometric templates must remain within jurisdictional boundaries.
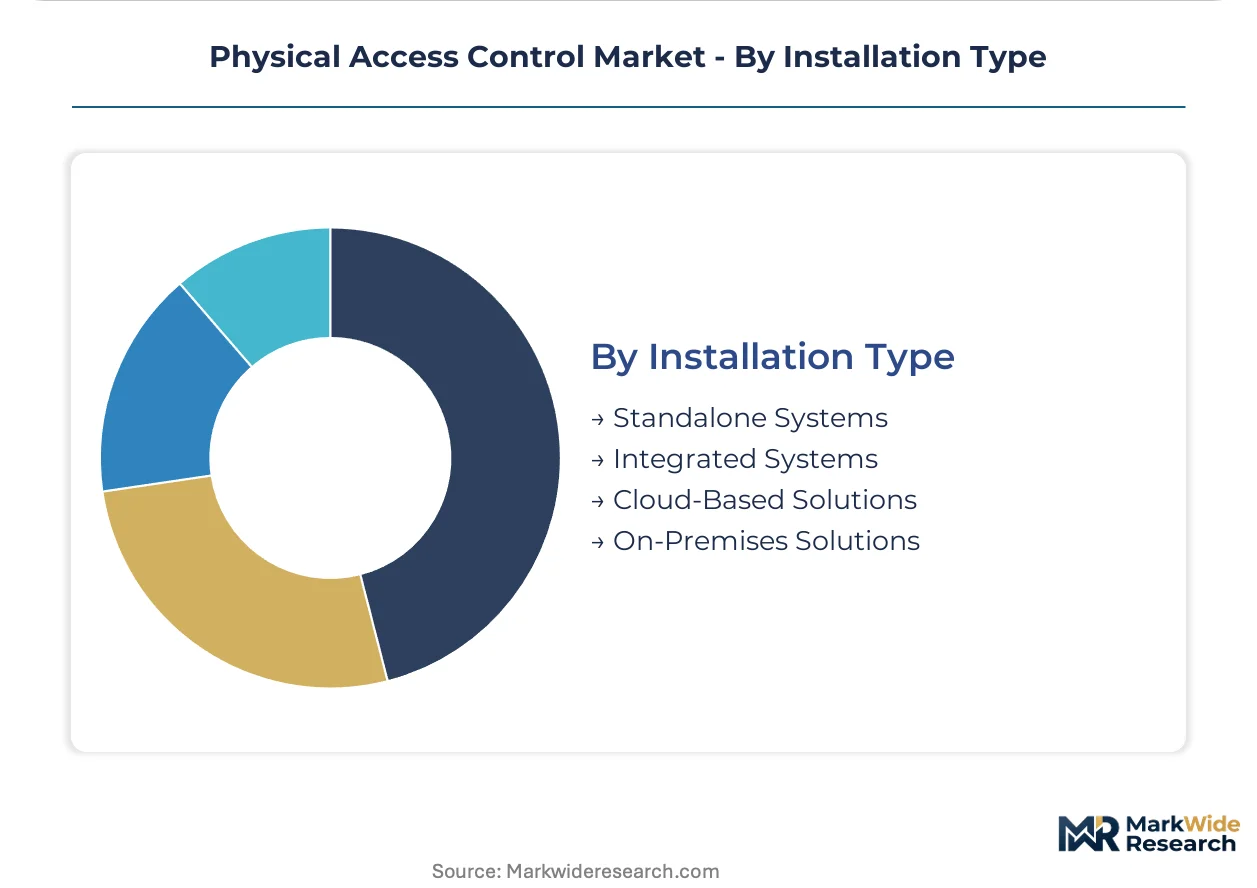
On-premises solutions absorb the bulk of installed capacity; cloud-based solutions are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundry capacity in Taiwan and South Korea anchors RFID transponder supply chains for credential manufacturing. European system integrators source 13.56 MHz high-frequency modules from these East Asian production hubs, exposing deployment timelines to semiconductor lead-time volatility. German hospital networks and UK government facilities absorb the bulk of European procurement volume.
United States
Federal identity credentialing standards drive architecture standardization across civilian agencies and defense installations. FICAM compliance mandates constrain vendor selection for biometric authentication deployments. The Washington DC-Baltimore corridor concentrates government facility upgrades, with NIH and Pentagon-adjacent campuses prioritizing multi-factor authentication integration.
Germany
Hospital consolidation across Bavaria and North Rhine-Westphalia generates bundled estate-wide access control contracts. The EU AI Act risk-classification framework mandates algorithmic transparency documentation for biometric systems serving healthcare verticals. Munich's medical technology cluster anchors procurement standardization for multi-site hospital networks.
United Kingdom
Mid-size commercial real estate operators in London and the Southeast adopt subscription-based access platforms to decouple capital expenditure from scalability. ICO enforcement actions harden consent documentation requirements for biometric enrollment workflows. The Thames Valley corridor concentrates corporate security upgrade cycles for financial services tenants.
France
CNIL regulatory pressure diverts vendor R&D resources from accuracy optimization toward GDPR Article 9 compliance automation for biometric template storage. Healthcare facilities in Île-de-France face heightened scrutiny of patient-facing enrollment interfaces. Parisian hospital networks redesign opt-in protocols and data-destruction timelines.
China
Domestic production of 125 kHz low-frequency RFID credentials supplies cost-constrained commercial deployments across manufacturing zones. MIIT cybersecurity standards for connected devices reshape product roadmaps for building automation integration. The Yangtze River Delta anchors electromechanical locking system manufacturing for export markets.
Physical Access Control Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue cloud-native platform specialization and mobile credential convergence. The vendor base stratifies across architectural hardware incumbents, electronic locking specialists, and biometric technology pure-plays. Three archetypes dominate: integrated building automation suppliers, credential-agnostic platform vendors, and component-focused sensor manufacturers. Competitive dynamics center on interoperability certification and managed services bundling.
Within the integrated platform tier, ASSA ABLOY exemplifies architectural hardware-to-software continuity that anchors multi-site healthcare contracts, while dormakaba Group occupies a position emphasizing building management infrastructure interoperability. Johnson Controls represents the cloud-based access platform archetype through building automation integration. These three entities collectively illustrate the competitive tension between hardware legacy and software-defined service models.
| Leading Market Players |
|---|
| ASSA ABLOY |
| dormakaba Group |
| Johnson Controls |
| Allegion plc |
| Honeywell International Inc. |
| Bosch Security Systems |
| Nedap N.V. |
| Suprema Inc. |
| Thales Group |
| Others |
Value Chain & Pricing Dynamics
Semiconductor wafer costs from Taiwan and South Korea flow through three pricing strata: premium biometric modules with embedded AES-256 encryption, standard 13.56 MHz RFID credentials, and economy-tier 125 kHz low-frequency tags for legacy estate renewals. German hospital networks and UK government facilities absorb the bulk of European procurement at premium tiers, while mid-size commercial landlords in France gravitate toward subscription-based SaaS models that unbundle hardware from software licensing.
Pricing Analysis
Warranty and managed-service bundling separates premium-tier suppliers from commodity credential manufacturers. Three-tier pricing structure across premium, standard, and economy levels tracks encryption certification grade and cloud-integration depth. Price differentiation hinges on FICAM compliance documentation for US federal deployments and EU AI Act algorithmic transparency certification for European healthcare verticals. Cost compression in the standard tier intensifies as Taiwanese foundry capacity constraints ease, though margins remain vulnerable to tariff exposure on high-frequency transponder imports. Mid-size UK commercial real estate operators exhibit highest price sensitivity, while German hospital consolidation waves favor least-sensitive buyers seeking estate-wide platform continuity.
Supply Chain Analysis
Domestic-content mandates in China's MIIT cybersecurity standards for connected devices are reshaping sourcing patterns for building automation integration modules. 13.56 MHz RFID transponder production concentrates in Taiwan, South Korea, and mainland China, drawing from silicon wafer feedstock and specialized antenna substrate materials. Single-source vulnerability pervades East Asian foundry capacity for biometric sensor ASICs, exposing European system integrators to lead-time volatility. Distribution runs through authorized security distributors and direct system-integrator relationships, with cloud-platform vendors increasingly bypassing traditional channel layers for end-user subscription contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU AI Act compliance costs and cloud-platform R&D investments force mid-tier credential specialists toward acquisition or niche retreat.
For Market Incumbents: Acquire edge-computing biometric calibration expertise to offset installation partner capacity constraints that delay project commissioning. Deepen backward integration into 13.56 MHz transponder supply through foundry partnerships or captive semiconductor sourcing, mitigating tariff exposure that erodes margin on fixed-price German hospital contracts. Cloud-native entrants with mobile credential convergence capabilities pose the most acute substitution threat to architectural hardware incumbents. For New Entrants and Emerging Players: Mid-size French commercial landlords with aging HVAC infrastructure represent the most penetrable buyer archetype for interoperability-focused electronic locking systems. White-space targets include subscription-based access platforms for UK real estate operators decoupling capital expenditure from scalability, and edge-computing controllers for German hospital networks seeking distributed biometric template matching. Go-to-market execution should prioritize direct engagement with facility management consortia rather than traditional security distributor channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor biometric technology pure-plays with EU AI Act certification documentation already filed, particularly those anchored in Munich's medical technology cluster or Parisian hospital network supplier rosters. Long-term viability over the next decade rests on algorithmic transparency compliance automation capabilities rather than raw accuracy optimization. The signal to watch is CNIL enforcement action velocity against non-compliant biometric enrollment workflows, which would accelerate distressed asset availability among French vendors.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Algorithmic transparency documentation unlocks German hospital network procurement cycles ahead of mid-tier competitors. |
| Edge-Computing Controller Development | Localized biometric template matching addresses GDPR Article 9 data-sovereignty requirements for French healthcare facilities. |
| Mobile Credential Convergence | Bluetooth Low Energy and NFC protocol integration captures UK commercial real estate subscription-platform demand. |
| Foundry Partnership or Captive Supply | Direct 13.56 MHz transponder sourcing mitigates Taiwanese semiconductor lead-time volatility for European system integrators. |
| Building Management Infrastructure Interoperability | Native HVAC and energy management integration captures retrofit opportunities in aging UK and German commercial stock. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with security system integrators, hospital procurement directors, commercial real estate facility managers, and biometric technology R&D leads. FDA cybersecurity guidance documents, EU AI Act implementation texts, GDPR Article 9 enforcement actions by CNIL and ICO, and FICAM federal identity credentialing standards provided regulatory boundary conditions. Bottom-up credential shipment analysis and top-down building automation expenditure estimates were triangulated against foundry production data from Taiwan and South Korea.
Granularity-level modeling tracked product-type segmentation across card-based, biometric, keypad, and RFID architectures; end-user verticals spanning corporate offices, government facilities, educational institutions, and healthcare organizations; and installation topology distinguishing standalone, integrated, cloud-based, and on-premises configurations. CAGRs were derived from installation base growth rates, replacement cycle compression, and biometric displacement penetration curves. Industry-specific inputs included German hospital consolidation transaction velocity, UK commercial real estate vacancy-adjusted security spend, and French CNIL enforcement action timelines.
Revisions become necessary when semiconductor foundry capacity constraints intensify, EU AI Act enforcement diverges from draft guidance, or quantum computing advancement accelerates AES-128 obsolescence timelines beyond current technical debt assumptions. Forecasts reflect documented assumptions regarding biometric accuracy improvement rates, cloud-platform adoption curves, and regulatory compliance cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Global Keyless Vehicle Access Control Systems Market
Access Control Systems
Latin America Pin-Based Access Control Market
Access Control Systems
Pedestrian Entrance Control System Market
Access Control Systems
Germany Access Control Market
Access Control Systems
Europe Home Security System Market
Access Control Systems
France Access Control Market
Access Control Systems
Home Control and Security Systems Market
Access Control Systems
Access Control As a Service Market
Access Control Systems
Airport Passenger Screening System Market
Access Control Systems
Perimeter Intrusion Detection Systems Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
Middle-East and Africa Airport Passenger Screening Systems Market
Access Control Systems
APAC Home Security System Market
Access Control Systems
North America Smart Locks Market
Access Control Systems
Global Digital Door Lock Systems Market
Access Control Systems
Anti-Theft System Market