
 Bangladesh Textile Manufacturing Market | 2026-2036
Bangladesh Textile Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Bangladesh Textile Manufacturing Market Outlook
Market Context
Technical outerwear and performance apparel demand is restructuring Bangladesh's traditional volume-basic mix toward higher-composition fabrics. Beximco Limited leverages backward integration from cotton spinning to finished garments, sustaining margin capture across multiple stages. Ha-meem Group anchors large-scale woven shirting capacity for European retailers, while Noman Group competes through specialized knitwear operations serving fast-fashion timelines.
Technical Definition and Segment Structure
Bangladesh textile manufacturing encompasses the conversion of natural and synthetic fibers into intermediate and finished textile goods through mechanical and chemical processes, with fabric weights typically ranging from 80 to 400 grams per square meter depending on end-use requirements. The output serves primarily as inputs for cut-make-trim apparel operations, home furnishing supply chains, and emerging industrial filtration applications. Knitted fabrics dominate export volume given the country's strength in T-shirt and pullover production, while technical textiles represent the fastest-expanding margin pool as automotive and geotextile specifications tighten. Woven fabrics maintain mature, stable demand from formalwear buyers, and non-woven segments are gaining traction in medical-grade disposable applications.
Regulatory Environment
The Bangladesh Garment Manufacturers and Exporters Association enforces fire and building safety protocols under the Remediation Coordination Cell framework, while the Department of Environment administers effluent discharge standards through the Environmental Conservation Act. The Bangladesh Bank's green refinancing scheme shapes capital access for dyeing and finishing upgrades. Stakeholders must monitor compliance cost trajectories against buyer willingness to absorb certified-premium pricing.
Market Dynamics
Waterless dyeing adoption is compressing the traditional wet-processing infrastructure that has dominated Narayanganj and Gazipur for decades. The Department of Environment's effluent discharge standards under the Environmental Conservation Act are forcing capital reallocation toward closed-loop systems, while the Bangladesh Bank's green refinancing scheme determines which mills secure upgrade financing.
Growth Catalysts
- Green refinancing access:The Bangladesh Bank's dedicated credit lines for effluent treatment and water recovery systems are unlocking capital for dyeing and finishing upgrades that were previously unfinanceable through conventional channels.
- Technical textile specifications:Automotive seating and geotextile applications are pulling Bangladeshi mills into higher-margin fabric categories with stringent performance testing requirements.
- Western sourcing consolidation:European and North American fashion retailers are consolidating vendor bases toward Dhaka-based suppliers with verified Remediation Coordination Cell compliance.
Market Restraints
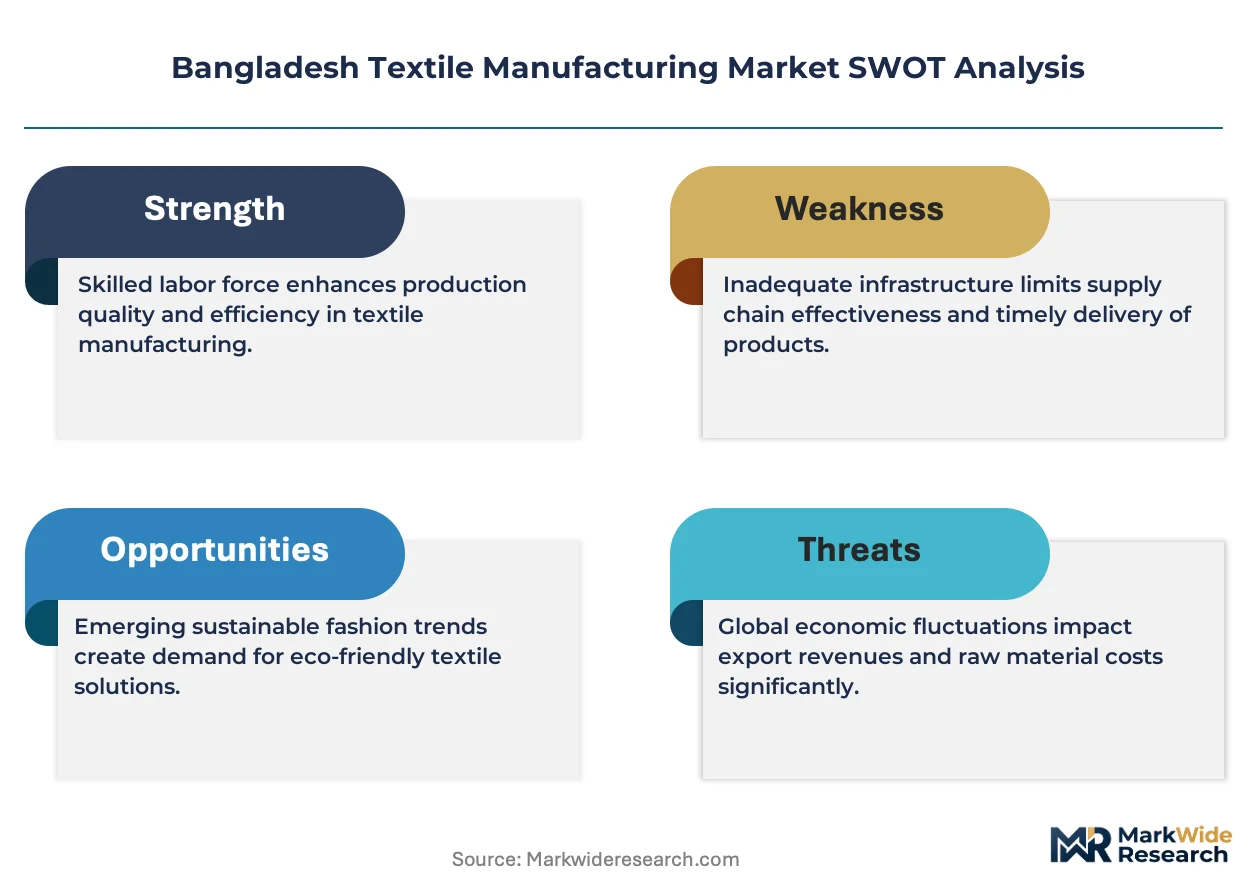
- Gas supply intermittency:Disruptions in captive power generation fuel supply force mills into expensive diesel backup, eroding the labor cost advantage that anchors Bangladesh's competitive position.
- Single-source chemical dependency:Specialty dyes and finishing auxiliaries concentrate among a narrow supplier base concentrated in China and India, exposing margins to input volatility.
- Effluent treatment capex drag:Central effluent treatment plant contributions and individual effluent treatment plant installations consume 15-20% of expansion budgets, diverting funds from productive capacity.
Strategic Opportunities
- Chittagong port corridor expansion:Underdeveloped industrial zones southeast of Dhaka offer greenfield sites with direct maritime access, bypassing the inland logistics congestion that plagues northern districts.
- Medical non-wovens:Surgical gown and disposable hygiene fabric specifications are creating entry points for spunbond and meltblown capacity that Bangladesh currently imports.
- Jeanologia-ColorZen technology convergence:The pairing of ozone finishing with cationic cotton pretreatment is enabling waterless denim production that meets premium brand sustainability requirements.
Industry Challenges
- Colorist and chemical engineer scarcity:The specialized workforce required for shade matching and recipe optimization in waterless systems remains concentrated among a handful of senior technicians, constraining technology rollout speed.
- Remediation Coordination Cell certification timelines:Fire and electrical safety audits create 6-12 month order qualification delays that conflict with fast-fashion procurement calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bangladesh Textile Manufacturing Market |
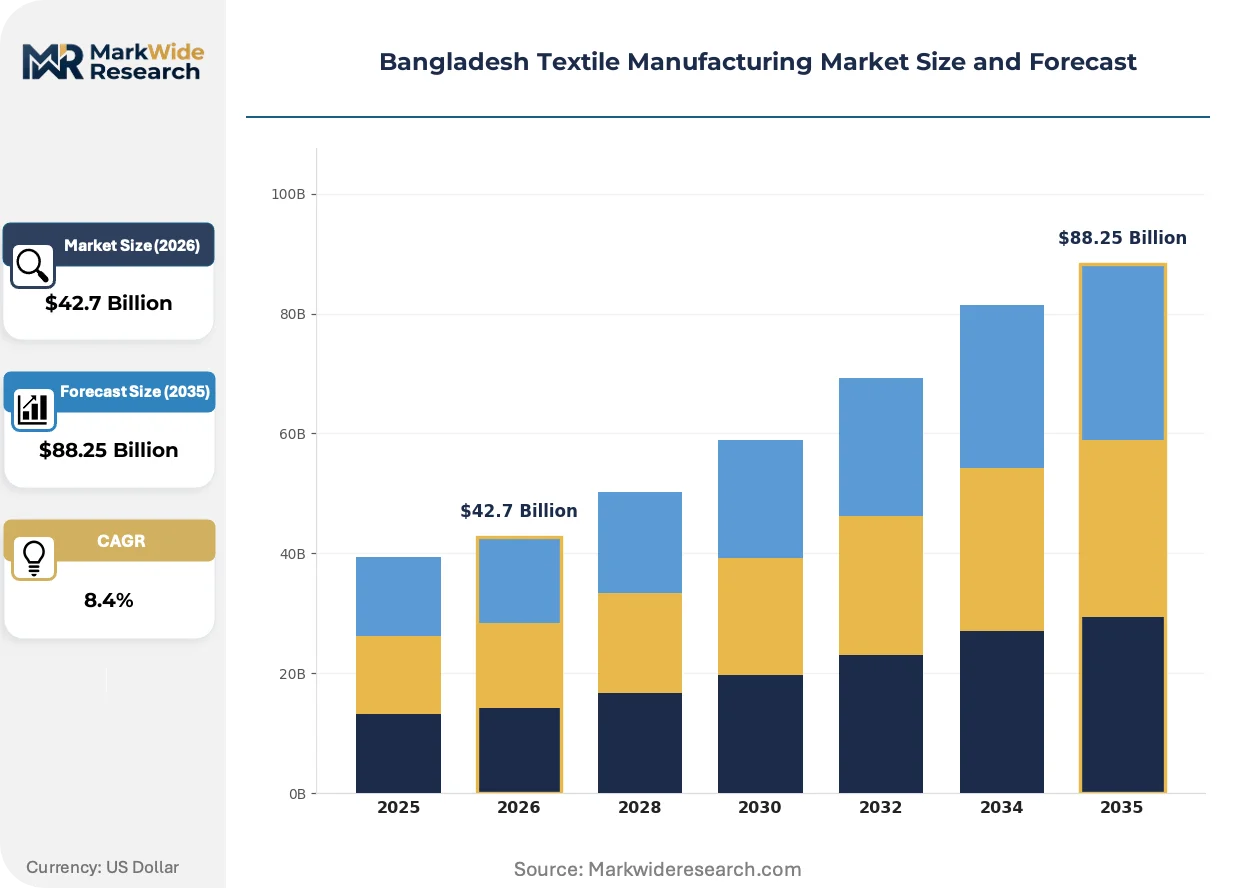
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $88.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabrics, Knitted Fabrics, Non-Woven Fabrics, Technical Textiles Application: Apparel, Home Textiles, Industrial Textiles, Healthcare Textiles End User: Fashion Brands, Retailers, Wholesalers, Exporters Technology: Spinning, Weaving, Dyeing, Finishing |
| Companies Covered | Bextex, Beximco Limited, Noman Group, Envoy Textiles, Denim Expert, Ha-meem Group, Pacific Jeans, Fakir Apparels Limited, Beximco Textile Division Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bangladesh Textile Manufacturing Market Strategic Shifts
Digitalization of color development and the convergence of sustainability verification systems are compressing traditional sample-to-production timelines while raising the technical bar for supplier qualification.
Laser finishing systems from Jeanologia are electrifying the denim washing segment by replacing manual scraping and potassium permanganate spraying with precise surface ablation. Premium European denim brands have adopted these systems at scale, and the technology is enabling Dhaka-based mills to offer distressing and vintage effects without the water intensity and chemical exposure of conventional methods.
The Department of Environment's enforcement of the Environmental Conservation Act effluent standards is mandating zero liquid discharge or near-zero configurations for new dyeing licenses. This regulatory pressure is compressing the competitive set to mills with capital access for membrane bioreactor and reverse osmosis installations, effectively filtering out smaller wet-processing operations.
Buyer sustainability scorecards are displacing transactional price negotiations as the primary vendor selection mechanism. Western fashion retailers now require Higg Index FEM scores and ZDHC MRSL conformance documentation before purchase order release, and this behavioral shift is most visible in knitwear procurement from Narayanganj-based suppliers serving mass-market European chains.
Bangladesh Textile Manufacturing Market Segmentation
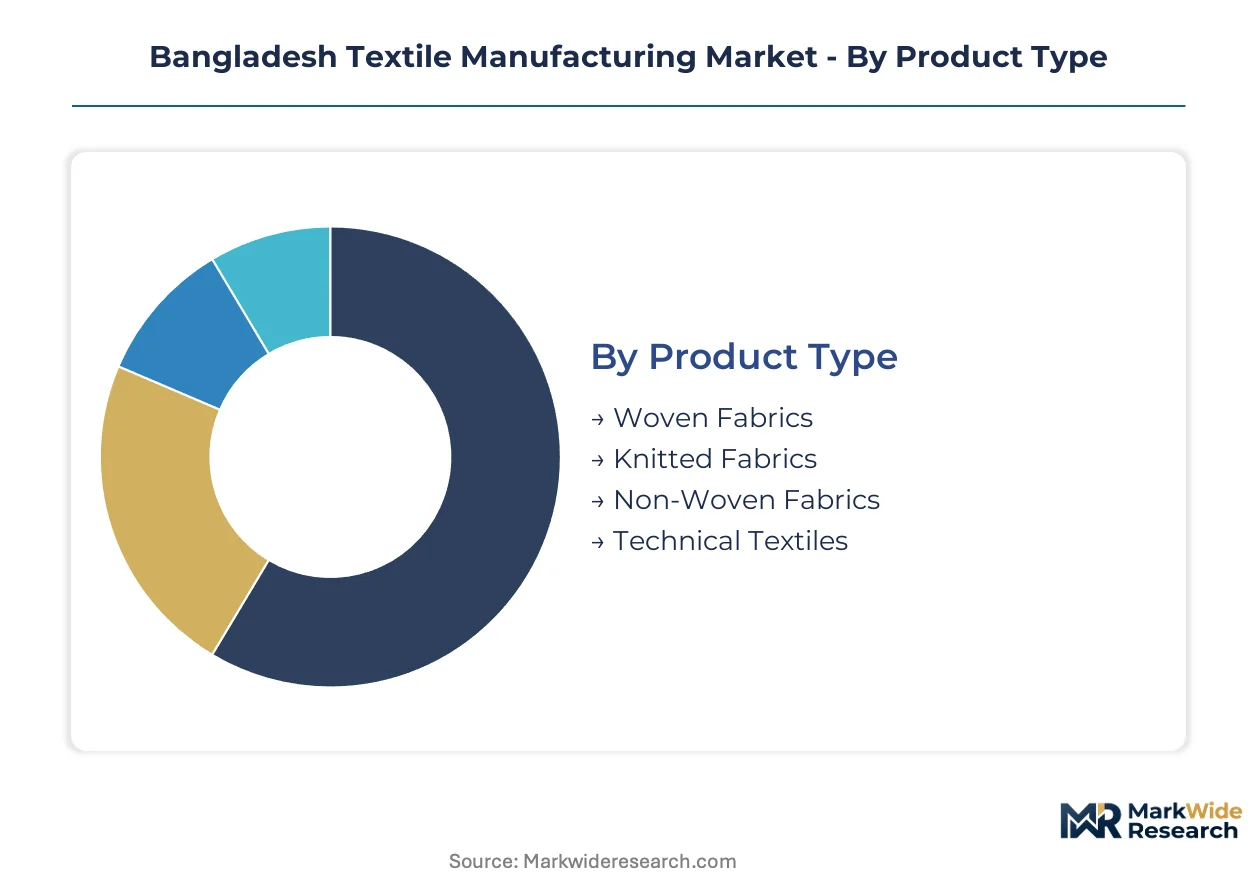
Segmentation reveals how Bangladeshi mills allocate capital across divergent technical requirements and buyer specifications. Understanding these divisions exposes where margin pools concentrate and which upgrade cycles offer the strongest returns on compliance investment.
Product Type:
Replacement cycles vary dramatically across fabric construction methods, with water-intensive processing infrastructure facing the most urgent retrofit deadlines under tightening effluent rules.
- Knitted Fabrics:Loop-structured constructions produced on circular or flat-bed machines, typically 120-200 GSM for T-shirt and pullover applications. Dhaka-based suppliers serving European fast-fashion retailers absorb the majority of volume placements, though gas supply intermittency forces costly diesel backup during peak production windows.
- Woven Fabrics:Interlaced warp-and-weft constructions ranging from 80 GSM shirting to 400 GSM canvas, requiring sizing and desizing operations that consume substantial water volumes. Ha-meem Group and similar large-scale operators anchor capacity around Gazipur, where Remediation Coordination Cell compliance certification has become a prerequisite for purchase order release from formalwear buyers.
- Non-Woven Fabrics:Spunbond and meltblown fiber webs bonded mechanically or thermally, currently imported for medical-grade applications but attracting domestic investment.
- Technical Textiles:Performance-specified fabrics for automotive seating, geotextile reinforcement, and industrial filtration with stringent testing protocols.
Volume placements concentrate in Knitted Fabrics; the faster expansion belongs to Technical Textiles.
Application:
End-use specifications dictate capital intensity, with healthcare and industrial applications demanding certification investments that apparel buyers rarely require.
- Apparel:Cut-make-trim inputs for T-shirts, denim, formal shirting, and outerwear. Narayanganj knitwear clusters and Gazipur denim operations dominate export volume, though buyer sustainability scorecards now require Higg Index FEM documentation before order confirmation.
- Home Textiles:Bed linen, curtain fabrics, and upholstery constructions with durability testing requirements. European retail consolidation favors Dhaka-based suppliers with verified fire safety protocols under the Remediation Coordination Cell framework.
- Industrial Textiles:Conveyor belting, filtration media, and composite reinforcements with specialized tensile specifications.
- Healthcare Textiles:Surgical gowns, drapes, and disposable hygiene products requiring sterile processing capabilities and biocompatibility testing that Bangladesh currently imports.
Margin capture is deepest in Healthcare Textiles; Apparel commands absolute volume leadership.
End User:
Procurement authority concentrates differently across buyer types, with fashion brands wielding specification power while exporters manage logistics complexity.
- Fashion Brands:Western labels with sustainability mandates and vendor consolidation strategies. ZDHC MRSL conformance and waterless dyeing adoption from Jeanologia and ColorZen technologies increasingly determine supplier qualification.
- Retailers:Mass-market chains with volume commitments and compressed lead times. Fast-fashion calendars conflict with Remediation Coordination Cell audit timelines, creating friction in order placement.
- Wholesalers:Intermediary buyers with price-sensitive spot purchasing and limited compliance documentation requirements.
- Exporters:Trading houses managing customs clearance and buyer relationship maintenance, particularly active in Chittagong port corridor operations.
Specification power clusters with Fashion Brands; Exporters manage the highest transaction velocity.
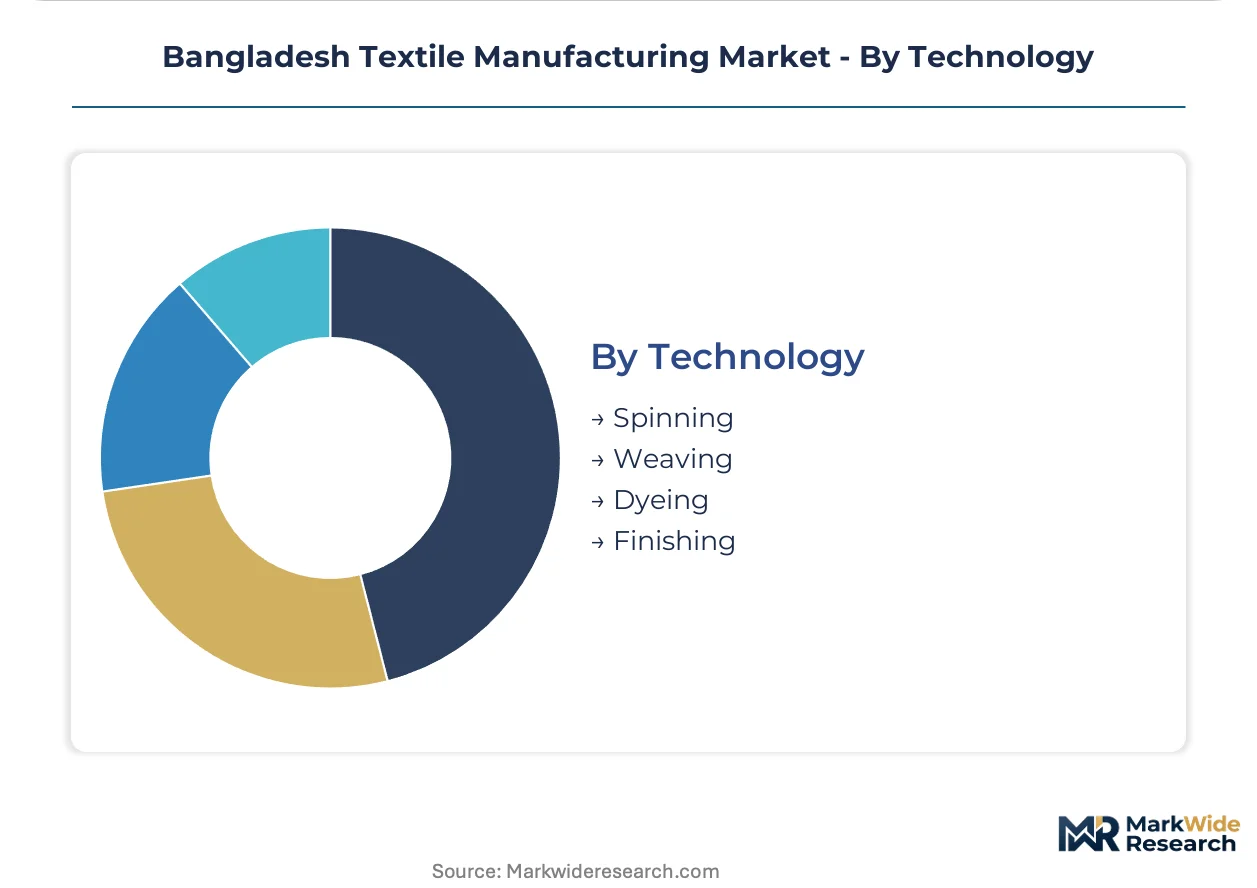
Technology:
Process-stage investments face divergent regulatory pressure, with effluent-generating operations absorbing disproportionate capital under Environmental Conservation Act enforcement.
- Dyeing:Color application through exhaust, padding, or spray methods, historically water-intensive but now subject to zero liquid discharge mandates. Department of Environment licensing requires membrane bioreactor or reverse osmosis installations that consume 15-20% of expansion budgets.
- Finishing:Surface modification through mechanical or chemical means including laser ablation and ozone treatment. Jeanologia systems enable waterless denim distressing that meets premium brand sustainability requirements without potassium permanganate exposure.
- Spinning:Fiber conversion into yarn through ring, rotor, or air-jet methods, with Beximco Limited leveraging backward integration into cotton spinning for margin capture.
- Weaving:Interlacing warp and weft threads on shuttle or shuttleless looms, concentrated in Gazipur shirting operations.
Capital intensity peaks in Dyeing; the steepest technology shift is occurring in Finishing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bangladesh Economic Zones Authority operates eight active public EPZs that concentrate textile investment through 10-year tax holidays and duty-free machinery imports.
Dhaka Division
Apparel export demand from European fast-fashion retailers drives fabric consumption in the capital region. The Bangladesh Bank's green refinancing scheme channels capital toward effluent treatment upgrades in dyeing clusters. Gazipur and Narayanganj host the densest concentration of knitwear and denim operations, where Remediation Coordination Cell certification has become mandatory for purchase order release.
Chittagong Division
Deep-water port access attracts greenfield spinning and weaving investments seeking direct maritime logistics. The Chittagong Port Authority's modernization program reduces container dwell times for cotton imports. Karnaphuli EPZ and adjacent private zones absorb capacity expansion from Dhaka-based groups diversifying geographic risk.
Rajshahi Division
Proximity to Indian border trade routes positions the northwest for cotton yarn imports and cross-border chemical sourcing. The Bangladesh Trade and Tariff Commission monitors anti-dumping measures on Indian textile inputs. Bogra and Naogaon districts concentrate smaller weaving operations serving domestic shirting and lungi markets.
Khulna Division
Underdeveloped industrial infrastructure offers lower land costs for integrated textile parks. The Bangladesh Economic Zones Authority promotes Mongla EPZ as an alternative to congested Dhaka corridors. Jashore district attracts early-stage investments in non-woven medical textile capacity targeting export diversification.
Bangladesh Textile Manufacturing Market Competitive Environment
Top-tier vendors anchor large-scale integrated operations, while mid-tier specialists compete through compliance certification and fast-fashion responsiveness. The vendor base stratifies across backward-integrated conglomerates, standalone dyeing and finishing houses, and specialized knitwear operators. Three archetypes dominate: spinning-to-garment integrated groups, wet-processing specialists with zero liquid discharge capabilities, and denim-focused mills with laser finishing technology. Competitive moves concentrate on capacity expansion in Chittagong corridor zones and technology licensing partnerships for waterless dyeing systems.
Among Dhaka-based integrated groups, Beximco Limited and Ha-meem Group occupy positions exemplifying backward integration from fiber to finished fabric. Bextex and Noman Group represent specialized knitwear and woven operations respectively, anchoring the mid-tier segment where Remediation Coordination Cell compliance and buyer sustainability scorecards determine vendor qualification. These named entities illustrate how scale and certification investments stratify competitive positioning.
| Leading Market Players |
|---|
| Bextex |
| Beximco Limited |
| Noman Group |
| Envoy Textiles |
| Denim Expert |
| Ha-meem Group |
| Pacific Jeans |
| Fakir Apparels Limited |
| Beximco Textile Division Limited |
| Others |
Value Chain & Pricing Dynamics
Cotton futures on the Intercontinental Exchange and benchmark polyester staple fiber indices from China set the baseline cost structure that cascades through Bangladesh's textile manufacturing tiers. Gas supply intermittency forces mills into expensive diesel backup, compressing margins and stratifying pricing power between integrated groups with captive power and standalone processors exposed to spot fuel markets.
Pricing Analysis
Lead-time premiums dominate vendor selection, with European fast-fashion retailers paying 8-15% above base rates for 45-day turnaround versus 90-day standard cycles. Three-tier pricing structure across premium, standard, and economy levels separates ZDHC MRSL-certified mills with Jeanologia waterless systems from conventional wet-processors and spot-market traders. Price differentiation hinges on Remediation Coordination Cell certification status and backward integration depth. Pricing pressure stems from gas supply intermittency eroding the labor cost advantage. Spot buyers and wholesalers exhibit highest price sensitivity; sustainability-mandated fashion brands show lowest.
Supply Chain Analysis
Reverse logistics for defective fabric lots and sample returns flows through Dhaka-based trading houses that consolidate rejected inventory for secondary market disposal. Raw cotton draws from India, the United States, and Brazil; specialty dyes and finishing auxiliaries rest on concentrated Chinese and Indian chemical suppliers. Single-source chemical dependency creates vulnerability to input volatility and tariff exposure. Distribution runs through Chittagong port for deep-water access, with inland logistics from Gazipur and Narayanganj clusters feeding cut-make-trim operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Environmental Conservation Act enforcement is filtering out smaller wet-processing operations, creating consolidation opportunities for capital-rich integrated groups. The Department of Environment's zero liquid discharge mandates favor mills with membrane bioreactor installations and Bangladesh Bank green refinancing access.
For Market Incumbents: Cement market position through Chittagong corridor capacity expansion and Jeanologia laser finishing technology licensing. Prioritize backward integration into cotton spinning to capture margin across multiple production stages. Gas supply intermittency and effluent treatment capex drag threaten standalone dyeing houses; integrated groups with captive power and closed-loop water systems hold structural advantage. For New Entrants and Emerging Players: Direct-to-brand digital sampling platforms offer entry routes that bypass traditional exporter intermediaries. Target medical non-wovens in Khulna Division's underdeveloped zones where sterile processing capabilities remain scarce. White-space exists in technical textiles for automotive seating and geotextile applications with performance testing protocols. Sustainability-verified small-batch production serves premium European denim brands seeking waterless supply alternatives. For Investors and Strategic Acquirers: Distressed-cycle entries favor wet-processing specialists with partial effluent treatment infrastructure in Gazipur and Narayanganj. Mid-cap mills facing 15-20% capex burdens for zero liquid discharge compliance present acquisition targets with retrofit upside. Long-term viability centers on waterless technology adoption and Remediation Coordination Cell certification completion. Monitor Bangladesh Bank green refinancing disbursement rates as inflection indicator for capital-access differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Zero Liquid Discharge Retrofit | Department of Environment licensing mandates membrane bioreactor installations for dyeing operations. |
| Chittagong Corridor Expansion | Deep-water port access reduces inland logistics congestion and cotton import dwell times. |
| Jeanologia Technology Licensing | Ozone finishing and laser ablation enable waterless denim production for premium brand compliance. |
| Backward Integration into Spinning | Captive cotton yarn production insulates margin from raw material price volatility. |
| Medical Non-Wovens Capacity Buildout | Spunbond and meltblown investment targets surgical gown imports currently sourced externally. |
Study Parameters
Trade statistics from the Bangladesh Bank, customs records via the National Board of Revenue, and BGMEA export shipment data formed the secondary backbone for volume and value estimation. Primary interviews with dyeing house operations managers, European retail procurement leads, chemical supplier technical directors, and Remediation Coordination Cell audit coordinators validated secondary findings. Bottom-up mill capacity surveys and top-down export value reconciliation provided cross-checks across the analysis window.
Historical trendline analysis of fabric export volumes and capital expenditure patterns informed the projection framework. Segmentation modeling covered product type, application, end user, and technology dimensions with specific weighting for effluent treatment compliance tiers. CAGRs derived from regression analysis against green refinancing disbursement trajectories and Western sourcing consolidation indices. Gas supply reliability assumptions and Jeanologia adoption curves served as industry-specific sensitivity inputs.
The model holds under continued Environmental Conservation Act enforcement and Bangladesh Bank green credit availability; deviation in gas supply normalization or Remediation Coordination Cell audit suspension would shift competitive dynamics. Forecasts reflect assumptions about technology adoption timelines and regulatory stringency maintenance. Practitioners should monitor green refinancing allocation rates and European buyer sustainability scorecard weighting changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Upholstery Fabric Market
Yarn and Fabric Manufacturing
Denim Fabric Market
Yarn and Fabric Manufacturing
Canvas and Muslin Bags Market
Yarn and Fabric Manufacturing
Europe Textile Market
Yarn and Fabric Manufacturing
Knitted Fabric Market
Yarn and Fabric Manufacturing
Flat Knitting Machine Market
Yarn and Fabric Manufacturing
Fancy Yarn Market
Yarn and Fabric Manufacturing
Fiberglass Fabric Market
Yarn and Fabric Manufacturing
Indonesia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Nylon 6 Filament Yarn Market
Yarn and Fabric Manufacturing
Cotton Bags Market
Yarn and Fabric Manufacturing
Europe Textile Fabrics Market
Yarn and Fabric Manufacturing
Ring Spinning Frame Market
Yarn and Fabric Manufacturing
Printed Textiles Market
Yarn and Fabric Manufacturing
Linen Fabric Market
Yarn and Fabric Manufacturing
Carpet Yarn Market