
 Asia- Pacific Food Micronized Salt Market | 2026-2036
Asia- Pacific Food Micronized Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Asia- Pacific Food Micronized Salt Market Outlook
The Asia-Pacific food micronized salt market is consolidating around a widening gap between premium specialty grades and commodity refined salt. Cargill Incorporated leverages its integrated supply chains to dominate premium micronized offerings for processed food manufacturers. Tata Chemicals anchors its position through captive brine reserves and sustained investment in particle-size control technology. K+S Aktiengesellschaft competes on European-origin brand strength, while local operators navigate tighter margin pools in bulk refined segments.
Food micronized salt consists of sodium chloride milled to particle sizes typically below 100 microns, enabling rapid dissolution and uniform distribution in processed food matrices. The milling process—often employing pin mills or fluid energy mills with air classification—produces controlled geometry essential for brining, curing, and flavor delivery in industrial food production. Refined salt and sea salt categories command the largest volume positions, though Himalayan pink salt differentiates on trace-mineral positioning for premium snack foods and health-oriented retail channels. Bakery and meat processing applications lead demand structurally, with meat processing representing the fastest-growing application as Southeast Asian processors adopt Western-style curing and emulsification techniques.
FSSAI standards in India and China's SAMR food-grade sodium chloride regulations shape product specifications, testing protocols, and import clearance requirements across the region. EFSA-aligned Codex standards influence export-oriented producers in Australia and New Zealand, while Japan's Ministry of Health maintains distinct purity thresholds affecting cross-border formulation compatibility. Stakeholders must monitor evolving iodization mandates and sodium-reduction policy signals from health ministries, as these will determine reformulation investments and premium-grade demand trajectories.
Market Dynamics
The Asia-Pacific food micronized salt market is bifurcating sharply between precision-grade specialty salts for processed food manufacturers and undifferentiated bulk refined salt, with FSSAI iodization mandates and SAMR purity standards accelerating compliance costs that only scaled processors can absorb.
Growth Catalysts
- Urban food retail expansion:Quick-service restaurant chains across India and China are scaling procurement of precision-grade salt ingredients for standardized flavor profiles across franchise networks.
- FSSAI iodization mandates:India's tightening food-grade purity requirements are forcing domestic and imported salt suppliers to upgrade milling and testing infrastructure, consolidating demand toward compliant producers.
- Western-style curing adoption:Southeast Asian meat processors are absorbing larger volumes of micronized salt to achieve uniform particle distribution in emulsified and cured products.
Market Restraints
- Energy cost volatility:Fluid energy milling and air classification processes are electricity-intensive, exposing processors to tariff fluctuations that compress margins on standard-grade output.
- Brine reserve concentration:Captive access to high-purity subterranean brine deposits concentrates in western India and select Chinese provinces, creating geographic supply vulnerability.
- Potassium chloride substitution:Sodium-reduction formulations in health-oriented snack foods are partially displacing micronized salt in premium retail channels.
Strategic Opportunities
- Vietnam and Indonesia penetration:Underdeveloped precision-salt infrastructure in these markets creates first-mover advantage for processors establishing local milling partnerships.
- Clean-label Himalayan positioning:Trace-mineral salt variants command shelf-space premiums in Australian and New Zealand health-food retail channels.
- PLI scheme alignment:India's production-linked incentive framework for food processing equipment indirectly subsidizes domestic salt micronization capacity expansion.
Industry Challenges
- Particle-size certification timelines:FSSAI and SAMR laboratory validation for sub-100-micron specifications extends product launch cycles by four to six months.
- Legacy ERP integration:Batch traceability requirements for iodization compliance force mid-scale processors to reconfigure manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia- Pacific Food Micronized Salt Market |
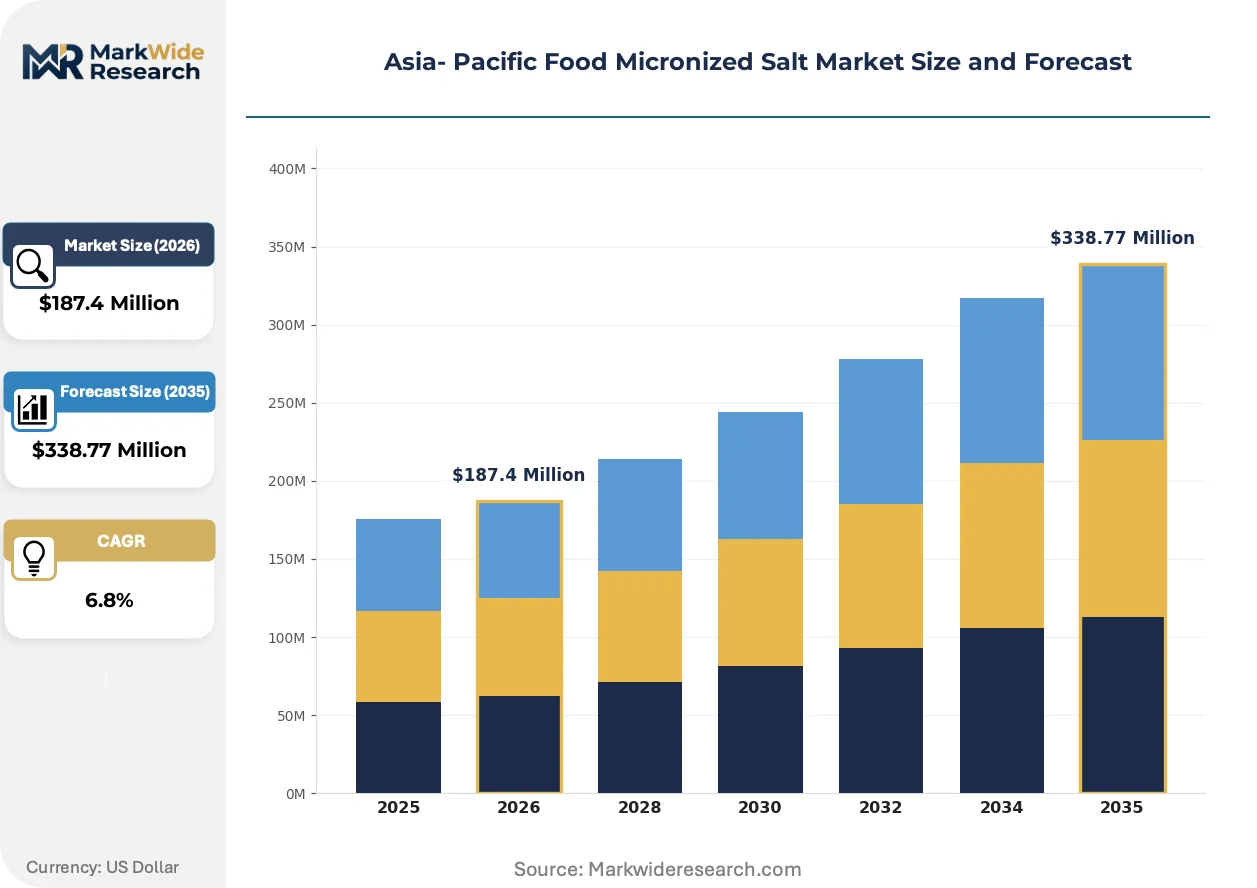
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Salt, Sea Salt, Himalayan Pink Salt, Table Salt Application: Bakery, Dairy Products, Meat Processing, Snack Foods Packaging Type: Sachets, Bulk Bags, Containers, Bottles End User: Household, Food Service, Food Retail, Industrial |
| Companies Covered | Cargill Incorporated, Tata Chemicals, Morton Salt, Compass Minerals, K+S Aktiengesellschaft, Tata Salt, DuPont, ADM, Tate & Lyle, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia- Pacific Food Micronized Salt Market Strategic Shifts
Precision milling technology and regulatory data transparency are restructuring how salt processors compete, with particle-size control becoming a technical differentiator rather than a commodity specification.
Pin mills with integrated air classification systems are absorbing capital investment from Southeast Asian processors seeking to replace imported precision-grade supply with domestic production. Thai and Vietnamese meat processors are adopting these systems at accelerating pace to meet export-market particle-distribution specifications. The technology is absorbing market share previously held by European-origin specialty salt imports.
China's SAMR has tightened food-grade sodium chloride purity thresholds, requiring expanded heavy-metal and insoluble-matter testing protocols for both domestic production and import clearance. This regulatory shift is forcing smaller Chinese processors to outsource testing to certified third-party laboratories or exit the food-grade segment entirely. Australian and New Zealand export-oriented producers are aligning testing protocols with EFSA-aligned Codex standards to maintain cross-border formulation compatibility.
Direct-procurement relationships between quick-service restaurant chains and salt processors are displacing traditional ingredient distributor intermediaries in India and China. Chains with standardized brining and curing protocols are negotiating multi-year supply agreements with particle-size guarantees. This pattern is most visible in the Bangalore and Shanghai metropolitan clusters where franchise density concentrates purchasing power.
Asia- Pacific Food Micronized Salt Market Segmentation
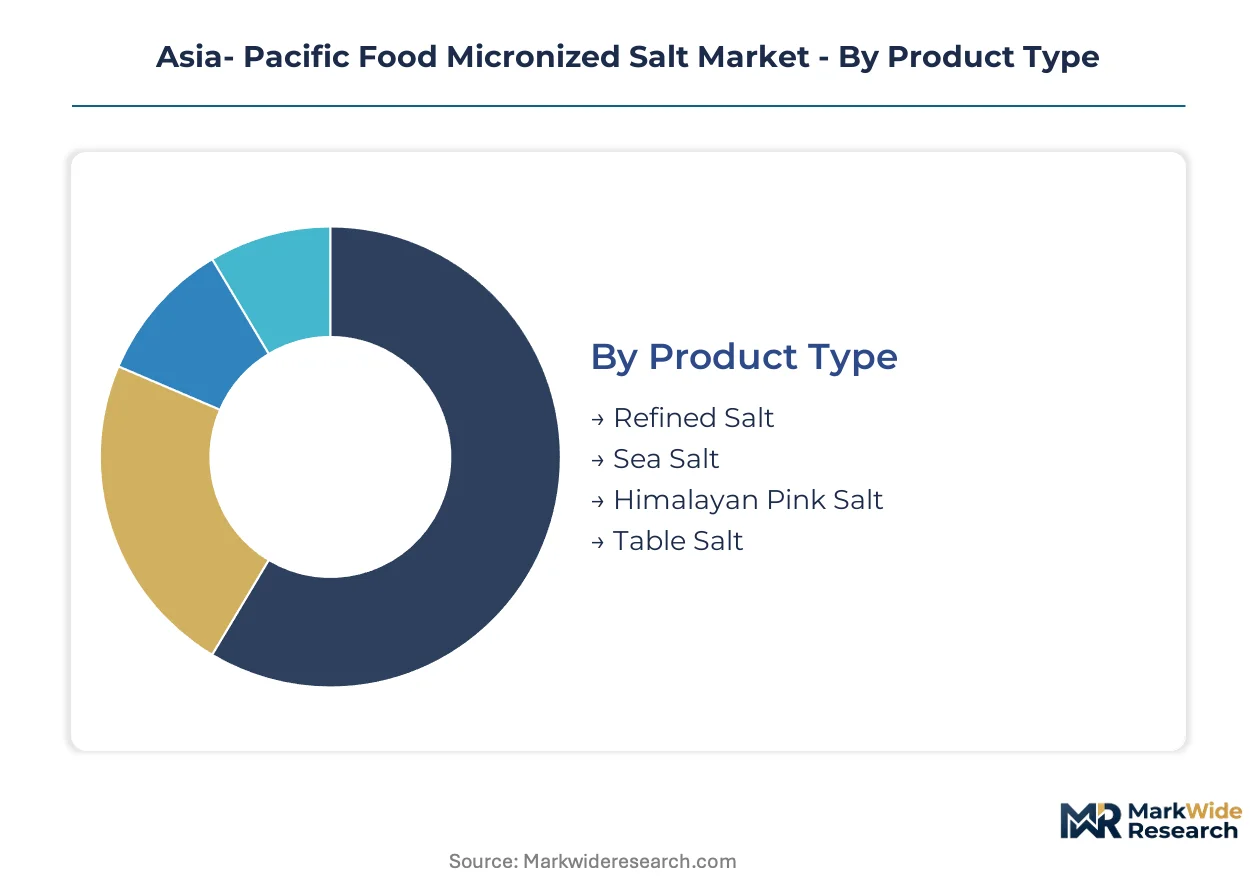
Segmentation in the Asia-Pacific food micronized salt market reveals how particle-size precision, regulatory compliance, and distribution format create distinct competitive arenas. Processors configure their product portfolios across these dimensions to capture margin pools in industrial bulk supply versus premium retail positioning.
Product Type:
Customization intensity varies sharply across this category, from commodity-grade bulk supply to trace-mineral differentiated positioning.
- Refined Salt:Sodium chloride processed through vacuum evaporation or solar evaporation to achieve 99%+ purity with controlled moisture content. India's FSSAI iodization mandates concentrate procurement toward processors with certified milling infrastructure in Gujarat and Rajasthan. Leading the category by volume: Refined Salt. Growing fastest: Himalayan Pink Salt.
- Sea Salt:Harvested from evaporated seawater with residual trace minerals influencing flavor profile and dissolution characteristics. Southeast Asian meat processors favor sea salt variants for artisanal cured products, though supply consistency lags refined alternatives.
- Himalayan Pink Salt:Mined from ancient marine deposits in Pakistan's Khewra region, commanding shelf-space premiums in Australian health-food retail through mineral-content marketing. Expanding most quickly as clean-label positioning penetrates premium snack channels.
- Table Salt:Fine-grained refined salt with anti-caking additives for direct consumer use, facing margin compression as private-label concentration intensifies in India and China supermarket channels.
Volume leadership rests with standardized grades. Premium expansion concentrates in trace-mineral variants.
Application:
End-use differentiation tracks the technical sophistication of dissolution requirements and brining protocol standardization.
- Meat Processing:Emulsified and cured products demand sub-100-micron particle distribution for uniform salt penetration and protein extraction. Vietnam and Indonesia processors are absorbing larger volumes as Western-style curing techniques displace traditional preservation methods. Climbing the fastest as Southeast Asian export-oriented facilities scale precision-grade procurement.
- Bakery:Rapid-dissolution requirements in dough mixing and fermentation control favor micronized grades with tight particle-size distribution. Chinese industrial bakeries concentrate demand in Shanghai and Guangzhou metropolitan clusters.
- Dairy Products:Cheese brining and butter manufacturing require food-grade purity with controlled calcium and magnesium levels to prevent flavor defects. Australian and New Zealand dairy exporters align specifications with EFSA-aligned Codex standards.
- Snack Foods:Surface application and seasoning adhesion drive demand for specific particle geometries, with sodium-reduction formulations partially displacing conventional salt in health-oriented retail channels.
Structural demand weight: Meat Processing and Bakery combined. Steepest trajectory: Meat Processing.
Packaging Type:
Format selection maps directly to customer scale and inventory velocity requirements across the value chain.
- Bulk Bags:Multi-ton flexible intermediate bulk containers dominate industrial procurement from quick-service restaurant chains and meat processors. India's PLI scheme for food processing equipment indirectly subsidizes domestic bulk handling infrastructure.
- Sachets:Single-serve portions concentrate in food service and airline catering channels across Southeast Asia, with FSSAI-mandated iodization labeling complicating small-format compliance.
- Containers:Rigid packaging for household and small food service quantities, facing substitution pressure from flexible formats in cost-sensitive Indian retail.
- Bottles:Shaker formats for table salt and specialty seasoning blends, concentrated in premium retail positioning through Australian and New Zealand supermarket channels.
Industrial procurement favors bulk formats. Premium retail differentiation concentrates in sachet and bottle convenience positioning.
End User:
Customer type determines specification stringency, contract structure, and margin capture potential.
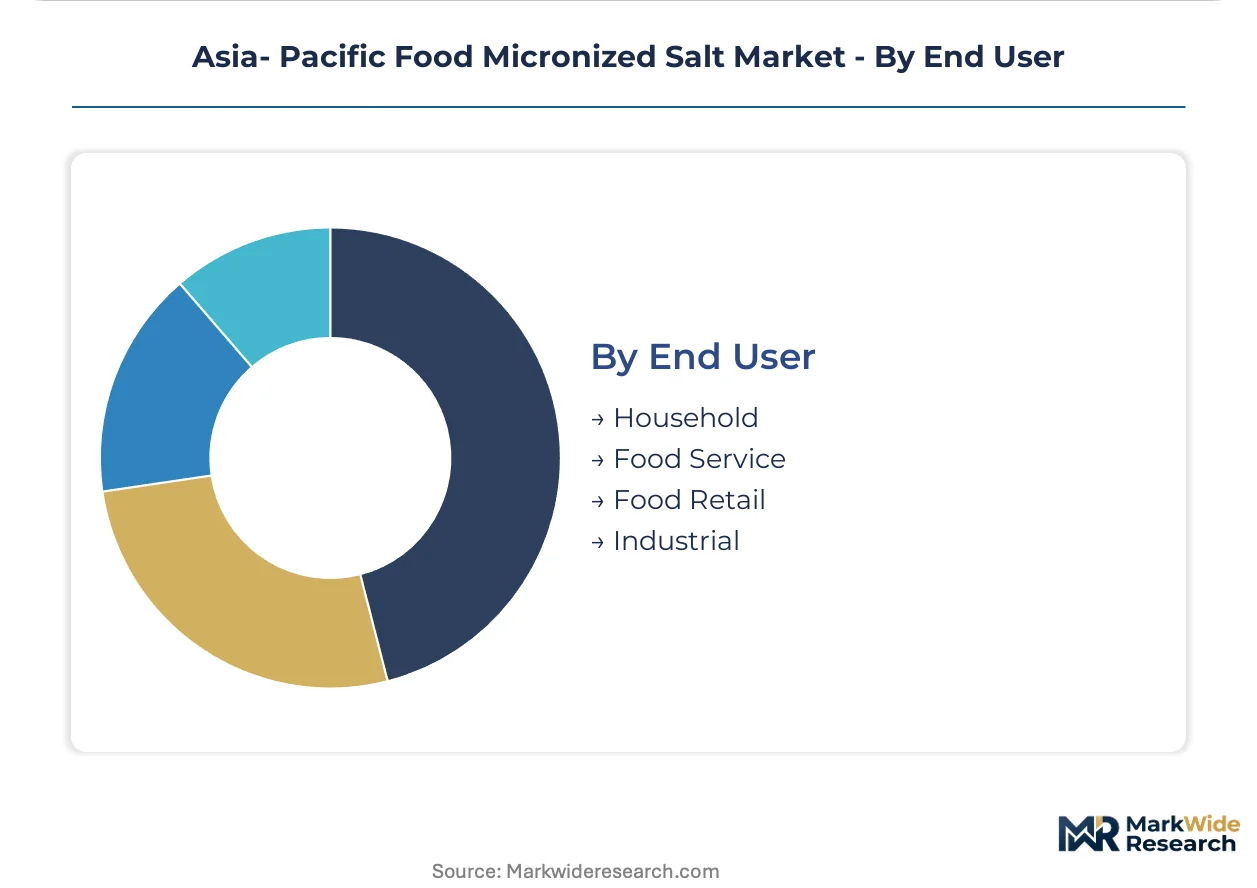
- Industrial:Processed food manufacturers and meat processors negotiate multi-year supply agreements with particle-size guarantees and batch traceability requirements. Direct procurement relationships are displacing traditional distributor intermediaries in Bangalore and Shanghai clusters.
- Food Service:Quick-service restaurant chains standardize salt specifications across franchise networks, creating concentrated purchasing power in India and China urban expansion corridors.
- Food Retail:Supermarket and hypermarket private-label concentration intensifies price competition, with clean-label Himalayan positioning offering margin escape in premium tiers.
- Household:Direct consumer purchase of table salt and specialty variants, governed by FSSAI and SAMR iodization mandates that constrain product differentiation.
Contract value concentrates in Industrial procurement. Volume expansion fastest in Food Service channel standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangalore's quick-service restaurant corridor concentrates procurement power for precision-grade salt as franchise networks standardize brining protocols across South India.
India
Gujarat and Rajasthan's captive brine reserves supply vacuum-evaporated refined salt to meat processors adopting Western curing techniques. FSSAI iodization mandates tighten compliance costs, consolidating procurement toward certified milling infrastructure. Mumbai-Pune industrial belt anchors domestic demand from packaged food manufacturers scaling particle-size-controlled formulations.
China
Shanghai and Guangzhou metropolitan clusters drive bakery and dairy applications requiring sub-100-micron distribution. SAMR purity thresholds for heavy-metal and insoluble-matter testing force smaller processors toward third-party laboratory outsourcing. Yangtze River Delta food manufacturers negotiate direct-procurement agreements with salt suppliers, bypassing traditional distributor channels.
Vietnam
Export-oriented meat processing facilities in Ho Chi Minh City corridor absorb accelerating volumes of micronized salt for emulsified products. Underdeveloped domestic milling infrastructure creates first-mover openings for processors establishing local pin-mill partnerships. Binh Duong and Dong Nai provinces concentrate foreign-invested food manufacturing driving specification-grade demand.
Indonesia
Jakarta-Bandung manufacturing belt generates structural demand from instant noodle and snack seasoning applications. Limited precision-salt production capacity leaves processors dependent on imported supply chains vulnerable to shipping cost volatility. Batam and Bintan free trade zones attract salt handling infrastructure investment targeting ASEAN export markets.
Australia
Sydney and Melbourne health-food retail channels command shelf-space premiums for Himalayan pink salt variants positioned on trace-mineral content. EFSA-aligned Codex standards govern export-oriented dairy salt specifications for cheese brining operations. Queensland meat processors align procurement with Japanese Ministry of Health purity thresholds for cross-border formulation compatibility.
Asia- Pacific Food Micronized Salt Market Competitive Environment
Capital-heavy producers compete with asset-light distributors across a bifurcated structure separating integrated brine-to-milling operators from trading-dependent importers. The market consolidates around three strategic tiers: captive-reserve integrated processors, European-origin specialty importers, and regional trading houses navigating compliance cost escalation. Dominant competitive moves include backward integration into brine reserve control and direct-procurement partnership formation with quick-service restaurant chains.
Within the integrated-processor tier, Cargill Incorporated and Tata Chemicals exemplify divergent geographic anchoring strategies. Cargill's North American-origin supply chains position it as a premium-grade importer serving Southeast Asian meat processors. Tata Chemicals represents the captive-reserve archetype through its Gujarat-based brine access and sustained milling infrastructure investment. K+S Aktiengesellschaft occupies the European-specialist position, competing on origin-brand strength for export-oriented Australian and New Zealand dairy applications.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Tata Chemicals |
| Morton Salt |
| Compass Minerals |
| K+S Aktiengesellschaft |
| Tata Salt |
| DuPont |
| ADM |
| Tate & Lyle |
| Others |
Value Chain & Pricing Dynamics
Quick-service restaurant chain procurement standardization across India and China is forcing salt processors to guarantee sub-100-micron particle distribution, concentrating supply relationships toward integrated brine-to-milling operators with certified laboratory infrastructure and compressing margins for undifferentiated bulk traders.
Pricing Analysis
Yield-guaranteed contract pricing anchors the Asia-Pacific food micronized salt market, with meat processors and bakery manufacturers paying premiums for batch-certified particle distribution that eliminates dissolution variability in automated brining systems. Three-tier pricing structure across precision-grade specialty, certified food-grade standard, and commodity refined levels tracks FSSAI and SAMR compliance certification status rather than sodium chloride purity alone. Cost compression in standard-grade segments is intensifying because fluid energy milling electricity tariffs fluctuate across Gujarat and Jiangsu provinces. Industrial quick-service restaurant chains exhibit lowest price sensitivity due to franchise network standardization requirements, while household retail channels face acute price competition from private-label concentration.
Supply Chain Analysis
Direct-to-industrial channels handle hyperscale buyer demand from meat processing and bakery manufacturing clusters, displacing traditional ingredient distributor intermediaries in Bangalore and Shanghai metropolitan corridors. Captive supply of high-purity brine concentrates in Gujarat, Rajasthan, and select Chinese provinces along the Yangtze River Delta, with Australian and New Zealand export-oriented producers drawing from coastal solar evaporation infrastructure. Fluid energy milling equipment, air classification systems, and certified third-party testing capacity constitute critical input dependencies. Single-source vulnerability runs through subterranean brine reserve access controlled by integrated processors, constraining supply flexibility for trading-dependent importers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive brine reserve scarcity and FSSAI-mandated iodization laboratory certification bottlenecks are propping pricing power for integrated processors while squeezing margin pools for asset-light trading houses dependent on spot procurement.
For Market Incumbents: Anchor particle-size control technology leadership through sustained pin-mill and air classification capital deployment in Vietnam and Indonesia corridors where Western-style curing adoption is accelerating. Secure backward integration into captive brine reserves or long-term offtake agreements with Gujarat and Rajasthan deposit holders to defend against potassium chloride substitution threats in health-oriented snack channels. Reinforce direct-procurement partnerships with quick-service restaurant chains through multi-year supply agreements embedding batch traceability guarantees. For New Entrants and Emerging Players: Launch via local milling partnerships in Ho Chi Minh City and Binh Duong provinces where export-oriented meat processing facilities face underdeveloped domestic precision-salt infrastructure. Target Vietnamese and Indonesian meat processing applications as the most penetrable segment, leveraging first-mover advantage in pin-mill technology transfer arrangements with Southeast Asian processors seeking to displace European-origin specialty imports. Pursue clean-label Himalayan pink salt positioning for Australian and New Zealand health-food retail channels as differentiated go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors integrated processors with captive brine reserves and certified milling infrastructure over trading-dependent distribution models. Long-term viability across the analysis window rests on regulatory compliance capability rather than commodity scale, positioning Gujarat-based operators with FSSAI certification and particle-size control technology as acquisition targets. Monitor SAMR purity threshold enforcement intensity as inflection indicator for Chinese market consolidation velocity and import substitution pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Reserves | Captive supply access in Gujarat and Rajasthan insulates processors from raw material volatility and import dependency. |
| Pin-Mill Technology Deployment | Domestic precision milling capacity in Vietnam and Indonesia displaces European-origin specialty salt imports for meat processors. |
| FSSAI Certification Investment | Certified iodization and particle-size laboratory infrastructure consolidates procurement toward compliant producers under tightening mandates. |
| Direct Procurement Partnership Formation | Multi-year agreements with quick-service restaurant chains in Bangalore and Shanghai standardize specifications and lock volume commitments. |
| Clean-Label Himalayan Positioning | Trace-mineral marketing commands shelf-space premiums in Australian and New Zealand health-food retail channels. |
Study Parameters
Document review covered FSSAI regulatory filings, SAMR food-grade sodium chloride standards, EFSA-aligned Codex documentation, and customs trade data, complemented by interviews with salt processing plant managers, procurement leads at meat processing and bakery manufacturing facilities, distribution channel partners, and technical R&D directors specializing in particle-size control technology. Primary fieldwork across India, China, Vietnam, Indonesia, and Australia validated secondary data through structured conversations with quick-service restaurant chain supply chain executives and health-food retail category buyers. Bottom-up volume modeling triangulated against top-down market sizing from trade flow analysis and production capacity assessments.
Segment-level value outputs across product type, application, packaging format, and end user dimensions were generated through multi-variable regression incorporating regulatory compliance cost escalation, urban food retail expansion velocity, and Western-style curing technique adoption rates. CAGRs were derived from curve-fitting historical procurement patterns against projected quick-service restaurant network expansion and export-oriented meat processing facility commissioning timelines. Industry-specific forecast inputs included FSSAI iodization mandate enforcement intensity and SAMR heavy-metal testing protocol expansion scope.
Regulatory enforcement variability, energy tariff fluctuations, and potassium chloride substitution acceleration are the dominant revision risks warranting scenario sensitivity analysis. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Coating Ingredients Market
Food Additives and Ingredients
Fish Tank Water Additives Market
Food Additives and Ingredients
Banana Powder Market
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
Food Acidulants Market
Food Additives and Ingredients
Germany Food Additives Market
Food Additives and Ingredients
Cake Enzyme Market
Food Additives and Ingredients
India Food Emulsifiers Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
Food Grade Acetic Acid Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
Modified Milk Ingredients Market
Food Additives and Ingredients
North America Fermented Ingredient Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
Olestra Market
Food Additives and Ingredients
Global Sodium Starch Glycolate Market