
 Flour Whiteners Market | 2026-2036
Flour Whiteners Market Size, Share, and Industry Trends Forecast 2026-2036
Flour Whiteners Market Analytics
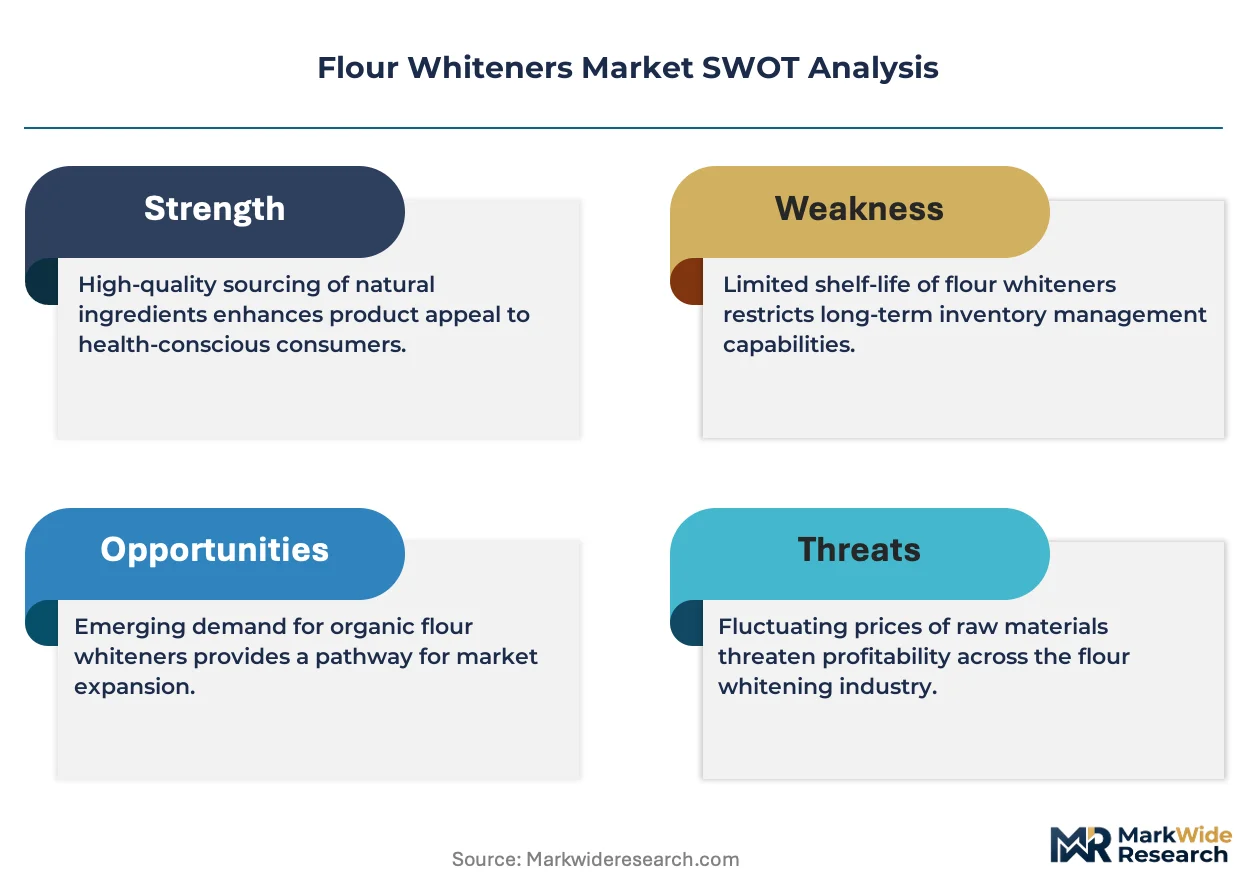
ISO 22000 certification is rotating competitive access across the flour whiteners supply base, filtering out smaller compounders lacking hazard-analysis documentation. Solvay leverages its integrated hydrogen peroxide chain to control chlorine dioxide precursor costs across European milling corridors. Evonik Industries AG anchors specialty organic peroxide R&D through dedicated polymer chemistry divisions in Germany. BASF SE competes on bulk benzoyl peroxide scale, supplying commodity-grade volumes to industrial baking conglomerates.
Flour whiteners comprise oxidizing and bleaching agents that modify carotenoid pigments in milled wheat, typically dosed at 15-50 ppm depending on protein content and desired crumb color. Benzoyl peroxide dominates commercial formulations due to thermal stability and predictable reaction kinetics during dough conditioning. The end use industry segment shows structural divergence: industrial baking commands volume share while pasta production concentrates margin pools in chlorine dioxide for premium semolina processing. Powder form leads distribution logistics for bulk millers, though liquid chlorine dioxide gains traction in continuous-flow processing installations.
EFSA evaluates benzoyl peroxide residue thresholds under renewed food additive reauthorization cycles, while FDA maintains GRAS status with specific labeling triggers for allergic sensitization. The EU F-Gas Regulation indirectly constrains chlorine dioxide generation equipment deployment, pushing capital toward closed-loop reactor systems. India's FSSAI import clearance requirements for bleaching agents create procedural friction for non-registered suppliers. Stakeholders must track divergent regulatory timelines across jurisdictions to anticipate formulation reformulation costs and regional supply reallocation.
Market Dynamics
EFSA's phased reauthorization of benzoyl peroxide under tightened residue thresholds is forcing European millers toward chlorine dioxide and alternative oxidizing chemistries, restructuring procurement priorities across industrial baking supply chains.
Growth Catalysts
- Industrial Baking Automation:Continuous-flow processing installations in Germany and the Netherlands drive standardized dosing of chlorine dioxide for consistent crumb color across high-volume production lines.
- REACH Compliance Adaptation:Chemical compounders reformulating azodicarbonamide substitutes into benzoyl peroxide blends capture displaced volume from delisted additives in EU member states.
- Premium Pasta Export Demand:Italian semolina processors absorb premium-grade chlorine dioxide to meet Middle Eastern and North African import specifications for bright yellow alimentary products.
Market Restraints
- Hydrogen Peroxide Feedstock Volatility:Chlorine dioxide precursor costs fluctuate with European electrolysis energy pricing, compressing margins for non-integrated compounders.
- Supply Concentration in Antwerp-Rotterdam:Solvay's captive hydrogen peroxide infrastructure dominates chlorine dioxide precursor availability, creating single-source dependency for regional millers.
- EFSA Additive Reauthorization Timelines:Pending toxicological reviews of benzoyl peroxide residue thresholds extend formulation uncertainty, freezing capital allocation for multi-year plant investments.
Strategic Opportunities
- Indian FSSAI Registration Gap:Non-registered bleaching agent suppliers face procedural import clearance friction, creating first-mover advantage for compounders completing domestic regulatory filings.
- Liquid Chlorine Dioxide Continuous Dosing:Automated injection systems displace powder handling in Turkish and Egyptian industrial baking corridors, opening equipment-chemical bundled service models.
- EU Green Deal Chemical Substitution Incentives:Low-carbon chlorine dioxide generation via closed-loop reactor systems qualifies for green transition financing in German milling clusters.
Industry Challenges
- ISO 22000 Documentation Burden:Hazard analysis critical control point certification requires 12-18 month preparation cycles for mid-sized compounders, filtering competitive access.
- Legacy Dosing Equipment Retrofit Costs:Powder-based benzoyl peroxide installations require capital-intensive conversion for liquid chlorine dioxide compatibility in continuous-flow environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flour Whiteners Market |
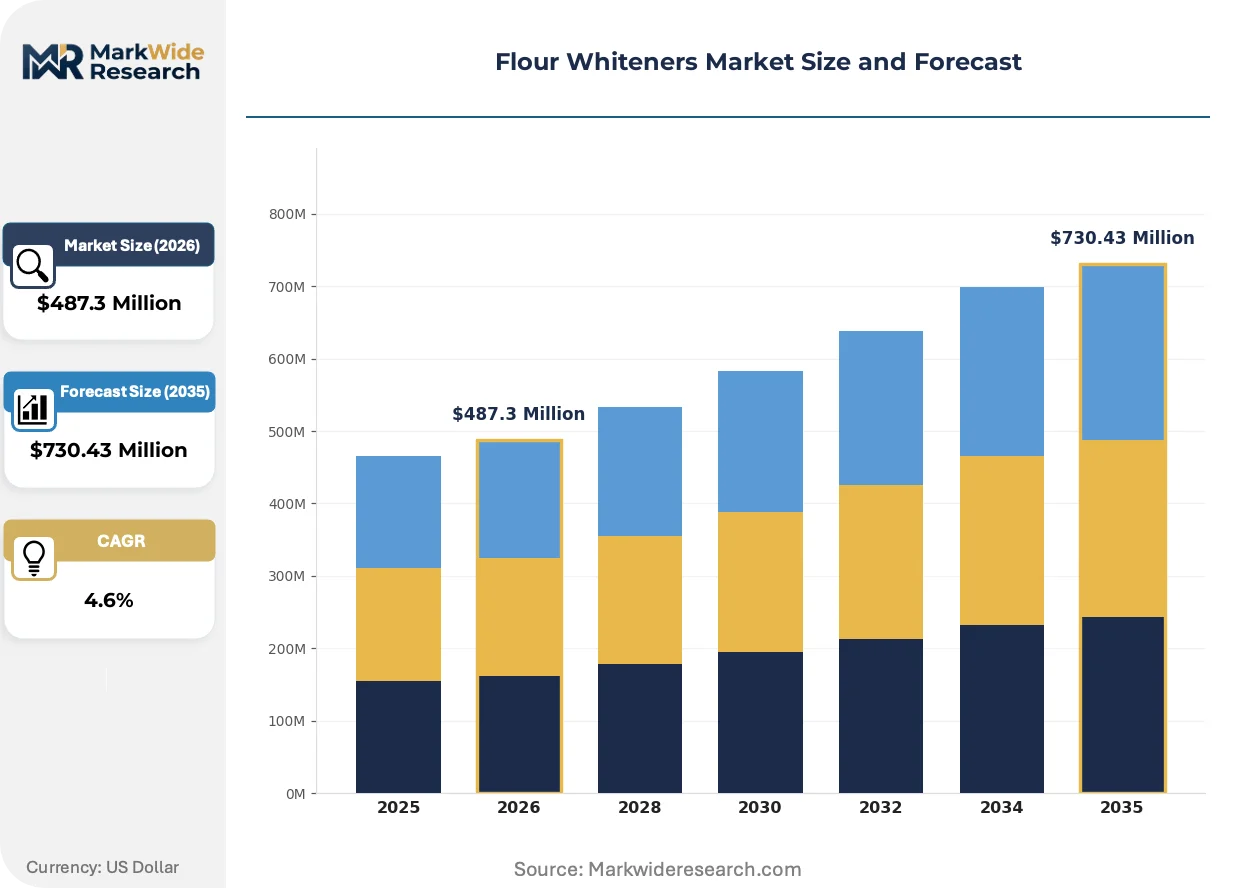
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chlorine Dioxide, Benzoyl Peroxide, Azodicarbonamide, Calcium Peroxide End Use Industry: Baking, Pasta Production, Snack Foods, Confectionery Form: Liquid, Powder, Granular, Spray Application: Industrial, Commercial, Home Baking, Food Processing |
| Companies Covered | Solvay, Evonik Industries AG, BASF SE, Arkema S.A., Nouryon, AkzoNobel N.V., Aditya Birla Chemicals, Kemira Oyj, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flour Whiteners Market Evolving Landscape
Formulation science and regulatory compliance systems are converging to redefine how flour whiteners are specified, dosed, and validated across industrial milling operations.
Encapsulated benzoyl peroxide microspheres is fragmenting conventional powder distribution by enabling delayed-release oxidation kinetics that align with extended dough fermentation cycles. Artisan and industrial bakers in France and Belgium adopt these modified-release formats to achieve target crumb color without premature gluten network disruption. The technology is fragmenting established supplier relationships as specialty polymer chemistry divisions capture formulation value previously held by commodity chemical distributors.
The EU F-Gas Regulation constrains chlorine dioxide generation equipment deployment by classifying certain precursor chemistries as controlled fluorinated gases. Industrial millers in Germany and Italy redirect capital toward closed-loop reactor systems that eliminate vented byproducts and satisfy tightening environmental operating permits. Premium semolina processors absorb higher equipment costs to maintain chlorine dioxide access for export-grade pasta whitening.
Buyer concentration among pan-European baking conglomerates compresses switching cycles for flour whitener procurement, forcing compounders into annual renegotiation frameworks with price-volume banding. Regional milling cooperatives in Spain and Portugal consolidate purchasing through shared technical service agreements that bundle chemical supply with dosing equipment maintenance. This concentration is most visible in Iberia, where industrial bakery chains have reduced active supplier rosters from six to two qualified vendors per production site.
Flour Whiteners Market Segmentation
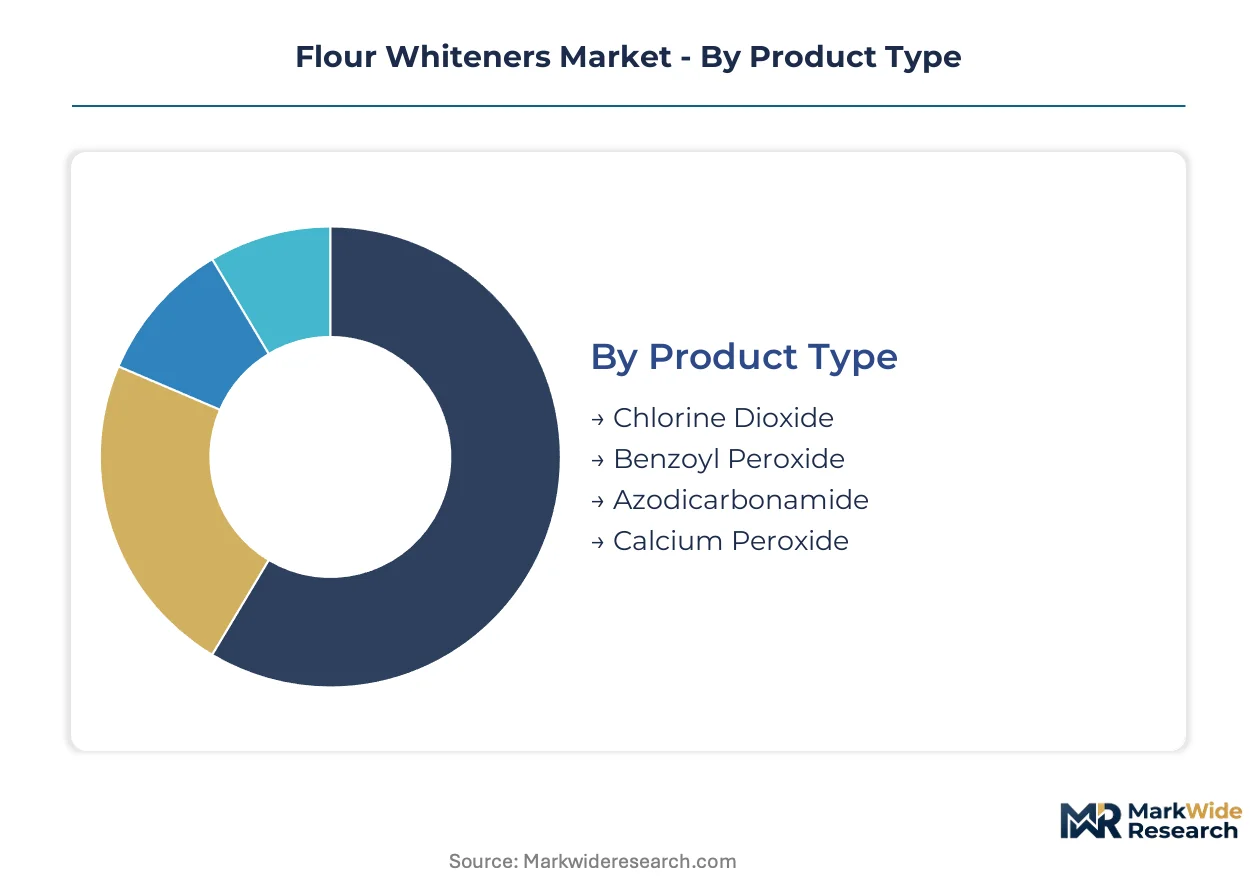
Flour whitener procurement patterns diverge sharply across product chemistries and end-use applications, with regulatory jurisdiction and export destination dictating formulation choices. Segmentation reveals how industrial baking automation, semolina export specifications, and dosing equipment compatibility reshape supplier-customer relationships.
Product Type:
Domestic consumption in Germany and Italy favors chlorine dioxide for premium pasta whitening, while export-oriented North American millers standardize on benzoyl peroxide for cross-border shipment compliance.
- Chlorine Dioxide:Generated via closed-loop reactor systems to satisfy EU F-Gas Regulation constraints on vented byproducts. Italian semolina processors absorb premium pricing to maintain access for Middle Eastern and North African export specifications requiring bright yellow alimentary products.
- Benzoyl Peroxide:Dominates commercial formulations due to thermal stability and predictable reaction kinetics during dough conditioning. EFSA's phased reauthorization under tightened residue thresholds is forcing European millers toward alternative oxidizing chemistries, though FDA GRAS status sustains North American volume.
- Azodicarbonamide:Delisted across EU member states under EFSA guidance; remaining demand concentrates in jurisdictions without equivalent prohibitions.
- Calcium Peroxide:Emerging substitute in clean-label formulations targeting artisan baking segments in France and Belgium.
Benzoyl peroxide holds the largest share; momentum sits with chlorine dioxide as regulatory pressure intensifies.
End Use Industry:
Volume concentration tracks industrial automation intensity, with high-throughput continuous-flow installations commanding standardized chemical procurement.
- Baking:Industrial bakeries in Germany and the Netherlands drive standardized dosing for consistent crumb color across high-volume production lines. Commercial baking chains consolidate supplier rosters from six to two qualified vendors per production site.
- Pasta Production:Premium semolina processors absorb chlorine dioxide at premium grades to satisfy export market color specifications. Italian milling corridors anchor specialty organic peroxide R&D through dedicated polymer chemistry divisions.
- Snack Foods:Lower per-unit dosing requirements favor commodity benzoyl peroxide procurement from bulk compounders.
- Confectionery:Minimal penetration due to alternative whitening approaches in sugar-based formulations.
Industrial baking commands volume leadership; pasta production captures margin concentration through premium-grade chemical absorption.
Form:
Equipment retrofit economics determine form selection, with legacy powder installations facing capital-intensive conversion for liquid compatibility.
- Liquid:Gains traction in continuous-flow processing installations through automated injection systems displacing powder handling. Turkish and Egyptian industrial baking corridors open equipment-chemical bundled service models.
- Powder:Leads distribution logistics for bulk millers with established pneumatic handling infrastructure. Solvay's integrated hydrogen peroxide chain controls precursor costs for regional compounders.
- Granular:Niche positioning in artisan baking segments requiring precise manual dosing control.
- Spray:Emerging format for specialized coating applications in snack food processing.
Powder retains installed base dominance; liquid form climbs fastest on automation retrofit cycles.
Application:
Customer scale dictates procurement sophistication, with industrial buyers demanding bundled technical service agreements.
- Industrial:Pan-European baking conglomerates compress switching cycles through annual renegotiation frameworks with price-volume banding. Spanish and Portuguese milling cooperatives consolidate purchasing through shared technical service agreements bundling chemical supply with dosing equipment maintenance.
- Commercial:Mid-sized bakeries in Belgium and France adopt encapsulated benzoyl peroxide microspheres for delayed-release oxidation aligning with extended fermentation cycles.
- Home Baking:Minimal penetration; consumer-grade flour typically arrives pre-treated from millers.
- Food Processing:Institutional buyers prioritize ISO 22000 certification, filtering out smaller compounders lacking hazard-analysis documentation.
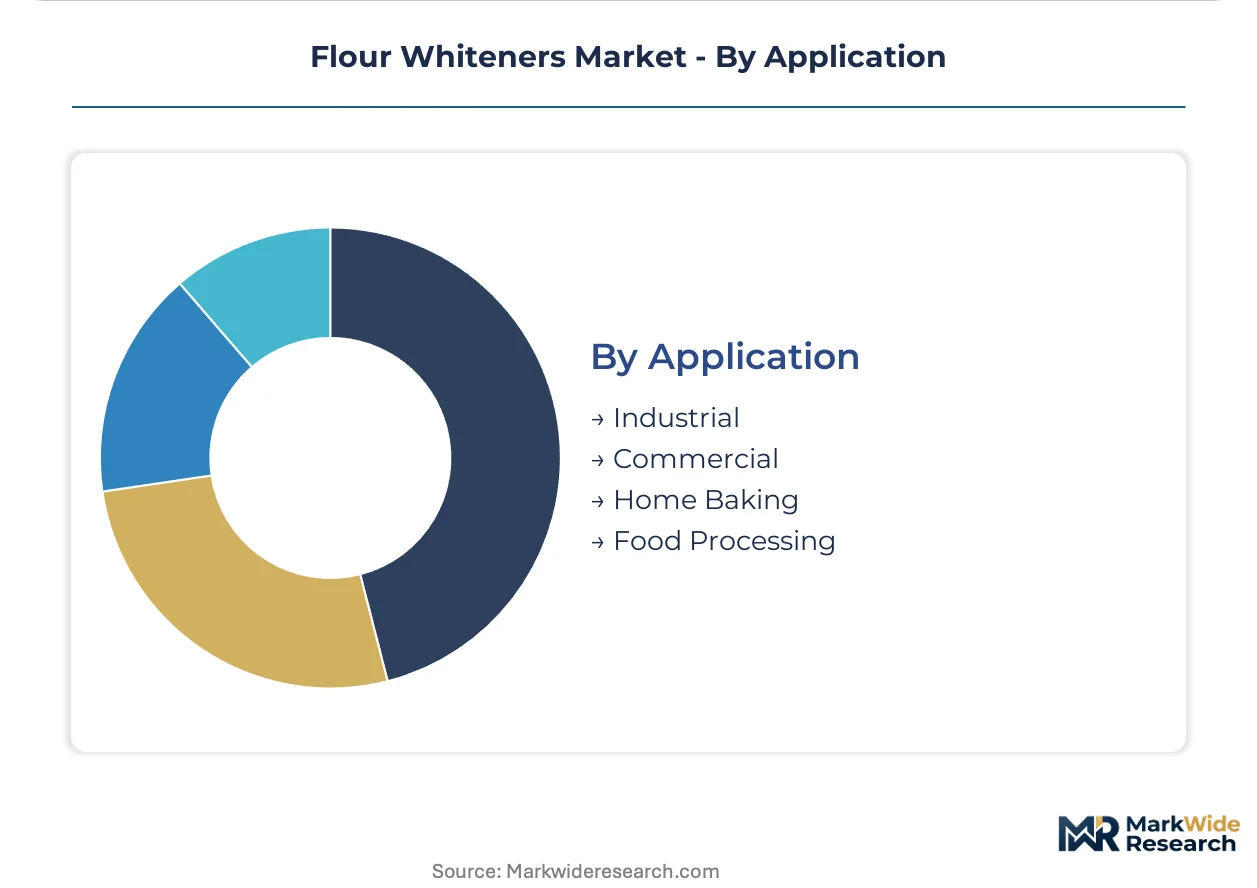
Industrial application holds the largest share; commercial segments gain share fastest on specialty formulation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial baking conglomerates and export-oriented millers concentrate procurement power across four major economies. Buyer archetypes span pan-European bakery chains, Italian pasta exporters, North American cross-border shippers, and Indian institutional food processors.
Germany
Industrial baking automation in North Rhine-Westphalia and Bavaria drives standardized chlorine dioxide dosing for consistent crumb color. EFSA's phased benzoyl peroxide reauthorization under tightened residue thresholds redirects millers toward alternative oxidizing chemistries. The Antwerp-Rotterdam corridor anchors hydrogen peroxide precursor supply, with Solvay's integrated infrastructure dominating regional availability.
Italy
Premium semolina processors absorb chlorine dioxide at premium grades to satisfy Middle Eastern and North African export specifications for bright yellow pasta. The EU F-Gas Regulation constrains generation equipment deployment, pushing capital toward closed-loop reactor systems in Emilia-Romagna milling clusters. Italian polymer chemistry divisions anchor specialty organic peroxide R&D for delayed-release formulations.
United States
Cross-border shipment compliance sustains benzoyl peroxide standardization across industrial baking lines in the Midwest and Southeast. FDA GRAS status with specific labeling triggers for allergic sensitization maintains regulatory clarity absent in European jurisdictions. Commercial bakery chains consolidate supplier rosters through annual renegotiation frameworks with price-volume banding.
India
FSSAI import clearance requirements for bleaching agents create procedural friction for non-registered suppliers, opening first-mover advantage for compliant compounders. Institutional food processors in Maharashtra and Gujarat prioritize ISO 22000 certification, filtering out smaller compounders lacking hazard-analysis documentation. Regional milling cooperatives absorb commodity-grade benzoyl peroxide for domestic snack food production.
Flour Whiteners Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive hydrogen peroxide supply chains. The vendor base concentrates around three strategic tiers: bulk commodity compounders serving industrial baking volume, specialty peroxide developers capturing premium pasta margins, and regional distributors bridging regulatory compliance gaps. Consolidation pressures intensify as ISO 22000 certification requirements filter competitive access and buyer concentration compresses switching cycles.
Within the integrated chemical tier, Solvay, Evonik Industries AG, and BASF SE exemplify divergent strategic positioning. Solvay leverages upstream hydrogen peroxide control across European milling corridors. Evonik anchors specialty organic peroxide development through dedicated polymer chemistry divisions. BASF competes on bulk benzoyl peroxide scale for commodity industrial baking supply. Arkema S.A., Nouryon, and AkzoNobel N.V. occupy mid-tier positions bridging regional regulatory compliance with technical service bundling.
| Leading Market Players |
|---|
| Solvay |
| Evonik Industries AG |
| BASF SE |
| Arkema S.A. |
| Nouryon |
| AkzoNobel N.V. |
| Aditya Birla Chemicals |
| Kemira Oyj |
| Clariant AG |
| Others |
Value Network & Pricing Analysis
Sixty-day hydrogen peroxide inventory cycles at Antwerp-Rotterdam terminals concentrate pricing leverage among integrated compounders, linking precursor availability directly to benzoyl peroxide and chlorine dioxide contract terms across European milling corridors. This lead-time compression amplifies buyer dependency on Solvay's captive supply infrastructure, translating into asymmetric bargaining power during annual procurement renegotiations.
Pricing Analysis
Cost-plus contracts with hydrogen peroxide indexation dominate chlorine dioxide procurement, tying miller payments to electrolysis energy benchmarks across the EU. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22000-certified compounders from commodity suppliers and regional distributors. Cost compression in standard-grade benzoyl peroxide is intensifying because REACH compliance adaptation expenses filter smaller compounders from tender participation. Industrial baking conglomerates exhibit lowest price sensitivity due to bundled technical service agreements, while mid-sized regional millers face acute margin pressure from retrofit equipment financing.
Supply Chain Analysis
Belgium and the Netherlands anchor hydrogen peroxide production through Solvay's integrated electrolysis infrastructure, while Germany hosts specialty organic peroxide formulation. Chlorine dioxide generation draws from sodium chlorate and sulfuric acid feedstocks sourced through Antwerp-Rotterdam chemical corridors. Single-source vulnerability concentrates in Solvay's captive precursor supply, exposing regional millers to allocation risk during energy price spikes. Distribution runs through pan-European chemical distributors with technical service bundling, though direct miller-compounder relationships are consolidating as buyer concentration intensifies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as clean-label calcium peroxide and enzyme-based alternatives capture artisan baking share, forcing incumbent compounders to demonstrate performance equivalence while navigating tightening residue thresholds.
For Market Incumbents: Shield market position by accelerating ISO 22000 certification for mid-tier compounders through hazard-analysis documentation partnerships, and deepen backward integration into hydrogen peroxide supply through long-term offtake agreements with electrolysis operators. EFSA's phased benzoyl peroxide reauthorization threatens volume displacement; counter with closed-loop chlorine dioxide reactor investments qualifying for EU Green Deal transition financing. For New Entrants and Emerging Players: FSSAI registration fast-track in India opens first-mover procurement access as institutional food processors filter non-compliant suppliers. Target Maharashtra and Gujarat milling cooperatives with commodity-grade benzoyl peroxide bundled with pneumatic handling equipment leasing. Penetrate through regulatory compliance arbitrage rather than price undercutting. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underperforming peroxide divisions lacking food-grade certification infrastructure. Long-term viability hinges on substitution resilience and regulatory navigation capability rather than volume scale alone. Monitor EFSA toxicological review timelines as inflection signal for benzoyl peroxide reauthorization outcomes and capital reallocation patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogen Peroxide | Solvay's captive electrolysis infrastructure demonstrates pricing control across European milling corridors. |
| ISO 22000 Certification Acceleration | Twelve-month hazard-analysis preparation cycles filter competitive access for mid-sized compounders. |
| Closed-Loop Reactor Deployment | German milling clusters qualify for EU Green Deal financing while satisfying F-Gas Regulation constraints. |
| Liquid Chlorine Dioxide Service Bundling | Turkish and Egyptian industrial baking corridors adopt automated injection systems displacing powder handling. |
| FSSAI Registration Completion | Non-registered bleaching agent suppliers face procedural friction creating first-mover advantage for compliant entrants. |
Research Methodology
Desk research of EFSA additive reauthorization documentation, EU F-Gas Regulation implementation guidance, and customs trade flow data preceded structured interviews with milling procurement directors, chemical compounder technical sales leads, and food safety certification auditors. Primary fieldwork with industrial baking operations in Germany and Italy validated dosing equipment retrofit economics and supplier switching patterns. Secondary triangulation incorporated SEC filings from integrated chemical conglomerates, Cefic peroxide market reports, and FSSAI import clearance procedural records. Bottom-up volume estimates from end-use application dosing rates were cross-checked against top-down chemical production capacity assessments.
Variance decomposition across product chemistry, end-use industry, and regional regulatory jurisdiction shaped the analytical framework over the projection horizon. Segmentation modeling captured benzoyl peroxide versus chlorine dioxide substitution dynamics, industrial versus commercial application scale effects, and powder versus liquid form equipment compatibility constraints. CAGRs were derived from production capacity expansion announcements correlated with export destination demand specifications. Hydrogen peroxide feedstock cost trajectories and EFSA reauthorization timeline scenarios served as key sensitivity inputs.
The analysis sits within stated boundaries; outcomes outside EFSA benzoyl peroxide residue threshold determinations, EU F-Gas Regulation enforcement intensity, or Indian FSSAI procedural streamlining would require recalibration. Forecasts reflect documented assumptions regarding industrial baking automation adoption rates and pasta export specification stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
North America Fermented Ingredient Market
Food Additives and Ingredients
Canada Food Emulsifiers Market
Food Additives and Ingredients
Canada Food Colorants Market
Food Additives and Ingredients
Japan Food Acidulants Market
Food Additives and Ingredients
Argentina Food Enzymes Market
Food Additives and Ingredients
Food Starch Market
Food Additives and Ingredients
Potassium Propionate Market
Food Additives and Ingredients
PVPP Beer Stabilizer Market
Food Additives and Ingredients
Natural Food Color Additives Market
Food Additives and Ingredients
Australia Food Enzymes Market
Food Additives and Ingredients
Film Forming Starches Market
Food Additives and Ingredients
South America Brewing Enzymes Market
Food Additives and Ingredients
Ellagic Acid Market
Food Additives and Ingredients
India Anti Caking Market
Food Additives and Ingredients
Global Food Release Agents Market
Food Additives and Ingredients
North America Clean Label Ingredient Market