
 Global Fruit Snacks Market | 2026-2036
Global Fruit Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fruit Snacks Market Analysis
The EU Green Deal is realigning ingredient sourcing and clean-label formulation priorities across the fruit snacks value chain. General Mills Inc. leverages its North American milling infrastructure to secure steady fruit puree supply. Welch Foods Inc. anchors its positioning through cooperative grape sourcing from grower networks. SunOpta Inc. differentiates via organic and non-GMO ingredient specialization that meets tightening European import standards.
Fruit snacks are shelf-stable processed fruit products manufactured through dehydration, extrusion, or gelling processes, typically containing fruit puree, concentrates, or pieces combined with binders and preservatives for extended stability. Dried fruit segments sustain premium positioning through minimal processing claims and fiber retention, while gummy snacks compete on convenience and child-oriented formats. Online retail channels are capturing margin pools through subscription models and direct-to-health-conscious-consumer positioning that bypasses traditional supermarket slotting fees.
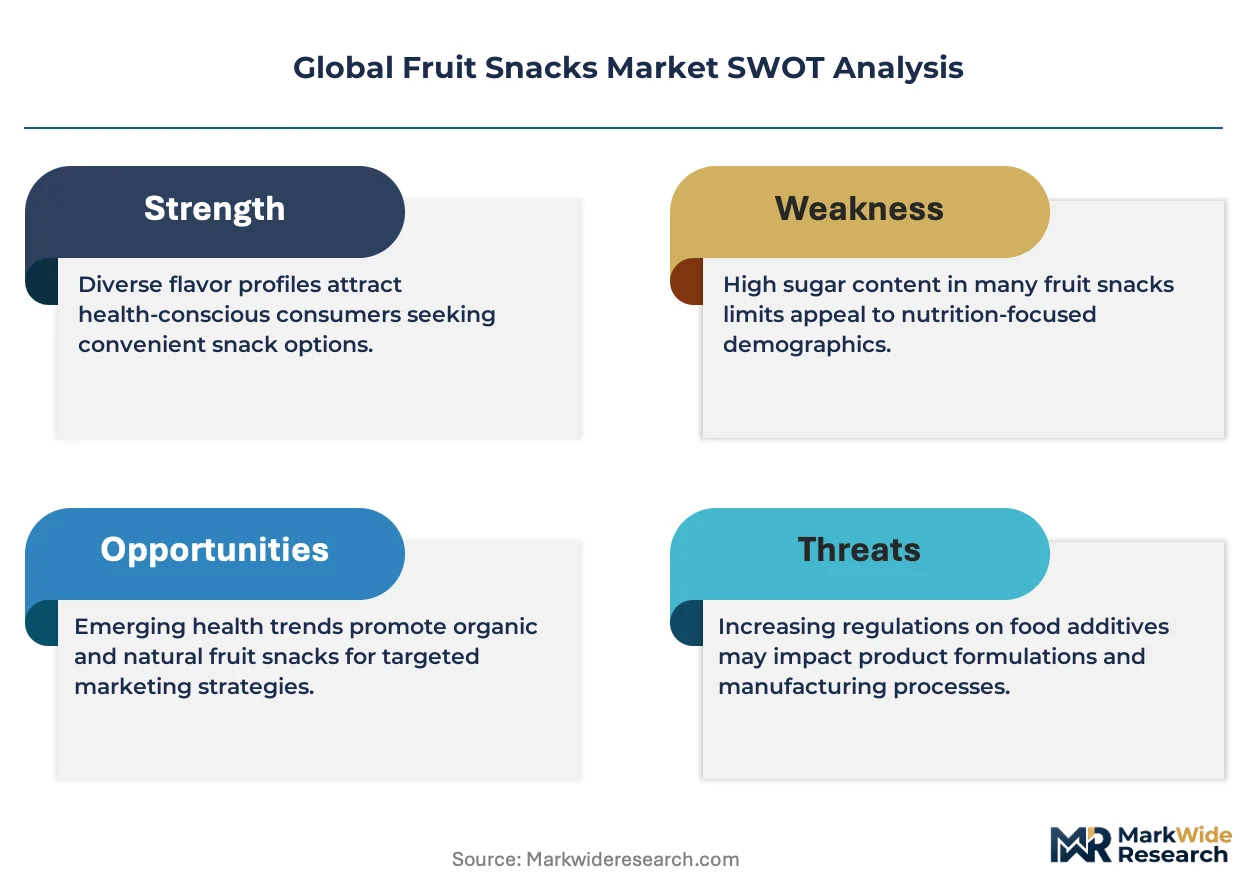
FDA nutrition labeling requirements and USDA school meal standards shape product formulation and permissible sugar content in the United States. EFSA health claim regulations and REACH chemical safety protocols govern additive use and marketing language across European markets. Stakeholders must monitor evolving extended producer responsibility frameworks for flexible pouch packaging and anticipate which regulatory jurisdiction will next mandate recycled content minimums.
Market Dynamics
Clean-label formulation mandates from the EU Green Deal and USDA school nutrition standards are compressing permissible ingredient lists while tropical processing capacity concentrates in Thailand and Vietnam, reshaping supplier geography and procurement risk profiles simultaneously.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility frameworks for flexible pouches are accelerating investment in recyclable barrier films and mono-material structures across European supply chains.
- USDA school meal standards:Permissible sugar thresholds and whole fruit requirements are expanding institutional procurement volumes for low-additive fruit snacks in K-12 nutrition programs.
- Thai-Vietnamese processing clusters:Tropical fruit puree capacity scaling near raw material sources is shortening supply chains for mango, pineapple, and passion fruit concentrates destined for export markets.
Market Restraints
- Fruit concentrate price volatility:Weather-driven crop yields in California grape regions and Thai mango belts create input cost instability that squeezes margin predictability for gummy and strip formats.
- Single-origin supply concentration:Over-dependence on Vietnamese cashew apple and Thai pineapple processors exposes buyers to climate disruption and port congestion risks without redundant sourcing.
- REACH additive restrictions:ECHA scrutiny of titanium dioxide whitening agents and certain pectin stabilizers is forcing costly reformulation cycles ahead of confirmed regulatory bans.
Strategic Opportunities
- Indian organized retail expansion:Reliance Retail and DMart shelf-space growth for packaged foods creates first-mover positioning for clean-label imports meeting FSSAI additive standards.
- Upcycled fruit fiber applications:Press cake from juice extraction is converging with extrusion technology to enable zero-waste snack formats with elevated fiber claims.
- Direct-to-consumer subscription channels:Recurring revenue models bypassing supermarket slotting fees allow margin capture from health-conscious households in Germany and the United Kingdom.
Industry Challenges
- Clean-label R&D talent scarcity:Formulation chemists skilled in natural preservation and binder substitution without synthetic additives command premium compensation and extended recruitment timelines.
- Organic certification backlog:USDA NOP and EU organic equivalence audits face 12-18 month queues, delaying product launches for brands dependent on non-GMO positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fruit Snacks Market |
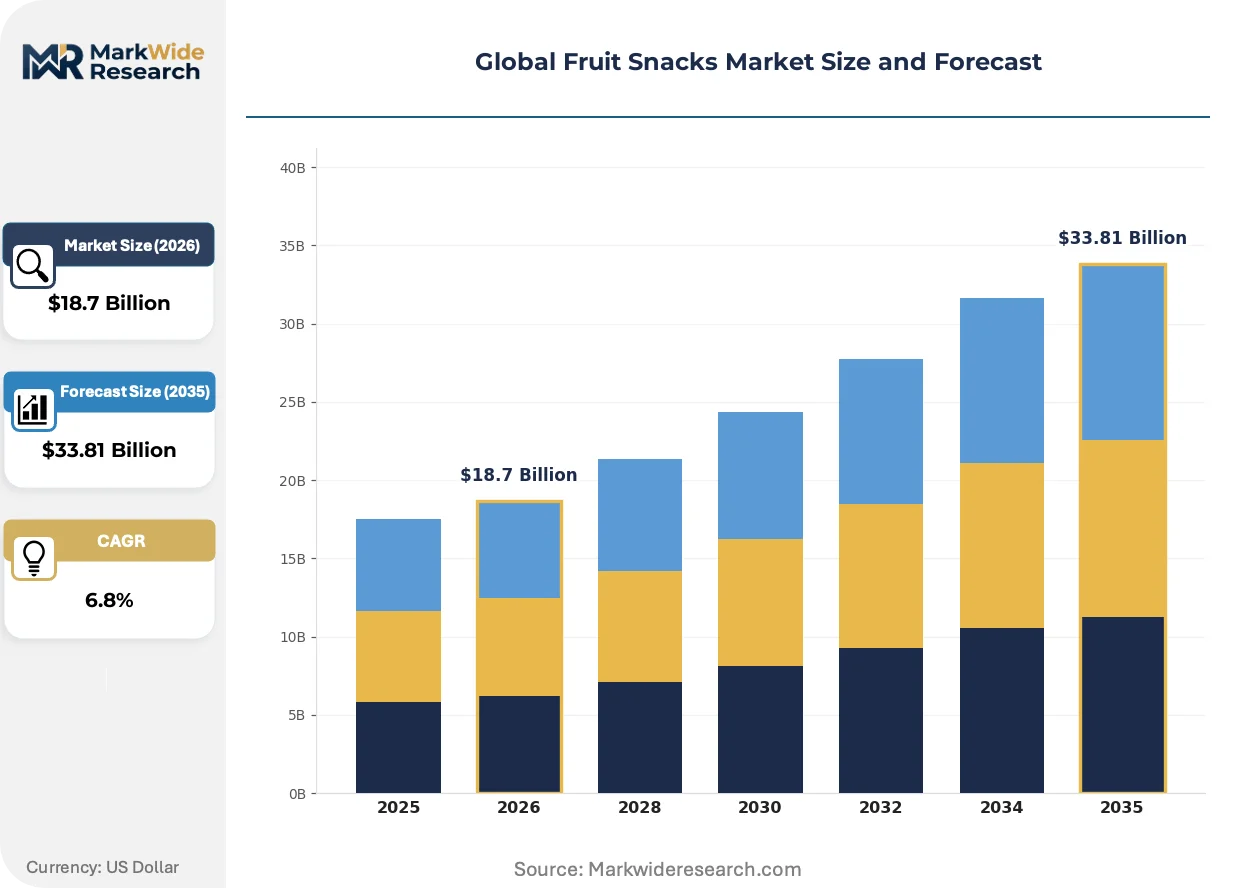
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dried Fruit, Fruit Leather, Gummy Snacks, Fruit Cups End User: Children, Health-conscious Consumers, Busy Professionals, Seniors Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Convenience Stores Packaging Type: Flexible Pouches, Resealable Bags, Containers, Individual Packs |
| Companies Covered | General Mills Inc., Kellogg Company, Welch Foods Inc., The Kraft Heinz Company, Mount Franklin Foods, SunOpta Inc., Crispy Green Inc., Sunkist Growers Inc., Keurig Dr Pepper Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fruit Snacks Market Emerging Trajectories
Dehydration and extrusion technologies are converging with bio-based packaging advances to compress processing energy intensity while meeting tightening single-use plastic restrictions across multiple regulatory jurisdictions.
High-pressure processing (HPP) is unifying pasteurization and texture preservation functions previously requiring thermal steps. Premium dried fruit brands in California and France are adopting HPP lines to eliminate sulfite preservatives while maintaining shelf stability. This technology is unifying clean-label credibility with extended distribution reach previously reserved for conventional formats.
REACH chemical safety protocols are tightening scrutiny of artificial colorants and synthetic flavor carriers in fruit snacks marketed across European Economic Area member states. Manufacturers are reformulating with fruit and vegetable juice concentrates for color and natural flavor systems ahead of anticipated ECHA restriction expansions. German and Dutch retail buyers are now requiring full substance disclosure for imported processed fruit products.
Health-conscious households are consolidating purchases through specialized e-commerce platforms that curate additive-free assortments. Traditional supermarket slotting fee structures are losing relevance as direct-to-consumer channels capture margin pools from subscription-driven replenishment. This behavioral pivot is most pronounced in urban centers across the United Kingdom, Germany, and the Netherlands where delivery density supports viable unit economics.
Global Fruit Snacks Market Segmentation
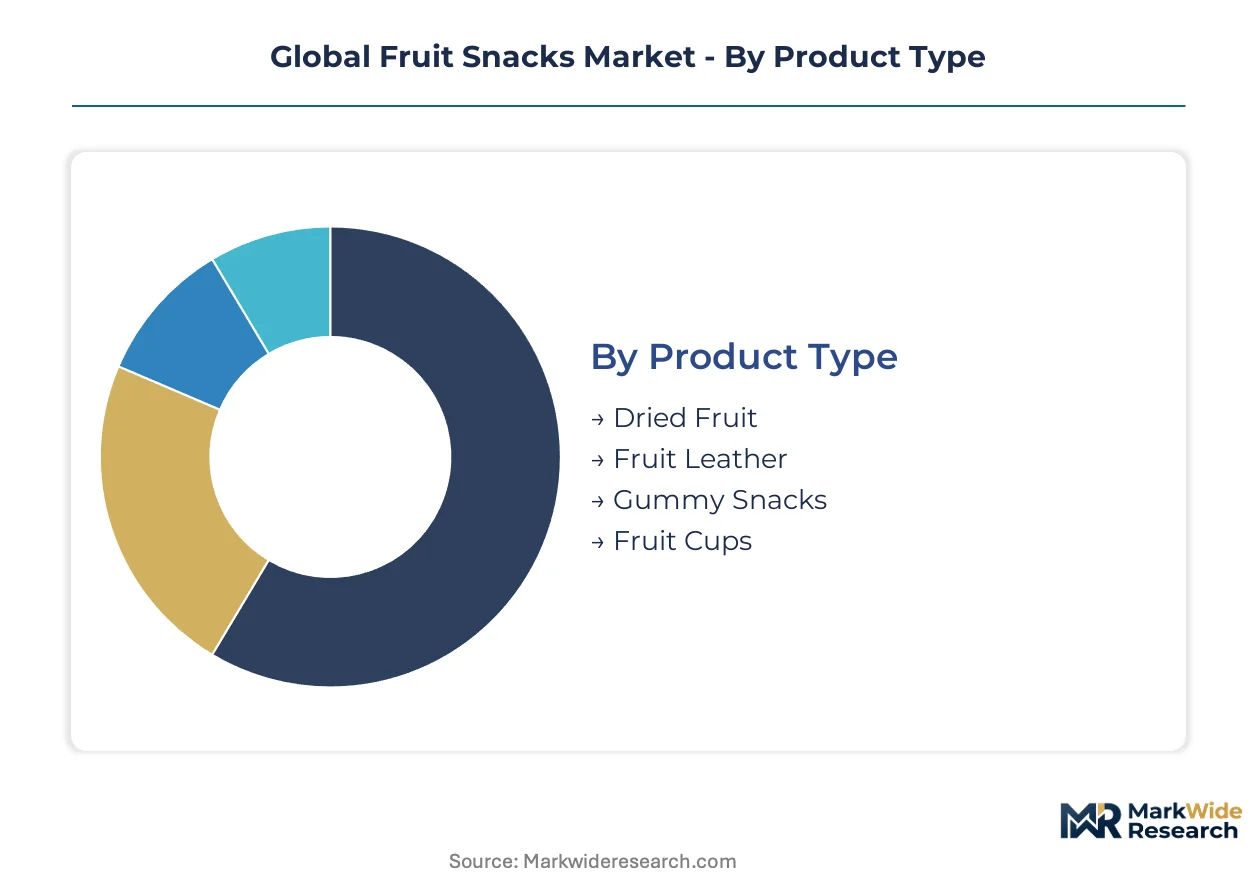
Fruit snacks segmentation reflects divergent processing intensities and consumption occasions. Product format determines shelf stability, ingredient permissibility, and regulatory classification. Distribution channel selection locks in margin structure and clean-label credibility simultaneously.
Product Type:
Standardization dominates at mass retail while customization concentrates in premium positioning across this category.
- Dried Fruit:Whole or sliced fruit dehydrated through air-drying, freeze-drying, or osmotic processes retains fiber content and enables minimal-ingredient claims. Demand concentrates in California and French procurement channels where sulfite-free HPP-treated lines command shelf space at Whole Foods Market and Carrefour locations.
- Gummy Snacks:Gelatin or pectin-based formulations using fruit puree concentrates compete on child-oriented portioning and texture engineering. German and Dutch retail buyers are tightening additive disclosure requirements ahead of anticipated ECHA restrictions on synthetic colorants.
- Fruit Leather:Puree-based sheets extruded and dried into roll formats target lunchbox occasions with flat packaging efficiency.
- Fruit Cups:Shelf-stable fruit pieces in single-serve liquid or gel mediums serve institutional nutrition programs with portion-controlled servings.
Leading the category by volume: Gummy Snacks. Growing fastest: Dried Fruit.
End User:
Application context shapes formulation rigor and permissible ingredient lists across consumer types.
- Children:Portion-controlled formats with texture engineering for palatability dominate this segment. USDA school meal standards in the United States are expanding permissible procurement volumes for low-additive options in K-12 programs.
- Health-conscious Consumers:Clean-label scrutiny concentrates here with organic certification and non-GMO verification as baseline requirements. EU Green Deal packaging mandates are accelerating demand for recyclable mono-material structures in German and United Kingdom households.
- Busy Professionals:Convenience-driven single-serve formats with resealable functionality target commuter consumption occasions.
- Seniors:Soft-texture requirements and nutrient-fortified positioning address chewing difficulty and targeted supplementation needs.
Volume concentration sits with Children. Steepest expansion trajectory: Health-conscious Consumers.
Distribution Channel:
Channel selection determines slotting fee exposure and direct consumer relationship depth.
- Online Retail:Subscription models and specialized curation platforms bypass traditional supermarket fee structures. United Kingdom and German urban delivery density supports viable unit economics for additive-free assortments.
- Supermarkets:Mass volume concentration with slotting fee barriers favors established brands with trade promotion budgets.
- Health Food Stores:Certification-verified assortments with staff education support premium positioning and trial conversion.
- Convenience Stores:Impulse-driven single-serve formats with extended shelf life requirements compete on grab-and-go accessibility.
Supermarkets retain volume leadership. Online Retail climbs fastest.
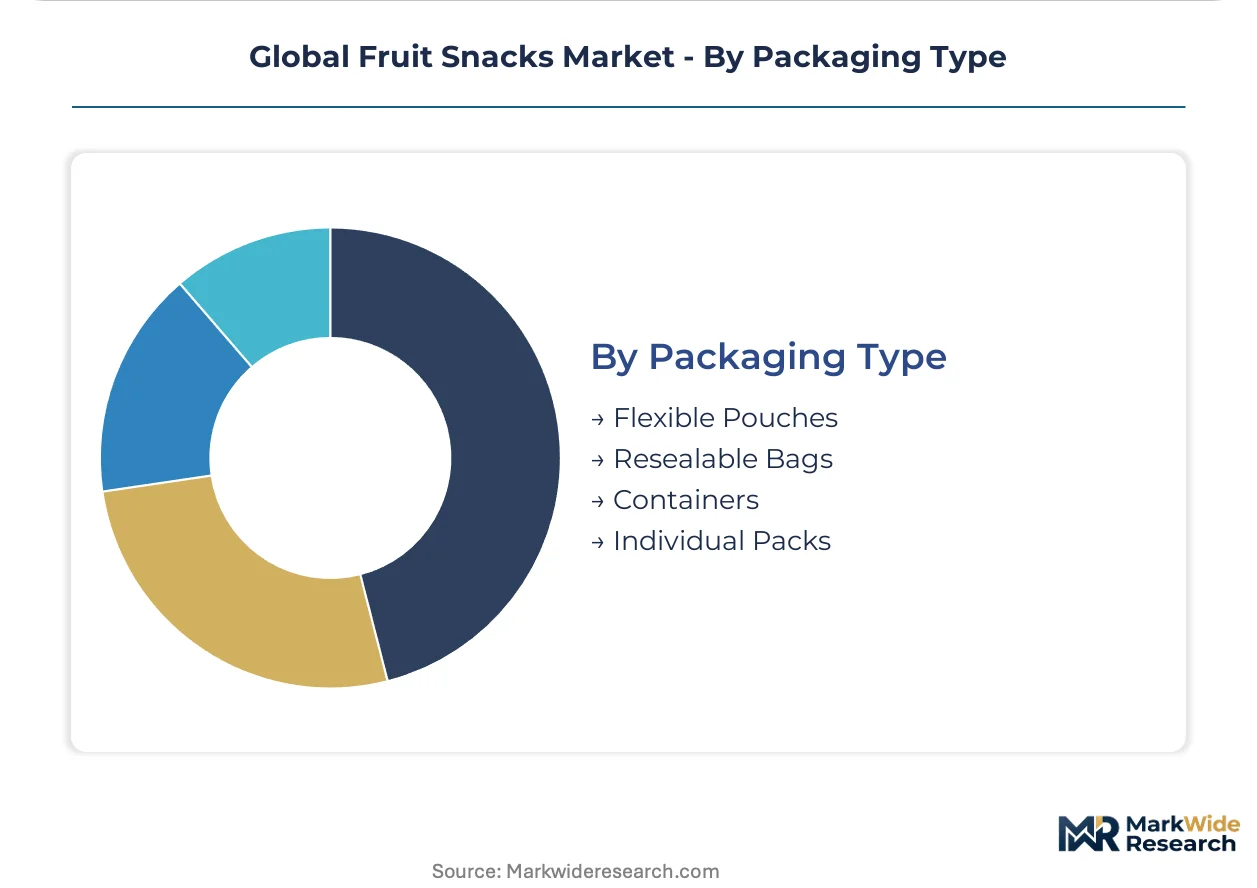
Packaging Type:
Regulatory pressure on single-use plastics is reshaping material selection and format viability.
- Flexible Pouches:Multi-layer barrier films dominate mass-market fruit snacks with lightweight shipping efficiency. Extended producer responsibility frameworks under the EU Green Deal are forcing investment in recyclable mono-material alternatives.
- Resealable Bags:Zipper-equipped multi-serve formats target household pantry stocking with portion control flexibility.
- Containers:Rigid formats for fruit cups and wet-packed segments enable stacking logistics and microwave compatibility.
- Individual Packs:Single-serve portioning for institutional and lunchbox occasions minimizes cross-contamination risk.
Flexible Pouches lead by shipment volume. Fastest material transition: recyclable barrier films.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand and Vietnam process the bulk of tropical fruit concentrates while Germany and the United States absorb the highest clean-label import volumes. This geographic split creates procurement risk for brands dependent on single-origin supply chains.
United States
USDA school meal standards are expanding institutional procurement of low-additive fruit snacks for K-12 nutrition programs. FDA nutrition labeling requirements and permissible sugar thresholds shape product formulation for domestic manufacturers. California's Central Valley anchors domestic dried fruit production with sulfite-free HPP-treated lines supplying Whole Foods Market locations.
Germany
EU Green Deal packaging mandates are accelerating demand for recyclable mono-material flexible pouches among German retail buyers. EFSA health claim regulations and REACH chemical safety protocols govern additive use and marketing language for processed fruit products. Berlin and Hamburg distribution hubs are consolidating direct-to-consumer subscription fulfillment for additive-free assortments.
Thailand
Tropical fruit puree capacity scaling near raw material sources is shortening supply chains for mango and pineapple concentrates destined for export markets. The country's national food safety regulator enforces standards aligned with EU import requirements. Chonburi and Rayong processing clusters are expanding extrusion and dehydration infrastructure for gummy and leather formats.
Vietnam
Cashew apple and pineapple processor concentration exposes buyers to climate disruption and port congestion risks without redundant sourcing. The central bank's trade financing facilities support working capital for export-oriented fruit processing ventures. Ho Chi Minh City and Binh Duong manufacturing zones are attracting foreign investment in clean-label ingredient extraction.
United Kingdom
Health-conscious households in urban centers are consolidating purchases through specialized e-commerce platforms that curate additive-free assortments. Extended producer responsibility frameworks are forcing investment in recyclable barrier films ahead of confirmed regulatory mandates. London and Manchester delivery density supports viable unit economics for subscription-driven replenishment models.
Global Fruit Snacks Market Vendor Landscape
The competitive structure tilts toward diversified food conglomerates with legacy distribution infrastructure. Mass-market shelf space concentration favors established brands with trade promotion budgets and supermarket slotting fee capacity. Three archetypes dominate: multinational processed food conglomerates, cooperative grower-network processors, and organic ingredient specialists. Capacity expansion in Southeast Asian processing clusters and portfolio diversification into clean-label formats represent the dominant competitive moves.
Within the multinational conglomerate tier, General Mills Inc. and Kellogg Company occupy positions anchored by North American milling and distribution infrastructure. Welch Foods Inc. exemplifies the cooperative grower-network model with grape sourcing relationships. SunOpta Inc. represents the organic and non-GMO specialization archetype that meets tightening European import standards. These three company structures illustrate how geographic origin and organizational form map to distinct competitive positioning in procurement and regulatory compliance.
| Leading Market Players |
|---|
| General Mills Inc. |
| Kellogg Company |
| Welch Foods Inc. |
| The Kraft Heinz Company |
| Mount Franklin Foods |
| SunOpta Inc. |
| Crispy Green Inc. |
| Sunkist Growers Inc. |
| Keurig Dr Pepper Inc. |
| Others |
Supply Flow & Price Mechanics
Fruit concentrate costs from Thai mango belts and California grape regions cascade through three distinct pricing tiers, with organic certification premiums widening spreads between mass-market gummy formats and sulfite-free dried fruit lines destined for Whole Foods Market and Carrefour locations.
Pricing Analysis
Value-based pricing anchors on clean-label credibility metrics including organic certification, non-GMO verification, and minimal-ingredient claims that command shelf space premiums. Pricing stratifies across premium, standard, and economy tiers driven by certification grade and volume scale, with health-conscious households showing lowest price sensitivity. Cost compression in mass-market gummy segments is intensifying because REACH-mandated reformulation of titanium dioxide and synthetic colorants is raising input costs without commensurate price recovery.
Supply Chain Analysis
Direct-to-retail channels handle hyperscale buyer demand from German and United Kingdom supermarket chains, while specialized e-commerce platforms manage subscription-driven replenishment for additive-free assortments. Raw material supply concentrates in Thailand, Vietnam, and California, drawing from tropical fruit puree processors and domestic dried fruit operations. The chain rests on mango concentrate, grape puree, and pectin stabilizer inputs. Single-origin exposure to Vietnamese cashew apple and Thai pineapple processors creates climate disruption vulnerability. Distribution runs through European retail buying offices and North American institutional procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label R&D talent scarcity functions as the binding capacity constraint, propping formulation premiums and extending recruitment timelines for brands seeking natural preservation expertise.
For Market Incumbents: Cement procurement relationships with Thai-Vietnamese processing clusters through long-term offtake agreements that lock in tropical fruit concentrate supply. Deepen backward integration into organic certification pipelines to circumvent USDA NOP and EU equivalence audit backlogs. Channel control through direct-to-consumer subscription platforms defends margin position against supermarket slotting fee erosion. For New Entrants and Emerging Players: Capture white-space in Indian organized retail through Reliance Retail and DMart shelf-space expansion for packaged foods meeting FSSAI additive standards. Target health-conscious consumer segments in German and United Kingdom urban centers where delivery density supports viable unit economics. Lead with upcycled fruit fiber positioning leveraging press cake from juice extraction to differentiate on zero-waste claims. For Investors and Strategic Acquirers: EU Green Deal packaging mandate acceleration is the leading indicator that recyclable mono-material flexible pouch capacity will command scarcity premiums. Long-term viability favors acquiring organic ingredient specialists with established European import compliance and captive Southeast Asian sourcing relationships. Watch for ECHA restriction expansions on remaining synthetic additives as the signal for reformulation-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thai-Vietnamese Processing | Captures margin from tropical fruit concentrate supply and reduces climate disruption exposure. |
| Clean-Label Certification Investment | USDA NOP and EU organic equivalence unlocks premium shelf space at Whole Foods Market and Carrefour. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket slotting fees and captures recurring revenue from health-conscious households. |
| Upcycled Fruit Fiber Product Line | Press cake utilization enables zero-waste positioning aligned with EU Green Deal circularity mandates. |
| Recyclable Mono-Material Packaging Transition | Extended producer responsibility compliance secures German and United Kingdom retail buyer approval. |
Methodological Framework
Document review covered FDA nutrition labeling guidance, EFSA health claim registers, and REACH chemical safety protocols, complemented by interviews with fruit processing plant managers, retail category buyers at German supermarket chains, organic certification auditors, and supply chain directors at Southeast Asian export operations. Secondary validation drew from customs trade data, USDA school meal procurement records, and EU Green Deal implementation documents. Bottom-up volume modeling and top-down value triangulation converged on segment-level estimates.
Historical shipment patterns were cross-referenced against panel input from procurement leads and distribution channel partners across the analysis window. Segmentation dimensions included product format, end-user application, distribution channel, and packaging material type. CAGRs were derived from trend extrapolation of clean-label adoption curves and institutional procurement expansion. Forecast inputs incorporated REACH regulatory timelines and Thai-Vietnamese processing capacity buildout announcements.
The model holds under stable regulatory enforcement and intact trade financing conditions; deviation in ECHA restriction timing or central bank liquidity contraction would shift volume trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
South Africa Snack Bar Market
Snacks
Specialty Snacks Market
Snacks
Protein Bars Market
Snacks
United States Children's Snack Bar Market
Snacks
Global Rice Snacks Market
Snacks
High Carb Low Fat Snack Market
Snacks
Low-Fat Tortillas Market
Snacks
High Fiber Snack Foods Market
Snacks
India Energy Bar Market
Snacks
North America Frozen Snacks Market
Snacks
Global Snack Food Market
Snacks
United Kingdom Energy Bar Market
Snacks
Low Fat Protein Snacks Market
Snacks
Vegan Protein Balls Market
Snacks
Asia-Pacific Popcorn Market
Snacks
Meat Protein Chips Market