
 Forklift Battery Rental Market | 2026-2036
Forklift Battery Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Forklift Battery Rental Market Insights
Lithium-ion chemistry is rebalancing forklift battery rental economics as fleets abandon heavier lead-acid units. EnerSys leverages its vertical integration across cell manufacturing and service networks to capture premium rental contracts. Toyota Industries Corporation anchors its position through captive supply of traction batteries paired with its lift truck installed base. Jungheinrich AG differentiates via integrated fleet management software that optimizes battery swap timing across multi-site operations.
Forklift battery rental supplies rechargeable electrochemical power units—typically 24V to 80V systems with capacities from 200Ah to 1,200Ah—on a usage-based contract rather than purchase, eliminating capital expenditure and disposal liability for warehouse operators. Lithium-ion segments command expanding share as thermal runaway protection systems and opportunity-charging protocols extend shift availability beyond legacy lead-acid limitations. Medium-term and long-term rental durations concentrate margin pools by locking in predictable revenue streams and reducing customer churn across third-party logistics and cold storage facilities.
OSHA indoor air quality standards and the EU F-Gas Regulation restrict emissions from material handling equipment in enclosed facilities, directly elevating demand for zero-emission battery rental over internal combustion alternatives. EPA hazardous waste rules governing spent lead-acid battery disposal further tilt procurement toward rental models where suppliers retain recycling obligations. Stakeholders must monitor how solid-state battery prototyping and sodium-ion chemistry maturation alter replacement cycles and residual value calculations in rental portfolios.
Market Dynamics
Lithium-ion chemistry is rebalancing rental economics as warehouse operators abandon lead-acid units to eliminate watering maintenance and extend shift availability through opportunity charging protocols.
Growth Catalysts
- EU F-Gas Regulation:Stricter phase-down schedules for fluorinated greenhouse gases in cold storage facilities are accelerating replacement of internal combustion forklifts with zero-emission battery rental fleets.
- Third-party logistics:E-commerce fulfillment centers operating multi-shift schedules favor rental models that transfer thermal runaway liability and end-of-life recycling obligations to suppliers.
- Opportunity charging infrastructure:Lithium-ion cells tolerate intermittent high-rate charging without capacity fade, enabling battery pool reduction and floor space recovery in dense warehouse layouts.
Market Restraints
- Cobalt and lithium carbonate volatility:Cell material cost swings compress rental margin predictability and complicate long-term contract pricing for fleet operators.
- Regional cell production concentration:Asian cathode and electrolyte supply dominance exposes European and North American rental providers to logistics disruption and tariff exposure.
- Lead-acid residual infrastructure:Existing watering stations and charging rooms at legacy facilities create switching friction even where total cost of ownership favors lithium-ion alternatives.
Strategic Opportunities
- India warehousing expansion:Cold chain and organized retail growth in Maharashtra and Karnataka creates demand for flexible power solutions without capital-intensive battery ownership.
- CSRD reporting requirements:Corporate sustainability disclosure mandates in Europe are elevating Scope 3 emissions tracking, making rental models with supplier-managed recycling attractive to ESG-conscious procurement teams.
- Battery-as-a-service convergence:Integration of telematics-enabled state-of-charge monitoring with warehouse management systems enables predictive swap scheduling and uptime guarantees.
Industry Challenges
- Fire suppression engineering:Lithium-ion thermal runaway containment requires specialized gas-based extinguishing systems and ventilation design that many facility engineering teams lack experience specifying.
- Interoperability certification:UL 2580 and UN 38.3 testing timelines for new cell formats delay fleet rollout schedules and tie up working capital in pre-certified inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forklift Battery Rental Market |
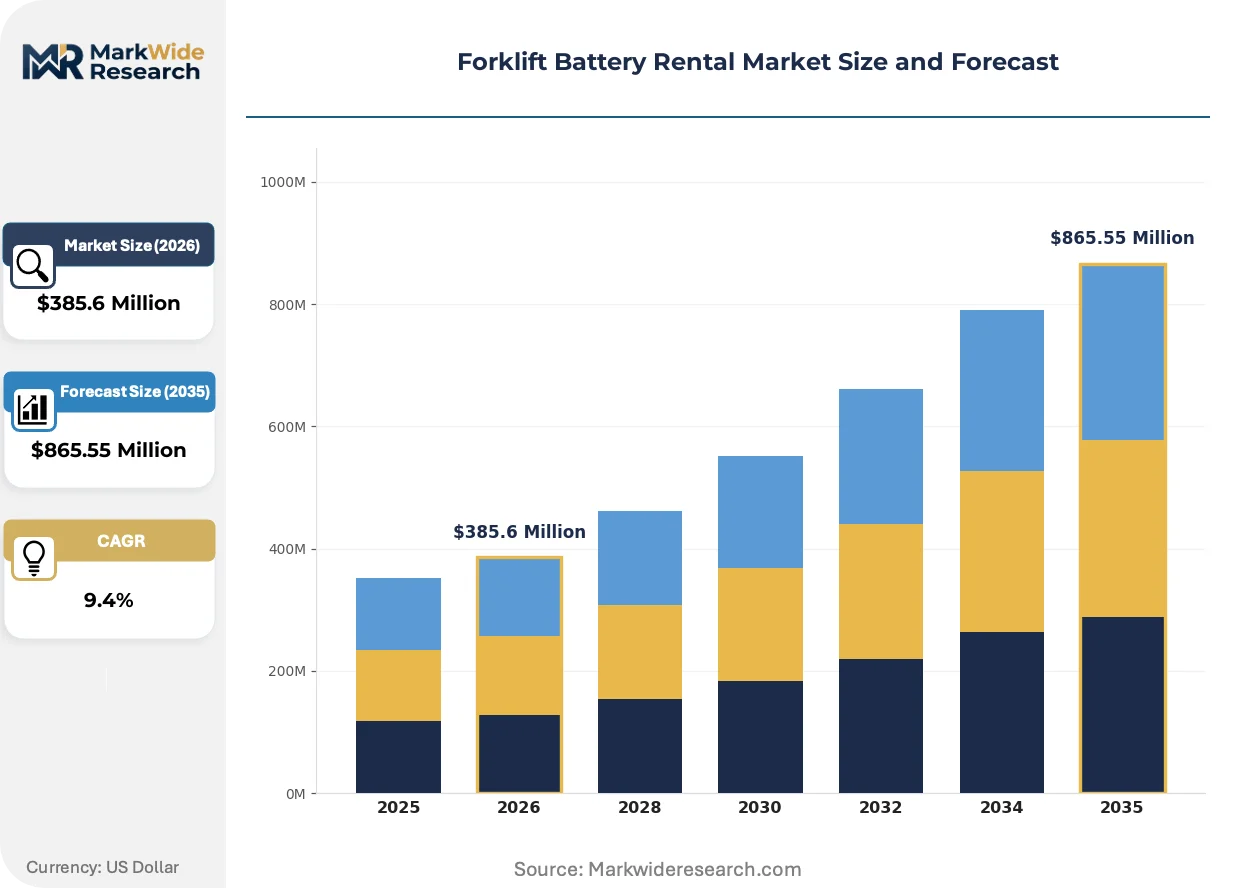
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $865.55 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lead Acid, Lithium-Ion, Nickel-Cadmium, Gel, Nickel-Metal Hydride End User Industry: Warehouse Management, Wholesale Distribution, Packaging Plants, Cold Storage Facilities, Third-Party Logistics Rental Duration: Short-Term, Medium-Term, Long-Term, Project-Based Delivery Model: On-Site Delivery, Off-Site Pickup, Scheduled Replacement, Emergency Swap Services |
| Companies Covered | Crown Equipment Corporation, KION Group AG, Toyota Industries Corporation, Hyster-Yale Materials Handling, Inc., Jungheinrich AG, EnerSys, East Penn Manufacturing, Exide Technologies, Saft Batteries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forklift Battery Rental Market Trends and Innovations
Rental fleet architecture is evolving from standardized battery pools toward chemistry-agnostic swap stations and telemetry-integrated power contracts that align supplier revenue with customer uptime metrics.
Modular lithium iron phosphate packs are modularizing forklift battery architecture by replacing monolithic lead-acid blocks with interchangeable 24V segments. Cold storage operators in Germany and the Netherlands are adopting these configurations fastest, drawn by reduced lifting equipment requirements and the ability to right-size capacity to seasonal demand swings. This modularity is modularizing residual value recovery by enabling cell-level refurbishment and second-life stationary storage redeployment.
The EU F-Gas Regulation is tightening enforcement timelines for industrial refrigeration equipment, indirectly elevating demand for electric material handling in temperature-controlled warehouses. Facility operators face simultaneous pressure to eliminate propane forklifts and upgrade cooling infrastructure, creating bundled procurement decisions that favor full-service battery rental over capital purchase. Cold chain third-party logistics providers in Belgium and Denmark are responding by specifying rental contracts with guaranteed cycle life and included recycling.
Consumption patterns among fleet operators are fragmenting away from single-vendor lift truck and battery pairings toward multi-brand equipment pools served by independent rental specialists. Large distribution centers in the United States are unbundling power supply from OEM maintenance agreements, selecting rental providers based on swap response time rather than equipment brand affiliation. This unbundling is most pronounced in automotive parts distribution and pharmaceutical wholesale verticals where uptime penalties exceed rental rate differentials.
Forklift Battery Rental Market Segmentation
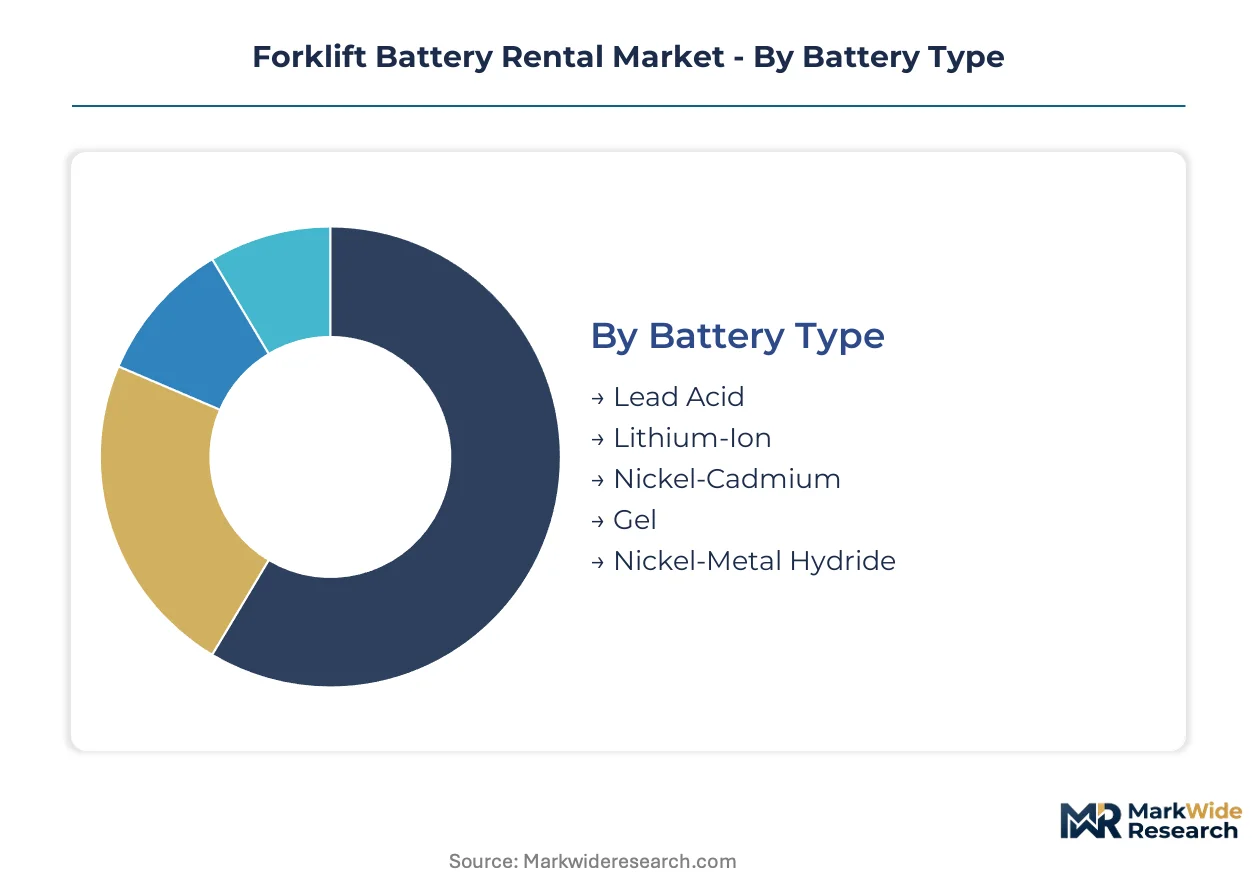
Segmentation in forklift battery rental reveals how capital deployment, operational tempo, and liability allocation shape contract structures. Rental providers calibrate pricing and service tiers to match the technical demands of each battery chemistry and the uptime requirements of specific facility types.
Battery Type:
Capital intensity varies sharply across chemistries, with lithium-ion requiring the highest upfront cell investment but delivering the lowest lifetime service burden.
- Lithium-Ion:Cells operate at 3.2V nominal with integrated battery management systems monitoring thermal thresholds. Cold storage operators in Germany and the Netherlands specify these for opportunity-charging compatibility and reduced ventilation infrastructure. EU F-Gas Regulation enforcement is accelerating displacement of propane fleets with lithium-ion electric alternatives in temperature-controlled warehouses.
- Lead Acid:Flooded and valve-regulated designs dominate legacy installed base with established watering and equalization protocols. Warehouse operators in the United States retain these where existing charging rooms and maintenance staff reduce switching friction, though OSHA indoor air quality standards are narrowing permissible use in enclosed facilities.
- Nickel-Cadmium:Sintered plate construction tolerates extreme temperature swings without capacity degradation. Aviation ground support and outdoor lumber yards specify these for reliability in unconditioned environments.
- Gel:Immobilized electrolyte eliminates spill risk and enables multi-directional mounting. Pharmaceutical distribution centers favor these for cleanroom compatibility and minimal gas emission during charging cycles.
- Nickel-Metal Hydride:Rare-earth hybrid chemistry offers intermediate energy density with reduced cadmium disposal liability. Niche applications in food-grade facilities with strict heavy-metal contamination protocols drive limited rental demand.
Lead acid absorbs the bulk of installed capacity; lithium-ion is expanding most quickly.
End User Industry:
Application-specific duty cycles determine rental contract terms, with multi-shift operations commanding premium service tiers and guaranteed swap response times.
- Warehouse Management:E-commerce fulfillment centers operating 18-20 hour schedules specify rental agreements with telemetry-integrated state-of-charge monitoring. Amazon and Walmart distribution networks in the United States unbundle power supply from OEM maintenance contracts to optimize swap logistics.
- Third-Party Logistics:Seasonal volume spikes and shipper turnover create demand for flexible rental durations without capital commitment. DHL and Kuehne+Nagel facilities across Belgium and Denmark specify contracts with included recycling to satisfy CSRD Scope 3 disclosure requirements.
- Cold Storage Facilities:Temperature-controlled warehouses require batteries with extended cycle life at sub-zero discharge rates. Operators face bundled procurement pressure from simultaneous EU F-Gas Regulation cooling upgrades and forklift fleet electrification mandates.
- Wholesale Distribution:Lower utilization rates and single-shift operations favor medium-term rental structures. Automotive parts distributors prioritize swap response time over chemistry performance to minimize downtime penalties.
- Packaging Plants:Corrugated and consumer goods facilities with moderate duty cycles select standardized battery pools. These operations emphasize capital preservation over opportunity-charging infrastructure investment.
Warehouse management commands the highest rental rates per kilowatt-hour; third-party logistics is gaining share fastest as e-commerce fulfillment networks expand.
Rental Duration:
Contract length directly determines supplier working capital exposure and customer switching costs, with longer terms locking in predictable revenue streams.
- Long-Term:Multi-year agreements spanning 36-60 months include full maintenance and end-of-life recycling obligations. Third-party logistics providers in cold chain verticals favor these to transfer thermal runaway liability and satisfy CSRD reporting requirements.
- Medium-Term:12-24 month contracts balance capital flexibility with rate predictability for warehouse operators with stable but uncertain growth trajectories. These structures concentrate margin pools by reducing churn across established distribution networks.
- Short-Term:Monthly or quarterly arrangements serve peak season surges and facility expansions. Retail fulfillment centers in the United States deploy these for holiday volume spikes without permanent fleet expansion.
- Project-Based:Event-driven or construction-linked rentals align billing with specific contract milestones. Infrastructure projects and temporary warehousing operations specify these for precise cost allocation.
Long-term contracts anchor supplier revenue stability; project-based terms are climbing fastest as just-in-time construction logistics expand.
Delivery Model:
Service architecture determines competitive differentiation, with response time guarantees becoming the primary selection criterion as battery unbundling from OEM agreements accelerates.
- Emergency Swap Services:Guaranteed sub-2-hour replacement protocols command premium pricing for 24/7 operations. Pharmaceutical wholesale and automotive parts distributors specify these where downtime penalties exceed rental rate differentials by an order of magnitude.
- Scheduled Replacement:Predictable swap windows aligned with shift changes minimize labor disruption. Large distribution centers in the United States optimize these through integration with warehouse management systems for predictive battery dispatch.
- On-Site Delivery:Battery pool placement at customer facilities eliminates transport delays but requires dedicated floor space and fire suppression infrastructure. Cold storage operators with constrained layouts resist this model despite faster swap availability.
- Off-Site Pickup:Customer collection from regional depots reduces supplier logistics cost but extends effective downtime. Smaller wholesale distributors with spare battery inventory accept this trade-off for lower rental rates.
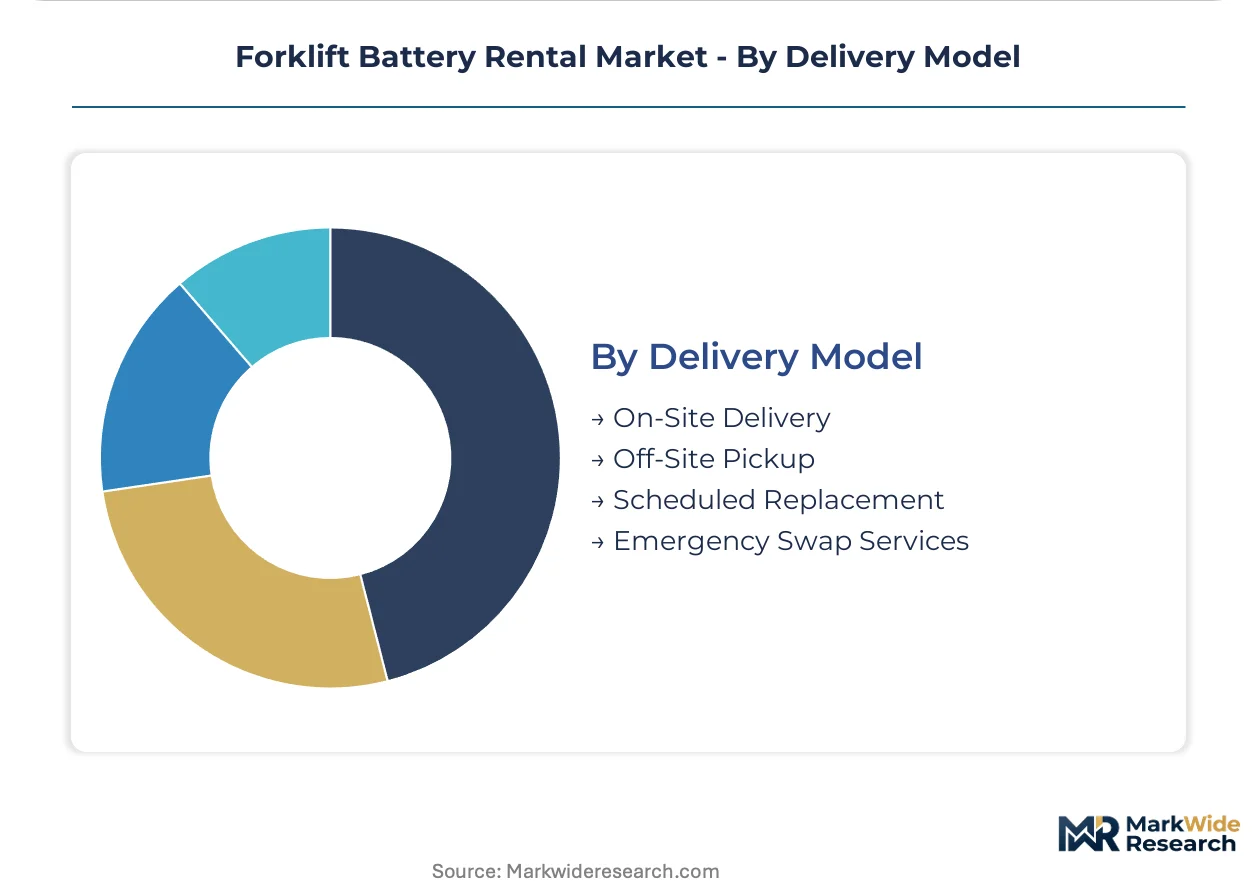
Scheduled replacement handles the greatest transaction volume; emergency swap services are scaling fastest as uptime guarantees become standard procurement requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zones in the United States and bonded logistics parks in China concentrate battery rental demand where tariff exemptions and deferred duty structures incentivize high-velocity warehousing operations.
United States
E-commerce fulfillment networks in the Midwest and Southeast drive lithium-ion rental uptake as Amazon and Walmart distribution centers eliminate lead-acid watering infrastructure. OSHA indoor air quality standards restrict propane forklift operation in enclosed facilities, elevating electric alternatives. Chicago and Dallas-Fort Worth logistics corridors anchor the highest rental contract density.
Germany
Automotive parts distributors in Bavaria and Baden-Württemberg unbundle power supply from OEM maintenance agreements to optimize swap logistics. The EU F-Gas Regulation accelerates cold storage electrification mandates. Hamburg and Rotterdam-Antwerp corridor facilities specify rental contracts with guaranteed cycle life and included recycling.
China
Yangtze River Delta bonded logistics zones absorb premium lithium-ion rental capacity for export-oriented manufacturing. MIIT dual carbon goals pressure warehouse operators toward zero-emission fleets. Shanghai and Suzhou cold chain hubs deploy modular battery pools to match seasonal demand fluctuations.
India
Organized retail expansion in Maharashtra and Karnataka creates demand for flexible power solutions without capital-intensive battery ownership. BIS certification requirements for industrial batteries elevate supplier compliance costs. Mumbai-Pune logistics belt operators favor medium-term rental structures to preserve balance sheet flexibility.
Netherlands
Third-party logistics providers in the Randstad cluster specify rental agreements with CSRD-aligned Scope 3 emissions tracking. EU Green Deal warehousing standards mandate electrification of material handling equipment. Rotterdam port logistics facilities lead adoption of telemetry-integrated battery swap scheduling.
Forklift Battery Rental Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated lift truck OEMs commanding captive fleet relationships while independent battery suppliers capture unbundled power contracts. Market structure tilts toward consolidation at the top tier where captive battery supply chains lock in multi-year rental agreements. Three archetypes dominate: vertically integrated material handling OEMs, independent electrochemical specialists with service networks, and regional rental operators with localized swap infrastructure. Competitive moves concentrate on M&A to acquire telemetry capabilities and geographic expansion into high-growth warehousing corridors.
Among integrated OEMs, Toyota Industries Corporation and Jungheinrich AG occupy positions where captive battery supply reinforces rental contract stickiness. EnerSys represents the independent electrochemical specialist archetype with established service density across North American and European logistics markets. Crown Equipment Corporation and KION Group AG exemplify equipment manufacturers extending into power-as-a-service models to capture recurring revenue streams beyond initial lift truck sales.
| Leading Market Players |
|---|
| Crown Equipment Corporation |
| KION Group AG |
| Toyota Industries Corporation |
| Hyster-Yale Materials Handling, Inc. |
| Jungheinrich AG |
| EnerSys |
| East Penn Manufacturing |
| Exide Technologies |
| Saft Batteries |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up battery rental specialists have consolidated regional swap networks across the American Midwest and German industrial corridors, concentrating pricing power with operators who control both cell inventory and emergency response fleets. This ownership pattern tightens supply discipline during cobalt carbonate volatility while allowing premium capture from warehouse operators facing OSHA indoor air quality compliance deadlines.
Pricing Analysis
Short lead-time premiums dominate contract structures, with sub-2-hour emergency swap services commanding rate multiples over scheduled replacement windows. Three-tier pricing structure across premium, standard, and economy levels stratifies by telemetry integration depth and thermal runaway liability allocation. Pricing pressure stems from lithium carbonate spot volatility compressing margin predictability on long-term agreements. Third-party logistics providers exhibit highest price sensitivity, while pharmaceutical wholesale distributors prioritize uptime guarantees over rate differentials.
Supply Chain Analysis
Freight costs from Chinese cathode and electrolyte production centers to European and North American assembly facilities absorb working capital before cells enter rental rotation. Cell manufacturing concentrates in China, South Korea, and Japan, with Korean producers supplying premium nickel-manganese-cobalt formulations for cold storage applications. Raw material dependencies span lithium carbonate, cobalt hydroxide, and copper foil substrates. Single-source vulnerability in refined lithium processing exposes rental providers to contract repricing risk. Distribution runs through regional battery depots positioned within two-hour drive time of major logistics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where the EU F-Gas Regulation and OSHA indoor air quality standards erect capital-intensive certification barriers that protect incumbents with pre-certified inventory and established recycling infrastructure.
For Market Incumbents: Acquire telemetry-enabled fleet management platforms to deepen predictive swap scheduling capabilities against independent rental specialists unbundling power from OEM maintenance agreements. Consolidate regional swap station density in the Chicago and Dallas-Fort Worth corridors where Amazon and Walmart distribution networks concentrate demand. Backward integration into cell refurbishment and second-life stationary storage redeployment secures residual value recovery as lithium-ion replacement cycles compress. For New Entrants and Emerging Players: Digital-channel direct procurement relationships with mid-sized automotive parts distributors bypass established OEM-captive rental contracts. Target project-based rental structures in Indian organized retail expansion across Maharashtra and Karnataka where capital constraints favor flexible power solutions without battery ownership. White-space exists in telemetry-integrated state-of-charge monitoring for cold storage operators facing simultaneous EU F-Gas Regulation cooling upgrades and fleet electrification mandates. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional rental operators with established depot infrastructure in Germany and the Netherlands where CSRD reporting requirements accelerate supplier-managed recycling demand. Long-term viability hinges on chemistry-agnostic swap station architecture accommodating solid-state and sodium-ion maturation. Monitor BIS certification timeline delays in India as inflection indicator for market entry window compression.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry-Integrated Fleet Management | Amazon and Walmart distribution networks prioritize predictive swap scheduling over brand affiliation. |
| Cell Refurbishment and Second-Life Redeployment | Modular lithium iron phosphate packs enable residual value recovery through stationary storage conversion. |
| Chemistry-Agnostic Swap Station Architecture | Cold storage operators in Belgium and Denmark demand flexibility for solid-state battery prototyping integration. |
| Regional Depot Density Expansion | Chicago and Dallas-Fort Worth logistics corridors anchor highest rental contract concentration. |
| Supplier-Managed Recycling Obligations | DHL and Kuehne+Nagel facilities specify CSRD-aligned Scope 3 emissions tracking in procurement. |
Research Methodology
Trade databases, customs filings, and SEC 10-K disclosures formed the secondary backbone for supplier capacity and pricing trend analysis. Primary interviews with fleet maintenance directors, warehouse operations managers, battery rental contract specialists, and cold storage facility engineers validated demand patterns and swap service requirements. Bottom-up cell deployment estimates triangulated against top-down logistics sector capital expenditure surveys across the analysis window.
Historical trendline analysis of rental contract volumes and chemistry mix shifts informed projection modeling across battery type, end-user industry, rental duration, and delivery model segments. CAGRs were derived from fitted growth curves calibrated to e-commerce fulfillment center expansion trajectories and EU F-Gas Regulation enforcement timelines. Forecast inputs incorporated opportunity-charging infrastructure penetration rates and thermal runaway protection system adoption curves.
Inputs from rental contract registries and logistics real estate databases were available through the study window; gaps in proprietary fleet utilization metrics introduce uncertainty bands around short-term rental demand spikes. Forecasts reflect documented assumptions regarding lithium carbonate price stabilization and certification timeline adherence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Forklift Battery Market
Batteries
Battery Coolant-Antifreeze Refractometer Market
Batteries
South America Primary Battery Market
Batteries
All-In-One Solar Storage Battery Market
Batteries
Utility Battery Market
Batteries
Automotive AGM Battery Market
Batteries
Europe Automotive Lead-Acid Battery Market
Batteries
Stretchable Battery Market
Batteries
Battery Separators Market
Batteries
India Electric Vehicle Battery Manufacturing Equipment Market
Batteries
Lithium Carbon Monofluoride Battery Market
Batteries
Carbon Black in Lead-Acid Battery Market
Batteries
America SLI Battery Market
Batteries
ASEAN Countries Electric Vehicle Battery Electrolyte Market
Batteries
Battery Cases Market
Batteries
Atomic Battery Market