
 Battery Cell Market | 2026-2036
Battery Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Cell Market Outlook
Direct procurement channels between automotive OEMs and cell manufacturers is narrowing as long-term offtake agreements replace spot-market purchasing. CATL leverages captive lithium refining and cathode production to secure volume commitments from European automakers. LG Energy Solution anchors its competitive stance through R&D intensity in high-nickel chemistries and dedicated production lines for premium vehicle platforms. BYD competes through in-house semiconductor and cell integration, controlling costs across the pack-to-vehicle architecture.
A battery cell is an electrochemical device comprising an anode, cathode, separator, and electrolyte that stores and releases energy through reversible redox reactions, with lithium-ion variants typically operating at nominal voltages of 3.2–3.7 V and energy densities of 150–300 Wh/kg depending on cathode chemistry. Its primary industrial purpose is to serve as the core energy storage component in electric vehicles, grid-scale storage installations, and portable electronics. Lithium-ion cells dominate current manufacturing throughput and margin pools due to established supply chains and continuous cost reduction, while solid-state technology occupies the fastest-growing development trajectory as manufacturers resolve ceramic electrolyte manufacturing scalability. Electric vehicle applications sustain the largest demand pull, though renewable energy storage is extending growth vectors as utility-scale deployments accelerate.
China's SAMR enforces GB standards on cell safety and cycle-life testing, while the EU's Battery Regulation mandates carbon footprint declarations and recycled-content quotas that reshape import eligibility for Asian suppliers. The US IRA ties production tax credits to North American assembly and critical mineral sourcing thresholds, redirecting capital toward localized cathode and cell plants. Stakeholders must monitor how divergent carbon-accounting rules across Beijing, Brussels, and Washington create compliance fragmentation that favors vertically integrated producers with multi-jurisdictional certification capabilities.
Market Dynamics
Long-term offtake agreements between automotive OEMs and cell manufacturers are displacing spot-market purchasing, locking in volume commitments that reshape capital allocation across the supply chain. This structural shift toward direct procurement channels concentrates margin capture among vertically integrated producers with captive material refining.
Growth Catalysts
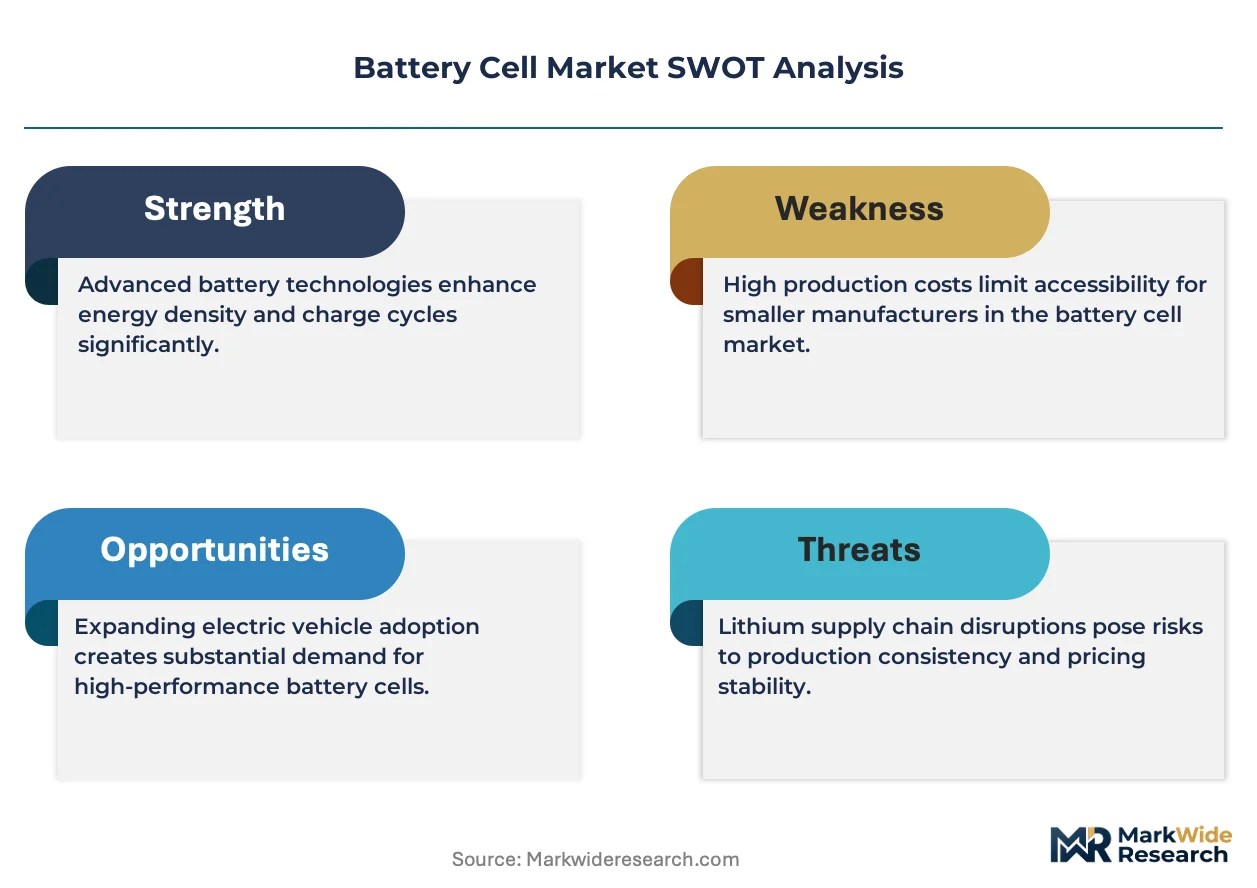
- EU Battery Regulation:Mandates for carbon footprint declarations and recycled-content quotas are redirecting investment toward localized cathode plants in Germany and Hungary.
- High-nickel cathode chemistries:Energy density improvements above 300 Wh/kg are extending electric vehicle range thresholds for premium vehicle platforms.
- South Korea's cathode precursor cluster:Production concentration near Gwangyang is reducing logistics costs for cell manufacturers serving European automakers.
Market Restraints
- Lithium carbonate price volatility:Spot market swings exceeding 400% annually are compressing margin visibility for cell manufacturers without captive mining assets.
- China's NMPA purity standards:Tightening cell-grade material specifications are disqualifying second-tier cathode suppliers from export eligibility.
- Solid-state ceramic electrolyte manufacturing:Scalability barriers in dry-room processing are delaying commercial deployment beyond pilot lines.
Strategic Opportunities
- US IRA production tax credits:North American assembly thresholds are incentivizing cathode and cell plant construction in Texas and Tennessee.
- Grid-scale storage deployments:Utility-scale installations are diversifying demand beyond automotive applications.
- Sodium-ion chemistry convergence:Lithium-substitute cells are opening cost-competitive segments for stationary storage and entry-level electric two-wheelers.
Industry Challenges
- Dry electrode coating expertise:Talent scarcity in solvent-free manufacturing processes is constraining solid-state pilot line expansion.
- Multi-jurisdictional carbon accounting:Divergent disclosure rules across Beijing, Brussels, and Washington are fragmenting compliance certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Cell Market |
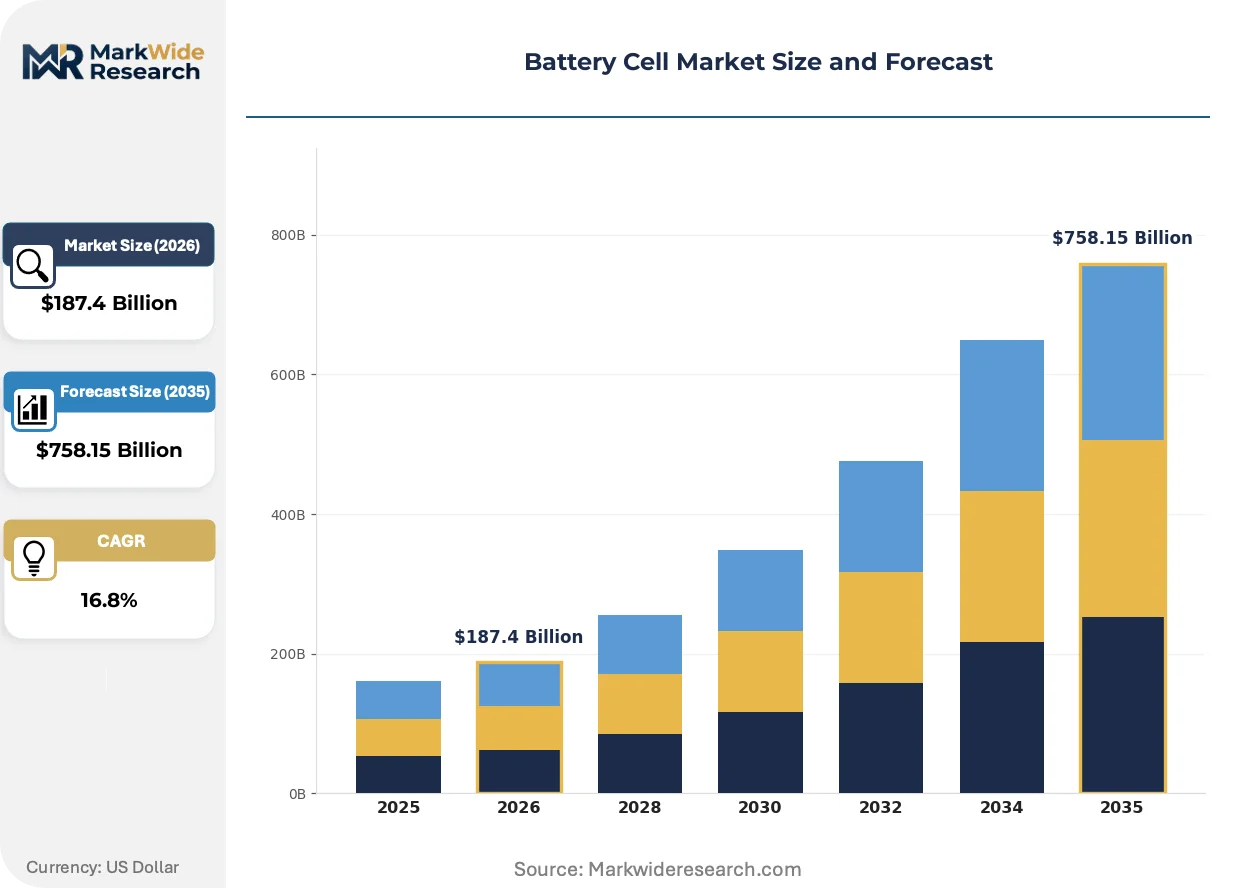
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $758.15 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Solid-State Application: Electric Vehicles, Consumer Electronics, Renewable Energy Storage, Industrial Equipment Form Factor: Cylindrical, Prismatic, Pouch, Custom Technology: Energy Density, Fast Charging, Battery Management Systems, Recycling Processes |
| Companies Covered | Contemporary Amperex Technology Co. Limited (CATL), LG Energy Solution Ltd., BYD Company Limited, Panasonic Holdings Corporation, Samsung SDI Co. Ltd., SK On Co. Ltd., Northvolt AB, CALB Group Co. Ltd., EVE Energy Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Cell Market Strategic Shifts
Solid-state electrolyte architectures and silicon-dominant anode formulations are compressing conventional lithium-ion performance boundaries. Manufacturing process innovations and regulatory carbon-accounting mandates are simultaneously reshaping competitive positioning.
Silicon-dominant anode materials are collapsing the energy density gap between conventional graphite cells and next-generation architectures. Automakers targeting 800-kilometer electric vehicle range specifications are qualifying silicon loadings above 10% by 2026. This chemistry transition is collapsing the cost-per-kilometer advantage that nickel-cobalt-manganese cells held in premium segments.
China's SAMR enforcement of updated GB standards on cell safety and cycle-life testing is raising entry barriers for export-oriented manufacturers. The regulations mandate thermal runaway propagation resistance and 1,500-cycle minimum lifespans under accelerated aging protocols. Cell producers without in-house testing laboratories are contracting third-party certification in Shanghai and Shenzhen to maintain NMPA registration validity.
Automotive OEMs are consolidating supplier bases through decade-long offtake agreements with volume floors and price collars. Tier-one cell manufacturers are responding by dedicating production lines to single-vehicle platforms. This concentration is most visible in Germany, where Volkswagen, BMW, and Mercedes-Benz have each anchored European cell plants with binding procurement commitments.
Battery Cell Market Segmentation
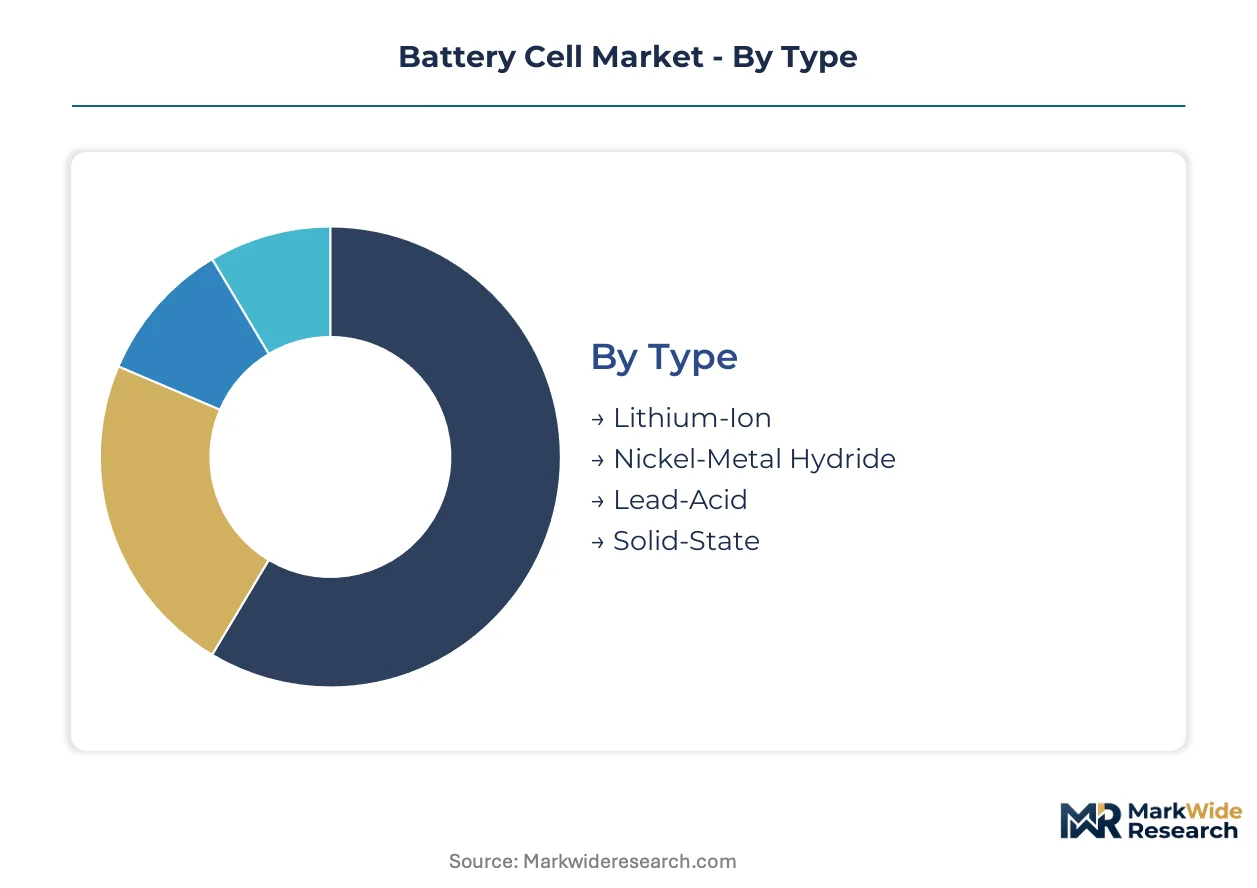
Battery cell segmentation reveals how chemistry choices, physical packaging, and end-use specifications fragment procurement strategies across automotive, electronics, and grid-scale buyers. Each dimension carries distinct margin profiles, certification requirements, and supply chain configurations that reshape competitive positioning.
Type:
Electrochemical chemistry determines energy density, cycle life, and cost trajectories across mobility and stationary applications.
- Lithium-Ion:Dominant chemistry employing layered oxide cathodes and graphite or silicon-blend anodes, achieving 150-300 Wh/kg energy density. Demand concentrates in electric vehicle platforms from European and Chinese automakers seeking range optimization, constrained by lithium carbonate spot price volatility exceeding 400% annually.
- Solid-State:Ceramic or sulfide electrolyte architectures replacing liquid electrolytes, promising 400+ Wh/kg density and enhanced thermal stability. Emerging adoption favors premium vehicle platforms where safety margins justify unit cost premiums, though dry-room processing scalability delays commercial deployment.
- Nickel-Metal Hydride:Mature chemistry using rare-earth metal hydride anodes, retaining cost advantages in hybrid electric vehicle applications with moderate duty cycles.
- Lead-Acid:Flooded or valve-regulated designs with established recycling infrastructure, serving industrial backup power and entry-level two-wheeler segments where capital cost sensitivity dominates.
Established volume favors Lithium-Ion; emerging adoption favors Solid-State.
Application:
End-use specifications fragment procurement volumes, certification intensity, and margin structures across mobility and stationary segments.
- Electric Vehicles:High-capacity cells with 800-kilometer range targets, fast-charging compatibility, and thermal runaway propagation resistance per China's SAMR GB standards. OEM offtake agreements with volume floors and price collars dominate procurement, concentrating margin capture among vertically integrated producers with captive cathode production.
- Consumer Electronics:Compact pouch and cylindrical formats prioritizing volumetric energy density and form factor flexibility. Demand clusters in Shenzhen and Seoul manufacturing corridors for smartphones, laptops, and wearables.
- Renewable Energy Storage:Grid-scale installations requiring 6,000+ cycle lifespans and containerized thermal management. Utility procurement is diversifying demand beyond automotive applications, with sodium-ion substitutes gaining traction for cost-sensitive stationary deployments.
- Industrial Equipment:Forklifts, mining vehicles, and material handling systems utilizing lead-acid or lithium-iron-phosphate variants for high-discharge rate tolerance and operational durability.
Electric Vehicles command the steepest expansion trajectory; Renewable Energy Storage is climbing fastest in absolute gigawatt-hour terms.
Form Factor:
Physical cell architecture shapes manufacturing equipment, pack integration complexity, and thermal management system design.
- Cylindrical:Rolled electrode jellyroll design with steel or aluminum casing, enabling automated high-speed winding and consistent quality control. Tesla's 4680 format and legacy 18650/21700 standards anchor demand in performance-oriented electric vehicle platforms.
- Prismatic:Stacked or wound electrodes in rectangular aluminum shells, optimizing space utilization in battery pack architectures. Chinese cell manufacturers dominate prismatic output for domestic electric vehicle OEMs.
- Pouch:Flexible polymer laminate packaging allowing thin-profile designs and high packing efficiency. Consumer electronics applications in South Korea and Japan favor pouch formats for smartphone and tablet integration.
- Custom:Application-specific dimensions for aerospace, marine, or medical devices requiring non-standard volumetric constraints and specialized safety certifications.
Cylindrical formats retain manufacturing scale advantages; prismatic designs are gaining share fastest in automotive pack integration.
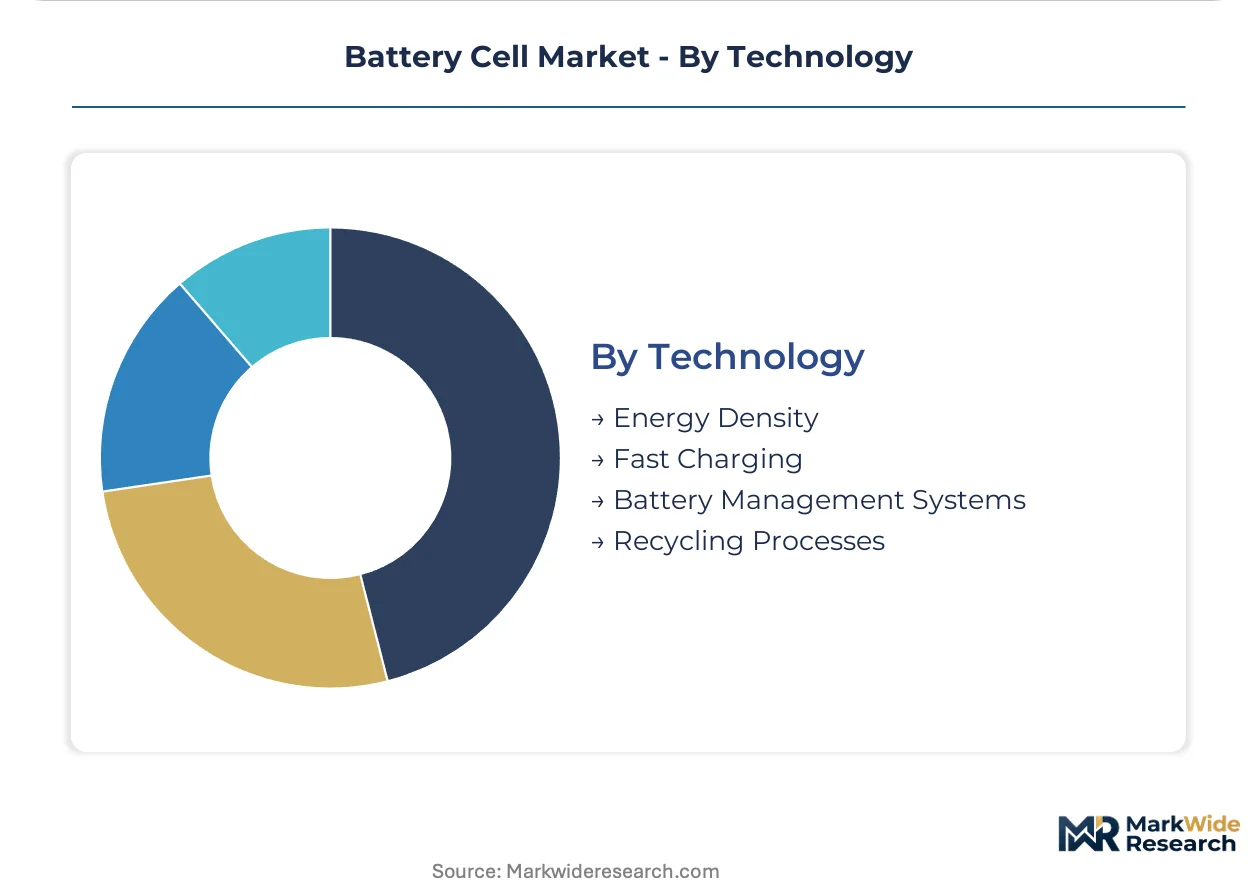
Technology:
Performance and lifecycle attributes differentiate cell value propositions beyond base chemistry and form factor specifications.
- Energy Density:Gravimetric and volumetric capacity metrics determining vehicle range and pack weight. High-nickel cathode chemistries from NCM 811 to NCM 9.5.5 compositions are extending thresholds above 300 Wh/kg for premium European vehicle platforms.
- Fast Charging:Electrode architectures and electrolyte additives enabling 10-80% state-of-charge in under 20 minutes. Silicon-dominant anode formulations and advanced thermal management are qualifying for 800-volt vehicle electrical architectures.
- Battery Management Systems:Cell-level monitoring electronics, state-of-health algorithms, and thermal runaway detection circuits. BYD and CATL integrate proprietary semiconductor and BMS designs to control pack-to-vehicle architecture costs.
- Recycling Processes:Hydrometallurgical and direct recycling methods recovering lithium, cobalt, and nickel from end-of-life cells. The EU Battery Regulation mandates recycled-content quotas that reshape import eligibility for Asian suppliers.
Energy Density improvements anchor premium positioning; Fast Charging capability is expanding most quickly as a competitive discriminator.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act production tax credits are redirecting cathode and cell plant construction toward Texas and Tennessee. China's SAMR enforces GB standards tightening export eligibility for second-tier suppliers. Germany's KBA implements EU Battery Regulation carbon footprint declarations that reshape import requirements.
China
CATL and BYD anchor domestic procurement for light-duty and commercial fleet electrification. SAMR's updated GB standards mandate thermal runaway propagation resistance and 1,500-cycle minimum lifespans under accelerated aging protocols. The Ningbo-Li ion materials corridor concentrates cathode precursor refining and cell assembly operations serving European automaker commitments.
United States
IRA assembly thresholds and critical mineral sourcing requirements concentrate investment in cathode active material plants. NHTSA coordinates with FERC on grid-scale storage safety standards for utility-scale deployments. Texas and Tennessee industrial zones host emerging cell manufacturing clusters targeting North American electric vehicle platform integration.
Germany
Volkswagen, BMW, and Mercedes-Benz have anchored European cell plants with binding decade-long offtake agreements. KBA enforcement of EU Battery Regulation mandates carbon footprint declarations and recycled-content quotas. The country's industrial heartland hosts dedicated production lines for premium vehicle platform specifications.
South Korea
LG Energy Solution and Samsung SDI serve European automaker demand through high-nickel chemistry R&D intensity. MFDS coordinates industrial safety standards for cell manufacturing facilities. The Gwangyang cathode precursor cluster reduces logistics costs for manufacturers exporting to German and Hungarian automotive integration plants.
Japan
Panasonic Holdings supplies cylindrical cell formats for performance-oriented electric vehicle platforms. METI directs national battery strategy toward solid-state ceramic electrolyte commercialization timelines. Domestic manufacturing corridors maintain specialized production for consumer electronics and automotive qualification programs.
Battery Cell Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated producers with captive material refining and dedicated production line commitments. Long-term offtake agreements with volume floors and price collars are displacing spot-market purchasing. Three archetypes dominate: scale-driven Asian conglomerates with upstream mining control, European specialists targeting premium automotive qualification, and Chinese producers leveraging semiconductor-cell integration. Capacity expansion and strategic partnerships constitute the dominant competitive moves reshaping capital allocation.
Among scale-driven Asian conglomerates, Contemporary Amperex Technology Co. Limited exemplifies the vertically integrated archetype through captive lithium refining and cathode production. LG Energy Solution Ltd. occupies a position within the high-nickel chemistry specialization tier. BYD Company Limited represents the semiconductor-cell integration model controlling costs across pack-to-vehicle architectures.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited (CATL) |
| LG Energy Solution Ltd. |
| BYD Company Limited |
| Panasonic Holdings Corporation |
| Samsung SDI Co. Ltd. |
| SK On Co. Ltd. |
| Northvolt AB |
| CALB Group Co. Ltd. |
| EVE Energy Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Lithium carbonate spot volatility exceeding 400% annually compresses margin visibility and forces dual-track procurement strategies that separate long-term contract tiers from spot-exposed supply chains. This commodity turbulence widens pricing spreads between captive-refining producers and merchant buyers while accelerating geographic diversification of cathode precursor sourcing.
Pricing Analysis
Certification level under China's SAMR GB standards and the EU Battery Regulation's carbon footprint declarations creates the primary spread between export-eligible premium cells and domestic-grade commodity supply. Long-term offtake agreements with volume floors and price collars dominate automotive procurement, while spot-market exposure persists in consumer electronics and industrial segments. Cost compression in standard-grade lithium-ion cells is intensifying because second-tier cathode suppliers face disqualification under tightening NMPA purity specifications. Entry-level electric two-wheeler and stationary storage buyers exhibit highest price sensitivity; premium European OEMs prioritize qualification timelines and cycle-life guarantees over unit cost.
Supply Chain Analysis
Upstream lithium feedstock draws from Australian spodumene concentrates, Chilean and Argentine brine operations, and Chinese hard-rock refining corridors. Cathode precursor manufacturing concentrates in China's Ningbo-Li ion materials corridor and South Korea's Gwangyang cluster, with graphite anode supply anchored in Heilongjiang province and synthetic production in Japan. Single-source vulnerability in ceramic electrolyte processing for solid-state architectures constrains pilot line expansion. Distribution runs through dedicated automotive logistics corridors serving German, Hungarian, and Texan cell integration plants, with containerized bulk shipment dominating grid-scale storage deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery cell demand sits in early-cycle expansion as utility-scale storage deployments extend growth vectors beyond automotive electrification penetration curves. OEM platform standardization around 800-volt architectures and silicon-dominant anode qualification timelines compress adoption windows for next-generation chemistries.
For Market Incumbents: Insulate margin pools by deepening captive control over lithium refining and cathode precursor production in jurisdictions qualifying for US IRA production tax credits. Dedicate production lines to single-vehicle platforms with decade-long offtake agreements to lock in volume commitments. Sodium-ion substitute technologies and solid-state ceramic electrolyte manufacturing delays represent the primary substitution threats requiring monitoring. For New Entrants and Emerging Players: Establish a beachhead in sodium-ion chemistry convergence for stationary storage and entry-level electric two-wheeler segments where lithium cost sensitivity dominates procurement decisions. Target grid-scale utility procurement channels in Texas and Tennessee industrial zones where IRA incentives reduce customer acquisition friction. Qualify under divergent carbon-accounting rules across Beijing, Brussels, and Washington to capture multi-jurisdictional certification premiums. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors vertically integrated producers with upstream mining control and in-house semiconductor integration. Five-to-ten-year viability hinges on securing cathode active material plant positions in North American and European regulatory zones. The signal to watch is dry electrode coating talent scarcity constraining solid-state pilot line expansion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks volume commitments from Volkswagen, BMW, and Mercedes-Benz platform integrations. |
| Backward Integration | Captive lithium refining secures CATL's cost position against carbonate spot volatility. |
| Capacity Expansion | Texas and Tennessee plant construction targets US IRA assembly threshold compliance. |
| Technology Licensing | Silicon-dominant anode formulations transfer to premium European vehicle platform suppliers. |
| Green Certification Program | EU Battery Regulation carbon footprint declarations reshape Asian supplier import eligibility. |
Study Parameters
Initial hypotheses were tested against primary input from cell manufacturing executives, automotive OEM procurement directors, cathode precursor plant managers, and utility-scale storage project developers and refined through secondary validation against SEC filings, customs and trade data, SAMR GB standard documentation, and IEA battery supply chain databases. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers produced convergent estimates.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation by chemistry type, form factor, end-use application, and regional regulatory cluster. CAGRs were derived from installed capacity ramp rates and OEM platform electrification timelines. Forecast inputs incorporated silicon-dominant anode qualification schedules and solid-state ceramic electrolyte manufacturing scalability assumptions.
Stress conditions across lithium carbonate spot price bands, IRA critical mineral sourcing threshold revisions, and EU Battery Regulation recycled-content quota implementations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory enforcement timing or technological breakthroughs in sodium-ion chemistry convergence. Cross-checking against IEA and BNEF external benchmark projections is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Absorbed Glass Mat (AGM) Separator Batteries Market
Batteries
Middle East and Africa SLI Battery Market
Batteries
Battery Terminal Brushes Market
Batteries
Japan Mobile Battery Market
Batteries
Bio Based Battery Market
Batteries
SLI Battery Market
Batteries
Asia-Pacific Industrial Battery Market
Batteries
South America Primary Battery Market
Batteries
Global Zinc Air Batteries Market
Batteries
Cobalt-Free Battery Market
Batteries
Submarine Batteries Market
Batteries
Battery Coolant-Antifreeze Refractometer Market
Batteries
Power-Sports Batteries Market
Batteries
Nuclear Battery Sales Market
Batteries
Medical Batteries Market
Batteries
Echelon Utilization of Power Battery Market