
 Automotive Active Purge Pump Market | 2026-2036
Automotive Active Purge Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Active Purge Pump Market Analysis
Modular integration of purge pump assemblies with onboard diagnostic modules is expanding buyer choice across vehicle platforms. Continental AG leverages its emissions systems portfolio to anchor European OEM relationships. BorgWarner Inc. competes through thermal management crossover expertise that extends into purge system design. Denso Corporation dominates Asian supply chains with manufacturing scale that sustains cost competitiveness across hybrid and conventional powertrains.
An automotive active purge pump is an electromechanical device that evacuates fuel vapor from the charcoal canister and delivers it to the engine intake manifold for combustion, typically operating at flow rates between 15–40 liters per minute and pressures up to 15 kPa. Electric purge pumps are displacing mechanical variants as engine bay electrification advances, with electronic control segments capturing margin pools through sensor fusion and precise duty-cycle management. Aftermarket providers occupy a mature channel with replacement-driven demand, while OEM direct supply concentrates around emission control applications where regulatory certification creates entry barriers.
The EPA enforces evaporative emission standards through onboard refueling vapor recovery mandates that shape product specifications for US-bound vehicles. California Air Resources Board operates parallel LEV III regulations that exceed federal thresholds and force dual-certification strategies from suppliers. The EU F-Gas Regulation and China MIIT fuel consumption standards add compliance layers that determine market access across production regions. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate redesign cycles and qualification timelines.
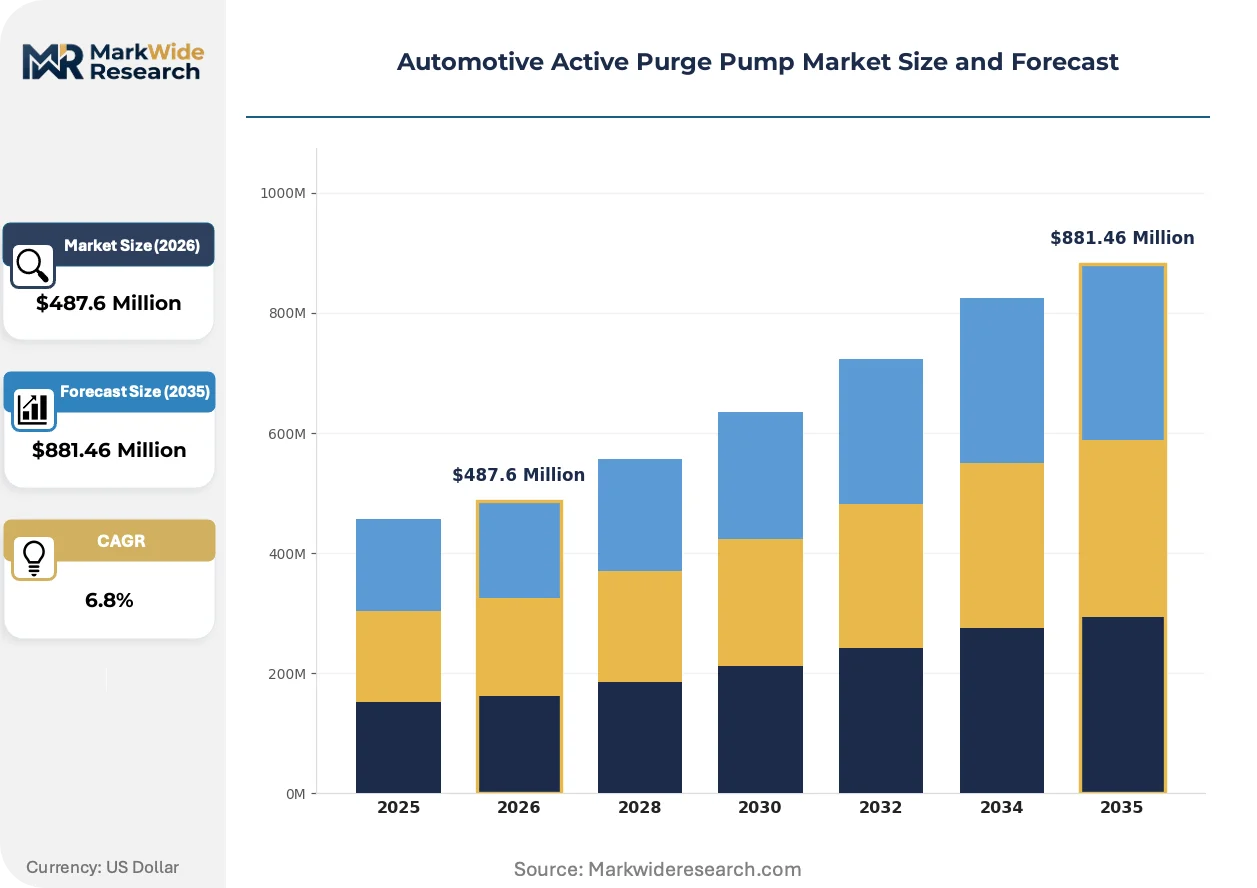
Market Dynamics
Engine bay electrification is compressing mechanical purge pump architectures while EPA Tier 3 and California LEV III certification timelines force synchronized redesign cycles across supplier networks.
Growth Catalysts
- EPA Tier 3 evaporative emission mandates:Onboard refueling vapor recovery requirements compel OEMs to upgrade from passive to active purge systems across light-duty vehicle portfolios.
- Hybrid powertrain proliferation:Intermittent engine operation in PHEVs and HEVs demands electrically actuated purge pumps capable of precise duty-cycle management during stop-start events.
- China MIIT fuel consumption standards:Stringent corporate average fuel economy targets accelerate adoption of active purge technology in domestic passenger vehicle production.
Market Restraints
- Neodymium magnet cost volatility:Rare-earth price swings in electric motor supply chains compress margins for pump manufacturers locked into fixed OEM pricing agreements.
- Dual-certification burden:Divergent EPA and CARB test protocols force redundant validation cycles that extend qualification timelines by 8-14 months.
- Mechanical purge pump residual demand:Low-cost vehicle segments in emerging markets sustain legacy architecture volumes that dilute scale advantages for electric variants.
Strategic Opportunities
- India BS-VI Stage II compliance gap:Tightening evaporative emission limits create first-mover advantage for suppliers establishing local assembly operations ahead of 2027 enforcement.
- Sensor fusion convergence:Integration of pressure transducers and flow meters into pump housings enables predictive diagnostic revenue streams through software-enabled service contracts.
- Aftermarket channel digitization:Direct-to-workshop platforms bypass traditional distributor networks and capture margin pools in replacement-driven demand segments.
Industry Challenges
- Embedded software validation:ISO 26262 functional safety certification for motor control algorithms demands specialized automotive firmware engineering talent in short supply.
- Legacy vehicle integration:Retrofit compatibility with 2010-2020 model year canister designs requires mechanical interface adaptation that fragments SKU portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Active Purge Pump Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Purge Pumps, Mechanical Purge Pumps, Solenoid Pumps, Vacuum Pumps End User: OEMs, Aftermarket Providers, Vehicle Manufacturers, Automotive Assemblers Technology: Hybrid Technology, Hydraulic Systems, Pneumatic Systems, Electronic Control Application: Fuel Evaporation Control, Emission Control, Engine Cooling, HVAC Systems |
| Companies Covered | Agilent Technologies, Aisin Seiki Co., Ltd., Continental AG, BorgWarner Inc., HELLA GmbH & Co. KGaA, Robert Bosch GmbH, Vitesco Technologies, Aptiv PLC, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Active Purge Pump Market Emerging Trajectories
Active purge pump architectures are converging with thermal management and diagnostic systems, blurring traditional component boundaries and reshaping supplier value propositions.
Brushless DC motor technology is integrating permanent magnet synchronous designs with integrated motor control electronics to deliver precise flow modulation across variable engine load conditions. Tier 1 suppliers are adopting these platforms for 48V mild-hybrid applications where electromagnetic compatibility requirements exceed mechanical pump capabilities. The technology is integrating pump, sensor, and controller into single housing assemblies that reduce wiring complexity and assembly labor content.
California Air Resources Board LEV III regulations are tightening evaporative emission thresholds to 0.020 grams per test, forcing active purge system duty cycles to extend into previously exempt operating modes. OEM engineering teams must recalibrate canister loading models and purge scheduling algorithms to maintain compliance across temperature extremes. European suppliers serving US-bound vehicle programs face parallel EU F-Gas Regulation constraints that complicate unified platform strategies.
Procurement consolidation among passenger vehicle OEMs is compressing approved vendor lists and elevating tier 0.5 integration responsibilities onto pump suppliers. Long-term service agreements now bundle hardware supply with diagnostic software licensing and over-the-air update obligations. German and Chinese automotive groups are most aggressive in unbundling traditional component purchasing from embedded system lifecycle management.
Automotive Active Purge Pump Market Segmentation
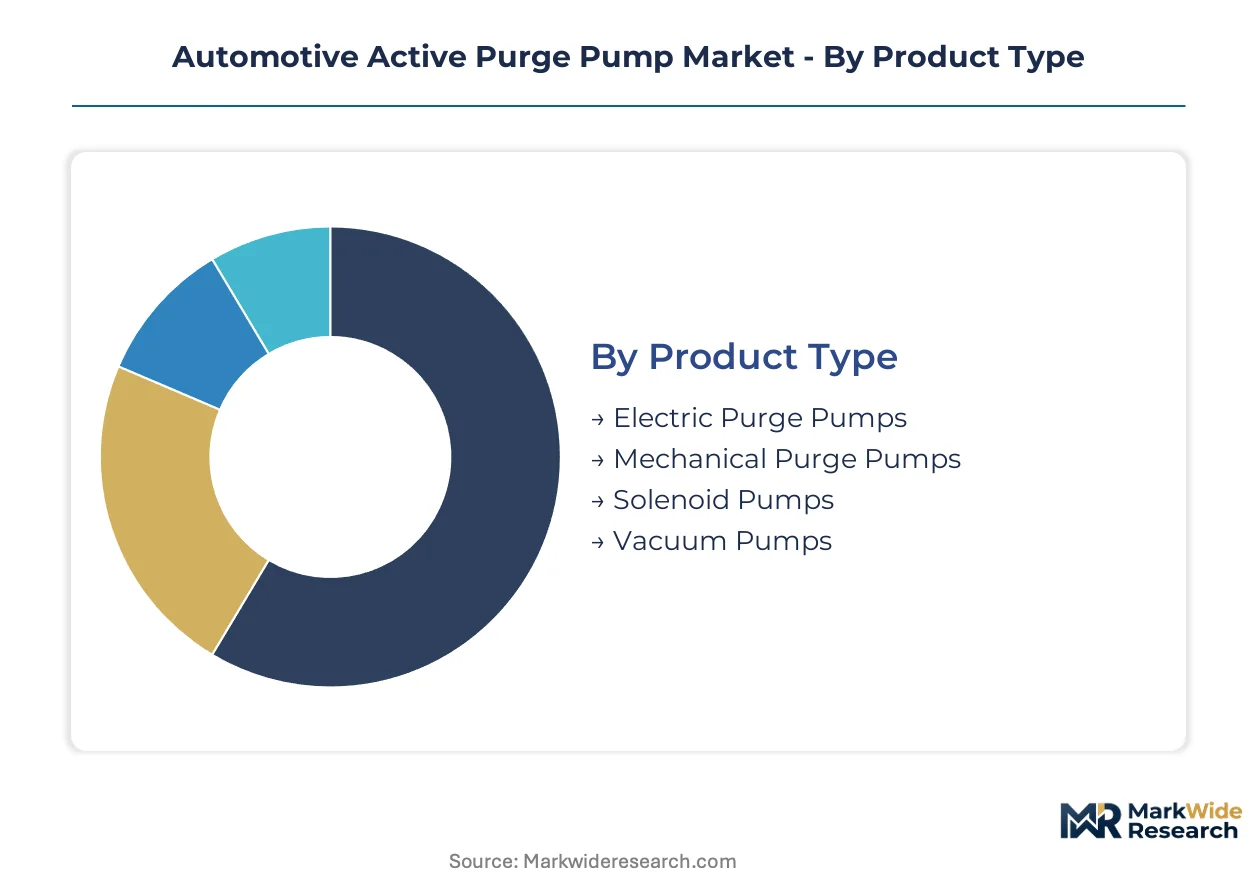
Segmentation in the automotive active purge pump market reflects divergent technology maturity curves and regulatory compliance tiers across vehicle platforms. Suppliers calibrate product portfolios against electrification roadmaps and emission certification pathways that vary by production region and OEM integration strategy.
Product Type:
Technical specifications differentiate purge pump architectures across motor topology, flow modulation capability, and thermal operating envelopes.
- Electric Purge Pumps:Brushless DC motors with integrated motor control electronics deliver precise duty-cycle modulation between 15–40 liters per minute. Demand concentrates in US-bound passenger vehicles facing EPA Tier 3 evaporative emission mandates that require active purge capability across all operating modes.
- Mechanical Purge Pumps:Engine-driven diaphragm or vane pumps operate without electrical actuation, suited to cost-optimized vehicle segments in emerging markets where regulatory lead times extend compliance deadlines.
- Solenoid Pumps:Electromagnetic actuation provides discrete on-off flow control for auxiliary vapor recovery functions in commercial vehicle applications.
- Vacuum Pumps:Dedicated vacuum generation units serve hybrid powertrains where engine manifold vacuum availability is intermittent during electric-only operation.
Electric purge pumps lead on scale; vacuum pumps lead on momentum as hybrid powertrain proliferation accelerates.
End User:
Customer type determines certification burden, pricing power, and lifecycle service obligations across the value chain.
- OEMs:Direct supply relationships with passenger vehicle manufacturers carry ISO 26262 functional safety certification requirements and multi-year platform lock-in. Procurement concentrates among German and Chinese automotive groups bundling hardware with diagnostic software licensing.
- Vehicle Manufacturers:Light-duty and commercial vehicle producers specify purge systems against regional emission test protocols, with US and Chinese producers driving active purge adoption fastest.
- Aftermarket Providers:Replacement-driven demand channels serve 2010–2020 model year vehicles with mechanical interface adaptation requirements that fragment SKU portfolios.
- Automotive Assemblers:Contract manufacturing operations for emerging market vehicle production sustain legacy mechanical pump volumes where cost minimization dominates specification.
OEMs command the steepest expansion trajectory; aftermarket providers anchor residual revenue stability.
Technology:
Technology selection tracks powertrain electrification intensity and control precision requirements across vehicle architectures.
- Electronic Control:Sensor-fusion platforms integrating pressure transducers and flow meters enable predictive diagnostics and over-the-air calibration updates. Demand concentrates in 48V mild-hybrid applications where electromagnetic compatibility requirements exceed mechanical alternatives.
- Hybrid Technology:Dual-mode electric-mechanical architectures bridge transition vehicle programs optimizing cost against compliance timing.
- Hydraulic Systems:Fluid-actuated purge mechanisms serve niche commercial vehicle segments with extreme temperature operating requirements.
- Pneumatic Systems:Compressed air-driven pumps maintain presence in heavy-duty diesel applications with abundant auxiliary air supply.
Electronic control leads on scale; hybrid technology leads on momentum as powertrain transition timelines compress.
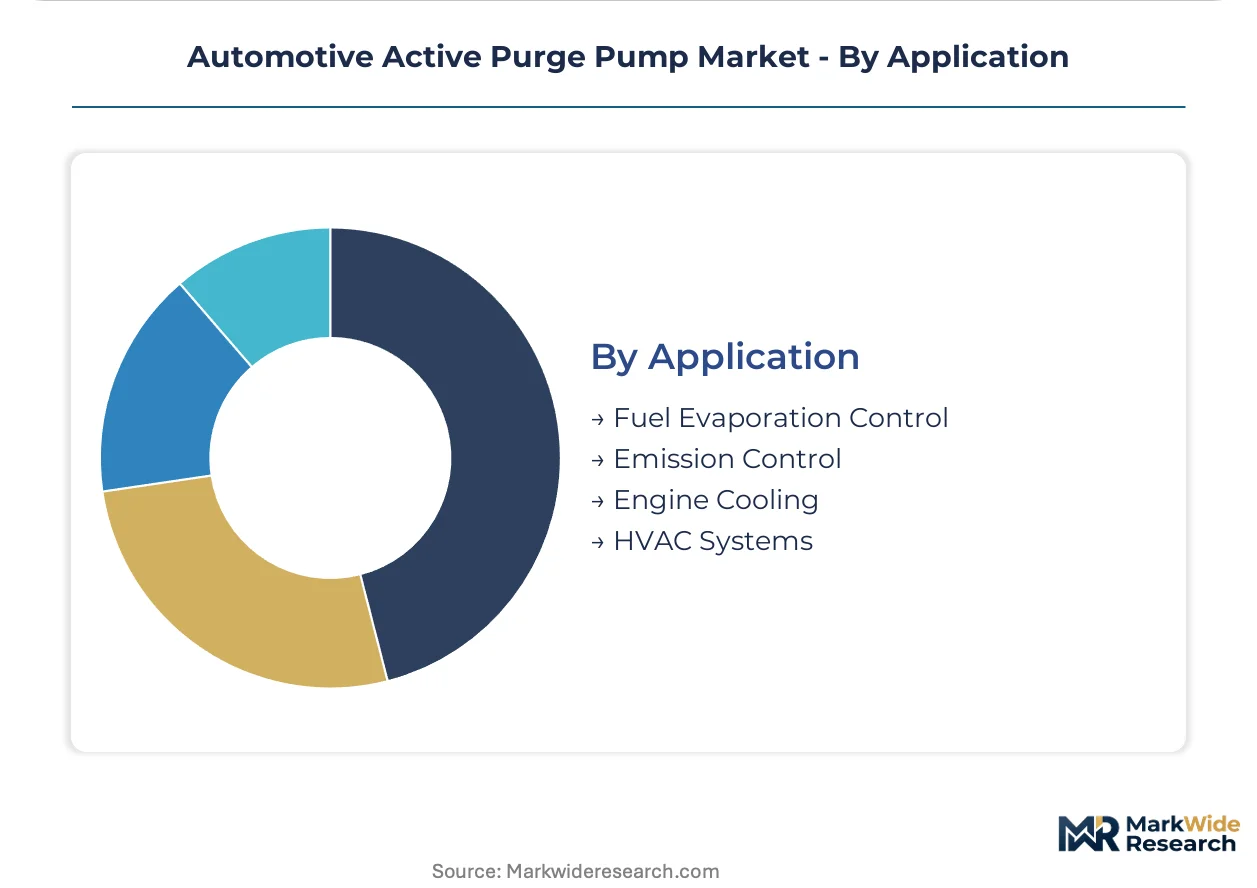
Application:
Application segmentation aligns with emission control subsystem integration depth and thermal management convergence trends.
- Fuel Evaporation Control:Charcoal canister evacuation and vapor delivery to intake manifold represents core active purge function. Demand concentrates in US, Germany, and China production where evaporative emission standards are strictest.
- Emission Control:Broader system integration including onboard refueling vapor recovery and leak detection pump functions expands supplier responsibility into tier 0.5 integration roles.
- Engine Cooling:Auxiliary coolant circulation support in start-stop powertrains extends purge pump thermal management crossover applications.
- HVAC Systems:Climate control subsystem integration in electric vehicles repurposes pump architectures for refrigerant loop management.
Fuel evaporation control leads on scale; emission control leads on momentum as regulatory thresholds tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive active purge pump industry traces its commercial origins to German emissions engineering clusters that developed evaporative control systems for European OEMs during the 1990s regulatory expansion. This heritage established technical standards later adopted by US and Asian manufacturers confronting parallel emission mandates.
United States
EPA Tier 3 onboard refueling vapor recovery requirements drive active purge system upgrades across light-duty portfolios. The California Air Resources Board operates LEV III thresholds at 0.020 grams per test, forcing dual-certification strategies from suppliers. Detroit-area engineering centers coordinate validation cycles for US-bound vehicle programs.
Germany
EU F-Gas Regulation compliance layers intersect with export requirements for US and Chinese markets. Stuttgart and Munich host tier 1 supplier headquarters managing unified platform strategies across regulatory jurisdictions. Baden-Württemberg manufacturing clusters produce integrated pump-sensor-controller assemblies for 48V mild-hybrid applications.
China
MIIT fuel consumption standards accelerate domestic adoption of active purge technology in passenger vehicle production. Shanghai and Yangtze River Delta manufacturing bases supply both local OEMs and export programs. Beijing-Tianjin-Hebei corridor concentrates engineering resources for hybrid powertrain integration.
Japan
METI energy efficiency guidelines shape supplier specifications for domestic and export vehicle production. Toyota City and Nagoya industrial zones anchor development of brushless DC motor platforms with integrated control electronics. Kanto region engineering centers focus on sensor fusion convergence for predictive diagnostics.
India
BS-VI Stage II evaporative emission limits create compliance-driven demand ahead of 2027 enforcement. Chennai and Pune automotive clusters attract supplier assembly investments for domestic and export vehicle programs. Delhi-NCR technical centers coordinate with global OEMs on platform localization requirements.
Automotive Active Purge Pump Market Vendor Landscape
Premium-margin players sit above commodity-margin players across integration depth and software licensing capabilities. The vendor base organizes around tier 0.5 integration responsibilities, tier 1 component supply, and specialized motor manufacturing. Three archetypes dominate: full-system integrators bundling hardware with diagnostic platforms; component specialists focusing on pump mechanics and motor assemblies; and electronics providers supplying control modules and sensor fusion. Competitive moves concentrate on strategic partnerships for software-enabled service contracts and geographic expansion into emerging market compliance windows.
Among German-based full-system integrators, Continental AG and Robert Bosch GmbH exemplify tier 0.5 positioning through bundled hardware and embedded system lifecycle management. Denso Corporation represents the Japanese manufacturing-scale archetype with cost competitiveness across hybrid and conventional powertrains. BorgWarner Inc. occupies the thermal management crossover specialist position, extending expertise into purge system design through integrated engineering capabilities.
| Leading Market Players |
|---|
| Agilent Technologies |
| Aisin Seiki Co., Ltd. |
| Continental AG |
| BorgWarner Inc. |
| HELLA GmbH & Co. KGaA |
| Robert Bosch GmbH |
| Vitesco Technologies |
| Aptiv PLC |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
EPA Tier 3 evaporative emission mandates gate qualified supply and premium-tier pricing access by requiring ISO 26262 functional safety certification that only established tier 1 suppliers possess. OEM procurement teams pay certification premiums for active purge pumps bundled with diagnostic software licensing, while uncertified mechanical variants compete on cost in emerging market segments where compliance deadlines remain distant.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-certified electric purge pumps with embedded diagnostics from basic electric variants and legacy mechanical pumps. Price differentiation rests on certification grade and volume scale, with OEM direct contracts commanding premiums over aftermarket channels. Cost compression in the economy tier is intensifying because Chinese domestic suppliers are scaling brushless DC motor production for local vehicle programs. Fleet operators and contract assemblers exhibit the highest price sensitivity, while German and US OEMs prioritize certification compliance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for warranty returns and remanufactured pump cores are emerging as secondary supply sources for aftermarket providers serving 2010-2020 model year vehicles. Manufacturing concentrates in Germany, China, and Japan, with Baden-Württemberg and Yangtze River Delta clusters producing integrated pump-sensor-controller assemblies. Neodymium permanent magnets and precision-machined aluminum housings draw from concentrated rare-earth and metallurgical supply chains. Single-source vulnerability in electric motor laminations threatens production continuity. Distribution runs through tier 1 direct supply to OEMs, with aftermarket channels fragmenting across regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Tier 3 and California LEV III certification timelines synchronize demand cycles across supplier networks. Stakeholders must align capability investments with emission standard enforcement windows to capture platform lock-in opportunities.
For Market Incumbents: Deepen embedded software validation capabilities to defend against electronics specialists encroaching on tier 0.5 integration roles. Expand backward integration into brushless DC motor manufacturing to offset neodymium price volatility and secure margin control. Prioritize dual-certification engineering resources to compress EPA-CARB validation timelines that currently extend qualification cycles. For New Entrants and Emerging Players: Direct-to-workshop digital platforms offer the most penetrable route to bypass entrenched distributor networks in the aftermarket channel. Target India's BS-VI Stage II compliance gap ahead of 2027 enforcement by establishing local assembly partnerships with Chennai and Pune automotive clusters. Lead with sensor fusion convergence capabilities to differentiate against mechanical pump incumbents in cost-sensitive segments. For Investors and Strategic Acquirers: Valuations sit cheapest among component specialists with pump mechanics expertise but lacking diagnostic software licensing revenue streams. Long-term viability over a 5-10 year horizon favors suppliers bundling hardware with over-the-air update obligations under long-term service agreements. Monitor California Air Resources Board threshold tightening beyond 0.020 grams per test as the signal for accelerated active purge system replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Unifies purge pump architectures across 48V mild-hybrid and PHEV powertrains for Continental AG and Robert Bosch GmbH. |
| Battery Supply Agreement | Secures neodymium permanent magnet volumes for brushless DC motor production against rare-earth price volatility. |
| Software-Defined Vehicle Investment | Enables predictive diagnostic revenue streams through sensor fusion convergence in Denso Corporation control modules. |
| Geographic Manufacturing Footprint | Establishes local assembly in India ahead of BS-VI Stage II enforcement to capture first-mover compliance advantage. |
| Charging Infrastructure Partnership | Extends purge pump thermal management expertise into electric vehicle HVAC refrigerant loop applications. |
Methodological Framework
Direct dialogue with OEM platform engineers, tier 1 supplier procurement leads, aftermarket distributors, and dealership service operations grounded qualitative findings in operational reality. Secondary validation drew from EPA certification filings, California Air Resources Board test protocol documentation, vehicle production databases, and IHS Markit registration data. Bottom-up unit demand estimates triangulated against top-down OEM platform penetration assumptions to constrain forecast variance.
Segmented outputs across the projection horizon reflect vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs emerged from logistic diffusion modeling of electric purge pump substitution rates against mechanical baseline decay. Industry-specific inputs included EPA Tier 3 phase-in schedules, China MIIT corporate average fuel consumption target trajectories, and hybrid powertrain production mix projections by OEM group.
The model assumes a particular technology adoption path; alternative pathways for solid-state sensor integration or silicon carbide motor control electronics would alter the outlook for incumbent brushless DC architectures. Forecasts reflect assumptions regarding regulatory enforcement consistency and rare-earth supply chain stability. Practitioners should monitor CARB threshold announcements, MIIT standard revisions, and neodymium price indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Global Driveline Market
Powertrain
Reciprocating Engine Market
Powertrain
Automatic Transmission Solenoid Pack Market
Powertrain
North America Torque Vectoring Market
Powertrain
Drive Mode-Linked Powertrain Actuator Systems Market
Powertrain
Global Automotive Engine Pulley Market
Powertrain
Transmission Oil Pumps Market
Powertrain
United States Automotive Engine Oils Market
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Europe Internal Combustion Engines Market
Powertrain
Diesel Particulate Filter (DPF) Market
Powertrain
Modular Belt Drive Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Europe Automatic Transmission for Passenger Car Market
Powertrain
Automotive Chain Tensioners Market
Powertrain
Timing Belt Market