
 North America Bee Products Market | 2026-2036
North America Bee Products Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bee Products Market Analytics
Functional food and beverage manufacturers are rotating toward bee-derived ingredients faster than conventional bakeries and table-sweetener channels. Dutch Gold Honey leverages vertical integration from hive to bottle across Pennsylvania and Florida operations. Wedderspoon Organic differentiates through Manuka honey certification standards and direct-to-consumer channel control. Nature Nate's Honey Co. sustains brand strength via raw, unfiltered positioning in mainstream retail.
Bee products encompass honey, beeswax, pollen, and propolis—substances produced by Apis mellifera colonies, with honey containing fructose-glucose ratios near 1.2:1 and enzymatic activity measured by diastase number. These materials serve food formulation, topical therapeutics, and nutritional supplementation across industrial and consumer markets. Honey dominates product type value pools due to established food industry procurement, while propolis extracts represent the fastest-expanding segment as pharmaceutical and dietary supplement applications deepen. Distribution channel structure shows online retail gaining fastest, though supermarkets still anchor volume throughput for mass-market honey SKUs.
The FDA oversees dietary supplement labeling and New Dietary Ingredient notifications for propolis and pollen extracts, while USDA Organic certification and state-level apiary inspection programs in California, Florida, and Texas shape production compliance burdens. The EPA regulates pesticide exposure near pollinator habitats, directly constraining hive placement density in agricultural zones. Stakeholders must monitor how state pollinator protection plans and evolving organic honey authentication standards reshape sourcing requirements and margin structures.
Market Dynamics
The North America bee products market is being restructured by the FDA's New Dietary Ingredient notification pathway, which now governs propolis and pollen extract commercialization timelines and creates compliance bottlenecks that favor capitalized incumbents over new entrants.
Growth Catalysts
- EPA pollinator protection mandates:Restrictions on neonicotinoid applications near hive clusters in California's Central Valley are stabilizing colony survival rates and securing supply continuity for processors.
- Manuka honey certification standards:Wedderspoon Organic's methylglyoxal grading protocols are creating premium price tiers that expand margin pools beyond commodity honey benchmarks.
- Dietary supplement channel expansion:Propolis extract demand from nutraceutical formulators is pulling volume away from traditional food processors and accelerating SKU diversification.
Market Restraints
- Input cost volatility:Varroa mite treatment expenses and supplemental feeding costs during drought cycles in Texas and Florida apiaries compress producer margins unpredictably.
- Supply concentration risk:California's Central Valley corridors host disproportionate hive density, creating single-point vulnerability to wildfire smoke and agricultural pesticide drift events.
- Substitution threat:Plant-based sweeteners and synthetic propolis analogs from fermentation biotechnology are capturing price-sensitive segments in mass retail honey categories.
Strategic Opportunities
- Direct-to-consumer channel control:Subscription honey models and apiary-tourism integrations in Pennsylvania and Florida are bypassing supermarket margin extraction.
- USDA Organic certification tailwind:Updated organic livestock origin requirements for honey bees are creating authentication premiums that reward compliant producers.
- Pharmaceutical application expansion:Propolis extract partnerships with topical therapeutic developers are opening prescription-adjacent revenue streams beyond over-the-counter supplements.
Industry Challenges
- Apiary labor scarcity:Commercial beekeeper apprenticeship programs in the US and Canada are failing to replace retiring operators, constraining hive expansion capacity.
- NDI notification timelines:FDA dietary ingredient review periods for novel propolis formulations are extending product launch cycles by 18-24 months.
- Authentication technology integration:Isotope ratio mass spectrometry and pollen DNA barcoding deployment costs are prohibitive for mid-scale honey packers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bee Products Market |
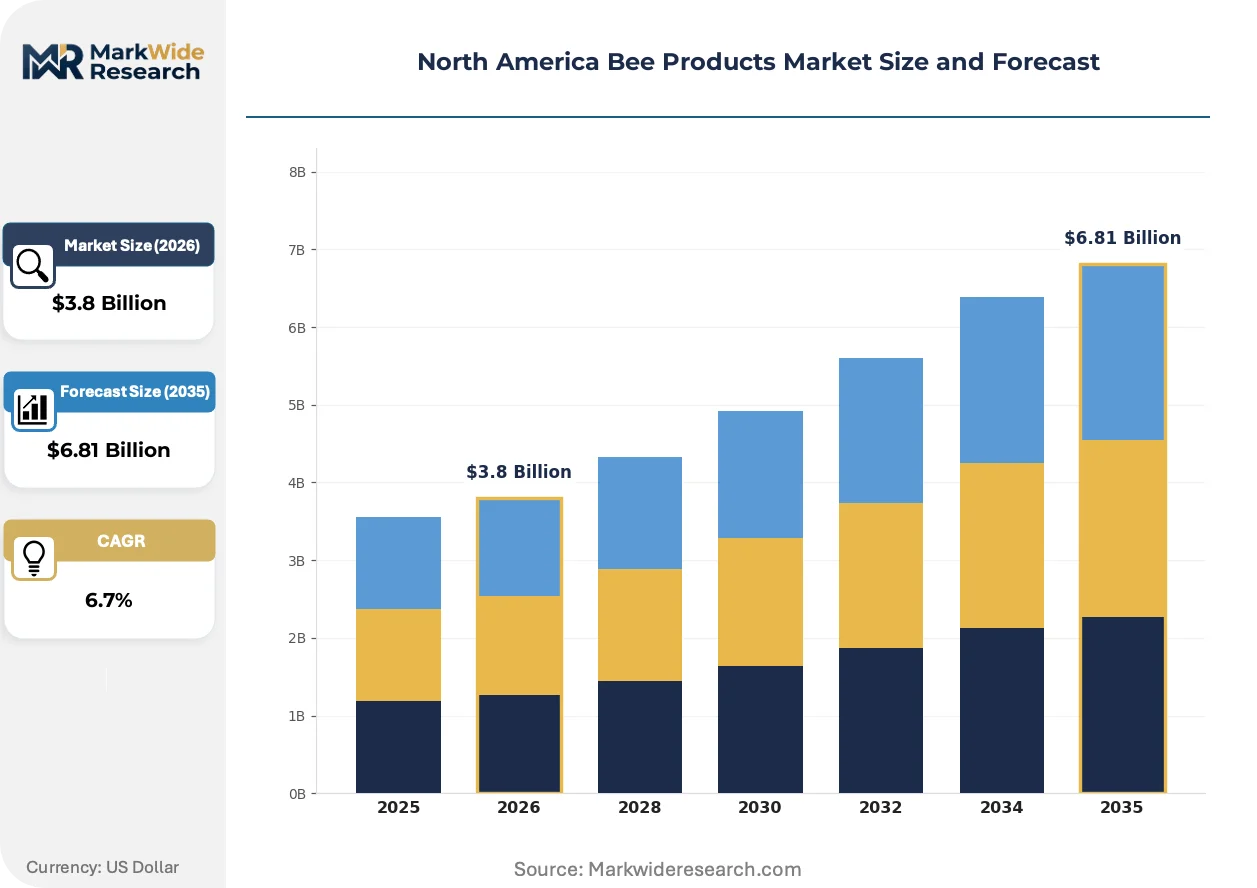
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Honey, Beeswax, Pollen, Propolis End User: Food Industry, Cosmetics, Pharmaceuticals, Dietary Supplements Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Application: Food Additive, Skin Care, Immune Support, Natural Remedies |
| Companies Covered | Dutch Gold Honey, Wedderspoon Organic, Nature Nate's Honey Co., Barkman Honey, GloryBee, Savannah Bee Company, Comvita USA, Sue Bee Honey, Bee Maid Honey Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bee Products Market Evolving Landscape
Blockchain-based hive-to-shelf traceability systems are reshaping procurement verification standards across the North American supply chain. Three distinct movements are compressing legacy operational models.
Nuclear magnetic resonance spectroscopy for honey authenticity verification is displacing traditional pollen analysis and stable carbon isotope methods at major US retail procurement desks. Costco and Whole Foods Market quality assurance teams are mandating NMR screening for private-label honey SKUs. The technology is compressing fraud tolerance thresholds and forcing packers to consolidate around certified laboratory partnerships.
The FDA's draft guidance on New Dietary Ingredient notifications for bee-derived substances is tightening pre-market submission requirements for propolis and royal jelly extracts. Supplement manufacturers must now demonstrate 75 years of documented use or submit comprehensive safety dossiers. California and Texas-based formulators are responding by archiving historical ethnobotanical literature to grandfather ingredient status.
Raw, unfiltered honey positioning is capturing refrigerated section placement in conventional supermarkets, displacing shelf-stable processed honey in center-store locations. Nature Nate's Honey Co. and regional apiary brands are securing end-cap displays previously reserved for Greek yogurt and kombucha. This rotation is most visible in Texas H-E-B and California Safeway banners where perimeter-store traffic exceeds center-store conversion rates.
North America Bee Products Market Segmentation
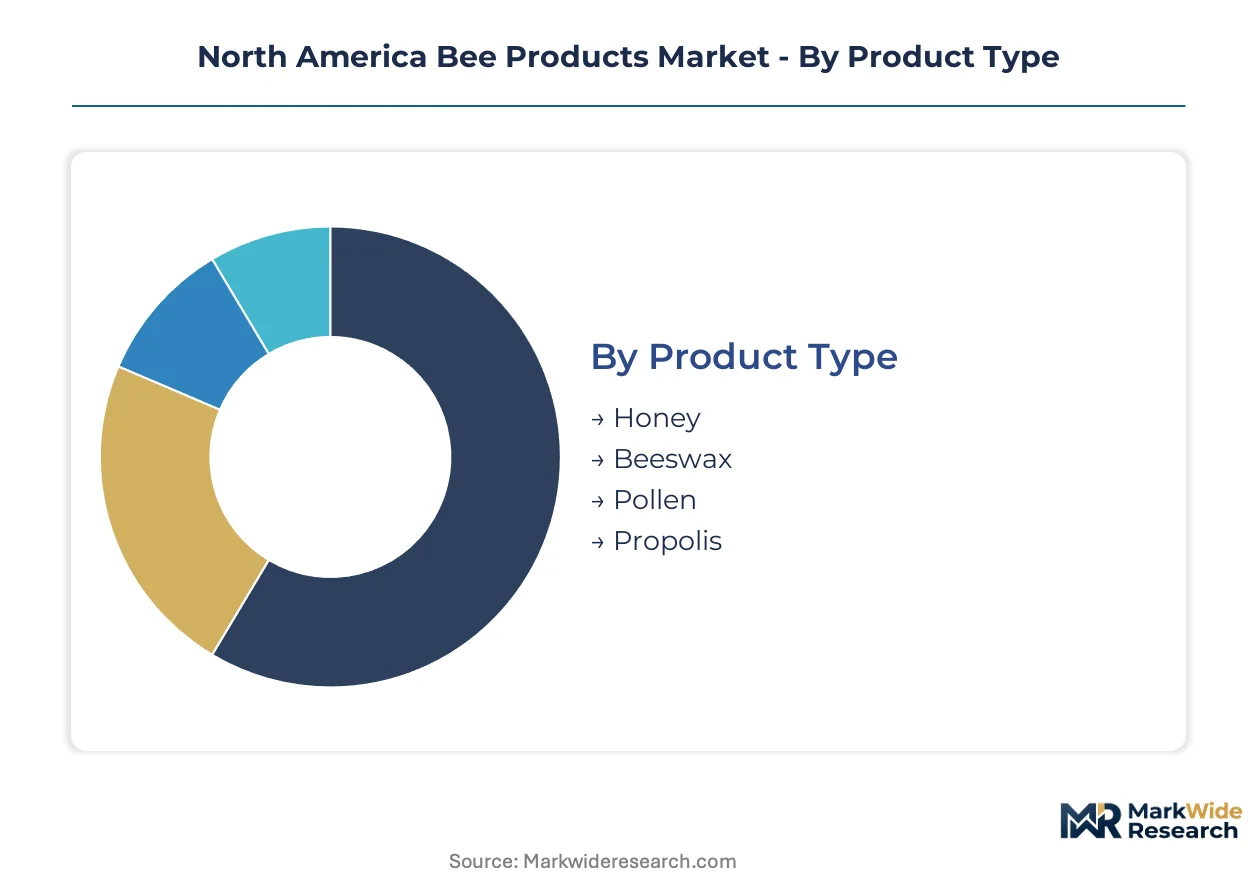
Segmentation in the North America bee products market reveals how regulatory pathways and procurement channels reshape margin capture. Product categories face divergent compliance burdens while distribution channels determine authentication technology deployment feasibility.
Product Type:
FDA dietary ingredient notifications and USDA organic livestock standards create tiered compliance costs that reshape competitive positioning across product categories.
- Honey:Fructose-glucose ratios near 1.2:1 define quality benchmarks, with diastase number measuring enzymatic activity. California Central Valley apiary corridors anchor procurement volume, though colony survival volatility from wildfire smoke exposure constrains supply continuity.
- Propolis:Resinous plant-derived extracts with flavonoid concentrations driving pharmaceutical formulation interest. Nutraceutical manufacturers in California and Texas are pulling volume fastest as FDA New Dietary Ingredient pathways extend launch timelines for novel formulations.
- Beeswax:Ester-based lipid compounds serving cosmetic emulsification and candle manufacturing. Cosmetic formulators in Pennsylvania prioritize certified organic grades for natural positioning claims.
- Pollen:Protein-rich granular collections with amino acid profiles varying by floral source. Dietary supplement brands face NDI notification requirements that favor capitalized incumbents with archived ethnobotanical documentation.
Established volume favors honey; emerging adoption favors propolis.
End User:
Customer procurement sophistication determines authentication technology requirements and pricing tolerance.
- Dietary Supplements:Propolis and pollen extracts concentrated in capsule and tincture formats. California and Texas formulators navigate FDA NDI review periods extending 18-24 months, compressing new entrant viability.
- Food Industry:Bulk honey procurement for bakery, beverage, and table-sweetener applications. Supermarket private-label programs in Texas H-E-B and California Safeway banners now mandate nuclear magnetic resonance spectroscopy screening.
- Cosmetics:Beeswax emulsifiers and honey humectants in topical formulations. Clean beauty positioning in Pennsylvania and Florida drives organic certification premiums.
- Pharmaceuticals:Prescription-adjacent propolis extracts for wound healing and antimicrobial applications. Partnership structures with topical therapeutic developers are opening revenue streams beyond over-the-counter channels.
Food industry procurement anchors volume throughput; dietary supplement channels capture margin expansion.
Distribution Channel:
Channel control determines traceability investment recovery and margin extraction efficiency.
- Online Retail:Subscription honey models and direct-to-consumer platforms bypass supermarket margin extraction. Wedderspoon Organic's methylglyoxal grading protocols deploy most effectively through controlled digital channels.
- Supermarkets:Center-store shelf-stable SKUs face displacement pressure from refrigerated raw honey placement. End-cap positioning in perimeter sections now competes with Greek yogurt and kombucha for traffic conversion.
- Specialty Stores:Manuka honey certification standards and apiary-tourism integrations concentrate in premium natural products retailers. Pennsylvania and Florida operations leverage regional brand recognition.
- Direct Sales:Apiary-tourism and farm-gate purchasing in Florida and Pennsylvania capture authentication premiums through consumer hive visitation. Labor scarcity in commercial beekeeper apprenticeship programs constrains expansion capacity.
Supermarket volume remains foundational; direct sales channels gain share fastest through authentication premium capture.
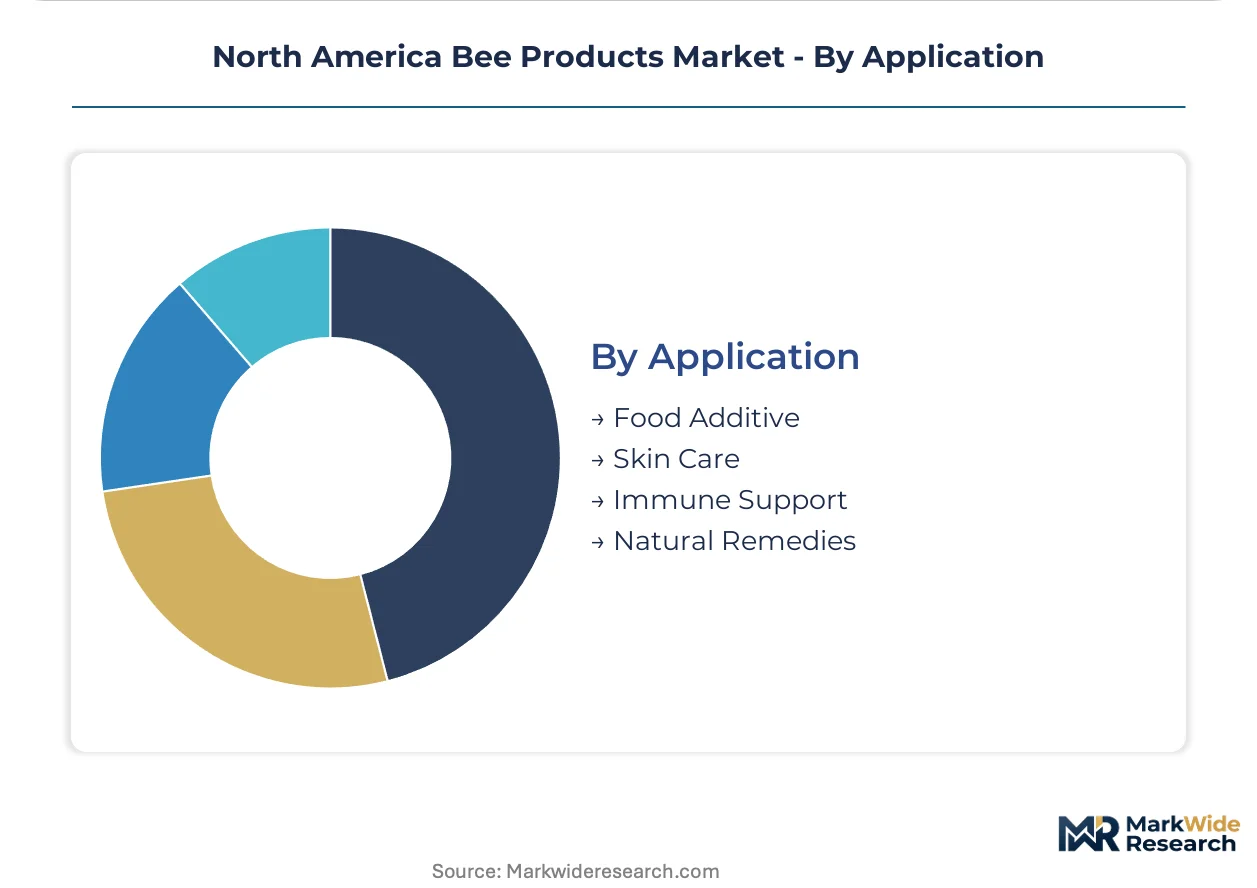
Application:
Functional positioning determines regulatory pathway selection and clinical substantiation requirements.
- Food Additive:Natural sweetener replacement in bakery and beverage formulation. Costco and Whole Foods Market procurement desks now require NMR screening for private-label honey SKUs.
- Skin Care:Humectant and antimicrobial properties in topical formulations. Beeswax emulsification demand from clean beauty brands in Pennsylvania drives organic grade premiums.
- Immune Support:Propolis extract positioning in supplement formulations requires FDA structure-function claim compliance. Historical ethnobotanical literature archiving supports grandfathered ingredient status petitions.
- Natural Remedies:Traditional use positioning for honey wound care and propolis throat applications. Isotope ratio mass spectrometry and pollen DNA barcoding deployment costs constrain mid-scale packer participation.
Food additive applications anchor procurement scale; immune support formulations climb the fastest through pharmaceutical partnership expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian apiaries export bulk honey and beeswax to US food processors and cosmetic formulators, establishing cross-border procurement corridors that concentrate hive management expertise in Alberta and Manitoba prairie zones.
United States
California Central Valley apiary corridors host the densest commercial hive placement for almond pollination services and varietal honey production. EPA pollinator protection mandates restrict neonicotinoid applications near hive clusters, stabilizing colony survival rates. Texas H-E-B and California Safeway retail banners now mandate nuclear magnetic resonance spectroscopy screening for private-label honey SKUs.
Canada
Prairie provinces of Alberta and Manitoba anchor canola honey production volume with lower Varroa mite pressure than US counterparts. Health Canada and the Pest Management Regulatory Agency regulate pesticide exposure thresholds near pollinator habitats. Quebec-based packers specialize in organic certification tiers that command authentication premiums in cross-border US distribution.
Mexico
Yucatán Peninsula meliponiculture traditions supply stingless bee honey to specialty importers in Texas and California. Mexico's national food safety regulator, COFEPRIS, oversees honey export certification for US-bound shipments. Jalisco and Michoacán highland apiaries concentrate on coffee blossom varietals that bypass commodity pricing through direct-to-restaurant channels.
North America Bee Products Market Competitive Landscape
Player mix skews toward vertically integrated packers with captive hive networks and direct-to-consumer specialists with certification-controlled supply chains. The market structure shows moderate consolidation at the premium tier alongside fragmentation in commodity honey packing. Three archetypes dominate: integrated apiary-to-retail operators, Manuka certification specialists, and raw honey positioning brands. Competitive moves concentrate on backward integration into hive ownership and subscription channel bypass of supermarket margin extraction.
Within the integrated packer tier, Dutch Gold Honey and Barkman Honey exemplify scale-driven operators with multi-state hive networks and retail private-label penetration. Wedderspoon Organic occupies a position as the certification-specialist archetype, anchoring methylglyoxal-graded Manuka positioning through controlled digital channels. Nature Nate's Honey Co. represents the raw-unfiltered positioning vector that has secured refrigerated section placement displacing shelf-stable alternatives.
| Leading Market Players |
|---|
| Dutch Gold Honey |
| Wedderspoon Organic |
| Nature Nate's Honey Co. |
| Barkman Honey |
| GloryBee |
| Savannah Bee Company |
| Comvita USA |
| Sue Bee Honey |
| Bee Maid Honey Limited |
| Others |
Value Network & Pricing Analysis
USDA Organic certification gates both supply qualification and price differentiation simultaneously, creating authentication premiums that reward compliant producers while excluding mid-scale packers lacking laboratory partnerships. The FDA's New Dietary Ingredient notification pathway extends product launch timelines, compressing margin recovery windows for novel propolis and pollen formulations.
Pricing Analysis
Prior-generation commodity honey pricing faces displacement pressure from current-generation methylglyoxal-graded Manuka tiers and next-generation pharmaceutical-grade propolis extracts. Three-tier pricing structure across premium, standard, and economy levels separates certified organic varietals from conventional bulk grades and private-label shelf-stable SKUs. Price differentiation hinges on isotope ratio verification costs and direct-to-consumer channel control. Cost compression in commodity honey runs through plant-based sweetener substitution and synthetic propolis analog competition from fermentation biotechnology. Mass retail channels exhibit highest price sensitivity; pharmaceutical partnership channels show lowest.
Supply Chain Analysis
Strategic stockpile preferences dominate California Central Valley apiary corridors where almond pollination contracts require guaranteed hive placement, while just-in-time procurement governs cosmetic beeswax orders from Pennsylvania formulators. Supply concentrates in the United States, Canada, and Mexico with cross-border bulk honey flows from Alberta prairie zones to US food processors. Raw material dependencies include Varroa mite treatments, supplemental pollen substitutes, and certified organic hive foundation. Single-source vulnerability to California wildfire smoke exposure creates supply continuity risk. Distribution runs through vertically integrated packers with captive hive networks and direct-to-consumer subscription platforms bypassing supermarket margin extraction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where FDA NDI notification timelines and USDA organic authentication standards create switching costs that protect capitalized incumbents. Network effects concentrate in laboratory partnerships for nuclear magnetic resonance spectroscopy verification.
For Market Incumbents: Compound backward integration into hive ownership across Pennsylvania and Florida corridors to secure captive supply against Varroa mite treatment cost volatility. Deepen pharmaceutical partnership pipelines for prescription-adjacent propolis extracts before synthetic fermentation analogs capture therapeutic positioning. Prioritize archival ethnobotanical documentation to grandfather ingredient status under FDA draft guidance. For New Entrants and Emerging Players: Anchor in direct-to-consumer subscription models and apiary-tourism integrations in Florida and Pennsylvania where authentication premiums bypass supermarket margin extraction. Target white-space in refrigerated raw honey placement displacing shelf-stable center-store SKUs. Pursue methylglyoxal grading certification for controlled digital channel deployment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade propolis extraction capacity as FDA safety dossier requirements demand dedicated laboratory infrastructure. Long-term viability favors vertically integrated operators with multi-state hive networks and archived ethnobotanical libraries. Watch NDI notification approval velocity as inflection indicator for supplement channel expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hive Ownership | Secures captive supply against California wildfire smoke concentration risk and Varroa mite cost volatility. |
| Pharmaceutical Partnership Expansion | Opens prescription-adjacent revenue streams for propolis extracts beyond over-the-counter supplement channels. |
| Direct-to-Consumer Channel Launch | Bypasses supermarket margin extraction through subscription honey models and apiary-tourism integrations. |
| Organic Certification Investment | Captures authentication premiums as Costco and Whole Foods Market mandate NMR screening for private-label SKUs. |
| Laboratory Partnership Consolidation | Enables isotope ratio mass spectrometry deployment for fraud tolerance compression at mid-scale packer tier. |
Research Methodology
A standing panel of commercial beekeepers, honey packer procurement managers, dietary supplement formulators, and retail category buyers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA New Dietary Ingredient notification filings, USDA Organic certification databases, EPA pollinator protection plan documents, and state-level apiary inspection records from California, Florida, and Texas. Customs trade data for cross-border honey flows and SEC 10-K disclosures from integrated packers anchored quantitative triangulation. Bottom-up hive count modeling and top-down retail channel value estimation were cross-referenced for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled included product type, end-user industry, distribution channel, and application function. CAGRs were derived from segment-level growth trajectory analysis incorporating colony survival rate trends, NDI approval pipeline velocity, and organic certification adoption curves. Forecast inputs included EPA neonicotinoid restriction enforcement patterns and nuclear magnetic resonance spectroscopy deployment rates at major retail procurement desks.
Material uncertainties — regulatory guidance revisions, colony collapse disorder recurrence, and synthetic propolis analog commercialization — sit outside the modeled envelope. Forecasts reflect assumptions about FDA NDI review period stability and organic honey authentication standard continuity. Revision becomes warranted when synthetic fermentation substitute cost curves cross natural propolis extraction economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Indonesia Bamboos Market
Agriculture and Agri Products
Global Palm Oil Market
Agriculture and Agri Products
Sorghum by-Products Market
Agriculture and Agri Products
Europe Compound Feed Market
Agriculture and Agri Products
Corn Co-Products Market
Agriculture and Agri Products
Cut Flower Market
Agriculture and Agri Products
Brazil Cashew Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
Primary Feed Materials Market
Agriculture and Agri Products
Egypt Compound Feed Market
Agriculture and Agri Products
France Alfalfa Hay Market
Agriculture and Agri Products
LAMEA Artificial Humus Market
Agriculture and Agri Products
Netherlands Floriculture Market
Agriculture and Agri Products
Saudi Arabia Alfalfa Market
Agriculture and Agri Products
Spain Alfalfa Hay Market
Agriculture and Agri Products
Organic Starter-Grower Chicken Feed Market