
 Flower and Ornamental Plants Market | 2026-2036
Flower and Ornamental Plants Market Size, Share, and Industry Trends Forecast 2026-2036
Flower and Ornamental Plants Market Insights
Market Dynamics
The capital-intensity gap between tissue-culture laboratories and open-field growers is collapsing as automated propagation systems diffuse downstream. Ball Horticultural Company leverages its global breeding network to sustain year-round cultivar pipelines across temperate and tropical zones. Selecta Klemm GmbH & Co. KG anchors European potted-plant supply through controlled-environment production in Germany and Iberia. Syngenta Flowers differentiates via gene-edited trait stacks that reduce chemical input requirements for commercial nurseries.
Product Structure and Segment Architecture
Flower and ornamental plants encompass vascular plant species cultivated for aesthetic display, landscape function, or emotional signaling, propagated through sexual seed, vegetative cutting, or in vitro meristem culture under controlled photoperiod and humidity regimes. Cuts dominate value pools through perishable logistics premiums and event-driven procurement spikes, while potted plants capture recurring household expenditure through extended shelf life and gifting rituals. Bedding and perennials compete for share in municipal landscaping budgets, where procurement criteria weigh establishment speed against multi-season return.
Regulatory Environment and Outlook
The EU Plant Health Regulation and REACH phytosanitary protocols restrict pesticide residues on imported propagation material, forcing exporters toward integrated pest management certification. The USDA APHIS quarantine framework and NPDES water discharge rules shape domestic production location decisions, particularly in Florida and California growing regions. Stakeholders must monitor evolving pollinator-protection statutes and carbon-border adjustment mechanisms as these frameworks increasingly determine market access eligibility for international suppliers.
Market Dynamics
Automated propagation systems are collapsing the capital-intensity gap between tissue-culture laboratories and open-field growers, redistributing competitive advantage toward mid-scale operations that can deploy precision-controlled environments without legacy infrastructure overhead.
Growth Catalysts
- Biophilic design mandates:Corporate real estate portfolios in the Netherlands and Germany now specify living walls and interior plant installations as standard fit-out requirements, driving recurring procurement contracts for maintenance and seasonal rotation.
- EU Green Deal biodiversity restoration:Nursery stock procurement across member states is redirecting toward native cultivars, creating premium positioning for suppliers with certified local provenance and phytosanitary documentation.
- Controlled-environment agriculture diffusion:LED photoperiod management and automated humidity systems are enabling year-round production of temperate-zone ornamentals in Iberian and Italian growing regions previously limited by seasonality.
Market Restraints
- Phytosanitary compliance friction:USDA APHIS quarantine protocols and EU Plant Health Regulation certification timelines add 6-18 months to cultivar introduction cycles, disadvantaging smaller breeders against established networks.
- Input cost volatility:Peat substrate and controlled-release fertilizer prices fluctuate with energy markets, compressing margins for open-field perennial producers unable to pass through costs to municipal landscaping contracts.
- Perishable logistics concentration:Cold-chain dependency on Aalsmeer auction infrastructure and Schiphol air freight creates single-point vulnerability for cut-flower exporters serving event-driven demand spikes.
Strategic Opportunities
- Subscription household models:Direct-to-consumer plant rental and rotation services in urban Germany and France are bypassing traditional retail garden centers, capturing recurring revenue from apartment-dwelling millennials.
- Gene-edited trait stacks:Reduced chemical input requirements from disease-resistance breeding are opening municipal procurement channels where integrated pest management certification is mandatory.
- Carbon-border adjustment preparation:Early certification of supply-chain emissions intensity positions exporters for preferential access as EU CBAM mechanisms extend to agricultural inputs beyond 2026.
Industry Challenges
- Meristem culture technician scarcity:In vitro propagation expertise concentrates in Dutch and Belgian research clusters, limiting scaling of tissue-culture operations in emerging production regions.
- Legacy irrigation infrastructure:Florida and California growing regions face NPDES discharge compliance costs for open-field runoff, forcing capital reallocation toward closed-loop hydroponic systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flower and Ornamental Plants Market |
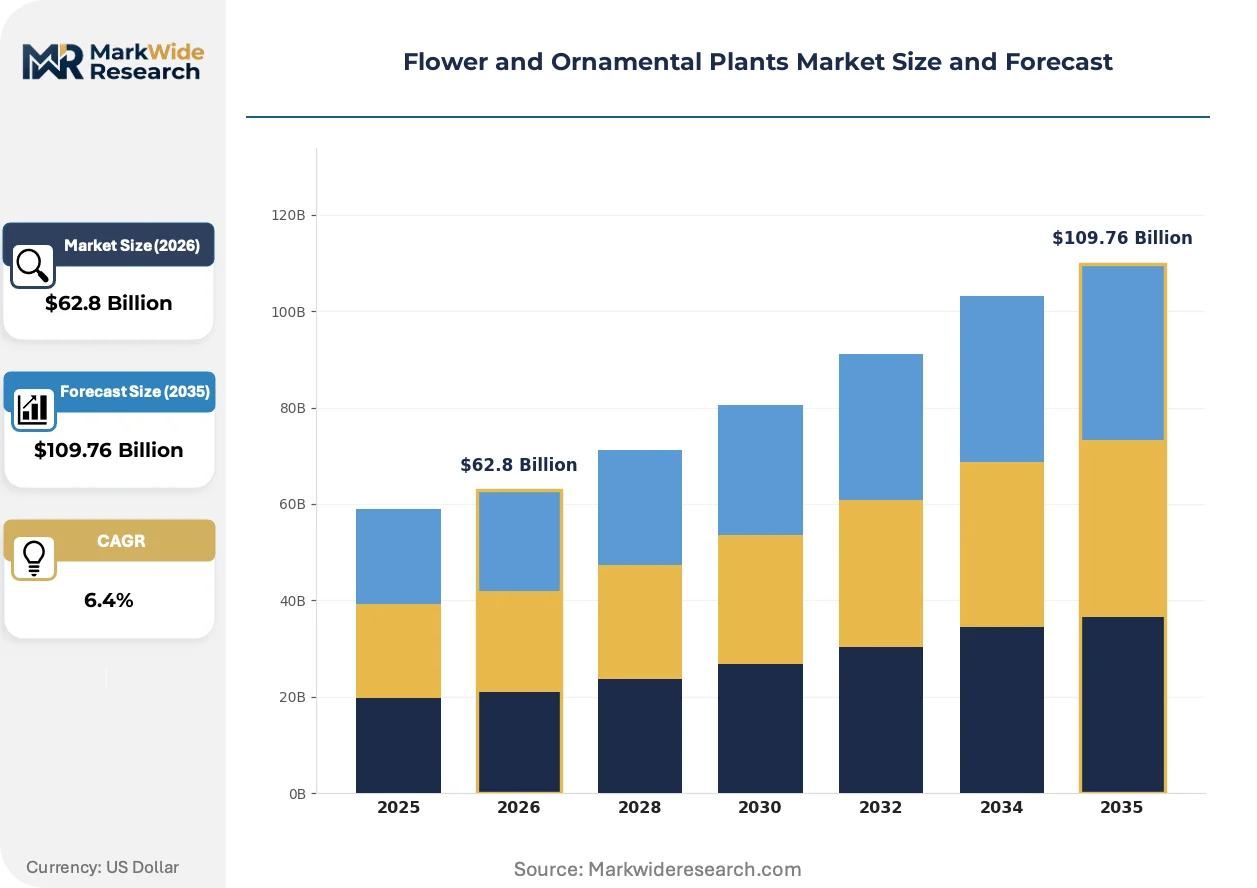
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $109.76 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Plant Type: Cuts, Potted, Bedding, Perennials Distribution Channel: Online Retail, Garden Centers, Wholesale, Supermarkets End User: Horticulturists, Nurseries, Home Gardeners, Landscaping Companies Plant Variety: Tropical Flowers, Succulents, Herbs, Annuals |
| Companies Covered | Ball Horticultural Company, Selecta Klemm GmbH & Co. KG, Syngenta Flowers, Monrovia Nursery Co., Beekenkamp Group, Flamingo Horticulture, Florensis, Kurt Weiss Greenhouses Inc., Dümmen Orange, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flower and Ornamental Plants Market Trends and Innovations
Digital phenotyping and sensor-driven cultivation protocols are compressing breeding cycles and enabling real-time quality grading, shifting competitive advantage from scale toward data-integration capabilities across the value chain.
CRISPR-based gene editing is decomposing the traditional trade-off between ornamental trait novelty and agronomic robustness. Commercial nurseries in the Netherlands and Colombia are adopting edited cultivars for powdery mildew resistance at accelerating rates. This technology is decomposing the historical premium commanded by chemical-intensive production methods in temperate-climate forcing operations.
REACH phytosanitary protocols and the EU Fertilizing Products Regulation are tightening residue limits on imported propagation material. Breeders must now maintain dual certification tracks for EU and non-EU supply chains. The bedding and perennial segment faces the steepest compliance burden, with Dutch exporters investing in third-party IPM auditing to maintain auction access.
Corporate procurement departments are consolidating vendor relationships for interior landscaping services, replacing fragmented local contracts with national facility-management agreements. Multi-site retail and hospitality chains in Germany and the UK now specify single-source suppliers for living wall maintenance across property portfolios. This concentration is most visible in London and Frankfurt financial district office towers, where biophilic fit-out standards have become tenant-retention tools.
Flower and Ornamental Plants Market Segmentation
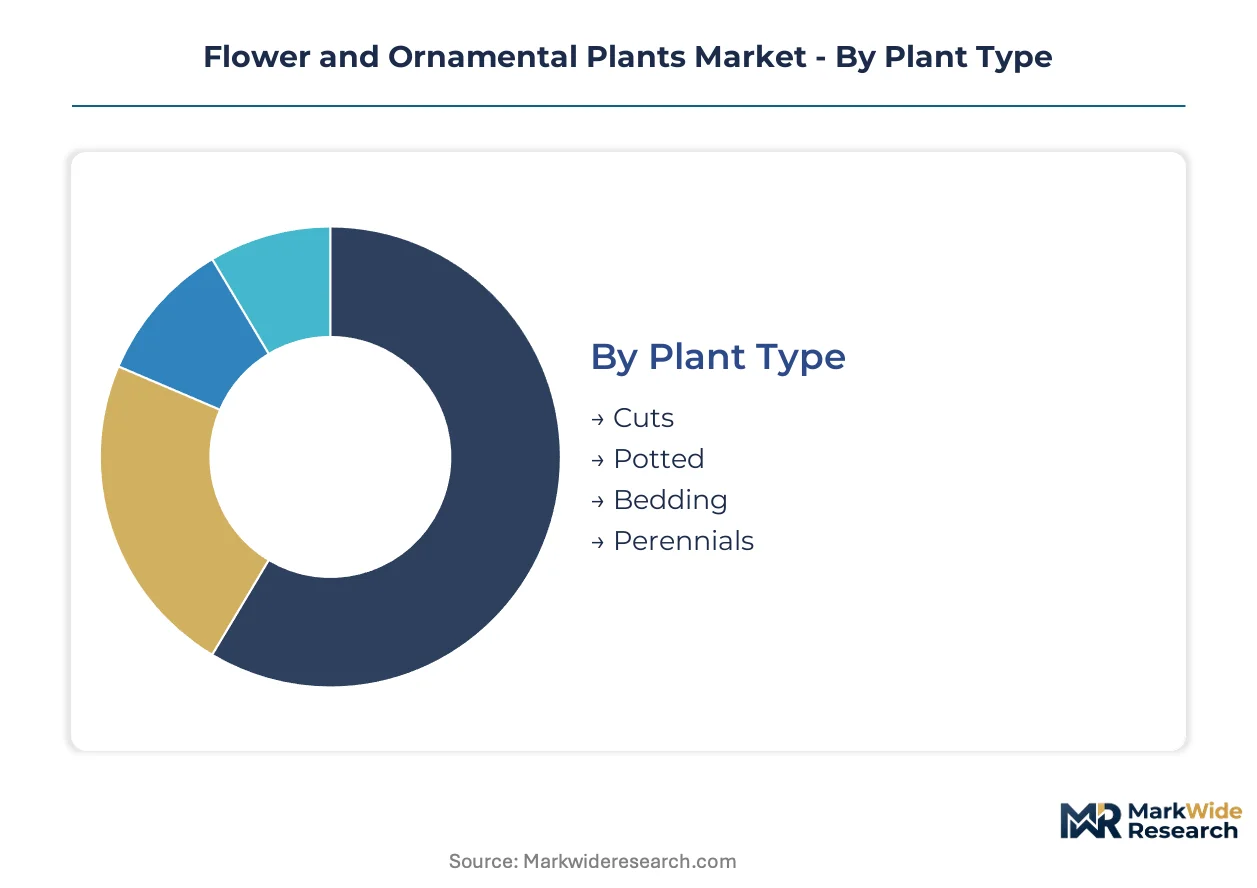
Segmentation in flower and ornamental plants reveals divergent margin structures and logistics requirements across product types. Cuts command perishable premiums through auction infrastructure, while potted plants build recurring household revenue through extended shelf life and gifting rituals.
Plant Type:
Cuts concentrate in Dutch auction exports; bedding and perennials serve domestic municipal landscaping procurement cycles.
- Cuts:Harvested floral stems requiring cold-chain logistics within 48 hours of cutting to maintain vase-life performance. Dutch Aalsmeer auction infrastructure anchors global supply, with Colombian and Kenyan producers capturing event-driven demand spikes through Schiphol air freight corridors.
- Potted:Container-grown specimens with 4-12 week retail shelf life enabling recurring household expenditure. German and French urban millennials drive subscription rotation services, bypassing traditional garden center channels for direct-to-consumer delivery.
- Bedding:Seasonal annuals for mass landscape color establishment. Municipal procurement in Florida and California weighs establishment speed against single-season replacement costs.
- Perennials:Multi-season herbaceous plants competing for landscaping budgets on return-on-investment metrics. EU Green Deal biodiversity mandates redirect nursery stock toward native cultivar provenance.
Cuts hold the largest share; momentum sits with potted plants through subscription household models.
Distribution Channel:
Channel selection stratifies by perishability tolerance and customer acquisition cost tier.
- Online Retail:Direct-to-consumer platforms capturing urban apartment dwellers through subscription mechanics and same-day delivery promises. Returns management complexity limits category expansion for live goods.
- Garden Centers:Destination retail with staff expertise driving higher basket values and impulse purchases. Iberian and Italian independent operators face consolidation pressure from national chains.
- Wholesale:Volume aggregation for landscapers, event florists, and retail chains. Dutch auction cooperatives maintain price discovery transparency through clock auction mechanisms.
- Supermarkets:Mass-market penetration for standardized potted varieties with extended shelf life. Seasonal promotional cycles drive volume spikes in UK and German grocery channels.
Wholesale channels dominate value capture; online retail is expanding most quickly through millennial household penetration.
End User:
User type determines specification complexity and recurring revenue potential.
- Horticulturists:Specialized growers requiring certified propagation material and phytosanitary documentation. Tissue-culture expertise concentration in Dutch and Belgian clusters limits scaling in emerging regions.
- Nurseries:Commercial propagation operations serving downstream retail and landscape channels. REACH residue protocols and EU Plant Health Regulation certification timelines add 6-18 months to cultivar introduction cycles.
- Home Gardeners:Discretionary consumers responding to biophilic design trends and social media cultivation content. Apartment living in Frankfurt and London financial districts drives interior plant installation demand.
- Landscaping Companies:B2B procurement consolidating toward national facility-management agreements. Corporate real estate portfolios in Germany and the Netherlands now specify living walls as standard fit-out requirements.
Landscaping companies hold the largest share; home gardeners show steepest expansion trajectory through digital channel migration.
Plant Variety:
Variety selection reflects climate adaptability and maintenance intensity preferences.
- Tropical Flowers:Climate-controlled forcing operations in the Netherlands and Colombia supply year-round orchid and anthurium demand. LED photoperiod management enables temperate-zone production previously limited by seasonality.
- Succulents:Low-water-input specimens capturing drought-conscious California and Australian markets. Extended shelf life reduces retail shrinkage compared to herbaceous alternatives.
- Herbs:Dual-purpose ornamental and culinary plants driving kitchen-window placement. German and French supermarket chains promote living herb pots as repeat-purchase categories.
- Annuals:Single-season color plants dominating bedding and container applications. Municipal procurement criteria increasingly weigh native provenance against establishment speed.
Tropical flowers hold the largest share; succulents are gaining share fastest through water-scarcity positioning and retail durability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between auction-driven cut-flower economies and subscription-oriented potted-plant markets, with procurement specifications varying by climate zone and regulatory environment.
Netherlands
Aalsmeer auction infrastructure processes the majority of global cut-flower trade volume through clock auction mechanisms. EU Plant Health Regulation and REACH protocols enforce strict phytosanitary certification on all propagation material entering Dutch distribution channels. Westland greenhouse clusters deploy LED photoperiod systems to extend temperate-zone production windows year-round.
United States
Florida and California growing regions supply domestic bedding and perennial demand for municipal landscaping contracts. USDA APHIS quarantine frameworks and NPDES water discharge rules shape production location decisions, particularly for open-field runoff compliance. Miami-Dade and Ventura County nurseries face capital reallocation toward closed-loop hydroponic infrastructure.
Germany
Corporate real estate portfolios in Frankfurt and Berlin specify living walls and biophilic installations as standard tenant fit-out requirements. Selecta Klemm GmbH & Co. KG anchors European potted-plant supply through controlled-environment production in Lower Saxony and Iberian satellite operations. Federal building energy codes accelerate demand for interior plant-based humidity regulation systems.
Colombia
Equatorial highland farms capture event-driven rose and carnation demand spikes through Bogotá-El Dorado air freight corridors serving Schiphol connections. Powdery mildew resistance breeding programs accelerate CRISPR-edited cultivar adoption among commercial nurseries. Cundinamarca and Antioquia departments concentrate temperature-controlled forcing operations for year-round temperate-zone flower supply.
United Kingdom
London financial district office towers consolidate vendor relationships for living wall maintenance across multi-site property portfolios. Supermarket chains drive seasonal volume spikes for standardized potted varieties with extended retail shelf life. Kent and Sussex nursery clusters face EU Green Deal biodiversity mandates redirecting stock toward native cultivar provenance certification.
Flower and Ornamental Plants Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with breeding networks and auction access determining competitive position. The structure stratifies between global cultivar pipelines, regional propagation specialists, and local retail distributors. Three archetypes dominate: integrated breeding-to-retail networks, controlled-environment propagation specialists, and gene-edited trait developers. Competitive moves concentrate on M&A for germplasm portfolios and strategic partnerships for phytosanitary certification fast-tracking.
Within the integrated breeding tier, Ball Horticultural Company and Syngenta Flowers exemplify global network operators sustaining year-round cultivar pipelines across climate zones. Selecta Klemm GmbH & Co. KG occupies a position among European controlled-environment specialists with production infrastructure spanning Germany and Iberia. These three entities represent the dominant archetypes: transcontinental breeding networks, regional propagation scale players, and gene-edited trait stack developers reducing chemical input requirements for commercial nursery certification compliance.
| Leading Market Players |
|---|
| Ball Horticultural Company |
| Selecta Klemm GmbH & Co. KG |
| Syngenta Flowers |
| Monrovia Nursery Co. |
| Beekenkamp Group |
| Flamingo Horticulture |
| Florensis |
| Kurt Weiss Greenhouses Inc. |
| Dümmen Orange |
| Others |
Pricing and Supply Chain Analysis
Long-term maintenance contracts for corporate living wall installations lock in supply access for Dutch and German facility managers while fixing price visibility against input cost swings in peat substrate and controlled-release fertilizers. These multi-year service agreements insulate procurement departments from auction volatility at Aalsmeer while guaranteeing cultivar rotation schedules.
Pricing Analysis
After-sales revenue from recurring maintenance and seasonal rotation services drives lifetime value for interior landscaping providers serving Frankfurt and London financial district towers. Three-tier pricing structure across premium, standard, and economy levels separates gene-edited disease-resistant cultivars from conventional breeding stock and open-field perennials. Pricing pressure stems from energy-linked volatility in peat and fertilizer inputs compressing margins for uncontracted open-field growers. Municipal landscaping buyers exhibit highest price sensitivity due to fixed annual budgets, while corporate real estate portfolios prioritize biophilic certification compliance over unit cost.
Supply Chain Analysis
Schiphol air freight corridors and Aalsmeer auction infrastructure create a chokepoint for Kenyan and Colombian cut-flower exporters serving event-driven European demand spikes. Production gravity centers on the Netherlands, Colombia, and Kenya for cuts, with Germany and Iberia anchoring potted-plant supply through controlled-environment clusters. Raw material dependencies include peat substrate, controlled-release fertilizers, and LED propagation systems. Single-source vulnerability concentrates in Dutch meristem culture technician expertise. Distribution runs through wholesale auction cooperatives for cuts and direct-to-consumer platforms for urban subscription services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the flower and ornamental plants market creates entry niches as EU Green Deal biodiversity mandates splinter procurement specifications toward native cultivar provenance certification.
For Market Incumbents: Consolidate germplasm portfolios through targeted acquisition of regional breeding specialists with certified native provenance collections. Lock in auction access through third-party IPM auditing investments before REACH residue protocols tighten further. Defensive capacity expansion in Iberian LED-controlled environments offsets seasonality constraints threatening Dutch greenhouse margins. For New Entrants and Emerging Players: Lead with subscription household models targeting apartment-dwelling millennials in urban Germany and France through direct-to-consumer delivery bypassing garden center intermediaries. White-space concentration sits in gene-edited trait stacks for powdery mildew resistance where CRISPR expertise remains scarce outside Dutch and Belgian clusters. Go-to-market positioning emphasizes integrated pest management certification for municipal procurement channels. For Investors and Strategic Acquirers: Capital is best deployed toward controlled-environment propagation specialists with backward integration into tissue-culture laboratories and forward linkages to corporate facility-management contracts. Long-term viability across the analysis window favors operations with dual EU and non-EU certification tracks. The signal to watch is carbon-border adjustment mechanism expansion beyond 2026, which would revalue early emissions-intensity certification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tissue-Culture Labs | Captures margin from meristem propagation expertise concentrated in Dutch clusters. |
| Gene-Edited Cultivar Development | Reduces chemical input requirements for EU Plant Health Regulation compliance. |
| Corporate Facility-Management Partnerships | Locks in recurring revenue from biophilic fit-out mandates in Frankfurt towers. |
| Native Provenance Certification Investment | Positions for EU Green Deal biodiversity restoration procurement redirection. |
| Direct-to-Consumer Platform Launch | Bypasses garden center consolidation pressure in German and French urban markets. |
Research Methodology
Operator-level perspectives from nursery operations managers, corporate facility procurement leads, auction cooperative directors, and tissue-culture laboratory technicians anchored the qualitative base for this study. Primary fieldwork combined with secondary validation from EU Plant Health Regulation documentation, REACH phytosanitary protocol filings, Dutch auction trade data, and USDA APHIS quarantine records. Bottom-up cultivar volume estimates triangulated against top-down regional consumption assessments.
Sensitivity analysis tested forecast outputs against input cost volatility scenarios and regulatory timeline variations across the projection horizon. Segmentation modeling captured plant type, distribution channel, end user, and plant variety dimensions with regional regulatory cluster overlays. CAGRs derived from historical trade flow analysis and forward capacity buildout tracking. Forecast inputs included LED photoperiod adoption curves and carbon-border adjustment mechanism phase-in assumptions.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or accelerated CRISPR regulatory approval would require recalibration. Forecasts reflect documented assumptions regarding phytosanitary certification timeline stability and air freight corridor capacity. Revision becomes warranted when peat substrate price volatility crosses thresholds forcing open-field producer exit.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Vietnam Floriculture Market
Agriculture and Agri Products
Arnica Oil Market
Agriculture and Agri Products
Saudi Arabia Alfalfa Market
Agriculture and Agri Products
Alfalfa Market
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
North America Animal Protein Market
Agriculture and Agri Products
Japan Animal Protein Market
Agriculture and Agri Products
North America Compound Feed Market
Agriculture and Agri Products
South America Animal Protein Market
Agriculture and Agri Products
Global Ruminant Feed Market
Agriculture and Agri Products
Africa Poultry Feed Market
Agriculture and Agri Products
Colombia Floriculture Market
Agriculture and Agri Products
Taro Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
India Compound Feed Market
Agriculture and Agri Products
Europe Guar Market