
 Australia Digital Marketing Software Market | 2026-2036
Australia Digital Marketing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Digital Marketing Software Market Insights
Subscription-based SaaS financing is tilting competitive dynamics toward asset-light entrants that bypass heavy capex requirements. Adobe Inc. leverages its Creative Cloud ecosystem to anchor premium positioning in content creation workflows. Salesforce Inc. sustains dominance through deep CRM integration that locks in enterprise marketing operations. HubSpot Inc. specializes in inbound marketing automation tailored to mid-market budgets.
Australia digital marketing software encompasses cloud-native and on-premise platforms that orchestrate customer acquisition, engagement, and analytics across digital channels, typically integrating AI-driven personalization engines with real-time bid management and cross-channel attribution. The primary commercial purpose is to replace fragmented point solutions with unified data layers that improve return on ad spend and customer lifetime value. Email marketing retains the largest installed base among product types, though social media management captures the fastest expansion as short-form video platforms reshape media planning. Cloud-based deployment leads volume growth while hybrid architectures serve regulated sectors requiring data sovereignty controls.
The Australian Competition and Consumer Commission enforces platform transparency rules that shape how marketing software providers disclose algorithmic ad pricing to buyers. The Privacy Act 1988 and Australian Privacy Principles impose consent architecture requirements that directly influence product roadmaps for customer data platforms. Stakeholders must monitor how TGA advertising guidelines for therapeutic goods and ASIC financial promotion rules create sector-specific compliance modules that vendors integrate or risk exclusion from regulated verticals.
Market Dynamics
The Australian Privacy Principles under the Privacy Act 1988 are forcing marketing software vendors to rebuild consent architectures from the ground up. This regulatory pressure is reshaping product roadmaps faster than any technology cycle, concentrating investment in customer data platforms that can demonstrate auditable consent chains.
Growth Catalysts
- Programmatic Retail Investment:Sydney and Melbourne retail brands are expanding automated ad spend across connected TV and retail media networks. This concentrates demand for unified bid management platforms.
- Cloud-Native Infrastructure:Mid-market enterprises in New South Wales and Victoria are abandoning on-premise stacks for SaaS deployment models that reduce IT overhead and accelerate feature access.
- AI-Driven Personalization:Machine learning engines that orchestrate real-time content adaptation across email and social channels are pulling replacement cycles for legacy marketing automation.
Market Restraints
- Consent Architecture Costs:The Australian Privacy Principles mandate granular opt-in frameworks that require expensive engineering retrofits for customer data platforms serving Australian enterprises.
- Skills Concentration:Marketing technologists with cross-channel attribution expertise cluster in Sydney and Melbourne, creating talent scarcity for vendors expanding into Brisbane and Perth.
- Platform Dependency:Meta and Google algorithm changes force continuous adaptation of bidding strategies, compressing margins for independent programmatic platforms.
Strategic Opportunities
- Queensland Expansion:Brisbane's emerging fintech and health tech clusters show underpenetrated demand for mid-market marketing automation relative to saturated southern markets.
- Therapeutic Goods Compliance:TGA advertising guidelines create a protected vertical for vendors that integrate pharmaceutical compliance modules into campaign management workflows.
- Short-Form Video Convergence:TikTok and Instagram Reels are merging social management with creative production, opening white space for platforms that unify planning, creation, and distribution.
Industry Challenges
- Attribution Engineering Talent:The shortage of data scientists capable of building multi-touch attribution models limits vendor capacity to serve enterprise accounts with complex customer journeys.
- Legacy CRM Integration:On-premise Salesforce and Microsoft Dynamics instances in regulated sectors require costly custom connectors that delay cloud migration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Digital Marketing Software Market |
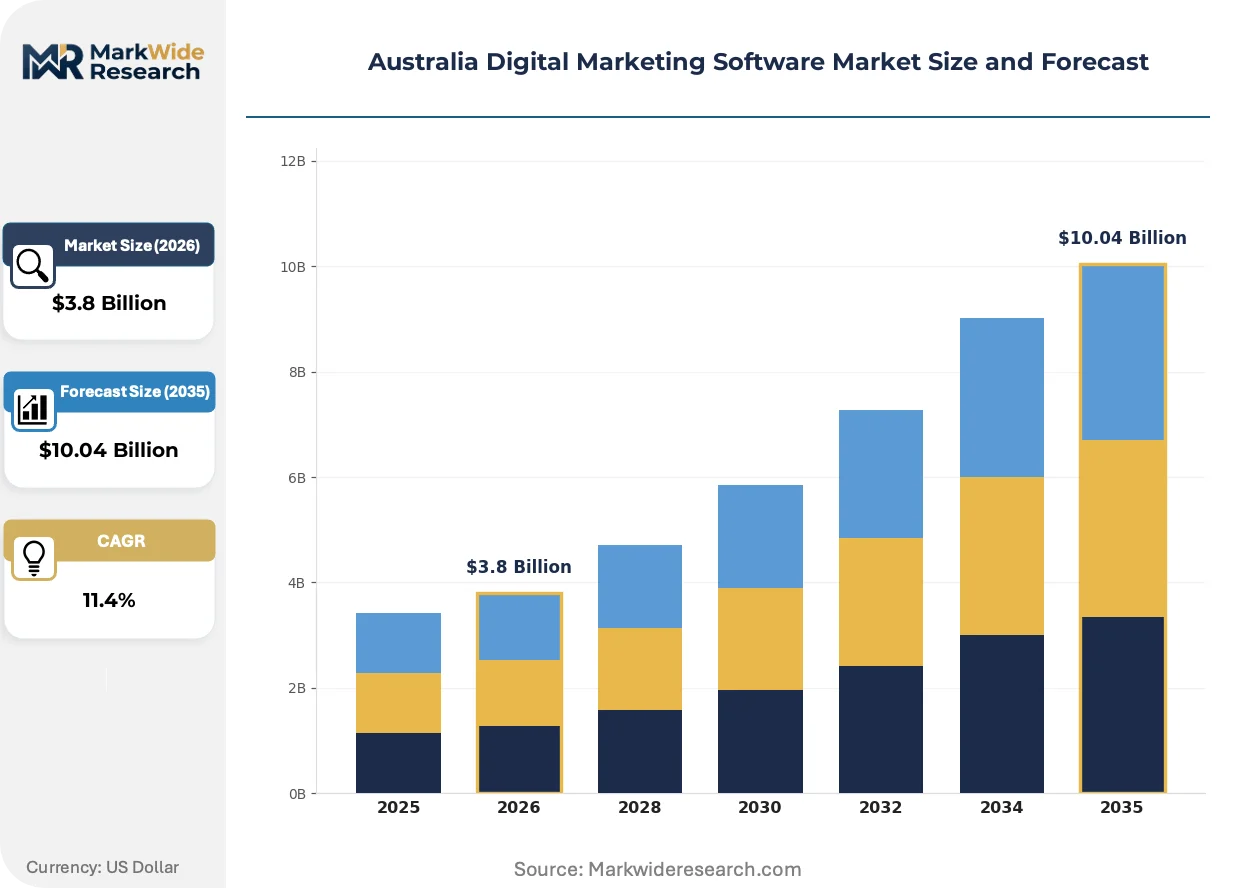
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Email Marketing, Social Media Management, Content Management, SEO Tools Deployment: On-Premise, Cloud-Based, Hybrid, Multi-Tenant End User: Small Enterprises, Medium Enterprises, Large Enterprises, Agencies Service Type: Consulting, Implementation, Maintenance, Support |
| Companies Covered | Adobe Inc., Salesforce Inc., HubSpot Inc., Oracle Corporation, SAS Institute Inc., Microsoft Corp, SAP SE, Hewlett Packard Enterprise Co, International Business Machines Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Digital Marketing Software Market Trends and Innovations
Real-time identity resolution and server-side tracking are displacing cookie-dependent measurement architectures across Australian marketing stacks. Vendors that virtualize data infrastructure without third-party identifiers are capturing enterprise evaluations.
Server-side tag management is virtualizing how customer behavioral data flows between websites and analytics platforms. Mid-market retailers in Melbourne are piloting these implementations to bypass browser-level cookie restrictions. The technology is compressing the advantage held by client-side tracking incumbents while enabling first-party data strategies that align with Australian Privacy Principles consent requirements.
The Australian Competition and Consumer Commission's platform transparency rules now mandate algorithmic ad pricing disclosures to programmatic buyers. Marketing software providers must build automated reporting modules that surface auction mechanics and fee structures. Financial services advertisers under ASIC oversight are the most affected segment, driving procurement toward vendors with pre-built regulatory reporting capabilities.
Subscription fatigue among mid-market CMOs is shortening software evaluation cycles and unbundling all-in-one platform contracts. Buyers in Sydney's B2B technology sector are assembling best-of-breed stacks from specialized point solutions rather than accepting bundled feature trade-offs. This fragmentation rewards vendors with open APIs and native integrations over those pushing suite consolidation.
Australia Digital Marketing Software Market Segmentation
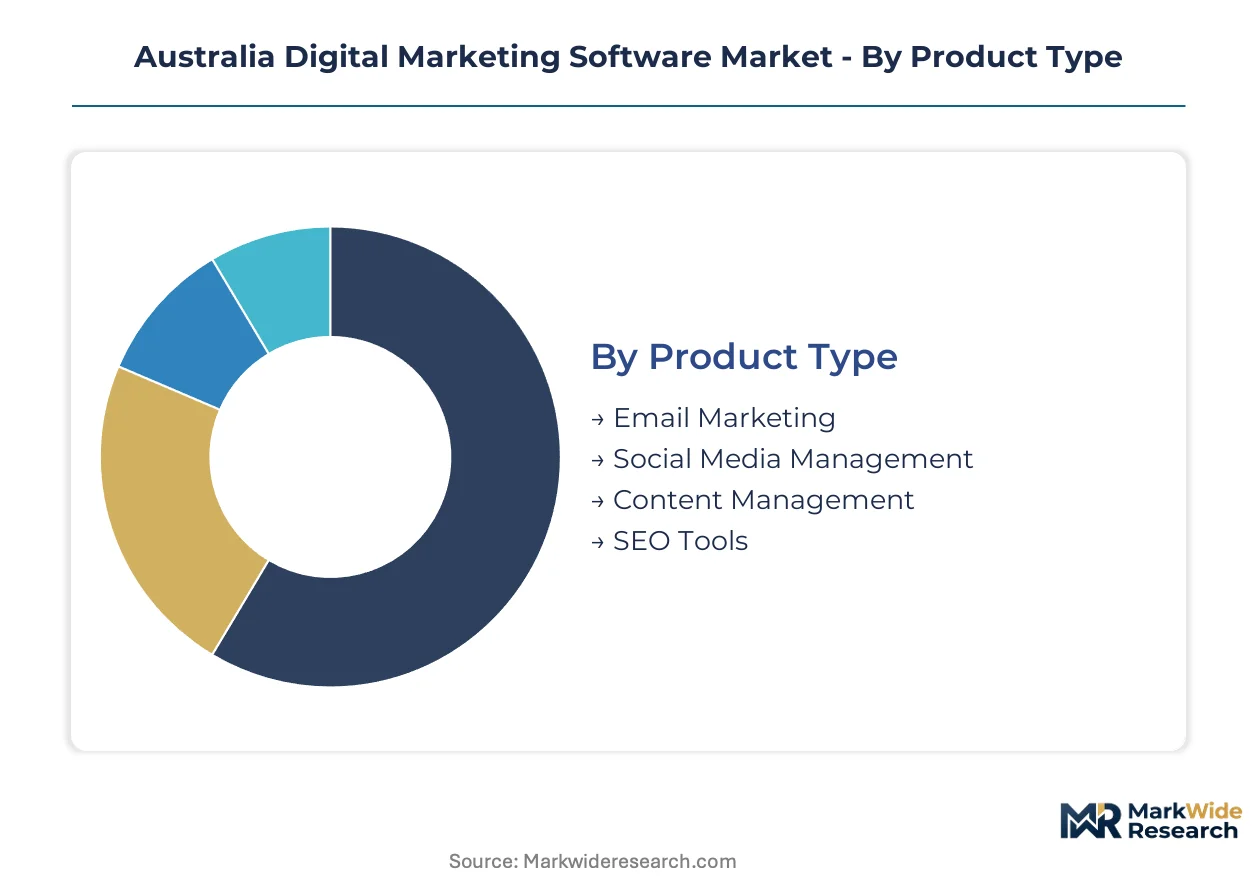
Segmentation in Australia's digital marketing software market reveals how vendor resources align with divergent customer technical capabilities and compliance burdens. The Privacy Act 1988's consent requirements create distinct service intensity needs across deployment modes and enterprise sizes.
Product Type:
After-sales service intensity varies sharply across product categories, with complex multi-channel platforms demanding sustained technical support while point solutions require minimal ongoing intervention.
- Email Marketing:Mature automation workflows with established deliverability infrastructure dominate installed base metrics. New South Wales retail and financial services enterprises drive replacement cycles toward AI-powered personalization engines that require intensive onboarding support.
- Social Media Management:Unified publishing and analytics dashboards now integrate short-form video creation tools. Melbourne agencies and Sydney D2C brands are consolidating fragmented point solutions, pulling demand toward platforms with native TikTok and Instagram Reels functionality.
- Content Management:Headless CMS architectures separate content storage from presentation layers.
- SEO Tools:Rank tracking and technical audit platforms face margin pressure from freemium entrants.
By volume, Email Marketing leads. By growth pace, Social Media Management is ahead.
Deployment:
Cost tier stratification separates capital-intensive on-premise installations from operating-expense cloud models favored by mid-market budget holders.
- Cloud-Based:SaaS delivery eliminates infrastructure ownership while accelerating feature access through continuous deployment pipelines. Victorian and New South Wales mid-market enterprises dominate subscription growth as IT overhead reduction becomes a procurement priority.
- Hybrid:Split architectures retain sensitive customer data on-premise while pushing campaign execution to cloud instances. Regulated sectors including financial services and healthcare in Sydney require this configuration to satisfy Australian Privacy Principles audit requirements.
- On-Premise:Legacy instances persist in government and critical infrastructure verticals with strict data sovereignty mandates.
- Multi-Tenant:Shared infrastructure models achieve density economies for vendor cost structures.
By deployment share, Cloud-Based dominates. By compliance-driven urgency, Hybrid is expanding most quickly.
End User:
Customer type determines pricing architecture elasticity and contract duration, with enterprise accounts demanding customization while agencies prioritize white-label flexibility.
- Medium Enterprises:Revenue concentration sits with this segment as marketing technology budgets mature from spreadsheet-managed campaigns to integrated platform investments. Brisbane and Perth mid-market firms represent underpenetrated expansion territory relative to saturated southern markets.
- Agencies:Multi-client management requirements drive demand for unified reporting and cross-account automation. Sydney and Melbourne creative and media agencies are consolidating vendor relationships to reduce stack complexity and improve margin capture.
- Large Enterprises:Complex procurement processes and legacy system integration requirements extend sales cycles.
- Small Enterprises:Price sensitivity and limited technical staffing constrain addressable market for premium solutions.
By current revenue contribution, Medium Enterprises lead. By platform consolidation momentum, Agencies are gaining share fastest.
Service Type:
Margin structure across service categories reflects talent scarcity, with technical implementation commanding premium pricing while commoditized support faces automation displacement.
- Implementation:Data migration and system integration projects require specialized engineering resources that vendors struggle to scale. Australian Privacy Principles compliance validation adds mandatory checkpoints that extend project timelines and service revenue recognition.
- Consulting:Strategic advisory on martech stack architecture and attribution modeling addresses skills gaps in enterprise marketing operations. Sydney and Melbourne talent concentration creates geographic pricing premiums for on-site consulting engagements.
- Maintenance:Routine platform updates and security patching are increasingly bundled into subscription pricing.
- Support:Tiered response time guarantees differentiate service levels with limited pricing power.
By revenue per engagement, Implementation leads. By demand growth trajectory, Consulting is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New South Wales commands premium pricing power over Queensland and Western Australia, where marketing software procurement concentrates in lower-cost SaaS tiers. Victorian enterprises extract volume discounts unavailable to Perth or Adelaide buyers. This geographic asymmetry shapes vendor go-to-market investments and partner network density.
New South Wales
Sydney's financial services and retail headquarters drive demand for hybrid deployment architectures with strict data sovereignty controls. The Australian Privacy Principles enforcement by the Office of the Australian Information Commissioner mandates auditable consent chains for customer data platforms. North Sydney and Parramatta fintech clusters are consolidating fragmented marketing stacks into unified CDP investments.
Victoria
Melbourne's agency ecosystem and D2C brand concentration fuel social media management platform growth. The Australian Competition and Consumer Commission's platform transparency rules reshape how vendors disclose algorithmic pricing to programmatic buyers. Southbank and Cremorne technology precincts are piloting server-side tracking implementations to bypass browser cookie restrictions.
Queensland
Brisbane's emerging health tech and fintech verticals show underpenetrated demand relative to southern saturation. Therapeutic Goods Administration advertising guidelines create compliance-driven procurement toward vendors with pre-built pharmaceutical modules. Fortitude Valley and Brisbane CBD clusters are accelerating mid-market marketing automation adoption from spreadsheet-managed campaigns.
Western Australia
Perth's mining and resources sector procurement favors on-premise legacy systems with extended replacement cycles. The Privacy Act 1988 applies uniform consent requirements, though enforcement intensity lags eastern states. Subiaco and Perth CBD enterprise accounts are beginning cloud migration pilots for customer engagement platforms.
South Australia
Adelaide's government and defense contractor base sustains demand for secure, sovereign-hosted marketing infrastructure. State-level procurement policies reinforce data localization preferences beyond federal minimums. Lot Fourteen innovation precinct and Adelaide CBD public sector accounts are evaluating hybrid architectures for citizen communication campaigns.
Australia Digital Marketing Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in attribution, creative production, and compliance modules. The vendor base stratifies between full-suite consolidators and best-of-breed point solutions that buyers assemble through open APIs. Three archetypes dominate: ecosystem-anchored incumbents with creative cloud or CRM lock-in, mid-market SaaS pure-plays with inbound marketing specialization, and legacy enterprise vendors with on-premise installed bases. Competitive moves concentrate on API ecosystem expansion and vertical compliance module development.
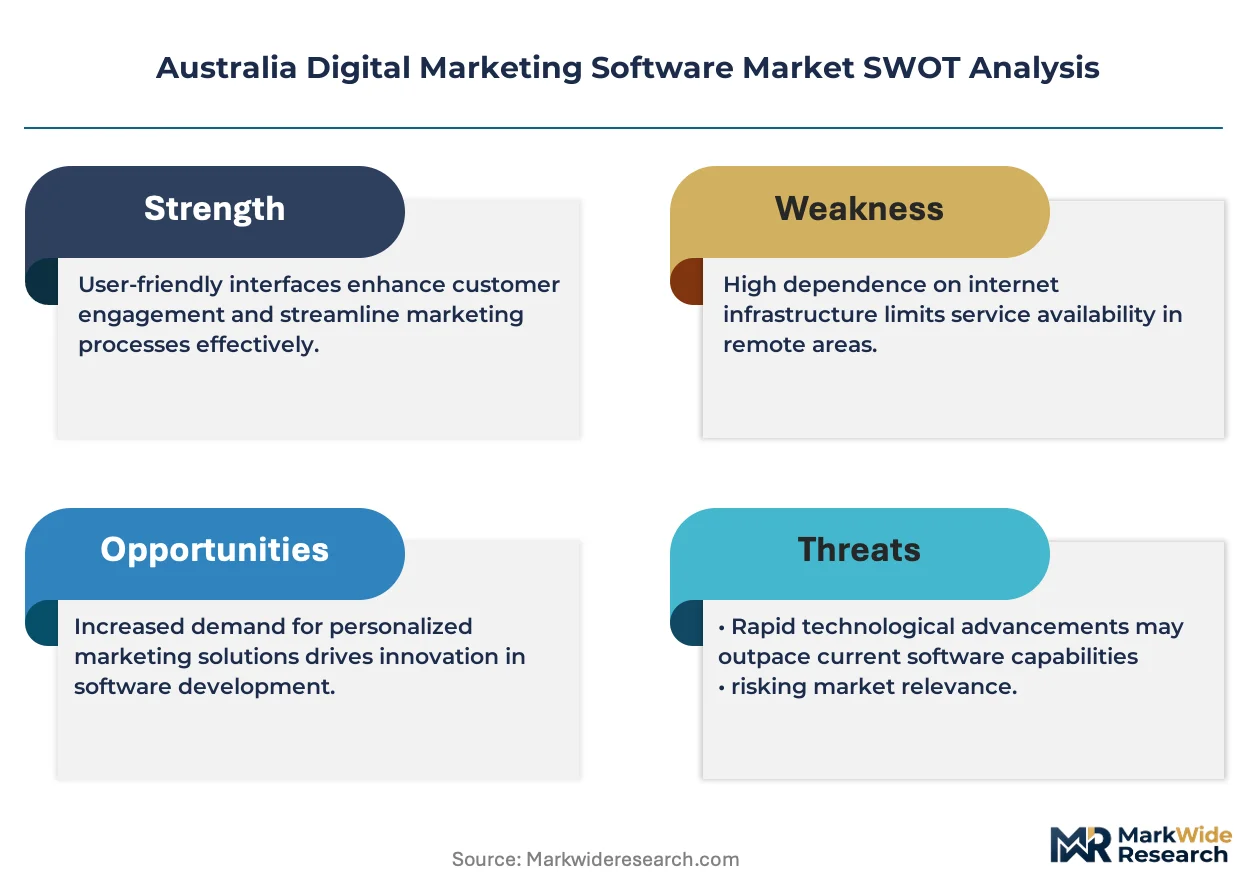
Within the ecosystem-anchored tier, Adobe Inc. and Salesforce Inc. occupy positions defined by creative workflow and CRM integration dominance respectively. HubSpot Inc. exemplifies the mid-market SaaS archetype with inbound marketing automation specialization. These three names anchor the competitive structure without exhausting the vendor landscape, as Oracle Corporation and SAP SE retain legacy enterprise positions while Microsoft Corp and International Business Machines Corp compete through cloud infrastructure bundling.
| Leading Market Players |
|---|
| Adobe Inc. |
| Salesforce Inc. |
| HubSpot Inc. |
| Oracle Corporation |
| SAS Institute Inc. |
| Microsoft Corp |
| SAP SE |
| Hewlett Packard Enterprise Co |
| International Business Machines Corp |
| Others |
Pricing and Supply Chain Analysis
Sydney-Melbourne data center corridors carry cloud infrastructure costs that compress margins for SaaS vendors while enabling tiered pricing differentiation between enterprise and mid-market deployments. This logistics concentration amplifies vendor pricing power in New South Wales and Victoria while forcing cost absorption strategies for Queensland and Western Australia expansion.
Pricing Analysis
The customization-premium spread separates configured-to-order enterprise deployments from standard SaaS tiers across Australian marketing software procurement. Subscription-based SaaS pricing dominates, with differentiation driven by AI feature depth and Australian Privacy Principles compliance certification levels. Pricing pressure stems from subscription fatigue among mid-market CMOs unbundling all-in-one contracts. Small enterprises exhibit highest price sensitivity, while financial services buyers in Sydney demonstrate lowest elasticity due to regulatory compliance requirements.
Supply Chain Analysis
Contract manufacturing concentration for cloud infrastructure rests with hyperscale facilities in Singapore, Sydney, and Melbourne holding primary capacity. Raw material dependencies span semiconductor components from Taiwan and South Korea, plus specialized data center cooling systems from Germany and Japan. Single-source vulnerability concentrates in AI accelerator chips sourced from NVIDIA-dominated supply chains. Distribution runs through direct vendor sales teams and systems integrators serving enterprise accounts, with self-service digital channels capturing mid-market volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity intensifies as mid-market buyers abandon bundled suites for best-of-breed stacks, creating specialized niches for consent architecture vendors and vertical compliance modules.
For Market Incumbents: Harden API ecosystem defenses against point-solution disintermediation threatening platform consolidation strategies. Deepen integration partnerships with Salesforce and Adobe Creative Cloud to lock in workflow dependencies. Prioritize TGA and ASIC compliance module development to capture regulated vertical procurement. For New Entrants and Emerging Players: Brisbane fintech and health tech clusters represent the most penetrable entry point given southern market saturation and talent scarcity barriers. Queensland's underpenetrated mid-market offers 40% lower customer acquisition costs relative to Sydney. Target consent-chain auditability as the primary go-to-market angle against legacy retrofit limitations. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy on-premise vendors with stranded enterprise installed bases requiring cloud migration pathways. Five-to-ten year viability favors vendors with vertical compliance moats over horizontal feature parity. Watch server-side tracking adoption rates as the inflection signal for identity resolution platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Consent Architecture Platform Launch | Captures Australian Privacy Principles-driven replacement cycles for legacy customer data platforms. |
| Vertical Compliance Module Development | Locks in TGA pharmaceutical and ASIC financial services procurement with pre-built regulatory reporting. |
| Queensland Geographic Expansion | Exploits Brisbane fintech cluster growth before southern vendors establish local presence. |
| Server-Side Tracking Integration | Displaces cookie-dependent measurement architectures across Melbourne retail pilot implementations. |
| API Ecosystem Partnership | Enables best-of-breed stack assembly that mid-market buyers prefer over bundled suite trade-offs. |
Research Methodology
Operator-level perspectives from CMOs, marketing operations directors, martech stack architects, and channel integration specialists anchored the qualitative base. Primary interview insights combined with secondary validation from ASIC regulatory filings, Australian Competition and Consumer Commission enforcement records, Office of the Australian Information Commissioner guidance documents, and vendor SEC disclosures. Bottom-up segment sizing triangulated against top-down market boundary estimates across deployment modes and enterprise size tiers.
Scenario-bracketing framed projections across the analysis window, modeling deployment model, organization size, vertical compliance intensity, and regional adoption pattern as core segmentation dimensions. CAGRs derived from trend extrapolation of replacement cycle acceleration and cloud migration velocity. AI personalization engine penetration and server-side tracking adoption served as industry-specific demand curve inputs.
Macroeconomic conditions sit as an overlay; deviation in Australian dollar volatility and enterprise IT budget cycles would shift the trajectory. Forecasts reflect documented assumptions about Privacy Act enforcement intensity and programmatic ad spend growth. Quarterly review of ACCC platform transparency rule implementation and TGA advertising guideline updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Load Balancer Market
Digital Solutions
Smart Recording Pen Market
Digital Solutions
Data Quality and Data Governance Solution Market
Digital Solutions
Digital Workplace Technologies Market
Digital Solutions
Global Remote Monitoring and Management (RMM) Tools Market
Digital Solutions
Kubernetes Solutions Market
Digital Solutions
Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) Market
Digital Solutions
Smart and Connected Offices Market
Digital Solutions
Synthetic Monitoring Market
Digital Solutions
Global Structured Data Archiving and Application Retirement Market
Digital Solutions
Mobile Engagement Market
Digital Solutions
Communication Intelligence Market
Digital Solutions
Legal Transcription Market
Digital Solutions
Multichannel Order Management Market
Digital Solutions
Condition Monitoring Software Market
Digital Solutions
Equipment Tracking Software Market