
 Global Automatic Content Recognition (ACR) Market | 2026-2036
Global Automatic Content Recognition (ACR) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automatic Content Recognition (ACR) Market Foresight
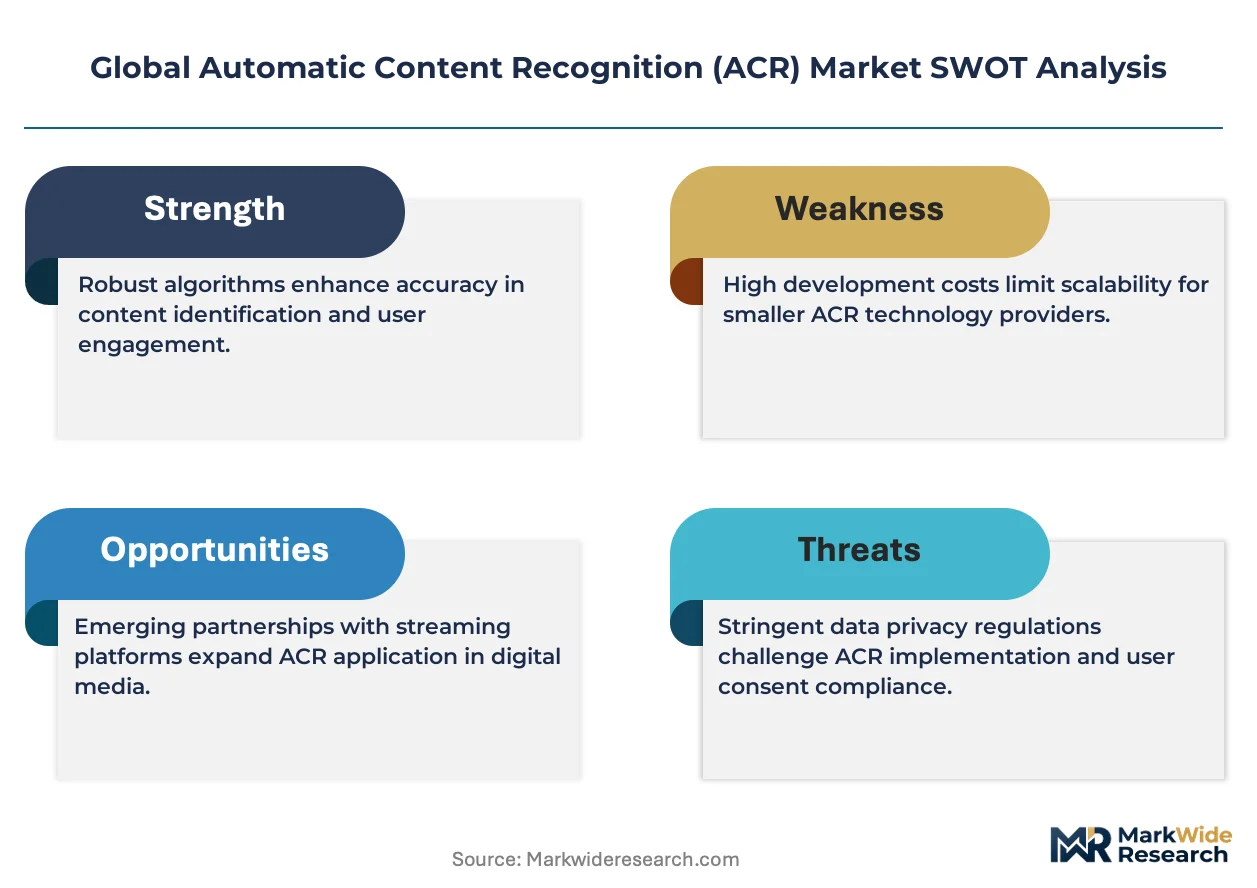
High-precision fingerprinting is bifurcating the competitive landscape between premium recognition engines and commodity matching tools. Google LLC leverages its cloud infrastructure to sustain large-scale video fingerprinting operations across YouTube's content ecosystem. Microsoft Corporation anchors enterprise demand through Azure Media Services integration with broadcast monitoring pipelines. Gracenote Inc. differentiates via proprietary audio fingerprint databases that dominate music identification and second-screen synchronization applications.
Automatic Content Recognition denotes computational systems that extract perceptual features from audio or video signals and match them against reference databases to identify content without embedded metadata. These systems operate on spectral fingerprints sampled at 5-10 second intervals, enabling real-time identification even when signals are compressed, degraded, or partially obscured. Audio Fingerprinting occupies the largest technology segment due to its maturity in music services and broadcast monitoring, while Video Fingerprinting registers the fastest expansion as streaming platforms deploy frame-level matching for copyright enforcement and personalized advertising insertion. Content Identification and Advertising Analytics represent the most margin-intensive application segments, where real-time data feeds command premium pricing from media buyers and rights holders.
The Federal Communications Commission shapes U.S. market access through closed-captioning mandates that drive subtitling and metadata matching adoption, while the European Union's AI Act imposes transparency obligations on automated content classification systems deployed across member states. Japan's Ministry of Economy, Trade and Industry promotes interoperability through JIS standards for broadcast metadata exchange, reducing fragmentation in Asian deployment architectures. Stakeholders must monitor evolving algorithmic accountability requirements that will determine which fingerprinting architectures qualify for regulatory compliance in major content markets.
Market Dynamics
Streaming platforms are compressing identification latency requirements from minutes to seconds, forcing fingerprinting architectures toward edge-compute deployments that process perceptual signatures before cloud transmission.
Growth Catalysts
- EU AI Act transparency mandates:Automated content classification systems in member states must maintain auditable decision trails, expanding demand for fingerprinting solutions with built-in explainability layers.
- Live sports betting synchronization:Second-screen applications in the United Kingdom and Germany require sub-second audio matching to align wagering interfaces with broadcast feeds.
- Cloud-native broadcast workflows:Media organizations migrating from on-premise infrastructure to containerized production pipelines need API-first recognition engines that integrate with Adobe, Avid, and Dalet orchestration platforms.
Market Restraints
- Reference database construction costs:Building proprietary fingerprint libraries demands sustained capital outlay for content licensing and storage infrastructure that commodity providers cannot amortize.
- Signal degradation in low-bitrate environments:Aggressive audio compression on mobile networks and social platforms introduces spectral artifacts that reduce matching confidence below commercial thresholds.
- Cross-border data localization requirements:Brazil's ANVISA-equivalent data governance frameworks and India's TRAI storage mandates fragment cloud architectures and multiply compliance overhead.
Strategic Opportunities
- Interactive advertising insertion:Addressable TV deployments in the United States enable frame-accurate ad replacement based on real-time household demographics, creating premium inventory for media buyers.
- Synthetic media provenance verification:Deepfake detection applications are converging with traditional fingerprinting to establish content authenticity chains for news organizations and political campaigns.
- Japan's METI broadcast metadata standards:Interoperability protocols reduce integration friction for vendors entering Asian markets where JIS-compliant systems receive preferential procurement consideration.
Industry Challenges
- Perceptual hashing talent scarcity:The specialized intersection of signal processing, machine learning, and distributed systems commands compensation premiums that mid-tier vendors cannot match.
- Legacy SDI infrastructure integration:Broadcast facilities with decades-old serial digital interface investments require gateway hardware that adds latency and cost to otherwise software-defined recognition pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automatic Content Recognition (ACR) Market |
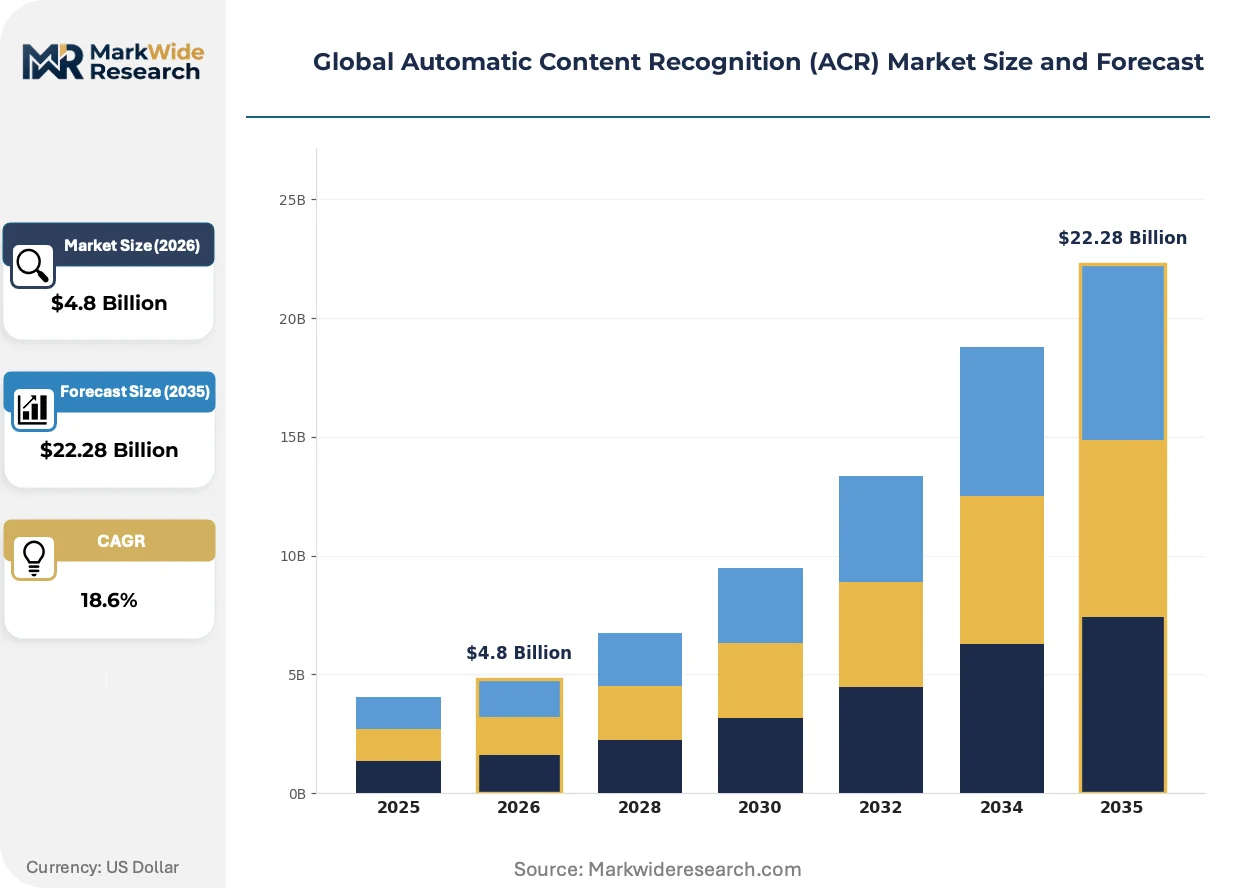
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Audio Fingerprinting, Video Fingerprinting, Subtitling, Metadata Matching Application: Broadcast Monitoring, Advertising Analytics, Content Identification, Copyright Detection End User: Media Companies, Advertisers, Content Creators, Streaming Services Deployment: Cloud-based, On-premises, Hybrid, Mobile |
| Companies Covered | Apple Inc., Microsoft Corporation, Google LLC, Gracenote Inc., Digimarc Corporation, ACRCloud, Audible Magic Corporation, Nuance Communications Inc., IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automatic Content Recognition (ACR) Market Shifts & Advancements
Neural fingerprinting architectures are replacing classical spectral methods, compressing matching latency while expanding robustness against signal manipulation and format conversion artifacts.
Transformer-based embedding models are displacing Mel-frequency cepstral coefficient extraction as the dominant feature representation in production systems. Major streaming services in the United States and Germany have shifted inference workloads to GPU clusters that process 10-second audio windows in under 200 milliseconds. This displacement is collapsing the performance gap between research prototypes and real-time broadcast monitoring deployments.
The EU AI Act's risk classification framework for biometric and content analysis systems imposes conformity assessment obligations on vendors serving European broadcasters and platforms. Media technology procurement teams in France and Germany now require algorithmic impact documentation that traces training data provenance and decision boundary specifications. Vendors without pre-positioned compliance engineering are losing RFP eligibility across public service broadcasters.
Media buyers are consolidating recognition service contracts under enterprise-wide master agreements rather than project-based engagements. Large agency holding companies in the United Kingdom and the United States are demanding unified reporting dashboards that aggregate cross-platform content exposure metrics. This consolidation is squeezing independent analytics providers and favoring vendors with existing cloud partnerships and pre-negotiated enterprise terms.
Global Automatic Content Recognition (ACR) Market Segmentation
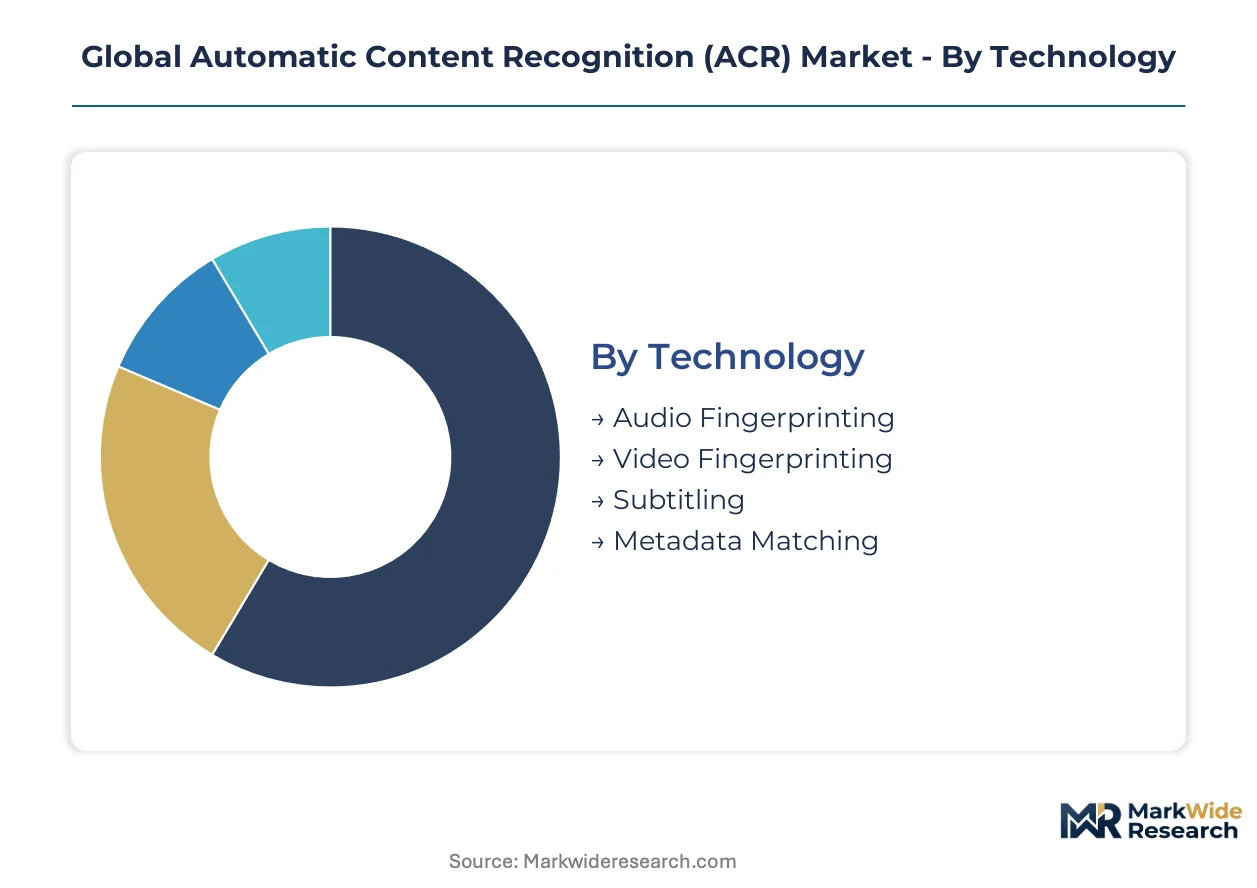
ACR segmentation reveals distinct technology maturity curves and deployment economics that shape vendor positioning across broadcast, streaming, and advertising verticals. Understanding these divisions clarifies where fingerprinting architectures command premium pricing versus commodity substitution.
Technology:
Audio Fingerprinting dominates domestic deployments across the United States, Germany, and Japan where broadcast infrastructure and music services anchor demand, while Video Fingerprinting expansion concentrates in export-led streaming platform integrations.
- Audio Fingerprinting:Spectral feature extraction operating on 5-10 second sampling windows enables real-time music identification and broadcast monitoring even under aggressive compression. United States broadcasters and German public service media deploy this technology for second-screen synchronization and royalty tracking, with EU AI Act transparency requirements now mandating auditable decision trails in member state deployments.
- Video Fingerprinting:Frame-level perceptual hashing identifies content across format conversions, cropping, and overlay manipulations. Streaming services in the United States and United Kingdom deploy edge-compute architectures to compress identification latency below 200 milliseconds for copyright enforcement and personalized ad insertion, with transformer-based embedding models displacing classical spectral methods in production systems.
- Subtitling:Closed-caption synchronization and automated transcription matching serve FCC mandates in the United States and accessibility requirements across European broadcasters.
- Metadata Matching:Embedded watermark and descriptor correlation provides fallback identification when perceptual fingerprints fail, particularly valuable in low-bitrate mobile environments.
Audio Fingerprinting holds the largest share; momentum sits with Video Fingerprinting as streaming platforms compress latency requirements.
Application:
Content Identification and Advertising Analytics concentrate margin-intensive real-time data feeds commanding premium pricing from media buyers, while Broadcast Monitoring and Copyright Detection span cost-tiered deployment scales from enterprise to mid-market.
- Broadcast Monitoring:Real-time channel surveillance for ad verification, content compliance, and audience measurement. United Kingdom and German broadcasters integrate these systems with cloud-native production pipelines from Adobe, Avid, and Dalet, with Japan's METI JIS standards reducing integration friction for vendors entering Asian markets.
- Advertising Analytics:Cross-platform exposure measurement and attribution modeling for media buyers. Large agency holding companies in the United States and United Kingdom consolidate contracts under enterprise-wide master agreements demanding unified reporting dashboards, squeezing independent analytics providers.
- Content Identification:Automated cataloging and recommendation engine feeding for streaming services and digital asset management systems.
- Copyright Detection:Infringement identification across user-generated content platforms and peer-to-peer networks, with deepfake detection applications converging with traditional fingerprinting for synthetic media provenance verification.
Advertising Analytics captures the highest margins; Content Identification is climbing the fastest as streaming catalog expansion accelerates.
End User:
Media Companies and Streaming Services drive volume demand through cloud-native workflow migration, while Advertisers and Content Creators concentrate in customer-type segments requiring API-first integration and self-service analytics.
- Media Companies:Traditional broadcasters and publishers modernizing from SDI infrastructure to software-defined recognition pipelines. Legacy serial digital interface investments in aging facilities require gateway hardware that adds latency and cost, creating upgrade urgency in the United States and European markets.
- Streaming Services:Subscription and advertising-supported platforms deploying frame-accurate recognition for dynamic ad insertion and content recommendation. These buyers compress identification latency from minutes to seconds, forcing architectures toward edge-compute deployments that process perceptual signatures before cloud transmission.
- Advertisers:Brand safety monitoring and campaign verification buyers consolidating spend under holding company procurement.
- Content Creators:Individual producers and independent studios seeking affordable fingerprinting for rights management and distribution tracking.
Media Companies hold the largest share; Streaming Services gain share fastest as cord-cutting accelerates platform investment cycles.
Deployment:
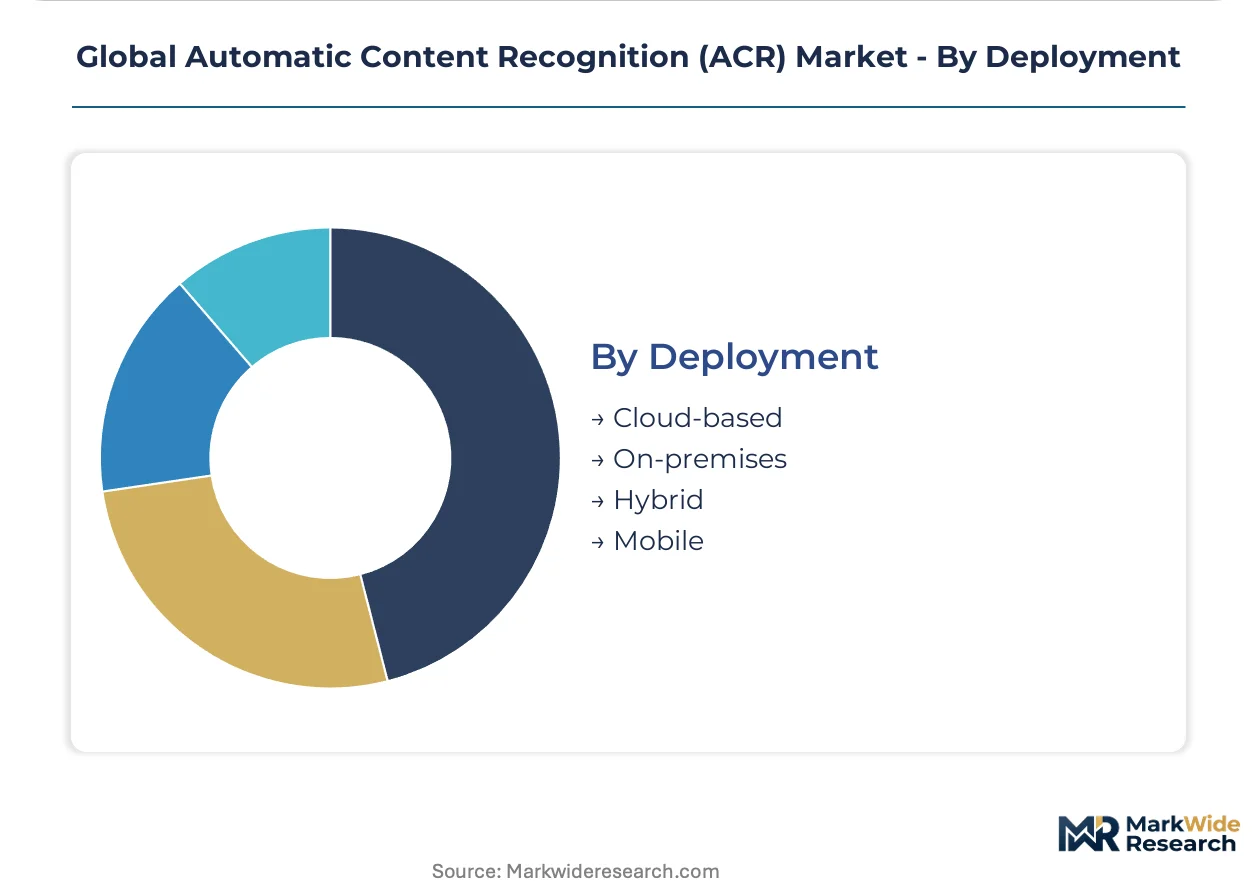
Cloud-based and Hybrid architectures dominate volume as containerized production pipelines replace on-premise infrastructure, while On-premises and Mobile deployments persist in data-localization-constrained and field-production contexts.
- Cloud-based:API-first recognition engines integrating with orchestration platforms and scaling elastically with content volume. Brazil's data governance frameworks and India's TRAI storage mandates fragment architectures and multiply compliance overhead for pure-cloud strategies.
- Hybrid:Edge preprocessing with cloud aggregation balances latency requirements against reference database scale. This architecture satisfies cross-border data localization while enabling real-time matching against centralized fingerprint libraries.
- On-premises:Air-gapped deployments for classified content, legacy facility constraints, and jurisdictions with strict data sovereignty requirements.
- Mobile:Embedded recognition for second-screen applications and field production verification, constrained by signal degradation in low-bitrate environments.
Cloud-based holds the largest share; Hybrid deployment shows the steepest expansion trajectory as latency and localization requirements converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States exports ACR technology and reference database services while importing specialized broadcast monitoring hardware from German and Japanese manufacturers. Trade flows concentrate in cloud-based recognition engines and edge-compute hardware components.
United States
Streaming platforms and broadcast networks drive demand for real-time fingerprinting systems. The FCC mandates closed-caption synchronization that accelerates subtitling technology adoption. Silicon Valley clusters host cloud infrastructure providers deploying neural fingerprinting architectures for sub-200-millisecond matching latency.
Germany
Public service broadcasters and live sports betting operators require precision audio synchronization for second-screen wagering interfaces. The EU AI Act imposes transparency obligations on automated content classification systems deployed across member states. Berlin and Munich anchor broadcast technology development centers where vendors engineer compliance-ready recognition engines.
United Kingdom
Agency holding companies consolidate advertising analytics contracts under enterprise-wide master agreements. Ofcom regulations govern broadcast metadata standards and audience measurement accuracy requirements. London's media technology corridor attracts fingerprinting vendors seeking proximity to major broadcasters and advertising buyers.
Japan
Broadcasters and electronics manufacturers integrate ACR for second-screen synchronization and content recommendation engines. METI promotes JIS standards for broadcast metadata exchange that reduce integration friction for technology vendors. Tokyo and Osaka metropolitan areas concentrate media technology procurement and systems integration expertise.
India
Streaming services and telecommunications operators deploy recognition systems for regional language content identification and dynamic advertising insertion. TRAI storage mandates and data localization requirements fragment cloud architectures and multiply compliance overhead for foreign vendors. Mumbai and Bangalore emerge as hubs for media technology engineering and broadcast systems integration.
Global Automatic Content Recognition (ACR) Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and cloud infrastructure dimensions. The market structure tilts toward consolidated cloud platforms with integrated recognition capabilities, though specialized fingerprinting vendors retain defensible positions in audio database licensing and broadcast monitoring niches. Three archetypes dominate: hyperscale cloud providers with embedded media services, proprietary database licensors with deep content catalogs, and API-first specialists serving mid-market streaming platforms. Competitive intensity centers on M&A activity targeting perceptual hashing engineering teams and strategic partnerships with broadcast orchestration platform vendors.
Within the hyperscale tier, Google LLC and Microsoft Corporation exemplify cloud-native platform strategies that bundle recognition engines with elastic infrastructure. Gracenote Inc. occupies a specialized position as a proprietary database licensor serving music identification and second-screen synchronization applications. These three anchors illustrate divergent paths: infrastructure integration versus content catalog depth as competitive moats.
| Leading Market Players |
|---|
| Apple Inc. |
| Microsoft Corporation |
| Google LLC |
| Gracenote Inc. |
| Digimarc Corporation |
| ACRCloud |
| Audible Magic Corporation |
| Nuance Communications Inc. |
| IBM Corporation |
| Others |
Supply & Pricing Matrix
Transformer-based embedding models replacing classical spectral fingerprinting methods are redistributing supply geography toward GPU cluster operators in the United States and Germany while compressing pricing premiums previously commanded by specialized signal processing vendors. This substitution simultaneously erodes legacy audio fingerprinting margins and elevates cloud-native recognition engines toward SaaS-tiered pricing structures.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the ACR market. Premium tiers command substantial markups for sub-200-millisecond latency guarantees and EU AI Act-compliant audit trails, while economy tiers serve mid-market streaming platforms with higher tolerance for batch processing. Pricing pressure stems from hyperscale cloud providers bundling recognition capabilities into infrastructure contracts, squeezing standalone vendor margins. Advertisers and media buyers exhibit lowest price sensitivity due to campaign verification requirements, whereas independent content creators face acute cost constraints.
Supply Chain Analysis
Reference database construction cycles now stretch 18-24 months for proprietary fingerprint libraries, constraining vendor scaling velocity. Silicon Valley and Berlin anchor GPU cluster supply for neural inference workloads, while Tokyo and Seoul concentrate edge-compute hardware fabrication. The supply chain draws from specialized perceptual hashing engineering talent pools, high-bandwidth memory components, and licensed content catalogs for training data. Single-source vulnerability concentrates in NVIDIA GPU supply for transformer model training. Distribution runs through API-first platform integrations with Adobe, Avid, and Dalet orchestration systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ACR market is recovering from infrastructure consolidation pressure as streaming platform investment cycles reaccelerate post-pandemic normalization. Cloud-native workflow migration among broadcasters and media companies provides the cyclical impetus.
For Market Incumbents: Secure exclusive reference database licensing agreements with major music labels and film studios to lock out commodity competitors. Acquire perceptual hashing engineering teams in Germany and Japan where EU AI Act compliance expertise and METI standardization knowledge concentrate. Vertical integration into edge-compute hardware partnerships with Tokyo-based manufacturers mitigates GPU supply risk. For New Entrants and Emerging Players: API-first self-service analytics for mid-market content creators represents the most penetrable white-space where hyperscale providers under-serve price-sensitive independents. Target Brazil and India where data localization mandates fragment pure-cloud architectures and create demand for hybrid deployment specialists. Pursue channel partnerships with regional systems integrators in Mumbai and São Paulo rather than direct enterprise sales. For Investors and Strategic Acquirers: Capital is best deployed toward proprietary database licensors with deep audio fingerprint catalogs and established second-screen synchronization revenue streams. Long-term viability hinges on regulatory compliance engineering capabilities as algorithmic accountability frameworks proliferate. Watch EU AI Act enforcement patterns across German and French public service broadcasters as the inflection signal for compliance-ready vendor valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Neural Architecture Migration | Transformer-based embedding models displace classical spectral methods in United States and German production systems. |
| EU AI Act Compliance Engineering | Pre-positioned audit trail capabilities unlock French and German public broadcaster procurement eligibility. |
| Edge-Compute Partnership | Tokyo-based hardware collaboration reduces latency for United Kingdom live sports betting synchronization. |
| Reference Database Expansion | Licensed content catalog depth defends against hyperscale cloud provider bundling strategies. |
| Hybrid Deployment Specialization | Brazil and India data localization expertise captures fragmented cloud architecture demand. |
Research Methodology
Operator-level perspectives from streaming platform CTOs, broadcast technology directors, advertising agency procurement leads, and perceptual hashing engineering specialists anchored the qualitative base. Primary interviews combined with secondary validation from FCC filing databases, EU AI Act implementation guidance, METI JIS standard documentation, and hyperscaler media services capex disclosures. Bottom-up segment sizing triangulated against top-down market reconstruction across technology, application, end user, and deployment dimensions.
Sensitivity analysis tested forecast robustness across the projection horizon against streaming subscriber growth trajectories, regulatory enforcement intensity variations, and GPU supply availability scenarios. The analytical framework modeled Audio Fingerprinting, Video Fingerprinting, Subtitling, and Metadata Matching technologies; Content Identification, Advertising Analytics, Broadcast Monitoring, and Copyright Detection applications; and Cloud-based, Hybrid, On-premises, and Mobile deployments. CAGRs derived from segment-level growth rate distributions weighted by end-user investment cycle timing. Neural fingerprinting adoption curves and edge-compute penetration rates served as key forecast inputs.
Forecasts assume regulatory continuity in EU AI Act implementation, FCC closed-captioning mandates, and TRAI data localization requirements; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Landing Page Builders Market
Digital Solutions
Digital Marketing Software Market
Digital Solutions
Europe Digital Pen Market
Digital Solutions
Enterprise Application Integration (EAI) Market
Digital Solutions
Asia-Pacific Digital Twin Market
Digital Solutions
Mobile Ticketing Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
Asia-Pacific Digital Pen Market
Digital Solutions
Canada ICT Market
Digital Solutions
Middle East and Africa Digital Scent Technology Market
Digital Solutions
Global Workflow Orchestration Market
Digital Solutions
Japan Digital Twin Market
Digital Solutions
On-Shelf Availability Solutions Market
Digital Solutions
US Supply Chain Management Software Market
Digital Solutions
Global Interactive Whiteboard (IWB) Market
Digital Solutions
Global Advanced Distribution Management System (ADMS) Market